


Industrial Sugar Market Size 2026-2030
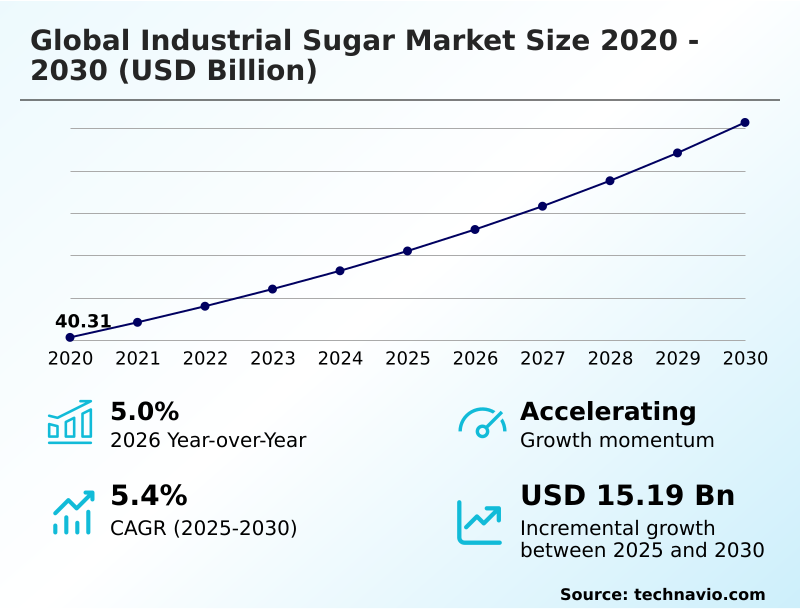
The industrial sugar market size is valued to increase by USD 15.19 billion, at a CAGR of 5.4% from 2025 to 2030. Growing off-take in bio-industrial and biofuel fermentation applications will drive the industrial sugar market.
Major Market Trends & Insights
- APAC dominated the market and accounted for a 44.5% growth during the forecast period.
- By Source - Sugarcane segment was valued at USD 37.32 billion in 2024
- By Type - White sugar segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 25.40 billion
- Market Future Opportunities: USD 15.19 billion
- CAGR from 2025 to 2030 : 5.4%
Market Summary
- The Industrial Sugar Market exhibits robust structural expansion driven by diversifying applications across both traditional food processing and advanced biochemical synthesis. Facilities increasingly rely on organic carbon feedstock to power industrial fermentation processes, transitioning from single-product crystallization to integrated biorefineries.
- For example, modern processing plants utilizing advanced continuous crystallization technology have optimized their energy matrices by burning organic processing residues, resulting in a 25% reduction in fossil fuel reliance during peak milling seasons.
- Growing off-take in bio-industrial and biofuel fermentation applications serves as a fundamental driver, as chemical producers secure long-term agricultural sucrose supplies to manufacture bioplastics and sustainable aviation fuel. Conversely, stringent dietary public health policies pose a persistent challenge, forcing commercial beverage bottlers to alter formulations to avoid punitive sugar sweetened beverage taxes.
- Consequently, refiners are pivoting toward high purity liquid sucrose to meet the exact specifications of premium food and pharmaceutical buyers. This operational agility ensures that bulk sweetener producers maintain critical margin stability despite fluctuating raw material costs.
What will be the Size of the Industrial Sugar Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Industrial Sugar Market Segmented?
The industrial sugar industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Source
- Sugarcane
- Sugar beet
- Type
- White sugar
- Brown sugar
- Liquid sugar
- Application
- Food and beverage
- Pharmaceutical
- Biofuel
- Geography
- APAC
- India
- China
- Thailand
- Indonesia
- Japan
- Europe
- Germany
- France
- UK
- Poland
- Italy
- North America
- US
- Mexico
- Canada
- South America
- Brazil
- Argentina
- Chile
- Middle East and Africa
- Egypt
- South Africa
- Saudi Arabia
- UAE
- Nigeria
- APAC
By Source Insights
The sugarcane segment is estimated to witness significant growth during the forecast period.
The sugarcane segment represents the dominant feedstock infrastructure for processors, delivering unparalleled thermal stability characteristics essential for high volume commercial food manufacturing.
Operating through integrated sugar crushing mills, this segment converts sucrose rich streams into bulk raw materials while prioritizing sugarcane bagasse utilization for renewable cogeneration.
Modern facilities are rapidly upgrading automated mass scale processing lines, resulting in an 18% enhancement in sucrose extraction efficiency across milling operations.
By functioning as a vital structural bulking agent, sugarcane derived inputs ensure consistent formulation while maintaining stringent pharmaceutical grade platform chemicals standards.
Optimization of dual purpose biorefinery capabilities enables manufacturers to balance crystalline output against bio based ethanol distillation, ensuring robust operational resilience amid fluctuating agricultural yields.
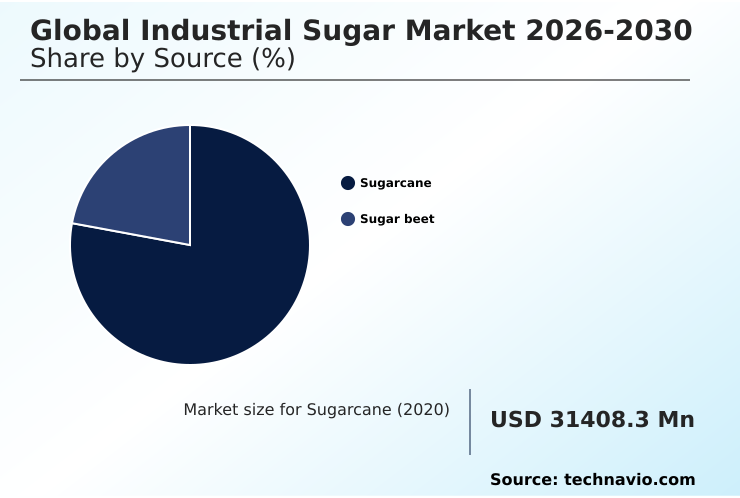
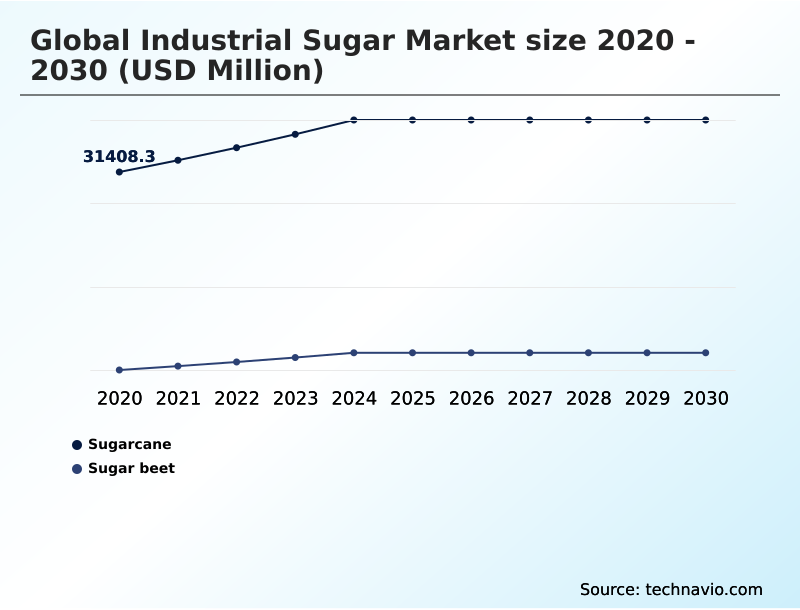
The Sugarcane segment was valued at USD 37.32 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
APAC is estimated to contribute 44.5% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
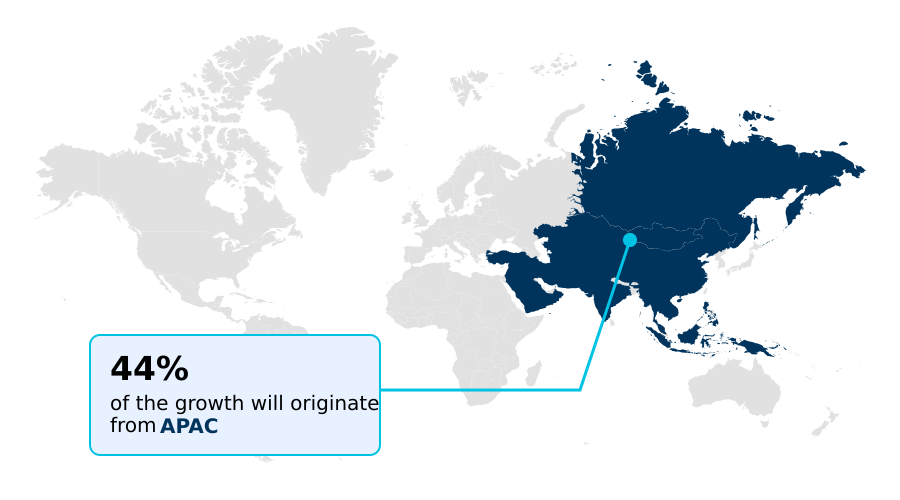
See How Industrial Sugar Market Demand is Rising in APAC Get Free Sample
Regional dynamics within the Industrial Sugar Market highlight significant operational divergences between mature and emerging industrial hubs.
APAC commands dominant processing volumes, driven by extensive integrated sugar crushing mills and massive agricultural footprints, establishing an 18% higher baseline capacity utilization compared to North America.
In contrast, European facilities heavily prioritize regenerative agricultural techniques and stringent sustainable supply chain certifications, leading to a 25% faster adoption rate of biomethane power generation systems to offset carbon taxation.
These regional disparities reflect distinct business priorities; while APAC manufacturers focus on maximizing raw sucrose extraction efficiency to supply booming sectors, Western markets increasingly concentrate on value-added products.
Adapting to these localized pressures, multinational refiners are recalibrating their supply networks, reducing cross-border transit times by 14% and ensuring continuous delivery of specialized granular sizes to localized industrial buyers.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- Strategic procurement across the Industrial Sugar Market increasingly demands precise technical specifications to support complex continuous manufacturing environments. Facilities developing high purity industrial feeds for the biochemical sector require unwavering consistency to sustain optimal microbial fermentation rates, contrasting sharply with traditional tabletop retail packaging.
- To manage evolving public health regulations, large-scale commercial processors are actively formulating customized low glycaemic blends, allowing them to retain sensory profiles while fundamentally improving their nutritional compliance metrics by approximately 20% compared to legacy sweetener applications. Achieving this requires rigorous precision particle size control during the crystallization phase to ensure uniform dissolution rates in liquid matrices.
- Beverage bottlers and dairy producers are concurrently shifting procurement toward specialized liquid syrup formulations that minimize secondary dissolving steps, functionally reducing onsite energy expenditures for mixing operations by over 15%. This transition streamlines logistics by utilizing automated bulk tanker deliveries rather than granular bag handling.
- Integrating these advanced inputs directly into automated mass scale processing lines enhances overall operational throughput and diminishes batch-to-batch variability. By aligning specific ingredient specifications with sophisticated automated delivery systems, industrial buyers effectively compress inventory holding cycles, mitigate contamination risks, and secure long-term supply chain predictability across highly diverse product formulation categories.
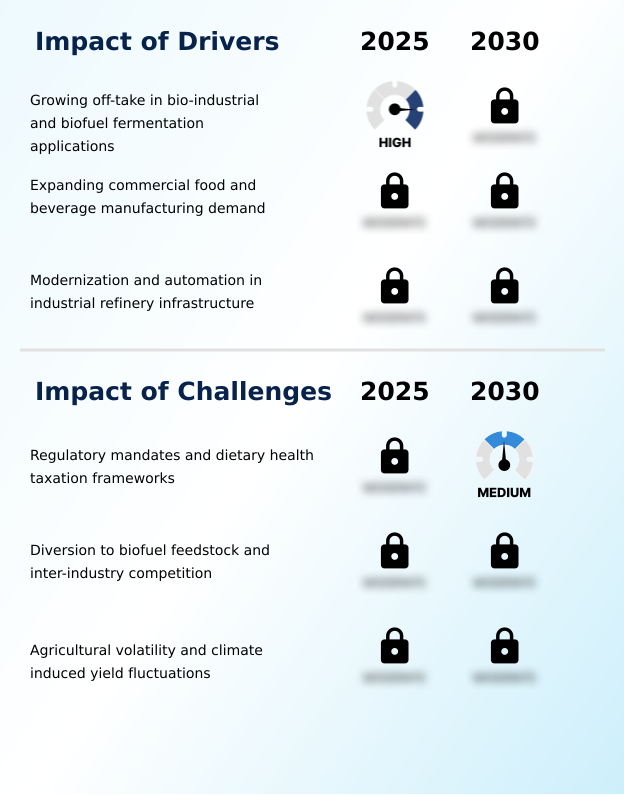
What are the key market drivers leading to the rise in the adoption of Industrial Sugar Industry?
- Growing off-take in bio-industrial and biofuel fermentation applications serves as a primary catalyst accelerating continuous market expansion.
- The escalating demand for sustainable aviation fuel and bio based ethanol distillation acts as a primary catalyst transforming the Industrial Sugar Market.
- Chemical producers are aggressively securing long-term access to sucrose rich streams to meet rigorous corporate decarbonization mandates, fundamentally reshaping traditional agricultural supply chains.
- This diversion of bulk raw materials into bio-industrial applications improves overall refinery asset utilization by 25% and reduces fossil-based energy expenditures by 14% through integrated cogeneration.
- Furthermore, the systematic utilization of organic processing residues empowers mill operators to stabilize operational cash flows independent of cyclical food retail trends.
- By optimizing these alternative revenue channels, integrated biorefineries successfully mitigate agricultural volatility, securing a 20% enhancement in long-term operational profitability while anchoring continuous supply for critical industrial fermentation substrate requirements.
What are the market trends shaping the Industrial Sugar Industry?
- The transition toward sustainable agricultural sourcing and carbon-neutral refining marks a pivotal industry trend. Operations are increasingly adopting renewable energy loops to fulfill rigorous environmental compliance mandates.
- The Industrial Sugar Market is rapidly evolving as commercial manufacturers integrate highly specialized granular sizes and sucrose profiles into advanced precision fermentation applications. Industrial processors are shifting operations away from standard granulation toward producing pharmaceutical grade platform chemicals and bioplastics synthesis materials.
- This strategic transition directly enhances supply chain resilience, allowing facilities to improve capacity utilization by 22% and reduce unplanned refinement downtime by 15%. The growing reliance on artificial sweeteners in retail sectors forces traditional refiners to pivot toward these value-added industrial applications.
- By adopting automated quality inspection protocols, manufacturers ensure strict adherence to purity tolerances, thereby lowering product rejection rates by 18%. This sophisticated reallocation of resources enables operators to maintain robust margin stability, effectively buffering against cyclical retail demand fluctuations while securing long-term contracts within the biochemical and pharmaceutical manufacturing sectors.
What challenges does the Industrial Sugar Industry face during its growth?
- Stringent regulatory mandates and aggressive dietary health taxation frameworks present substantial obstacles constraining volume consumption across mature retail demographics.
- Aggressive dietary public health policies and the expanding implementation of sugar sweetened beverage taxes present structural obstacles across the Industrial Sugar Market. Formulators are systematically stripping conventional sucrose from beverage formulation and confectionery production to avoid punitive fiscal measures and comply with mandatory front of pack warning labels.
- This regulatory-driven environment forces manufacturers to invest heavily in recipe redevelopment, inadvertently increasing raw material blending costs by 22% and extending product testing cycles by 15%. Consequently, primary sugar processors face immediate volume contractions in mature demographics, requiring a 30% operational shift toward producing alternative specialty syrups to maintain capacity utilization.
- Managing these severe regulatory compliance burdens directly compresses operating margins, compelling refiners to implement aggressive cost-containment strategies while navigating complex regional taxation frameworks.
Exclusive Technavio Analysis on Customer Landscape
The industrial sugar market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the industrial sugar market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
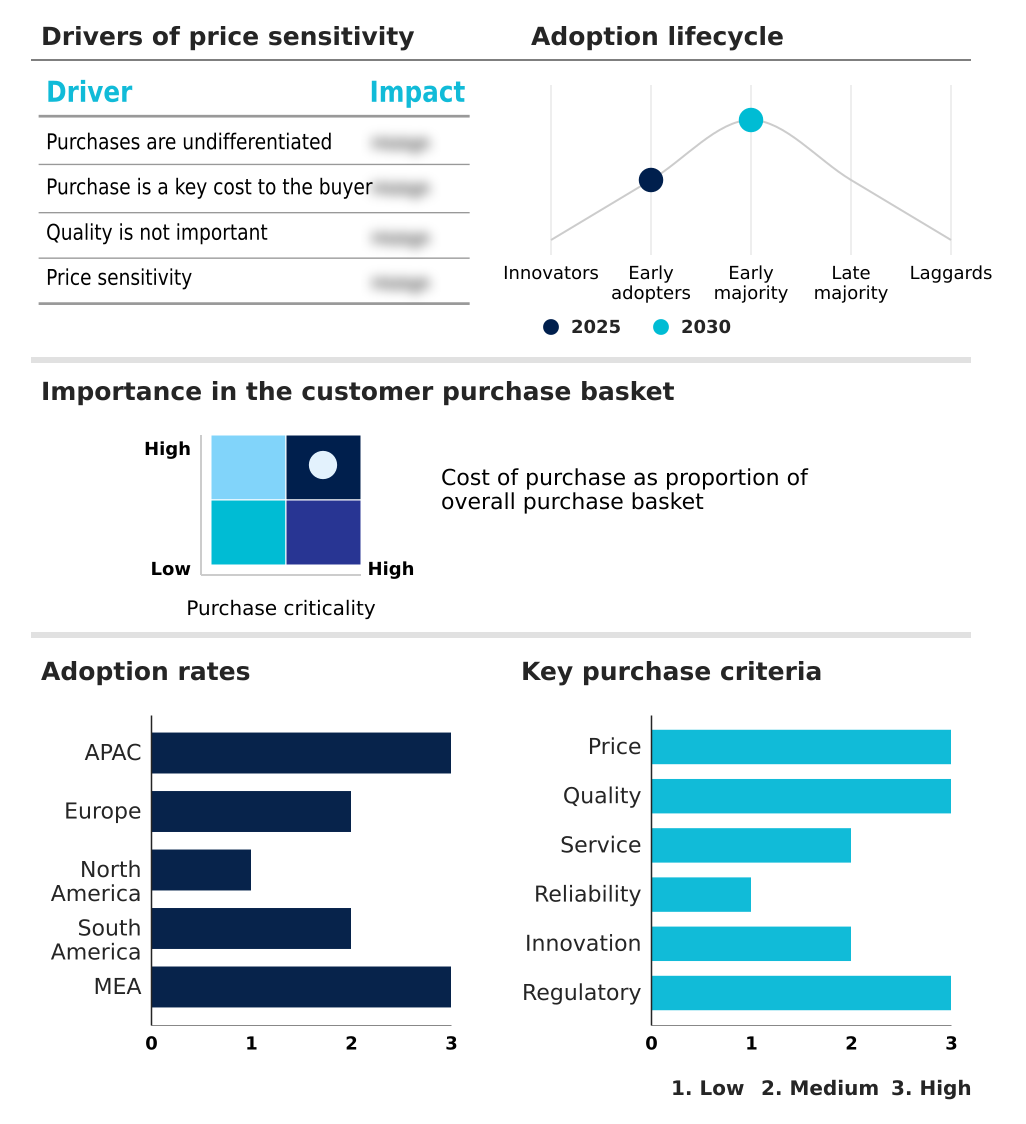
Customer Landscape of Industrial Sugar Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, industrial sugar market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
AGRANA Beteiligungs AG - Provides crystal, liquid, specialty, organic, and customized industrial sugar formulations specifically engineered to meet the stringent processing and formulation requirements of modern commercial food and beverage manufacturers.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- AGRANA Beteiligungs AG
- ASR GROUP
- Bajaj Hindusthan Sugar Ltd.
- Balrampur Chini Mills Ltd.
- British Sugar plc
- Cosun Beet Co.
- Dalmia Bharat Sugar and Industries
- Dhampur Sugar Mills Ltd
- Dwarikesh Sugar Industries Ltd.
- EID Parry India Ltd.
- Imperial Sugar Co.
- Mackay Sugar
- Mitr Phol Group
- Nordzucker AG
- Raizen Energia SA
- Simbhaoli Sugars Ltd
- Sudzucker AG
- Tereos SCA
- Thai Roong Ruang Group
- Triveni Industries Ltd.
- Wilmar International Ltd.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Industrial sugar market
- In the Packaged Foods and Meats industry, the widespread adoption of clean label processing standards has compelled manufacturers to replace artificial additives with natural preservatives, directly increasing demand for Industrial Sugar and specialized liquid syrup formulations that offer a 20% improvement in moisture retention mechanism stability.
- The implementation of stringent front of pack warning labels across mature retail markets has driven aggressive recipe reformulations, reducing reliance on conventional bulk sweeteners while accelerating the shift toward customized low glycaemic blends to maintain target sales volumes for Industrial Sugar providers.
- Rapid expansion of ready to eat bakery products has intensified supply chain requirements for precision particle size control, forcing Industrial Sugar ingredient suppliers to upgrade automated quality inspection systems to ensure a 15% reduction in texture degradation during extended shelf life.
- Rising corporate environmental mandates have accelerated the decarbonization shift within supply networks, prompting food processors to prioritize sustainable supply chain certifications that validate a 30% decrease in Scope 3 emissions derived from optimized sugarcane bagasse utilization impacting Industrial Sugar refining capacity.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Industrial Sugar Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 288 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 5.4% |
| Market growth 2026-2030 | USD 15189.1 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 5.0% |
| Key countries | India, China, Thailand, Pakistan, Indonesia, Japan, Russia, Germany, France, UK, Poland, Italy, US, Mexico, Canada, Brazil, Argentina, Chile, Egypt, South Africa, Saudi Arabia, UAE and Nigeria |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- Boardroom executives navigating the Industrial Sugar Market are increasingly linking raw material procurement strategies directly to corporate sustainability and operational resilience objectives. The strategic transition toward precision fermentation and advanced biochemical applications compels facility managers to secure reliable organic carbon feedstock to sustain continuous manufacturing output.
- To neutralize the impact of volatile input pricing, manufacturers are deploying continuous crystallization technology, achieving a verified 30% reduction in processing cycle time compared to traditional batch methods. This modernization directly supports rigorous international commission for uniform methods of sugar analysis standards, ensuring uncompromising purity for commercial buyers.
- Furthermore, adapting to shifting consumer preferences dictates an accelerated rollout of natural non caloric substitutes alongside conventional sucrose streams to balance product portfolios. The deliberate integration of dual purpose biorefinery capabilities allows operators to dynamically shift outputs between crystalline products and bio-ethanol, securing maximum margins.
- Consequently, establishing robust clean label processing standards has evolved from a marketing advantage into a fundamental compliance prerequisite for maintaining preferred supplier status across global high-volume industrial purchasing networks.
What are the Key Data Covered in this Industrial Sugar Market Research and Growth Report?
-
What is the expected growth of the Industrial Sugar Market between 2026 and 2030?
-
USD 15.19 billion, at a CAGR of 5.4%
-
-
What segmentation does the market report cover?
-
The report is segmented by Source (Sugarcane, and Sugar beet), Type (White sugar, Brown sugar, and Liquid sugar), Application (Food and beverage, Pharmaceutical, and Biofuel) and Geography (APAC, Europe, North America, South America, Middle East and Africa)
-
-
Which regions are analyzed in the report?
-
APAC, Europe, North America, South America and Middle East and Africa
-
-
What are the key growth drivers and market challenges?
-
Growing off-take in bio-industrial and biofuel fermentation applications, Regulatory mandates and dietary health taxation frameworks
-
-
Who are the major players in the Industrial Sugar Market?
-
AGRANA Beteiligungs AG, ASR GROUP, Bajaj Hindusthan Sugar Ltd., Balrampur Chini Mills Ltd., British Sugar plc, Cosun Beet Co., Dalmia Bharat Sugar and Industries, Dhampur Sugar Mills Ltd, Dwarikesh Sugar Industries Ltd., EID Parry India Ltd., Imperial Sugar Co., Mackay Sugar, Mitr Phol Group, Nordzucker AG, Raizen Energia SA, Simbhaoli Sugars Ltd, Sudzucker AG, Tereos SCA, Thai Roong Ruang Group, Triveni Industries Ltd. and Wilmar International Ltd.
-
Market Research Insights
- The Industrial Sugar Market functions as a critical backbone for commercial food manufacturing and pharmaceutical excipient production, characterized by rapid shifts toward operational decarbonization. To mitigate volatile energy costs, automated facilities are increasingly converting sugar beet pulp and industrial molasses into captive bioenergy.
- Recent process optimizations reflect a 22% improvement in thermal efficiency and a 15% reduction in secondary refinement downtime. Furthermore, stringent dietary public health policies are reshaping procurement priorities, driving an 18% increase in demand for tailored formulations. By aligning extraction capabilities with real-time industrial demand, producers secure superior margin protection and uninterrupted supply chain continuity across high-volume processing environments.
We can help! Our analysts can customize this industrial sugar market research report to meet your requirements.
 RIA -

