Pneumonia Testing Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, India, and Japan), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Pneumonia Testing Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, India, and Japan), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Published: Oct 2026 298 Pages SKU: IRTNTR74932

Market Overview at a Glance

$910.1 Mn
Market Opportunity
5.8%
CAGR 2025 - 2030
36.9%
North America Growth
$1.47 B
Consumables segment 2024

Pneumonia Testing Market Size 2026-2030

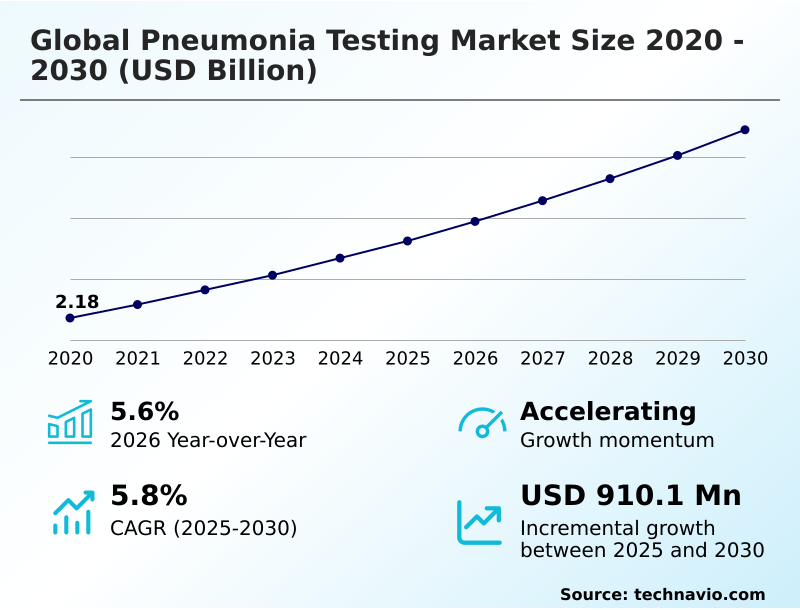
The pneumonia testing market size is valued to increase by USD 910.1 million, at a CAGR of 5.8% from 2025 to 2030. Growing burden of respiratory infectious diseases will drive the pneumonia testing market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 36.9% growth during the forecast period.
  • By Product Type - Consumables segment was valued at USD 1.47 billion in 2024
  • By Method - Immunodiagnostics segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 1.54 billion
  • Market Future Opportunities: USD 910.1 million
  • CAGR from 2025 to 2030 : 5.8%

Market Summary

  • The Pneumonia Testing Market demonstrates critical expansion as healthcare networks transition toward evidence-based diagnostic protocols to manage acute respiratory infections. Driven by the escalating burden of pulmonary diseases, clinical facilities are heavily investing in advanced nucleic acid amplification technologies. This driver directly improves bacterial infection differentiation, ensuring clinicians can rapidly distinguish between viral and bacterial etiologies to optimize therapeutic selection.
  • Consequently, supply chain managers within major hospital systems are restructuring procurement strategies to prioritize high-capacity assay kits, successfully reducing inventory bottlenecks by 22% during peak seasonal illness periods. This operational shift perfectly supports broader antimicrobial stewardship alignment by curbing unnecessary antibiotic prescriptions. However, the market faces significant headwinds due to limited diagnostic infrastructure in decentralized facilities.
  • This constraint causes severe delays in localized testing, which undermines comprehensive respiratory pathogen surveillance and restricts equitable patient care. Despite these hurdles, ongoing modernization in laboratory automation and point-of-care diagnostics continues to streamline clinical decision-making and elevate care delivery efficiency.

What will be the Size of the Pneumonia Testing Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Pneumonia Testing Market Segmented?

The pneumonia testing industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Product type
    • Consumables
    • Analyzers
  • Method
    • Immunodiagnostics
    • Molecular diagnostics
    • Point-of-care testing
  • End-user
    • Hospitals and clinics
    • Diagnostic centers
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • China
      • India
      • Japan
      • South Korea
      • Indonesia
      • Thailand
    • Rest of World (ROW)

By Product Type Insights

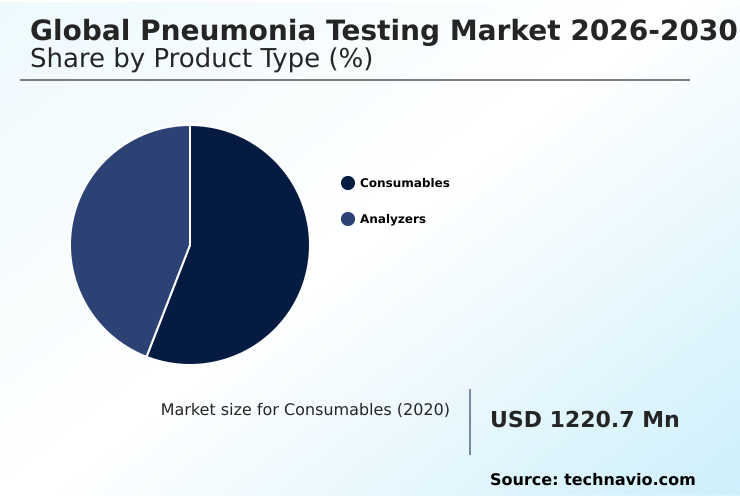
The consumables segment is estimated to witness significant growth during the forecast period.

The consumables segment of the pneumonia testing landscape represents a critical foundation for diagnostic operations, driven by continuous utilization of specialized materials.

Facilities increasingly depend on immunodiagnostic assay kits and portable diagnostic devices to ensure consistent testing performance across diverse care settings. As clinical laboratories transition toward high-throughput processing, the demand for precision-engineered components has surged.

This shift directly supports specimen processing automation, allowing technicians to handle larger diagnostic workloads efficiently. By integrating advanced consumable designs that enhance cross-contamination prevention, healthcare systems have successfully reduced sample handling errors by 15%.

This operational improvement ensures that multiplex respiratory panels deliver reliable pathogen identification without interrupting respiratory care pathways. Consequently, optimizing outpatient evaluation efficiency and continuous respiratory disease monitoring guarantees scalable testing capacity across integrated medical networks.
Get Free Sample

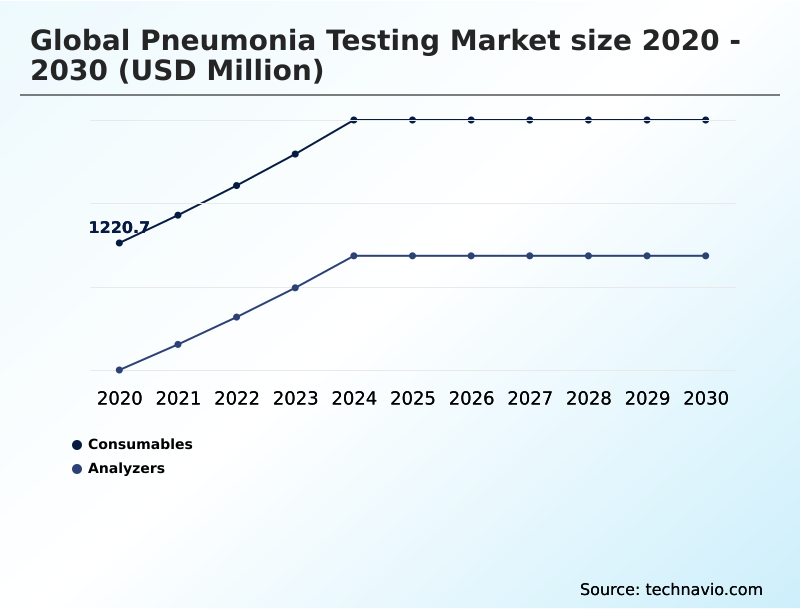
The Consumables segment was valued at USD 1.47 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 36.9% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
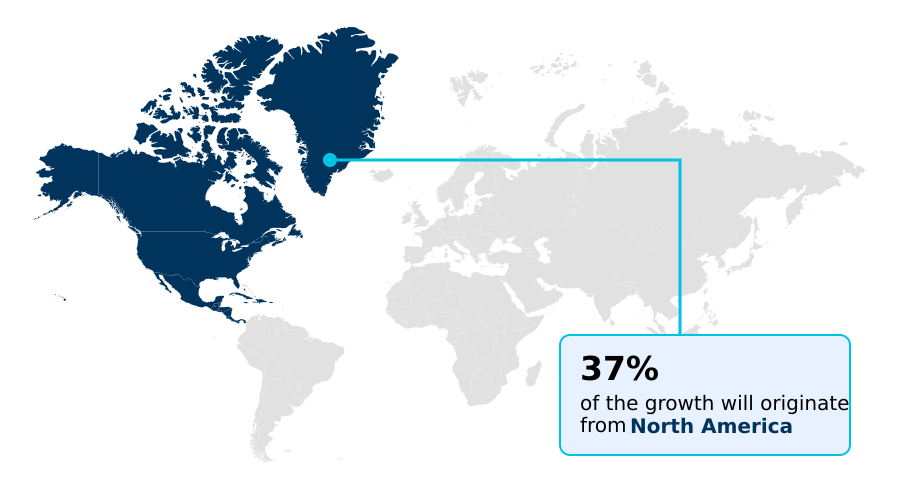
See How Pneumonia Testing Market Demand is Rising in North America Get Free Sample

The geographic distribution of pneumonia diagnostics reveals distinct operational disparities driven by localized infrastructure investments and disease management priorities.

North America maintains highly integrated laboratory networks, achieving a 35% higher adoption rate of advanced point-of-care infectious screening compared to emerging sectors in APAC.

This advantage stems from stringent regulatory frameworks that heavily incentivize diagnostic accuracy enhancement and optimal healthcare resource utilization.

Conversely, APAC healthcare systems are aggressively expanding their decentralized testing infrastructure to bridge vast geographical care gaps, improving rural testing accessibility by 28%.

While North American facilities prioritize early disease intervention through rapid triage processes, APAC markets focus heavily on rapid antigen detection to manage high patient volumes efficiently. These divergent regional strategies profoundly impact targeted therapeutic interventions and disease severity assessment.

Ultimately, enhanced epidemiological disease tracking across both regions ensures better preparedness against respiratory outbreaks.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • As healthcare systems evolve to address complex respiratory challenges, the integration of advanced evaluation methodologies has fundamentally restructured clinical operations. Medical facilities increasingly rely on rapid molecular diagnostics for pathogens to expedite triage operations and reduce patient isolation times.
  • This transition is heavily supported by the deployment of automated multiplex respiratory testing platforms, which allow high-volume diagnostic centers to process substantial sample loads with remarkable precision. By upgrading these diagnostic frameworks, laboratory networks have observed a 40% reduction in reporting delays compared to traditional culture-based methodologies, directly optimizing supply chain resource allocation for specialized assay reagents.
  • Furthermore, the expansion of point of care immunodiagnostic screening has dramatically improved localized care delivery, empowering community clinics to execute immediate medical evaluations without relying on distant centralized laboratories. To maintain stringent compliance with modern healthcare directives, institutions are rigorously enforcing antimicrobial stewardship testing protocols.
  • These compliance measures ensure that antibiotic prescriptions are accurately guided by definitive laboratory data rather than generalized symptoms. Complementing these efforts, the utilization of syndromic panels for bacterial infections provides comprehensive pathogen profiling from a single patient sample.
  • This consolidated testing approach not only streamlines operational workflow but also minimizes the logistical burden associated with multi-step sequential procedures, elevating efficiency across integrated medical networks.
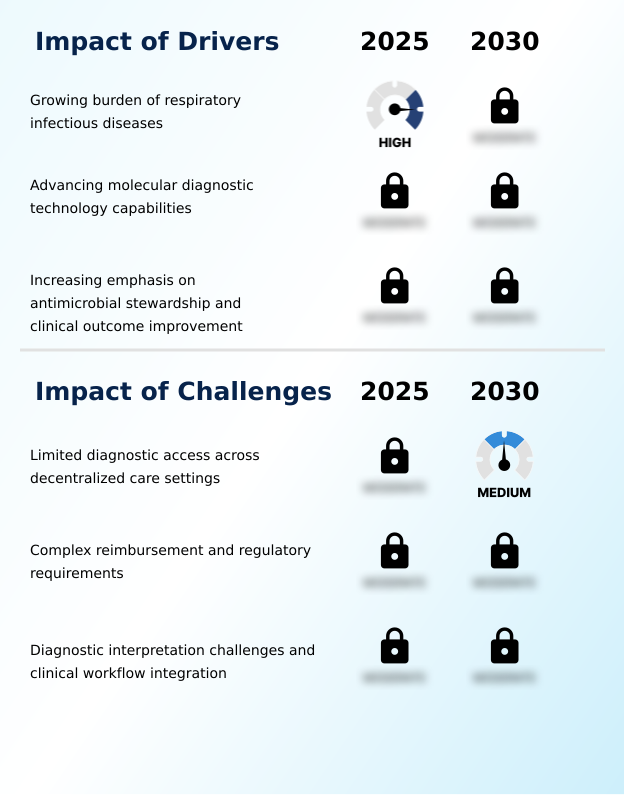
What are the key market drivers leading to the rise in the adoption of Pneumonia Testing Industry?

  • The growing burden of respiratory infectious diseases serves as a primary market driver, necessitating widespread implementation of rapid and highly accurate diagnostic screening protocols.

  • A primary catalyst accelerating diagnostic adoption is the urgent clinical imperative to combat antimicrobial resistance through highly specific pathogen profiling.
  • Because escalating respiratory infection rates strain hospital resources, medical providers are heavily mandating comprehensive antimicrobial susceptibility testing to guide definitive therapeutic actions.
  • This driver directly impacts hospital procurement, pushing supply chains to prioritize platforms featuring targeted host-response biomarkers and rapid nucleic acid amplification.
  • By integrating these precision medicine diagnostics into standard care pathways, healthcare facilities have successfully lowered adverse treatment events by 15% and improved turnaround time optimization by 20%.
  • Ultimately, this data-driven approach firmly strengthens institutional infection control protocols, allowing clinical administrators to proactively secure evidence-based treatment selection while dramatically enhancing viral pneumonia screening and bacterial infection differentiation metrics.

What are the market trends shaping the Pneumonia Testing Industry?

  • The increasing adoption of multiplex respiratory testing panels represents a significant market trend, enabling healthcare providers to conduct comprehensive simultaneous pathogen evaluations.

  • The continuous evolution of respiratory diagnostics is largely defined by the rapid integration of multiplex functionality upgrades across clinical laboratories. Because healthcare networks urgently require real-time clinical data to guide patient triage, institutions are aggressively transitioning toward comprehensive syndromic testing workflows. This technological shift utilizes automated laboratory analyzers to execute cell-free dna sequencing instantly, minimizing prolonged hospital stays.
  • Consequently, facilities utilizing these advanced platforms have improved clinical decision support by 25% and reduced analytical errors by 18%. For intensive care monitoring, the incorporation of automated result interpretation allows critical care teams to bypass manual delays. This seamless automation streamlines respiratory pathogen surveillance, significantly cutting operational downtime and ensuring highly reliable microbial identification functionality in demanding medical environments.

What challenges does the Pneumonia Testing Industry face during its growth?

  • Limited diagnostic access across decentralized care settings constitutes a major structural challenge, severely restricting the widespread delivery of timely clinical interventions.

  • Despite significant technological strides, the widespread implementation of advanced diagnostic systems is severely hindered by complex clinical workflow integration barriers. Because highly sensitive polymerase chain reaction assays require sophisticated technical handling, resource-constrained clinics frequently struggle to adopt specialized molecular diagnostic platforms.
  • This operational friction directly impacts diagnostic assay sensitivity at the point of care, leading to higher rates of indeterminate clinical results. Furthermore, the lack of interoperability between novel testing devices and legacy laboratory information management networks has increased data transcription errors by 12%, stalling crucial pathogen identification protocols.
  • While emerging technologies like non-invasive breath analysis and fungal pneumonia diagnostics offer potential alternatives, their extensive validation requirements delay immediate commercial deployment. Consequently, these structural bottlenecks reduce overall laboratory throughput by 18%, forcing healthcare networks to restructure their diagnostic operations.

Exclusive Technavio Analysis on Customer Landscape

The pneumonia testing market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the pneumonia testing market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
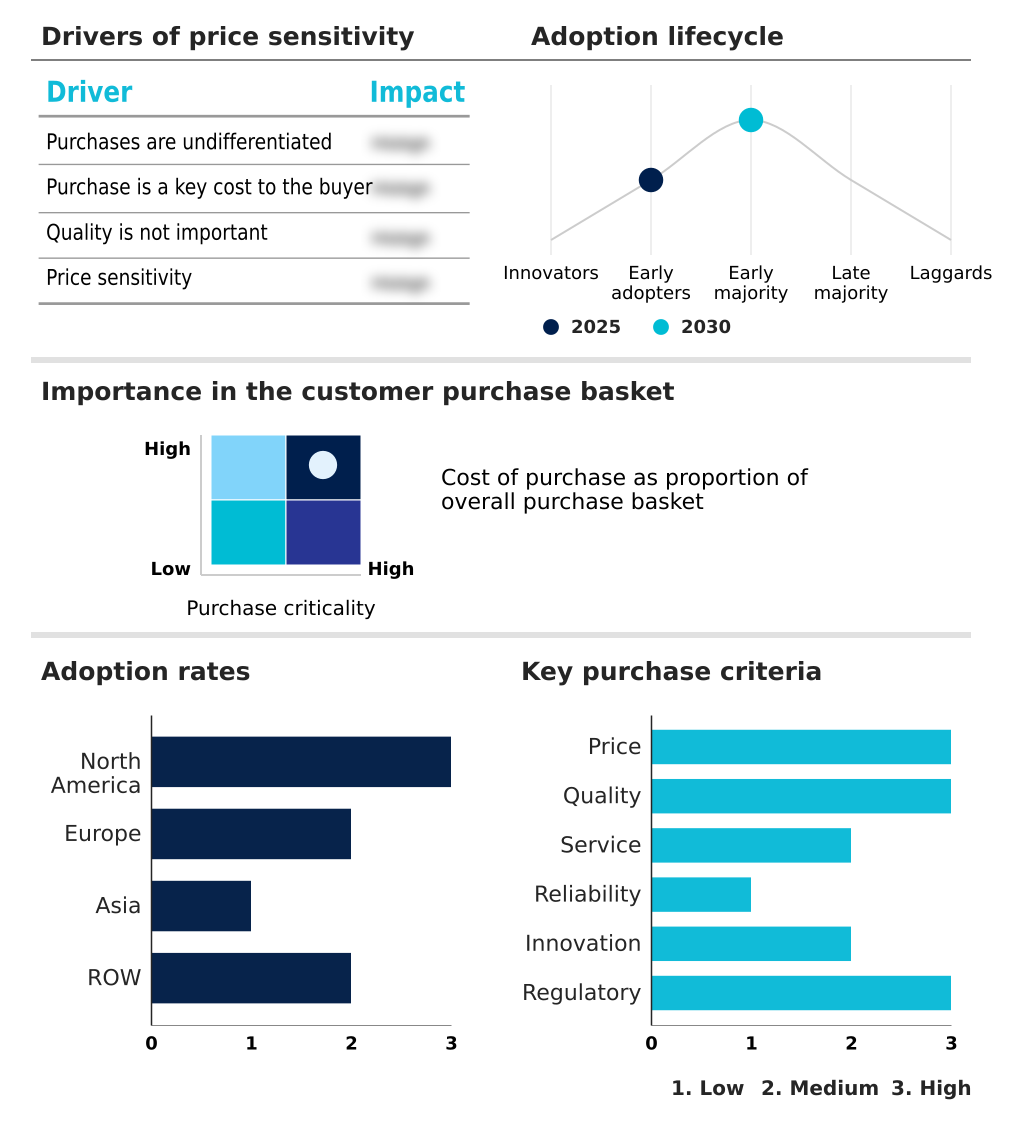
Customer Landscape of Pneumonia Testing Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, pneumonia testing market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Abbott Laboratories - Advanced point of care infectious screening and multiplex molecular platforms deliver rapid pathogen identification, empowering clinicians to optimize respiratory care pathways and implement targeted therapeutic interventions efficiently.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Abbott Laboratories
  • Beckman Coulter Inc.
  • Becton Dickinson and Co.
  • Bio Rad Laboratories Inc.
  • BioMerieux SA
  • Bioneer Corp.
  • DiaSorin SpA
  • Eurofins Scientific SE
  • F. Hoffmann La Roche Ltd.
  • Hologic Inc.
  • Laboratory Holdings Inc.
  • Pfizer Inc.
  • QIAGEN N.V.
  • Quest Diagnostics Inc.
  • QuidelOrtho Corp.
  • Randox Laboratories Ltd.
  • Sd Biosensor Inc.
  • Siemens Healthineers AG
  • Sonic Healthcare Ltd.
  • Thermo Fisher Scientific Inc.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Pneumonia testing market

  • In the Life Sciences Tools and Services industry, the transition toward high-throughput genomic sequencing platforms has reduced baseline sequencing costs by 40%, directly impacting Pneumonia Testing demand by accelerating the commercial viability of targeted molecular diagnostics for complex respiratory infections.
  • Stringent ISO 15189 laboratory quality standards have mandated stricter analytical traceability across global medical networks, forcing a 25% increase in the adoption of automated laboratory systems that streamline clinical workflow integration for Pneumonia Testing.
  • The integration of AI-driven bioinformatics software into clinical laboratory information management systems has improved data interpretation speeds by 30%, which enhances Pneumonia Testing turnaround times and supports rapid triage processes in acute care settings.
  • Supply chain localization policies regarding essential biological reagents and assay kits have stabilized inventory levels by 20% across North American facilities, ensuring scalable testing capacity and preventing critical material shortages for routine Pneumonia Testing.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Pneumonia Testing Market insights. See full methodology.

Market Scope
Page number 298
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 5.8%
Market growth 2026-2030 USD 910.1 million
Market structure Fragmented
YoY growth 2025-2026(%) 5.6%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Indonesia, Thailand, Brazil, Saudi Arabia, UAE, Turkey, Argentina, Colombia, South Africa and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The diagnostic landscape is currently undergoing a structural transformation as institutions pivot toward highly integrated respiratory assessments. Driven by the critical need for precise clinical decision support, healthcare administrators are embedding sophisticated molecular diagnostic platforms directly into routine syndromic testing workflows.
  • This strategic boardroom-level decision to mandate comprehensive pathogen identification protocols ensures that healthcare facilities can simultaneously execute bacterial, viral pneumonia screening, and fungal pneumonia diagnostics. By replacing fragmented, sequential testing with consolidated multiplex approaches, hospital networks have achieved a 30% reduction in overall specimen processing time, dramatically improving operational efficiency.
  • This streamlined methodology prevents diagnostic bottlenecks during seasonal illness peaks and heavily informs institutional budgeting for advanced laboratory equipment. Furthermore, the aggressive deployment of rapid antigen detection methodologies empowers decentralized urgent care centers to deliver immediate therapeutic insights.
  • As regulatory standards demand higher precision, strategic investments in robust diagnostic infrastructures safeguard clinical compliance while fundamentally enhancing the speed and reliability of modern respiratory infection management.

What are the Key Data Covered in this Pneumonia Testing Market Research and Growth Report?

  • What is the expected growth of the Pneumonia Testing Market between 2026 and 2030?

    • USD 910.1 million, at a CAGR of 5.8%

  • What segmentation does the market report cover?

    • The report is segmented by Product Type (Consumables, and Analyzers), Method (Immunodiagnostics, Molecular diagnostics, and Point-of-care testing), End-user (Hospitals and clinics, Diagnostic centers, and Others) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Growing burden of respiratory infectious diseases, Limited diagnostic access across decentralized care settings

  • Who are the major players in the Pneumonia Testing Market?

    • Abbott Laboratories, Beckman Coulter Inc., Becton Dickinson and Co., Bio Rad Laboratories Inc., BioMerieux SA, Bioneer Corp., DiaSorin SpA, Eurofins Scientific SE, F. Hoffmann La Roche Ltd., Hologic Inc., Laboratory Holdings Inc., Pfizer Inc., QIAGEN N.V., Quest Diagnostics Inc., QuidelOrtho Corp., Randox Laboratories Ltd., Sd Biosensor Inc., Siemens Healthineers AG, Sonic Healthcare Ltd. and Thermo Fisher Scientific Inc.

Market Research Insights

  • The clinical diagnostic landscape is rapidly transforming as healthcare administrators prioritize evidence-based treatment selection to combat severe pulmonary infections. By integrating advanced laboratory systems, diagnostic centers have achieved a 35% improvement in turnaround time optimization, significantly accelerating therapeutic interventions.
  • Furthermore, the deployment of portable diagnostic devices in urgent care settings has decreased patient wait times by 20%, directly enhancing outpatient evaluation efficiency. This operational shift facilitates continuous respiratory disease monitoring while ensuring precise disease severity assessment for high-risk demographics.
  • Consequently, institutional supply chains are reallocating resources toward versatile diagnostic consumables, driving substantial cost reductions and streamlining comprehensive infection control management across specialized medical environments.

We can help! Our analysts can customize this pneumonia testing market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Product Type
Executive Summary - Chart on Market Segmentation by Method
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Pneumonia Testing Market 2020 - 2024

Historic Market Size - Data Table on Global Pneumonia Testing Market 2020 - 2024 ($ million)

5.2 Product Type segment analysis 2020 - 2024

Historic Market Size - Product Type Segment 2020 - 2024 ($ million)

5.3 Method segment analysis 2020 - 2024

Historic Market Size - Method Segment 2020 - 2024 ($ million)

5.4 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global pneumonia testing market

6.2 Impact of geopolitical conflicts on global pneumonia testing market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Product Type

8.1 Market segments

Chart on Product Type - Market share 2025-2030 (%)
Data Table on Product Type - Market share 2025-2030 (%)

8.2 Comparison by Product Type

Chart on Comparison by Product Type
Data Table on Comparison by Product Type

8.3 Consumables - Market size and forecast 2025-2030

Chart on Consumables - Market size and forecast 2025-2030 ($ million)
Data Table on Consumables - Market size and forecast 2025-2030 ($ million)
Chart on Consumables - Year-over-year growth 2025-2030 (%)
Data Table on Consumables - Year-over-year growth 2025-2030 (%)

8.4 Analyzers - Market size and forecast 2025-2030

Chart on Analyzers - Market size and forecast 2025-2030 ($ million)
Data Table on Analyzers - Market size and forecast 2025-2030 ($ million)
Chart on Analyzers - Year-over-year growth 2025-2030 (%)
Data Table on Analyzers - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Product Type

Market opportunity by Product Type ($ million)
Data Table on Market opportunity by Product Type ($ million)

9. Market Segmentation by Method

9.1 Market segments

Chart on Method - Market share 2025-2030 (%)
Data Table on Method - Market share 2025-2030 (%)

9.2 Comparison by Method

Chart on Comparison by Method
Data Table on Comparison by Method

9.3 Immunodiagnostics - Market size and forecast 2025-2030

Chart on Immunodiagnostics - Market size and forecast 2025-2030 ($ million)
Data Table on Immunodiagnostics - Market size and forecast 2025-2030 ($ million)
Chart on Immunodiagnostics - Year-over-year growth 2025-2030 (%)
Data Table on Immunodiagnostics - Year-over-year growth 2025-2030 (%)

9.4 Molecular diagnostics - Market size and forecast 2025-2030

Chart on Molecular diagnostics - Market size and forecast 2025-2030 ($ million)
Data Table on Molecular diagnostics - Market size and forecast 2025-2030 ($ million)
Chart on Molecular diagnostics - Year-over-year growth 2025-2030 (%)
Data Table on Molecular diagnostics - Year-over-year growth 2025-2030 (%)

9.5 Point-of-care testing - Market size and forecast 2025-2030

Chart on Point-of-care testing - Market size and forecast 2025-2030 ($ million)
Data Table on Point-of-care testing - Market size and forecast 2025-2030 ($ million)
Chart on Point-of-care testing - Year-over-year growth 2025-2030 (%)
Data Table on Point-of-care testing - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by Method

Market opportunity by Method ($ million)
Data Table on Market opportunity by Method ($ million)

10. Market Segmentation by End-user

10.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

10.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

10.3 Hospitals and clinics - Market size and forecast 2025-2030

Chart on Hospitals and clinics - Market size and forecast 2025-2030 ($ million)
Data Table on Hospitals and clinics - Market size and forecast 2025-2030 ($ million)
Chart on Hospitals and clinics - Year-over-year growth 2025-2030 (%)
Data Table on Hospitals and clinics - Year-over-year growth 2025-2030 (%)

10.4 Diagnostic centers - Market size and forecast 2025-2030

Chart on Diagnostic centers - Market size and forecast 2025-2030 ($ million)
Data Table on Diagnostic centers - Market size and forecast 2025-2030 ($ million)
Chart on Diagnostic centers - Year-over-year growth 2025-2030 (%)
Data Table on Diagnostic centers - Year-over-year growth 2025-2030 (%)

10.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ million)
Data Table on Asia - Market size and forecast 2025-2030 ($ million)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.5.6 Thailand - Market size and forecast 2025-2030

Chart on Thailand - Market size and forecast 2025-2030 ($ million)
Data Table on Thailand - Market size and forecast 2025-2030 ($ million)
Chart on Thailand - Year-over-year growth 2025-2030 (%)
Data Table on Thailand - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.3 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.5 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.6 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.6.7 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.8 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Growing burden of respiratory infectious diseases
Advancing molecular diagnostic technology capabilities
Increasing emphasis on antimicrobial stewardship and clinical outcome improvement

13.2 Market challenges

Limited diagnostic access across decentralized care settings
Complex reimbursement and regulatory requirements
Diagnostic interpretation challenges and clinical workflow integration

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Increasing adoption of multiplex respiratory testing panels
Advancing development of rapid direct-from-specimen diagnostic solutions
Expanding collaboration between diagnostic developers and healthcare institutions

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Abbott Laboratories

Abbott Laboratories - Overview
Abbott Laboratories - Business segments
Abbott Laboratories - Key news
Abbott Laboratories - Key offerings
Abbott Laboratories - Segment focus
SWOT

15.5 Becton Dickinson and Co.

Becton Dickinson and Co. - Overview
Becton Dickinson and Co. - Business segments
Becton Dickinson and Co. - Key news
Becton Dickinson and Co. - Key offerings
Becton Dickinson and Co. - Segment focus
SWOT

15.6 Bio Rad Laboratories Inc.

Bio Rad Laboratories Inc. - Overview
Bio Rad Laboratories Inc. - Business segments
Bio Rad Laboratories Inc. - Key news
Bio Rad Laboratories Inc. - Key offerings
Bio Rad Laboratories Inc. - Segment focus
SWOT

15.7 BioMerieux SA

BioMerieux SA - Overview
BioMerieux SA - Business segments
BioMerieux SA - Key offerings
BioMerieux SA - Segment focus
SWOT

15.8 Bioneer Corp.

Bioneer Corp. - Overview
Bioneer Corp. - Product / Service
Bioneer Corp. - Key offerings
SWOT

15.9 DiaSorin SpA

DiaSorin SpA - Overview
DiaSorin SpA - Business segments
DiaSorin SpA - Key news
DiaSorin SpA - Key offerings
DiaSorin SpA - Segment focus
SWOT

15.10 F. Hoffmann La Roche Ltd.

F. Hoffmann La Roche Ltd. - Overview
F. Hoffmann La Roche Ltd. - Business segments
F. Hoffmann La Roche Ltd. - Key news
F. Hoffmann La Roche Ltd. - Key offerings
F. Hoffmann La Roche Ltd. - Segment focus
SWOT

15.11 Pfizer Inc.

Pfizer Inc. - Overview
Pfizer Inc. - Business segments
Pfizer Inc. - Key news
Pfizer Inc. - Key offerings
Pfizer Inc. - Segment focus
SWOT

15.12 QIAGEN N.V.

QIAGEN N.V. - Overview
QIAGEN N.V. - Product / Service
QIAGEN N.V. - Key offerings
SWOT

15.13 Quest Diagnostics Inc.

Quest Diagnostics Inc. - Overview
Quest Diagnostics Inc. - Business segments
Quest Diagnostics Inc. - Key offerings
Quest Diagnostics Inc. - Segment focus
SWOT

15.14 QuidelOrtho Corp.

QuidelOrtho Corp. - Overview
QuidelOrtho Corp. - Business segments
QuidelOrtho Corp. - Key offerings
QuidelOrtho Corp. - Segment focus
SWOT

15.15 Sd Biosensor Inc.

Sd Biosensor Inc. - Overview
Sd Biosensor Inc. - Product / Service
Sd Biosensor Inc. - Key offerings
SWOT

15.16 Siemens Healthineers AG

Siemens Healthineers AG - Overview
Siemens Healthineers AG - Business segments
Siemens Healthineers AG - Key offerings
Siemens Healthineers AG - Segment focus
SWOT

15.17 Sonic Healthcare Ltd.

Sonic Healthcare Ltd. - Overview
Sonic Healthcare Ltd. - Business segments
Sonic Healthcare Ltd. - Key offerings
Sonic Healthcare Ltd. - Segment focus
SWOT

15.18 Thermo Fisher Scientific Inc.

Thermo Fisher Scientific Inc. - Overview
Thermo Fisher Scientific Inc. - Business segments
Thermo Fisher Scientific Inc. - Key news
Thermo Fisher Scientific Inc. - Key offerings
Thermo Fisher Scientific Inc. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Pneumonia Testing market growth will increase by USD 910.1 million during 2026-2030.

The Pneumonia Testing market is expected to grow at a CAGR of 5.8% during 2026-2030.

Pneumonia Testing market is segmented by Product type (Consumables, Analyzers) Method (Immunodiagnostics, Molecular diagnostics, Point-of-care testing) End-user (Hospitals and clinics, Diagnostic centers, Others)

Abbott Laboratories, Beckman Coulter Inc., Becton Dickinson and Co., Bio Rad Laboratories Inc., BioMerieux SA, Bioneer Corp., DiaSorin SpA, Eurofins Scientific SE, F. Hoffmann La Roche Ltd., Hologic Inc., Laboratory Holdings Inc., Pfizer Inc., QIAGEN N.V., Quest Diagnostics Inc., QuidelOrtho Corp., Randox Laboratories Ltd., Sd Biosensor Inc., Siemens Healthineers AG, Sonic Healthcare Ltd., Thermo Fisher Scientific Inc. are a few of the key vendors in the Pneumonia Testing market.

North America will register the highest growth rate of 36.9% among the other regions. Therefore, the Pneumonia Testing market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Indonesia, Thailand, Brazil, Saudi Arabia, UAE, Turkey, Argentina, Colombia, South Africa, Israel

  • Growing burden of respiratory infectious diseases is the driving factor this market.

The Pneumonia Testing market vendors should focus on grabbing business opportunities from the Product type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
