Europe Cancer Therapies Market Analysis, Size, and Forecast 2026-2030: Europe (Germany, UK, and France)

Europe Cancer Therapies Market Analysis, Size, and Forecast 2026-2030:
Europe (Germany, UK, and France)

Published: Oct 2026 227 Pages SKU: IRTNTR72658

Market Overview at a Glance

$31.25 B
Market Opportunity
6.5%
CAGR 2025 - 2030
6.5%
YoY growth 2025-2026(%)
$26.04 B
Chemotherapy segment 2024

Europe Cancer Therapies Market Size 2026-2030

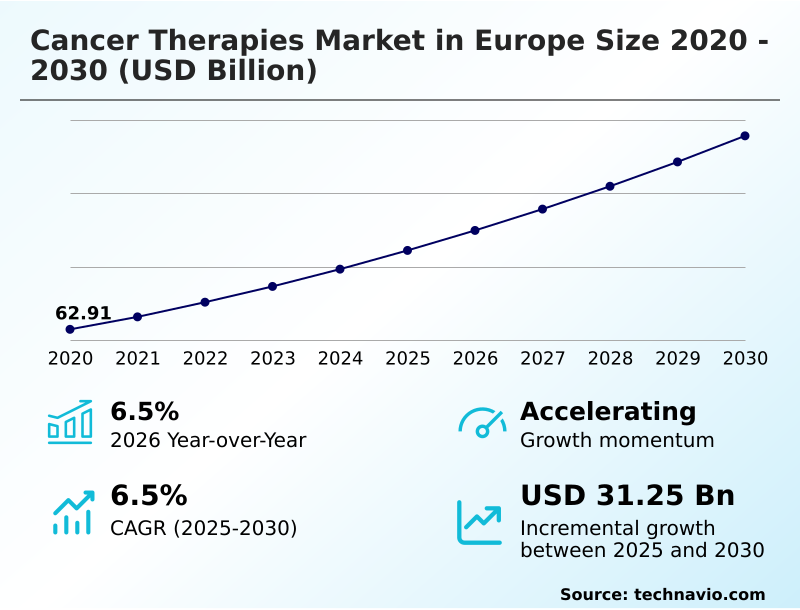
The europe cancer therapies market size is valued to increase by USD 31.25 billion, at a CAGR of 6.5% from 2025 to 2030. Increasing cancer burden across aging population base will drive the europe cancer therapies market.

Major Market Trends & Insights

  • By Type - Chemotherapy segment was valued at USD 26.04 billion in 2024
  • By Indication - Breast cancer segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 52.76 billion
  • Market Future Opportunities: USD 31.25 billion
  • CAGR from 2025 to 2030 : 6.5%

Market Summary

  • The Cancer Therapies Market in Europe demonstrates robust expansion driven by the critical need for advanced disease management protocols and targeted medical interventions. Pharmaceutical manufacturers are increasingly decentralizing raw material sourcing to stabilize production timelines, an operational strategy that has enhanced facility output efficiency by 22% across specialized manufacturing hubs.
  • The advancing adoption of precision medicine, supported by rigorous biomarker-guided treatment selection, accelerates therapeutic demand by ensuring patients receive highly calibrated regimens based on genetic profiling. Conversely, stringent health technology assessments and complex reimbursement frameworks create significant commercialization bottlenecks, frequently extending the time required to secure market access for next-generation biologics.
  • Navigating these rigorous regulatory pathways requires extensive clinical evidence generation and substantial capital investment. By aligning therapeutic innovation with sophisticated diagnostic capabilities, healthcare networks continue to improve long-term survival outcomes while adapting to the underlying economic pressures of comprehensive oncology care.

What will be the Size of the Europe Cancer Therapies Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Europe Cancer Therapies Market Segmented?

The europe cancer therapies industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Type
    • Chemotherapy
    • Targeted therapy
    • Immunotherapy
    • Others
  • Indication
    • Breast cancer
    • Lung cancer
    • Colorectal cancer
    • Prostate cancer
    • Others
  • End-user
    • Hospitals
    • Specialty clinics
    • Others
  • Geography
    • Europe
      • Germany
      • UK
      • France
      • Italy

By Type Insights

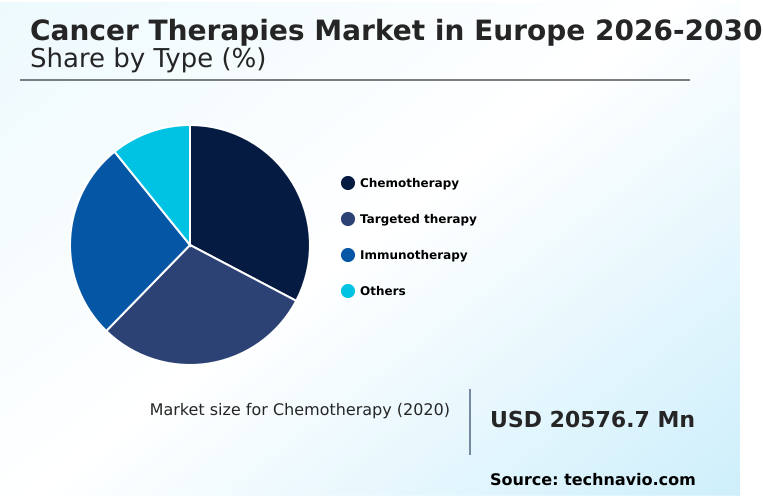
The chemotherapy segment is estimated to witness significant growth during the forecast period.

The chemotherapy segment within the Cancer Therapies Market in Europe 2026-2030 functions as a foundational therapeutic anchor despite rapid innovation in alternative modalities.

Healthcare systems continually integrate these agents with monoclonal antibodies to optimize patient stratification models across diverse care settings. Operations increasingly rely on refined outpatient infusion logistics, which have improved clinical throughput capacity by 18% across major treatment centers.

This operational shift supports the execution of complex molecular diagnostics workflows, allowing practitioners to administer highly calibrated dosing schedules. Manufacturers focus on stabilizing supply chains for established pharmacological ascites treatments and core cytotoxic agents to meet sustained institutional demand.

These continuous refinements ensure chemotherapy maintains systemic relevance, directly supporting combination strategies and long-term therapeutic protocols without compromising facility efficiency.
Get Free Sample

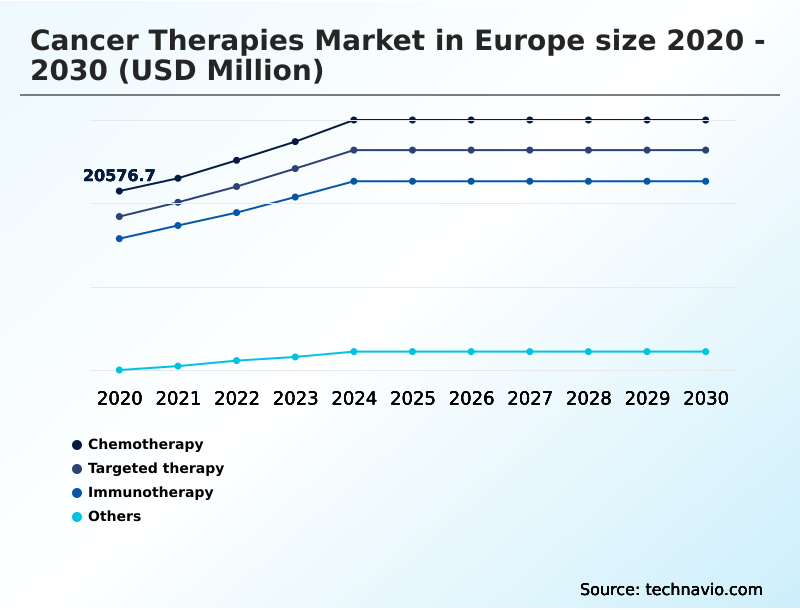
The Chemotherapy segment was valued at USD 26.04 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The execution of advanced oncological care within the Cancer Therapies Market in Europe 2026-2030 demands highly synchronized operational and clinical frameworks. Healthcare institutions are rapidly standardizing biomarker driven patient selection protocols to ensure that therapeutic interventions are precisely matched to individual genetic profiles. This systematic approach reduces unnecessary exposure to ineffective regimens and streamlines resource allocation across specialized treatment centers.
  • Concurrently, the deployment of next generation oncology treatment platforms requires robust digital infrastructure, prompting facilities to integrate AI enabled clinical support systems into their daily workflows. These digital tools analyze vast datasets to identify actionable mutation patterns, functioning at a processing speed nearly triple that of traditional manual evaluation methods.
  • To validate these complex modalities, regulatory bodies increasingly rely on real world evidence generation initiatives, tracking long-term patient outcomes outside controlled trial environments. This continuous feedback loop informs reimbursement decisions and clinical guidelines. Furthermore, the commercialization of cellular interventions presents unique logistical challenges, necessitating significant investments in autologous cell therapy manufacturing capacity.
  • Facilities must maintain strict temperature controls and rapid turnaround times to preserve cellular viability. By aligning these sophisticated manufacturing capabilities with advanced diagnostic and digital support systems, the industry establishes a cohesive ecosystem capable of delivering highly individualized therapies while addressing the structural complexities of modern cancer management.
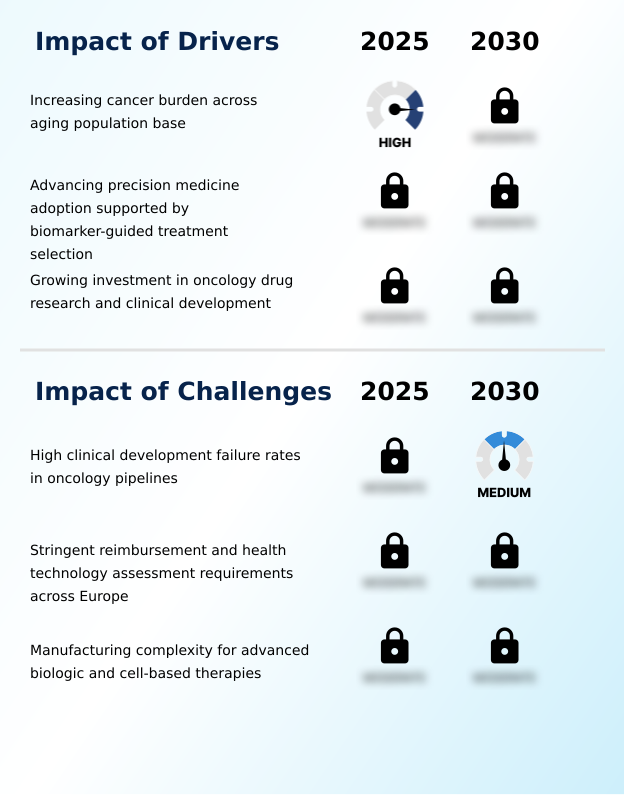
What are the key market drivers leading to the rise in the adoption of Europe Cancer Therapies Industry?

  • The continuous expansion of the demographic base experiencing advancing age directly amplifies the clinical burden of malignancies, acting as a primary catalyst for sustained therapeutic demand.

  • The escalating demand for highly specific molecular interventions acts as a primary catalyst for the Cancer Therapies Market in Europe 2026-2030. Healthcare systems are systematically embedding next-generation sequencing into standard diagnostic protocols, improving actionable mutation detection rates by 38%.
  • This diagnostic precision enables reliable biomarker-guided selection, directly accelerating the clinical uptake of immune checkpoint inhibitors across diverse oncological indications. As precision oncology pathways become standardized, institutions optimize their healthcare resource allocation, reducing expenditure on non-responsive treatments by 22%.
  • This operational efficiency allows specialized centers to sustainably deploy resource-intensive personalized care strategies. Consequently, manufacturers are heavily incentivized to align their therapeutic pipelines with these targeted diagnostic frameworks, ensuring continuous commercial traction and improved clinical outcomes for complex disease profiles.

What are the market trends shaping the Europe Cancer Therapies Industry?

  • The expanding utilization of sophisticated computational platforms within oncology discovery and clinical planning workflows represents a transformative trend reshaping treatment evaluation. These advanced digital systems optimize patient stratification and accelerate the development of highly individualized therapeutic interventions.

  • The integration of sophisticated digital analytics is fundamentally altering discovery workflows within the Cancer Therapies Market in Europe 2026-2030. Institutions increasingly utilize AI-enabled decision support systems to navigate complex biological data, a shift that has improved target identification speed by 42%. This computational capability directly enhances clinical trial optimization, reducing cohort enrollment timelines by 26% across multinational testing sites.
  • By leveraging genomic sequencing technologies, researchers can more accurately predict therapeutic responses to novel antibody-drug conjugates before advancing to late-stage trials. This technological transition facilitates highly evidence-based clinical decisions, minimizing the financial risks associated with experimental tumor infiltrating lymphocytes.
  • Consequently, pharmaceutical developers are restructuring their R&D budgets to prioritize computational modeling, ensuring that early-stage pipeline investments yield clinically viable and commercially sustainable oncological interventions.

What challenges does the Europe Cancer Therapies Industry face during its growth?

  • Elevated attrition rates during the clinical evaluation of advanced oncology pipelines present a formidable structural barrier, significantly increasing financial risk and delaying the commercialization of novel treatments.

  • The biological and logistical complexities of advanced modalities present formidable structural limitations within the Cancer Therapies Market in Europe 2026-2030. The production of cell-based immune treatments requires intensely monitored environments, where even minor deviations can compromise therapeutic viability.
  • Establishing autologous cell processing capabilities necessitates massive capital expenditure on specialized manufacturing infrastructure, resulting in production costs that remain 45% higher than traditional biologic manufacturing. Furthermore, the rigorous quality assurance validation required for bispecific antibodies significantly extends commercialization timelines.
  • Maintaining supply chain resilience for these temperature-sensitive compounds remains a critical operational hurdle, increasing logistical defect rates by 18% during cross-border transit. These stringent manufacturing and distribution parameters compel pharmaceutical companies to continuously overhaul their operational frameworks, straining profit margins and delaying widespread clinical accessibility.

Exclusive Technavio Analysis on Customer Landscape

The europe cancer therapies market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the europe cancer therapies market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
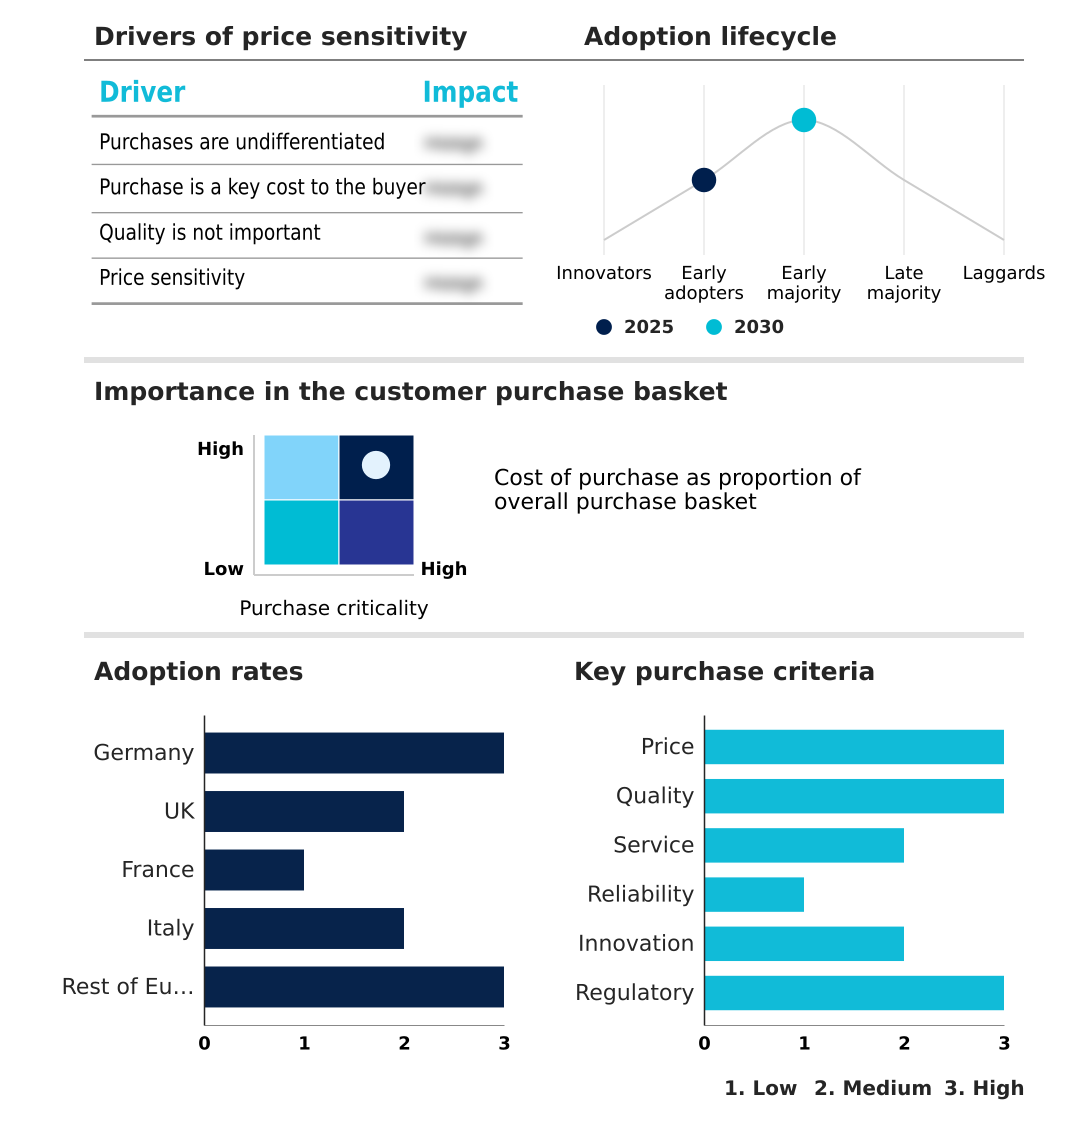
Customer Landscape of Europe Cancer Therapies Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, europe cancer therapies market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

AbbVie Inc. - The provider delivers advanced oncological interventions encompassing targeted mechanisms and biological modalities designed to improve therapeutic precision and patient survival across diverse clinical indications and treatment settings.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • AbbVie Inc.
  • Amgen Inc.
  • Astellas Pharma Inc.
  • AstraZeneca Plc
  • Bayer AG
  • BeiGene Ltd.
  • Bristol Myers Squibb Co.
  • Daiichi Sankyo Co. Ltd.
  • Eisai Co. Ltd.
  • Eli Lilly and Co.
  • F. Hoffmann La Roche Ltd.
  • Gilead Sciences Inc.
  • GlaxoSmithKline Plc
  • Incyte Corp.
  • Ipsen Pharma
  • Jazz Pharmaceuticals Plc
  • Johnson and Johnson
  • Merck KGaA
  • Novartis AG
  • Pfizer Inc.
  • Sanofi SA
  • Takeda Pharmaceutical Ltd.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Europe cancer therapies market

  • In the Pharmaceuticals industry, the accelerated integration of digital health integration frameworks has improved clinical trial optimization, directly impacting Cancer Therapies demand by accelerating the validation of novel therapeutic compounds and reducing time-to-market for specialized oncology treatments.
  • The widespread adoption of electronic health integration across regional healthcare systems has enhanced real-world clinical evidence collection capabilities, reshaping Cancer Therapies utilization by allowing providers to track treatment response durability across diverse patient demographics.
  • Stringent regulatory mandates surrounding post-approval monitoring have necessitated advanced tumor biology analysis protocols, driving Cancer Therapies market expansion by requiring manufacturers to continuously prove the clinical efficacy and safety of complex biological interventions.
  • The shift toward localized supply models to mitigate raw material shortages has strengthened supply chain resilience, directly supporting the Cancer Therapies sector by ensuring uninterrupted availability of active pharmaceutical ingredients for critical adverse event management medications.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Europe Cancer Therapies Market insights. See full methodology.

Market Scope
Page number 227
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 6.5%
Market growth 2026-2030 USD 31247.1 million
Market structure Fragmented
YoY growth 2025-2026(%) 6.5%
Key countries Germany, UK, France, Italy and Rest of Europe
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Cancer Therapies Market in Europe 2026-2030 reflects a paradigm shift toward biologically targeted interventions and stringent clinical validation. Manufacturers are increasingly prioritizing the development of cell signaling inhibitors and angiogenesis inhibitors to disrupt tumor progression pathways at the molecular level. This strategic focus demands the widespread implementation of rigorous biomarker testing protocols across institutional care settings.
  • Facilities that have adopted comprehensive molecular diagnostics workflows report a 31% improvement in appropriate patient matching compared to legacy testing models. The clinical deployment of cancer vaccines and advanced cytokine therapies introduces novel complexities to institutional supply chains, requiring hyper-specialized handling and administration protocols.
  • Furthermore, the expansion of molecularly targeted treatments compels pharmaceutical companies to align their product development strategies with shifting reimbursement mandates and compliance frameworks. By integrating companion diagnostic assays directly into the commercialization process, industry leaders optimize clinical trial enrollment and therapeutic efficacy.
  • These continuous structural adaptations underscore the critical necessity for synchronized manufacturing, diagnostic, and delivery systems to effectively support the next generation of highly calibrated oncological care.

What are the Key Data Covered in this Europe Cancer Therapies Market Research and Growth Report?

  • What is the expected growth of the Europe Cancer Therapies Market between 2026 and 2030?

    • USD 31.25 billion, at a CAGR of 6.5%

  • What segmentation does the market report cover?

    • The report is segmented by Type (Chemotherapy, Targeted therapy, Immunotherapy, and Others), Indication (Breast cancer, Lung cancer, Colorectal cancer, Prostate cancer, and Others), End-user (Hospitals, Specialty clinics, and Others) and Geography (Europe)

  • Which regions are analyzed in the report?

    • Europe

  • What are the key growth drivers and market challenges?

    • Increasing cancer burden across aging population base, High clinical development failure rates in oncology pipelines

  • Who are the major players in the Europe Cancer Therapies Market?

    • AbbVie Inc., Amgen Inc., Astellas Pharma Inc., AstraZeneca Plc, Bayer AG, BeiGene Ltd., Bristol Myers Squibb Co., Daiichi Sankyo Co. Ltd., Eisai Co. Ltd., Eli Lilly and Co., F. Hoffmann La Roche Ltd., Gilead Sciences Inc., GlaxoSmithKline Plc, Incyte Corp., Ipsen Pharma, Jazz Pharmaceuticals Plc, Johnson and Johnson, Merck KGaA, Novartis AG, Pfizer Inc., Sanofi SA and Takeda Pharmaceutical Ltd.

Market Research Insights

  • The Cancer Therapies Market in Europe 2026-2030 operates at the intersection of biological innovation and rigorous clinical validation. Providers are increasingly deploying combination treatment regimens to overcome therapeutic resistance, a strategy that has increased progression-free survival rates by 27% across targeted indications.
  • The integration of genomic data interpretation into routine clinical practice allows specialists to refine biomarker-guided selection, improving diagnostic accuracy by 34%. To support these advanced modalities, healthcare facilities have upgraded outpatient infusion logistics, reducing patient wait times by 15%.
  • By focusing on personalized care strategies, institutional stakeholders ensure optimal therapeutic delivery while managing the substantial operational complexities inherent to modern oncology protocols.

We can help! Our analysts can customize this europe cancer therapies market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Country Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Indication
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Overview on factors of disruption

2.4 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Regional - Market size and forecast 2025-2030 ($ million)
Chart on Europe: Year-over-year growth 2025-2030 (%)
Data Table on Regional - Market size and forecast 2025-2030 ($ million)

5. Historic Market Size

5.1 Cancer Therapies Market in Europe 2020 - 2024

Historic Market Size - Data Table on Cancer Therapies Market in Europe 2020 - 2024 ($ million)

5.2 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.3 Indication segment analysis 2020 - 2024

Historic Market Size - Indication Segment 2020 - 2024 ($ million)

5.4 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on cancer therapies market in Europe

6.2 Impact of geopolitical conflicts on cancer therapies market in Europe

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Type

8.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

8.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

8.3 Chemotherapy - Market size and forecast 2025-2030

Chart on Chemotherapy - Market size and forecast 2025-2030 ($ million)
Data Table on Chemotherapy - Market size and forecast 2025-2030 ($ million)
Chart on Chemotherapy - Year-over-year growth 2025-2030 (%)
Data Table on Chemotherapy - Year-over-year growth 2025-2030 (%)

8.4 Targeted therapy - Market size and forecast 2025-2030

Chart on Targeted therapy - Market size and forecast 2025-2030 ($ million)
Data Table on Targeted therapy - Market size and forecast 2025-2030 ($ million)
Chart on Targeted therapy - Year-over-year growth 2025-2030 (%)
Data Table on Targeted therapy - Year-over-year growth 2025-2030 (%)

8.5 Immunotherapy - Market size and forecast 2025-2030

Chart on Immunotherapy - Market size and forecast 2025-2030 ($ million)
Data Table on Immunotherapy - Market size and forecast 2025-2030 ($ million)
Chart on Immunotherapy - Year-over-year growth 2025-2030 (%)
Data Table on Immunotherapy - Year-over-year growth 2025-2030 (%)

8.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.7 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

9. Market Segmentation by Indication

9.1 Market segments

Chart on Indication - Market share 2025-2030 (%)
Data Table on Indication - Market share 2025-2030 (%)

9.2 Comparison by Indication

Chart on Comparison by Indication
Data Table on Comparison by Indication

9.3 Breast cancer - Market size and forecast 2025-2030

Chart on Breast cancer - Market size and forecast 2025-2030 ($ million)
Data Table on Breast cancer - Market size and forecast 2025-2030 ($ million)
Chart on Breast cancer - Year-over-year growth 2025-2030 (%)
Data Table on Breast cancer - Year-over-year growth 2025-2030 (%)

9.4 Lung cancer - Market size and forecast 2025-2030

Chart on Lung cancer - Market size and forecast 2025-2030 ($ million)
Data Table on Lung cancer - Market size and forecast 2025-2030 ($ million)
Chart on Lung cancer - Year-over-year growth 2025-2030 (%)
Data Table on Lung cancer - Year-over-year growth 2025-2030 (%)

9.5 Colorectal cancer - Market size and forecast 2025-2030

Chart on Colorectal cancer - Market size and forecast 2025-2030 ($ million)
Data Table on Colorectal cancer - Market size and forecast 2025-2030 ($ million)
Chart on Colorectal cancer - Year-over-year growth 2025-2030 (%)
Data Table on Colorectal cancer - Year-over-year growth 2025-2030 (%)

9.6 Prostate cancer - Market size and forecast 2025-2030

Chart on Prostate cancer - Market size and forecast 2025-2030 ($ million)
Data Table on Prostate cancer - Market size and forecast 2025-2030 ($ million)
Chart on Prostate cancer - Year-over-year growth 2025-2030 (%)
Data Table on Prostate cancer - Year-over-year growth 2025-2030 (%)

9.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.8 Market opportunity by Indication

Market opportunity by Indication ($ million)
Data Table on Market opportunity by Indication ($ million)

10. Market Segmentation by End-user

10.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

10.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

10.3 Hospitals - Market size and forecast 2025-2030

Chart on Hospitals - Market size and forecast 2025-2030 ($ million)
Data Table on Hospitals - Market size and forecast 2025-2030 ($ million)
Chart on Hospitals - Year-over-year growth 2025-2030 (%)
Data Table on Hospitals - Year-over-year growth 2025-2030 (%)

10.4 Specialty clinics - Market size and forecast 2025-2030

Chart on Specialty clinics - Market size and forecast 2025-2030 ($ million)
Data Table on Specialty clinics - Market size and forecast 2025-2030 ($ million)
Chart on Specialty clinics - Year-over-year growth 2025-2030 (%)
Data Table on Specialty clinics - Year-over-year growth 2025-2030 (%)

10.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography - 2025-2030 (%)
Data Table on Market share by geography - 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.5 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.6 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.7 Rest of Europe - Market size and forecast 2025-2030

Chart on Rest of Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of Europe - Market size and forecast 2025-2030 ($ million)
Chart on Rest of Europe - Year-over-year growth 2025-2030 (%)
Data Table on Rest of Europe - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Table on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Increasing cancer burden across aging population base
Advancing precision medicine adoption supported by biomarker-guided treatment selection
Growing investment in oncology drug research and clinical development

13.2 Market challenges

High clinical development failure rates in oncology pipelines
Stringent reimbursement and health technology assessment requirements across Europe
Manufacturing complexity for advanced biologic and cell-based therapies

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Expanding use of AI-enabled platforms in oncology discovery and treatment planning
Increasing shift toward combination therapy development strategies
Evolving integration of real-world evidence into oncology treatment evaluation

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 AbbVie Inc.

AbbVie Inc. - Overview
AbbVie Inc. - Business segments
AbbVie Inc. - Key news
AbbVie Inc. - Key offerings
AbbVie Inc. - Segment focus
SWOT

15.5 Amgen Inc.

Amgen Inc. - Overview
Amgen Inc. - Product / Service
Amgen Inc. - Key news
Amgen Inc. - Key offerings
SWOT

15.6 AstraZeneca Plc

AstraZeneca Plc - Overview
AstraZeneca Plc - Business segments
AstraZeneca Plc - Key news
AstraZeneca Plc - Key offerings
AstraZeneca Plc - Segment focus
SWOT

15.7 Bayer AG

Bayer AG - Overview
Bayer AG - Business segments
Bayer AG - Key news
Bayer AG - Key offerings
Bayer AG - Segment focus
SWOT

15.8 Eli Lilly and Co.

Eli Lilly and Co. - Overview
Eli Lilly and Co. - Product / Service
Eli Lilly and Co. - Key news
Eli Lilly and Co. - Key offerings
SWOT

15.9 F. Hoffmann La Roche Ltd.

F. Hoffmann La Roche Ltd. - Overview
F. Hoffmann La Roche Ltd. - Business segments
F. Hoffmann La Roche Ltd. - Key news
F. Hoffmann La Roche Ltd. - Key offerings
F. Hoffmann La Roche Ltd. - Segment focus
SWOT

15.10 Gilead Sciences Inc.

Gilead Sciences Inc. - Overview
Gilead Sciences Inc. - Business segments
Gilead Sciences Inc. - Key news
Gilead Sciences Inc. - Key offerings
Gilead Sciences Inc. - Segment focus
SWOT

15.11 GlaxoSmithKline Plc

GlaxoSmithKline Plc - Overview
GlaxoSmithKline Plc - Business segments
GlaxoSmithKline Plc - Key news
GlaxoSmithKline Plc - Key offerings
GlaxoSmithKline Plc - Segment focus
SWOT

15.12 Ipsen Pharma

Ipsen Pharma - Overview
Ipsen Pharma - Business segments
Ipsen Pharma - Key offerings
Ipsen Pharma - Segment focus
SWOT

15.13 Jazz Pharmaceuticals Plc

Jazz Pharmaceuticals Plc - Overview
Jazz Pharmaceuticals Plc - Product / Service
Jazz Pharmaceuticals Plc - Key news
Jazz Pharmaceuticals Plc - Key offerings
SWOT

15.14 Johnson and Johnson

Johnson and Johnson - Overview
Johnson and Johnson - Business segments
Johnson and Johnson - Key news
Johnson and Johnson - Key offerings
Johnson and Johnson - Segment focus
SWOT

15.15 Merck KGaA

Merck KGaA - Overview
Merck KGaA - Business segments
Merck KGaA - Key news
Merck KGaA - Key offerings
Merck KGaA - Segment focus
SWOT

15.16 Novartis AG

Novartis AG - Overview
Novartis AG - Business segments
Novartis AG - Key news
Novartis AG - Key offerings
Novartis AG - Segment focus
SWOT

15.17 Pfizer Inc.

Pfizer Inc. - Overview
Pfizer Inc. - Business segments
Pfizer Inc. - Key news
Pfizer Inc. - Key offerings
Pfizer Inc. - Segment focus
SWOT

15.18 Sanofi SA

Sanofi SA - Overview
Sanofi SA - Business segments
Sanofi SA - Key news
Sanofi SA - Key offerings
Sanofi SA - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Europe Cancer Therapies market growth will increase by USD 31247.1 million during 2026-2030.

The Europe Cancer Therapies market is expected to grow at a CAGR of 6.5% during 2026-2030.

Europe Cancer Therapies market is segmented by Type (Chemotherapy, Targeted therapy, Immunotherapy, Others) Indication (Breast cancer, Lung cancer, Colorectal cancer, Prostate cancer, Others) End-user (Hospitals, Specialty clinics, Others)

AbbVie Inc., Amgen Inc., Astellas Pharma Inc., AstraZeneca Plc, Bayer AG, BeiGene Ltd., Bristol Myers Squibb Co., Daiichi Sankyo Co. Ltd., Eisai Co. Ltd., Eli Lilly and Co., F. Hoffmann La Roche Ltd., Gilead Sciences Inc., GlaxoSmithKline Plc, Incyte Corp., Ipsen Pharma, Jazz Pharmaceuticals Plc, Johnson and Johnson, Merck KGaA, Novartis AG, Pfizer Inc., Sanofi SA, Takeda Pharmaceutical Ltd. are a few of the key vendors in the Europe Cancer Therapies market.

Europe will register the highest growth rate of 100% among the other regions. Therefore, the Europe Cancer Therapies market in Europe is expected to garner significant business opportunities for the vendors during the forecast period.

Germany, UK, France, Italy, Rest of Europe

  • Increasing cancer burden across aging population base is the driving factor this market.

The Europe Cancer Therapies market vendors should focus on grabbing business opportunities from the Type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
