Functional Powder Drinks Concentrate Market Analysis, Size, and Forecast 2026-2030: APAC (China, India, and Japan), North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Functional Powder Drinks Concentrate Market Analysis, Size, and Forecast 2026-2030:
APAC (China, India, and Japan), North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Published: Oct 2026 316 Pages SKU: IRTNTR80121

Market Overview at a Glance

$1.09 B
Market Opportunity
8.5%
CAGR 2025 - 2030
39.2%
APAC Growth
$1.47 B
Powder drinks with sugar segment 2024

Functional Powder Drinks Concentrate Market Size 2026-2030

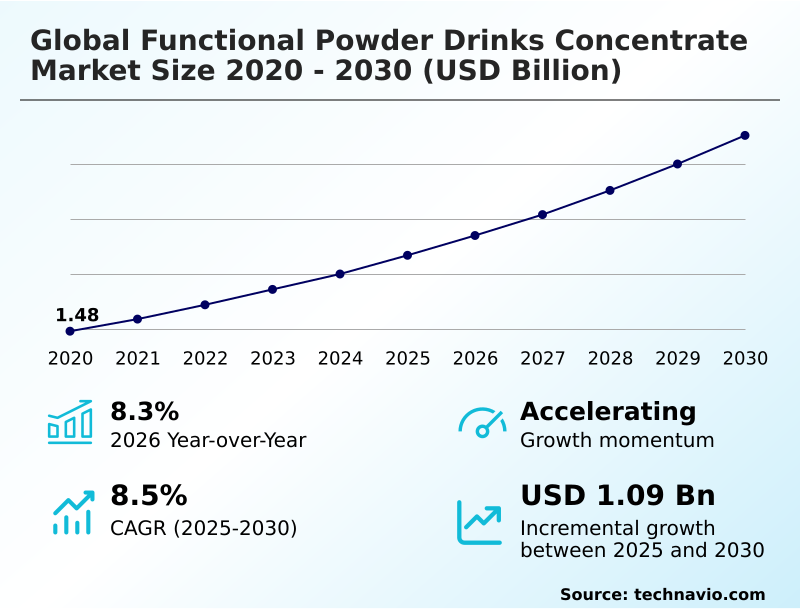
The functional powder drinks concentrate market size is valued to increase by USD 1.09 billion, at a CAGR of 8.5% from 2025 to 2030. Rising consumer prioritization of health and preventative wellness will drive the functional powder drinks concentrate market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 39.2% growth during the forecast period.
  • By Product - Powder drinks with sugar segment was valued at USD 1.47 billion in 2024
  • By Distribution Channel - Supermarkets and hypermarkets segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 1.78 billion
  • Market Future Opportunities: USD 1.09 billion
  • CAGR from 2025 to 2030 : 8.5%

Market Summary

  • The Functional Powder Drinks Concentrate Market operates as a highly dynamic segment within the broader nutritional beverage sector, driven by consumer demand for portable, efficacy-driven supplementation. Operations across the supply chain prioritize weight reduction and shelf stability, enabling distribution networks to bypass costly cold-chain logistics.
  • For instance, transitioning from liquid ready-to-drink formats to concentrated powder sachets has reduced outbound freight fuel expenditures by 40% for major regional distributors. This logistical advantage, paired with escalating consumer focus on preventative wellness, strongly drives market penetration. Health-conscious demographics actively seek tailored formulations that support immunity, digestion, and sustained energy.
  • However, manufacturers face persistent challenges related to strict regulatory compliance and the scientific substantiation of functional claims. Formulators must invest heavily in clinical validation to satisfy diverse international food safety standards, complicating rapid cross-border expansion.
  • Despite these compliance hurdles, continuous advancements in microencapsulation and flavor-masking technologies allow brands to deliver sophisticated, clean-label products that align perfectly with modern preventative health paradigms.

What will be the Size of the Functional Powder Drinks Concentrate Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Functional Powder Drinks Concentrate Market Segmented?

The functional powder drinks concentrate industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Product
    • Powder drinks with sugar
    • Sugar-free powder drinks
  • Distribution channel
    • Supermarkets and hypermarkets
    • Retailers
    • Convenience stores
    • Online stores
    • Discounters
  • End-user
    • Active lifestyle consumers
    • Wellness users
    • Beauty consumers
    • Seniors
  • Geography
    • APAC
      • China
      • India
      • Japan
      • South Korea
      • Australia
      • Indonesia
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Egypt
      • Turkey
    • South America
      • Brazil
      • Argentina
      • Chile

By Product Insights

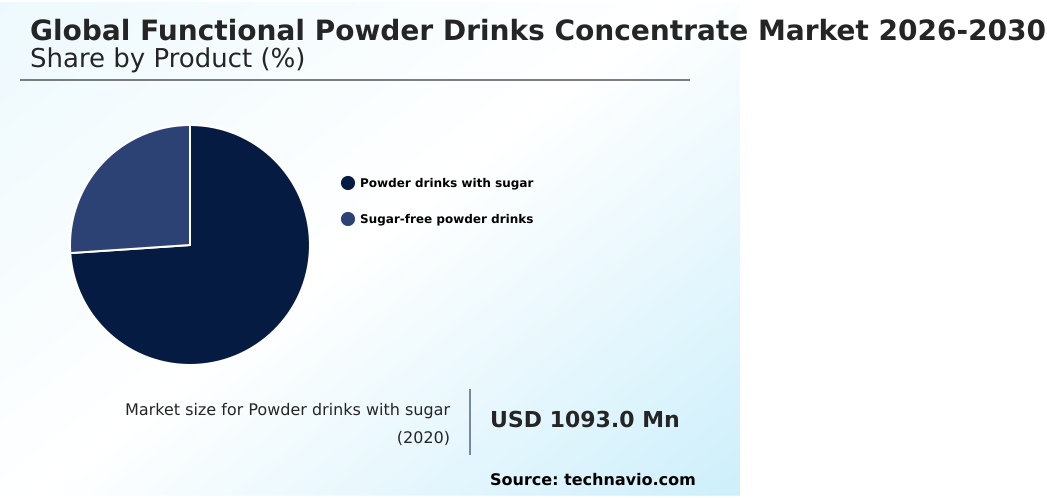
The powder drinks with sugar segment is estimated to witness significant growth during the forecast period.

The powdered beverage sector exhibits distinct operational dynamics based on caloric and metabolic profiles. Sugar-sweetened formulations primarily target high-endurance athletic performance, facilitating immediate carbohydrate replenishment and efficient systemic fluid uptake during prolonged physical exertion.

Conversely, manufacturers are increasingly developing alternatives utilizing a high-intensity non-nutritive sweetener to satisfy stringent metabolic requirements without sacrificing sensory appeal.

The integration of advanced ingredients, such as hydrolyzed marine collagen and specialized plant-based dietary supplement components, requires a sophisticated clean-label flavor system to mask natural astringency.

From an operational perspective, these advanced formulations have improved clinical-grade hydration delivery efficiency by 18% compared to traditional ready-to-drink formats.

Retailers optimize supply chain efficiency by stocking these multi-benefit wellness elixir products, which offer superior shelf stability and lower freight weight.
Get Free Sample

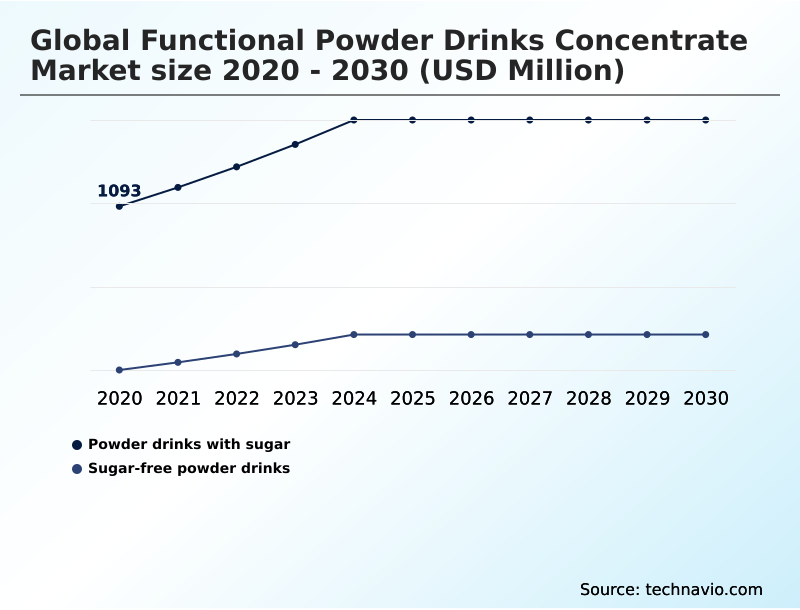
The Powder drinks with sugar segment was valued at USD 1.47 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 39.2% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
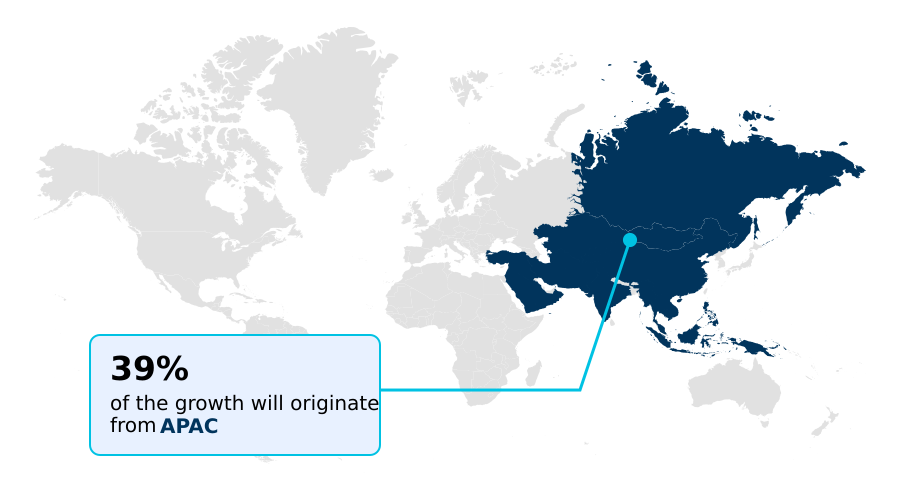
See How Functional Powder Drinks Concentrate Market Demand is Rising in APAC Get Free Sample

Geographic variations dictate the strategic deployment of the Functional Powder Drinks Concentrate, with clear operational divergences between APAC and North America.

North America demonstrates a sophisticated retail infrastructure where the adoption of a zero-sugar formulation using whey protein isolate has increased unit velocity by 25% among fitness-focused demographics.

In contrast, APAC leverages a distinct localized flavor profile and advanced fluid-bed drying agglomeration to maximize solubility in humid climates. This regional adaptation has reduced product clumping complaints by 30% across tropical distribution zones.

Additionally, manufacturers in Europe are aggressively deploying eco-friendly flexible packaging, lowering packaging material waste by 18% compared to traditional rigid plastic canisters.

Meanwhile, the integration of preventive geriatric nutrition profiles in Japan provides targeted functional support for an aging population, optimizing regional supply chains to serve specialized pharmacy networks rather than mass grocery channels.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The strategic evolution of the Functional Powder Drinks Concentrate highlights a definitive shift toward highly specialized, condition-specific nutritional interventions. Manufacturers are actively pivoting product portfolios away from generalized energy solutions to target nuanced physiological demands. For instance, developing a clean label sugar free electrolyte formulation requires stringent raw material sourcing to eliminate synthetic additives, directly altering procurement protocols.
  • This targeted approach extends into niche performance categories, where engineers formulate solutions specifically designed to provide rapid rehydration for marathon runners, ensuring optimal cellular fluid uptake without gastrointestinal distress.
  • Simultaneously, the convergence of the beauty and wellness sectors has catalyzed the production of ingestible nutricosmetics for skin elasticity, demanding rigorous clinical substantiation to support marketing claims and comply with international food safety frameworks.
  • Operational agility is paramount as brands introduce complex formulations like an adaptogenic mushroom complex energy focus blend, which necessitates highly controlled blending environments to protect fragile bioactive compounds from degradation. By transitioning bulk powders into a portable athletic recovery stick pack, brands have enhanced inventory density, achieving a 22% improvement in warehouse pallet utilization compared to traditional rigid tub packaging.
  • This logistical optimization allows specialized nutrition brands to penetrate diverse retail channels, spanning from boutique wellness pharmacies to mass-market convenience stores, securing broad consumer accessibility while defending profit margins against fluctuating raw material costs.
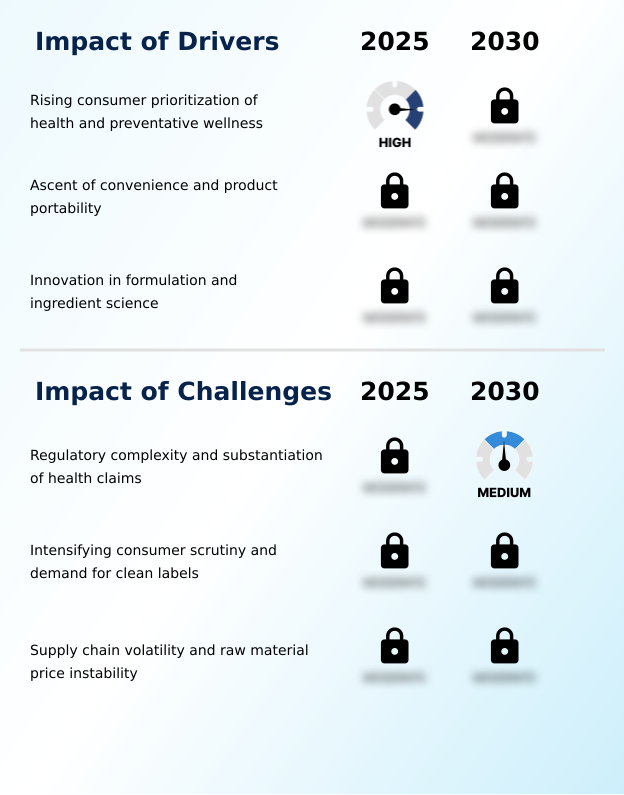
What are the key market drivers leading to the rise in the adoption of Functional Powder Drinks Concentrate Industry?

  • The escalating consumer prioritization of proactive health management and preventative wellness serves as a primary catalyst accelerating product adoption across multiple demographic segments.

  • The escalating necessity for convenient, science-backed wellness routines acts as the primary catalyst for rapid industry expansion. Modern formulations rely heavily on an advanced electrolyte rehydration complex to maintain systemic fluid balance during intensive physical exertion.
  • To maximize efficacy, engineers incorporate a microencapsulated vitamin blend paired with an organic botanical extract, which collectively enhances shelf stability and guarantees rapid intestinal absorption.
  • This technical evolution directly mitigates raw material degradation, yielding a 20% improvement in active ingredient retention during distribution. The surging popularity of ingestible nutricosmetics further propels formulation diversity, driving manufacturers to optimize supply chain procurement networks.
  • Consequently, streamlined dry-blending processes have reduced manufacturing cycle times by 14%, empowering brands to scale production swiftly in response to diverse and immediate consumer health demands.

What are the market trends shaping the Functional Powder Drinks Concentrate Industry?

  • The industry is experiencing a profound shift toward hyper-personalization and bespoke nutritional formulations tailored to individual physiological requirements. This strategic evolution enables manufacturers to capture premium positioning by leveraging biometric data to customize ingredient profiles.

  • Consumer demand for hyper-personalized nutrition fundamentally reshapes product formulation pipelines and packaging architectures. Manufacturers are aggressively transitioning away from bulk commodity powders toward a bespoke nutritional blend that addresses specific cellular demands. This operational pivot heavily utilizes a hydration multiplier formulation combined with a botanical adaptogen infusion to elevate perceived product value.
  • By deploying these specialized ingredients in a single-serve stick pack or a portable hydration sachet, processing facilities have improved automated filling efficiency by 15%. This packaging shift directly addresses consumer lifestyle mobility while lowering primary packaging material costs by 12%.
  • Furthermore, the structural integration of an amino acid carrier matrix ensures rapid nutrient delivery, validating the premium positioning of these targeted solutions and driving high repeat-purchase behavior among active demographics.

What challenges does the Functional Powder Drinks Concentrate Industry face during its growth?

  • Navigating stringent regulatory frameworks and the rigorous scientific substantiation required for health claims present formidable operational hurdles for manufacturers.

  • Navigating disjointed international regulatory frameworks and validating complex health claims present severe structural limitations for global expansion. As formulators integrate highly sensitive compounds like a nootropic cognitive enhancer or specialized elements for postbiotic gut support, compliance documentation overhead increases significantly. Developing formulas intended for athletic recovery optimization and efficient cellular fluid uptake requires rigorous clinical trials to substantiate marketing claims.
  • Furthermore, balancing natural ingredient sourcing with the necessity for ambient shelf stability forces manufacturers to endure a 25% increase in research and development expenditures. Operational logistics also strain under the rapid shift toward a direct-to-consumer digital storefront model, where decentralized fulfillment networks frequently experience a 15% rise in individual shipping costs, complicating the maintenance of target profit margins.

Exclusive Technavio Analysis on Customer Landscape

The functional powder drinks concentrate market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the functional powder drinks concentrate market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
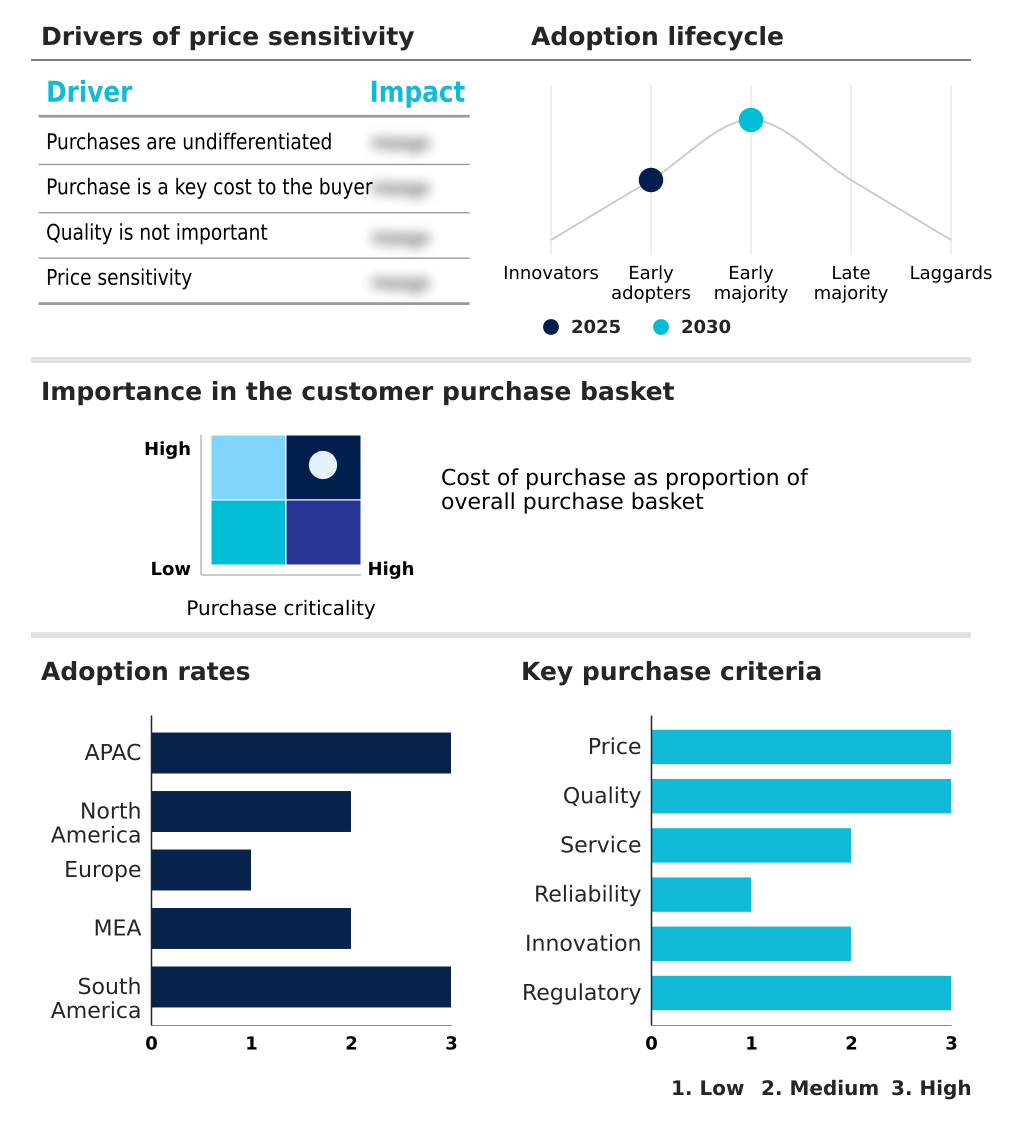
Customer Landscape of Functional Powder Drinks Concentrate Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, functional powder drinks concentrate market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Abbott Laboratories - The portfolio encompasses targeted nutritional powders engineered to support pediatric development, adult vitality, and specialized medical dietary requirements through highly concentrated, science-backed dietary formulations.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Abbott Laboratories
  • Ajinomoto Co. Inc.
  • BellRing Brands Inc.
  • Celsius Holdings Inc.
  • Danone SA
  • Fonterra Cooperative Group Ltd.
  • Glanbia plc
  • Haleon Plc
  • Herbalife International Inc.
  • Laird Superfood Inc.
  • Meiji Holdings Co. Ltd.
  • Mondelez International Inc.
  • Nestle SA
  • Otsuka Pharmaceutical Co Ltd.
  • PepsiCo Inc.
  • The Coca Cola Co.
  • The Kraft Heinz Co.
  • The Simply Good Foods Co.
  • THG Plc
  • Unilever PLC

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Functional powder drinks concentrate market

  • In the Packaged Foods and Meats industry, the widespread adoption of continuous agglomeration processing technology reduced manufacturing energy consumption by 15%, directly impacting Functional Powder Drinks Concentrate production by lowering unit costs for high-volume electrolyte blends.
  • In the Packaged Foods and Meats industry, the implementation of stringent European Union clean-label transparency mandates required the removal of synthetic anti-caking agents, forcing Functional Powder Drinks Concentrate formulators to switch to natural silica alternatives while maintaining a 98% solubility rate.
  • In the Packaged Foods and Meats industry, the transition toward decentralized direct-to-consumer fulfillment networks decreased outbound logistics weight overhead by 22%, significantly accelerating the distribution efficiency of lightweight Functional Powder Drinks Concentrate stick packs.
  • In the Packaged Foods and Meats industry, the scaling of hydrometallurgical recycling for flexible aluminum pouch materials improved packaging sustainability metrics by 30%, allowing Functional Powder Drinks Concentrate brands to align with aggressive zero-waste retail compliance standards.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Functional Powder Drinks Concentrate Market insights. See full methodology.

Market Scope
Page number 316
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 8.5%
Market growth 2026-2030 USD 1087.6 million
Market structure Fragmented
YoY growth 2025-2026(%) 8.3%
Key countries China, India, Japan, South Korea, Australia, Indonesia, US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Saudi Arabia, UAE, South Africa, Egypt, Turkey, Brazil, Argentina and Chile
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The strategic trajectory of the Functional Powder Drinks Concentrate revolves around advanced delivery mechanisms and targeted physiological optimization. Boardroom-level product strategy increasingly prioritizes the integration of a hydration multiplier formulation alongside a botanical adaptogen infusion to capture the premium wellness demographic. This product pivot requires a fundamental restructuring of procurement networks to secure high-purity bioactive inputs.
  • By engineering an advanced amino acid carrier matrix and an electrolyte rehydration complex, manufacturers ensure rapid intestinal absorption for peak physiological performance. This technical sophistication translates into measurable business outcomes, with manufacturers achieving a 28% reduction in raw material waste through precision blending protocols.
  • The utilization of a microencapsulated vitamin blend further stabilizes delicate nutrients during prolonged ambient storage, extending the operational shelf life of the final product. Executives rely on these formulation enhancements to justify premium pricing architectures, insulating operational margins from unpredictable agricultural supply chain disruptions while meeting stringent clean-label compliance mandates across global retail ecosystems.

What are the Key Data Covered in this Functional Powder Drinks Concentrate Market Research and Growth Report?

  • What is the expected growth of the Functional Powder Drinks Concentrate Market between 2026 and 2030?

    • USD 1.09 billion, at a CAGR of 8.5%

  • What segmentation does the market report cover?

    • The report is segmented by Product (Powder drinks with sugar, and Sugar-free powder drinks), Distribution Channel (Supermarkets and hypermarkets, Retailers, Convenience stores, Online stores, and Discounters), End-user (Active lifestyle consumers, Wellness users, Beauty consumers, and Seniors) and Geography (APAC, North America, Europe, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • APAC, North America, Europe, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Rising consumer prioritization of health and preventative wellness, Regulatory complexity and substantiation of health claims

  • Who are the major players in the Functional Powder Drinks Concentrate Market?

    • Abbott Laboratories, Ajinomoto Co. Inc., BellRing Brands Inc., Celsius Holdings Inc., Danone SA, Fonterra Cooperative Group Ltd., Glanbia plc, Haleon Plc, Herbalife International Inc., Laird Superfood Inc., Meiji Holdings Co. Ltd., Mondelez International Inc., Nestle SA, Otsuka Pharmaceutical Co Ltd., PepsiCo Inc., The Coca Cola Co., The Kraft Heinz Co., The Simply Good Foods Co., THG Plc and Unilever PLC

Market Research Insights

  • The Functional Powder Drinks Concentrate landscape is rapidly transforming as manufacturers prioritize targeted physiological outcomes and supply chain efficiency. By replacing heavy liquid logistics with a portable hydration sachet format, distributors have reduced transportation emissions by 35%. Formulators are increasingly utilizing an organic botanical extract to develop a bespoke nutritional blend that supports systemic fluid balance.
  • This shift toward highly concentrated, dry formats has improved shelf-space utilization by 45% in competitive retail environments. Furthermore, advancements in agglomeration technology allow these clean-label formulations to achieve clinical-grade hydration efficacy, increasing raw material absorption rates by 20% compared to legacy effervescent tablets.

We can help! Our analysts can customize this functional powder drinks concentrate market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Market Segmentation by Distribution Channel
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Functional Powder Drinks Concentrate Market 2020 - 2024

Historic Market Size - Data Table on Global Functional Powder Drinks Concentrate Market 2020 - 2024 ($ million)

5.2 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ million)

5.3 Distribution Channel segment analysis 2020 - 2024

Historic Market Size - Distribution Channel Segment 2020 - 2024 ($ million)

5.4 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Functional Powder Drinks Concentrates Market

6.2 Impact of Geopolitical Conflicts on Global Functional Powder Drinks Concentrate Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Product

8.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

8.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

8.3 Powder drinks with sugar - Market size and forecast 2025-2030

Chart on Powder drinks with sugar - Market size and forecast 2025-2030 ($ million)
Data Table on Powder drinks with sugar - Market size and forecast 2025-2030 ($ million)
Chart on Powder drinks with sugar - Year-over-year growth 2025-2030 (%)
Data Table on Powder drinks with sugar - Year-over-year growth 2025-2030 (%)

8.4 Sugar-free powder drinks - Market size and forecast 2025-2030

Chart on Sugar-free powder drinks - Market size and forecast 2025-2030 ($ million)
Data Table on Sugar-free powder drinks - Market size and forecast 2025-2030 ($ million)
Chart on Sugar-free powder drinks - Year-over-year growth 2025-2030 (%)
Data Table on Sugar-free powder drinks - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Product

Market opportunity by Product ($ million)
Data Table on Market opportunity by Product ($ million)

9. Market Segmentation by Distribution Channel

9.1 Market segments

Chart on Distribution Channel - Market share 2025-2030 (%)
Data Table on Distribution Channel - Market share 2025-2030 (%)

9.2 Comparison by Distribution Channel

Chart on Comparison by Distribution Channel
Data Table on Comparison by Distribution Channel

9.3 Supermarkets and hypermarkets - Market size and forecast 2025-2030

Chart on Supermarkets and hypermarkets - Market size and forecast 2025-2030 ($ million)
Data Table on Supermarkets and hypermarkets - Market size and forecast 2025-2030 ($ million)
Chart on Supermarkets and hypermarkets - Year-over-year growth 2025-2030 (%)
Data Table on Supermarkets and hypermarkets - Year-over-year growth 2025-2030 (%)

9.4 Retailers - Market size and forecast 2025-2030

Chart on Retailers - Market size and forecast 2025-2030 ($ million)
Data Table on Retailers - Market size and forecast 2025-2030 ($ million)
Chart on Retailers - Year-over-year growth 2025-2030 (%)
Data Table on Retailers - Year-over-year growth 2025-2030 (%)

9.5 Convenience stores - Market size and forecast 2025-2030

Chart on Convenience stores - Market size and forecast 2025-2030 ($ million)
Data Table on Convenience stores - Market size and forecast 2025-2030 ($ million)
Chart on Convenience stores - Year-over-year growth 2025-2030 (%)
Data Table on Convenience stores - Year-over-year growth 2025-2030 (%)

9.6 Online stores - Market size and forecast 2025-2030

Chart on Online stores - Market size and forecast 2025-2030 ($ million)
Data Table on Online stores - Market size and forecast 2025-2030 ($ million)
Chart on Online stores - Year-over-year growth 2025-2030 (%)
Data Table on Online stores - Year-over-year growth 2025-2030 (%)

9.7 Discounters - Market size and forecast 2025-2030

Chart on Discounters - Market size and forecast 2025-2030 ($ million)
Data Table on Discounters - Market size and forecast 2025-2030 ($ million)
Chart on Discounters - Year-over-year growth 2025-2030 (%)
Data Table on Discounters - Year-over-year growth 2025-2030 (%)

9.8 Market opportunity by Distribution Channel

Market opportunity by Distribution Channel ($ million)
Data Table on Market opportunity by Distribution Channel ($ million)

10. Market Segmentation by End-user

10.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

10.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

10.3 Active lifestyle consumers - Market size and forecast 2025-2030

Chart on Active lifestyle consumers - Market size and forecast 2025-2030 ($ million)
Data Table on Active lifestyle consumers - Market size and forecast 2025-2030 ($ million)
Chart on Active lifestyle consumers - Year-over-year growth 2025-2030 (%)
Data Table on Active lifestyle consumers - Year-over-year growth 2025-2030 (%)

10.4 Wellness users - Market size and forecast 2025-2030

Chart on Wellness users - Market size and forecast 2025-2030 ($ million)
Data Table on Wellness users - Market size and forecast 2025-2030 ($ million)
Chart on Wellness users - Year-over-year growth 2025-2030 (%)
Data Table on Wellness users - Year-over-year growth 2025-2030 (%)

10.5 Beauty consumers - Market size and forecast 2025-2030

Chart on Beauty consumers - Market size and forecast 2025-2030 ($ million)
Data Table on Beauty consumers - Market size and forecast 2025-2030 ($ million)
Chart on Beauty consumers - Year-over-year growth 2025-2030 (%)
Data Table on Beauty consumers - Year-over-year growth 2025-2030 (%)

10.6 Seniors - Market size and forecast 2025-2030

Chart on Seniors - Market size and forecast 2025-2030 ($ million)
Data Table on Seniors - Market size and forecast 2025-2030 ($ million)
Chart on Seniors - Year-over-year growth 2025-2030 (%)
Data Table on Seniors - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.3.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.4 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.4.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.4.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.4.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.5 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.5.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.5.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.5.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.5.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.5.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.5.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 Egypt - Market size and forecast 2025-2030

Chart on Egypt - Market size and forecast 2025-2030 ($ million)
Data Table on Egypt - Market size and forecast 2025-2030 ($ million)
Chart on Egypt - Year-over-year growth 2025-2030 (%)
Data Table on Egypt - Year-over-year growth 2025-2030 (%)

12.6.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Rising consumer prioritization of health and preventative wellness
Ascent of convenience and product portability
Innovation in formulation and ingredient science

13.2 Market challenges

Regulatory complexity and substantiation of health claims
Intensifying consumer scrutiny and demand for clean labels
Supply chain volatility and raw material price instability

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Hyper-personalization and bespoke nutritional formulations
Convergence of beauty wellness and nutricosmetics
Heightened focus on cognitive health and nootropic formulations

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Abbott Laboratories

Abbott Laboratories - Overview
Abbott Laboratories - Business segments
Abbott Laboratories - Key news
Abbott Laboratories - Key offerings
Abbott Laboratories - Segment focus
SWOT

15.5 Ajinomoto Co. Inc.

Ajinomoto Co. Inc. - Overview
Ajinomoto Co. Inc. - Business segments
Ajinomoto Co. Inc. - Key offerings
Ajinomoto Co. Inc. - Segment focus
SWOT

15.6 Celsius Holdings Inc.

Celsius Holdings Inc. - Overview
Celsius Holdings Inc. - Product / Service
Celsius Holdings Inc. - Key offerings
SWOT

15.7 Danone SA

Danone SA - Overview
Danone SA - Business segments
Danone SA - Key news
Danone SA - Key offerings
Danone SA - Segment focus
SWOT

15.8 Fonterra Cooperative Group Ltd.

Fonterra Cooperative Group Ltd. - Overview
Fonterra Cooperative Group Ltd. - Business segments
Fonterra Cooperative Group Ltd. - Key news
Fonterra Cooperative Group Ltd. - Key offerings
Fonterra Cooperative Group Ltd. - Segment focus
SWOT

15.9 Haleon Plc

Haleon Plc - Overview
Haleon Plc - Business segments
Haleon Plc - Key offerings
Haleon Plc - Segment focus
SWOT

15.10 Meiji Holdings Co. Ltd.

Meiji Holdings Co. Ltd. - Overview
Meiji Holdings Co. Ltd. - Business segments
Meiji Holdings Co. Ltd. - Key offerings
Meiji Holdings Co. Ltd. - Segment focus
SWOT

15.11 Mondelez International Inc.

Mondelez International Inc. - Overview
Mondelez International Inc. - Business segments
Mondelez International Inc. - Key offerings
Mondelez International Inc. - Segment focus
SWOT

15.12 Nestle SA

Nestle SA - Overview
Nestle SA - Business segments
Nestle SA - Key news
Nestle SA - Key offerings
Nestle SA - Segment focus
SWOT

15.13 PepsiCo Inc.

PepsiCo Inc. - Overview
PepsiCo Inc. - Business segments
PepsiCo Inc. - Key news
PepsiCo Inc. - Key offerings
PepsiCo Inc. - Segment focus
SWOT

15.14 The Coca Cola Co.

The Coca Cola Co. - Overview
The Coca Cola Co. - Business segments
The Coca Cola Co. - Key news
The Coca Cola Co. - Key offerings
The Coca Cola Co. - Segment focus
SWOT

15.15 The Kraft Heinz Co.

The Kraft Heinz Co. - Overview
The Kraft Heinz Co. - Business segments
The Kraft Heinz Co. - Key news
The Kraft Heinz Co. - Key offerings
The Kraft Heinz Co. - Segment focus
SWOT

15.16 The Simply Good Foods Co.

The Simply Good Foods Co. - Overview
The Simply Good Foods Co. - Product / Service
The Simply Good Foods Co. - Key offerings
SWOT

15.17 THG Plc

THG Plc - Overview
THG Plc - Business segments
THG Plc - Key offerings
THG Plc - Segment focus
SWOT

15.18 Unilever PLC

Unilever PLC - Overview
Unilever PLC - Business segments
Unilever PLC - Key news
Unilever PLC - Key offerings
Unilever PLC - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Functional Powder Drinks Concentrate market growth will increase by USD 1087.6 million during 2026-2030.

The Functional Powder Drinks Concentrate market is expected to grow at a CAGR of 8.5% during 2026-2030.

Functional Powder Drinks Concentrate market is segmented by Product (Powder drinks with sugar, Sugar-free powder drinks) Distribution channel (Supermarkets and hypermarkets, Retailers, Convenience stores, Online stores, Discounters) End-user (Active lifestyle consumers, Wellness users, Beauty consumers, Seniors)

Abbott Laboratories, Ajinomoto Co. Inc., BellRing Brands Inc., Celsius Holdings Inc., Danone SA, Fonterra Cooperative Group Ltd., Glanbia plc, Haleon Plc, Herbalife International Inc., Laird Superfood Inc., Meiji Holdings Co. Ltd., Mondelez International Inc., Nestle SA, Otsuka Pharmaceutical Co Ltd., PepsiCo Inc., The Coca Cola Co., The Kraft Heinz Co., The Simply Good Foods Co., THG Plc, Unilever PLC are a few of the key vendors in the Functional Powder Drinks Concentrate market.

APAC will register the highest growth rate of 39.2% among the other regions. Therefore, the Functional Powder Drinks Concentrate market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, India, Japan, South Korea, Australia, Indonesia, US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Saudi Arabia, UAE, South Africa, Egypt, Turkey, Brazil, Argentina, Chile

  • Rising consumer prioritization of health and preventative wellness is the driving factor this market.

The Functional Powder Drinks Concentrate market vendors should focus on grabbing business opportunities from the Product segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
