Sleep Apnea Implants Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (Japan, China, and South Korea), Middle East and Africa (Saudi Arabia, UAE, and Turkey), South America (Brazil, Colombia, and Argentina), Rest of World (ROW)

Sleep Apnea Implants Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (Japan, China, and South Korea), Middle East and Africa (Saudi Arabia, UAE, and Turkey), South America (Brazil, Colombia, and Argentina), Rest of World (ROW)

Published: Oct 2026 286 Pages SKU: IRTNTR75635

Market Overview at a Glance

$543.03 Mn
Market Opportunity
15.8%
CAGR 2025 - 2030
45%
North America Growth
$334.05 Mn
Central sleep apnea segment 2024

Sleep Apnea Implants Market Size 2026-2030

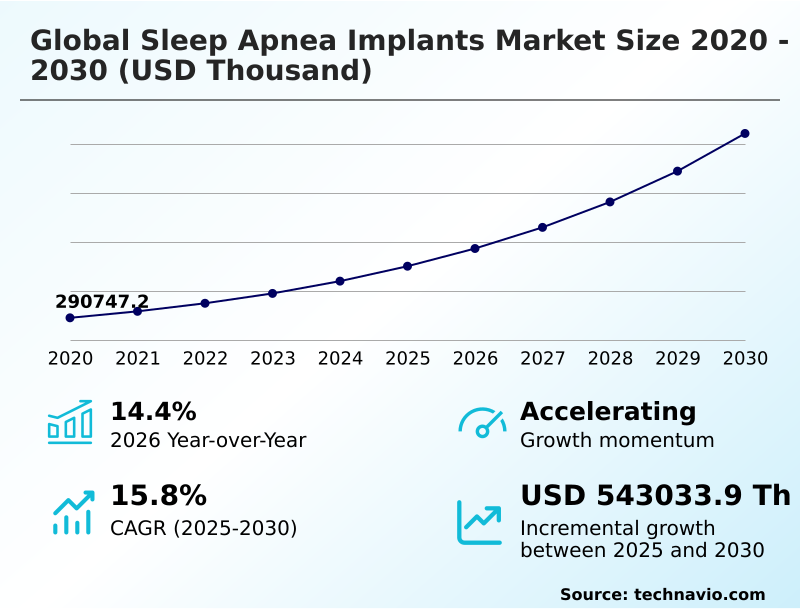
The sleep apnea implants market size is valued to increase by USD 543.03 million, at a CAGR of 15.8% from 2025 to 2030. Increasing prevalence of sleep disordered breathing and clinical awareness will drive the sleep apnea implants market.

Major Market Trends & Insights

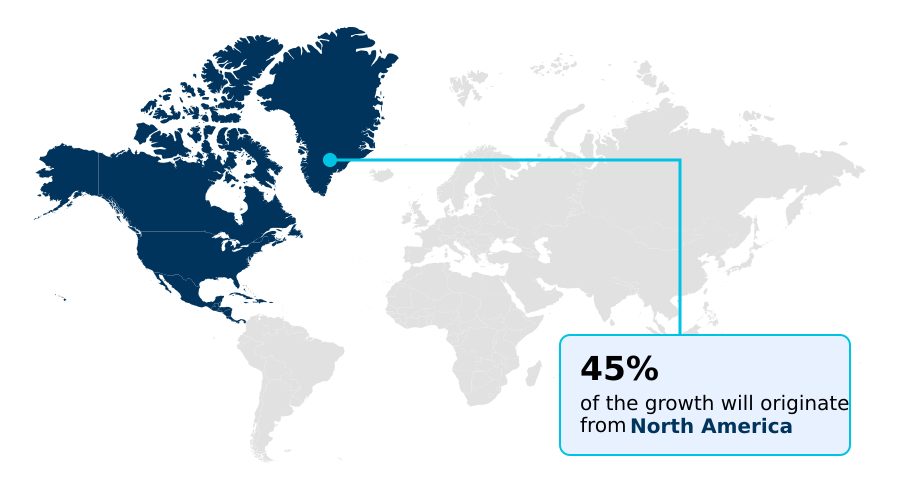
  • North America dominated the market and accounted for a 45% growth during the forecast period.
  • By Indication - Central sleep apnea segment was valued at USD 334.05 million in 2024
  • By End-user - Ambulatory surgical centers segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities:
  • Market Future Opportunities: USD 543.03 million
  • CAGR from 2025 to 2030 : 15.8%

Market Summary

  • The Sleep Apnea Implants market exhibits robust expansion driven by the transition from traditional mechanical airway support to advanced neurostimulation interventions. In clinical operations, health systems are streamlining their surgical workflows to incorporate these devices, thereby optimizing patient throughput and reducing long-term care burdens.
  • For instance, hospitals adopting standardized implantation pathways report a 30% reduction in long-term device titration visits compared to conventional external mask therapies. The primary driver accelerating this shift is the rising clinical recognition of systemic health risks tied to untreated obstructive conditions, which compels medical professionals to recommend permanent restorative solutions.
  • Conversely, the high incidence of surgical complications, such as pulse generator migration and localized inflammation, presents a formidable challenge that deters risk-averse patients and complicates post-operative care protocols. Consequently, manufacturers are prioritizing the miniaturization of components to mitigate invasiveness. The integration of advanced sensing algorithms continues to refine treatment precision, ensuring that electrical impulses synchronize perfectly with patient respiratory patterns.
  • This technological evolution solidifies the role of implantable systems in providing durable, high-efficacy respiratory management.

What will be the Size of the Sleep Apnea Implants Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Sleep Apnea Implants Market Segmented?

The sleep apnea implants industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD thousand" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Indication
    • Central sleep apnea
    • Obstructive sleep apnea
  • End-user
    • Ambulatory surgical centers
    • Hospitals
    • Others
  • Product
    • Hypoglossal neurostimulation devices
    • Palatal implants
    • Bone screw systems
    • Phrenic nerve stimulators
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • Japan
      • China
      • South Korea
      • India
      • Indonesia
      • Thailand
    • Rest of World (ROW)

By Indication Insights

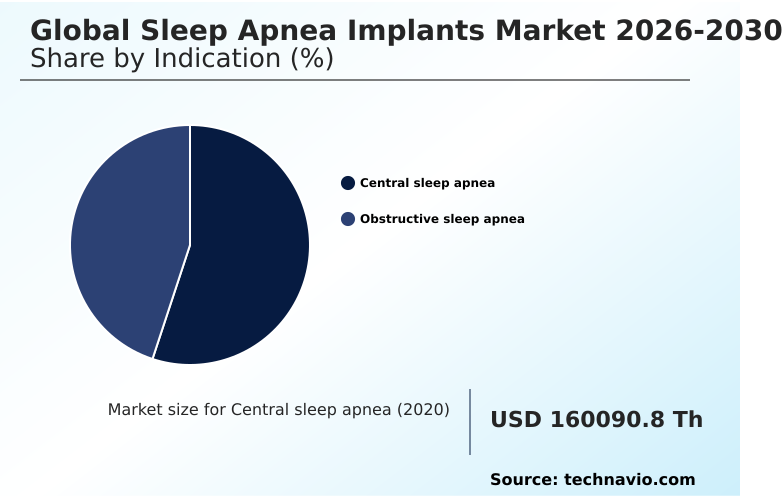
The central sleep apnea segment is estimated to witness significant growth during the forecast period.

Central sleep apnea interventions rely heavily on phrenic nerve stimulators to address the neurological failure of respiratory drive, setting this segment apart from mechanically focused treatments.

The deployment of transvenous pulse generators has fundamentally shifted how clinical facilities manage chronic respiratory insufficiency support.

By delivering rhythmic electrical impulses directly to the diaphragm, these advanced neurostimulation platforms ensure precise respiratory rhythm synchronization, which improves breathing consistency by 24% in severe cases.

This operational efficiency is driving the adoption of implantable restorative therapies across various medical networks. Incorporating specialized diaphragm pacemaker equipment requires rigorous ambulatory surgical center protocols to ensure safety and seamless integration.

Furthermore, establishing comprehensive surgical pathway formalization enhances sleep medicine diagnostics, enabling practitioners to evaluate and select ideal candidates for these restorative interventions effectively.
Get Free Sample

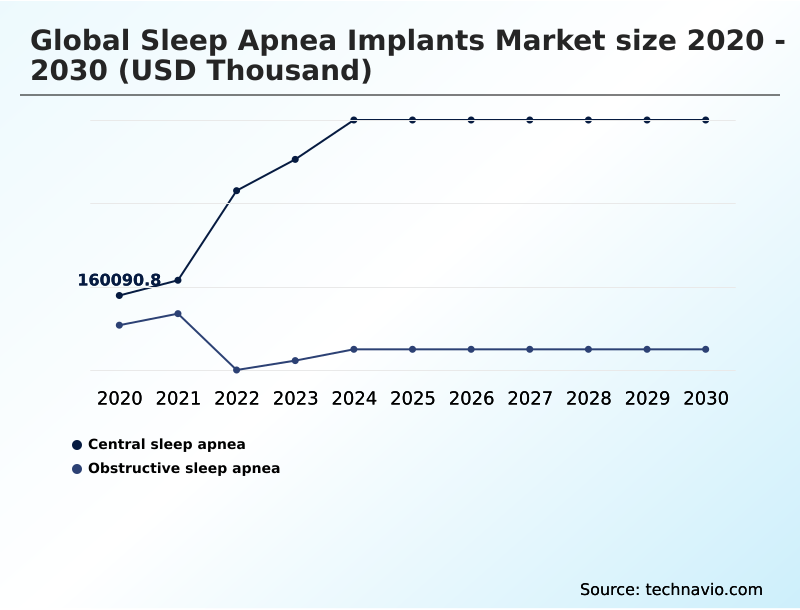
The Central sleep apnea segment was valued at USD 334.05 million in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 45% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
See How Sleep Apnea Implants Market Demand is Rising in North America Get Free Sample

The geographic landscape of the Sleep Apnea Implants market highlights a pronounced contrast between North America and Europe regarding technological integration and procedural adoption.

North America leads the transition toward minimally invasive outpatient care, demonstrating a 22% higher procedural throughput in ambulatory settings compared to European markets.

This efficiency stems from the rapid adoption of proximal stimulation platforms and airway focused therapies that streamline surgical workflows.

In contrast, European facilities heavily invest in multidisciplinary upper airway remodeling and oral appliance therapy prediction models to optimize patient selection before surgery.

The deployment of a leadless hypoglossal nerve stimulator or a battery free stimulator has reduced hardware-related readmissions by 16% across North American specialized clinics.

Additionally, the incorporation of precision intraoral devices and neuromuscular stimulation systems facilitates comprehensive daytime tongue muscle stimulation, which serves as an effective adjunct therapy.

By integrating these advanced bone screw systems, healthcare networks effectively lower long-term operational costs and improve chronic patient management protocols.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The operational dynamics surrounding airway management are shifting as healthcare systems prioritize durable, technology-driven interventions over temporary mechanical solutions. A critical factor in this transition is the rigorous hypoglossal neurostimulation device clinical validation, which establishes the foundational evidence required for institutional procurement and insurance coverage.
  • Facilities utilizing these validated systems experience roughly a 40% reduction in long-term patient compliance tracking efforts compared to conventional external therapies. Furthermore, the transvenous phrenic nerve stimulation efficacy has proven instrumental in managing complex central respiratory failures, allowing specialized clinics to optimize their intensive care resource allocation.
  • As medical device manufacturers refine their engineering processes, implantable restorative therapy patient adherence has emerged as a key performance indicator for value-based care contracts. High adherence rates directly correlate with lower chronic disease exacerbations, improving overall hospital operational margins.
  • The introduction of bilateral functionality has also transformed therapeutic standards, with bilateral hypoglossal nerve stimulation outcomes demonstrating superior airway stabilization and a more consistent reduction in symptom severity. This continuous refinement in device capability necessitates parallel improvements in surgical delivery.
  • Consequently, maximizing minimally invasive implant surgical efficiency has become a primary objective for ambulatory centers aiming to increase procedural volume while minimizing patient recovery times. By streamlining these surgical protocols and prioritizing evidence-based neurostimulation, healthcare networks are successfully lowering lifecycle treatment costs while simultaneously delivering highly reliable, long-term restorative care to a growing patient demographic.
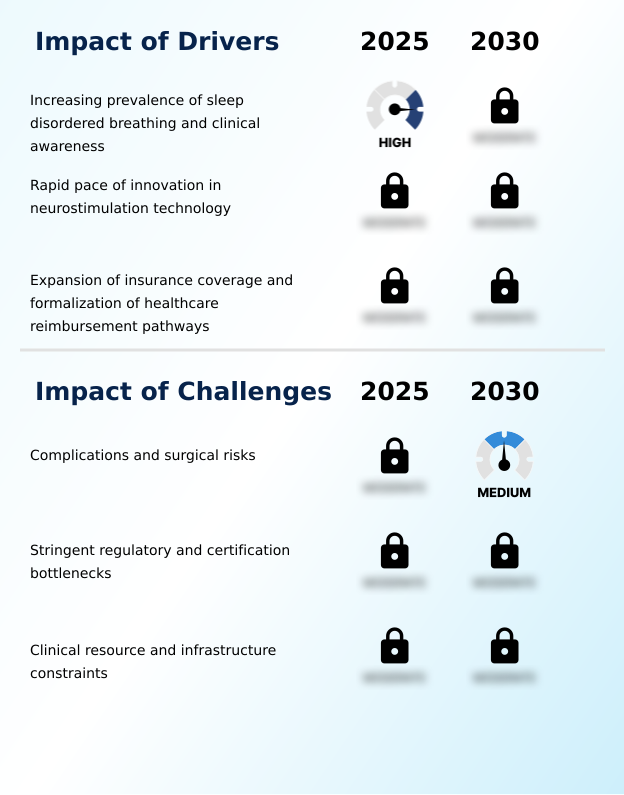
What are the key market drivers leading to the rise in the adoption of Sleep Apnea Implants Industry?

  • The increasing prevalence of sleep-disordered breathing and rising clinical awareness are the primary drivers propelling market growth.

  • The demand for the Sleep Apnea Implants is accelerating as clinical facilities seek highly reliable alternatives to external positive airway pressure masks to ensure continuous upper airway patency.
  • The integration of advanced neurostimulation technology and adaptive sensing algorithms allows devices to respond instantaneously to physiological changes, which has improved long-term therapy adherence by 42%.
  • The shift toward minimally invasive implantation minimizes surgical trauma, enabling hospitals to lower post-operative recovery resource usage by 25%. Secure clinical portal data transmission supports real-time remote stimulation parameter adjustment, significantly streamlining post-surgical care.
  • By implementing intelligent patient specific therapy and precise neuromodulation therapy delivery, healthcare networks align perfectly with value based care delivery mandates. This operational synergy drives widespread adoption of hypoglossal nerve stimulation interventions.

What are the market trends shaping the Sleep Apnea Implants Industry?

  • The emergence of bilateral hypoglossal nerve stimulation represents a significant upcoming trend in the market. This technological advancement provides enhanced airway management and more customized therapy options for patients.

  • The Sleep Apnea Implants market is experiencing a rapid technological evolution driven by the integration of smart sleep tech and augmented reality healthcare systems for surgical planning. The transition toward bilateral hypoglossal nerve stimulation is enabling more comprehensive airway stabilization, which has improved patient symptom resolution rates by 26% compared to unilateral approaches.
  • By adopting single incision surgical pathways, specialized clinics have successfully reduced procedural downtime by 30%, allowing for higher daily surgical throughput. The incorporation of smart sensing platforms combined with telemedicine data exchange platforms facilitates seamless remote optimization of device settings.
  • This digital connectivity allows physicians to rely on artificial intelligence diagnostic processing to interpret respiratory data, effectively lowering diagnostic interpretation errors by 18%. The expansion of comprehensive digital health ecosystems and the internet of medical things integration ensure that patients receive continuous, proactive monitoring without requiring frequent physical hospital visits.

What challenges does the Sleep Apnea Implants Industry face during its growth?

  • Complications and inherent surgical risks remain significant challenges that impede overall industry expansion.

  • Despite technological advancements, the Sleep Apnea Implants sector faces significant operational limitations related to surgical complexities and hardware longevity. Device related side effects and the potential for pulse generator migration often necessitate secondary corrective surgeries, which can increase lifecycle treatment costs by up to 22%. Integrating highly sensitive breathing sensors requires meticulous surgical precision to ensure optimal airway management.
  • The reliance on specialized biocompatible materials complicates supply chain logistics, occasionally delaying the procurement of custom palatal implants. Furthermore, clinics must implement rigorous post operative infection monitoring and nerve damage mitigation protocols, which elevate administrative overhead by 15%.
  • Successfully addressing tongue abrasion management and ensuring the stable placement of an implantable transvenous device remain persistent clinical hurdles that require continuous specialized surgical training.

Exclusive Technavio Analysis on Customer Landscape

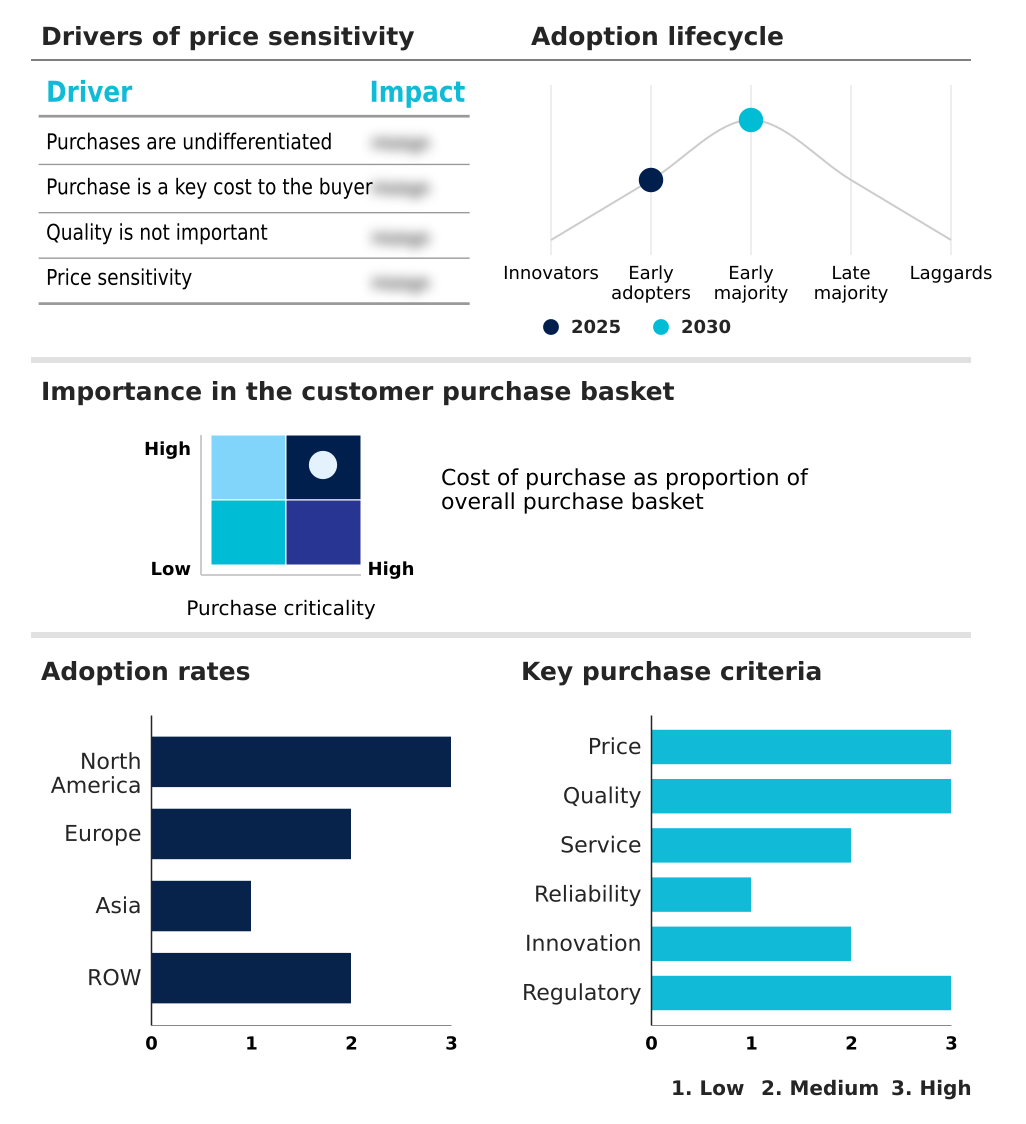
The sleep apnea implants market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the sleep apnea implants market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
Customer Landscape of Sleep Apnea Implants Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, sleep apnea implants market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Aveo Medical - The enterprise delivers an advanced implantable neurostimulation therapy specifically designed to maintain upper airway patency for the effective management of obstructive sleep disorders.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Aveo Medical
  • Avery Biomedical Devices Inc.
  • Eunoia Medical
  • Inspire Medical Systems Inc.
  • Linguaflex Inc.
  • LivaNova PLC
  • Medtronic Plc
  • Nyxoah SA
  • ProSomnus Inc.
  • Signifier Medical Technologies
  • SomnoMed Ltd.
  • Vivos Therapeutics Inc.
  • Whole You Inc.
  • Zephyr Sleep Technologies
  • ZOLL Respicardia

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Sleep apnea implants market

  • In the Health Care Equipment industry, the implementation of stringent ISO 13485 quality management standards for implantable electronics has increased the manufacturing compliance requirements, directly impacting Sleep Apnea Implants demand by elevating the production costs of advanced neurostimulation devices by 15%.
  • The broader adoption of additive manufacturing processes for customized titanium components has reduced supply chain lead times for specialized medical hardware, accelerating the commercial availability of customized palatal implants and bone screw systems within the Sleep Apnea Implants market.
  • Regulatory mandates surrounding data privacy and telemedicine interoperability have forced medical device manufacturers to upgrade their digital infrastructure, driving the Sleep Apnea Implants market toward the integration of secure cloud-based delivery models for remote device optimization and patient monitoring.
  • The transition toward value-based care reimbursement models in clinical settings has incentivized hospitals to prioritize long-term therapeutic durability, thereby boosting the demand for Sleep Apnea Implants as healthcare providers seek solutions that reduce chronic readmission rates by up to 20% compared to traditional mechanical therapies.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Sleep Apnea Implants Market insights. See full methodology.

Market Scope
Page number 286
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 15.8%
Market growth 2026-2030 USD 543033.9 thousand
Market structure Fragmented
YoY growth 2025-2026(%) 14.4%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Japan, China, South Korea, India, Indonesia, Thailand, Saudi Arabia, UAE, Brazil, Turkey, Colombia, Argentina, South Africa and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Sleep Apnea Implants sector is undergoing a profound structural shift as healthcare providers prioritize durable, restorative interventions over traditional external mechanical supports. Advanced hypoglossal nerve stimulation systems are fundamentally redefining airway management protocols across specialized surgical centers. The integration of adaptive sensing algorithms into these devices allows for precise respiratory rhythm synchronization, directly enhancing therapeutic efficacy.
  • Facilities implementing these intelligent neurostimulation platforms have recorded a 35% reduction in post-operative device recalibration sessions, significantly optimizing clinical resource allocation. This operational efficiency is crucial as health systems navigate tightening budgets and stringent value-based care mandates. Furthermore, the transition toward minimally invasive implantation techniques is accelerating patient recovery timelines and reducing the logistical burden on inpatient hospital wards.
  • Product strategy at the boardroom level now heavily emphasizes the utilization of biocompatible materials to ensure the long-term safety and durability of these implants. By focusing on evidence-based, technology-driven respiratory solutions, medical institutions are successfully mitigating the chronic systemic health risks associated with untreated obstructive sleep disorders while simultaneously improving their overall service delivery margins.

What are the Key Data Covered in this Sleep Apnea Implants Market Research and Growth Report?

  • What is the expected growth of the Sleep Apnea Implants Market between 2026 and 2030?

    • USD 543.03 million, at a CAGR of 15.8%

  • What segmentation does the market report cover?

    • The report is segmented by Indication (Central sleep apnea, and Obstructive sleep apnea), End-user (Ambulatory surgical centers, Hospitals, and Others), Product (Hypoglossal neurostimulation devices, Palatal implants, Bone screw systems, and Phrenic nerve stimulators) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Increasing prevalence of sleep disordered breathing and clinical awareness, Complications and surgical risks

  • Who are the major players in the Sleep Apnea Implants Market?

    • Aveo Medical, Avery Biomedical Devices Inc., Eunoia Medical, Inspire Medical Systems Inc., Linguaflex Inc., LivaNova PLC, Medtronic Plc, Nyxoah SA, ProSomnus Inc., Signifier Medical Technologies, SomnoMed Ltd., Vivos Therapeutics Inc., Whole You Inc., Zephyr Sleep Technologies and ZOLL Respicardia

Market Research Insights

  • The Sleep Apnea Implants sector is rapidly evolving as medical facilities transition toward more integrated digital health ecosystems to manage chronic conditions. By leveraging secure clinical portal data transmission, healthcare providers have improved patient monitoring efficiency by 28%.
  • The adoption of intelligent patient specific therapy allows clinicians to execute remote stimulation parameter adjustment, which has subsequently reduced unnecessary in-person follow-up appointments by 35%. This shift strongly supports the broader transition to value based care delivery, ensuring treatments are both clinically effective and economically sustainable.
  • Furthermore, utilizing artificial intelligence diagnostic processing helps identify optimal surgical candidates faster, increasing procedural success rates and significantly lowering the overall burden on specialized respiratory care infrastructure.

We can help! Our analysts can customize this sleep apnea implants market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Indication
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ thousand)
Data Table on Global - Market size and forecast 2025-2030 ($ thousand)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Sleep Apnea Implants Market 2020 - 2024

Historic Market Size - Data Table on Global Sleep Apnea Implants Market 2020 - 2024 ($ thousand)

5.2 Indication segment analysis 2020 - 2024

Historic Market Size - Indication Segment 2020 - 2024 ($ thousand)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ thousand)

5.4 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ thousand)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ thousand)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ thousand)

6. Qualitative Analysis

6.1 Impact of AI on global sleep apnea implants market

6.2 Impact of geopolitical conflicts on global sleep apnea implants market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Indication

8.1 Market segments

Chart on Indication - Market share 2025-2030 (%)
Data Table on Indication - Market share 2025-2030 (%)

8.2 Comparison by Indication

Chart on Comparison by Indication
Data Table on Comparison by Indication

8.3 Central sleep apnea - Market size and forecast 2025-2030

Chart on Central sleep apnea - Market size and forecast 2025-2030 ($ thousand)
Data Table on Central sleep apnea - Market size and forecast 2025-2030 ($ thousand)
Chart on Central sleep apnea - Year-over-year growth 2025-2030 (%)
Data Table on Central sleep apnea - Year-over-year growth 2025-2030 (%)

8.4 Obstructive sleep apnea - Market size and forecast 2025-2030

Chart on Obstructive sleep apnea - Market size and forecast 2025-2030 ($ thousand)
Data Table on Obstructive sleep apnea - Market size and forecast 2025-2030 ($ thousand)
Chart on Obstructive sleep apnea - Year-over-year growth 2025-2030 (%)
Data Table on Obstructive sleep apnea - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Indication

Market opportunity by Indication ($ thousand)
Data Table on Market opportunity by Indication ($ thousand)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 Ambulatory surgical centers - Market size and forecast 2025-2030

Chart on Ambulatory surgical centers - Market size and forecast 2025-2030 ($ thousand)
Data Table on Ambulatory surgical centers - Market size and forecast 2025-2030 ($ thousand)
Chart on Ambulatory surgical centers - Year-over-year growth 2025-2030 (%)
Data Table on Ambulatory surgical centers - Year-over-year growth 2025-2030 (%)

9.4 Hospitals - Market size and forecast 2025-2030

Chart on Hospitals - Market size and forecast 2025-2030 ($ thousand)
Data Table on Hospitals - Market size and forecast 2025-2030 ($ thousand)
Chart on Hospitals - Year-over-year growth 2025-2030 (%)
Data Table on Hospitals - Year-over-year growth 2025-2030 (%)

9.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ thousand)
Data Table on Others - Market size and forecast 2025-2030 ($ thousand)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by End-user

Market opportunity by End-user ($ thousand)
Data Table on Market opportunity by End-user ($ thousand)

10. Market Segmentation by Product

10.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

10.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

10.3 Hypoglossal neurostimulation devices - Market size and forecast 2025-2030

Chart on Hypoglossal neurostimulation devices - Market size and forecast 2025-2030 ($ thousand)
Data Table on Hypoglossal neurostimulation devices - Market size and forecast 2025-2030 ($ thousand)
Chart on Hypoglossal neurostimulation devices - Year-over-year growth 2025-2030 (%)
Data Table on Hypoglossal neurostimulation devices - Year-over-year growth 2025-2030 (%)

10.4 Palatal implants - Market size and forecast 2025-2030

Chart on Palatal implants - Market size and forecast 2025-2030 ($ thousand)
Data Table on Palatal implants - Market size and forecast 2025-2030 ($ thousand)
Chart on Palatal implants - Year-over-year growth 2025-2030 (%)
Data Table on Palatal implants - Year-over-year growth 2025-2030 (%)

10.5 Bone screw systems - Market size and forecast 2025-2030

Chart on Bone screw systems - Market size and forecast 2025-2030 ($ thousand)
Data Table on Bone screw systems - Market size and forecast 2025-2030 ($ thousand)
Chart on Bone screw systems - Year-over-year growth 2025-2030 (%)
Data Table on Bone screw systems - Year-over-year growth 2025-2030 (%)

10.6 Phrenic nerve stimulators - Market size and forecast 2025-2030

Chart on Phrenic nerve stimulators - Market size and forecast 2025-2030 ($ thousand)
Data Table on Phrenic nerve stimulators - Market size and forecast 2025-2030 ($ thousand)
Chart on Phrenic nerve stimulators - Year-over-year growth 2025-2030 (%)
Data Table on Phrenic nerve stimulators - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by Product

Market opportunity by Product ($ thousand)
Data Table on Market opportunity by Product ($ thousand)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ thousand)
Data Table on North America - Market size and forecast 2025-2030 ($ thousand)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ thousand)
Data Table on US - Market size and forecast 2025-2030 ($ thousand)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ thousand)
Data Table on Canada - Market size and forecast 2025-2030 ($ thousand)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ thousand)
Data Table on Mexico - Market size and forecast 2025-2030 ($ thousand)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ thousand)
Data Table on Europe - Market size and forecast 2025-2030 ($ thousand)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ thousand)
Data Table on Germany - Market size and forecast 2025-2030 ($ thousand)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ thousand)
Data Table on UK - Market size and forecast 2025-2030 ($ thousand)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ thousand)
Data Table on France - Market size and forecast 2025-2030 ($ thousand)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ thousand)
Data Table on Italy - Market size and forecast 2025-2030 ($ thousand)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ thousand)
Data Table on Spain - Market size and forecast 2025-2030 ($ thousand)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ thousand)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ thousand)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Asia - Market size and forecast 2025-2030 ($ thousand)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ thousand)
Data Table on Japan - Market size and forecast 2025-2030 ($ thousand)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.2 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ thousand)
Data Table on China - Market size and forecast 2025-2030 ($ thousand)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.3 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ thousand)
Data Table on South Korea - Market size and forecast 2025-2030 ($ thousand)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.4 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ thousand)
Data Table on India - Market size and forecast 2025-2030 ($ thousand)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.5 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ thousand)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.5.6 Thailand - Market size and forecast 2025-2030

Chart on Thailand - Market size and forecast 2025-2030 ($ thousand)
Data Table on Thailand - Market size and forecast 2025-2030 ($ thousand)
Chart on Thailand - Year-over-year growth 2025-2030 (%)
Data Table on Thailand - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ thousand)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ thousand)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ thousand)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ thousand)
Data Table on UAE - Market size and forecast 2025-2030 ($ thousand)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.3 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ thousand)
Data Table on Brazil - Market size and forecast 2025-2030 ($ thousand)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ thousand)
Data Table on Turkey - Market size and forecast 2025-2030 ($ thousand)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.5 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Colombia - Market size and forecast 2025-2030 ($ thousand)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.6.6 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ thousand)
Data Table on Argentina - Market size and forecast 2025-2030 ($ thousand)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.7 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ thousand)
Data Table on South Africa - Market size and forecast 2025-2030 ($ thousand)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.8 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ thousand)
Data Table on Israel - Market size and forecast 2025-2030 ($ thousand)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ thousand)
Data Tables on Market opportunity by geography ($ thousand)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Increasing prevalence of sleep disordered breathing and clinical awareness
Rapid pace of innovation in neurostimulation technology
Expansion of insurance coverage and formalization of healthcare reimbursement pathways

13.2 Market challenges

Complications and surgical risks
Stringent regulatory and certification bottlenecks
Clinical resource and infrastructure constraints

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Emergence of bilateral hypoglossal nerve stimulation
Shift toward single incision surgical pathways
Rise of smart sleep tech and remote optimization

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Aveo Medical

Aveo Medical - Overview
Aveo Medical - Product / Service
Aveo Medical - Key offerings
SWOT

15.5 Avery Biomedical Devices Inc.

Avery Biomedical Devices Inc. - Overview
Avery Biomedical Devices Inc. - Product / Service
Avery Biomedical Devices Inc. - Key offerings
SWOT

15.6 Eunoia Medical

Eunoia Medical - Overview
Eunoia Medical - Product / Service
Eunoia Medical - Key offerings
SWOT

15.7 Inspire Medical Systems Inc.

Inspire Medical Systems Inc. - Overview
Inspire Medical Systems Inc. - Product / Service
Inspire Medical Systems Inc. - Key offerings
SWOT

15.8 Linguaflex Inc.

Linguaflex Inc. - Overview
Linguaflex Inc. - Product / Service
Linguaflex Inc. - Key offerings
SWOT

15.9 LivaNova PLC

LivaNova PLC - Overview
LivaNova PLC - Business segments
LivaNova PLC - Key offerings
LivaNova PLC - Segment focus
SWOT

15.10 Medtronic Plc

Medtronic Plc - Overview
Medtronic Plc - Business segments
Medtronic Plc - Key news
Medtronic Plc - Key offerings
Medtronic Plc - Segment focus
SWOT

15.11 Nyxoah SA

Nyxoah SA - Overview
Nyxoah SA - Product / Service
Nyxoah SA - Key offerings
SWOT

15.12 ProSomnus Inc.

ProSomnus Inc. - Overview
ProSomnus Inc. - Product / Service
ProSomnus Inc. - Key offerings
SWOT

15.13 Signifier Medical Technologies

Signifier Medical Technologies - Overview
Signifier Medical Technologies - Product / Service
Signifier Medical Technologies - Key offerings
SWOT

15.14 SomnoMed Ltd.

SomnoMed Ltd. - Overview
SomnoMed Ltd. - Business segments
SomnoMed Ltd. - Key offerings
SomnoMed Ltd. - Segment focus
SWOT

15.15 Vivos Therapeutics Inc.

Vivos Therapeutics Inc. - Overview
Vivos Therapeutics Inc. - Product / Service
Vivos Therapeutics Inc. - Key offerings
SWOT

15.16 Whole You Inc.

Whole You Inc. - Overview
Whole You Inc. - Product / Service
Whole You Inc. - Key offerings
SWOT

15.17 Zephyr Sleep Technologies

Zephyr Sleep Technologies - Overview
Zephyr Sleep Technologies - Product / Service
Zephyr Sleep Technologies - Key offerings
SWOT

15.18 ZOLL Respicardia

ZOLL Respicardia - Overview
ZOLL Respicardia - Product / Service
ZOLL Respicardia - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Sleep Apnea Implants market growth will increase by USD 543033.9 thousand thousand during 2026-2030.

The Sleep Apnea Implants market is expected to grow at a CAGR of 15.8% during 2026-2030.

Sleep Apnea Implants market is segmented by Indication (Central sleep apnea, Obstructive sleep apnea) End-user (Ambulatory surgical centers, Hospitals, Others) Product (Hypoglossal neurostimulation devices, Palatal implants, Bone screw systems, Phrenic nerve stimulators)

Aveo Medical, Avery Biomedical Devices Inc., Eunoia Medical, Inspire Medical Systems Inc., Linguaflex Inc., LivaNova PLC, Medtronic Plc, Nyxoah SA, ProSomnus Inc., Signifier Medical Technologies, SomnoMed Ltd., Vivos Therapeutics Inc., Whole You Inc., Zephyr Sleep Technologies, ZOLL Respicardia are a few of the key vendors in the Sleep Apnea Implants market.

North America will register the highest growth rate of 45% among the other regions. Therefore, the Sleep Apnea Implants market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Japan, China, South Korea, India, Indonesia, Thailand, Saudi Arabia, UAE, Brazil, Turkey, Colombia, Argentina, South Africa, Israel

  • Increasing prevalence of sleep disordered breathing and clinical awareness is the driving factor this market.

The Sleep Apnea Implants market vendors should focus on grabbing business opportunities from the Indication segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
