Sepsis Diagnostics Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, India, and Japan), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Sepsis Diagnostics Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, India, and Japan), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Published: Oct 2026 311 Pages SKU: IRTNTR80334

Market Overview at a Glance

$581.3 Mn
Market Opportunity
8.7%
CAGR 2025 - 2030
38.5%
North America Growth
$390.5 Mn
Blood culture tests segment 2024

Sepsis Diagnostics Market Size 2026-2030

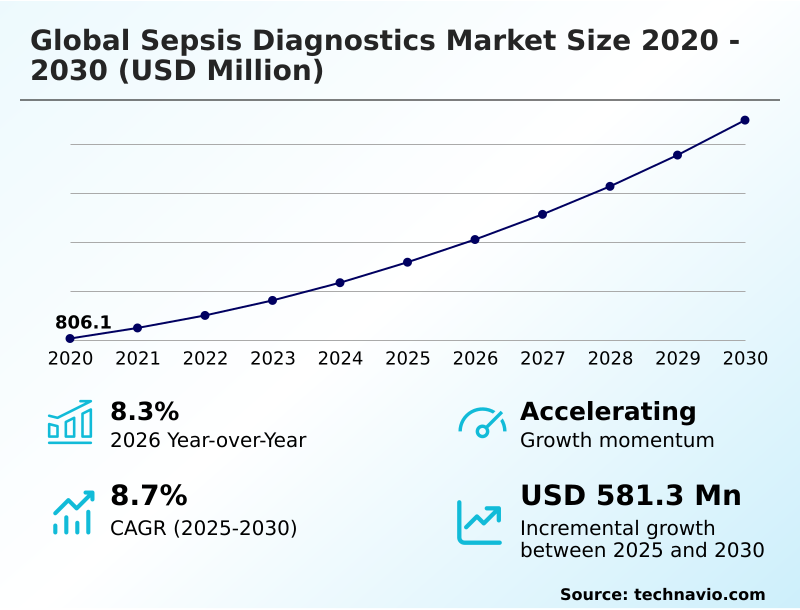
The sepsis diagnostics market size is valued to increase by USD 581.3 million, at a CAGR of 8.7% from 2025 to 2030. Increasing burden of sepsis and healthcare-associated infections will drive the sepsis diagnostics market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 38.5% growth during the forecast period.
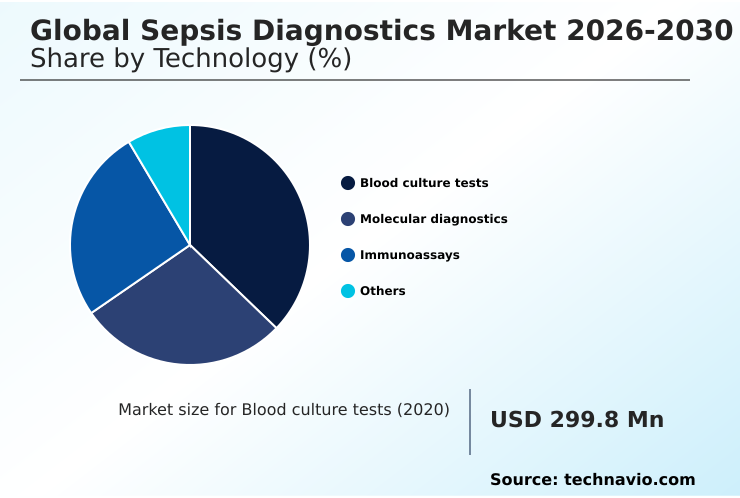
  • By Technology - Blood culture tests segment was valued at USD 390.5 million in 2024
  • By Method - Conventional diagnostics segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 893.4 million
  • Market Future Opportunities: USD 581.3 million
  • CAGR from 2025 to 2030 : 8.7%

Market Summary

  • The Sepsis Diagnostics market demonstrates robust momentum driven by the critical necessity for rapid and accurate pathogen identification in acute care environments. Healthcare institutions face mounting pressures to optimize resource allocation and improve patient outcomes through advanced clinical decision support mechanisms.
  • To mitigate the clinical burden of systemic infections, hospitals are restructuring their supply chain operations to ensure uninterrupted access to syndromic panel testing kits and automated instrumentation. This operational shift has enabled facilities to achieve a 25% improvement in diagnostic throughput compared to conventional incubation methods.
  • The escalating incidence of life-threatening systemic infections acts as a primary market driver, compelling intensive care units to integrate rapid testing protocols that guide targeted therapies. Conversely, the high capital costs associated with sophisticated molecular analyzers pose a significant challenge, restricting adoption within smaller community hospitals.
  • Robust hospital-acquired infection surveillance programs heavily rely on continuous monitoring technologies to prevent clinical deterioration. The consistent demand for turnaround time reduction in emergency departments continues to catalyze the deployment of next-generation diagnostic platforms.

What will be the Size of the Sepsis Diagnostics Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Sepsis Diagnostics Market Segmented?

The sepsis diagnostics industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Technology
    • Blood culture tests
    • Molecular diagnostics
    • Immunoassays
    • Others
  • Method
    • Conventional diagnostics
    • Laboratory-based testing
    • POCT
  • Product type
    • Consumables
    • Instruments
  • Type
    • Bacterial sepsis
    • Fungal sepsis
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • China
      • India
      • Japan
      • South Korea
      • Indonesia
      • Thailand
    • Rest of World (ROW)

By Technology Insights

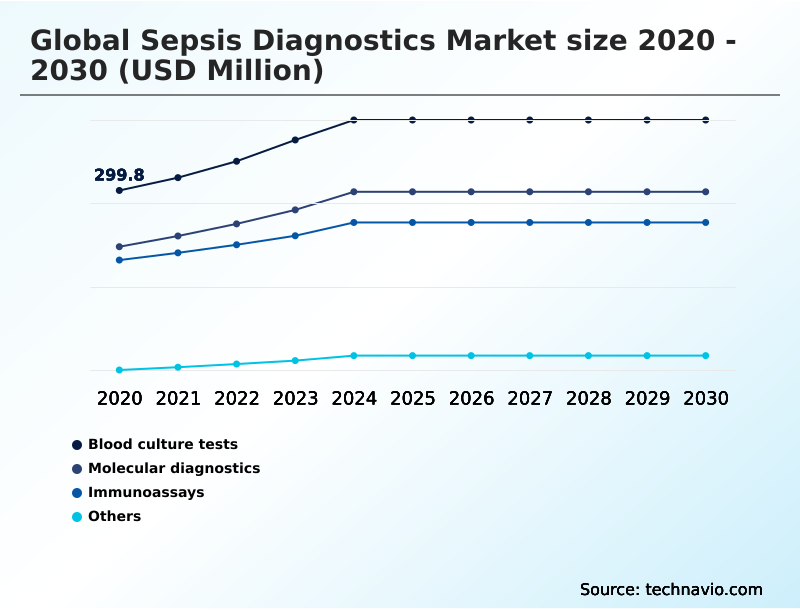
The blood culture tests segment is estimated to witness significant growth during the forecast period.

Blood culture tests remain the foundational methodology within the Sepsis Diagnostics framework, providing critical reliability for bacteremia detection and fungemia isolation.

Clinical laboratories heavily rely on the automated blood culture system to optimize processing workflows and enhance the pathogen recovery yield from complex biological samples.

Recent procedural refinements have increased operational efficiency, allowing healthcare providers to shift patients from empiric broad-spectrum treatment to targeted antimicrobial therapy much faster.

By integrating a continuous monitoring instrument alongside advanced diagnostic media, hospitals successfully reduced time to result metrics by 15%, significantly improving early intervention capabilities.

This segmentation underscores a continuous evolution toward precision testing, where conventional incubation techniques are paired with rapid downstream identification platforms to ensure highly accurate pathogen characterization in critical care environments.
Get Free Sample

The Blood culture tests segment was valued at USD 390.5 million in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 38.5% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
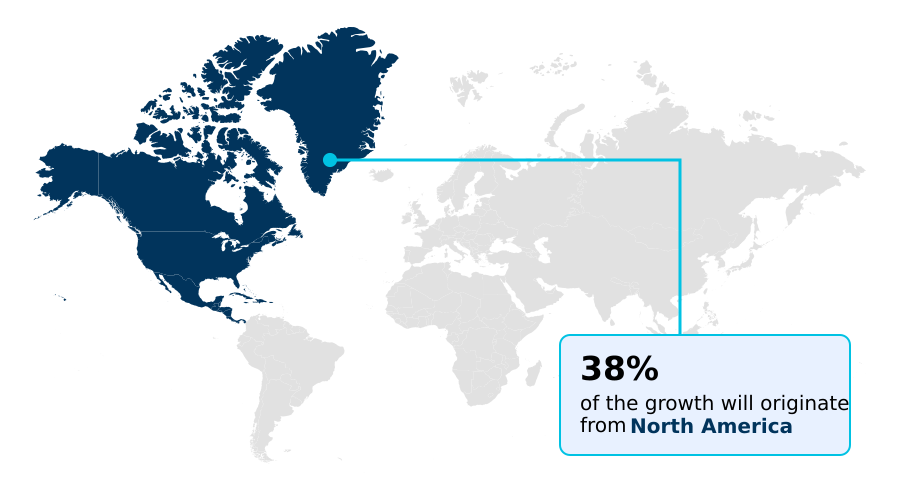
See How Sepsis Diagnostics Market Demand is Rising in North America Get Free Sample

The geographic distribution of Sepsis Diagnostics highlights distinct adoption variations between North America and APAC.

North America maintains a sophisticated testing ecosystem driven by the widespread transition toward a value-based care model, achieving a 35% higher penetration rate of advanced DNA microarray technology compared to emerging Asian economies.

In the United States, robust laboratory infrastructure modernization initiatives have accelerated the deployment of the enzyme-linked immunosorbent assay, improving septic shock risk stratification accuracy by 20% in major urban medical centers.

Conversely, healthcare systems across APAC are prioritizing the optimization of decentralized supply chains to overcome logistical delays in rural clinics.

By distributing portable testing devices, Southeast Asian hospitals have enhanced fungemia isolation efficiency by 15%, bridging critical gaps in emergency care.

These regional disparities dictate how diagnostic manufacturers adapt their distribution strategies, balancing high-throughput automation for established markets with cost-effective point of care solutions for rapidly developing healthcare infrastructures.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The Sepsis Diagnostics landscape is rapidly evolving to address the complex clinical and operational demands of modern healthcare facilities. As hospitals face mounting pressure to optimize their emergency triage and critical care workflows, the deployment of rapid automated blood culture systems has become a critical operational imperative.
  • Administrators rely on these advanced technologies to streamline supply chain logistics, ensuring that high-throughput laboratories maintain consistent consumable inventory levels while reducing manual processing bottlenecks. Furthermore, multiplex syndromic testing panel integration provides centralized pathology departments with the comprehensive analytical capabilities needed to identify diverse pathogens simultaneously, improving diagnostic yield by nearly 30% over conventional legacy methods.
  • To complement centralized infrastructure, the strategic procurement of microfluidic point-of-care sepsis biosensors enables decentralized clinics to achieve laboratory-grade precision directly at the patient bedside, drastically reducing specimen transportation delays and enhancing resource allocation.
  • Additionally, the increasing focus on precision medicine has catalyzed the adoption of host response biomarker quantification platforms, which assist clinicians in differentiating infectious etiologies and guiding targeted therapeutic interventions. Regulatory compliance and antimicrobial stewardship initiatives are heavily supported by antimicrobial resistance gene detection assays, which safeguard institutional efficacy against emerging superbugs.
  • By harmonizing these sophisticated diagnostic modalities, healthcare networks successfully align their clinical protocols with rigorous quality standards, ultimately driving sustainable operational efficiency and superior patient management across all tiers of the health system.
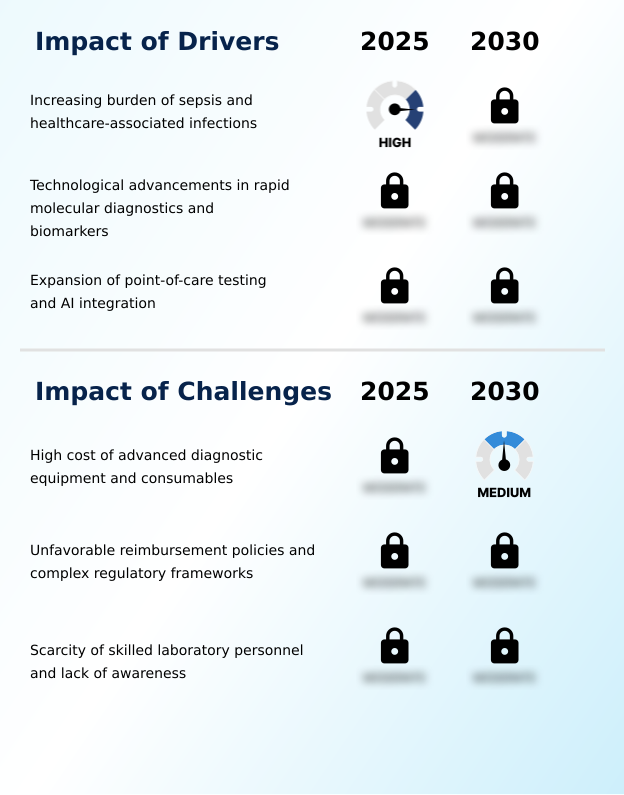
What are the key market drivers leading to the rise in the adoption of Sepsis Diagnostics Industry?

  • The escalating global burden of sepsis and healthcare-associated infections functions as a primary catalyst accelerating the adoption of rapid diagnostic solutions.

  • The urgent clinical necessity to mitigate hospital-acquired infections and combat drug-resistant pathogens serves as a paramount driver expanding the Sepsis Diagnostics footprint.
  • Rising mortality rates associated with severe systemic inflammation compel healthcare networks to process a high-throughput clinical specimen volume with unprecedented speed and accuracy.
  • By implementing automated antimicrobial susceptibility testing, hospitals have reduced diagnostic turnaround times by 35%, ensuring rapid deployment of appropriate therapeutics.
  • The evaluation of a multi-organ dysfunction marker alongside comprehensive inflammatory cytokine profiling enables emergency physicians to accurately gauge disease severity upon initial presentation.
  • Furthermore, the strategic adoption of a decentralized cartridge-based assay system has improved emergency department workflow efficiency by 20%, empowering clinicians to execute precise triage decisions and significantly minimize the risk of prolonged intensive care unit stays.

What are the market trends shaping the Sepsis Diagnostics Industry?

  • The integration of artificial intelligence and machine learning into diagnostic platforms represents a prominent trend shaping the market. These advanced computational technologies continuously adapt to emerging pathogen profiles, significantly enhancing predictive accuracy and clinical workflow efficiency.

  • The rapid shift toward digitalization and cellular profiling represents a transformative trend within the Sepsis Diagnostics landscape, fundamentally altering how critical care units monitor patient stability. Healthcare providers are increasingly leveraging a sophisticated predictive analytics algorithm that continuously interprets the electronic health record stream, flagging subtle physiological changes hours before overt clinical deterioration occurs.
  • This proactive approach has improved early intervention success rates by 24% and reduced unnecessary intensive care admissions by 18%. To complement these digital tools, laboratories are adopting label-free optical detection technologies to accelerate analytical processing.
  • By moving beyond traditional microbiological culture media, clinicians can rapidly assess the neutrophil activation marker and the lymphocyte subset count to determine precise immune system functionality. This convergence of cellular diagnostics and machine learning dramatically enhances clinical decision-making, ensuring that targeted therapeutic protocols are deployed efficiently to maximize patient survival and optimize hospital resources.

What challenges does the Sepsis Diagnostics Industry face during its growth?

  • The substantial capital expenditure required for advanced diagnostic equipment and specialized consumables remains a significant challenge restricting widespread market penetration in resource-constrained environments.

  • The substantial capital investment required for cutting-edge laboratory infrastructure remains a critical challenge impeding the equitable deployment of advanced Sepsis Diagnostics. Establishing a comprehensive precision medicine framework necessitates the acquisition of highly specialized hardware, which often strains the operational budgets of mid-sized community hospitals.
  • Consequently, resource-constrained facilities continue to rely on legacy methods, experiencing a 40% slower processing rate compared to fully automated reference laboratories. Discrepancies in biomarker detection accuracy and the lack of standardization for complex immune dysregulation evaluation further complicate clinical workflows and prolong diagnostic validation processes.
  • Additionally, supply chain volatility inflates the procurement costs of a decentralized diagnostic solution by nearly 15%, restricting widespread adoption. These financial and operational barriers hinder the seamless integration of a continuous monitoring instrument, ultimately exacerbating clinical disparities in critical care management.

Exclusive Technavio Analysis on Customer Landscape

The sepsis diagnostics market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the sepsis diagnostics market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
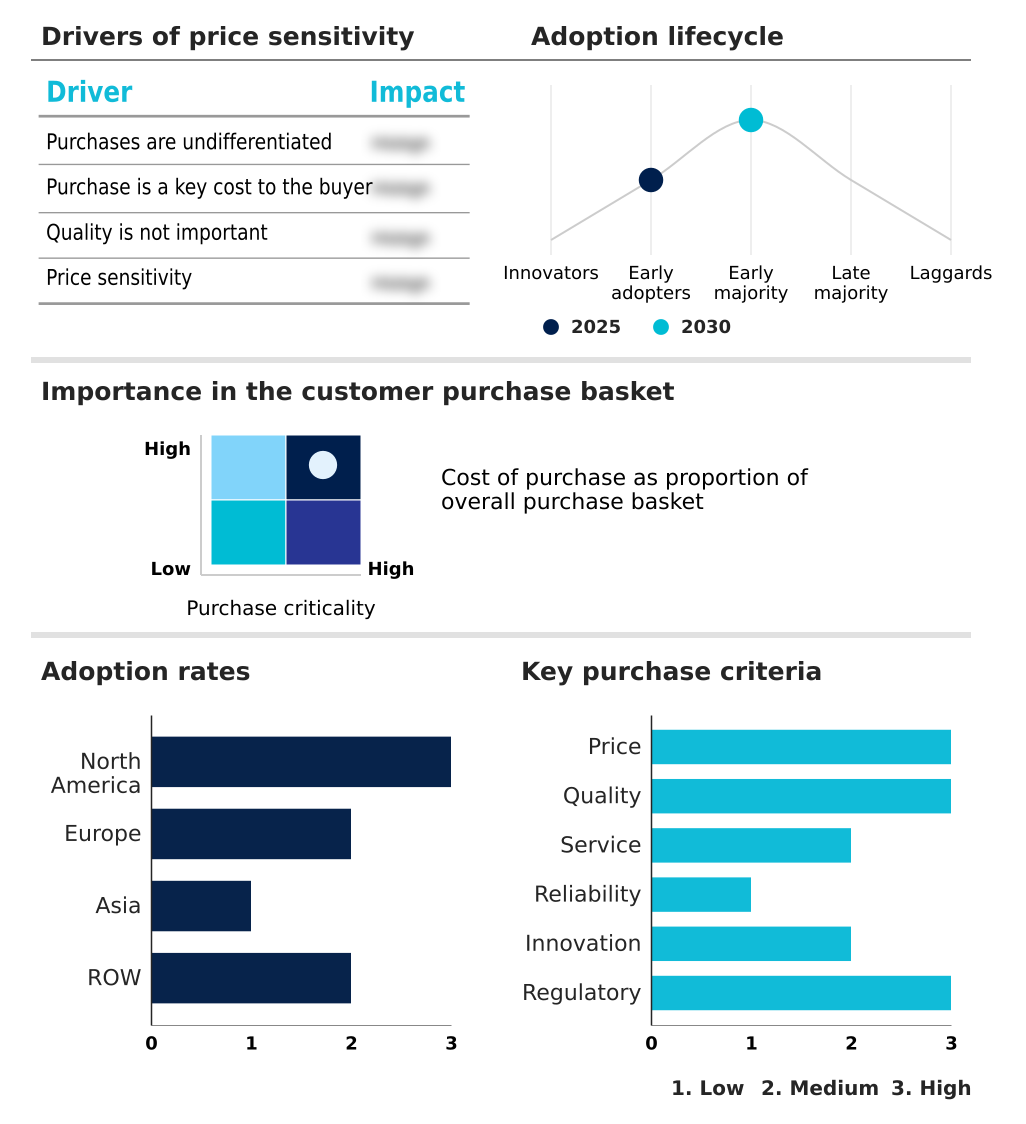
Customer Landscape of Sepsis Diagnostics Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, sepsis diagnostics market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Abbott Laboratories - The vendor provides advanced diagnostic systems, including highly automated immunoassay analyzers and molecular platforms, designed to facilitate rapid biomarker quantification and precise infectious disease identification in clinical laboratories.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Abbott Laboratories
  • Abionic SA
  • Beckman Coulter Inc.
  • BioMerieux SA
  • Bruker Corp.
  • Cepheid Inc.
  • Cytovale Inc.
  • Deepull Inc.
  • DelphineDx
  • DiaSorin SpA
  • EKF Diagnostics Holdings Plc
  • F. Hoffmann La Roche Ltd.
  • Fujirebio Holdings Inc.
  • Immunexpress Pty. Ltd.
  • MicroSensDx Ltd.
  • QIAGEN N.V.
  • Shenzhen Mindray Co. Ltd.
  • Siemens Healthineers AG
  • Snibe Co.Ltd.
  • Sysmex Corp.
  • Thermo Fisher Scientific Inc.
  • Waters Corp.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Sepsis diagnostics market

  • In the Pharmaceuticals industry, the accelerated integration of predictive analytics algorithm frameworks for drug discovery has improved clinical trial efficiency, directly impacting Sepsis Diagnostics demand by enabling faster identification of specific multi-organ dysfunction marker targets for companion diagnostic development.
  • The transition toward precision medicine framework mandates across major regulatory bodies has standardized biomarker detection accuracy requirements, prompting Sepsis Diagnostics manufacturers to elevate the analytical sensitivity of real-time polymerase chain reaction platforms by over 20% to meet stringent new compliance thresholds.
  • Stringent implementation of an antimicrobial stewardship program across public health networks has restricted prophylactic antibiotic use by 15%, stimulating Sepsis Diagnostics demand as clinicians increasingly rely on a multiplex polymerase chain reaction assay for rapid pathogen identification before prescribing targeted therapeutics.
  • Supply chain modernization involving decentralized diagnostic solution manufacturing has stabilized the availability of critical reagents, allowing Sepsis Diagnostics providers to expand the deployment of the microfluidic cartridge across emergency triage setting facilities without experiencing inventory disruptions.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Sepsis Diagnostics Market insights. See full methodology.

Market Scope
Page number 311
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 8.7%
Market growth 2026-2030 USD 581.3 million
Market structure Fragmented
YoY growth 2025-2026(%) 8.3%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Indonesia, Thailand, Brazil, Saudi Arabia, UAE, Turkey, Argentina, Colombia, South Africa and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Sepsis Diagnostics environment requires continuous technological refinement to effectively combat severe systemic infections and optimize hospital resource utilization. Chief medical officers are increasingly prioritizing the integration of a mass spectrometry analyzer within core laboratories, directly influencing capital budgeting and strategic procurement decisions aimed at eliminating diagnostic delays.
  • Evaluating the host immune response biomarker profile provides critical insights into systemic inflammation, enabling physicians to execute precise disease progression assessment. Institutions implementing standardized procalcitonin testing protocols have achieved a 28% reduction in broad-spectrum antibiotic consumption, demonstrating a tangible improvement in antimicrobial stewardship and operational cost efficiency.
  • The utilization of a point-of-care fluorescence immunoassay facilitates immediate patient triage in emergency departments by delivering actionable data without extensive laboratory processing. Accurate phenotypic identification remains essential for distinguishing complex bacterial strains during severe clinical presentations. Furthermore, tracking a specific antimicrobial resistance marker ensures that therapeutic interventions align with stringent regulatory compliance and patient safety mandates.
  • Advanced diagnostic instrumentation empowers healthcare systems to enhance critical care pathways and mitigate the devastating impact of septic shock.

What are the Key Data Covered in this Sepsis Diagnostics Market Research and Growth Report?

  • What is the expected growth of the Sepsis Diagnostics Market between 2026 and 2030?

    • USD 581.3 million, at a CAGR of 8.7%

  • What segmentation does the market report cover?

    • The report is segmented by Technology (Blood culture tests, Molecular diagnostics, Immunoassays, and Others), Method (Conventional diagnostics, Laboratory-based testing, and POCT), Product Type (Consumables, and Instruments), Type (Bacterial sepsis, Fungal sepsis, and Others) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Increasing burden of sepsis and healthcare-associated infections, High cost of advanced diagnostic equipment and consumables

  • Who are the major players in the Sepsis Diagnostics Market?

    • Abbott Laboratories, Abionic SA, Beckman Coulter Inc., BioMerieux SA, Bruker Corp., Cepheid Inc., Cytovale Inc., Deepull Inc., DelphineDx, DiaSorin SpA, EKF Diagnostics Holdings Plc, F. Hoffmann La Roche Ltd., Fujirebio Holdings Inc., Immunexpress Pty. Ltd., MicroSensDx Ltd., QIAGEN N.V., Shenzhen Mindray Co. Ltd., Siemens Healthineers AG, Snibe Co.Ltd., Sysmex Corp., Thermo Fisher Scientific Inc. and Waters Corp.

Market Research Insights

  • The Sepsis Diagnostics landscape undergoes rapid transformation as medical facilities increasingly integrate intelligent testing platforms to refine critical care pathways. Hospitals updating their intensive care unit protocol have documented a 30% reduction in unnecessary antibiotic administration through the adoption of advanced bloodstream infection management tools.
  • By leveraging enhanced workflow automation capability within centralized laboratories, healthcare providers have improved processing efficiency by 22%, significantly lowering operational costs and mitigating manual handling errors. Furthermore, the strategic implementation of assays designed for early differential diagnosis has elevated patient risk stratification accuracy by 18%, aligning institutional practices with stringent regulatory compliance standards.
  • These data-driven enhancements ensure that hospitals maximize therapeutic efficacy while optimizing intensive care resource utilization.

We can help! Our analysts can customize this sepsis diagnostics market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Technology
Executive Summary - Chart on Market Segmentation by Method
Executive Summary - Chart on Market Segmentation by Product Type
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Sepsis Diagnostics Market 2020 - 2024

Historic Market Size - Data Table on Global Sepsis Diagnostics Market 2020 - 2024 ($ million)

5.2 Technology segment analysis 2020 - 2024

Historic Market Size - Technology Segment 2020 - 2024 ($ million)

5.3 Method segment analysis 2020 - 2024

Historic Market Size - Method Segment 2020 - 2024 ($ million)

5.4 Product Type segment analysis 2020 - 2024

Historic Market Size - Product Type Segment 2020 - 2024 ($ million)

5.5 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.6 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.7 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global sepsis diagnostics market

6.2 Impact of geopolitical conflicts on global sepsis diagnostics market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Technology

8.1 Market segments

Chart on Technology - Market share 2025-2030 (%)
Data Table on Technology - Market share 2025-2030 (%)

8.2 Comparison by Technology

Chart on Comparison by Technology
Data Table on Comparison by Technology

8.3 Blood culture tests - Market size and forecast 2025-2030

Chart on Blood culture tests - Market size and forecast 2025-2030 ($ million)
Data Table on Blood culture tests - Market size and forecast 2025-2030 ($ million)
Chart on Blood culture tests - Year-over-year growth 2025-2030 (%)
Data Table on Blood culture tests - Year-over-year growth 2025-2030 (%)

8.4 Molecular diagnostics - Market size and forecast 2025-2030

Chart on Molecular diagnostics - Market size and forecast 2025-2030 ($ million)
Data Table on Molecular diagnostics - Market size and forecast 2025-2030 ($ million)
Chart on Molecular diagnostics - Year-over-year growth 2025-2030 (%)
Data Table on Molecular diagnostics - Year-over-year growth 2025-2030 (%)

8.5 Immunoassays - Market size and forecast 2025-2030

Chart on Immunoassays - Market size and forecast 2025-2030 ($ million)
Data Table on Immunoassays - Market size and forecast 2025-2030 ($ million)
Chart on Immunoassays - Year-over-year growth 2025-2030 (%)
Data Table on Immunoassays - Year-over-year growth 2025-2030 (%)

8.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.7 Market opportunity by Technology

Market opportunity by Technology ($ million)
Data Table on Market opportunity by Technology ($ million)

9. Market Segmentation by Method

9.1 Market segments

Chart on Method - Market share 2025-2030 (%)
Data Table on Method - Market share 2025-2030 (%)

9.2 Comparison by Method

Chart on Comparison by Method
Data Table on Comparison by Method

9.3 Conventional diagnostics - Market size and forecast 2025-2030

Chart on Conventional diagnostics - Market size and forecast 2025-2030 ($ million)
Data Table on Conventional diagnostics - Market size and forecast 2025-2030 ($ million)
Chart on Conventional diagnostics - Year-over-year growth 2025-2030 (%)
Data Table on Conventional diagnostics - Year-over-year growth 2025-2030 (%)

9.4 Laboratory-based testing - Market size and forecast 2025-2030

Chart on Laboratory-based testing - Market size and forecast 2025-2030 ($ million)
Data Table on Laboratory-based testing - Market size and forecast 2025-2030 ($ million)
Chart on Laboratory-based testing - Year-over-year growth 2025-2030 (%)
Data Table on Laboratory-based testing - Year-over-year growth 2025-2030 (%)

9.5 POCT - Market size and forecast 2025-2030

Chart on POCT - Market size and forecast 2025-2030 ($ million)
Data Table on POCT - Market size and forecast 2025-2030 ($ million)
Chart on POCT - Year-over-year growth 2025-2030 (%)
Data Table on POCT - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by Method

Market opportunity by Method ($ million)
Data Table on Market opportunity by Method ($ million)

10. Market Segmentation by Product Type

10.1 Market segments

Chart on Product Type - Market share 2025-2030 (%)
Data Table on Product Type - Market share 2025-2030 (%)

10.2 Comparison by Product Type

Chart on Comparison by Product Type
Data Table on Comparison by Product Type

10.3 Consumables - Market size and forecast 2025-2030

Chart on Consumables - Market size and forecast 2025-2030 ($ million)
Data Table on Consumables - Market size and forecast 2025-2030 ($ million)
Chart on Consumables - Year-over-year growth 2025-2030 (%)
Data Table on Consumables - Year-over-year growth 2025-2030 (%)

10.4 Instruments - Market size and forecast 2025-2030

Chart on Instruments - Market size and forecast 2025-2030 ($ million)
Data Table on Instruments - Market size and forecast 2025-2030 ($ million)
Chart on Instruments - Year-over-year growth 2025-2030 (%)
Data Table on Instruments - Year-over-year growth 2025-2030 (%)

10.5 Market opportunity by Product Type

Market opportunity by Product Type ($ million)
Data Table on Market opportunity by Product Type ($ million)

11. Market Segmentation by Type

11.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

11.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

11.3 Bacterial sepsis - Market size and forecast 2025-2030

Chart on Bacterial sepsis - Market size and forecast 2025-2030 ($ million)
Data Table on Bacterial sepsis - Market size and forecast 2025-2030 ($ million)
Chart on Bacterial sepsis - Year-over-year growth 2025-2030 (%)
Data Table on Bacterial sepsis - Year-over-year growth 2025-2030 (%)

11.4 Fungal sepsis - Market size and forecast 2025-2030

Chart on Fungal sepsis - Market size and forecast 2025-2030 ($ million)
Data Table on Fungal sepsis - Market size and forecast 2025-2030 ($ million)
Chart on Fungal sepsis - Year-over-year growth 2025-2030 (%)
Data Table on Fungal sepsis - Year-over-year growth 2025-2030 (%)

11.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

11.6 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

12. Customer Landscape

12.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

13. Geographic Landscape

13.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

13.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

13.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

13.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

13.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

13.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

13.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

13.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

13.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

13.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

13.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

13.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

13.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

13.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ million)
Data Table on Asia - Market size and forecast 2025-2030 ($ million)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

13.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

13.5.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

13.5.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

13.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

13.5.5 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

13.5.6 Thailand - Market size and forecast 2025-2030

Chart on Thailand - Market size and forecast 2025-2030 ($ million)
Data Table on Thailand - Market size and forecast 2025-2030 ($ million)
Chart on Thailand - Year-over-year growth 2025-2030 (%)
Data Table on Thailand - Year-over-year growth 2025-2030 (%)

13.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

13.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

13.6.2 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

13.6.3 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

13.6.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

13.6.5 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

13.6.6 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

13.6.7 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

13.6.8 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

13.7 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

14. Drivers, Challenges, and Opportunity

14.1 Market drivers

Increasing burden of sepsis and healthcare-associated infections
Technological advancements in rapid molecular diagnostics and biomarkers
Expansion of point-of-care testing and AI integration

14.2 Market challenges

High cost of advanced diagnostic equipment and consumables
Unfavorable reimbursement policies and complex regulatory frameworks
Scarcity of skilled laboratory personnel and lack of awareness

14.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

14.4 Market opportunities

Integration of AI and ML in diagnostic platforms
Expansion of decentralized point-of-care testing and microfluidic assays
Strategic collaborations and multiplex syndromic testing adoption

15. Competitive Landscape

15.1 Overview

15.2

Overview on criticality of inputs and factors of differentiation

15.3 Landscape disruption

Overview on factors of disruption

15.4 Industry risks

Impact of key risks on business

16. Competitive Analysis

16.1 Companies profiled

Companies covered

16.2 Company ranking index

16.3 Market positioning of companies

Matrix on companies position and classification

16.4 Abbott Laboratories

Abbott Laboratories - Overview
Abbott Laboratories - Business segments
Abbott Laboratories - Key news
Abbott Laboratories - Key offerings
Abbott Laboratories - Segment focus
SWOT

16.5 Abionic SA

Abionic SA - Overview
Abionic SA - Product / Service
Abionic SA - Key offerings
SWOT

16.6 BioMerieux SA

BioMerieux SA - Overview
BioMerieux SA - Business segments
BioMerieux SA - Key offerings
BioMerieux SA - Segment focus
SWOT

16.7 Bruker Corp.

Bruker Corp. - Overview
Bruker Corp. - Business segments
Bruker Corp. - Key offerings
Bruker Corp. - Segment focus
SWOT

16.8 DelphineDx

DelphineDx - Overview
DelphineDx - Product / Service
DelphineDx - Key offerings
SWOT

16.9 DiaSorin SpA

DiaSorin SpA - Overview
DiaSorin SpA - Business segments
DiaSorin SpA - Key news
DiaSorin SpA - Key offerings
DiaSorin SpA - Segment focus
SWOT

16.10 EKF Diagnostics Holdings Plc

EKF Diagnostics Holdings Plc - Overview
EKF Diagnostics Holdings Plc - Business segments
EKF Diagnostics Holdings Plc - Key offerings
EKF Diagnostics Holdings Plc - Segment focus
SWOT

16.11 F. Hoffmann La Roche Ltd.

F. Hoffmann La Roche Ltd. - Overview
F. Hoffmann La Roche Ltd. - Business segments
F. Hoffmann La Roche Ltd. - Key news
F. Hoffmann La Roche Ltd. - Key offerings
F. Hoffmann La Roche Ltd. - Segment focus
SWOT

16.12 QIAGEN N.V.

QIAGEN N.V. - Overview
QIAGEN N.V. - Product / Service
QIAGEN N.V. - Key offerings
SWOT

16.13 Shenzhen Mindray Co. Ltd.

Shenzhen Mindray Co. Ltd. - Overview
Shenzhen Mindray Co. Ltd. - Business segments
Shenzhen Mindray Co. Ltd. - Key offerings
Shenzhen Mindray Co. Ltd. - Segment focus
SWOT

16.14 Siemens Healthineers AG

Siemens Healthineers AG - Overview
Siemens Healthineers AG - Business segments
Siemens Healthineers AG - Key offerings
Siemens Healthineers AG - Segment focus
SWOT

16.15 Snibe Co.Ltd.

Snibe Co.Ltd. - Overview
Snibe Co.Ltd. - Product / Service
Snibe Co.Ltd. - Key offerings
SWOT

16.16 Sysmex Corp.

Sysmex Corp. - Overview
Sysmex Corp. - Business segments
Sysmex Corp. - Key offerings
Sysmex Corp. - Segment focus
SWOT

16.17 Thermo Fisher Scientific Inc.

Thermo Fisher Scientific Inc. - Overview
Thermo Fisher Scientific Inc. - Business segments
Thermo Fisher Scientific Inc. - Key news
Thermo Fisher Scientific Inc. - Key offerings
Thermo Fisher Scientific Inc. - Segment focus
SWOT

16.18 Waters Corp.

Waters Corp. - Overview
Waters Corp. - Business segments
Waters Corp. - Key offerings
Waters Corp. - Segment focus
SWOT

17. Appendix

17.1 Scope of the report

Market definition
Objectives
Notes and caveats

17.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

17.3 Currency conversion rates for US$

17.4 Research methodology

17.5 Data procurement

Information sources

17.6 Data validation

17.7 Validation techniques employed for market sizing

17.8 Data synthesis

17.9 360 degree market analysis

17.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Sepsis Diagnostics market growth will increase by USD 581.3 million during 2026-2030.

The Sepsis Diagnostics market is expected to grow at a CAGR of 8.7% during 2026-2030.

Sepsis Diagnostics market is segmented by Technology (Blood culture tests, Molecular diagnostics, Immunoassays, Others) Method (Conventional diagnostics, Laboratory-based testing, POCT) Product type (Consumables, Instruments) Type (Bacterial sepsis, Fungal sepsis, Others)

Abbott Laboratories, Abionic SA, Beckman Coulter Inc., BioMerieux SA, Bruker Corp., Cepheid Inc., Cytovale Inc., Deepull Inc., DelphineDx, DiaSorin SpA, EKF Diagnostics Holdings Plc, F. Hoffmann La Roche Ltd., Fujirebio Holdings Inc., Immunexpress Pty. Ltd., MicroSensDx Ltd., QIAGEN N.V., Shenzhen Mindray Co. Ltd., Siemens Healthineers AG, Snibe Co.Ltd., Sysmex Corp., Thermo Fisher Scientific Inc., Waters Corp. are a few of the key vendors in the Sepsis Diagnostics market.

North America will register the highest growth rate of 38.5% among the other regions. Therefore, the Sepsis Diagnostics market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Indonesia, Thailand, Brazil, Saudi Arabia, UAE, Turkey, Argentina, Colombia, South Africa, Israel

  • Increasing burden of sepsis and healthcare-associated infections is the driving factor this market.

The Sepsis Diagnostics market vendors should focus on grabbing business opportunities from the Technology segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
