


5G Equipment Market Size 2026-2030
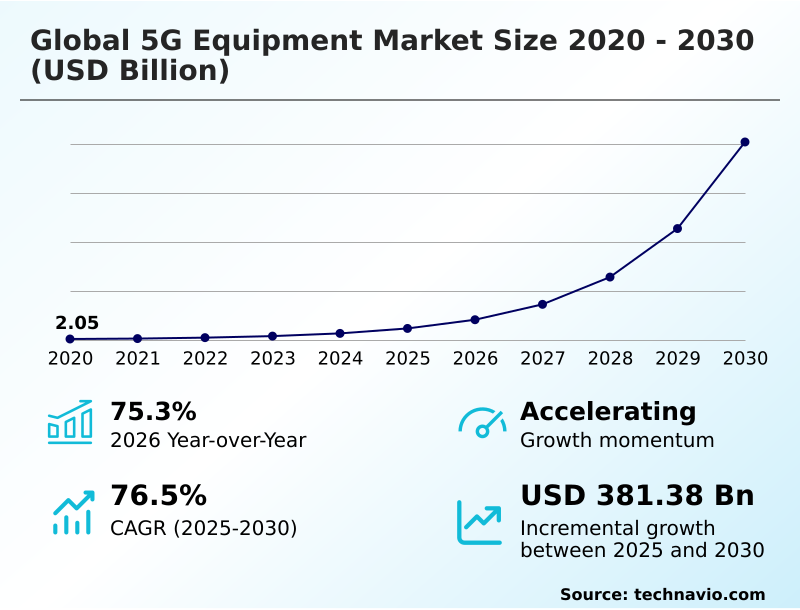
The 5g equipment market size is valued to increase by USD 381.38 billion, at a CAGR of 76.5% from 2025 to 2030. Surge in IoT adoption and enterprise digital transformation will drive the 5g equipment market.
Major Market Trends & Insights
- North America dominated the market and accounted for a 31.7% growth during the forecast period.
- By Product - Macrocell segment was valued at USD 8.40 billion in 2024
- By End-user - Non-retail sector segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 402.97 billion
- Market Future Opportunities: USD 381.38 billion
- CAGR from 2025 to 2030 : 76.5%
Market Summary
- The 5G Equipment market facilitates the critical transition from legacy telecommunications infrastructure to advanced wireless architectures capable of supporting complex industrial operations. A primary driver of this market is the aggressive adoption of intelligent automation in manufacturing, where ultra reliable low latency communication ensures real-time synchronization of robotics.
- This demand forces operators to deploy dense networks of small cells and edge computing hardware to support localized data processing. Conversely, the market faces a significant challenge regarding the intricate technical complexity and capital required for comprehensive spectrum allocation and network deployment. Securing municipal site permits and upgrading backhaul transport systems disrupt implementation timelines and operational budgets.
- In real-world supply chain optimization, enterprises utilizing private 5G networks achieve a 30% reduction in inventory tracking latency compared to traditional wireless setups, significantly enhancing predictive logistics. These hardware investments empower organizations to leverage high-bandwidth applications, thereby fundamentally altering operational capabilities while demanding rigorous strategic planning to overcome formidable deployment barriers.
What will be the Size of the 5G Equipment Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the 5G Equipment Market Segmented?
The 5g equipment industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Product
- Macrocell
- Small cell
- Others
- End-user
- Non-retail sector
- Retail sector
- Technology
- NFV
- SDN
- MEC
- Geography
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- APAC
- China
- Japan
- South Korea
- India
- Australia
- Indonesia
- Middle East and Africa
- Saudi Arabia
- UAE
- South Africa
- Turkey
- Israel
- South America
- Brazil
- Argentina
- Chile
- North America
By Product Insights
The macrocell segment is estimated to witness significant growth during the forecast period.
The macrocell segment in the 5G Equipment market functions as the foundational layer for establishing widespread and contiguous network coverage essential for continuous digital connectivity.
These high-power base stations support broad regional footprints where small cell densification proves less operationally viable. The integration of a massive MIMO antenna and millimeter-wave spectrum drastically improves network throughput in high-traffic zones.
Utilizing an energy-efficient base station alongside advanced radio technology enables operators to achieve a 25% reduction in power consumption per gigabyte transferred.
This network capacity expansion directly enhances enterprise connectivity, resulting in a 15% improvement in data transmission reliability across suburban deployments compared to traditional cell towers.
Such technological integration fundamentally re-architects the macro layer, yielding a highly automated infrastructure capable of managing dynamic traffic loads with precision.
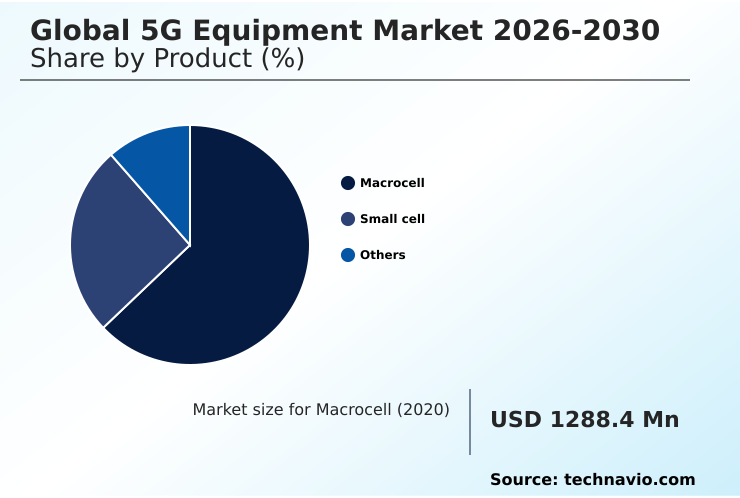
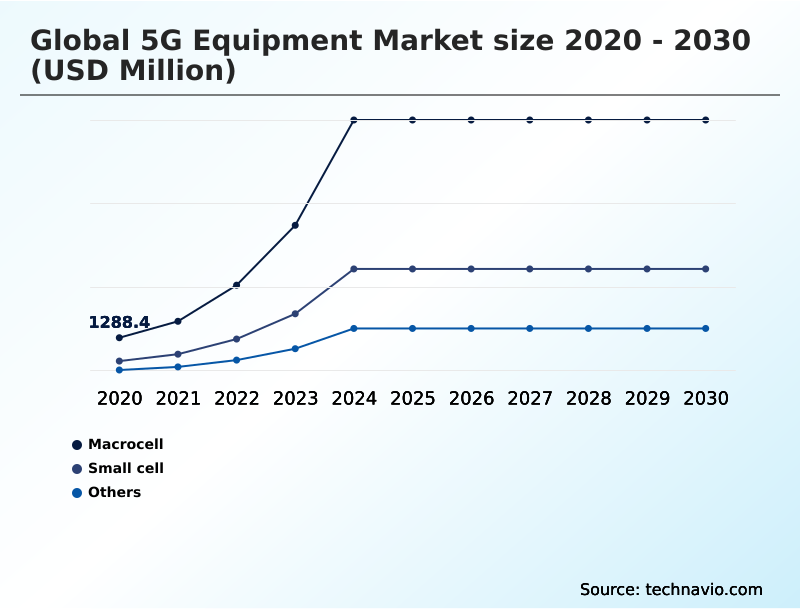
The Macrocell segment was valued at USD 8.40 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
North America is estimated to contribute 31.7% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
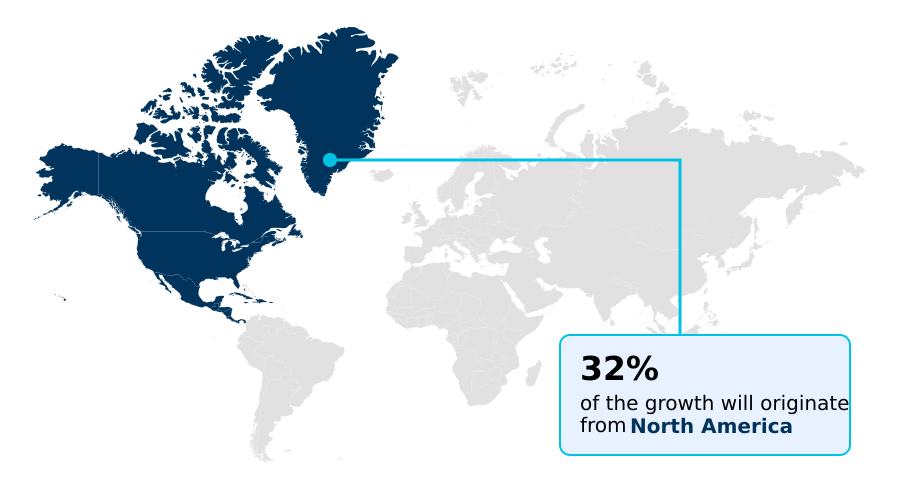
See How 5G Equipment Market Demand is Rising in North America Get Free Sample
The geographic landscape of the 5G Equipment market reveals distinct deployment strategies driven by localized industrial demands and regulatory frameworks.
North America accelerates its transition toward a standalone 5G architecture, focusing heavily on small cell densification to support enterprise connectivity, which has improved urban network capacity by 35% compared to legacy LTE environments.
In contrast, Europe emphasizes the integration of an open radio access network ecosystem to diversify supply chains, reducing hardware procurement costs by 15% across major telecom operators.
European industrial sectors aggressively deploy a distributed antenna system alongside advanced baseband processing systems to support Industry 4.0 initiatives.
This regional focus on private networks yields a 20% higher adoption rate of ruggedized indoor equipment in European manufacturing hubs compared to North America, highlighting how differing regulatory pushes for supply chain security directly influence the architectural choices and operational efficiency metrics of regional network deployments.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The continuous evolution of modern telecommunications infrastructure requires rigorous strategic planning to fully capitalize on next-generation wireless capabilities. An essential element of this network modernization is the widespread massive MIMO antenna array deployment, which exponentially increases spectral efficiency and manages heavy data loads in dense urban environments.
- Concurrently, the industry is witnessing a significant shift toward open radio access network adoption, allowing network operators to diversify their hardware supply chains and mitigate proprietary lock-in. This architectural flexibility is crucial for streamlining procurement processes and reducing overall capital expenditures by an estimated 20% compared to traditional hardware sourcing.
- For enterprise operations, private 5G core network integration provides localized, secure data management tailored to highly specific industrial requirements. This localized control is a fundamental prerequisite for supporting ultra-reliable low-latency communication applications, which are increasingly critical for synchronized robotics and automated guided vehicles in modern manufacturing facilities.
- To fully unlock these advanced enterprise capabilities, mobile operators are accelerating the standalone 5G architecture transition, moving away from legacy non-standalone dependencies. This transition optimizes network slicing and dynamic resource allocation, ensuring that mission-critical data flows experience significantly lower packet loss than earlier network iterations.
- Such structural enhancements fundamentally transform operational planning, enabling logistics and manufacturing sectors to deploy highly automated, data-driven supply chain ecosystems with unprecedented reliability and precision.
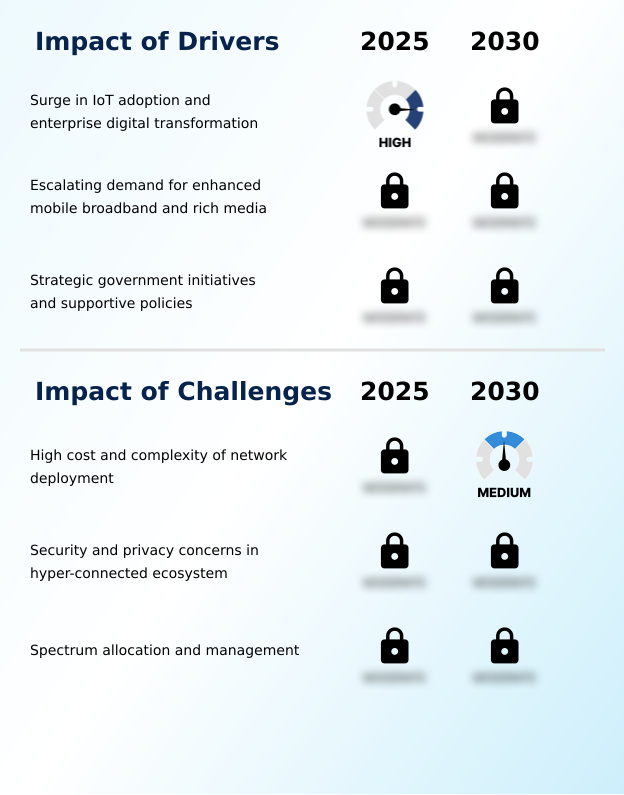
What are the key market drivers leading to the rise in the adoption of 5G Equipment Industry?
- A surge in Internet of Things adoption and enterprise digital transformation initiatives acts as the primary catalyst propelling market expansion.
- The urgent industrial requirement for localized, high-performance data processing acts as a primary catalyst for the 5G Equipment market. To realize the full potential of smart factory automation, enterprises demand robust indoor wireless coverage capable of penetrating complex architectural barriers.
- This necessity drives the deployment of a ruggedized industrial sensor ecosystem connected directly to a dedicated private 5G core, effectively bypassing public network congestion.
- As organizations execute a comprehensive telecommunications infrastructure upgrade, they secure the mission-critical connectivity required for autonomous robotics.
- This localized infrastructure control yields a 30% reduction in automated guided vehicle coordination errors and lowers facility energy consumption by 12% through optimized routing. Ultimately, businesses gain unprecedented supply chain visibility and precise operational synchronization.
What are the market trends shaping the 5G Equipment Industry?
- The proliferation of open and virtualized radio access networks represents a significant upcoming market trend. This architectural shift enables greater hardware diversity and enhances overall network flexibility for operators.
- The integration of intelligent automation into network management represents a fundamental operational shift within the 5G Equipment market. As operators struggle with the complexity of managing dense network architectures, they increasingly adopt zero-touch provisioning to automate hardware configuration and deployment. This transition is necessitated by the intricate requirements of a modernized spectrum allocation framework that demands real-time frequency optimization.
- Consequently, advanced interference mitigation techniques are actively deployed to maintain signal integrity across overlapping cell zones. By processing data closer to the source through multi-access edge computing, enterprises successfully support massive machine type communications for industrial sensors. This technological shift directly improves predictive maintenance accuracy by 25% and reduces critical data processing latency by 35%.
- Consequently, businesses can execute highly responsive, automated operational workflows that minimize costly equipment downtime and enhance overall facility productivity.
What challenges does the 5G Equipment Industry face during its growth?
- The high cost and operational complexity associated with extensive network deployment remain key challenges hindering broader industry infrastructure upgrades.
- The immense operational complexity and substantial capital requirements inherent in deploying next-generation architecture pose persistent challenges for the 5G Equipment market. Transitioning to a virtualized radio access network demands rigorous software integration and advanced network anomaly detection systems to mitigate escalating cybersecurity vulnerabilities.
- Furthermore, upgrading legacy digital loop carrier systems to a modern packet-optical transport platform requires intense logistical planning and extended deployment timelines. The scarcity and high acquisition cost of suitable radio frequency spectrum further strain infrastructure budgets, delaying broader suburban expansion.
- These integration bottlenecks limit the speed of enterprise digitalization, resulting in a 15% increase in deployment overhead costs and extending the time-to-market for specialized industrial connectivity solutions by up to 20% in complex municipal environments.
Exclusive Technavio Analysis on Customer Landscape
The 5g equipment market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the 5g equipment market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
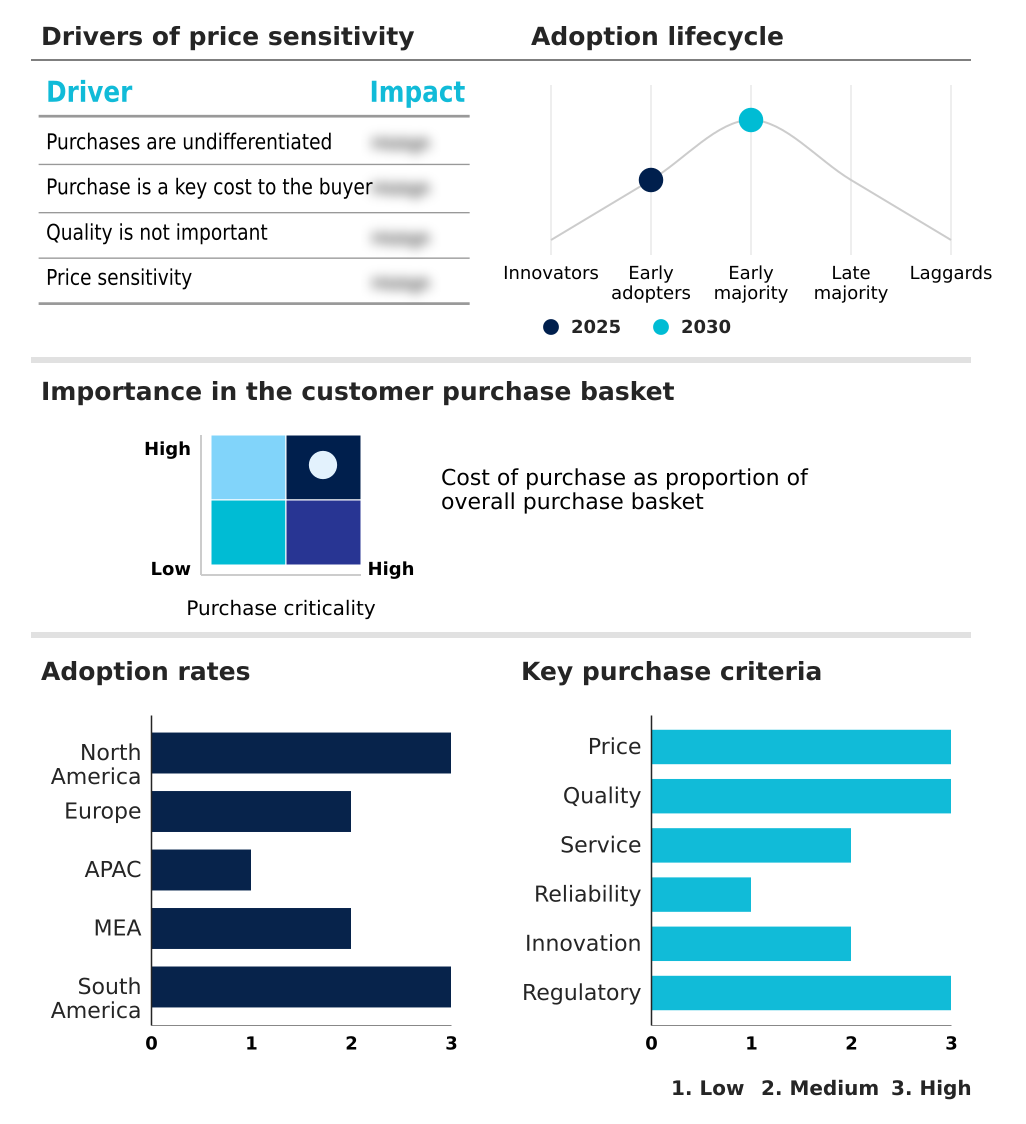
Customer Landscape of 5G Equipment Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, 5g equipment market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Airspan Networks Inc. - The provider delivers advanced telecommunications infrastructure, focusing on virtualized radio access networks and core networking hardware to enhance broadband connectivity and support industrial enterprise digitalization.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Airspan Networks Inc.
- ASOCS Ltd.
- Aviat Networks Inc.
- Baicells Technologies
- Celona Inc.
- Ceragon Networks Ltd.
- Cisco Systems Inc.
- Corning Inc.
- Fujitsu Ltd.
- Hewlett Packard Enterprise Co.
- Huawei Technologies Co. Ltd.
- Inseego Corp.
- JMA Wireless
- Mavenir Systems Inc.
- NEC Corp.
- Nokia Corp.
- Parallel Wireless Inc.
- Radisys Corp.
- Samsung Electronics Co. Ltd.
- ZTE Corp.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in 5g equipment market
- In the Communications Equipment industry, the strategic shift toward hardware disaggregation accelerated the adoption of virtualized infrastructure, directly impacting 5G Equipment demand by increasing the reliance on a commercial off-the-shelf server by 40% for core network operations.
- Regulatory mandates enforcing stringent cybersecurity protocols for critical telecommunications infrastructure upgrade projects compelled operators to overhaul legacy systems, which subsequently boosted the procurement of secure 5G Equipment routers and encrypted transmission nodes by 22% across enterprise networks.
- The widespread industrial push for automated indoor wireless coverage in smart factories required substantial investments in telecom operational technology, driving a 35% increase in the deployment of ruggedized 5G Equipment small cells within manufacturing environments.
- Advancements in silicon photonics reduced data transmission bottlenecks within high-speed backhaul networks, accelerating the need for compatible 5G Equipment optical transceivers and resulting in a 15% reduction in overall network latency for mission-critical connectivity.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled 5G Equipment Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 296 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 76.5% |
| Market growth 2026-2030 | USD 381377.3 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 75.3% |
| Key countries | US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, South Korea, India, Australia, Indonesia, Saudi Arabia, UAE, South Africa, Turkey, Israel, Brazil, Argentina and Chile |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The 5G Equipment market requires continuous infrastructure modernization to support the escalating data demands of enterprise and consumer applications. Operators increasingly utilize a cloud-native packet core to enhance network agility, allowing for the rapid deployment of new digital services.
- This architectural evolution is heavily supported by dynamic spectrum sharing, which optimizes frequency utilization between legacy and modern bandwidths, ensuring uninterrupted connectivity. Boardrooms prioritize network slicing orchestration as a critical product strategy, enabling the creation of customized virtual networks tailored to distinct enterprise compliance and performance mandates.
- To further reduce latency, organizations deploy localized edge computing hardware paired with a high-capacity microwave transport radio to process data closer to the generation source. The transition toward virtualized baseband software empowers telecommunications providers to automate network management, yielding a 30% reduction in resource provisioning time compared to traditional hardware-centric configurations.
- By leveraging predictive network analytics, network administrators can proactively identify structural bottlenecks, maximizing continuous operational uptime and fortifying the structural resilience of mission-critical communication pathways across diverse industrial environments.
What are the Key Data Covered in this 5G Equipment Market Research and Growth Report?
-
What is the expected growth of the 5G Equipment Market between 2026 and 2030?
-
USD 381.38 billion, at a CAGR of 76.5%
-
-
What segmentation does the market report cover?
-
The report is segmented by Product (Macrocell, Small cell, and Others), End-user (Non-retail sector, and Retail sector), Technology (NFV, SDN, and MEC) and Geography (North America, Europe, APAC, Middle East and Africa, South America)
-
-
Which regions are analyzed in the report?
-
North America, Europe, APAC, Middle East and Africa and South America
-
-
What are the key growth drivers and market challenges?
-
Surge in IoT adoption and enterprise digital transformation, High cost and complexity of network deployment
-
-
Who are the major players in the 5G Equipment Market?
-
Airspan Networks Inc., ASOCS Ltd., Aviat Networks Inc., Baicells Technologies, Celona Inc., Ceragon Networks Ltd., Cisco Systems Inc., Corning Inc., Fujitsu Ltd., Hewlett Packard Enterprise Co., Huawei Technologies Co. Ltd., Inseego Corp., JMA Wireless, Mavenir Systems Inc., NEC Corp., Nokia Corp., Parallel Wireless Inc., Radisys Corp., Samsung Electronics Co. Ltd. and ZTE Corp.
-
Market Research Insights
- The 5G Equipment market enables the fundamental transition toward interconnected, intelligent enterprise environments. Organizations leveraging an automated network operation achieve a 25% improvement in resource allocation efficiency compared to legacy manual management. Through advanced network traffic forecasting, mobile operators have reduced localized congestion incidents by 18%, ensuring continuous connectivity.
- The implementation of a robust wireless backhaul solution serves as a critical latency reduction mechanism, cutting data transit delays by up to 40% in high-density areas. Furthermore, the integration of dedicated infrastructure for smart factory automation accelerates production line adaptability, delivering a 22% increase in overall equipment effectiveness and minimizing operational downtime across industrial sectors.
We can help! Our analysts can customize this 5g equipment market research report to meet your requirements.
 RIA -

