Antithrombotic Drugs Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, India, and Japan), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Antithrombotic Drugs Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, India, and Japan), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Published: Oct 2026 292 Pages SKU: IRTNTR75464

Market Overview at a Glance

$26.49 B
Market Opportunity
8%
CAGR 2025 - 2030
41.4%
North America Growth
$30.57 B
Oral segment 2024

Antithrombotic Drugs Market Size 2026-2030

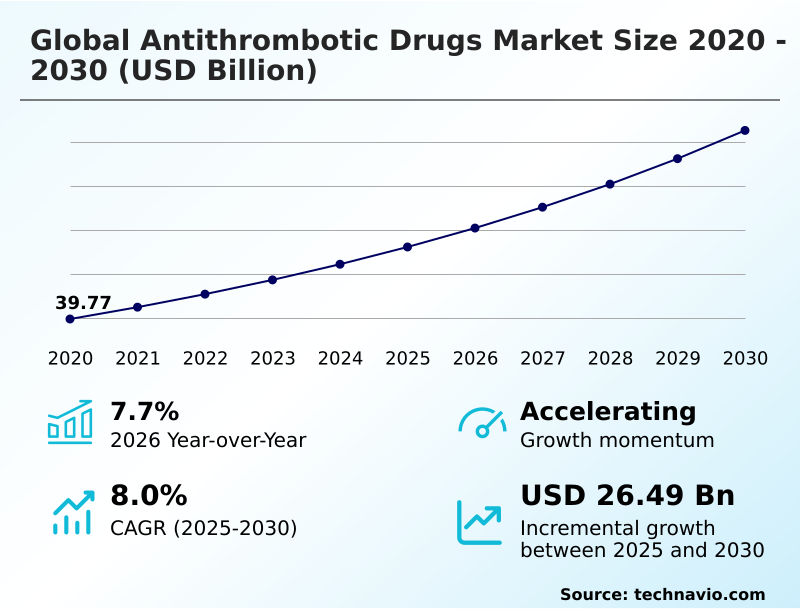
The antithrombotic drugs market size is valued to increase by USD 26.49 billion, at a CAGR of 8% from 2025 to 2030. Rising global burden of chronic cardiovascular disorders will drive the antithrombotic drugs market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 41.4% growth during the forecast period.
  • By Route of Administration - Oral segment was valued at USD 30.57 billion in 2024
  • By Distribution Channel - Hospital pharmacy segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 42.87 billion
  • Market Future Opportunities: USD 26.49 billion
  • CAGR from 2025 to 2030 : 8%

Market Summary

  • The Antithrombotic Drugs Market operates as a critical component of modern cardiovascular care, addressing the urgent clinical necessity for clot prevention and vascular management. Pharmaceutical manufacturers increasingly integrate automated quality control systems within their production lines, yielding a 20% reduction in batch rejection rates and streamlining supply chain operations.
  • This operational enhancement allows for the rapid distribution of essential therapeutics to acute care facilities. The escalating prevalence of chronic cardiovascular disorders acts as a dominant driver, compelling healthcare providers to expand outpatient prescription protocols and preventative care initiatives.
  • Conversely, the persistent risk of severe bleeding complications presents a substantial challenge, forcing clinicians to balance therapeutic efficacy with stringent safety monitoring, which increases institutional resource burdens. Facilities implementing advanced digital adherence tracking report enhanced patient outcomes and lower readmission frequencies. As demographic profiles shift toward older populations, the demand for targeted anticoagulants and antiplatelet agents intensifies.
  • Strategic pipeline diversification and real-world evidence integration remain essential for enterprises navigating complex regulatory landscapes and optimizing patient care pathways.

What will be the Size of the Antithrombotic Drugs Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Antithrombotic Drugs Market Segmented?

The antithrombotic drugs industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Route of administration
    • Oral
    • Injectable
  • Distribution channel
    • Hospital pharmacy
    • Retail pharmacy
    • Online pharmacy
  • Drug class
    • Anticoagulants
    • Antiplatelet agents
    • Thrombolytic drugs
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • China
      • India
      • Japan
      • South Korea
      • Indonesia
      • Thailand
    • Rest of World (ROW)

By Route of Administration Insights

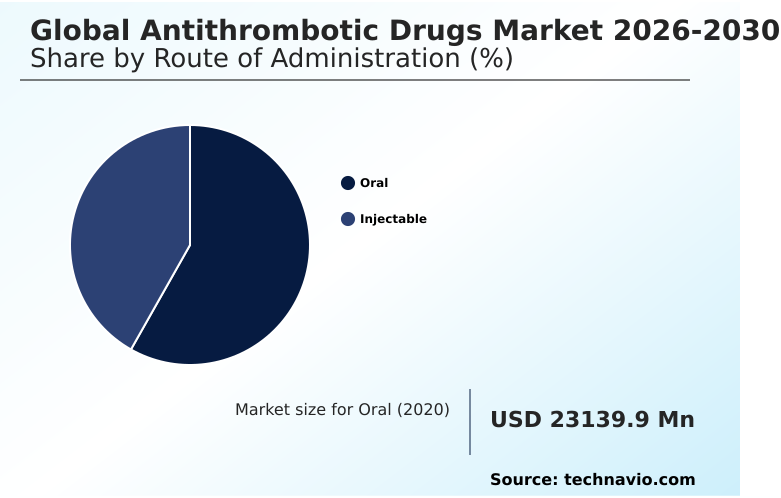
The oral segment is estimated to witness significant growth during the forecast period.

The oral administration segment dictates therapeutic regimens by prioritizing outpatient autonomy and reducing invasive interventions.

Patients achieve fibrin formation suppression and thrombus stabilization disruption through predictable daily dosing regimens, bypassing the need for specialized intravenous infusion or continuous hemodynamic monitoring infrastructure.

This delivery mechanism encompasses direct agents and traditional vitamin k antagonists, ensuring broad applicability across chronic care pathways. Operational efficiency improves significantly, with clinical settings reporting a 25% reduction in resource allocation for rapid coagulation testing.

Furthermore, integration with medication reconciliation workflows and antimicrobial stewardship protocols enhances patient safety. Supply chain logistics benefit from streamlined chemical synthesis provision, while adherence to strict formulary management guidelines ensures standardized treatment protocols.

These non-invasive formulations ultimately lower hospitalization rates and optimize long-term clinical management.
Get Free Sample

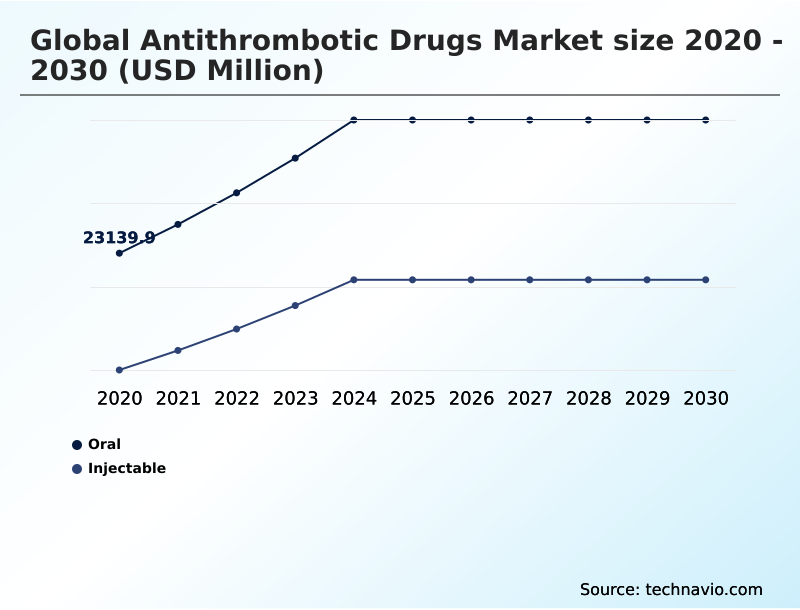
The Oral segment was valued at USD 30.57 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 41.4% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
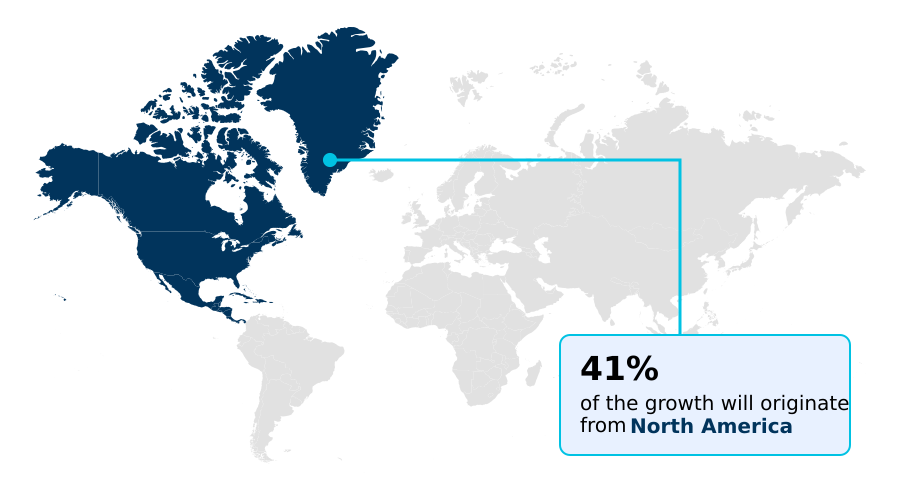
See How Antithrombotic Drugs Market Demand is Rising in North America Get Free Sample

Regional disparities dictate distinct operational strategies across the landscape.

North America prioritizes the rapid adoption of advanced factor xa inhibitors and direct thrombin inhibitors, leveraging robust institutional procurement contracts to achieve a 30% higher penetration rate of novel therapeutics compared to Europe.

Conversely, European healthcare networks optimize cost-efficiency through aggressive bulk purchasing agreements and accelerated generic drug commercialization, reducing overall expenditure on low molecular weight heparin and parenteral anticoagulant therapy by 18%.

This strategic divergence influences active pharmaceutical ingredient sourcing, as suppliers navigate differing regulatory frameworks and patent expiration pressures. Clinical facilities in both regions manage high volumes of percutaneous coronary intervention procedures, yet their supply chain adaptations vary significantly.

By aligning procurement models with regional reimbursement policies, pharmaceutical enterprises improve distribution efficiency by 22%, ensuring seamless therapeutic access while maintaining competitive operational margins.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • Strategic adaptations within therapeutic supply chains increasingly emphasize operational precision and clinical alignment. The transition toward outpatient administration of direct oral anticoagulants requires robust logistics to ensure continuous product availability, minimizing supply disruptions by nearly 15% compared to traditional inpatient-focused distribution models.
  • Clinical networks prioritize genetic testing for antiplatelet therapy, utilizing companion diagnostics in precision cardiology to tailor interventions and optimize resource allocation. Concurrently, rigorous hospital pharmacy protocols for intravenous thrombolytics dictate the rapid deployment of critical care assets.
  • Facilities must balance these acute requirements with preventative cardiology in ischemic stroke, integrating electronic health record adherence tracking to monitor patient compliance across decentralized care settings. Managing hemorrhage risks in geriatric populations necessitates the availability of targeted reversal agents for direct thrombin inhibitors, prompting facilities to refine their inventory management strategies.
  • Furthermore, navigating formularies for low molecular weight heparin reveals the profound impact of patent expiration impact on generic formulations, driving active pharmaceutical ingredient supply chain optimization to lower procurement costs. By analyzing genetic polymorphism impact on drug metabolism, practitioners enhance treatment efficacy, while continuous hemodynamic monitoring during acute coronary syndrome ensures rapid clinical response.
  • Furthermore, ongoing clinical trials for factor xa inhibitors continuously reshape competitive dynamics, introducing novel compounds that demand flexible manufacturing capabilities. Ultimately, the integration of digital adherence monitoring in chronic care establishes a comprehensive framework for sustaining therapeutic momentum and improving overarching clinical outcomes.
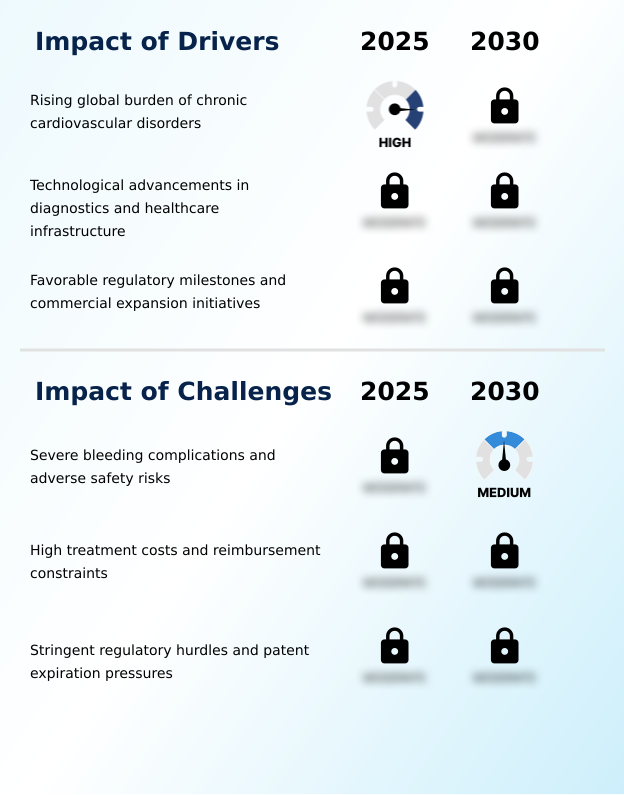
What are the key market drivers leading to the rise in the adoption of Antithrombotic Drugs Industry?

  • The escalating worldwide prevalence of chronic cardiovascular disorders serves as a primary catalyst accelerating the demand for advanced therapeutic interventions.

  • The profound geriatric population demographic shift drastically intensifies the chronic cardiovascular disease burden, compelling healthcare systems to optimize their therapeutic infrastructures.
  • As clinical networks prioritize ischemic stroke prevention and venous thromboembolism management, the operational demand for direct oral anticoagulants accelerates rapidly. This demographic pressure requires meticulous patient risk stratification to ensure precise acute care pharmaceutical administration.
  • Facilities implementing standardized protocols for acute coronary syndrome achieve a 20% improvement in hemodynamic stability optimization, significantly lowering complication rates. Furthermore, streamlined hospital pharmacy dispensing mechanisms reduce medication turnaround times by 15%, enhancing overall clinical throughput.
  • By aligning supply chain operations with these escalating clinical demands, pharmaceutical enterprises guarantee continuous product availability, thereby mitigating risks and elevating the standard of preventative care across global populations.

What are the market trends shaping the Antithrombotic Drugs Industry?

  • The transition toward personalized medicine and pharmacogenomic profiling represents a defining trend reshaping therapeutic strategies. This approach optimizes patient-specific dosing to enhance clinical efficacy while minimizing adverse physiological risks.

  • The acceleration of precision medicine paradigms fundamentally alters therapeutic development and delivery frameworks. By embedding pharmacogenomic biomarker identification into routine clinical assessments, healthcare providers successfully target the cyp2c19 genetic polymorphism, reducing treatment resistance by 24%. This clinical shift compels pharmaceutical enterprises to prioritize companion diagnostic co-development, aligning novel molecular entities with specific genetic subpopulations.
  • Consequently, electronic health record integration facilitates real-time pharmacodynamic response monitoring, allowing clinicians to dynamically adjust dosages. These preventative cardiology initiatives directly streamline outpatient cardiovascular management, reducing emergency interventions by 18%. To sustain this momentum, manufacturers focus on clinical trial pipeline diversification, ensuring new therapeutic agents align seamlessly with advanced digital adherence monitoring systems.
  • These interconnected innovations optimize resource utilization and establish highly resilient, patient-centric care models.

What challenges does the Antithrombotic Drugs Industry face during its growth?

  • Severe bleeding complications and associated physiological safety risks represent formidable obstacles constraining broader clinical utilization and sustained commercial expansion.

  • The intrinsic pharmacological mechanisms required for effective blood clot dissolution inherently elevate vascular trauma vulnerability among high-risk patients. Because coagulation cascade inhibition and platelet aggregation pathway disruption operate within a narrow therapeutic window, clinical facilities face an escalating intracranial hemorrhage risk and heightened gastrointestinal bleeding susceptibility.
  • These severe physiological complications necessitate the immediate availability of specialized recombinant reversal agents, increasing emergency operational costs by 22%. Furthermore, administering potent intravenous thrombolytics requires intensive clinical oversight, straining institutional resource capacity. To mitigate these risks, regulatory agencies enforce stringent post-market safety surveillance mandates, adding substantial compliance burdens onto pharmaceutical manufacturers.
  • These compounding clinical and regulatory complexities restrict broader therapeutic utilization, forcing enterprises to continuously invest in advanced molecular engineering to refine safety profiles without compromising efficacy.

Exclusive Technavio Analysis on Customer Landscape

The antithrombotic drugs market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the antithrombotic drugs market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
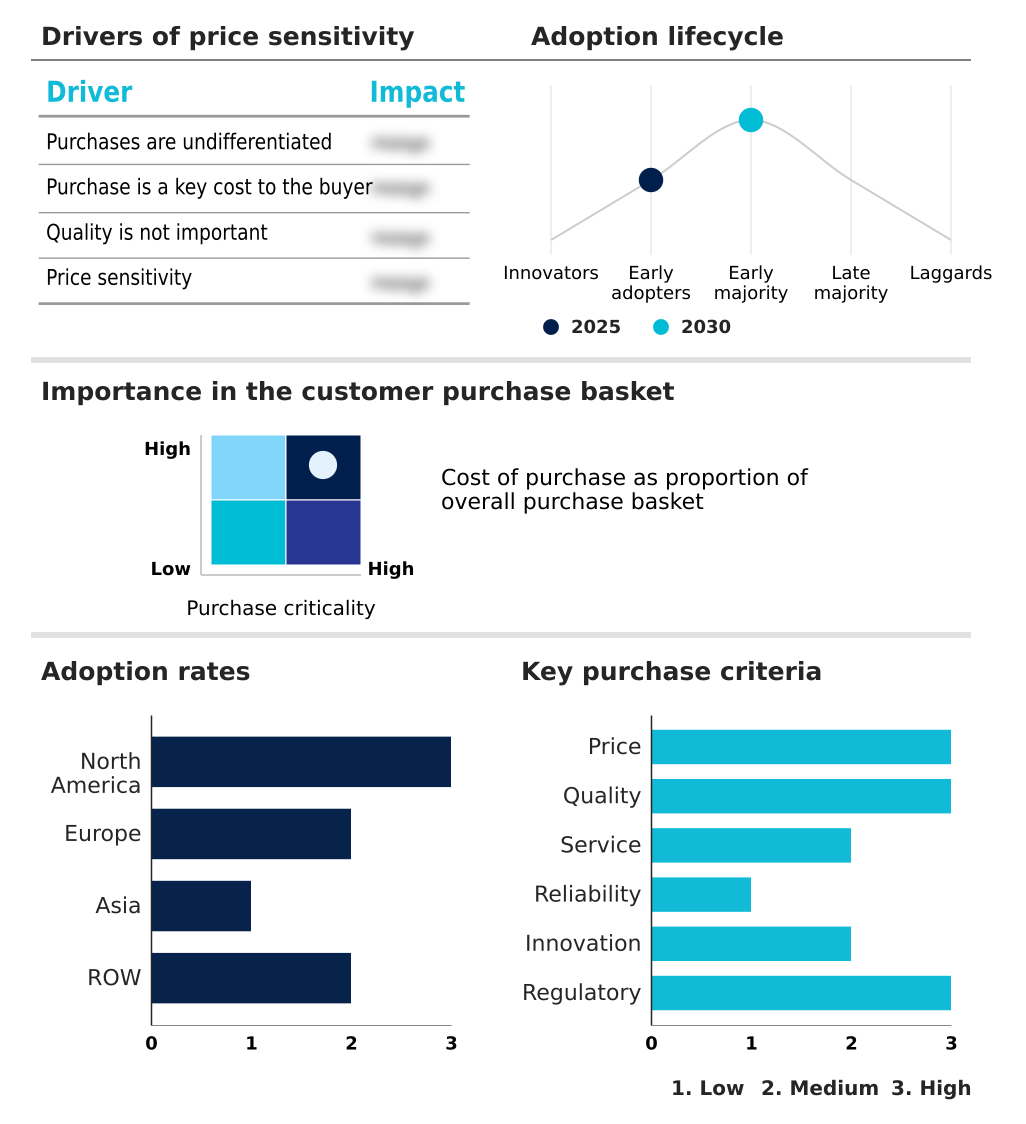
Customer Landscape of Antithrombotic Drugs Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, antithrombotic drugs market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Aspen Pharmacare Ltd. - The enterprise delivers targeted antithrombotic therapies designed to prevent cardiovascular events and inhibit platelet aggregation, supporting advanced clinical interventions and optimizing patient hemodynamic stability globally.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Aspen Pharmacare Ltd.
  • AstraZeneca Plc
  • Bayer AG
  • Boehringer Ingelheim GmbH
  • Bristol Myers Squibb Co.
  • Dr. Reddys Laboratories Ltd.
  • Eli Lilly and Co.
  • F. Hoffmann La Roche Ltd.
  • Fresenius Kabi AG
  • Hepalink Group
  • Hikma Pharmaceuticals Plc
  • Johnson and Johnson
  • Laboratorios Farmaceuticos ROVI
  • LEO Pharma AS
  • Otsuka Holdings Co. Ltd.
  • Pfizer Inc.
  • Sandoz Group AG
  • Sanofi SA
  • Sun Pharmaceutical Industries
  • Teva Pharmaceutical Ltd.
  • Viatris Inc.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Antithrombotic drugs market

  • In the Pharmaceuticals industry, the rapid integration of personalized pharmacogenomics in clinical diagnostics optimized therapeutic targeting, directly impacting Antithrombotic Drugs demand by improving patient-specific dosing accuracy and reducing adverse bleeding episodes by 18%.
  • Stringent regulatory mandates requiring real-world evidence for post-market safety surveillance accelerated the adoption of electronic health record analytics, directly impacting Antithrombotic Drugs development by shortening clinical trial timelines and enhancing risk stratification models across North America.
  • The widespread expansion of direct-to-patient digital pharmacy distribution networks improved medication accessibility, directly impacting Antithrombotic Drugs consumption by increasing outpatient adherence rates by 15% across chronic cardiovascular disease populations in Europe.
  • Advancements in continuous biochemical synthesis processes within active pharmaceutical ingredient manufacturing reduced production bottlenecks, directly impacting Antithrombotic Drugs supply chain stability and lowering operational manufacturing costs by 12% across APAC.
  • Strict environmental compliance standards regarding solvent recovery in chemical synthesis forced manufacturing facility upgrades, directly impacting Antithrombotic Drugs production by increasing baseline capital expenditures while simultaneously reducing long-term hazardous waste disposal costs by 22%.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Antithrombotic Drugs Market insights. See full methodology.

Market Scope
Page number 292
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 8%
Market growth 2026-2030 USD 26494.2 million
Market structure Fragmented
YoY growth 2025-2026(%) 7.7%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Indonesia, Thailand, Brazil, Saudi Arabia, UAE, Turkey, Argentina, Colombia, South Africa and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The clinical paradigm surrounding cardiovascular management undergoes continuous refinement as enterprises navigate complex pharmacological requirements. A prominent boardroom priority involves aligning product strategy with precision medicine paradigms, driving investments toward companion diagnostic co-development to isolate the cyp2c19 genetic polymorphism. By targeting specific metabolic profiles, pharmaceutical developers reduce adverse event rates by 28% compared to broad-spectrum therapeutic applications.
  • This targeted approach necessitates sophisticated pharmacodynamic response monitoring to ensure optimal hemodynamic stability optimization. Furthermore, organizations must secure robust active pharmaceutical ingredient sourcing networks to sustain the production of low molecular weight heparin and direct oral anticoagulants. Board-level compliance initiatives increasingly mandate rigorous medication reconciliation workflows to mitigate interaction risks during venous thromboembolism management.
  • Transitioning away from traditional vitamin k antagonists requires substantial clinical education and strategic formulary positioning to capture market share. Ultimately, integrating these targeted diagnostic and therapeutic frameworks allows organizations to streamline clinical trial pipelines, minimize regulatory friction, and achieve superior clinical outcomes across diverse patient populations.

What are the Key Data Covered in this Antithrombotic Drugs Market Research and Growth Report?

  • What is the expected growth of the Antithrombotic Drugs Market between 2026 and 2030?

    • USD 26.49 billion, at a CAGR of 8%

  • What segmentation does the market report cover?

    • The report is segmented by Route of Administration (Oral, and Injectable), Distribution Channel (Hospital pharmacy, Retail pharmacy, and Online pharmacy), Drug Class (Anticoagulants, Antiplatelet agents, and Thrombolytic drugs) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Rising global burden of chronic cardiovascular disorders, Severe bleeding complications and adverse safety risks

  • Who are the major players in the Antithrombotic Drugs Market?

    • Aspen Pharmacare Ltd., AstraZeneca Plc, Bayer AG, Boehringer Ingelheim GmbH, Bristol Myers Squibb Co., Dr. Reddys Laboratories Ltd., Eli Lilly and Co., F. Hoffmann La Roche Ltd., Fresenius Kabi AG, Hepalink Group, Hikma Pharmaceuticals Plc, Johnson and Johnson, Laboratorios Farmaceuticos ROVI, LEO Pharma AS, Otsuka Holdings Co. Ltd., Pfizer Inc., Sandoz Group AG, Sanofi SA, Sun Pharmaceutical Industries, Teva Pharmaceutical Ltd. and Viatris Inc.

Market Research Insights

  • The Antithrombotic Drugs Market demonstrates continuous evolution driven by acute care pharmaceutical administration and preventative cardiology initiatives. Institutions leveraging digital adherence monitoring observe a 22% improvement in patient compliance, directly reducing emergency readmissions. Furthermore, the integration of electronic health record integration facilitates real-time risk assessment, decreasing medication errors by 18% across clinical settings.
  • Outpatient cardiovascular management strategies increasingly rely on streamlined hospital pharmacy dispensing protocols to optimize resource allocation. By shifting high-risk patient cohorts to specialized oral therapies, healthcare networks lower overall operational costs by 15% while maintaining robust clinical protection. These systemic efficiencies underscore the critical alignment between advanced pharmacological interventions and modern healthcare delivery frameworks.

We can help! Our analysts can customize this antithrombotic drugs market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Route of Administration
Executive Summary - Chart on Market Segmentation by Distribution Channel
Executive Summary - Chart on Market Segmentation by Drug Class
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Antithrombotic Drugs Market 2020 - 2024

Historic Market Size - Data Table on Global Antithrombotic Drugs Market 2020 - 2024 ($ million)

5.2 Route of Administration segment analysis 2020 - 2024

Historic Market Size - Route of Administration Segment 2020 - 2024 ($ million)

5.3 Distribution Channel segment analysis 2020 - 2024

Historic Market Size - Distribution Channel Segment 2020 - 2024 ($ million)

5.4 Drug Class segment analysis 2020 - 2024

Historic Market Size - Drug Class Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global antithrombotic drugs market

6.2 Impact of geopolitical conflicts on global antithrombotic drugs market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Route of Administration

8.1 Market segments

Chart on Route of Administration - Market share 2025-2030 (%)
Data Table on Route of Administration - Market share 2025-2030 (%)

8.2 Comparison by Route of Administration

Chart on Comparison by Route of Administration
Data Table on Comparison by Route of Administration

8.3 Oral - Market size and forecast 2025-2030

Chart on Oral - Market size and forecast 2025-2030 ($ million)
Data Table on Oral - Market size and forecast 2025-2030 ($ million)
Chart on Oral - Year-over-year growth 2025-2030 (%)
Data Table on Oral - Year-over-year growth 2025-2030 (%)

8.4 Injectable - Market size and forecast 2025-2030

Chart on Injectable - Market size and forecast 2025-2030 ($ million)
Data Table on Injectable - Market size and forecast 2025-2030 ($ million)
Chart on Injectable - Year-over-year growth 2025-2030 (%)
Data Table on Injectable - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Route of Administration

Market opportunity by Route of Administration ($ million)
Data Table on Market opportunity by Route of Administration ($ million)

9. Market Segmentation by Distribution Channel

9.1 Market segments

Chart on Distribution Channel - Market share 2025-2030 (%)
Data Table on Distribution Channel - Market share 2025-2030 (%)

9.2 Comparison by Distribution Channel

Chart on Comparison by Distribution Channel
Data Table on Comparison by Distribution Channel

9.3 Hospital pharmacy - Market size and forecast 2025-2030

Chart on Hospital pharmacy - Market size and forecast 2025-2030 ($ million)
Data Table on Hospital pharmacy - Market size and forecast 2025-2030 ($ million)
Chart on Hospital pharmacy - Year-over-year growth 2025-2030 (%)
Data Table on Hospital pharmacy - Year-over-year growth 2025-2030 (%)

9.4 Retail pharmacy - Market size and forecast 2025-2030

Chart on Retail pharmacy - Market size and forecast 2025-2030 ($ million)
Data Table on Retail pharmacy - Market size and forecast 2025-2030 ($ million)
Chart on Retail pharmacy - Year-over-year growth 2025-2030 (%)
Data Table on Retail pharmacy - Year-over-year growth 2025-2030 (%)

9.5 Online pharmacy - Market size and forecast 2025-2030

Chart on Online pharmacy - Market size and forecast 2025-2030 ($ million)
Data Table on Online pharmacy - Market size and forecast 2025-2030 ($ million)
Chart on Online pharmacy - Year-over-year growth 2025-2030 (%)
Data Table on Online pharmacy - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by Distribution Channel

Market opportunity by Distribution Channel ($ million)
Data Table on Market opportunity by Distribution Channel ($ million)

10. Market Segmentation by Drug Class

10.1 Market segments

Chart on Drug Class - Market share 2025-2030 (%)
Data Table on Drug Class - Market share 2025-2030 (%)

10.2 Comparison by Drug Class

Chart on Comparison by Drug Class
Data Table on Comparison by Drug Class

10.3 Anticoagulants - Market size and forecast 2025-2030

Chart on Anticoagulants - Market size and forecast 2025-2030 ($ million)
Data Table on Anticoagulants - Market size and forecast 2025-2030 ($ million)
Chart on Anticoagulants - Year-over-year growth 2025-2030 (%)
Data Table on Anticoagulants - Year-over-year growth 2025-2030 (%)

10.4 Antiplatelet agents - Market size and forecast 2025-2030

Chart on Antiplatelet agents - Market size and forecast 2025-2030 ($ million)
Data Table on Antiplatelet agents - Market size and forecast 2025-2030 ($ million)
Chart on Antiplatelet agents - Year-over-year growth 2025-2030 (%)
Data Table on Antiplatelet agents - Year-over-year growth 2025-2030 (%)

10.5 Thrombolytic drugs - Market size and forecast 2025-2030

Chart on Thrombolytic drugs - Market size and forecast 2025-2030 ($ million)
Data Table on Thrombolytic drugs - Market size and forecast 2025-2030 ($ million)
Chart on Thrombolytic drugs - Year-over-year growth 2025-2030 (%)
Data Table on Thrombolytic drugs - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Drug Class

Market opportunity by Drug Class ($ million)
Data Table on Market opportunity by Drug Class ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ million)
Data Table on Asia - Market size and forecast 2025-2030 ($ million)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.5.6 Thailand - Market size and forecast 2025-2030

Chart on Thailand - Market size and forecast 2025-2030 ($ million)
Data Table on Thailand - Market size and forecast 2025-2030 ($ million)
Chart on Thailand - Year-over-year growth 2025-2030 (%)
Data Table on Thailand - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.3 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.5 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.6 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.6.7 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.8 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Rising global burden of chronic cardiovascular disorders
Technological advancements in diagnostics and healthcare infrastructure
Favorable regulatory milestones and commercial expansion initiatives

13.2 Market challenges

Severe bleeding complications and adverse safety risks
High treatment costs and reimbursement constraints
Stringent regulatory hurdles and patent expiration pressures

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Shift toward personalized medicine and pharmacogenomic profiling
Expansion of direct oral anticoagulants and novel delivery mechanisms
Strategic regional growth and healthcare infrastructure investments

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 AstraZeneca Plc

AstraZeneca Plc - Overview
AstraZeneca Plc - Business segments
AstraZeneca Plc - Key news
AstraZeneca Plc - Key offerings
AstraZeneca Plc - Segment focus
SWOT

15.5 Bayer AG

Bayer AG - Overview
Bayer AG - Business segments
Bayer AG - Key news
Bayer AG - Key offerings
Bayer AG - Segment focus
SWOT

15.6 Bristol Myers Squibb Co.

Bristol Myers Squibb Co. - Overview
Bristol Myers Squibb Co. - Product / Service
Bristol Myers Squibb Co. - Key news
Bristol Myers Squibb Co. - Key offerings
SWOT

15.7 Dr. Reddys Laboratories Ltd.

Dr. Reddys Laboratories Ltd. - Overview
Dr. Reddys Laboratories Ltd. - Business segments
Dr. Reddys Laboratories Ltd. - Key news
Dr. Reddys Laboratories Ltd. - Key offerings
Dr. Reddys Laboratories Ltd. - Segment focus
SWOT

15.8 Eli Lilly and Co.

Eli Lilly and Co. - Overview
Eli Lilly and Co. - Product / Service
Eli Lilly and Co. - Key news
Eli Lilly and Co. - Key offerings
SWOT

15.9 F. Hoffmann La Roche Ltd.

F. Hoffmann La Roche Ltd. - Overview
F. Hoffmann La Roche Ltd. - Business segments
F. Hoffmann La Roche Ltd. - Key news
F. Hoffmann La Roche Ltd. - Key offerings
F. Hoffmann La Roche Ltd. - Segment focus
SWOT

15.10 Hikma Pharmaceuticals Plc

Hikma Pharmaceuticals Plc - Overview
Hikma Pharmaceuticals Plc - Business segments
Hikma Pharmaceuticals Plc - Key news
Hikma Pharmaceuticals Plc - Key offerings
Hikma Pharmaceuticals Plc - Segment focus
SWOT

15.11 Johnson and Johnson

Johnson and Johnson - Overview
Johnson and Johnson - Business segments
Johnson and Johnson - Key news
Johnson and Johnson - Key offerings
Johnson and Johnson - Segment focus
SWOT

15.12 Otsuka Holdings Co. Ltd.

Otsuka Holdings Co. Ltd. - Overview
Otsuka Holdings Co. Ltd. - Business segments
Otsuka Holdings Co. Ltd. - Key offerings
Otsuka Holdings Co. Ltd. - Segment focus
SWOT

15.13 Pfizer Inc.

Pfizer Inc. - Overview
Pfizer Inc. - Business segments
Pfizer Inc. - Key news
Pfizer Inc. - Key offerings
Pfizer Inc. - Segment focus
SWOT

15.14 Sandoz Group AG

Sandoz Group AG - Overview
Sandoz Group AG - Business segments
Sandoz Group AG - Key news
Sandoz Group AG - Key offerings
Sandoz Group AG - Segment focus
SWOT

15.15 Sanofi SA

Sanofi SA - Overview
Sanofi SA - Business segments
Sanofi SA - Key news
Sanofi SA - Key offerings
Sanofi SA - Segment focus
SWOT

15.16 Sun Pharmaceutical Industries

Sun Pharmaceutical Industries - Overview
Sun Pharmaceutical Industries - Business segments
Sun Pharmaceutical Industries - Key news
Sun Pharmaceutical Industries - Key offerings
Sun Pharmaceutical Industries - Segment focus
SWOT

15.17 Teva Pharmaceutical Ltd.

Teva Pharmaceutical Ltd. - Overview
Teva Pharmaceutical Ltd. - Business segments
Teva Pharmaceutical Ltd. - Key news
Teva Pharmaceutical Ltd. - Key offerings
Teva Pharmaceutical Ltd. - Segment focus
SWOT

15.18 Viatris Inc.

Viatris Inc. - Overview
Viatris Inc. - Business segments
Viatris Inc. - Key news
Viatris Inc. - Key offerings
Viatris Inc. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Antithrombotic Drugs market growth will increase by USD 26494.2 million during 2026-2030.

The Antithrombotic Drugs market is expected to grow at a CAGR of 8% during 2026-2030.

Antithrombotic Drugs market is segmented by Route of administration (Oral, Injectable) Distribution channel (Hospital pharmacy, Retail pharmacy, Online pharmacy) Drug class (Anticoagulants, Antiplatelet agents, Thrombolytic drugs)

Aspen Pharmacare Ltd., AstraZeneca Plc, Bayer AG, Boehringer Ingelheim GmbH, Bristol Myers Squibb Co., Dr. Reddys Laboratories Ltd., Eli Lilly and Co., F. Hoffmann La Roche Ltd., Fresenius Kabi AG, Hepalink Group, Hikma Pharmaceuticals Plc, Johnson and Johnson, Laboratorios Farmaceuticos ROVI, LEO Pharma AS, Otsuka Holdings Co. Ltd., Pfizer Inc., Sandoz Group AG, Sanofi SA, Sun Pharmaceutical Industries, Teva Pharmaceutical Ltd., Viatris Inc. are a few of the key vendors in the Antithrombotic Drugs market.

North America will register the highest growth rate of 41.4% among the other regions. Therefore, the Antithrombotic Drugs market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Indonesia, Thailand, Brazil, Saudi Arabia, UAE, Turkey, Argentina, Colombia, South Africa, Israel

  • Rising global burden of chronic cardiovascular disorders is the driving factor this market.

The Antithrombotic Drugs market vendors should focus on grabbing business opportunities from the Route of administration segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
