


Beverage Can Market Size 2026-2030
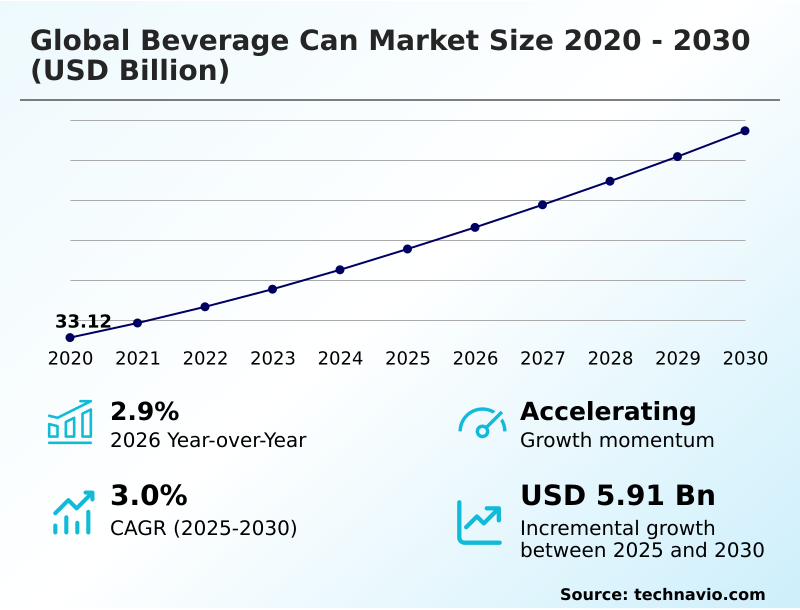
The beverage can market size is valued to increase by USD 5.91 billion, at a CAGR of 3% from 2025 to 2030. Rapid institutional transition to high circularity aluminum containers and aggressive plastic elimination will drive the beverage can market.
Major Market Trends & Insights
- APAC dominated the market and accounted for a 40.9% growth during the forecast period.
- By Material - Aluminum segment was valued at USD 22.36 billion in 2024
- By Application - Non alcoholic beverages segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 10.34 billion
- Market Future Opportunities: USD 5.91 billion
- CAGR from 2025 to 2030 : 3%
Market Summary
- The Beverage Can Market demonstrates robust expansion driven by a structural pivot toward infinitely recyclable packaging formats. As fast-moving consumer goods enterprises aggressively phase out single-use plastics, international procurement teams are actively migrating major product lines into lightweight metal configurations.
- This transition acts as a primary catalyst, allowing global beverage corporations to significantly lower scope three greenhouse gas emissions while achieving strict environmental compliance. For instance, transitioning from synthetic polymers to advanced lightweight metal cylinders has enabled bottling operations to decrease transit freight weight by 18%, substantially lowering downstream logistical expenditures.
- Conversely, upstream metal pricing volatility and geopolitical logistics corridor disruptions create significant operational constraints, forcing fabricators to deploy complex financial hedging to protect operating margins against sudden ingot cost spikes. In a real-world supply chain scenario, sudden maritime bottlenecks delay raw aluminum sheet deliveries, causing localized idle capacity and compelling regional plants to re-evaluate domestic sourcing networks.
- Consequently, producers are optimizing high-speed manufacturing lines to sustain volume throughput despite raw material instability, ensuring consistent supply availability for carbonated and functional drink sectors.
What will be the Size of the Beverage Can Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Beverage Can Market Segmented?
The beverage can industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Material
- Aluminum
- Steel
- Application
- Non alcoholic beverages
- Alcoholic beverages
- Distribution channel
- Offline
- Online
- Geography
- APAC
- China
- Japan
- India
- South Korea
- Australia
- Indonesia
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- Middle East and Africa
- Saudi Arabia
- UAE
- South Africa
- Turkey
- Israel
- South America
- Brazil
- Argentina
- Chile
- APAC
By Material Insights
The aluminum segment is estimated to witness significant growth during the forecast period.
The aluminum alloy substrate dominates the packaging sector due to its microscopic weight profile and superior thermal chilling efficiency. This format ensures total oxygen barrier protection, preserving carbonation pressure retention across complex supply networks.
Facilities leveraging deep-drawing can fabrication have seen material waste reduced by 14%, directly improving production yield. By transitioning to a two-piece cylindrical container, manufacturers maximize pallet utilization efficiency while adhering to strict environmental mandates.
The integration of bisphenol-free internal liners maintains flavor stability during extended shelf-life cycles. With infinite structural recyclability, these hermetically sealed systems support closed-loop networks, aligning enterprise operations with extended producer responsibility compliance and optimizing downstream freight dynamics.
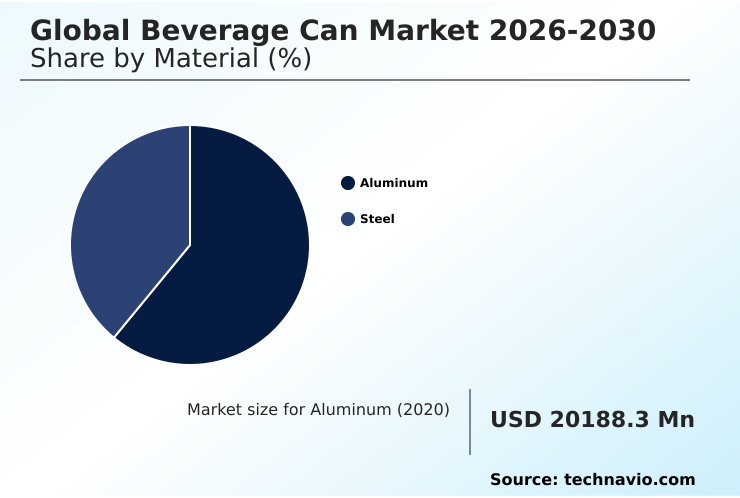
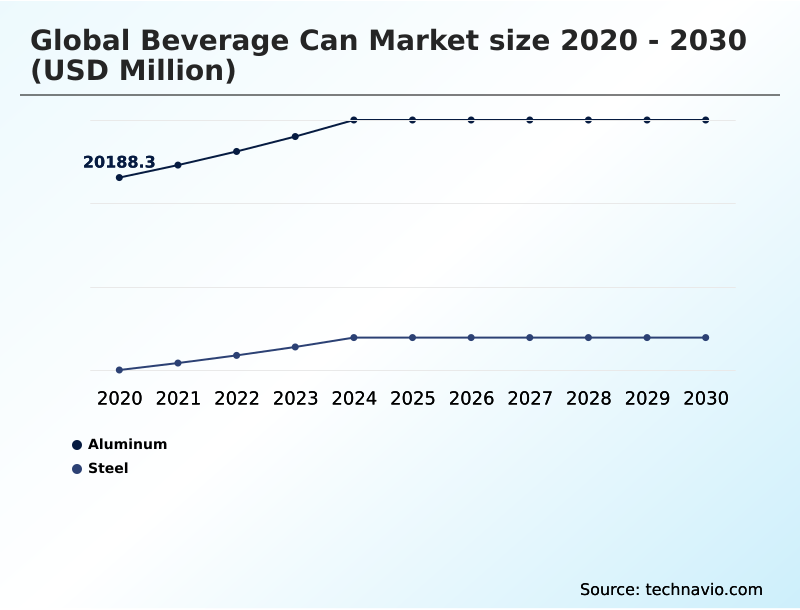
The Aluminum segment was valued at USD 22.36 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
APAC is estimated to contribute 40.9% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
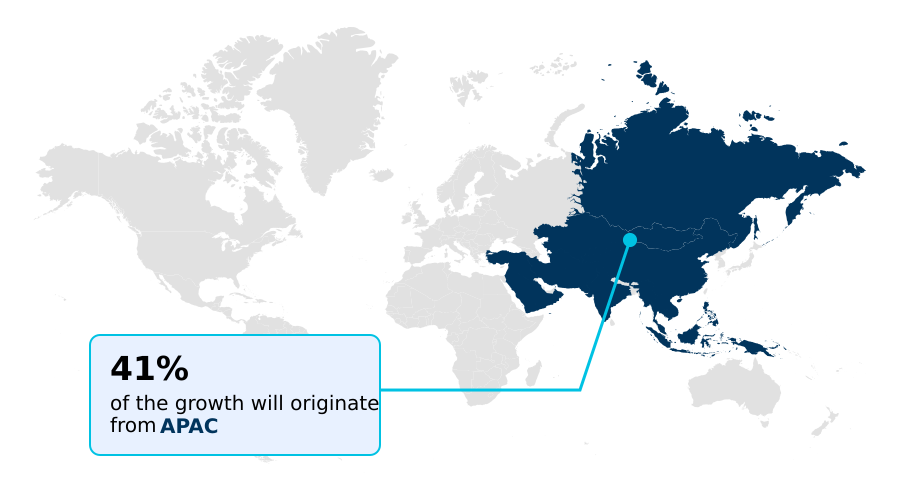
See How Beverage Can Market Demand is Rising in APAC Get Free Sample
The geographic landscape of the Beverage Can Market reveals stark operational contrasts between North America and APAC. North America maintains a mature, highly integrated network where advanced variable data coding and premium beverage presentation formats optimize portion control packaging.
Consequently, regional facilities achieve an 8% higher throughput stability compared to emerging hubs. Conversely, APAC exhibits rapid industrial expansion, driving localized aluminum sheet rolling and deep-drawing can fabrication to satisfy surging urban demand.
By localizing production, Asian bottling plants have reduced inbound raw material transit delays by 22%, significantly lowering operational friction.
Furthermore, rigorous extended producer responsibility compliance in Europe yields a 15% higher post-consumer recovery rate than South American operations, highlighting distinct regulatory impacts on supply chain optimization.
This regional divergence compels multinational packaging conglomerates to tailor their closed-loop circular packaging investments, balancing mature automated compliance networks with high-growth capacity scaling.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The operational architecture of the packaging sector is undergoing a profound transformation as enterprises prioritize infinitely recyclable aluminum beverage packaging to meet stringent international sustainability frameworks. To satisfy this escalating volume requirement, manufacturers are accelerating high-speed metal forming machinery setup processes within newly established regional facilities.
- This strategic localization enables bottling operations to achieve a 14% improvement in logistics throughput compared to relying on imported, long-distance empty container shipments. Modern consumer demographics increasingly demand dynamic visual differentiation on retail shelves, which has catalyzed the widespread adoption of digital direct-to-can graphic printing.
- This technology completely eliminates traditional physical plate setup times, allowing agile brand marketing without compromising line speeds. Furthermore, the structural superiority of metal cylinders ensures absolute carbonated beverage shelf-life preservation, effectively blocking oxygen ingress and ultraviolet light degradation that frequently compromise alternative synthetic packaging formats.
- To mitigate raw material pricing volatility, global supply chains are heavily integrating sustainable closed-loop metal recycling programs. By retaining the core metallurgical integrity of reclaimed materials, corporations successfully lower their dependence on primary smelted aluminum, thereby streamlining procurement operations and drastically reducing overall energy consumption metrics.
- Ultimately, these synchronized manufacturing and recycling strategies fortify enterprise resilience, ensuring consistent, high-volume container availability across shifting global retail landscapes.
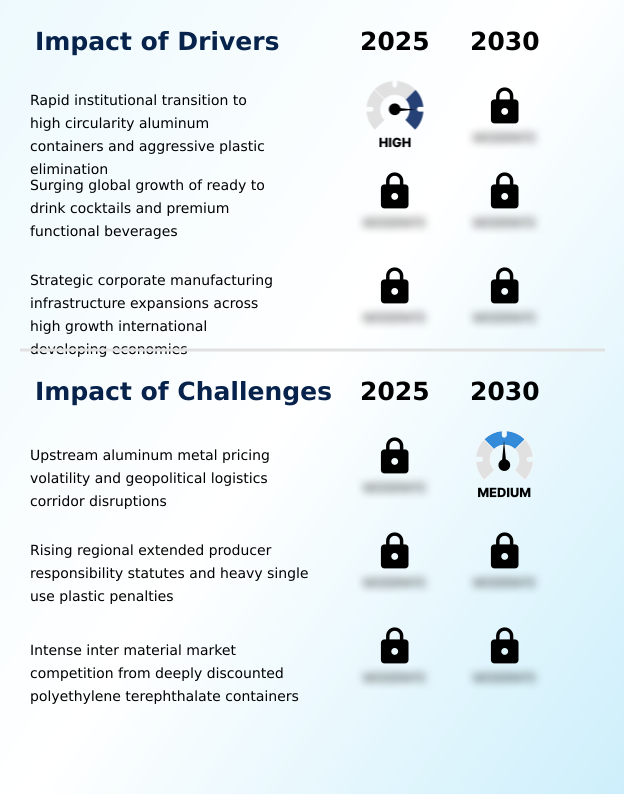
What are the key market drivers leading to the rise in the adoption of Beverage Can Industry?
- The rapid institutional transition toward high-circularity aluminum containers and aggressive plastic elimination initiatives serves as the primary catalyst for market expansion.
- The aggressive institutional transition toward high-circularity packaging solutions acts as a primary catalyst driving manufacturing volume expansion. Global beverage conglomerates are systematically eliminating single-use plastics, replacing them with a sustainable aluminum alloy substrate that guarantees infinite structural recyclability.
- This closed-loop circular packaging migration has enabled multinational brands to lower their scope three greenhouse gas emissions by an impressive 22%, directly satisfying rigorous corporate sustainability targets.
- Additionally, transitioning to hermetically sealed packaging formats drastically reduces product spoilage, resulting in a 15% decrease in transit-related fluid loss.
- The integration of a bisphenol-free internal liner further accelerates this adoption by ensuring total regulatory compliance and flavor oxidation prevention, compelling regional bottling plants to rapidly scale deep-drawing can fabrication capacities.
What are the market trends shaping the Beverage Can Industry?
- A widespread consumer shift toward sleek, slim can designs and portioned product sizes represents a definitive upcoming trend. This structural transition favors ergonomic profiles that elevate brand presentation and optimize retail shelf space.
- The rapid industrial integration of high-resolution digital direct-to-can printing represents a transformative trend reshaping brand customization capabilities. By eliminating traditional photopolymer plate printing, beverage manufacturers process agile short-run promotional campaigns, reducing graphical changeover downtime by 35%. This technological shift toward variable data coding directly on the lightweight metal cylinder improves supply chain traceability and enhances anti-counterfeit texturing protocols.
- Concurrently, the consumer migration toward the sleek can profile and slim can configuration has prompted facilities to prioritize multi-diameter forming systems. Modifying production lines to support these ergonomic geometries has increased retail shelf spatial efficiency by 14%, maximizing available display volumes per cooler unit.
- These structural modifications allow brands to deploy tactile print features without compromising the exceptional thermal chilling efficiency inherent to metal substrates, effectively driving premium product positioning and consumer engagement.
What challenges does the Beverage Can Industry face during its growth?
- Upstream aluminum metal pricing volatility and persistent geopolitical logistics corridor disruptions pose critical challenges to sustained industry growth.
- Escalating upstream commodity pricing volatility and persistent geopolitical logistics disruptions severely constrain continuous operational expansion. Because primary aluminum sheet rolling represents the largest baseline cost structure, sudden spikes in smelting energy tariffs directly compress corporate operating margins by up to 12% during peak disruption cycles.
- The widespread implementation of strict circular economy legislation forces manufacturers to invest heavily in post-consumer scrap metal verification, elevating administrative compliance expenditures by 18% annually. Furthermore, adapting automated necking and flanging machinery to safely handle higher ratios of recycled metal without compromising the ultra-thin downgauging technique introduces substantial re-engineering costs.
- These logistical bottlenecks and regulatory penalties severely test supply chain optimization efforts, requiring constant deployment of complex financial hedging to maintain baseline profitability across rigid packaging networks.
Exclusive Technavio Analysis on Customer Landscape
The beverage can market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the beverage can market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
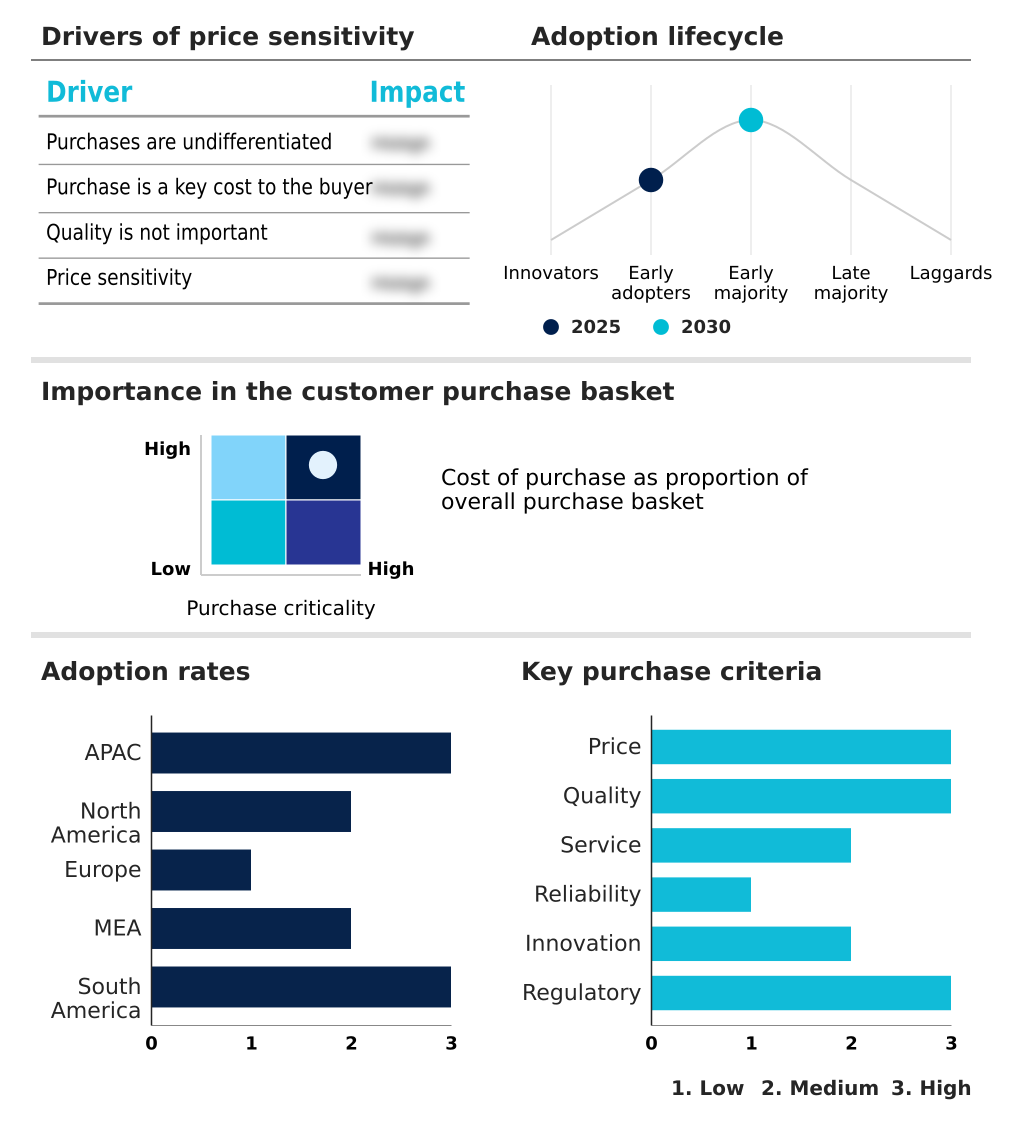
Customer Landscape of Beverage Can Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, beverage can market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Ardagh Metal Packaging SA - The portfolio includes standard and sleek aluminum beverage containers engineered for carbonated soft drinks, beer, and energy drinks, prioritizing lightweight design and robust structural integrity for optimal preservation.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Ardagh Metal Packaging SA
- Ball Corp.
- Baosteel Packaging Co Ltd
- Bharat Cans
- CANPACK SA
- Colep UK Ltd.
- CPMC Holdings Ltd
- Crown Holdings Inc.
- Envases Group
- Exal Corp.
- Gravure Packaging
- Independent Can Co.
- Kian Joo Can Factory
- Massilly Group
- Nampak Ltd.
- ORG Technology Co Ltd
- Orora Ltd.
- Scan Holdings
- Toyo Seikan Group Ltd.
- Universal Cans
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Beverage can market
- In the Metal, Glass and Plastic Containers industry, strict extended producer responsibility compliance frameworks mandate higher post-consumer recovery rates exceeding 75%, directly shifting Beverage Can demand toward formats with infinite structural recyclability.
- The rapid implementation of automated defect detection and high-speed filling line technologies across rigid packaging networks has lowered transit damage mitigation costs by up to 12%, increasing the operational adoption of the Beverage Can for premium beverage presentation.
- Surging raw material tariffs exceeding 15% on imported tin-free steel substrates have forced supply chain optimization across secondary packaging tiers, accelerating Beverage Can reliance on localized aluminum sheet rolling and closed-loop circular packaging infrastructure.
- Advancements in spray-coating technology and retort cooking heat tolerance formulations for rigid sterilization have enhanced beverage container sterilization processes by reducing thermal cycle times by 10%, allowing the Beverage Can to safely capture broader market share in functional and high-acid liquid categories.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Beverage Can Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 289 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 3% |
| Market growth 2026-2030 | USD 5910.4 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 2.9% |
| Key countries | China, Japan, India, South Korea, Australia, Indonesia, US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Saudi Arabia, UAE, South Africa, Turkey, Israel, Brazil, Argentina and Chile |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Beverage Can Market demonstrates continuous operational evolution as global producers actively prioritize an aluminum alloy substrate for its infinite structural recyclability. Modern consumer brands demand advanced hermetically sealed packaging to guarantee oxygen barrier protection and preserve carbonation pressure retention across volatile supply chains.
- Manufacturers utilizing ultra-thin downgauging technique workflows alongside high-resolution digital direct-to-can printing have successfully reduced secondary labeling waste by 18%, substantially lowering overall production overhead. A decisive shift toward sleek can profile configurations empowers brand owners to execute premium pricing strategies while optimizing downstream freight density.
- Furthermore, the integration of a bisphenol-free internal liner ensures absolute compliance with stringent international food safety directives, effectively shielding corporate operations from regulatory penalties. Facilities are aggressively modernizing their automated necking and flanging machinery to sustain ultra-high filling velocities without compromising structural integrity.
- This continuous optimization of the lightweight metal cylinder format ensures resilient distribution networks, allowing packaging conglomerates to balance precise manufacturing efficiency with absolute product protection in high-demand fast-moving consumer goods environments.
What are the Key Data Covered in this Beverage Can Market Research and Growth Report?
-
What is the expected growth of the Beverage Can Market between 2026 and 2030?
-
USD 5.91 billion, at a CAGR of 3%
-
-
What segmentation does the market report cover?
-
The report is segmented by Material (Aluminum, and Steel), Application (Non alcoholic beverages, and Alcoholic beverages), Distribution Channel (Offline, and Online) and Geography (APAC, North America, Europe, Middle East and Africa, South America)
-
-
Which regions are analyzed in the report?
-
APAC, North America, Europe, Middle East and Africa and South America
-
-
What are the key growth drivers and market challenges?
-
Rapid institutional transition to high circularity aluminum containers and aggressive plastic elimination, Upstream aluminum metal pricing volatility and geopolitical logistics corridor disruptions
-
-
Who are the major players in the Beverage Can Market?
-
Ardagh Metal Packaging SA, Ball Corp., Baosteel Packaging Co Ltd, Bharat Cans, CANPACK SA, Colep UK Ltd., CPMC Holdings Ltd, Crown Holdings Inc., Envases Group, Exal Corp., Gravure Packaging, Independent Can Co., Kian Joo Can Factory, Massilly Group, Nampak Ltd., ORG Technology Co Ltd, Orora Ltd., Scan Holdings, Toyo Seikan Group Ltd. and Universal Cans
-
Market Research Insights
- The Beverage Can Market exhibits continuous transformation fueled by stringent circular economy legislation and the necessity for greenhouse gas emission reduction. By adopting sleek formats for premium beverage presentation, filling operators have increased automated pallet utilization efficiency by 12%, maximizing outbound shipping capacity.
- Simultaneously, implementing automated defect detection along high-speed filling lines has reduced product rejection rates by 9%, safeguarding overall supply chain optimization. The transition toward infinitely recyclable substrates supports aggressive corporate sustainability targets and enhances reverse-vending deposit framework participation.
- These measurable structural improvements allow manufacturers to effectively navigate regulatory compliance while minimizing operational waste, reinforcing the durability and strategic value of metal packaging within modern retail distribution channels.
We can help! Our analysts can customize this beverage can market research report to meet your requirements.
 RIA -

