Consulting Services Segment Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (UK, Germany, and France), APAC (China, Japan, and India), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Consulting Services Segment Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (UK, Germany, and France), APAC (China, Japan, and India), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Published: Jul 2026 312 Pages SKU: IRTNTR80219

Market Overview at a Glance

$151.16 B
Market Opportunity
7.1%
CAGR 2025 - 2030
37.6%
North America Growth
$126.74 B
Management consulting segment 2024

Consulting Services Segment Market Size 2026-2030

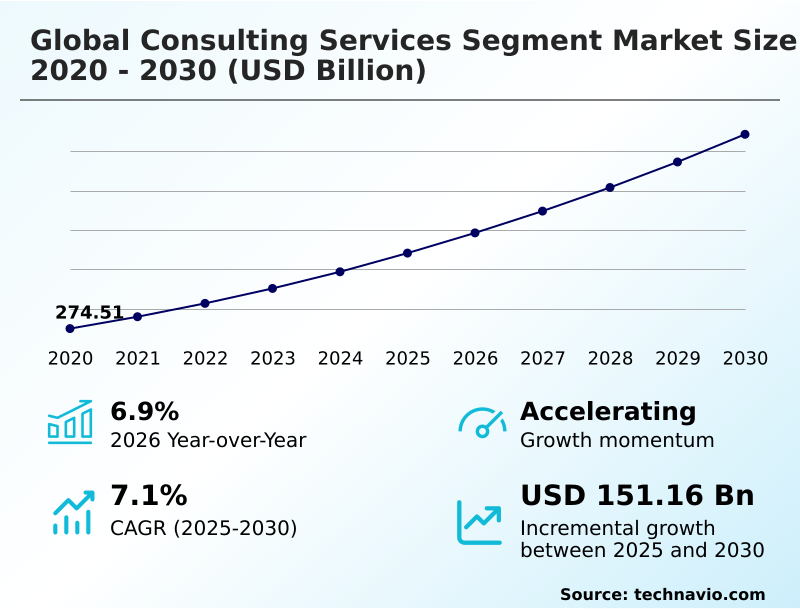
The consulting services segment market size is valued to increase by USD 151.16 billion, at a CAGR of 7.1% from 2025 to 2030. Accelerated enterprise AI integration creates unprecedented demand for specialized technology implementation consulting will drive the consulting services segment market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 37.6% growth during the forecast period.
  • By Type - Management consulting segment was valued at USD 126.74 billion in 2024
  • By Consumer - Large enterprises segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 247.27 billion
  • Market Future Opportunities: USD 151.16 billion
  • CAGR from 2025 to 2030 : 7.1%

Market Summary

  • The Consulting Services Segment is undergoing a profound structural evolution driven by the absolute necessity for enterprise digital modernization and operational resilience. Corporate leadership teams are aggressively transitioning from traditional strategic planning toward continuous, technology-driven execution models.
  • A primary driver of this market is the accelerated integration of artificial intelligence; as businesses attempt to deploy automated workflows, they require specialized external advisory to navigate complex data governance protocols. This transition directly enables logistics organizations to restructure multi-tier supplier networks, achieving a 20% reduction in supply chain disruption risks through predictive modeling.
  • Conversely, the rapid automation of labor-intensive analytical tasks presents a significant challenge by compressing traditional billable hours and undermining legacy time-based billing frameworks. To maintain profitability, advisory firms must pivot toward value-based pricing and outcome-driven engagements. The continuous implementation of stringent environmental and digital sovereignty regulations further solidifies the need for specialized external counsel.
  • Consequently, enterprises consistently rely on professional service networks to bridge the critical gap between high-level corporate strategy and complex technological execution.

What will be the Size of the Consulting Services Segment Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Consulting Services Segment Market Segmented?

The consulting services segment industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Type
    • Management consulting
    • IT consulting
    • Financial consulting
    • Marketing consulting
    • Others
  • Consumer
    • Large enterprises
    • Small and medium enterprises
  • Delivery mode
    • On-site
    • Hybrid
    • Remote or virtual
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • UK
      • Germany
      • France
      • Italy
      • Spain
      • The Netherlands
    • APAC
      • China
      • Japan
      • India
      • Australia
      • South Korea
      • Singapore
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Egypt
    • South America
      • Brazil
      • Argentina
      • Chile

By Type Insights

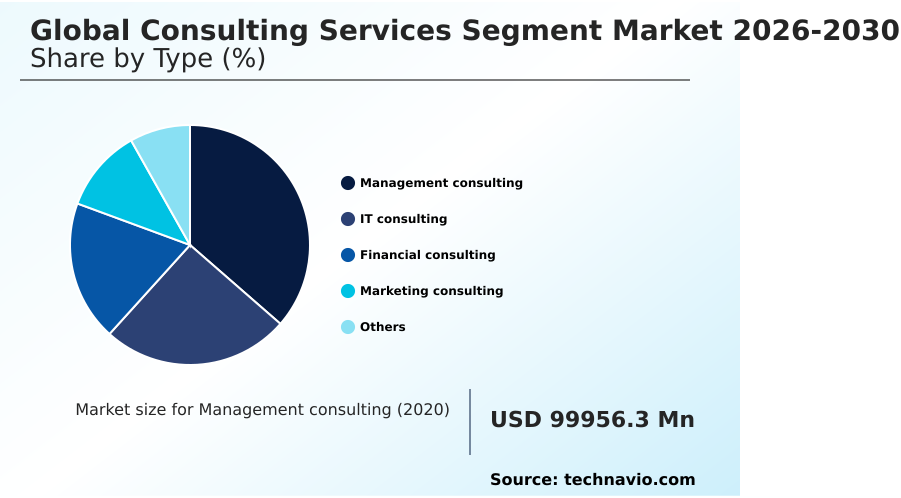
The management consulting segment is estimated to witness significant growth during the forecast period.

The management consulting sector within the Consulting Services Segment market serves as a fundamental mechanism for corporate leadership to navigate structural complexities. Organizations leverage strategy consulting to dismantle legacy data silos, directly enhancing overall execution agility.

By investing in comprehensive digital transformation, enterprises can fundamentally restructure their organizational design and align internal operations with external market demands. This alignment requires expert change management to facilitate seamless business model innovation across all departments.

Consequently, industrial firms experience a 15% metric increase in performance improvement by integrating strategic advisory into their core workflows. Furthermore, specialized consultants provide critical talent management strategies, ensuring that personnel capabilities match new technological deployments.

Through rigorous workforce optimization, businesses successfully lower overhead expenses by 12% while maintaining high productivity levels. The continuous reliance on external advisory ensures that corporate leadership can execute large-scale operational shifts with measurable precision.
Get Free Sample

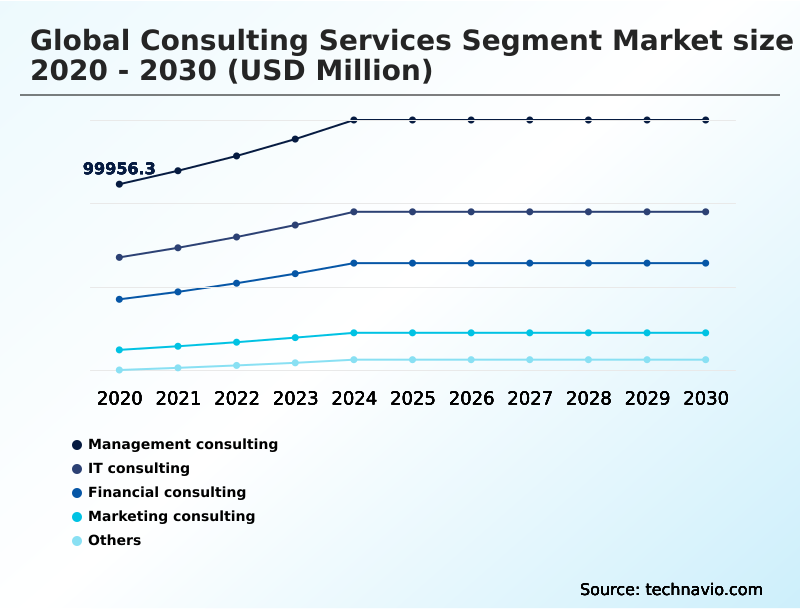
The Management consulting segment was valued at USD 126.74 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 37.6% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
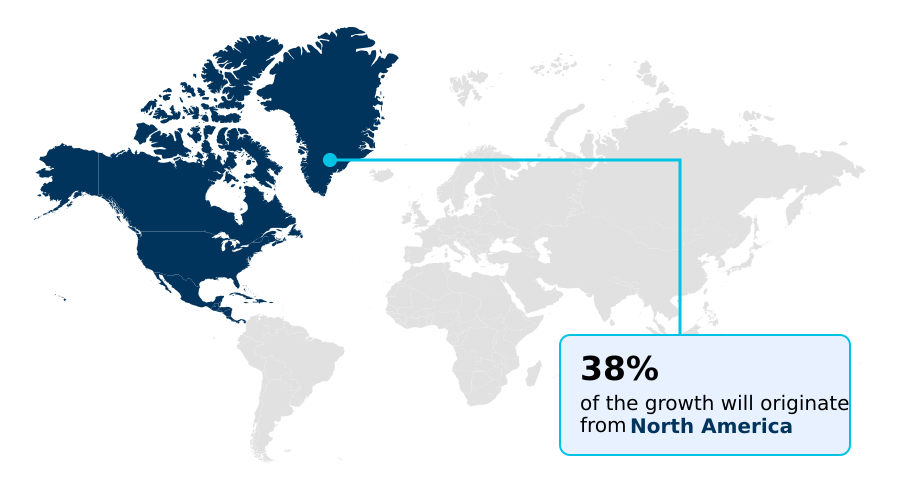
See How Consulting Services Segment Market Demand is Rising in North America Get Free Sample

The regional dynamics of the Consulting Services Segment reveal distinct variations in adoption drivers and operational priorities between North America and Europe.

North America demonstrates advanced technology integration, where high corporate digital literacy drives aggressive demand for cloud migration and the establishment of scalable cloud native infrastructure.

This environment allows regional enterprises to achieve a 25% faster deployment of smart factory lines and autonomous agentic workflows compared to their international counterparts.

Conversely, the market in Europe is heavily influenced by strict data protection mandates, forcing a transition toward localized sovereign cloud infrastructure. European organizations rely heavily on specialized advisory to build robust cybersecurity architecture and ensure strict data privacy compliance.

As a result, European firms experience a 30% higher utilization rate of carbon accounting and strategic technology planning consulting. By adapting complex data architecture to regional laws, consultants successfully lower enterprise risk exposure by 15% globally.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The continuous evolution of the Consulting Services Segment reflects a profound shift in how modern enterprises approach structural resilience and technological parity. Organizations facing relentless operational disruptions are prioritizing enterprise digital core modernization to eliminate inefficiencies and align with dynamic market demands.
  • A pivotal element of this transformation is autonomous agentic workflow integration, which enables companies to streamline routine processes and focus human capital on high-value strategic objectives. As businesses restructure their global operations to mitigate geopolitical risks, cross border supply chain restructuring has become absolutely essential for maintaining uninterrupted production cycles.
  • Industrial firms that actively overhaul their logistics networks routinely experience a 20% higher operational efficiency rate compared to competitors relying on rigid, single-source procurement models. Furthermore, heightened regulatory scrutiny surrounding environmental impact requires rigorous scope three greenhouse gas auditing to ensure compliance and maintain stakeholder trust.
  • To navigate complex regional data protection laws, multinational corporations are actively engaging advisory experts for sovereign artificial intelligence framework planning. This localized approach ensures that sensitive corporate data remains securely within designated jurisdictions while still leveraging advanced predictive capabilities. The convergence of these specialized advisory requirements underscores the indispensable nature of external consulting.
  • By orchestrating complex technological deployments and safeguarding global compliance, professional service firms provide the critical architectural blueprints necessary for sustaining long-term commercial viability and navigating shifting international business environments.
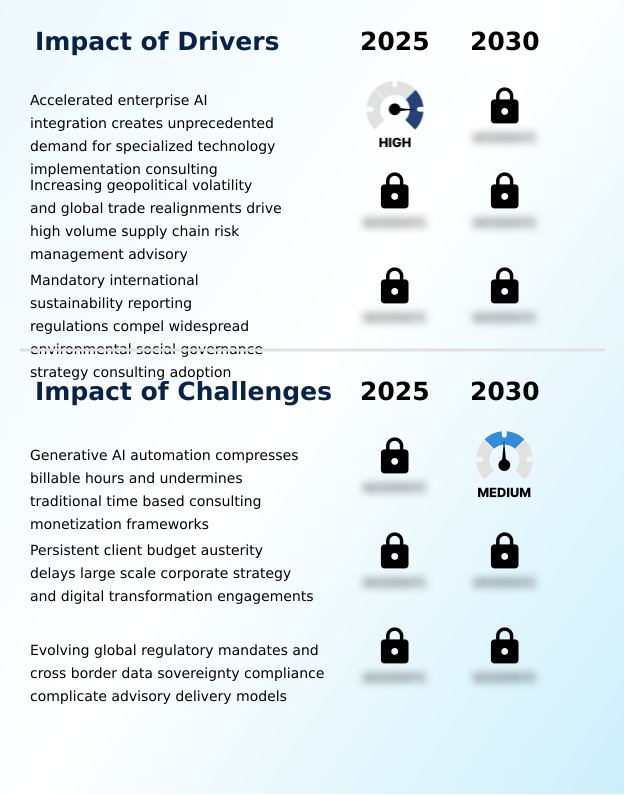
What are the key market drivers leading to the rise in the adoption of Consulting Services Segment Industry?

  • Accelerated enterprise artificial intelligence integration creates an unprecedented demand for specialized technology implementation consulting services.

  • The surging necessity for robust risk management advisory serves as a primary driver within the Consulting Services Segment, fundamentally altering corporate procurement strategies. Geopolitical volatility compels multinational corporations to execute comprehensive supply chain resilience initiatives.
  • By engaging external strategy experts to conduct digital twin simulation of their logistics networks, enterprises successfully reduce disruption costs by 25%. Companies actively reevaluate their manufacturing footprint to ensure complete supply chain transparency across diverse global markets.
  • Furthermore, shifting trade policies and complex cross border tax regulations force organizations to seek expert guidance on foreign direct investment protocols.
  • Firms that conduct rigorous external due diligence before launching infrastructure megaprojects manage to lower their capital expenditure overruns by 14%.
  • This intense operational pressure forces executive boards to continuously invest in advisory services, ensuring they possess the agile enterprise frameworks required to navigate global market fluctuations.

What are the market trends shaping the Consulting Services Segment Industry?

  • The accelerated enterprise transition toward outcome-based consulting contracts is systematically replacing traditional time-based billing models across the industry.

  • The Consulting Services Segment is experiencing a definitive trend wherein organizations aggressively shift toward value based pricing engagements to guarantee measurable investment returns. This transition drives advisory firms to expand their intellectual property access and deliver tangible software-driven outcomes.
  • Enterprises focus heavily on embedding circular economy principles into their operations, prompting consultants to develop advanced frameworks for sustainability reporting and tracking scope three emissions. Consequently, businesses reduce environmental compliance reporting times by 28% and improve supply chain sustainability metrics by 15%.
  • The growing emphasis on generative artificial intelligence and the deployment of a cognitive network platform enables brands to deliver an optimized omnichannel customer experience. By implementing robust predictive analytics, companies improve forecast accuracy by over 18%, driving sustained revenue expansion. This fundamental shift ensures that advisory interventions are directly tied to high-value technological innovation and verifiable business growth.

What challenges does the Consulting Services Segment Industry face during its growth?

  • Generative artificial intelligence automation compresses billable hours, fundamentally undermining traditional time-based consulting monetization frameworks and challenging industry growth.

  • The Consulting Services Segment faces a severe structural challenge as rapid machine learning integration compresses the billable hours traditionally associated with labor-intensive analytical tasks. Automated diagnostic tools and algorithmic decision engines now perform complex data syntheses in a fraction of the time, forcing advisory firms to overhaul legacy monetization frameworks.
  • Maintaining strict data lineage tracking for these automated outputs increases overhead costs by 15%, placing immense downward pressure on standard engagement margins. Additionally, continuously evolving tax compliance and strict regulatory compliance mandates complicate cross-border project delivery. Persistent macroeconomic volatility frequently delays large-scale mergers and acquisitions, lengthening sales conversion cycles by an average of 25%.
  • To survive this revenue compression, consultants must aggressively pivot from basic enterprise resource planning implementations toward comprehensive legacy system modernization, ensuring they deliver genuine operational efficiency to highly cost-conscious corporate clients.

Exclusive Technavio Analysis on Customer Landscape

The consulting services segment market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the consulting services segment market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
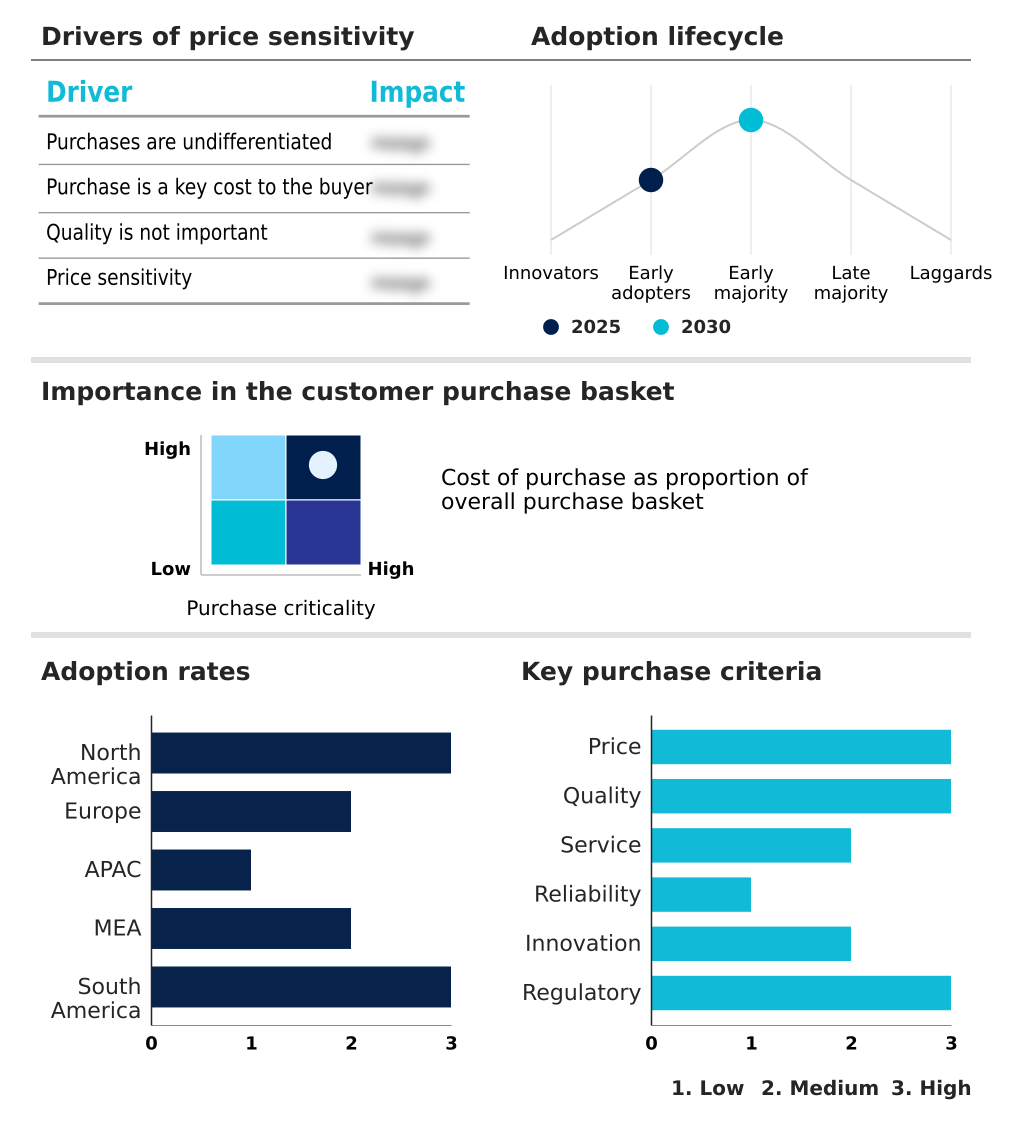
Customer Landscape of Consulting Services Segment Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, consulting services segment market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Accenture Plc - The provider delivers comprehensive management advisory, strategic technology implementation, digital systems integration, and operational performance improvement services to optimize enterprise efficiency and accelerate organizational change.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Accenture Plc
  • AlixPartners LLP
  • Alvarez and Marsal Holdings
  • Arthur D Little Ltd
  • Bain and Co. Inc.
  • Booz Allen Hamilton Corp.
  • Boston Consulting Group Inc.
  • CGI Inc.
  • Deloitte Touche Tohmatsu Ltd.
  • FTI Consulting Inc.
  • IBM Corp.
  • Kearney Inc
  • KPMG International Ltd.
  • L.E.K. Consulting LLC
  • McKinsey and Co.
  • Mercer LLC
  • Oliver Wyman LLC
  • PricewaterhouseCoopers LLP
  • Protiviti Inc.
  • Roland Berger GmbH

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Consulting services segment market

  • In the Research and Consulting Services industry, the mandatory implementation of environmental sustainability mandates across the European Union forced multinational enterprises to construct rigorous carbon accounting frameworks, directly increasing Consulting Services Segment demand for compliance and reporting expertise by over 40%.
  • The rapid transition toward cloud native infrastructure and sovereign data architectures compelled highly regulated financial institutions to redesign their data privacy protocols, driving massive adoption of specialized technology planning and advisory contracts.
  • Accelerated deployment of generative AI and algorithmic decision engines within enterprise workflows exposed significant workforce capability gaps, prompting corporate boards to dramatically expand procurement of strategic organizational design and talent management services.
  • Escalating geopolitical volatility and shifting foreign direct investment policies disrupted legacy logistics networks, resulting in a 25% surge in supply chain transparency assessments and cross border tax restructuring initiatives across the global advisory market.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Consulting Services Segment Market insights. See full methodology.

Market Scope
Page number 312
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 7.1%
Market growth 2026-2030 USD 151162.5 million
Market structure Fragmented
YoY growth 2025-2026(%) 6.9%
Key countries US, Canada, Mexico, UK, Germany, France, Italy, Spain, The Netherlands, China, Japan, India, Australia, South Korea, Singapore, Saudi Arabia, UAE, South Africa, Israel, Egypt, Brazil, Argentina and Chile
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Consulting Services Segment operates as a critical catalyst for corporate restructuring, driven by the absolute necessity to integrate advanced digital technologies into core business functions. The accelerated transition toward sovereign cloud deployment forces executive boards to completely reevaluate their technology planning and data architecture investments to ensure strict localized compliance.
  • This strategic boardroom mandate directly mitigates legal exposure while simultaneously unlocking new avenues for operational efficiency. Industrial enterprises leveraging these specialized advisory services report a 35% reduction in digital infrastructure vulnerabilities, validating the direct commercial impact of expert external guidance.
  • Furthermore, the pervasive shift toward automated systems compels organizations to adopt robust data tracking to maintain transparent and ethical decision engines. As enterprise resource planning systems become increasingly complex, the demand for sophisticated change management initiatives expands significantly. Organizations simply cannot execute these multifaceted structural realignments without specialized advisory frameworks.
  • Consequently, the reliance on external strategy and technology expertise remains an enduring structural pillar for multinational corporations navigating volatile trade environments and relentless technological disruption.

What are the Key Data Covered in this Consulting Services Segment Market Research and Growth Report?

  • What is the expected growth of the Consulting Services Segment Market between 2026 and 2030?

    • USD 151.16 billion, at a CAGR of 7.1%

  • What segmentation does the market report cover?

    • The report is segmented by Type (Management consulting, IT consulting, Financial consulting, Marketing consulting, and Others), Consumer (Large enterprises, and Small and medium enterprises), Delivery Mode (On-site, Hybrid, and Remote or virtual) and Geography (North America, Europe, APAC, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • North America, Europe, APAC, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Accelerated enterprise AI integration creates unprecedented demand for specialized technology implementation consulting, Generative AI automation compresses billable hours and undermines traditional time based consulting monetization frameworks

  • Who are the major players in the Consulting Services Segment Market?

    • Accenture Plc, AlixPartners LLP, Alvarez and Marsal Holdings, Arthur D Little Ltd, Bain and Co. Inc., Booz Allen Hamilton Corp., Boston Consulting Group Inc., CGI Inc., Deloitte Touche Tohmatsu Ltd., FTI Consulting Inc., IBM Corp., Kearney Inc, KPMG International Ltd., L.E.K. Consulting LLC, McKinsey and Co., Mercer LLC, Oliver Wyman LLC, PricewaterhouseCoopers LLP, Protiviti Inc. and Roland Berger GmbH

Market Research Insights

  • The Consulting Services Segment is rapidly shifting toward performance-driven pricing models as enterprises demand measurable returns on their advisory investments. Organizations implementing agile frameworks utilize specialized external guidance to optimize their manufacturing capabilities and streamline operations. This strategic alignment enables industrial manufacturers to increase operational performance metrics by 18% while simultaneously reducing procurement bottlenecks by 22%.
  • Furthermore, the rising complexity of international tax regulations forces multinational corporations to fundamentally alter their legacy structures. By adopting comprehensive transparency tools and leveraging external due diligence expertise, businesses successfully lower compliance violation risks by over 30%. This dynamic environment guarantees that professional advisory services remain critical for sustaining long-term organizational agility and robust technological execution.

We can help! Our analysts can customize this consulting services segment market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Consumer
Executive Summary - Chart on Market Segmentation by Delivery Mode
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Consulting Services Segment Market 2020 - 2024

Historic Market Size - Data Table on Global Consulting Services Segment Market 2020 - 2024 ($ million)

5.2 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.3 Consumer segment analysis 2020 - 2024

Historic Market Size - Consumer Segment 2020 - 2024 ($ million)

5.4 Delivery Mode segment analysis 2020 - 2024

Historic Market Size - Delivery Mode Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global consulting services segment market

6.2 Impact of geopolitical conflicts on global consulting services segment market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Type

8.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

8.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

8.3 Management consulting - Market size and forecast 2025-2030

Chart on Management consulting - Market size and forecast 2025-2030 ($ million)
Data Table on Management consulting - Market size and forecast 2025-2030 ($ million)
Chart on Management consulting - Year-over-year growth 2025-2030 (%)
Data Table on Management consulting - Year-over-year growth 2025-2030 (%)

8.4 IT consulting - Market size and forecast 2025-2030

Chart on IT consulting - Market size and forecast 2025-2030 ($ million)
Data Table on IT consulting - Market size and forecast 2025-2030 ($ million)
Chart on IT consulting - Year-over-year growth 2025-2030 (%)
Data Table on IT consulting - Year-over-year growth 2025-2030 (%)

8.5 Financial consulting - Market size and forecast 2025-2030

Chart on Financial consulting - Market size and forecast 2025-2030 ($ million)
Data Table on Financial consulting - Market size and forecast 2025-2030 ($ million)
Chart on Financial consulting - Year-over-year growth 2025-2030 (%)
Data Table on Financial consulting - Year-over-year growth 2025-2030 (%)

8.6 Marketing consulting - Market size and forecast 2025-2030

Chart on Marketing consulting - Market size and forecast 2025-2030 ($ million)
Data Table on Marketing consulting - Market size and forecast 2025-2030 ($ million)
Chart on Marketing consulting - Year-over-year growth 2025-2030 (%)
Data Table on Marketing consulting - Year-over-year growth 2025-2030 (%)

8.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.8 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

9. Market Segmentation by Consumer

9.1 Market segments

Chart on Consumer - Market share 2025-2030 (%)
Data Table on Consumer - Market share 2025-2030 (%)

9.2 Comparison by Consumer

Chart on Comparison by Consumer
Data Table on Comparison by Consumer

9.3 Large enterprises - Market size and forecast 2025-2030

Chart on Large enterprises - Market size and forecast 2025-2030 ($ million)
Data Table on Large enterprises - Market size and forecast 2025-2030 ($ million)
Chart on Large enterprises - Year-over-year growth 2025-2030 (%)
Data Table on Large enterprises - Year-over-year growth 2025-2030 (%)

9.4 Small and medium enterprises - Market size and forecast 2025-2030

Chart on Small and medium enterprises - Market size and forecast 2025-2030 ($ million)
Data Table on Small and medium enterprises - Market size and forecast 2025-2030 ($ million)
Chart on Small and medium enterprises - Year-over-year growth 2025-2030 (%)
Data Table on Small and medium enterprises - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Consumer

Market opportunity by Consumer ($ million)
Data Table on Market opportunity by Consumer ($ million)

10. Market Segmentation by Delivery Mode

10.1 Market segments

Chart on Delivery Mode - Market share 2025-2030 (%)
Data Table on Delivery Mode - Market share 2025-2030 (%)

10.2 Comparison by Delivery Mode

Chart on Comparison by Delivery Mode
Data Table on Comparison by Delivery Mode

10.3 On-site - Market size and forecast 2025-2030

Chart on On-site - Market size and forecast 2025-2030 ($ million)
Data Table on On-site - Market size and forecast 2025-2030 ($ million)
Chart on On-site - Year-over-year growth 2025-2030 (%)
Data Table on On-site - Year-over-year growth 2025-2030 (%)

10.4 Hybrid - Market size and forecast 2025-2030

Chart on Hybrid - Market size and forecast 2025-2030 ($ million)
Data Table on Hybrid - Market size and forecast 2025-2030 ($ million)
Chart on Hybrid - Year-over-year growth 2025-2030 (%)
Data Table on Hybrid - Year-over-year growth 2025-2030 (%)

10.5 Remote or virtual - Market size and forecast 2025-2030

Chart on Remote or virtual - Market size and forecast 2025-2030 ($ million)
Data Table on Remote or virtual - Market size and forecast 2025-2030 ($ million)
Chart on Remote or virtual - Year-over-year growth 2025-2030 (%)
Data Table on Remote or virtual - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Delivery Mode

Market opportunity by Delivery Mode ($ million)
Data Table on Market opportunity by Delivery Mode ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.2 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.5.5 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.6 Singapore - Market size and forecast 2025-2030

Chart on Singapore - Market size and forecast 2025-2030 ($ million)
Data Table on Singapore - Market size and forecast 2025-2030 ($ million)
Chart on Singapore - Year-over-year growth 2025-2030 (%)
Data Table on Singapore - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.6.5 Egypt - Market size and forecast 2025-2030

Chart on Egypt - Market size and forecast 2025-2030 ($ million)
Data Table on Egypt - Market size and forecast 2025-2030 ($ million)
Chart on Egypt - Year-over-year growth 2025-2030 (%)
Data Table on Egypt - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Accelerated enterprise AI integration creates unprecedented demand for specialized technology implementation consulting
Increasing geopolitical volatility and global trade realignments drive high volume supply chain risk management advisory
Mandatory international sustainability reporting regulations compel widespread environmental social governance strategy consulting adoption

13.2 Market challenges

Generative AI automation compresses billable hours and undermines traditional time based consulting monetization frameworks
Persistent client budget austerity delays large scale corporate strategy and digital transformation engagements
Evolving global regulatory mandates and cross border data sovereignty compliance complicate advisory delivery models

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Accelerated enterprise transition toward outcome based consulting contracts replaces traditional time based billing models
Strategic corporate acquisitions targeting niche technology providers build end to end digital delivery capabilities
Surging enterprise demand for sovereign AI frameworks shapes localized technology advisory solutions

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Accenture Plc

Accenture Plc - Overview
Accenture Plc - Business segments
Accenture Plc - Key news
Accenture Plc - Key offerings
Accenture Plc - Segment focus
SWOT

15.5 AlixPartners LLP

AlixPartners LLP - Overview
AlixPartners LLP - Product / Service
AlixPartners LLP - Key offerings
SWOT

15.6 Bain and Co. Inc.

Bain and Co. Inc. - Overview
Bain and Co. Inc. - Product / Service
Bain and Co. Inc. - Key offerings
SWOT

15.7 Booz Allen Hamilton Corp.

Booz Allen Hamilton Corp. - Overview
Booz Allen Hamilton Corp. - Product / Service
Booz Allen Hamilton Corp. - Key news
Booz Allen Hamilton Corp. - Key offerings
SWOT

15.8 Boston Consulting Group Inc.

Boston Consulting Group Inc. - Overview
Boston Consulting Group Inc. - Product / Service
Boston Consulting Group Inc. - Key offerings
SWOT

15.9 CGI Inc.

CGI Inc. - Overview
CGI Inc. - Business segments
CGI Inc. - Key news
CGI Inc. - Key offerings
CGI Inc. - Segment focus
SWOT

15.10 Deloitte Touche Tohmatsu Ltd.

Deloitte Touche Tohmatsu Ltd. - Overview
Deloitte Touche Tohmatsu Ltd. - Business segments
Deloitte Touche Tohmatsu Ltd. - Key offerings
Deloitte Touche Tohmatsu Ltd. - Segment focus
SWOT

15.11 FTI Consulting Inc.

FTI Consulting Inc. - Overview
FTI Consulting Inc. - Business segments
FTI Consulting Inc. - Key offerings
FTI Consulting Inc. - Segment focus
SWOT

15.12 IBM Corp.

IBM Corp. - Overview
IBM Corp. - Business segments
IBM Corp. - Key news
IBM Corp. - Key offerings
IBM Corp. - Segment focus
SWOT

15.13 Kearney Inc

Kearney Inc - Overview
Kearney Inc - Product / Service
Kearney Inc - Key offerings
SWOT

15.14 KPMG International Ltd.

KPMG International Ltd. - Overview
KPMG International Ltd. - Product / Service
KPMG International Ltd. - Key offerings
SWOT

15.15 McKinsey and Co.

McKinsey and Co. - Overview
McKinsey and Co. - Product / Service
McKinsey and Co. - Key offerings
SWOT

15.16 Mercer LLC

Mercer LLC - Overview
Mercer LLC - Product / Service
Mercer LLC - Key offerings
SWOT

15.17 PricewaterhouseCoopers LLP

PricewaterhouseCoopers LLP - Overview
PricewaterhouseCoopers LLP - Product / Service
PricewaterhouseCoopers LLP - Key offerings
SWOT

15.18 Roland Berger GmbH

Roland Berger GmbH - Overview
Roland Berger GmbH - Product / Service
Roland Berger GmbH - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Consulting Services Segment market growth will increase by USD 151162.5 million during 2026-2030.

The Consulting Services Segment market is expected to grow at a CAGR of 7.1% during 2026-2030.

Consulting Services Segment market is segmented by Type (Management consulting, IT consulting, Financial consulting, Marketing consulting, Others) Consumer (Large enterprises, Small and medium enterprises) Delivery mode (On-site, Hybrid, Remote or virtual)

Accenture Plc, AlixPartners LLP, Alvarez and Marsal Holdings, Arthur D Little Ltd, Bain and Co. Inc., Booz Allen Hamilton Corp., Boston Consulting Group Inc., CGI Inc., Deloitte Touche Tohmatsu Ltd., FTI Consulting Inc., IBM Corp., Kearney Inc, KPMG International Ltd., L.E.K. Consulting LLC, McKinsey and Co., Mercer LLC, Oliver Wyman LLC, PricewaterhouseCoopers LLP, Protiviti Inc., Roland Berger GmbH are a few of the key vendors in the Consulting Services Segment market.

North America will register the highest growth rate of 37.6% among the other regions. Therefore, the Consulting Services Segment market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, UK, Germany, France, Italy, Spain, The Netherlands, China, Japan, India, Australia, South Korea, Singapore, Saudi Arabia, UAE, South Africa, Israel, Egypt, Brazil, Argentina, Chile

  • Accelerated enterprise AI integration creates unprecedented demand for specialized technology implementation consulting is the driving factor this market.

The Consulting Services Segment market vendors should focus on grabbing business opportunities from the Type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
