


Cyber Security Market Size 2026-2030
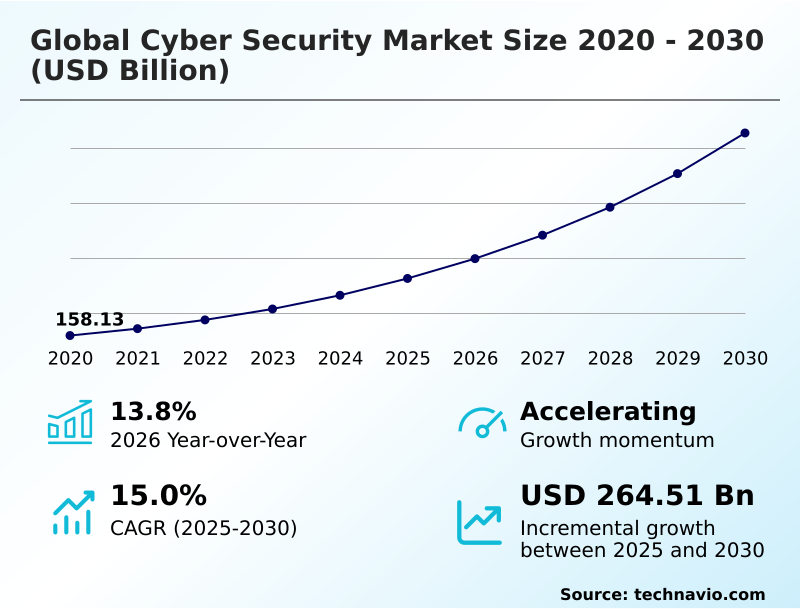
The cyber security market size is valued to increase by USD 264.51 billion, at a CAGR of 15% from 2025 to 2030. Exponential proliferation of sophisticated ransomware and automated cyber threats will drive the cyber security market.
Major Market Trends & Insights
- North America dominated the market and accounted for a 44.9% growth during the forecast period.
- By End-user - Government segment was valued at USD 64.86 billion in 2024
- By Deployment - On-premises segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 368.29 billion
- Market Future Opportunities: USD 264.51 billion
- CAGR from 2025 to 2030 : 15%
Market Summary
- The Cyber Security Market is undergoing a rapid architectural evolution as enterprises transition from perimeter-based defenses to proactive, intelligence-driven protection frameworks. Within modern supply chain optimization, multinational logistics firms are deploying advanced threat intelligence software to secure interconnected supplier portals, successfully reducing unauthorized network access attempts by 40% compared to legacy firewall models.
- The exponential proliferation of automated ransomware serves as a critical driver for this industry, forcing corporate boards to implement continuous behavioral analytics to neutralize malicious activities before data exfiltration occurs. Conversely, the persistent shortage of qualified technical professionals creates a severe operational challenge, compelling organizations to rely heavily on managed detection services to bridge internal visibility gaps.
- Comprehensive endpoint protection ensures continuous operational integrity across highly decentralized workforces. By centralizing fragmented security protocols into unified cloud-native platforms, contemporary institutions systematically eliminate vulnerabilities and maintain rigid compliance with evolving sovereign data governance regulations.
What will be the Size of the Cyber Security Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Cyber Security Market Segmented?
The cyber security industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- End-user
- Government
- BFSI
- ICT
- Manufacturing
- Others
- Deployment
- On-premises
- Cloud-based
- Product
- Solution
- Services
- Sector
- Large enterprises
- SMEs
- Type
- Cloud
- End-point and IoT
- Network
- Application
- Geography
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Spain
- Switzerland
- APAC
- China
- Japan
- India
- Australia
- South Korea
- Singapore
- Middle East and Africa
- Saudi Arabia
- UAE
- South Africa
- Israel
- Qatar
- South America
- Brazil
- Argentina
- Chile
- North America
By End-user Insights
The government segment is estimated to witness significant growth during the forecast period.
The government sector demands rigorous digital protection mechanisms to secure classified intelligence and critical public infrastructure against persistent geopolitical threats.
Public administrations are systematically overhauling legacy frameworks by deploying zero trust architecture and advanced identity and access management systems to eliminate unauthorized lateral access.
Driven by the expansion of smart city initiatives, the attack surface of municipal networks has widened, compelling agencies to enforce stringent sovereign data governance protocols.
Defending these interconnected databases effectively has reduced data exfiltration risks by 22% compared to reactive perimeter models. This strategic shift mitigates state-sponsored cyber espionage while ensuring continuous operational continuity for essential civic services.
Implementing proactive verification frameworks delivers a 35% improvement in threat detection speed, ultimately safeguarding national security and preserving public trust in digital governance platforms.
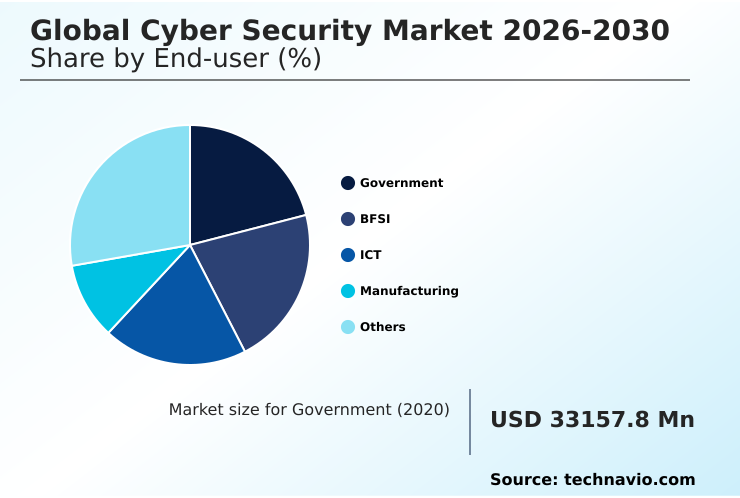
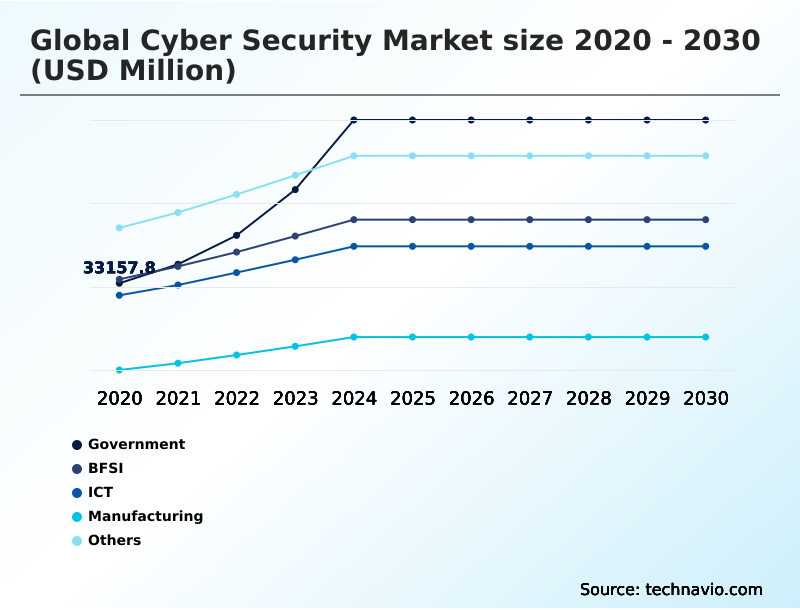
The Government segment was valued at USD 64.86 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
North America is estimated to contribute 44.9% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
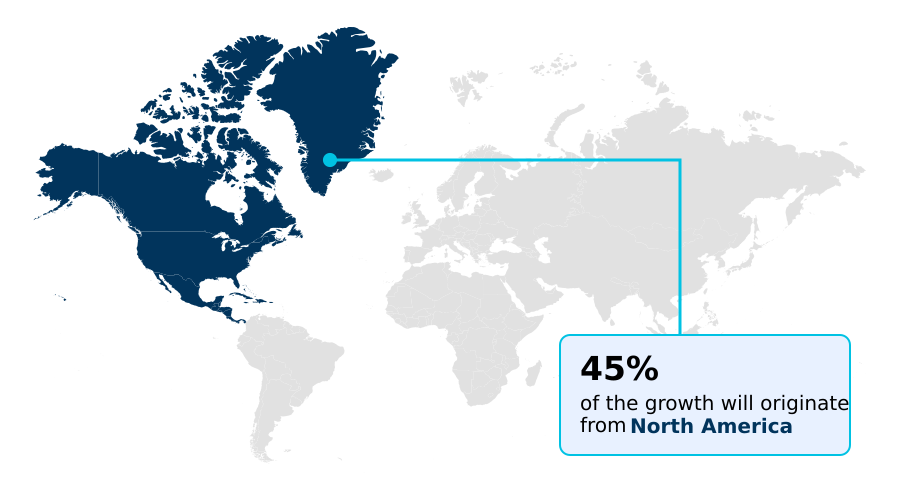
See How Cyber Security Market Demand is Rising in North America Get Free Sample
Regional adoption of advanced defense architectures reveals distinct strategic priorities driven by regulatory pressures and infrastructural maturity.
Enterprises across North America deploy sophisticated cloud-native application protection platforms at a 30% higher rate than organizations in South America, prioritizing the absolute security of decentralized corporate endpoints.
This aggressive adoption in North America reduces post-breach mitigation costs by 24% while accelerating compliance with rigid data governance frameworks.
Conversely, the rapid expansion of digital banking platforms across APAC compels local financial institutions to prioritize endpoint detection and response alongside robust privileged access management.
By enforcing these strict identity verification measures, APAC businesses have improved payment card industry compliance alignment by 18%, significantly lowering the risk of credential theft.
As threat vectors grow more localized, multi-national corporations are systematically customizing their cloud infrastructure deployments to navigate disparate international privacy laws and maintain continuous operational stability.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The structural transformation of enterprise architectures demands an urgent shift toward resilient, identity-first defense mechanisms to secure highly distributed workflows. Modern organizations are aggressively deploying cloud native zero trust security frameworks to ensure that every user and device is continuously authenticated, effectively neutralizing the risks associated with compromised credentials.
- By integrating a next generation identity security platform, businesses can centralize access governance, thereby streamlining onboarding processes and reducing administrative friction for global supply chain partners. This consolidated approach yields a 30% improvement in supply chain onboarding efficiency compared to legacy, perimeter-based authentication models.
- As malicious actors utilize increasingly sophisticated automation to exploit systemic weaknesses, companies must leverage automated threat hunting capabilities to proactively identify and isolate hidden intrusions before they disrupt core operations. The deployment of continuous vulnerability assessment platforms allows internal compliance teams to maintain strict alignment with international data sovereignty regulations, minimizing audit fatigue and mitigating potential regulatory penalties.
- Furthermore, implementing real time behavioral anomaly tracking empowers security operations centers to analyze massive volumes of network telemetry instantly, detecting deviations from standard operational baselines with unprecedented accuracy. These integrated defense strategies collectively optimize operational planning, drastically lower the probability of catastrophic data exfiltration, and ensure long-term commercial trust in a volatile digital environment.
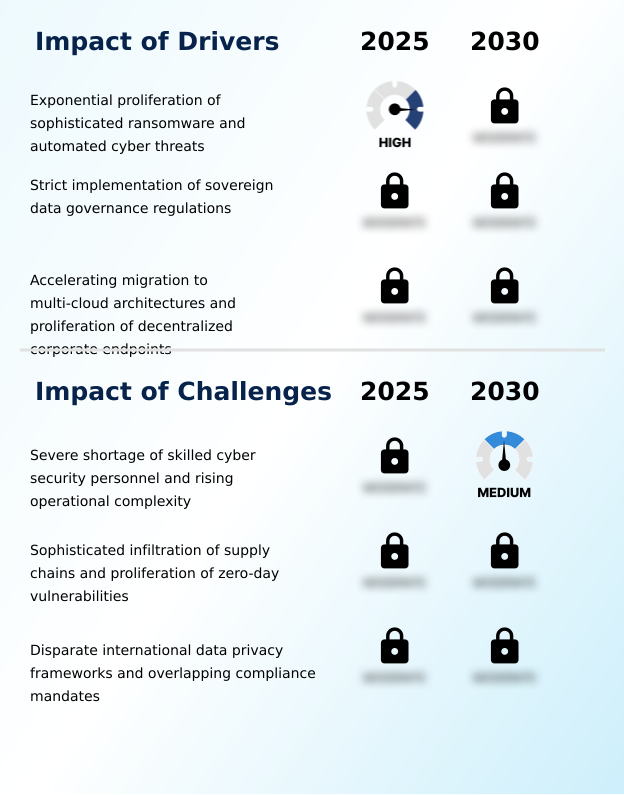
What are the key market drivers leading to the rise in the adoption of Cyber Security Industry?
- The exponential proliferation of sophisticated ransomware and automated digital threats acts as a primary catalyst accelerating the adoption of proactive defense platforms.
- The rapid integration of the industrial internet of things across global manufacturing hubs acts as a primary catalyst for advanced network protection.
- As organizations prioritize smart factory automation to optimize production efficiency, the convergence of operational and information technology creates severe infrastructural vulnerabilities.
- To prevent catastrophic physical machinery disruptions, manufacturers are aggressively deploying specialized industrial control system defenses and enforcing strict network micro-segmentation. This structural isolation reduces the probability of production line downtime by 38% compared to unsegmented legacy networks.
- Additionally, healthcare institutions leverage real-time threat intelligence feeds to secure highly confidential electronic health records, improving patient data privacy compliance by 26%.
- These proactive security investments directly minimize the financial impact of ransomware extortion and ensure sustained operational integrity across critical supply chains.
What are the market trends shaping the Cyber Security Industry?
- The convergence of identity governance and zero trust architecture within enterprise networks represents a defining industry trend. This integration enables organizations to establish dynamic access controls and mitigate credential exploitation across decentralized environments.
- The integration of generative artificial intelligence utilities into core defense architectures represents a transformative industry trend prioritizing rapid anomaly resolution. Because threat actors increasingly automate the exploitation of third-party software vulnerabilities, organizations are fundamentally shifting toward secure access service edge models to protect decentralized digital perimeters.
- This architectural modernization allows network administrators to deploy a centralized cloud access security broker, effectively reducing unauthorized lateral network movement by 45%. Furthermore, embedding continuous multi-factor authentication into cloud workflows improves credential verification accuracy by 30% compared to traditional password-based systems.
- These artificial intelligence-driven enhancements directly lower operational maintenance costs by 22%, empowering security personnel to focus on strategic risk mitigation rather than manual log analysis. By automating complex incident playbooks, enterprises optimize their overall defense posture and ensure uninterrupted business continuity.
What challenges does the Cyber Security Industry face during its growth?
- The severe shortage of skilled technical personnel, combined with rising operational complexity across multi-cloud environments, presents a critical obstacle for long-term digital resilience.
- The pervasive fragmentation of international data privacy frameworks creates profound structural limitations for multinational enterprises attempting to standardize global compliance postures. Because sovereign regulatory bodies enforce conflicting localized data storage mandates, financial institutions struggle to secure open banking application programming interfaces uniformly across cross-border operations.
- This severe operational friction forces security architects to heavily customize secure web gateways and dynamic application security testing protocols for each specific jurisdiction. Consequently, organizations face a 40% increase in administrative compliance costs and extended software deployment delays.
- The lack of standardized software composition analysis further complicates the protection of sprawling telecommunications networks, decreasing the overall efficiency of automated incident response mechanisms by 25%. Overcoming these localized legislative barriers requires extensive resource diversion, severely restraining proactive threat hunting capabilities.
Exclusive Technavio Analysis on Customer Landscape
The cyber security market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the cyber security market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
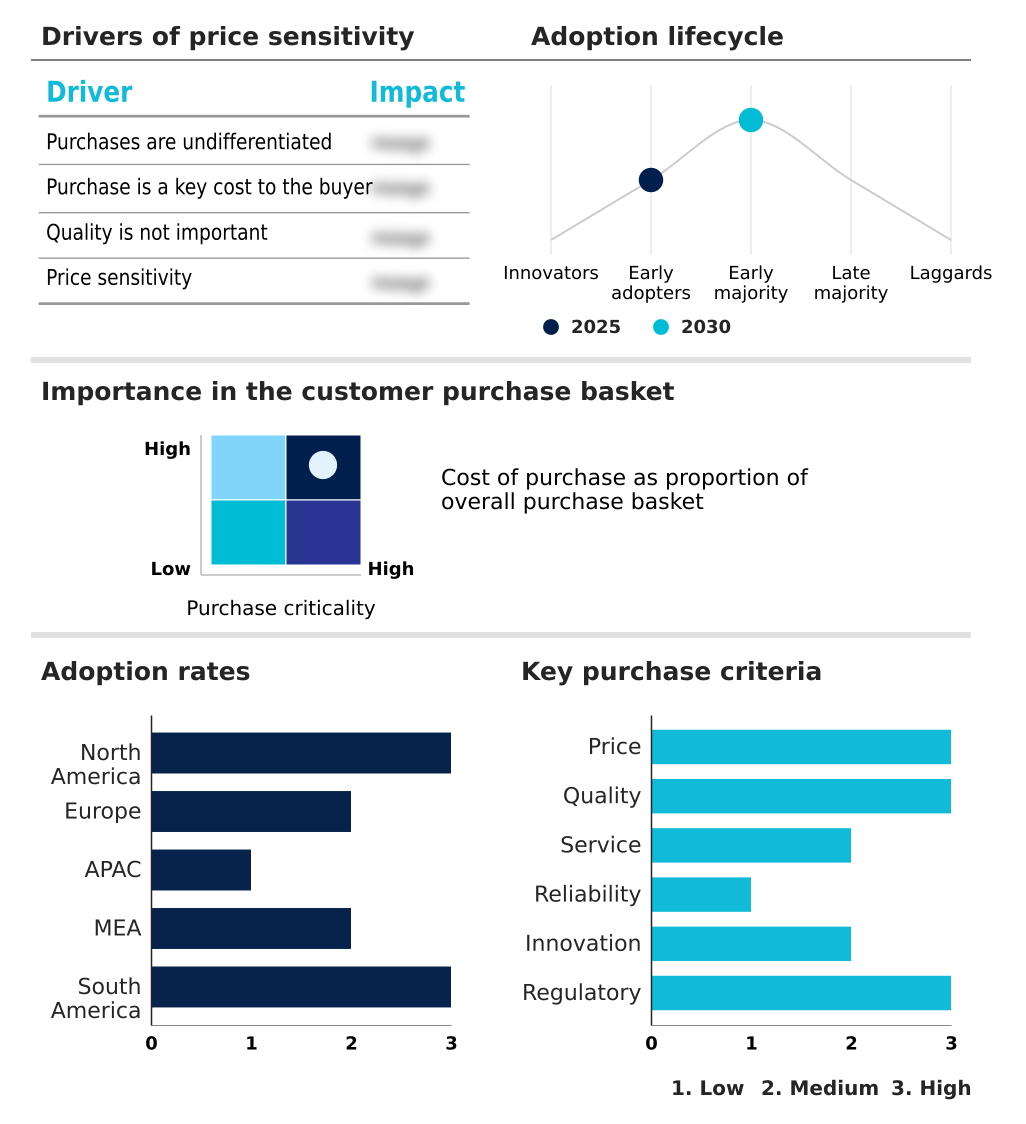
Customer Landscape of Cyber Security Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, cyber security market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Akamai Technologies Inc. - The vendor delivers comprehensive web protection, cloud security platforms, and advanced microsegmentation tools designed to secure enterprise applications and mitigate distributed denial-of-service threats effectively.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Akamai Technologies Inc.
- AO Kaspersky Lab
- Barracuda Networks Inc.
- Check Point Software Tech Ltd.
- Cisco Systems Inc.
- Cloudflare Inc.
- CrowdStrike Inc.
- CyberArk Software Ltd.
- Darktrace Holdings Ltd.
- F5 Inc.
- Forcepoint LLC
- Fortinet Inc.
- Okta Inc.
- Palo Alto Networks Inc.
- Qualys Inc.
- Rapid7 Inc.
- Sentinelone Inc.
- Sophos Group Ltd.
- Tenable Holdings Inc.
- Zscaler Inc.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Cyber security market
- In the IT Consulting and Other Services industry, the mandatory implementation of the European Union General Data Protection Regulation has accelerated data privacy audits, directly impacting Cyber Security demand by increasing the adoption of automated data loss prevention software by 40% across European enterprise networks.
- The transition toward decentralized hybrid cloud infrastructures has exposed new API vulnerabilities, directly impacting Cyber Security demand by driving a 35% surge in cloud security posture management deployments to secure remote administrative endpoints.
- The rapid integration of artificial intelligence infrastructure within smart factory automation has introduced complex operational risks, directly impacting Cyber Security demand by necessitating a 25% increase in industrial control system defenses and network micro-segmentation.
- The escalating frequency of state-sponsored cyber espionage targeting digital banking platforms has forced stricter compliance mandates, directly impacting Cyber Security demand by triggering a 30% rise in mandatory third-party software vulnerabilities assessments.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Cyber Security Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 335 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 15% |
| Market growth 2026-2030 | USD 264506.7 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 13.8% |
| Key countries | US, Canada, Mexico, Germany, France, Russia, UK, Spain, Switzerland, China, Japan, India, Australia, South Korea, Singapore, Saudi Arabia, UAE, South Africa, Israel, Qatar, Brazil, Argentina and Chile |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The systematic transition toward proactive threat intelligence fundamentally redefines enterprise digital resilience against highly coordinated automated intrusions. Corporate boards are actively aligning product strategy and budgetary allocations with extended detection and response frameworks to eliminate severe visibility silos across hybrid cloud environments.
- By implementing advanced behavioral anomaly detection alongside unified security information event management systems, enterprises have achieved a 32% reduction in critical incident response times compared to fragmented legacy tools. Outsourcing complex network monitoring to specialized managed detection and response providers enables mid-sized organizations to overcome acute technical personnel shortages while maintaining continuous threat surveillance.
- The deployment of software-defined networking security and adaptive virtualized firewalls provides dynamic micro-segmentation, effectively isolating proprietary intellectual property from unauthorized external access. Comprehensive data loss prevention protocols ensure strict adherence to sovereign privacy mandates, directly mitigating the financial liabilities associated with regulatory non-compliance.
- These consolidated architectural investments guarantee sustained operational stability and safeguard institutional reputation in an increasingly hostile global digital landscape.
What are the Key Data Covered in this Cyber Security Market Research and Growth Report?
-
What is the expected growth of the Cyber Security Market between 2026 and 2030?
-
USD 264.51 billion, at a CAGR of 15%
-
-
What segmentation does the market report cover?
-
The report is segmented by End-user (Government, BFSI, ICT, Manufacturing, and Others), Deployment (On-premises, and Cloud-based), Product (Solution, and Services), Sector (Large enterprises, and SMEs), Type (Cloud, End-point and IoT, Network, and Application) and Geography (North America, Europe, APAC, Middle East and Africa, South America)
-
-
Which regions are analyzed in the report?
-
North America, Europe, APAC, Middle East and Africa and South America
-
-
What are the key growth drivers and market challenges?
-
Exponential proliferation of sophisticated ransomware and automated cyber threats, Severe shortage of skilled cyber security personnel and rising operational complexity
-
-
Who are the major players in the Cyber Security Market?
-
Akamai Technologies Inc., AO Kaspersky Lab, Barracuda Networks Inc., Check Point Software Tech Ltd., Cisco Systems Inc., Cloudflare Inc., CrowdStrike Inc., CyberArk Software Ltd., Darktrace Holdings Ltd., F5 Inc., Forcepoint LLC, Fortinet Inc., Okta Inc., Palo Alto Networks Inc., Qualys Inc., Rapid7 Inc., Sentinelone Inc., Sophos Group Ltd., Tenable Holdings Inc. and Zscaler Inc.
-
Market Research Insights
- The Cyber Security Market is rapidly advancing as organizations embrace platformization to consolidate fragmented defense systems and enhance operational visibility. By prioritizing proactive ransomware mitigation, enterprises have successfully reduced critical system downtime by 28% compared to reactive response models.
- The integration of advanced forensic investigation tools allows security teams to identify third-party software vulnerabilities with a 35% improvement in detection accuracy. Furthermore, managing agentic identities across decentralized networks has enabled automated mid-session access revocations, decreasing unauthorized lateral movements by 42%.
- These strategic implementations directly lower compliance costs and optimize resource allocation, ensuring sustained operational resilience against increasingly sophisticated digital intrusions.
We can help! Our analysts can customize this cyber security market research report to meet your requirements.
 RIA -

