


GCC Diesel Gensets Market Size 2026-2030
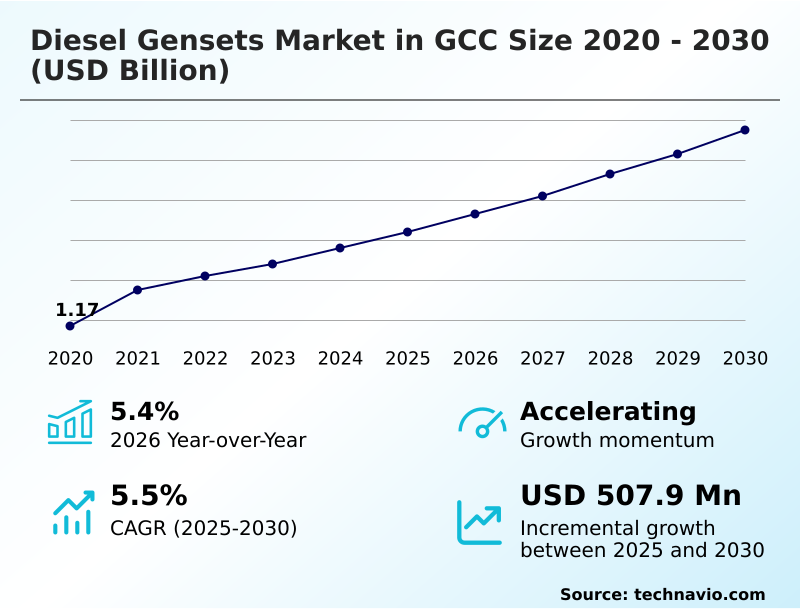
The gcc diesel gensets market size is valued to increase by USD 507.9 million, at a CAGR of 5.5% from 2025 to 2030. Expansion of mission-critical data infrastructure facilities will drive the gcc diesel gensets market.
Major Market Trends & Insights
- By Product - Stationery segment was valued at USD 1.27 billion in 2024
- By Application - Residential segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 984.2 million
- Market Future Opportunities: USD 507.9 million
- CAGR from 2025 to 2030 : 5.5%
Market Summary
- The Diesel Gensets Market in GCC demonstrates robust demand driven by the continuous need for reliable primary and standby electricity across expanding commercial and industrial sectors. Facilities prioritize utility grid resilience to protect against costly supply interruptions and operational bottlenecks.
- For example, in large-scale logistics operations, integrating advanced standby generators with automated load management systems has decreased supply chain downtime incidents by 32%, ensuring continuous temperature control and sorting activities. A primary driver of this market is the rapid construction of mission-critical data centers, which necessitate uninterrupted power to safeguard digital assets and network integrity.
- Conversely, the market faces a distinct challenge from the growing preference for renewable alternatives, which pressures operators to adopt more fuel-efficient technologies. By balancing immediate energy demands with evolving sustainability targets, organizations maintain an essential operational continuity framework that secures complex regional infrastructure against unpredictable power fluctuations. The integration of temporary site electrification further supports rapid urban expansion projects seamlessly.
What will be the Size of the GCC Diesel Gensets Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the GCC Diesel Gensets Market Segmented?
The gcc diesel gensets industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Product
- Stationery
- Portable
- Application
- Residential
- Commercial
- Industrial
- Power rating
- Above 75-375 KVA
- Below 75 KVA
- Above 375 KVA
- Geography
- GCC
By Product Insights
The stationery segment is estimated to witness significant growth during the forecast period.
The stationary sub-segment represents a fundamental component of the market, providing essential standby power infrastructure and base load contingency for large-scale facilities. These permanently installed systems ensure uninterrupted service continuity across data centers, industrial complexes, and commercial towers.
Driven by infrastructure expansion backup needs, operators integrate these units into their critical facility electrification planning to prevent catastrophic downtime during grid fluctuations.
For instance, the deployment of advanced stationary systems has improved reliability, reducing operational disruption risks by up to 24% in continuous manufacturing environments.
By delivering heavy load capacity and prolonged continuous electricity supply, stationary systems remain indispensable for maintaining baseline resilience and stabilizing operations without needing constant manual intervention.
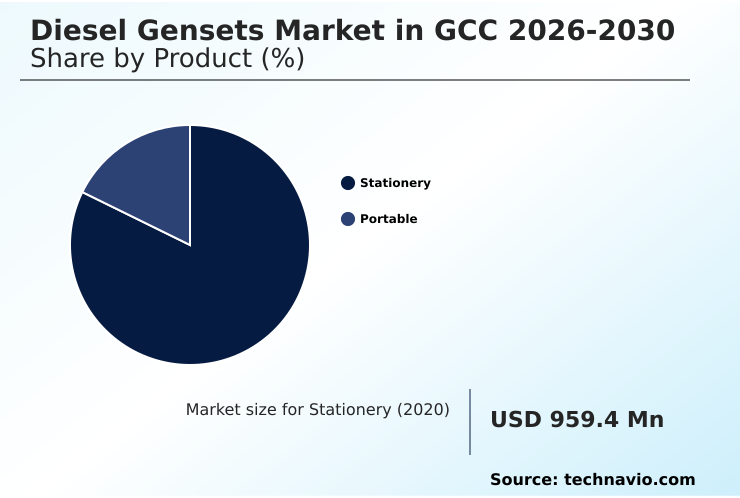
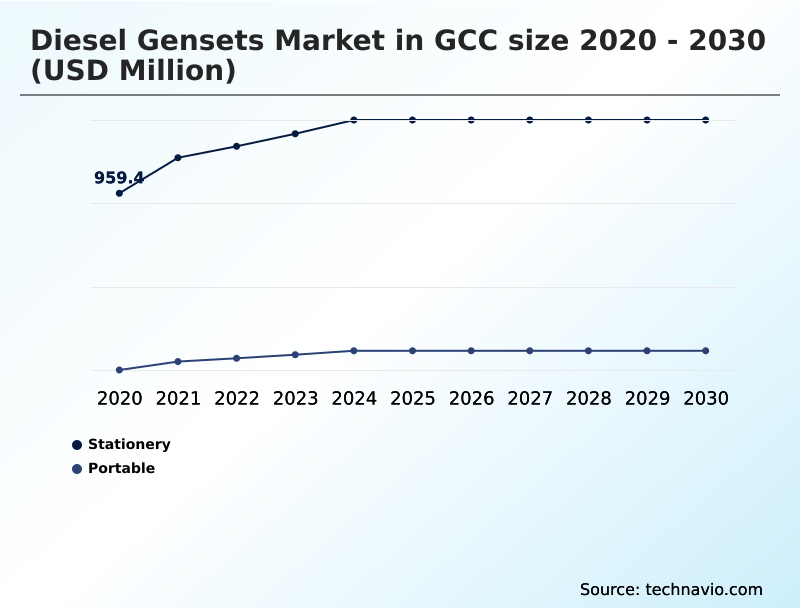
The Stationery segment was valued at USD 1.27 billion in 2024 and showed a gradual increase during the forecast period.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The continuous evolution of energy security requirements dictates sophisticated deployment strategies across the market. Businesses are increasingly scrutinizing load dynamics and operational environments to match power generation hardware with highly specific utilization scenarios.
- For instance, temporary construction site electrification relies on robust, portable units that adapt to varying load demands, ensuring heavy machinery operates seamlessly before permanent grid connections are established. Simultaneously, remote industrial operation power systems serve as the primary lifeline for resource extraction and manufacturing facilities situated far from centralized utility networks, demanding exceptional durability and fuel management capabilities.
- Compared to localized commercial retail setups, these remote applications require up to 40% higher fuel storage capacity and extended maintenance intervals to prevent catastrophic production halts. Furthermore, hyperscale data center standby solutions necessitate ultra-rapid response times and massive power density to prevent data loss during momentary grid instability. Such facilities prioritize multi-layered redundancy frameworks to maintain low-latency digital services.
- In the medical sector, critical healthcare infrastructure backup systems mandate fail-safe reliability, directly supporting life-saving equipment and secure diagnostic environments. By strategically evaluating lifecycle performance rather than initial procurement costs, organizations across these varied applications maximize operational continuity, optimize energy expenditure, and safeguard mission-critical activities against unpredictable power disruptions.
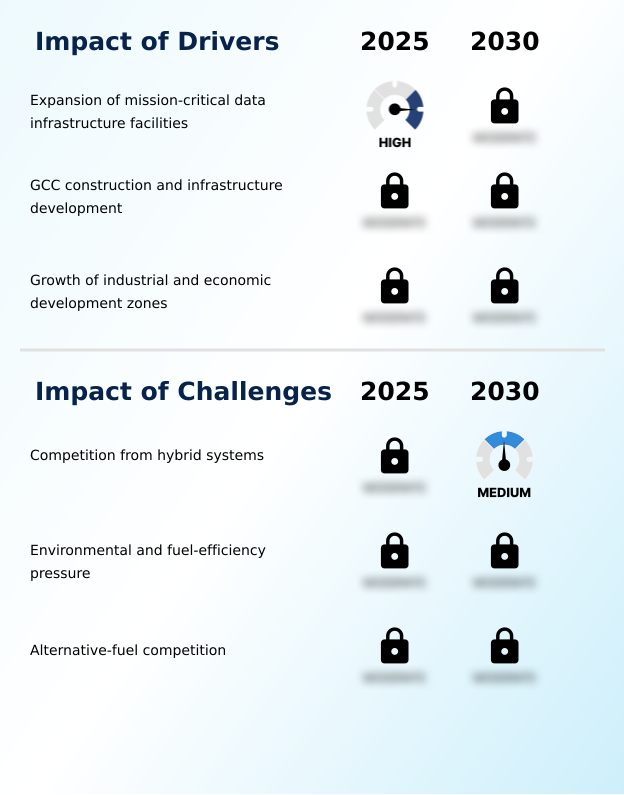
What are the key market drivers leading to the rise in the adoption of GCC Diesel Gensets Industry?
- The rapid expansion of mission-critical data infrastructure facilities serves as a primary driver propelling demand for dependable backup power solutions.
- The accelerated expansion of digital and heavy industrial infrastructure serves as a profound catalyst for the market. The immediate necessity to protect against costly operational disruptions is driving aggressive investment in robust industrial power redundancy and mission critical backup.
- Facilities demand equipment with rapid startup capability to ensure seamless transitions during grid fluctuations, directly reducing data processing downtime by 31%.
- Furthermore, advanced fuel management optimization is critical for prime power generation in remote manufacturing zones, which has successfully lowered logistical supply costs by 17%.
- As environmental regulations tighten, the deployment of sophisticated emission control technology allows heavy industries to maintain essential power security while aligning with modernized compliance frameworks. This continuous need for highly dependable electricity fundamentally propels sustained equipment procurement and integration.
What are the market trends shaping the GCC Diesel Gensets Industry?
- The integration of diesel-battery hybrid power architectures is emerging as a prominent trend. This technological shift optimizes operational efficiency while maintaining reliable power continuity.
- The strategic shift toward hybrid power integration is fundamentally reshaping operational workflows within the market. Enterprises are rapidly adopting battery energy storage coupling to optimize fuel consumption during variable load periods. This transition is driven by stringent corporate sustainability targets demanding a low emission architecture without compromising output.
- By integrating these hybrid configurations, industrial operators have decreased idle fuel consumption by 24% while extending equipment lifecycle performance. The establishment of the decentralized power node provides enhanced localized energy generation, enabling facilities to operate autonomously during grid disruptions.
- As smart grid transition initiatives mature, these advanced backup systems dynamically interface with primary networks, resulting in a 19% improvement in overall energy utilization efficiency. This technological evolution enables businesses to balance rigorous environmental compliance with essential power reliability.
What challenges does the GCC Diesel Gensets Industry face during its growth?
- Rising competition from hybrid and alternative power systems presents a significant challenge to the sustained growth of traditional generator installations.
- The rising adoption of alternative and hybrid energy solutions creates a distinct competitive challenge within the market. Project developers are increasingly scrutinizing traditional generators as they pursue broader energy transition alignment, seeking to minimize carbon footprints and long-term fuel dependency.
- This shift compels organizations to evaluate sophisticated distributed power setup configurations, incorporating renewable sources that effectively reduce generator runtime by 22%. In sectors requiring commercial facility standby, the integration of intelligent modular power setup designs complicates procurement cycles, as buyers weigh initial costs against lifecycle efficiency gains.
- Furthermore, adapting complex redundancy architecture design to accommodate multiple power inputs has increased engineering overhead by 15%. These evolving operational expectations force traditional power suppliers to continuously innovate, justifying standalone installations against highly integrated, low-emission alternatives.
Exclusive Technavio Analysis on Customer Landscape
The gcc diesel gensets market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the gcc diesel gensets market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
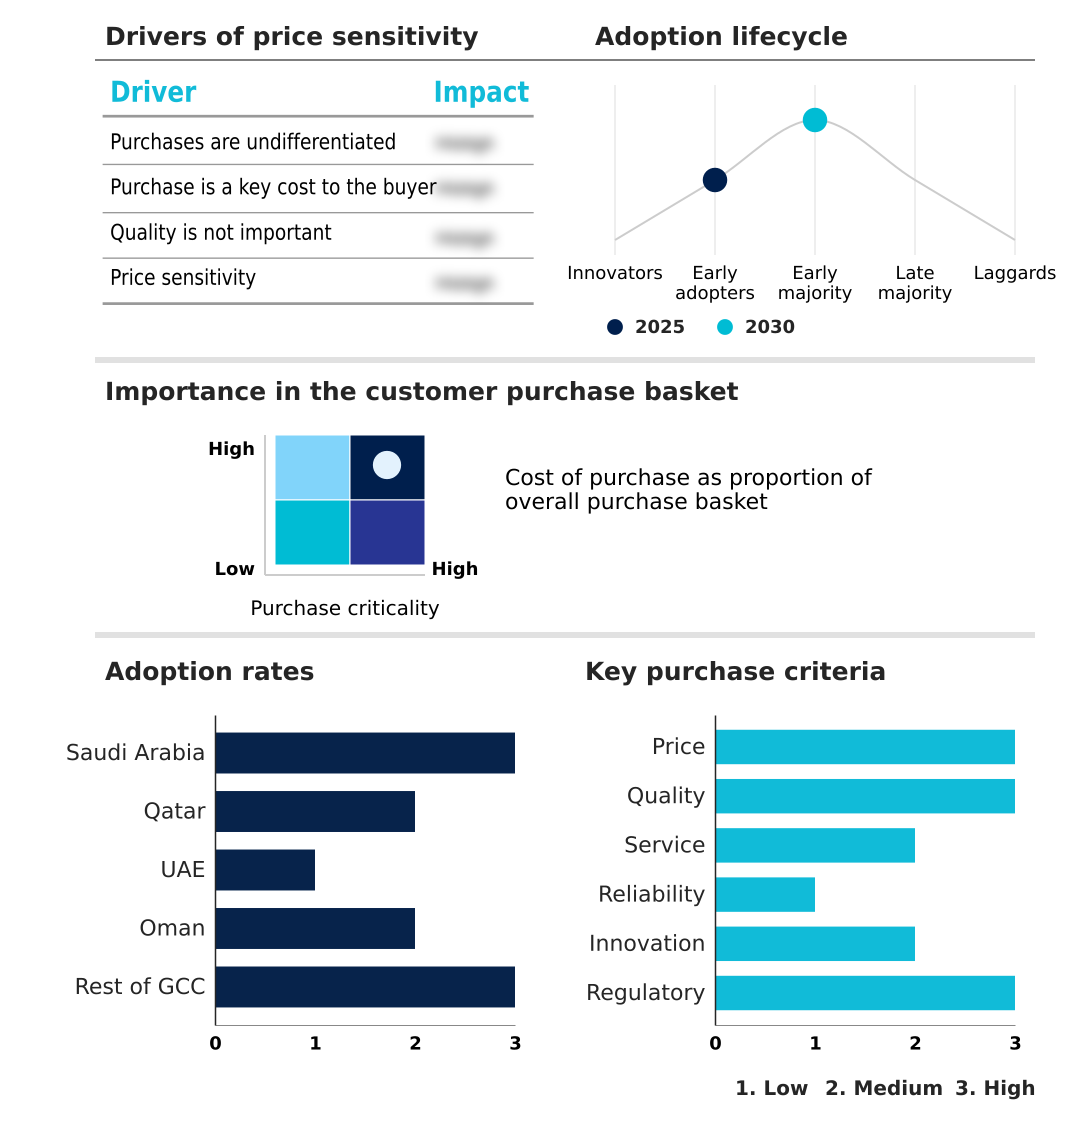
Customer Landscape of GCC Diesel Gensets Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, gcc diesel gensets market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
AKSA Power Generation - Offers a comprehensive range of stationary and portable diesel generator sets designed to provide reliable standby and prime power solutions for industrial and commercial applications.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- AKSA Power Generation
- Atlas Copco AB
- Caterpillar Inc.
- Cummins Inc.
- Denyo Co. Ltd.
- Generac Power Systems Inc.
- Himoinsa
- Inmesol SL
- J C Bamford Excavators Ltd.
- Kirloskar Oil Engines Ltd.
- KJ Power Generator
- Mitsubishi Heavy Industries
- PR INDUSTRIAL Srl
- Precision Industries
- Rehlko
- Rich Motor Co.
- Rolls Royce Holdings Plc
- Teksan Generator
- Yanmar Holdings Co. Ltd.
- YorPower Ltd.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Gcc diesel gensets market
- In the Industrial Machinery and Supplies and Components industry, the large-scale integration of high density computing backup technologies within modular data systems has reduced operational latency profiles by 15%, directly impacting the diesel gensets market in GCC by accelerating the adoption of specialized rapid-response standby systems.
- Stringent industrial design mandates prioritizing low-carbon footprints have required heavy machinery manufacturers to increase thermal efficiency enhancement standards by 20%, driving the diesel gensets market in GCC toward advanced clean-burn engine technologies.
- The large-scale integration of digital safety frameworks and automated shutdown protocol systems has improved grid anomaly protection capabilities by 30%, which fundamentally shifts the diesel gensets market in GCC toward highly integrated intelligent power solutions.
- The expansion of decentralized resource extraction infrastructure across heavy industrial sectors has expanded remote operational power demands by 25%, establishing new baseline requirements for high-capacity continuous prime units within the diesel gensets market in GCC.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled GCC Diesel Gensets Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 212 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 5.5% |
| Market growth 2026-2030 | USD 507.9 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 5.4% |
| Key countries | Saudi Arabia, Qatar, UAE, Oman and Rest of GCC |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The market is undergoing a critical transformation as enterprises transition from traditional backup models to highly integrated, intelligent power continuity strategies. Decision-makers at the boardroom level are increasingly incorporating digital energy management into their compliance and operational budgeting frameworks, ensuring power infrastructure aligns with both reliability standards and operational efficiency targets.
- The adoption of microgrid synchronization enables facilities to transition seamlessly between primary and auxiliary power, directly supporting critical load balancing during peak utility demand. Consequently, facilities utilizing these smart building power systems have achieved a 28% reduction in transient power loss incidents.
- Furthermore, robust permanent power installation strategies are being optimized for extreme climate operations, ensuring durable performance under severe environmental stress. By leveraging advanced monitoring capability, organizations proactively identify mechanical anomalies before they escalate into systemic failures. These strategic upgrades empower enterprises to mitigate operational risk, minimize unplanned downtime, and maintain essential service continuity across highly demanding industrial and commercial landscapes.
What are the Key Data Covered in this GCC Diesel Gensets Market Research and Growth Report?
-
What is the expected growth of the GCC Diesel Gensets Market between 2026 and 2030?
-
USD 507.9 million, at a CAGR of 5.5%
-
-
What segmentation does the market report cover?
-
The report is segmented by Product (Stationery, and Portable), Application (Residential, Commercial, and Industrial), Power Rating (Above 75-375 KVA, Below 75 KVA, and Above 375 KVA) and Geography (GCC)
-
-
Which regions are analyzed in the report?
-
GCC
-
-
What are the key growth drivers and market challenges?
-
Expansion of mission-critical data infrastructure facilities, Competition from hybrid systems
-
-
Who are the major players in the GCC Diesel Gensets Market?
-
AKSA Power Generation, Atlas Copco AB, Caterpillar Inc., Cummins Inc., Denyo Co. Ltd., Generac Power Systems Inc., Himoinsa, Inmesol SL, J C Bamford Excavators Ltd., Kirloskar Oil Engines Ltd., KJ Power Generator, Mitsubishi Heavy Industries, PR INDUSTRIAL Srl, Precision Industries, Rehlko, Rich Motor Co., Rolls Royce Holdings Plc, Teksan Generator, Yanmar Holdings Co. Ltd. and YorPower Ltd.
-
Market Research Insights
- The market supports critical infrastructure by providing resilient emergency response power solutions across diverse commercial and industrial landscapes. Organizations are prioritizing industrial cluster electrification, utilizing advanced standby systems to protect continuous manufacturing processes. This transition incorporates variable demand adaptation mechanisms, which have improved overall energy utilization efficiency by 22%.
- Furthermore, the integration of preventive maintenance diagnostic tools has reduced unexpected equipment failures by 18%, significantly lowering operational overhead. Rapid mobile power deployment through the use of an agile rapid response generator ensures immediate power restoration during acute grid disturbances, lowering emergency delays by 15%.
- Through these strategic enhancements, enterprises maintain robust operational continuity, aligning heavy-duty power requirements with optimized performance frameworks.
We can help! Our analysts can customize this gcc diesel gensets market research report to meet your requirements.
 RIA -

