Dispersing Agents Market Analysis, Size, and Forecast 2026-2030: APAC (China, Japan, and India), North America (US, Canada, and Mexico), Europe (Germany, UK, and France), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, South Africa, and UAE), and Rest of World (ROW)

Dispersing Agents Market Analysis, Size, and Forecast 2026-2030:
APAC (China, Japan, and India), North America (US, Canada, and Mexico), Europe (Germany, UK, and France), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, South Africa, and UAE), and Rest of World (ROW)

Published: Oct 2026 322 Pages SKU: IRTNTR74534

Market Overview at a Glance

$2.59 B
Market Opportunity
5.8%
CAGR 2025 - 2030
30%
APAC Growth
$2.53 B
Anionic dispersants segment 2024

Dispersing Agents Market Size 2026-2030

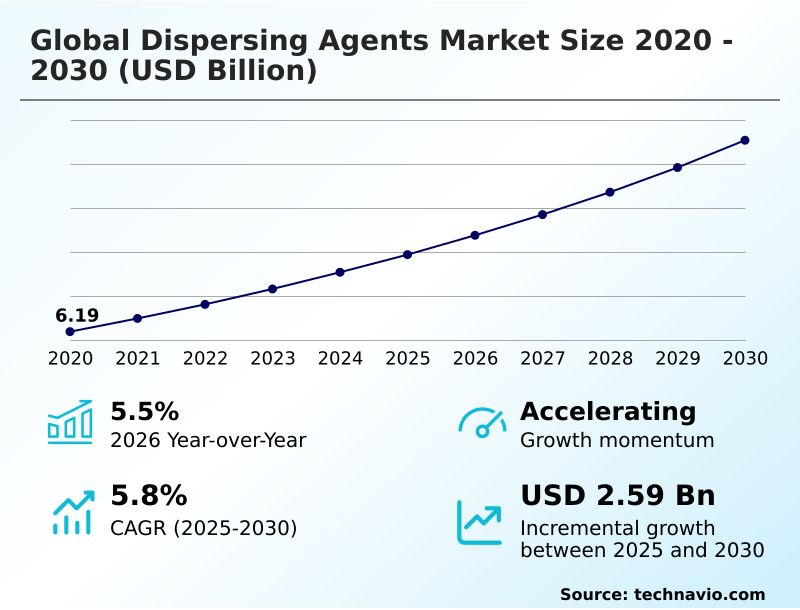
The dispersing agents market size is valued to increase by USD 2.59 billion, at a CAGR of 5.8% from 2025 to 2030. Rapid expansion of global construction and infrastructure sector will drive the dispersing agents market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 30% growth during the forecast period.
  • By Type - Anionic dispersants segment was valued at USD 2.53 billion in 2024
  • By End-user - Construction segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 4.34 billion
  • Market Future Opportunities: USD 2.59 billion
  • CAGR from 2025 to 2030 : 5.8%

Market Summary

  • The Dispersing Agents Market functions as a critical enabler of material stabilization, directly influencing the performance of coatings, agrochemicals, and construction materials. These specialized additives prevent particle agglomeration, ensuring uniform distribution and optimal rheology in complex fluid matrices.
  • In automotive manufacturing, production lines utilize advanced polymeric stabilizers for automotive refinish coatings, resulting in a 25% improvement in paint transfer efficiency compared to legacy solvent systems. The persistent expansion of civil infrastructure drives substantial demand, as superplasticizers allow builders to reduce water content in concrete while maintaining superior flowability.
  • Conversely, the industry faces severe challenges from stringent environmental mandates that restrict volatile emissions. Navigating these regulatory frameworks requires intensive formulation redesign, increasing R&D expenditures to develop functional alternatives. By integrating universal compatibility profiles and robust tension reducers, industrial formulators successfully balance mechanical durability with ecological compliance.
  • The continuous evolution of polymer synthesis empowers chemical suppliers to deliver highly efficient stabilizing solutions tailored to distinct viscosity requirements.

What will be the Size of the Dispersing Agents Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Dispersing Agents Market Segmented?

The dispersing agents industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Type
    • Anionic dispersants
    • Non-ionic dispersants
    • Cationic dispersants
    • Amphoteric dispersants
  • End-user
    • Construction
    • Paints and coatings
    • Oil and gas
    • Detergents
    • Others
  • Method
    • Water-based systems
    • Solvent-based systems
    • Powder-based systems
    • High-solid systems
  • Geography
    • APAC
      • China
      • Japan
      • India
      • Indonesia
      • Australia
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • South Africa
      • UAE
      • Turkey
      • Israel

By Type Insights

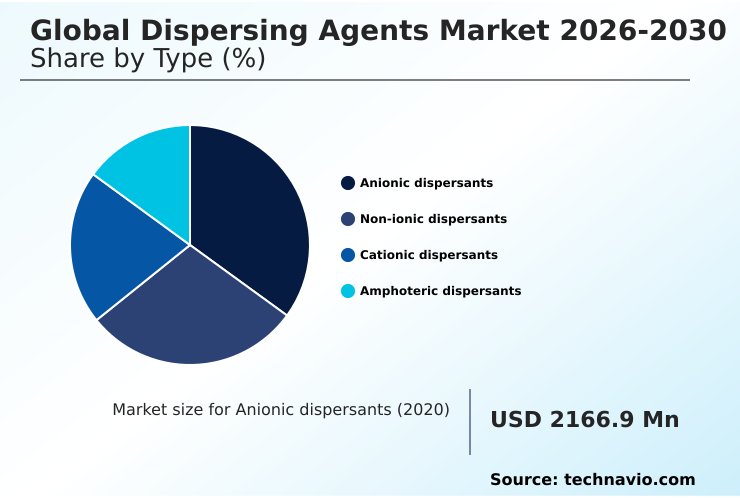
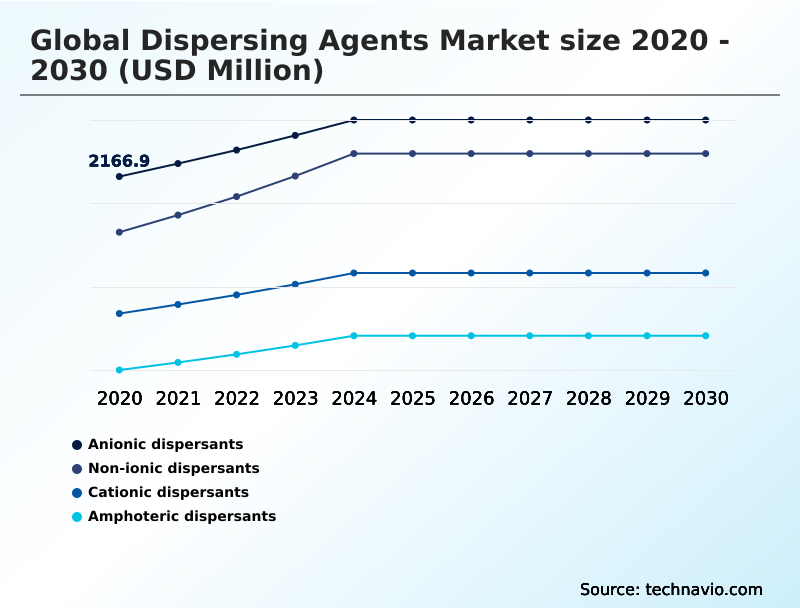
The anionic dispersants segment is estimated to witness significant growth during the forecast period.

Anionic dispersants play a critical role in aqueous formulations by deploying powerful electrostatic repulsion agents that prevent agglomeration and maintain low system viscosity.

These polycarboxylate ether superplasticizers and lignosulfonate additives attach to solid particles, creating negative surface charges that ensure efficient particle separation. Formulators leverage these robust solutions to optimize high-solids formulation polymers across civil construction and architectural paint formulations.

By stabilizing cementitious mixture plasticizers and dry-mix construction mortars, these anionic compounds enhance operational flowability and securely suspend hydrophobic mineral fillers. Facilities utilizing advanced anionic chemistries have recorded a 15% reduction in mechanical milling energy consumption compared to traditional alternatives.

This efficiency gain stems from superior electrosteric barrier formation that accelerates dispersion cycles while increasing maximum pigment volume concentration limits.
Get Free Sample

The Anionic dispersants segment was valued at USD 2.53 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

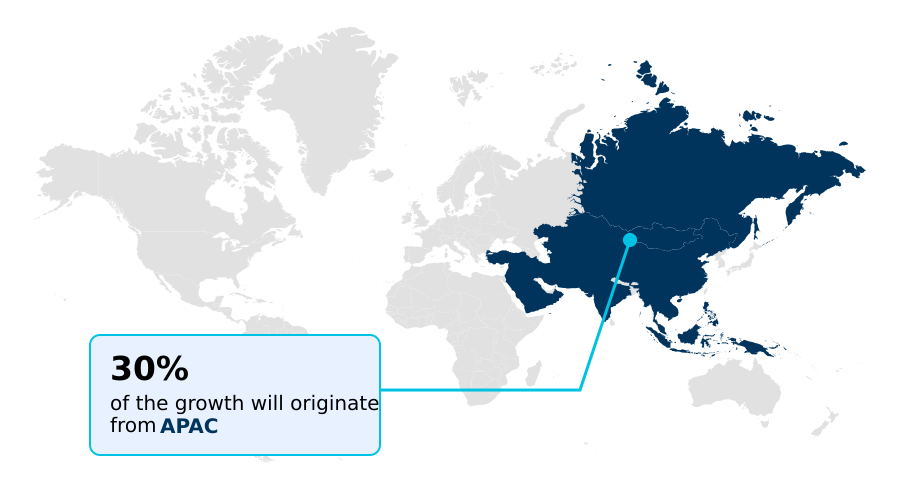
APAC is estimated to contribute 30% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
See How Dispersing Agents Market Demand is Rising in APAC Get Free Sample

The Dispersing Agents Market exhibits distinct regional consumption patterns driven by localized industrial priorities.

APAC dominates the landscape, fueled by aggressive infrastructure investments where contractors rely on advanced block copolymer architectures to achieve a 25% improvement in concrete slump retention during severe summer conditions.

Furthermore, regional facilities extensively utilize calcium carbonate deflocculants to optimize mineral slurries and industrial maintenance coatings. In contrast, North America focuses heavily on sustainable surface treatments and rigorous volatile organic compound reduction.

Driven by strict emission standards, North American formulators have increased the adoption of waterborne coating dispersants by 30% relative to legacy solvent-borne hyperdispersants, securing essential compliance cost reductions.

By integrating highly efficient zwitterionic amphoteric surfactants to wet titanium dioxide fillers, businesses across these divergent geographies adapt supply chain strategies to maintain exceptional aesthetic performance while lowering environmental impacts.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The formulation landscape relies heavily on specialized chemical additives to overcome the intrinsic challenges of particulate agglomeration in industrial processing. A critical focus lies in developing bio-based dispersing agents for coatings, which allow manufacturers to align their product portfolios with tightening environmental benchmarks.
  • Transitioning to these sustainable options frequently yields a 20% enhancement in supply chain resilience by reducing dependence on volatile petrochemical feedstocks. In the construction sector, civil engineers extensively utilize polycarboxylate dispersants for high-strength concrete to achieve superior workability and rapid strength development under challenging ambient conditions.
  • This enables contractors to execute infrastructure projects with fewer structural defects and lower maintenance overheads. Simultaneously, the deployment of waterborne pigment stabilization chemical additives is reshaping the decorative and automotive finishes sector. By ensuring optimal color distribution and preventing flocculation, these additives help coating facilities decrease batch rejection rates substantially compared to previous production cycles.
  • Furthermore, modern agricultural practices increasingly depend on anionic dispersing agents for agrochemicals to maintain the efficacy of active ingredients during prolonged storage, thereby safeguarding crop yields. To address the demands of ultra-high-solids formulations, the integration of solvent-free polymeric hyperdispersants provides exceptional viscosity reduction and robust steric stabilization.
  • These highly tailored dispersing solutions directly empower formulators to maximize pigment loading, optimize processing energy, and ensure consistent mechanical durability across diverse commercial applications.
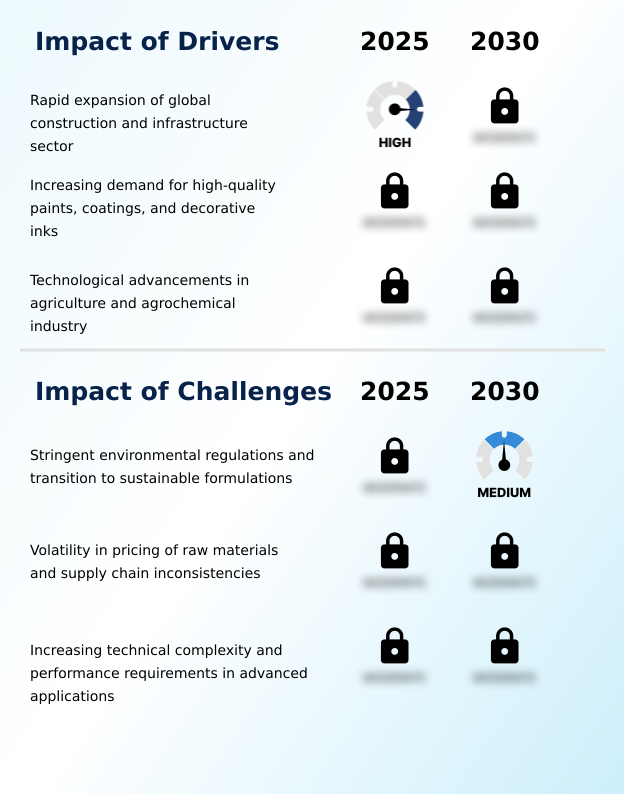
What are the key market drivers leading to the rise in the adoption of Dispersing Agents Industry?

  • The rapid expansion of civil construction and massive infrastructure projects serves as a primary catalyst accelerating the demand for high-performance chemical admixtures.

  • Rapid urbanization and the necessity for robust infrastructural resilience serve as primary demand catalysts for advanced chemical additives.
  • The continuous expansion of precision agriculture drives the immense consumption of agrochemical suspension concentrates, where formulators utilize sophisticated maleic acid copolymers to ensure active ingredients remain uniformly distributed, improving field application accuracy by 15% relative to conventional sprays.
  • Furthermore, deep-water energy exploration mandates the use of specialized drilling fluid thinners and steric stabilization mechanisms to maintain rheology under extreme pressure.
  • Automotive manufacturers also rely on polymeric quaternary amines to stabilize automotive refinish coatings and universal colorant systems, resulting in a 20% enhancement in cross-linking density optimization.
  • This sustained demand is driven by the absolute imperative to maximize mineral processing efficiency and construct highly durable marine protective barriers, enabling businesses to achieve accelerated project timelines and greater overall operational profitability.

What are the market trends shaping the Dispersing Agents Industry?

  • The transition toward bio-based and sustainable formulations represents a significant trend reshaping material development. This shift prioritizes renewable raw materials to meet rigorous ecological compliance standards.

  • The adoption of sustainable and highly functional particulate stabilizers represents a fundamental shift in material engineering. Manufacturers are rapidly integrating biodegradable wetting agents to address consumer demand for low-temperature wash formulations. This strategic transition allows chemical formulators to achieve a 25% improvement in overall energy efficiency during industrial cleaning cycles while ensuring crystal growth inhibition.
  • Concurrently, the deployment of advanced nano-dispersion technology is transforming the production of radiation-curable printing inks. By utilizing precise interfacial tension reducers and controlled radical polymerization techniques, ink producers have lowered printhead clogging incidents by up to 30% compared to traditional solvent mixtures. These innovations are critical for enhancing zinc oxide dispersion and optimizing ceramic slurry modifiers.
  • Because regulatory pressures compel industries to eliminate hazardous surfactants, businesses secure measurable operational cost reductions while maintaining superior colloidal suspension stability across modern manufacturing lines.

What challenges does the Dispersing Agents Industry face during its growth?

  • Rigorous environmental regulations and the complex transition toward green chemistry present substantial operational hurdles for formulation scientists.

  • Stringent environmental mandates and volatile raw material pricing impose severe constraints on formulation stability and production scalability. The forced elimination of traditional fatty alcohol ethoxylates heavily complicates emulsion polymerization synthesis, requiring intensive research into alternative pigment flocculation inhibitors.
  • Transitioning to these compliant chemistries frequently triggers a 15% increase in baseline manufacturing costs due to the necessity for sophisticated rheology modification polymers. Additionally, the inherent technical complexity of stabilizing asphaltene deposition inhibitors during macromolecular synthesis processing exacerbates persistent supply chain bottlenecks.
  • This friction occurs because protecting synthetic resin matrices from degradation during high-shear blending processes demands prolonged and expensive stability testing. As a result, specialty chemical providers experience extended product development cycles, which delays commercial time-to-market by up to 20% and heavily strains operational R&D budgets across the market.

Exclusive Technavio Analysis on Customer Landscape

The dispersing agents market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the dispersing agents market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
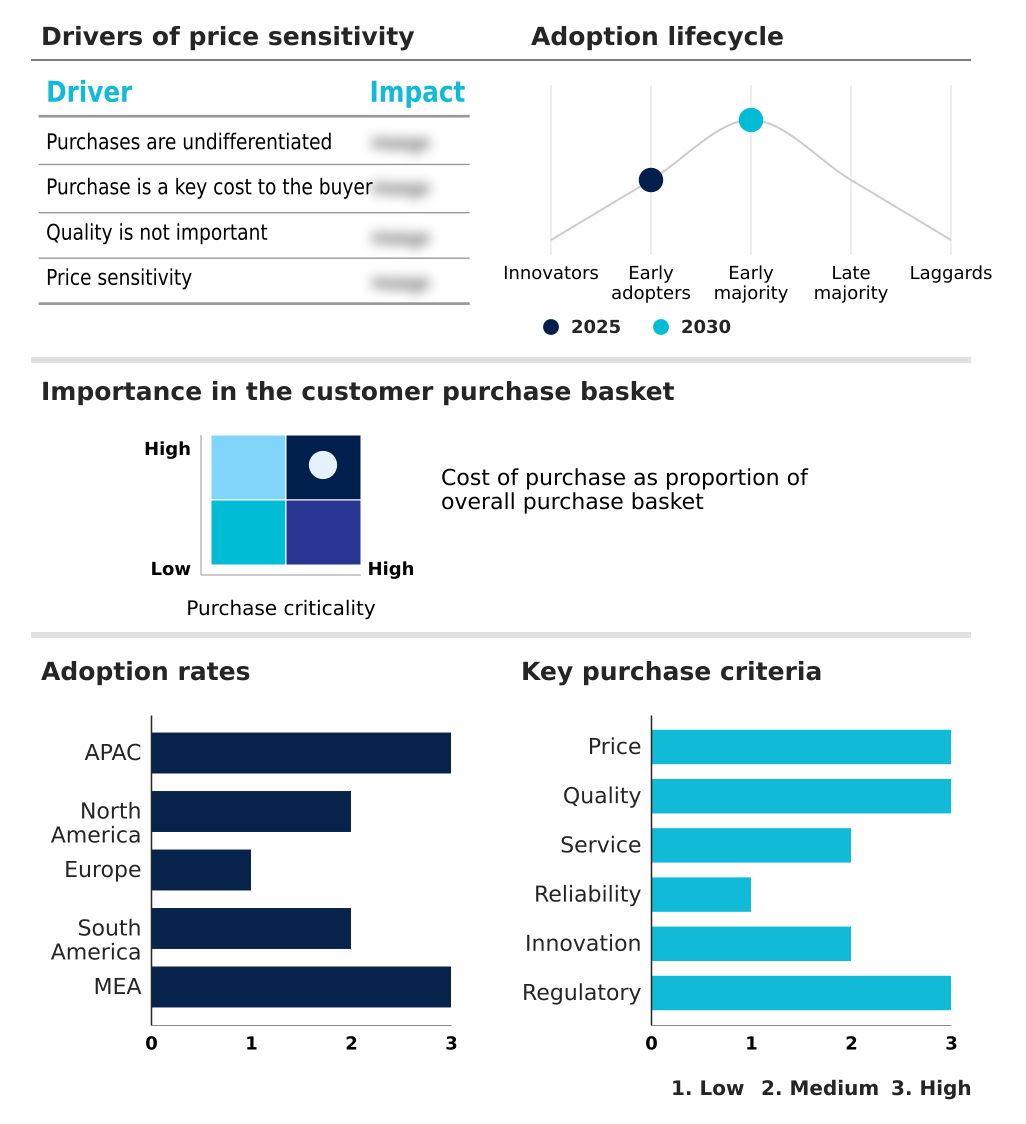
Customer Landscape of Dispersing Agents Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, dispersing agents market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Allnex GMBH - Provides advanced dispersing agents and superplasticizers designed to enhance flowability, optimize particle suspension, and improve stability across high-performance coatings, agrochemical formulations, and concrete admixtures.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Allnex GMBH
  • Altana AG
  • Arkema Group
  • Ashland Inc.
  • BASF SE
  • Borregaard ASA
  • Clariant International Ltd.
  • Croda International Plc
  • DIC Corp.
  • Dow Chemical Co.
  • Elementis Plc
  • Evonik Industries AG
  • Fine Organic Industries Ltd.
  • Ingevity Corp.
  • King Industries Inc.
  • Sika AG
  • Solvay SA
  • Synthomer Plc
  • The Lubrizol Corp.
  • Wacker Chemie AG

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Dispersing agents market

  • In the Specialty Chemicals industry, the widespread adoption of REACH compliance frameworks across European manufacturing has forced the elimination of hazardous surfactants, directly impacting Dispersing Agents demand by accelerating the formulation of biodegradable alternatives that maintain optimal colloidal suspension stability.
  • The transition toward zero-emission building certifications like LEED v4 has prompted a structural shift away from solvent-borne matrices, pulling demand for aqueous agents that meet strict volatile organic compound reduction targets without compromising fluid pumpability.
  • Advancements in precision dosing technologies have revolutionized paint mixing operations, enabling the creation of tailored blends that increase maximum pigment volume concentration by up to 15% to support high-solids applications.
  • The integration of precision agriculture technologies requires highly stable active ingredient delivery systems, creating a critical need for advanced stabilizers that prevent crystal growth inhibition during prolonged field application.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Dispersing Agents Market insights. See full methodology.

Market Scope
Page number 322
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 5.8%
Market growth 2026-2030 USD 2594.0 million
Market structure Fragmented
YoY growth 2025-2026(%) 5.5%
Key countries China, Japan, India, Indonesia, Australia, US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Brazil, Argentina, Chile, Saudi Arabia, South Africa, UAE, Turkey and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • Industrial formulators face mounting pressure to optimize material performance while adhering to rigorous ecological compliance targets. The Dispersing Agents Market is increasingly characterized by a strategic shift toward highly engineered steric mechanisms that prevent pigment agglomeration in complex liquid matrices.
  • This ongoing transition directly influences boardroom-level product strategy, as manufacturers must select additives that align with zero-emission mandates without sacrificing surface aesthetics. For example, adopting customized zwitterionic surfactants has enabled production facilities to achieve a 20% reduction in batch processing times, driving substantial operational cost savings.
  • Advanced formulation techniques leverage controlled radical polymerization to design specific molecular architectures that stabilize titanium dioxide efficiently. As product development teams navigate the complexities of mineral processing, integrating robust deflocculants becomes essential for maintaining low slurry viscosity. Furthermore, optimizing macromolecular synthesis processing ensures stable rheological profiles under extreme hydrostatic pressures.
  • These sophisticated innovations empower industrial chemical providers to maintain strict product consistency, enhance mechanical durability, and future-proof their commercial portfolios against evolving environmental regulations.

What are the Key Data Covered in this Dispersing Agents Market Research and Growth Report?

  • What is the expected growth of the Dispersing Agents Market between 2026 and 2030?

    • USD 2.59 billion, at a CAGR of 5.8%

  • What segmentation does the market report cover?

    • The report is segmented by Type (Anionic dispersants, Non-ionic dispersants, Cationic dispersants, and Amphoteric dispersants), End-user (Construction, Paints and coatings, Oil and gas, Detergents, and Others), Method (Water-based systems, Solvent-based systems, Powder-based systems, and High-solid systems) and Geography (APAC, North America, Europe, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • APAC, North America, Europe, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Rapid expansion of global construction and infrastructure sector, Stringent environmental regulations and transition to sustainable formulations

  • Who are the major players in the Dispersing Agents Market?

    • Allnex GMBH, Altana AG, Arkema Group, Ashland Inc., BASF SE, Borregaard ASA, Clariant International Ltd., Croda International Plc, DIC Corp., Dow Chemical Co., Elementis Plc, Evonik Industries AG, Fine Organic Industries Ltd., Ingevity Corp., King Industries Inc., Sika AG, Solvay SA, Synthomer Plc, The Lubrizol Corp. and Wacker Chemie AG

Market Research Insights

  • The operational landscape of the Dispersing Agents Market is evolving to meet advanced particulate stabilization requirements. Manufacturers rely on robust electrosteric barriers to maintain the integrity of synthetic resins during high-shear blending processes. Upgrading to advanced solvent-free dispersants has enabled industrial facilities to achieve a 20% reduction in processing cycle times.
  • Furthermore, optimizing cross-linking density in marine barriers yields a 30% improvement in long-term corrosion resistance. By incorporating highly efficient zinc oxide dispersion techniques, coating formulators reduce raw material waste by up to 15%, directly enhancing overall manufacturing profitability. These technical advancements ensure that complex slurry systems maintain exceptional colloidal stability across demanding industrial applications.

We can help! Our analysts can customize this dispersing agents market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Method
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Dispersing Agents Market 2020 - 2024

Historic Market Size - Data Table on Global Dispersing Agents Market 2020 - 2024 ($ million)

5.2 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.4 Method segment analysis 2020 - 2024

Historic Market Size - Method Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Dispersing Agents Market

6.2 Impact of Geopolitical Conflicts on Global Dispersing Agents Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Type

8.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

8.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

8.3 Anionic dispersants - Market size and forecast 2025-2030

Chart on Anionic dispersants - Market size and forecast 2025-2030 ($ million)
Data Table on Anionic dispersants - Market size and forecast 2025-2030 ($ million)
Chart on Anionic dispersants - Year-over-year growth 2025-2030 (%)
Data Table on Anionic dispersants - Year-over-year growth 2025-2030 (%)

8.4 Non-ionic dispersants - Market size and forecast 2025-2030

Chart on Non-ionic dispersants - Market size and forecast 2025-2030 ($ million)
Data Table on Non-ionic dispersants - Market size and forecast 2025-2030 ($ million)
Chart on Non-ionic dispersants - Year-over-year growth 2025-2030 (%)
Data Table on Non-ionic dispersants - Year-over-year growth 2025-2030 (%)

8.5 Cationic dispersants - Market size and forecast 2025-2030

Chart on Cationic dispersants - Market size and forecast 2025-2030 ($ million)
Data Table on Cationic dispersants - Market size and forecast 2025-2030 ($ million)
Chart on Cationic dispersants - Year-over-year growth 2025-2030 (%)
Data Table on Cationic dispersants - Year-over-year growth 2025-2030 (%)

8.6 Amphoteric dispersants - Market size and forecast 2025-2030

Chart on Amphoteric dispersants - Market size and forecast 2025-2030 ($ million)
Data Table on Amphoteric dispersants - Market size and forecast 2025-2030 ($ million)
Chart on Amphoteric dispersants - Year-over-year growth 2025-2030 (%)
Data Table on Amphoteric dispersants - Year-over-year growth 2025-2030 (%)

8.7 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 Construction - Market size and forecast 2025-2030

Chart on Construction - Market size and forecast 2025-2030 ($ million)
Data Table on Construction - Market size and forecast 2025-2030 ($ million)
Chart on Construction - Year-over-year growth 2025-2030 (%)
Data Table on Construction - Year-over-year growth 2025-2030 (%)

9.4 Paints and coatings - Market size and forecast 2025-2030

Chart on Paints and coatings - Market size and forecast 2025-2030 ($ million)
Data Table on Paints and coatings - Market size and forecast 2025-2030 ($ million)
Chart on Paints and coatings - Year-over-year growth 2025-2030 (%)
Data Table on Paints and coatings - Year-over-year growth 2025-2030 (%)

9.5 Oil and gas - Market size and forecast 2025-2030

Chart on Oil and gas - Market size and forecast 2025-2030 ($ million)
Data Table on Oil and gas - Market size and forecast 2025-2030 ($ million)
Chart on Oil and gas - Year-over-year growth 2025-2030 (%)
Data Table on Oil and gas - Year-over-year growth 2025-2030 (%)

9.6 Detergents - Market size and forecast 2025-2030

Chart on Detergents - Market size and forecast 2025-2030 ($ million)
Data Table on Detergents - Market size and forecast 2025-2030 ($ million)
Chart on Detergents - Year-over-year growth 2025-2030 (%)
Data Table on Detergents - Year-over-year growth 2025-2030 (%)

9.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.8 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

10. Market Segmentation by Method

10.1 Market segments

Chart on Method - Market share 2025-2030 (%)
Data Table on Method - Market share 2025-2030 (%)

10.2 Comparison by Method

Chart on Comparison by Method
Data Table on Comparison by Method

10.3 Water-based systems - Market size and forecast 2025-2030

Chart on Water-based systems - Market size and forecast 2025-2030 ($ million)
Data Table on Water-based systems - Market size and forecast 2025-2030 ($ million)
Chart on Water-based systems - Year-over-year growth 2025-2030 (%)
Data Table on Water-based systems - Year-over-year growth 2025-2030 (%)

10.4 Solvent-based systems - Market size and forecast 2025-2030

Chart on Solvent-based systems - Market size and forecast 2025-2030 ($ million)
Data Table on Solvent-based systems - Market size and forecast 2025-2030 ($ million)
Chart on Solvent-based systems - Year-over-year growth 2025-2030 (%)
Data Table on Solvent-based systems - Year-over-year growth 2025-2030 (%)

10.5 Powder-based systems - Market size and forecast 2025-2030

Chart on Powder-based systems - Market size and forecast 2025-2030 ($ million)
Data Table on Powder-based systems - Market size and forecast 2025-2030 ($ million)
Chart on Powder-based systems - Year-over-year growth 2025-2030 (%)
Data Table on Powder-based systems - Year-over-year growth 2025-2030 (%)

10.6 High-solid systems - Market size and forecast 2025-2030

Chart on High-solid systems - Market size and forecast 2025-2030 ($ million)
Data Table on High-solid systems - Market size and forecast 2025-2030 ($ million)
Chart on High-solid systems - Year-over-year growth 2025-2030 (%)
Data Table on High-solid systems - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by Method

Market opportunity by Method ($ million)
Data Table on Market opportunity by Method ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.4 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.3.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.4 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.4.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.4.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.4.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.5 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.5.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.5.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.5.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.5.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.5.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.5.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.3 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7.5 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Rapid expansion of global construction and infrastructure sector
Increasing demand for high-quality paints, coatings, and decorative inks
Technological advancements in agriculture and agrochemical industry

13.2 Market challenges

Stringent environmental regulations and transition to sustainable formulations
Volatility in pricing of raw materials and supply chain inconsistencies
Increasing technical complexity and performance requirements in advanced applications

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Global shift toward bio-based and sustainable dispersing solutions
Accelerating transition from solvent-borne to water-borne technologies
Integration of high-performance polymeric and multifunctional additives

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Arkema Group

Arkema Group - Overview
Arkema Group - Business segments
Arkema Group - Key news
Arkema Group - Key offerings
Arkema Group - Segment focus
SWOT

15.5 Ashland Inc.

Ashland Inc. - Overview
Ashland Inc. - Business segments
Ashland Inc. - Key news
Ashland Inc. - Key offerings
Ashland Inc. - Segment focus
SWOT

15.6 BASF SE

BASF SE - Overview
BASF SE - Business segments
BASF SE - Key news
BASF SE - Key offerings
BASF SE - Segment focus
SWOT

15.7 Clariant International Ltd.

Clariant International Ltd. - Overview
Clariant International Ltd. - Business segments
Clariant International Ltd. - Key offerings
Clariant International Ltd. - Segment focus
SWOT

15.8 Croda International Plc

Croda International Plc - Overview
Croda International Plc - Business segments
Croda International Plc - Key offerings
Croda International Plc - Segment focus
SWOT

15.9 DIC Corp.

DIC Corp. - Overview
DIC Corp. - Business segments
DIC Corp. - Key news
DIC Corp. - Key offerings
DIC Corp. - Segment focus
SWOT

15.10 Dow Chemical Co.

Dow Chemical Co. - Overview
Dow Chemical Co. - Business segments
Dow Chemical Co. - Key news
Dow Chemical Co. - Key offerings
Dow Chemical Co. - Segment focus
SWOT

15.11 Elementis Plc

Elementis Plc - Overview
Elementis Plc - Business segments
Elementis Plc - Key offerings
Elementis Plc - Segment focus
SWOT

15.12 Evonik Industries AG

Evonik Industries AG - Overview
Evonik Industries AG - Business segments
Evonik Industries AG - Key news
Evonik Industries AG - Key offerings
Evonik Industries AG - Segment focus
SWOT

15.13 Fine Organic Industries Ltd.

Fine Organic Industries Ltd. - Overview
Fine Organic Industries Ltd. - Product / Service
Fine Organic Industries Ltd. - Key offerings
SWOT

15.14 Ingevity Corp.

Ingevity Corp. - Overview
Ingevity Corp. - Business segments
Ingevity Corp. - Key offerings
Ingevity Corp. - Segment focus
SWOT

15.15 Sika AG

Sika AG - Overview
Sika AG - Business segments
Sika AG - Key news
Sika AG - Key offerings
Sika AG - Segment focus
SWOT

15.16 Solvay SA

Solvay SA - Overview
Solvay SA - Business segments
Solvay SA - Key offerings
Solvay SA - Segment focus
SWOT

15.17 Synthomer Plc

Synthomer Plc - Overview
Synthomer Plc - Business segments
Synthomer Plc - Key offerings
Synthomer Plc - Segment focus
SWOT

15.18 Wacker Chemie AG

Wacker Chemie AG - Overview
Wacker Chemie AG - Business segments
Wacker Chemie AG - Key offerings
Wacker Chemie AG - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Dispersing Agents market growth will increase by USD 2594.0 million during 2026-2030.

The Dispersing Agents market is expected to grow at a CAGR of 5.8% during 2026-2030.

Dispersing Agents market is segmented by Type (Anionic dispersants, Non-ionic dispersants, Cationic dispersants, Amphoteric dispersants) End-user (Construction, Paints and coatings, Oil and gas, Detergents, Others) Method (Water-based systems, Solvent-based systems, Powder-based systems, High-solid systems)

Allnex GMBH, Altana AG, Arkema Group, Ashland Inc., BASF SE, Borregaard ASA, Clariant International Ltd., Croda International Plc, DIC Corp., Dow Chemical Co., Elementis Plc, Evonik Industries AG, Fine Organic Industries Ltd., Ingevity Corp., King Industries Inc., Sika AG, Solvay SA, Synthomer Plc, The Lubrizol Corp., Wacker Chemie AG are a few of the key vendors in the Dispersing Agents market.

APAC will register the highest growth rate of 30% among the other regions. Therefore, the Dispersing Agents market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, Japan, India, Indonesia, Australia, US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Brazil, Argentina, Chile, Saudi Arabia, South Africa, UAE, Turkey, Israel

  • Rapid expansion of global construction and infrastructure sector is the driving factor this market.

The Dispersing Agents market vendors should focus on grabbing business opportunities from the Type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
