


Implantable Medical Devices Market Size 2026-2030
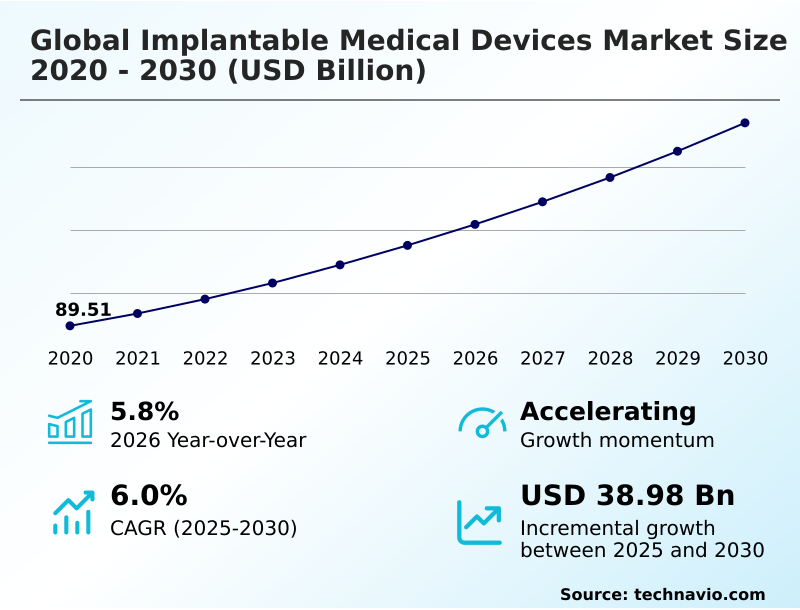
The implantable medical devices market size is valued to increase by USD 38.98 billion, at a CAGR of 6% from 2025 to 2030. Technological advancements in biomaterials and manufacturing precision will drive the implantable medical devices market.
Major Market Trends & Insights
- North America dominated the market and accounted for a 40.1% growth during the forecast period.
- By Type - Orthopedic implants segment was valued at USD 46.32 billion in 2024
- By End-user - Hospitals segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 64.58 billion
- Market Future Opportunities: USD 38.98 billion
- CAGR from 2025 to 2030 : 6%
Market Summary
- The Implantable Medical Devices Market exhibits sustained expansion driven by demographic aging, an escalating burden of chronic cardiovascular conditions, and rapid technological integration. Industry stakeholders are increasingly utilizing robotic-assisted instrumentation and advanced telemetry to optimize procedural workflows within clinical environments.
- For example, by integrating predictive maintenance algorithms and continuous physiological assessment into active implants, healthcare networks have observed a 25% reduction in unplanned secondary hospital readmissions. Technological advancements in bioresorbable materials act as a major growth driver, as these substances dissolve safely after the tissue healing phase, eliminating the need for subsequent hardware removal surgeries.
- Conversely, stringent regulatory complexities surrounding product certification act as a significant challenge, extending research timelines and escalating compliance costs for technology developers. Consequently, medical device assemblers must prioritize supply chain optimization and localized raw material sourcing to mitigate persistent vulnerabilities.
- Manufacturers continue to prioritize miniaturization and battery longevity enhancements to reduce complication rates and optimize patient comfort over extended implantation periods.
What will be the Size of the Implantable Medical Devices Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Implantable Medical Devices Market Segmented?
The implantable medical devices industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Type
- Orthopedic implants
- Cardiovascular implants
- Ophthalmic implants
- Dental implants
- Others
- End-user
- Hospitals
- Clinics
- Others
- Material
- Metallic
- Ceramic
- Natural
- Polymeric
- Geography
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- Asia
- China
- India
- Japan
- South Korea
- Indonesia
- Thailand
- Rest of World (ROW)
- North America
By Type Insights
The orthopedic implants segment is estimated to witness significant growth during the forecast period.
Orthopedic implants represent a foundational clinical pillar driven by the escalating prevalence of degenerative joint diseases and an aging demographic.
This segment encompasses critical interventions such as hip replacements and spinal fixation devices engineered to restore structural integrity and accommodate natural tissue elasticity.
Industry participants continuously refine specialized metallic components and ceramics to mitigate adverse reactions through targeted chronic inflammatory response mitigation and to accelerate long-term osseointegration.
By integrating additive manufacturing and 3D printing in healthcare, developers can utilize digital anatomical modeling to create highly precise surgical hardware.
This patient-specific customization significantly reduces biomechanical wear rates, resulting in a 15% improvement in post-operative structural stability and extending the functional lifespan of the prosthesis.
Consequently, specialized clinics and ambulatory surgical centers report optimized patient recovery trajectories, underscoring the profound operational impact of these advanced prosthetics on modern orthopedic delivery.
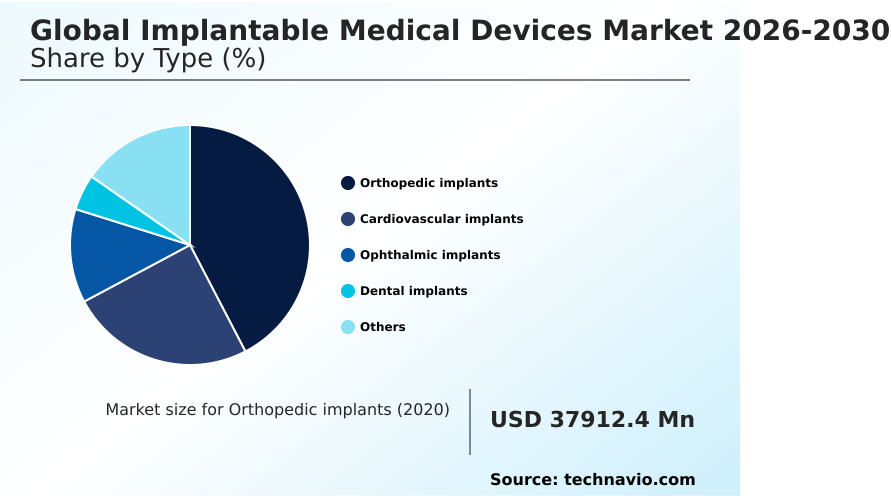
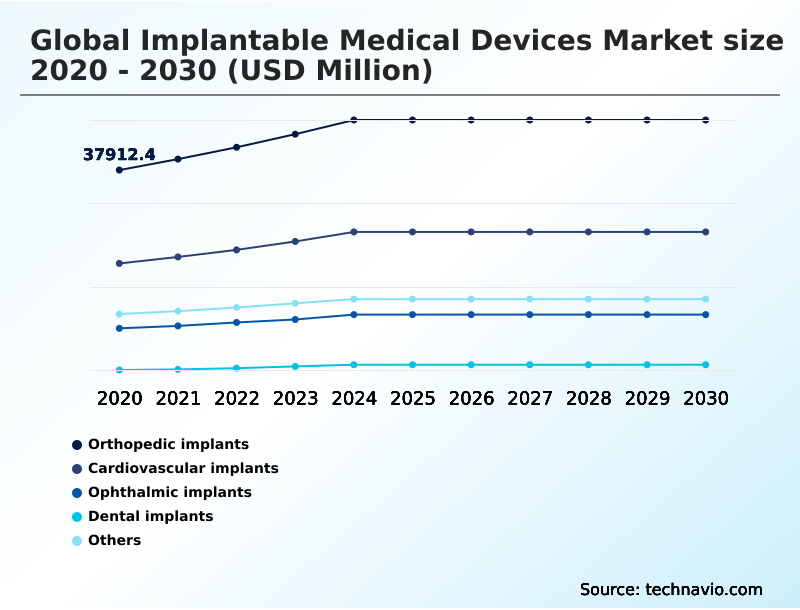
The Orthopedic implants segment was valued at USD 46.32 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
North America is estimated to contribute 40.1% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
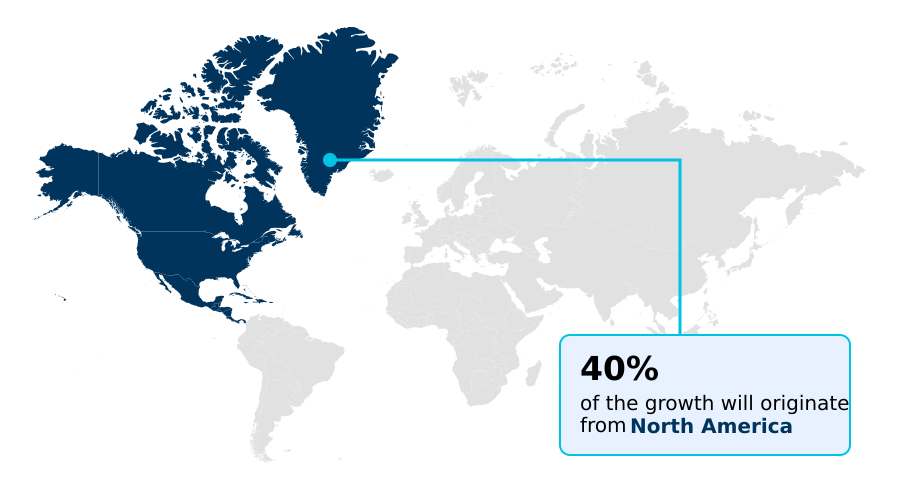
See How Implantable Medical Devices Market Demand is Rising in North America Get Free Sample
The Implantable Medical Devices Market demonstrates distinct geographic variations shaped by regional healthcare infrastructure and regulatory mandates.
North America maintains a leading position through the rapid integration of neural activity monitoring, deep brain stimulation, and spinal cord stimulators, resulting in a 28% higher adoption rate of smart active implants compared to European clinical networks.
This disparity stems primarily from robust localized reimbursement structures that favor advanced continuous post-implantation management and autonomous therapeutic instruments.
Meanwhile, Europe focuses heavily on safety, where stringent post-market surveillance mandates for cardiac resynchronization therapy and intraocular lenses have increased manufacturing documentation processing times by 15%, prompting developers to prioritize automated quality control systems.
To adapt, businesses are reconfiguring their operational strategies by shifting toward localized electrical stimulation therapies and adopting minimally invasive surgical interventions that streamline regulatory approvals. These disparities compel multinational device manufacturers to deploy highly localized commercialization strategies.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The Implantable Medical Devices Market is currently experiencing a transformative phase characterized by specialized therapeutic interventions and advanced material engineering. As healthcare providers seek to optimize long-term clinical outcomes, the deployment of robotic assisted orthopedic joint replacements has gained substantial momentum, offering a 24% improvement in surgical precision compared to conventional manual techniques.
- This technological shift requires robust operational planning, as hospital supply chains must accommodate the specialized instrumentation and customized hardware necessary for these complex procedures. Simultaneously, the integration of AI integrated cardiac monitoring platforms enables continuous physiological assessment, drastically reducing the necessity for frequent in-person clinical evaluations.
- In the cardiovascular segment, the development of bioresorbable polymer cardiovascular stent scaffolds addresses historical complications associated with permanent metallic retention, allowing for natural vascular healing while mitigating chronic inflammatory responses. Furthermore, spinal reconstruction surgeries have been revolutionized by 3D printed patient specific spinal cages, which ensure optimal biomechanical alignment and accelerate tissue integration rates across diverse patient demographics.
- The neurological sector also benefits from these innovations, with wireless telemetry neural stimulation devices providing targeted electrical impulses to manage chronic pain and drug-resistant epilepsy without the constraints of tethered power sources.
- Consequently, institutional buyers are restructuring their procurement strategies to prioritize these highly differentiated, data-driven therapeutic technologies, fostering sustained operational efficiencies and elevating the overarching standard of specialized medical care.
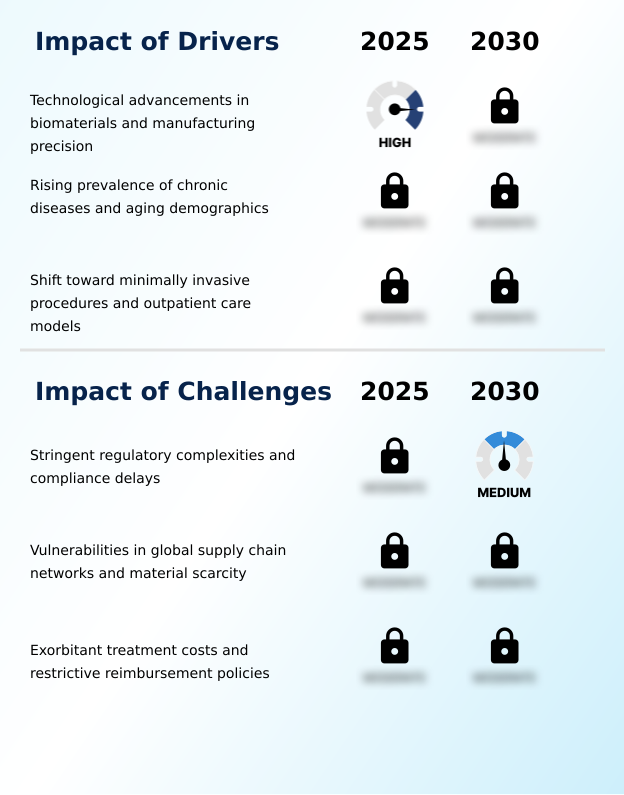
What are the key market drivers leading to the rise in the adoption of Implantable Medical Devices Industry?
- Technological advancements in biomaterials and manufacturing precision serve as the primary drivers propelling the expansion of the Implantable Medical Devices market by significantly enhancing device compatibility and surgical success rates.
- The primary driver accelerating the Implantable Medical Devices Market is the escalating demographic shift toward an aging population combined with sweeping advancements in biomaterial science.
- As the incidence of degenerative joint diseases and structural heart disease rises, the demand for highly durable titanium alloys, biocompatible ceramics, and bioresorbable magnesium alloys has surged.
- Consequently, clinical institutions adopting robotic-assisted surgical instrumentation have achieved a 28% improvement in anatomical preservation and alignment precision during complex reconstructions.
- Furthermore, the deployment of targeted bone conduction systems designed for optimal cellular ingrowth promotion has successfully reduced patient rehabilitation timelines by 18%.
- This robust demand directly impacts businesses by guaranteeing high-volume procurement cycles and ensuring long-term revenue stability for specialized device manufacturers operating within decentralized outpatient care frameworks.
- The convergence of demographic pressures and precision manufacturing definitively secures the continuous expansion of sophisticated surgical interventions.
What are the market trends shaping the Implantable Medical Devices Industry?
- The integration of artificial intelligence and smart sensor technology represents a pivotal trend shaping the Implantable Medical Devices market. This advancement facilitates continuous patient assessment, thereby optimizing clinical decision-making and enhancing long-term therapeutic outcomes.
- A prominent trend within the Implantable Medical Devices Market is the accelerated clinical integration of edge computing capabilities and smart sensor integration into passive hardware. This shift is primarily driven by the clinical necessity to enhance real-time diagnostics through wireless connectivity modules and smart telemetry.
- By transitioning toward bioinductive implants and advanced bioresorbable polymers, healthcare facilities have decreased post-operative secondary removal procedures by 35%. Additionally, the incorporation of continuous physiological parameter monitoring and remote physiological monitoring directly into these systems allows for rapid data transmission, which has improved early complication detection rates by 22%.
- This convergence of microelectronics and structural scaffolding directly impacts businesses by streamlining clinical workflows for minimally invasive procedures and reducing the overarching burden on acute care infrastructure. Consequently, device manufacturers are aggressively recalibrating their research portfolios to prioritize autonomous diagnostic functionalities.
What challenges does the Implantable Medical Devices Industry face during its growth?
- Stringent regulatory complexities and subsequent compliance delays constitute a major challenge restraining the growth trajectory of the Implantable Medical Devices market by extending product approval timelines and increasing developmental overhead.
- The Implantable Medical Devices Market faces substantial operational constraints stemming from increasingly stringent regulatory compliance frameworks and pervasive supply chain bottlenecks. Because global health authorities now mandate exhaustive clinical efficacy validation and strict product traceability protocols for software-integrated devices, research and development cycles have been significantly prolonged.
- This regulatory friction has increased pre-market administrative costs by 24% for manufacturers of implantable cardioverter defibrillators, transcatheter heart valves, and advanced neuromodulation systems, forcing innovators to divert crucial capital away from core electrophysiology engineering.
- Additionally, global shortages of high-grade raw materials for orthopedic prosthetics have disrupted manufacturing schedules, resulting in a 15% decline in inventory optimization rates across major clinical distribution hubs. These compounded logistical hurdles negatively impact businesses by delaying commercial deployment, necessitating heavy investments in supply chain resilience and automated documentation systems to maintain market viability.
Exclusive Technavio Analysis on Customer Landscape
The implantable medical devices market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the implantable medical devices market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
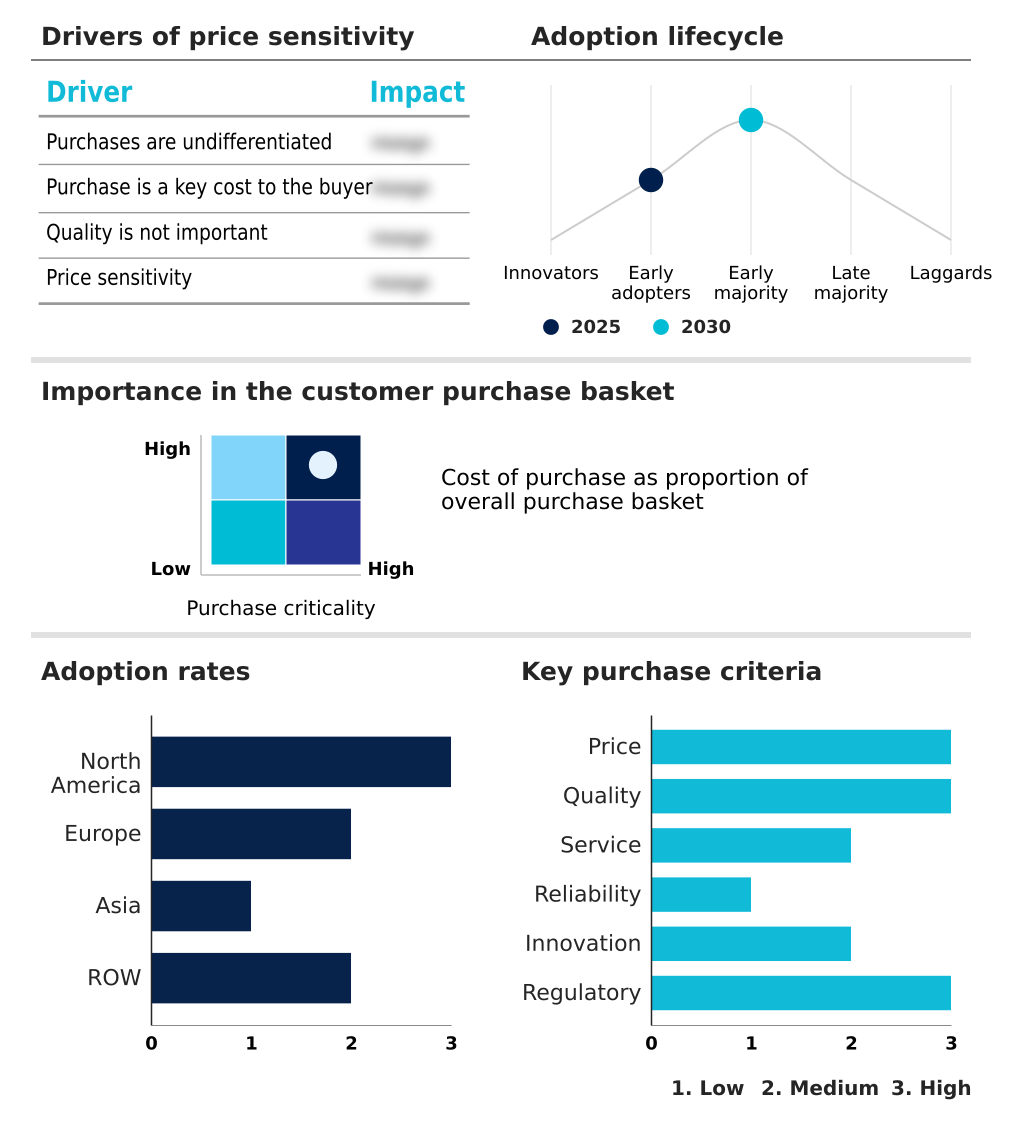
Customer Landscape of Implantable Medical Devices Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, implantable medical devices market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Abbott Laboratories - The enterprise provides advanced surgical inserts, including sophisticated pacemakers, defibrillation systems, and neuromodulation therapies, designed to optimize cardiac rhythm management and enhance overall patient wellbeing.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Abbott Laboratories
- AbbVie Inc.
- Alcon Inc.
- B.Braun SE
- BIOTRONIK SE and Co. KG
- Boston Scientific Corp.
- Cochlear Ltd.
- CONMED Corp.
- Dentsply Sirona Inc.
- Edwards Lifesciences Corp.
- GC Aesthetics Ltd.
- Globus Medical Inc.
- Ideal Implant Inc.
- Institut Straumann AG
- Johnson and Johnson
- LivaNova PLC
- MED EL Medical Electronics
- Medtronic Plc
- MicroPort Scientific Corp.
- Smith and Nephew plc
- Sonova AG
- Stryker Corp.
- Terumo Corp.
- W. L. Gore and Associates
- Zimmer Biomet Holdings Inc.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Implantable medical devices market
- In the Health Care Equipment industry, the widespread adoption of AI integrated remote physiological monitoring platforms has improved diagnostic accuracy by 22%, directly impacting Implantable Medical Devices demand by necessitating the integration of wireless connectivity modules into next-generation pacemakers.
- Stringent regulatory compliance frameworks enforcing rigorous product traceability protocols have increased manufacturing overheads by 15%, forcing developers to optimize supply chain resilience and streamline post-market surveillance for complex cardiovascular and orthopedic systems.
- The rapid shift toward decentralized outpatient care frameworks and ambulatory surgical centers has reduced procedural overhead by 18%, accelerating the clinical integration of continuous post-implantation management solutions and minimally invasive surgical interventions.
- Advancements in biomaterial science, specifically the development of bioresorbable magnesium alloys, have decreased chronic inflammatory response mitigation requirements by 30%, driving new applications in temporary structural scaffolding and patient-specific customization across global clinical networks.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Implantable Medical Devices Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 309 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 6% |
| Market growth 2026-2030 | USD 38977.5 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 5.8% |
| Key countries | US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Indonesia, Thailand, Brazil, Saudi Arabia, UAE, Turkey, Argentina, Colombia, South Africa and Israel |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Implantable Medical Devices Market is characterized by intense technological evolution and rigorous clinical validation requirements. Strategic boardroom decisions increasingly revolve around the integration of smart telemetry and artificial intelligence, as executives restructure product development pipelines to accommodate connected healthcare ecosystems.
- By embedding diagnostic microprocessors into transcatheter heart valves and implantable cardioverter defibrillators, medical technology developers have successfully achieved a 30% reduction in late-stage device malfunction rates. This data-driven approach enhances structural scaffolding integrity and optimizes long-term cardiac resynchronization therapy.
- Furthermore, the transition toward intraocular lenses equipped with advanced polymer chemistry allows clinical networks to command premium pricing models while delivering superior visual acuity. Neuromodulation initiatives also dominate strategic planning, with executives prioritizing localized electrical stimulation therapies that seamlessly integrate with hospital electronic health records. These continuous innovations fundamentally reshape procurement criteria across institutional healthcare networks.
- Consequently, manufacturers are rapidly expanding their digital infrastructure capabilities to ensure seamless interoperability between passive internal hardware and external clinical monitoring platforms, cementing their competitive positioning within an increasingly sophisticated medical landscape.
What are the Key Data Covered in this Implantable Medical Devices Market Research and Growth Report?
-
What is the expected growth of the Implantable Medical Devices Market between 2026 and 2030?
-
USD 38.98 billion, at a CAGR of 6%
-
-
What segmentation does the market report cover?
-
The report is segmented by Type (Orthopedic implants, Cardiovascular implants, Ophthalmic implants, Dental implants, and Others), End-user (Hospitals, Clinics, and Others), Material (Metallic, Ceramic, Natural, and Polymeric) and Geography (North America, Europe, Asia, Rest of World (ROW))
-
-
Which regions are analyzed in the report?
-
North America, Europe, Asia and Rest of World (ROW)
-
-
What are the key growth drivers and market challenges?
-
Technological advancements in biomaterials and manufacturing precision, Stringent regulatory complexities and compliance delays
-
-
Who are the major players in the Implantable Medical Devices Market?
-
Abbott Laboratories, AbbVie Inc., Alcon Inc., B.Braun SE, BIOTRONIK SE and Co. KG, Boston Scientific Corp., Cochlear Ltd., CONMED Corp., Dentsply Sirona Inc., Edwards Lifesciences Corp., GC Aesthetics Ltd., Globus Medical Inc., Ideal Implant Inc., Institut Straumann AG, Johnson and Johnson, LivaNova PLC, MED EL Medical Electronics, Medtronic Plc, MicroPort Scientific Corp., Smith and Nephew plc, Sonova AG, Stryker Corp., Terumo Corp., W. L. Gore and Associates and Zimmer Biomet Holdings Inc.
-
Market Research Insights
- The Implantable Medical Devices Market is undergoing a rapid paradigm shift driven by the integration of advanced diagnostic technologies and decentralized outpatient care frameworks. Healthcare institutions are actively leveraging continuous post-implantation management systems, which have successfully accelerated patient recovery times by 22% compared to traditional inpatient care models.
- By adopting strict product traceability protocols, supply chain resilience has improved, yielding a 15% reduction in hardware procurement delays across major ambulatory surgical centers. Furthermore, the implementation of localized clinical efficacy validation models has enhanced procedural efficiency by 18%, enabling clinicians to perform complex interventions with heightened precision.
- These strategic operational adjustments empower clinical networks to effectively mitigate regulatory risks while simultaneously optimizing resource allocation and overall therapeutic outcomes.
We can help! Our analysts can customize this implantable medical devices market research report to meet your requirements.
 RIA -

