Ambulatory Infusion Center Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, South Africa, and UAE), Rest of World (ROW)

Ambulatory Infusion Center Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, South Africa, and UAE), Rest of World (ROW)

Published: Oct 2026 303 Pages SKU: IRTNTR80272

Market Overview at a Glance

$16.09 B
Market Opportunity
5.6%
CAGR 2025 - 2030
49.8%
North America Growth
$22.10 B
Independent centers segment 2024

Ambulatory Infusion Center Market Size 2026-2030

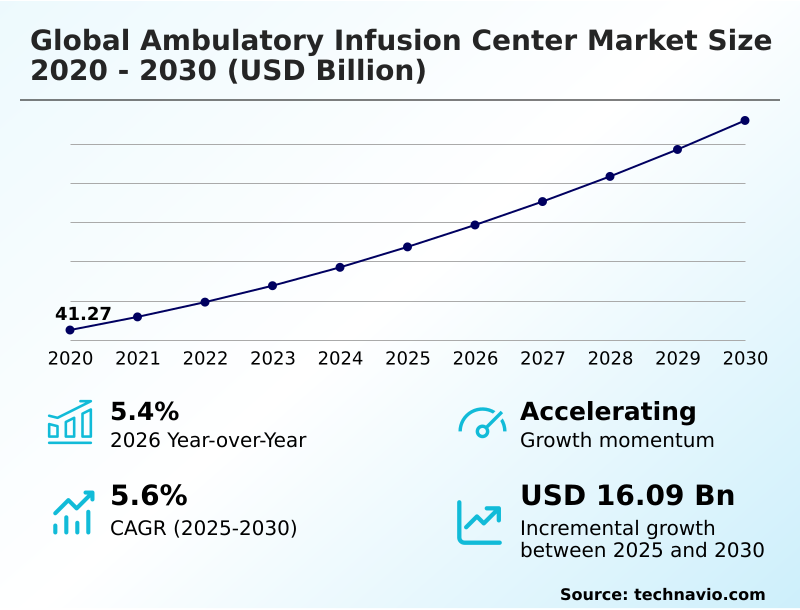
The ambulatory infusion center market size is valued to increase by USD 16.09 billion, at a CAGR of 5.6% from 2025 to 2030. Rising prevalence of chronic diseases and complex conditions will drive the ambulatory infusion center market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 49.8% growth during the forecast period.
  • By Type - Independent centers segment was valued at USD 22.10 billion in 2024
  • By Indication - Oncology segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 26.66 billion
  • Market Future Opportunities: USD 16.09 billion
  • CAGR from 2025 to 2030 : 5.6%

Market Summary

  • Ambulatory Infusion Center operations represent a critical shift in modern healthcare delivery, transitioning complex intravenous therapies from high-cost hospital wards to dedicated, specialized outpatient facilities. This structural realignment optimizes clinical resource utilization while providing a highly controlled environment for administering biologic and oncological treatments.
  • In a typical supply chain optimization scenario, independent clinic networks utilize predictive inventory software to manage temperature-sensitive biologic medications, ensuring precise stock levels and minimizing drug wastage. Facilities implementing these automated inventory models have achieved a 22% reduction in pharmaceutical holding costs compared to legacy manual tracking methods.
  • The escalating prevalence of chronic autoimmune and neurological conditions drives the continuous expansion of these decentralized care sites, as patients require lifelong, recurring therapeutic interventions. Conversely, navigating highly fragmented and restrictive insurance reimbursement frameworks poses a severe operational challenge, often delaying treatment authorizations and compressing facility profit margins.
  • Advanced smart infusion technologies and rigorous safety protocols ensure that these outpatient centers maintain clinical parity with acute care hospitals.

What will be the Size of the Ambulatory Infusion Center Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Ambulatory Infusion Center Market Segmented?

The ambulatory infusion center industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Type
    • Independent centers
    • Hospitals
    • Home healthcare
  • Indication
    • Oncology
    • Autoimmune disorders
    • Infectious diseases
    • Neurological disorders
    • Chronic pain conditions
  • Therapy
    • Immunoglobulin therapy
    • Anti-infective therapy
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • China
      • Japan
      • India
      • South Korea
      • Taiwan
      • Singapore
    • Rest of World (ROW)

By Type Insights

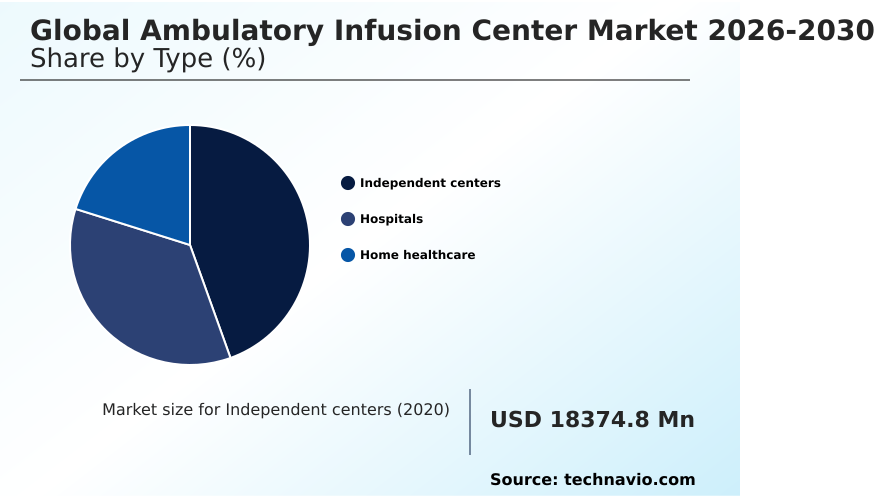
The independent centers segment is estimated to witness significant growth during the forecast period.

Independent centers operate autonomously from large hospital networks, providing a highly specialized and cost-effective environment for complex therapeutic administration. These dedicated facilities focus extensively on complex regimens such as outpatient parenteral antimicrobial therapy and subcutaneous immunoglobulin treatments.

By streamlining administrative workflows with advanced ambulatory scheduling algorithms, independent clinics have improved patient chair utilization by 24% compared to hospital outpatient departments.

The effective management of peripherally inserted central catheters and rigorous cytotoxic medication handling protocols ensure that clinical safety matches institutional standards. Seamless specialized pharmacy integration enables these centers to manage expensive biologic inventories efficiently, reducing operational delays.

Furthermore, the incorporation of telehealth consultation interfaces allows continuous physician oversight without requiring on-site presence. This operational autonomy reduces overhead expenses and significantly enhances the overall patient experience.
Get Free Sample

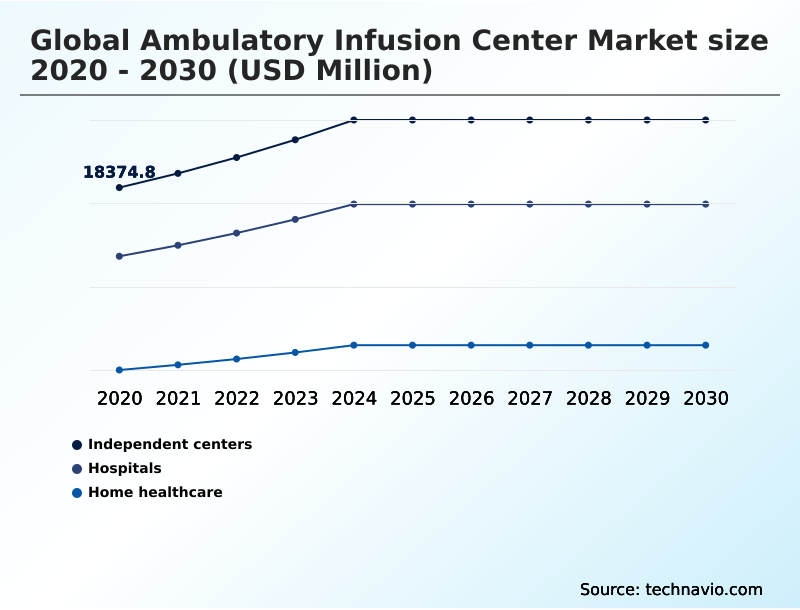
The Independent centers segment was valued at USD 22.10 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 49.8% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
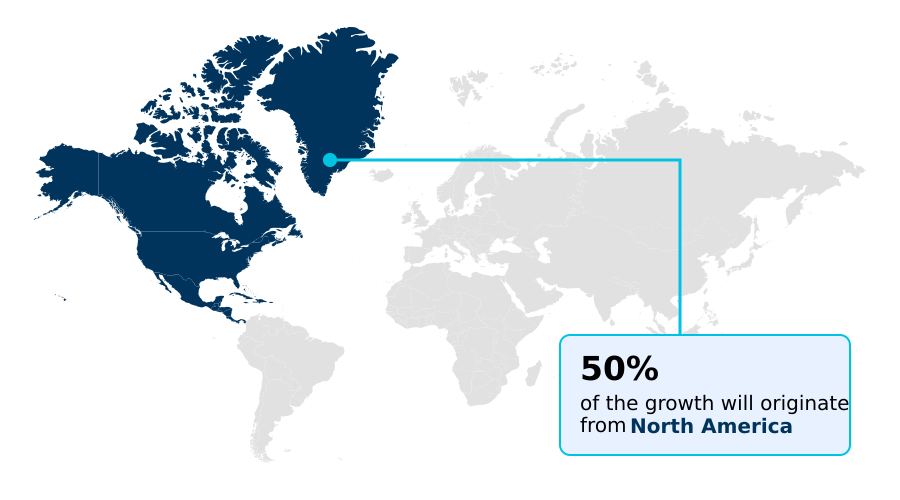
See How Ambulatory Infusion Center Market Demand is Rising in North America Get Free Sample

Regional variations in healthcare infrastructure dictate the adoption and operational scale of Ambulatory Infusion Center facilities across global territories. North America leads the transition, where robust multidisciplinary clinical coordination allows facilities to handle complex targeted monoclonal antibodies efficiently.

In contrast, Europe is rapidly expanding its outpatient capabilities for neurological disease modifying therapies, achieving a 20% higher patient throughput than traditional hospital wards.

Asian territories are investing heavily in specialized oncology nursing to support the growing demand for safe immunotherapy administration and immune checkpoint inhibitors.

Advanced therapeutic drug monitoring and continuous hemodynamic parameter tracking are increasingly standardized in developed regions to ensure safe infusion rate titration.

These regional adaptations directly influence patient adherence tracking, improving long-term treatment compliance by 18% in decentralized settings compared to centralized acute care hospitals.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The operational landscape of outpatient care is evolving rapidly as healthcare systems prioritize the decentralization of complex therapeutic interventions. Effective outpatient biologic infusion care coordination has become essential for managing patients with severe chronic conditions, ensuring that treatment regimens are seamlessly transferred from acute settings to specialized clinics.
  • To support this transition, facilities are heavily investing in smart infusion pump workflow integration, which connects administration devices directly to electronic health records. This digital connectivity allows clinicians to monitor real-time delivery metrics, reducing adverse events by 18% compared to non-integrated systems.
  • Concurrently, ambulatory oncology chemotherapy administration is expanding, providing cancer patients with a safer, more comfortable environment while alleviating severe capacity bottlenecks in hospital oncology wards. The success of these treatments relies heavily on rigorous safety protocols and specialized nursing expertise.
  • Furthermore, freestanding specialty infusion center operations are optimizing their supply chains and scheduling frameworks to accommodate higher patient volumes without escalating overhead expenses. By refining these logistical processes, independent clinics maintain a highly efficient therapeutic throughput.
  • Additionally, advancements in subcutaneous immunoglobulin therapy patient monitoring empower individuals to receive critical immune support with enhanced oversight, utilizing remote telemetry to track physiological responses. This comprehensive approach to outpatient management significantly improves clinical safety, operational agility, and long-term therapeutic adherence across the industry.
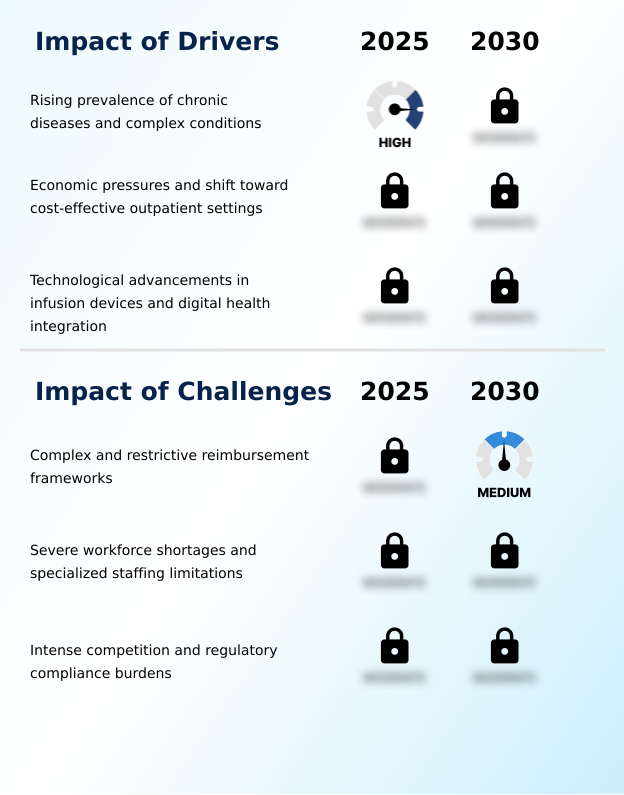
What are the key market drivers leading to the rise in the adoption of Ambulatory Infusion Center Industry?

  • The rising prevalence of chronic diseases and complex conditions serves as the primary catalyst propelling market expansion.

  • The rising clinical demand for specialized treatments outside traditional hospital walls is accelerating the expansion of dedicated Ambulatory Infusion Center infrastructure. An increasing global burden of complex conditions requires continuous chronic disease management through precise intravenous therapy delivery.
  • Facilities are standardizing biologic administration protocols to accommodate the surge in patients requiring lifelong biologic maintenance treatments. By transitioning stable patients to standalone chemotherapy infusion suites, healthcare systems achieve critical hospital capacity optimization, reducing inpatient bed occupancy by 18%.
  • Advancements in vascular access devices enable safer and more comfortable delivery of complex immunoglobulin formulations. This shift directly supports value based care alignment by lowering overall treatment costs while maintaining rigorous clinical standards.
  • Furthermore, strategic infusion site of care optimization allows providers to increase daily patient throughput by 25%, ensuring timely access to necessary therapies.

What are the market trends shaping the Ambulatory Infusion Center Industry?

  • The expansion of dedicated specialty infusion networks and decentralized outpatient care models represents a defining trend reshaping the market.

  • Ambulatory Infusion Center operations are rapidly shifting toward highly digitalized environments that integrate advanced technology to monitor and deliver complex medications. The implementation of smart infusion pumps alongside real time device telemetry enables clinical teams to track treatment progress continuously.
  • As decentralized therapeutic delivery expands, facilities are deploying automated compounding robotics to prepare medications, which has improved dosing precision by 22%. The integration of biosensor wearables facilitates continuous remote patient monitoring, reducing the incidence of unobserved adverse reactions. Advancements in electronic health records interoperability allow for seamless data sharing between acute hospitals and independent outpatient care models.
  • This transition significantly enhances clinical workflow efficiency and optimizes predictive inventory analytics, lowering medication wastage by 14%. Ultimately, these digital solutions empower specialized facilities to handle greater patient volumes without compromising safety or care quality.

What challenges does the Ambulatory Infusion Center Industry face during its growth?

  • Complex and restrictive reimbursement frameworks constitute a significant operational barrier constraining industry growth.

  • Strict regulatory mandates and the high technical complexity of specialized care present significant operational hurdles for Ambulatory Infusion Center management. Maintaining compliance with rigorous sterile compounding regulations requires substantial capital investment in cleanroom infrastructure and staff training. Facilities must strictly enforce aseptic preparation protocols to support nosocomial infection mitigation and prevent severe catheter related bloodstream infections.
  • Navigating cold chain pharmaceutical logistics for temperature-sensitive biologics increases overhead costs by up to 15%, complicating supply chain reliability. Additionally, the clinical necessity for advanced dose error reduction systems and robust pharmacovigilance systems places a heavy administrative burden on independent clinics.
  • Effective hypersensitivity reaction management and adverse drug event prevention require highly specialized nursing personnel, who are currently in short supply. Meeting the rigorous demands of emerging antimicrobial stewardship programs further challenges facility operators attempting to scale their services.

Exclusive Technavio Analysis on Customer Landscape

The ambulatory infusion center market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the ambulatory infusion center market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
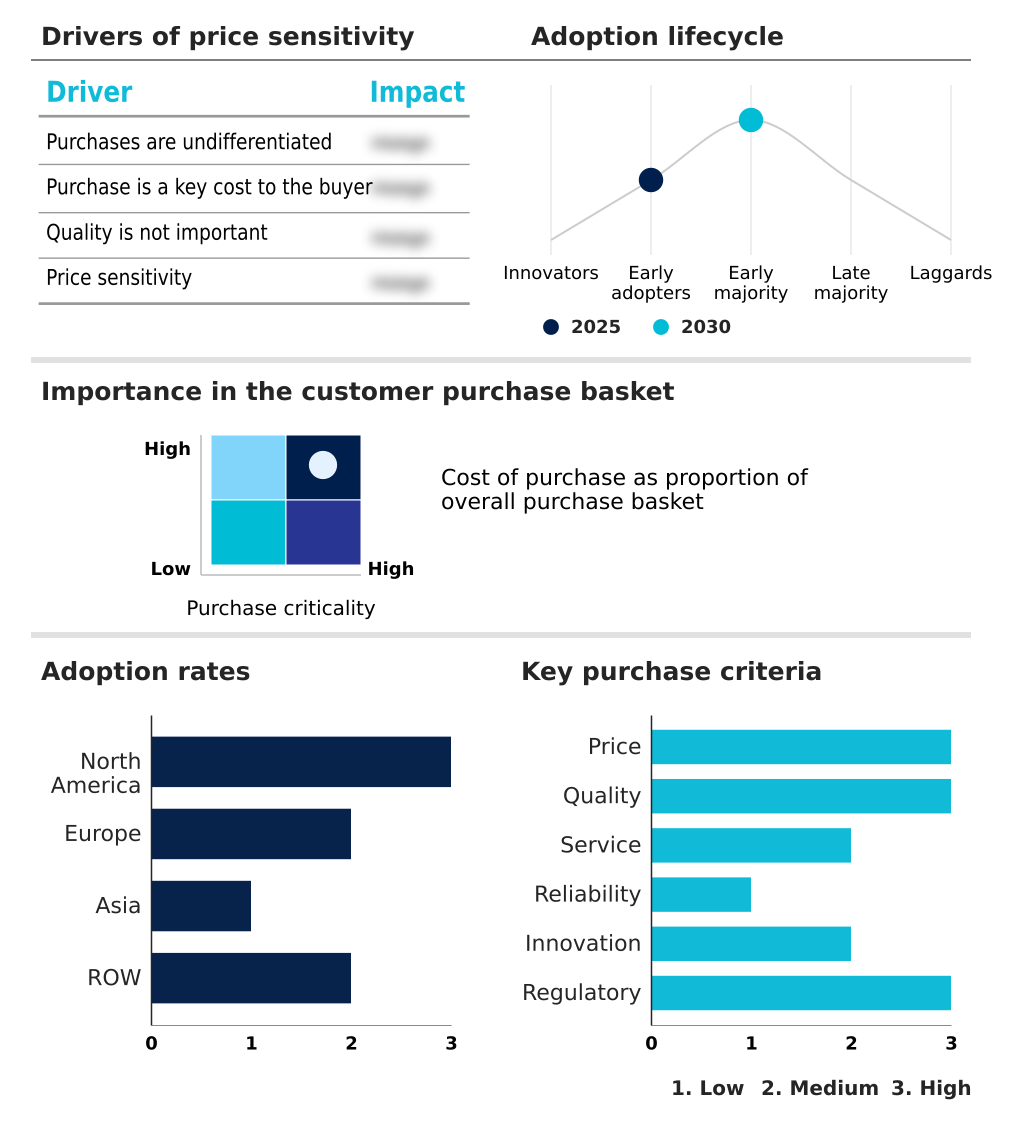
Customer Landscape of Ambulatory Infusion Center Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, ambulatory infusion center market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Cedars Sinai Health System - The organization provides specialized outpatient infusion care, including biologic therapies and chronic disease management, focusing on clinical excellence and patient comfort in dedicated ambulatory settings.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Cedars Sinai Health System
  • Community Health Systems Inc.
  • CVS Health Corp.
  • HCA Healthcare Inc.
  • Infusion for Health
  • IVX Health
  • Mayo Clinic
  • McKesson Corp.
  • Metro Infusion Center
  • Northwestern Medicine
  • Option Care Health Inc.
  • Sutter Health
  • Tenet Healthcare Corp.
  • The Cigna Group
  • The Cleveland Clinic Foundation
  • The Johns Hopkins Health System
  • United Health Group Inc.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Ambulatory infusion center market

  • In the Health Care Equipment industry, the transition toward decentralized digital health ecosystems has accelerated the deployment of interoperable electronic health records, directly impacting Ambulatory Infusion Center demand by enabling seamless care coordination between acute hospitals and remote clinics.
  • The standardization of rigorous cleanroom compliance frameworks for sterile medical device manufacturing has increased the operational requirements for medication preparation, directly impacting Ambulatory Infusion Center demand by driving investments in automated compounding technologies.
  • Advancements in closed-system transfer devices for hazardous drug handling have significantly reduced occupational exposure risks, directly impacting Ambulatory Infusion Center demand by allowing freestanding clinics to safely administer complex oncology regimens.
  • The integration of predictive analytics and cloud-based telemetry into connected medical devices has enhanced remote patient monitoring capabilities, directly impacting Ambulatory Infusion Center demand by improving the safety profile of multi-hour outpatient therapies.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Ambulatory Infusion Center Market insights. See full methodology.

Market Scope
Page number 303
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 5.6%
Market growth 2026-2030 USD 16086.3 million
Market structure Fragmented
YoY growth 2025-2026(%) 5.4%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Taiwan, Singapore, Brazil, Saudi Arabia, South Africa, Argentina, UAE, New Zealand, Chile and Egypt
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • Ambulatory Infusion Center networks operate as highly specialized clinical environments designed to manage the administration of complex intravenous therapies outside of traditional hospital settings. The integration of smart infusion pumps and continuous therapeutic drug monitoring ensures that high-risk medications are delivered with exceptional precision.
  • Facilities investing in advanced vascular access devices have reported a 20% decrease in catheter-related complications, directly enhancing patient safety and operational throughput. Strict adherence to aseptic preparation protocols remains critical for maintaining sterility and preventing nosocomial infections during drug compounding.
  • Strategic decision-making heavily prioritizes the optimization of cold chain pharmaceutical logistics, ensuring that temperature-sensitive biologics remain viable from the manufacturer to the patient chair. The deployment of comprehensive pharmacovigilance systems and automated dose error reduction systems allows independent clinics to mitigate liability and streamline regulatory compliance. Driven by specialized oncology nursing teams, these decentralized facilities manage high patient volumes efficiently.
  • This operational model continuously refines clinical workflows, balancing rigorous healthcare safety mandates with the need for cost-effective, patient-centric therapeutic delivery.

What are the Key Data Covered in this Ambulatory Infusion Center Market Research and Growth Report?

  • What is the expected growth of the Ambulatory Infusion Center Market between 2026 and 2030?

    • USD 16.09 billion, at a CAGR of 5.6%

  • What segmentation does the market report cover?

    • The report is segmented by Type (Independent centers, Hospitals, and Home healthcare), Indication (Oncology, Autoimmune disorders, Infectious diseases, Neurological disorders, and Chronic pain conditions), Therapy (Immunoglobulin therapy, Anti-infective therapy, and Others) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Rising prevalence of chronic diseases and complex conditions, Complex and restrictive reimbursement frameworks

  • Who are the major players in the Ambulatory Infusion Center Market?

    • Cedars Sinai Health System, Community Health Systems Inc., CVS Health Corp., HCA Healthcare Inc., Infusion for Health, IVX Health, Mayo Clinic, McKesson Corp., Metro Infusion Center, Northwestern Medicine, Option Care Health Inc., Sutter Health, Tenet Healthcare Corp., The Cigna Group, The Cleveland Clinic Foundation, The Johns Hopkins Health System and United Health Group Inc.

Market Research Insights

  • The Ambulatory Infusion Center landscape is transforming how complex therapeutics are administered by prioritizing decentralized therapeutic delivery. Healthcare networks are rapidly adopting outpatient care models to reduce institutional overhead and improve clinical workflow efficiency. Facilities transitioning from manual to automated ambulatory scheduling algorithms have increased patient chair utilization by 25%.
  • Additionally, robust specialized pharmacy integration has lowered medication dispensing errors by 18%, significantly enhancing patient safety. By focusing on chronic disease management in dedicated settings, these centers offer a streamlined alternative to crowded hospitals. This operational shift directly aligns with value-based care initiatives, delivering superior clinical outcomes while substantially lowering the overall cost of continuous therapeutic interventions.

We can help! Our analysts can customize this ambulatory infusion center market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Indication
Executive Summary - Chart on Market Segmentation by Therapy
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Ambulatory Infusion Center Market 2020 - 2024

Historic Market Size - Data Table on Global Ambulatory Infusion Center Market 2020 - 2024 ($ million)

5.2 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.3 Indication segment analysis 2020 - 2024

Historic Market Size - Indication Segment 2020 - 2024 ($ million)

5.4 Therapy segment analysis 2020 - 2024

Historic Market Size - Therapy Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global ambulatory infusion center market

6.2 Impact of geopolitical conflicts on global ambulatory infusion center market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Type

8.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

8.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

8.3 Independent centers - Market size and forecast 2025-2030

Chart on Independent centers - Market size and forecast 2025-2030 ($ million)
Data Table on Independent centers - Market size and forecast 2025-2030 ($ million)
Chart on Independent centers - Year-over-year growth 2025-2030 (%)
Data Table on Independent centers - Year-over-year growth 2025-2030 (%)

8.4 Hospitals - Market size and forecast 2025-2030

Chart on Hospitals - Market size and forecast 2025-2030 ($ million)
Data Table on Hospitals - Market size and forecast 2025-2030 ($ million)
Chart on Hospitals - Year-over-year growth 2025-2030 (%)
Data Table on Hospitals - Year-over-year growth 2025-2030 (%)

8.5 Home healthcare - Market size and forecast 2025-2030

Chart on Home healthcare - Market size and forecast 2025-2030 ($ million)
Data Table on Home healthcare - Market size and forecast 2025-2030 ($ million)
Chart on Home healthcare - Year-over-year growth 2025-2030 (%)
Data Table on Home healthcare - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

9. Market Segmentation by Indication

9.1 Market segments

Chart on Indication - Market share 2025-2030 (%)
Data Table on Indication - Market share 2025-2030 (%)

9.2 Comparison by Indication

Chart on Comparison by Indication
Data Table on Comparison by Indication

9.3 Oncology - Market size and forecast 2025-2030

Chart on Oncology - Market size and forecast 2025-2030 ($ million)
Data Table on Oncology - Market size and forecast 2025-2030 ($ million)
Chart on Oncology - Year-over-year growth 2025-2030 (%)
Data Table on Oncology - Year-over-year growth 2025-2030 (%)

9.4 Autoimmune disorders - Market size and forecast 2025-2030

Chart on Autoimmune disorders - Market size and forecast 2025-2030 ($ million)
Data Table on Autoimmune disorders - Market size and forecast 2025-2030 ($ million)
Chart on Autoimmune disorders - Year-over-year growth 2025-2030 (%)
Data Table on Autoimmune disorders - Year-over-year growth 2025-2030 (%)

9.5 Infectious diseases - Market size and forecast 2025-2030

Chart on Infectious diseases - Market size and forecast 2025-2030 ($ million)
Data Table on Infectious diseases - Market size and forecast 2025-2030 ($ million)
Chart on Infectious diseases - Year-over-year growth 2025-2030 (%)
Data Table on Infectious diseases - Year-over-year growth 2025-2030 (%)

9.6 Neurological disorders - Market size and forecast 2025-2030

Chart on Neurological disorders - Market size and forecast 2025-2030 ($ million)
Data Table on Neurological disorders - Market size and forecast 2025-2030 ($ million)
Chart on Neurological disorders - Year-over-year growth 2025-2030 (%)
Data Table on Neurological disorders - Year-over-year growth 2025-2030 (%)

9.7 Chronic pain conditions - Market size and forecast 2025-2030

Chart on Chronic pain conditions - Market size and forecast 2025-2030 ($ million)
Data Table on Chronic pain conditions - Market size and forecast 2025-2030 ($ million)
Chart on Chronic pain conditions - Year-over-year growth 2025-2030 (%)
Data Table on Chronic pain conditions - Year-over-year growth 2025-2030 (%)

9.8 Market opportunity by Indication

Market opportunity by Indication ($ million)
Data Table on Market opportunity by Indication ($ million)

10. Market Segmentation by Therapy

10.1 Market segments

Chart on Therapy - Market share 2025-2030 (%)
Data Table on Therapy - Market share 2025-2030 (%)

10.2 Comparison by Therapy

Chart on Comparison by Therapy
Data Table on Comparison by Therapy

10.3 Immunoglobulin therapy - Market size and forecast 2025-2030

Chart on Immunoglobulin therapy - Market size and forecast 2025-2030 ($ million)
Data Table on Immunoglobulin therapy - Market size and forecast 2025-2030 ($ million)
Chart on Immunoglobulin therapy - Year-over-year growth 2025-2030 (%)
Data Table on Immunoglobulin therapy - Year-over-year growth 2025-2030 (%)

10.4 Anti-infective therapy - Market size and forecast 2025-2030

Chart on Anti-infective therapy - Market size and forecast 2025-2030 ($ million)
Data Table on Anti-infective therapy - Market size and forecast 2025-2030 ($ million)
Chart on Anti-infective therapy - Year-over-year growth 2025-2030 (%)
Data Table on Anti-infective therapy - Year-over-year growth 2025-2030 (%)

10.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Therapy

Market opportunity by Therapy ($ million)
Data Table on Market opportunity by Therapy ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ million)
Data Table on Asia - Market size and forecast 2025-2030 ($ million)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Taiwan - Market size and forecast 2025-2030

Chart on Taiwan - Market size and forecast 2025-2030 ($ million)
Data Table on Taiwan - Market size and forecast 2025-2030 ($ million)
Chart on Taiwan - Year-over-year growth 2025-2030 (%)
Data Table on Taiwan - Year-over-year growth 2025-2030 (%)

12.5.6 Singapore - Market size and forecast 2025-2030

Chart on Singapore - Market size and forecast 2025-2030 ($ million)
Data Table on Singapore - Market size and forecast 2025-2030 ($ million)
Chart on Singapore - Year-over-year growth 2025-2030 (%)
Data Table on Singapore - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.5 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.6 New Zealand - Market size and forecast 2025-2030

Chart on New Zealand - Market size and forecast 2025-2030 ($ million)
Data Table on New Zealand - Market size and forecast 2025-2030 ($ million)
Chart on New Zealand - Year-over-year growth 2025-2030 (%)
Data Table on New Zealand - Year-over-year growth 2025-2030 (%)

12.6.7 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.6.8 Egypt - Market size and forecast 2025-2030

Chart on Egypt - Market size and forecast 2025-2030 ($ million)
Data Table on Egypt - Market size and forecast 2025-2030 ($ million)
Chart on Egypt - Year-over-year growth 2025-2030 (%)
Data Table on Egypt - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Rising prevalence of chronic diseases and complex conditions
Economic pressures and shift toward cost-effective outpatient settings
Technological advancements in infusion devices and digital health integration

13.2 Market challenges

Complex and restrictive reimbursement frameworks
Severe workforce shortages and specialized staffing limitations
Intense competition and regulatory compliance burdens

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Expansion of dedicated specialty infusion networks and decentralized outpatient care models
Integration of digital health ecosystems and automated inventory management
Rising adoption of biosimilar therapeutics and expanded payer coverage frameworks

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Cedars Sinai Health System

Cedars Sinai Health System - Overview
Cedars Sinai Health System - Product / Service
Cedars Sinai Health System - Key offerings
SWOT

15.5 Community Health Systems Inc.

Community Health Systems Inc. - Overview
Community Health Systems Inc. - Product / Service
Community Health Systems Inc. - Key offerings
SWOT

15.6 CVS Health Corp.

CVS Health Corp. - Overview
CVS Health Corp. - Business segments
CVS Health Corp. - Key offerings
CVS Health Corp. - Segment focus
SWOT

15.7 HCA Healthcare Inc.

HCA Healthcare Inc. - Overview
HCA Healthcare Inc. - Product / Service
HCA Healthcare Inc. - Key offerings
SWOT

15.8 IVX Health

IVX Health - Overview
IVX Health - Product / Service
IVX Health - Key offerings
SWOT

15.9 Mayo Clinic

Mayo Clinic - Overview
Mayo Clinic - Product / Service
Mayo Clinic - Key offerings
SWOT

15.10 McKesson Corp.

McKesson Corp. - Overview
McKesson Corp. - Business segments
McKesson Corp. - Key offerings
McKesson Corp. - Segment focus
SWOT

15.11 Northwestern Medicine

Northwestern Medicine - Overview
Northwestern Medicine - Product / Service
Northwestern Medicine - Key offerings
SWOT

15.12 Option Care Health Inc.

Option Care Health Inc. - Overview
Option Care Health Inc. - Product / Service
Option Care Health Inc. - Key offerings
SWOT

15.13 Sutter Health

Sutter Health - Overview
Sutter Health - Product / Service
Sutter Health - Key offerings
SWOT

15.14 Tenet Healthcare Corp.

Tenet Healthcare Corp. - Overview
Tenet Healthcare Corp. - Business segments
Tenet Healthcare Corp. - Key offerings
Tenet Healthcare Corp. - Segment focus
SWOT

15.15 The Cigna Group

The Cigna Group - Overview
The Cigna Group - Business segments
The Cigna Group - Key offerings
The Cigna Group - Segment focus
SWOT

15.16 The Cleveland Clinic Foundation

The Cleveland Clinic Foundation - Overview
The Cleveland Clinic Foundation - Product / Service
The Cleveland Clinic Foundation - Key offerings
SWOT

15.17 The Johns Hopkins Health System

The Johns Hopkins Health System - Overview
The Johns Hopkins Health System - Product / Service
The Johns Hopkins Health System - Key offerings
SWOT

15.18 United Health Group Inc.

United Health Group Inc. - Overview
United Health Group Inc. - Business segments
United Health Group Inc. - Key offerings
United Health Group Inc. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Ambulatory Infusion Center market growth will increase by USD 16086.3 million during 2026-2030.

The Ambulatory Infusion Center market is expected to grow at a CAGR of 5.6% during 2026-2030.

Ambulatory Infusion Center market is segmented by Type (Independent centers, Hospitals, Home healthcare) Indication (Oncology, Autoimmune disorders, Infectious diseases, Neurological disorders, Chronic pain conditions) Therapy (Immunoglobulin therapy, Anti-infective therapy, Others)

Cedars Sinai Health System, Community Health Systems Inc., CVS Health Corp., HCA Healthcare Inc., Infusion for Health, IVX Health, Mayo Clinic, McKesson Corp., Metro Infusion Center, Northwestern Medicine, Option Care Health Inc., Sutter Health, Tenet Healthcare Corp., The Cigna Group, The Cleveland Clinic Foundation, The Johns Hopkins Health System, United Health Group Inc. are a few of the key vendors in the Ambulatory Infusion Center market.

North America will register the highest growth rate of 49.8% among the other regions. Therefore, the Ambulatory Infusion Center market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Taiwan, Singapore, Brazil, Saudi Arabia, South Africa, Argentina, UAE, New Zealand, Chile, Egypt

  • Rising prevalence of chronic diseases and complex conditions is the driving factor this market.

The Ambulatory Infusion Center market vendors should focus on grabbing business opportunities from the Type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
