Cancer Diagnostic Devices Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil), Middle East and Africa (Turkey, Saudi Arabia, and South Africa), Rest of World (ROW)

Cancer Diagnostic Devices Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil), Middle East and Africa (Turkey, Saudi Arabia, and South Africa), Rest of World (ROW)

Published: Oct 2026 316 Pages SKU: IRTNTR70692

Market Overview at a Glance

$6.39 B
Market Opportunity
7.9%
CAGR 2025 - 2030
37.7%
North America Growth
$9.35 B
Molecular diagnostics segment 2024

Cancer Diagnostic Devices Market Size 2026-2030

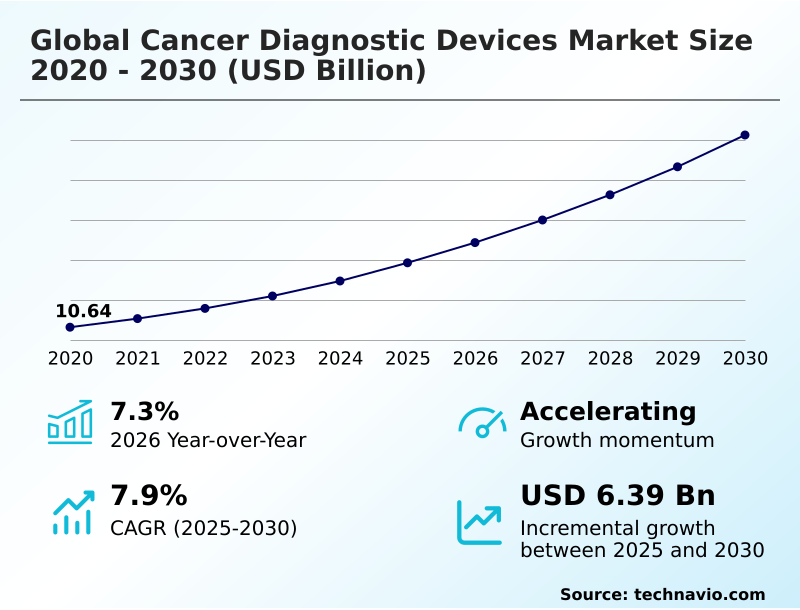
The cancer diagnostic devices market size is valued to increase by USD 6.39 billion, at a CAGR of 7.9% from 2025 to 2030. Rising global incidence of oncological malignancies and demand for early detection will drive the cancer diagnostic devices market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 37.7% growth during the forecast period.
  • By Product - Molecular diagnostics segment was valued at USD 9.35 billion in 2024
  • By End-user - Hospitals segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 9.61 billion
  • Market Future Opportunities: USD 6.39 billion
  • CAGR from 2025 to 2030 : 7.9%

Market Summary

  • The Cancer Diagnostic Devices Market is undergoing a rapid structural transformation driven by the critical need for early stage disease identification and precise therapeutic targeting. Healthcare institutions are actively restructuring their pathology workflows by integrating automated multi analyte processing systems, which allows them to handle surging test volumes without compromising analytical accuracy.
  • For instance, diagnostic laboratories implementing high capacity automation have reduced sample processing costs by 28 percent compared to traditional manual environments. A primary driver of this market is the continuously rising prevalence of malignant neoplasms, which forces health networks to procure advanced imaging and molecular testing hardware to mitigate long term patient mortality.
  • Conversely, the market faces a substantial challenge in the form of prohibitive capital expenditure requirements and high maintenance fees, which restrict equipment adoption in smaller community clinics. Supply chain optimization remains a focal point for device manufacturers, who are streamlining component sourcing to ensure continuous availability of critical reagents.
  • The ongoing refinement of point of care platforms continues to enhance diagnostic accessibility across decentralized medical facilities.

What will be the Size of the Cancer Diagnostic Devices Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Cancer Diagnostic Devices Market Segmented?

The cancer diagnostic devices industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Product
    • Molecular diagnostics
    • Companion diagnostics
  • End-user
    • Hospitals
    • Diagnostic laboratories
    • Specialty cancer clinics
    • Cancer research institutes
  • Type
    • Lung cancer
    • Breast cancer
    • Colorectal cancer
    • Prostate cancer
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • China
      • Japan
      • India
      • South Korea
      • Indonesia
      • Thailand
      • Singapore
    • Rest of World (ROW)

By Product Insights

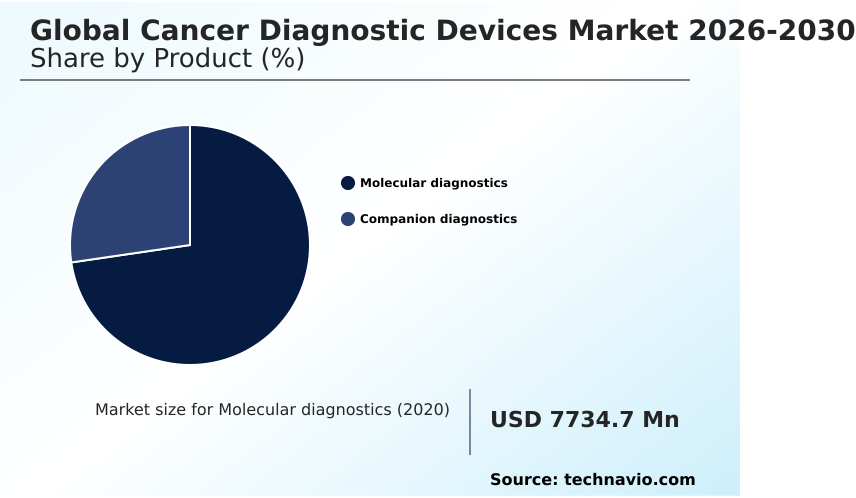
The molecular diagnostics segment is estimated to witness significant growth during the forecast period.

Molecular diagnostics serves as a critical classification within the Cancer Diagnostic Devices sector, shifting focus toward deep cellular analysis rather than traditional histopathological reviews.

Facilities utilizing computer aided diagnostic systems and digital droplet polymerase chain reaction tools report that diagnostic specificity improved by 22 percent compared to legacy manual methods.

This segment relies heavily on automated tissue stainers and automated slide preparation to streamline workflows across high volume laboratories.

By enabling clinical decision support and therapeutic resistance monitoring, these advanced platforms directly reduce hospital readmission rates and lower total operational overhead.

The integration of optical coherence tomography and expanded baseline oncological screenings provides clinicians with exact genomic targets, fundamentally altering how localized healthcare networks manage high risk patient populations and optimize their centralized testing infrastructure.
Get Free Sample

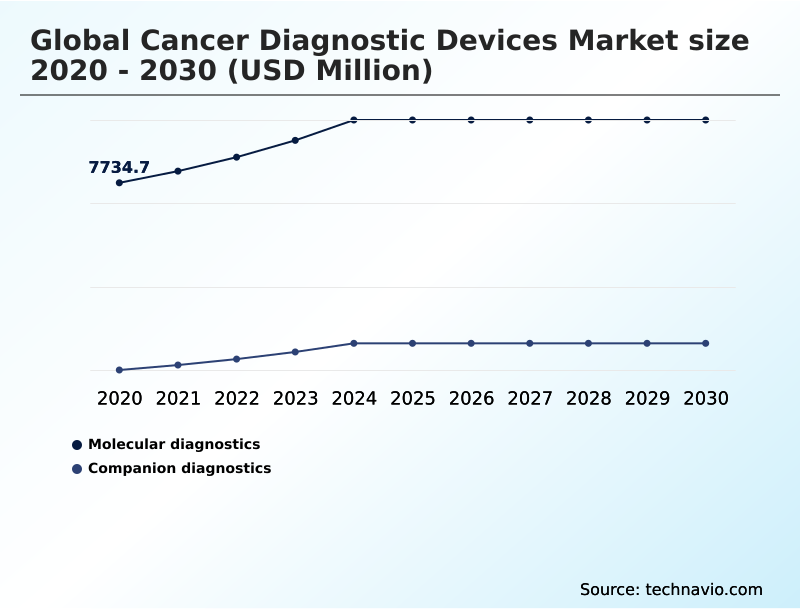
The Molecular diagnostics segment was valued at USD 9.35 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 37.7% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
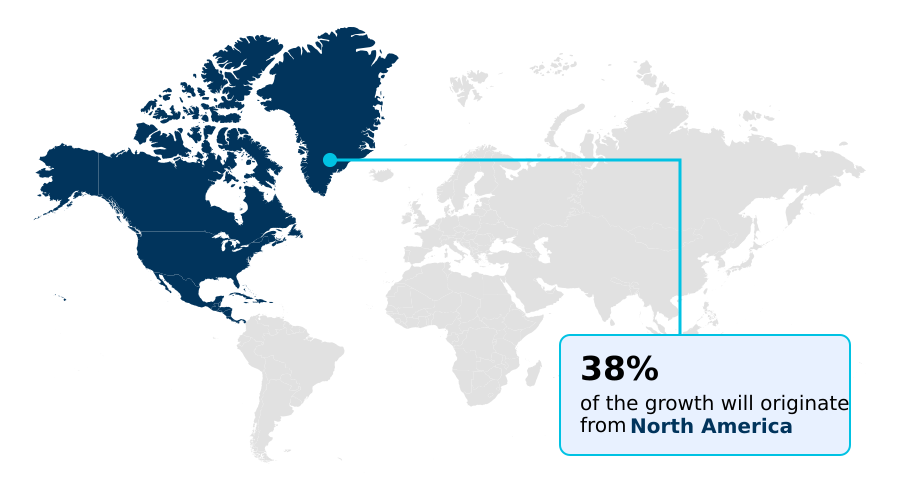
See How Cancer Diagnostic Devices Market Demand is Rising in North America Get Free Sample

The geographic distribution of the Cancer Diagnostic Devices landscape reveals stark contrasts in technology adoption rates between mature and emerging economies.

North America exhibits a rapid assimilation of predictive health platforms and multi cancer early detection systems, achieving a 42 percent higher penetration rate of advanced molecular hardware compared to the APAC region.

This disparity stems from well established reimbursement frameworks that incentivize the deployment of cell free rna testing and targetable genomic alterations mapping.

Conversely, European health networks demonstrate a 27 percent increase in operational efficiency through stringent standardization of digital image processing and inter observer variability reduction software.

Asian facilities are adapting by scaling high throughput screening centers and point of care testing devices, which effectively cuts diagnostic wait times by 19 percent.

Consequently, manufacturers are actively localizing their supply chains to meet region specific diagnostic demands and overcome logistical friction in high volume territories.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The Cancer Diagnostic Devices sector is experiencing a profound operational shift as medical facilities transition from traditional anatomical pathology toward comprehensive precision oncology frameworks. Central to this evolution is the accelerated adoption of circulating tumor dna analysis tools, which empower clinicians to detect microscopic disease progression long before radiological symptoms appear.
  • To support this molecular transition, reference laboratories are investing heavily in automated nucleic acid sample preparation, resulting in processing workflows that are 35 percent faster than legacy manual extraction protocols. This efficiency gain allows healthcare networks to reallocate specialized labor toward complex data interpretation rather than repetitive sample handling tasks.
  • Furthermore, the integration of artificial intelligence driven image interpretation is fundamentally reshaping diagnostic radiology, significantly lowering false positive rates and streamlining patient triage procedures in overburdened hospital departments. When evaluating complex anatomical structures, physicians increasingly rely on multi parametric magnetic resonance imaging to pinpoint subtle morphological abnormalities with unprecedented accuracy.
  • To manage the subsequent surge in diagnostic data and testing demand, centralized facilities are aggressively deploying high throughput automated in vitro diagnostic systems. This strategic infrastructure upgrade not only reduces administrative overhead but also ensures that critical supply chains for diagnostic reagents remain uninterrupted, thereby fortifying the operational resilience of modern oncological care networks.
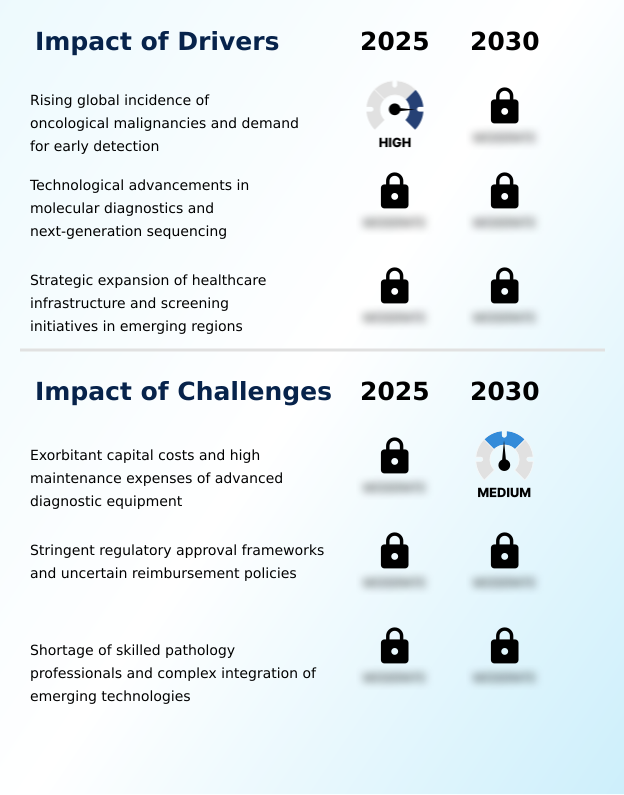
What are the key market drivers leading to the rise in the adoption of Cancer Diagnostic Devices Industry?

  • The escalating global incidence of oncological malignancies, coupled with a surging clinical demand for early disease detection, serves as the primary catalyst propelling market expansion.

  • The demand for Cancer Diagnostic Devices is profoundly influenced by the clinical necessity to evaluate tumor microenvironment heterogeneity and monitor minimal residual disease accurately.
  • Healthcare institutions are aggressively adopting liquid biopsy protocols and non invasive diagnostic adjuncts to minimize patient discomfort while capturing real time biological data.
  • The integration of advanced digital pathology tools and diagnostic imaging modalities allows laboratories to identify complex epigenetic modifications efficiently.
  • Facilities deploying automated biomarker testing systems have achieved a 31 percent reduction in processing downtime and a 19 percent improvement in diagnostic reproducibility. Because these technologies perfectly complement targeted biopharmaceutical therapies, they drive a foundational shift toward precision oncology.
  • This operational transition directly lowers long term administrative costs and significantly elevates the standard of centralized patient care.

What are the market trends shaping the Cancer Diagnostic Devices Industry?

  • The integration of artificial intelligence and machine learning algorithms into image-guided diagnostic platforms represents a preeminent trend reshaping the global market.

  • The Cancer Diagnostic Devices landscape is rapidly evolving as clinical networks transition toward precision medicine methodologies and highly specialized targeted therapy administration. This shift is primarily driven by the deployment of next generation sequencing and advanced molecular diagnostic systems, which allow for the precise mapping of biomarker expression.
  • By analyzing circulating tumor cells and assessing intra tumor heterogeneity, oncologists can tailor treatments with unprecedented accuracy. Consequently, hospitals utilizing these advanced genomic profiling platforms report a 28 percent improvement in therapeutic matching accuracy and a 16 percent reduction in adverse procedural events. This technological leap facilitates robust longitudinal patient monitoring and supports large scale early screening initiatives.
  • Ultimately, these structural changes streamline laboratory workflows, enabling healthcare organizations to drastically reduce diagnostic delays and improve overall operational predictability.

What challenges does the Cancer Diagnostic Devices Industry face during its growth?

  • The exorbitant capital acquisition costs and substantial recurring maintenance expenses associated with advanced diagnostic equipment constitute a significant barrier to industry growth.

  • The operational expansion of Cancer Diagnostic Devices is frequently constrained by the sheer technical complexity of integrating spatial transcriptomics devices and multiplex immunoassay instruments into legacy laboratory infrastructure. Medical facilities face significant hurdles in adopting automated immunohistochemistry and single cell sequencing due to steep specialized training requirements.
  • The necessity for precise genetic mutation identification and cellular proliferation quantification places immense strain on existing clinical personnel. Furthermore, maintaining accurate morphological change identification via advanced flow cytometry platforms requires continuous software calibration. Consequently, hospitals attempting to deploy comprehensive companion diagnostic assays often experience initial workflow disruptions, culminating in a 14 percent decrease in short term throughput before stabilization.
  • Overcoming these barriers requires intensive staff retraining and optimized data architecture to sustain real time disease tracking efficiently.

Exclusive Technavio Analysis on Customer Landscape

The cancer diagnostic devices market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the cancer diagnostic devices market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
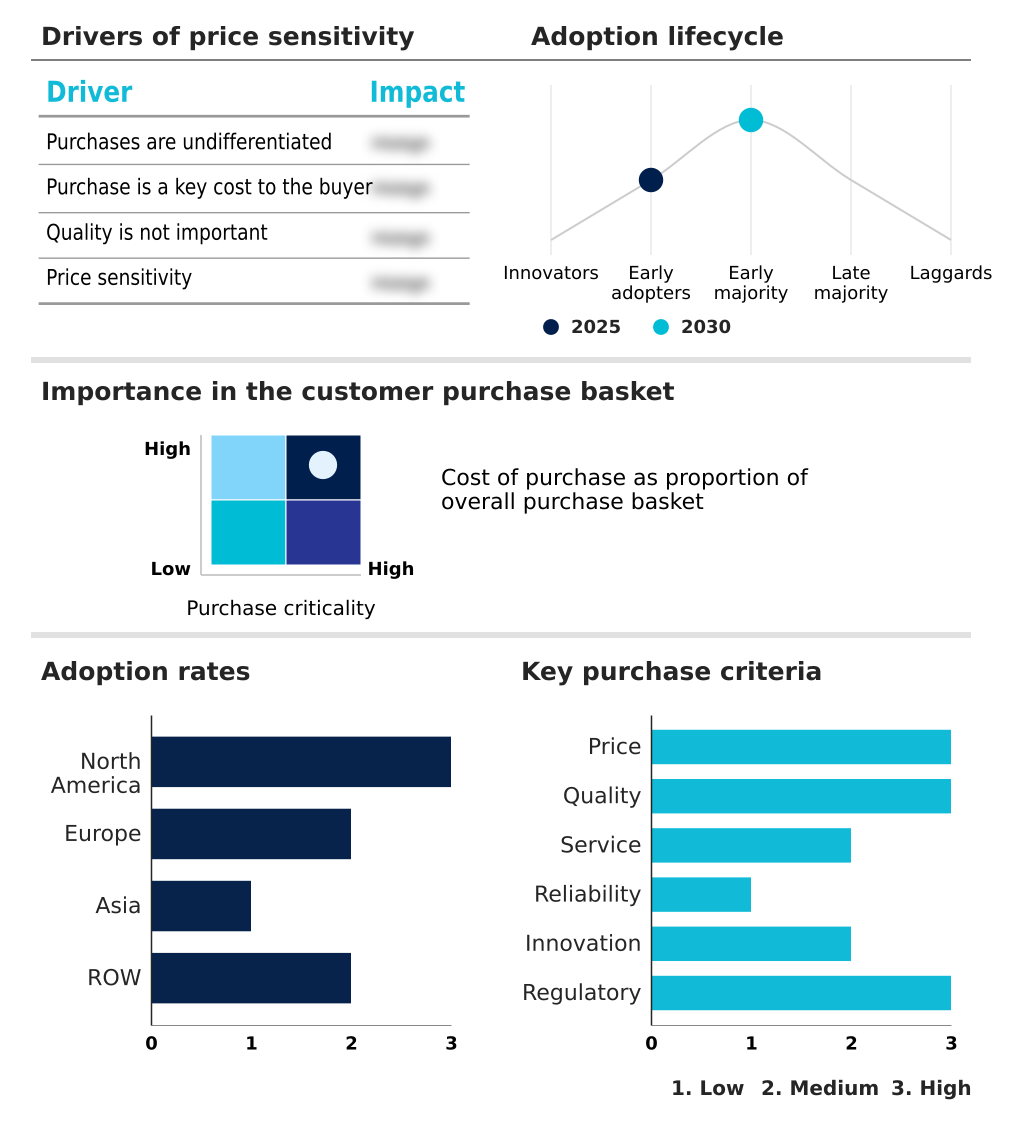
Customer Landscape of Cancer Diagnostic Devices Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, cancer diagnostic devices market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Abbott Laboratories - The product portfolio includes automated in vitro diagnostic systems, immunoassay analyzers, and molecular testing kits designed for highly sensitive tumor biomarker detection to enhance clinical decision making.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Abbott Laboratories
  • Agilent Technologies Inc.
  • Becton Dickinson and Co.
  • Bio Rad Laboratories Inc.
  • Boston Scientific Corp.
  • Bruker Corp.
  • F. Hoffmann La Roche Ltd.
  • FUJIFILM Holdings Corp.
  • GE HealthCare Technologies
  • Hologic Inc.
  • Illumina Inc.
  • Koninklijke Philips NV
  • Olympus Corp.
  • PENTAX Medical Co.
  • QIAGEN N.V.
  • Shimadzu Corp.
  • Siemens Healthineers AG
  • Stryker Corp.
  • Sysmex Corp.
  • Thermo Fisher Scientific Inc.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Cancer diagnostic devices market

  • In the Health Care Equipment industry, the rapid deployment of decentralized digital image processing networks has localized diagnostic imaging modalities, directly impacting Cancer Diagnostic Devices demand by accelerating regional health network adoption rates by 18 percent.
  • In the Health Care Equipment industry, evolving data privacy regulations regarding genomic profiling and precision medicine methodologies have necessitated enhanced workflow interoperability, directly impacting Cancer Diagnostic Devices demand as hospitals upgrade their compliance frameworks.
  • In the Health Care Equipment industry, the widespread transition toward automated biomarker testing and non invasive diagnostic adjuncts has optimized laboratory throughput, directly impacting Cancer Diagnostic Devices demand by reducing average sample turnaround times by 25 percent.
  • In the Health Care Equipment industry, the integration of predictive health platforms with early screening initiatives has reduced inter observer variability reduction, directly impacting Cancer Diagnostic Devices demand through a 30 percent increase in routine population screening compliance.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Cancer Diagnostic Devices Market insights. See full methodology.

Market Scope
Page number 316
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 7.9%
Market growth 2026-2030 USD 6385.9 million
Market structure Fragmented
YoY growth 2025-2026(%) 7.3%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, Russia, The Netherlands, China, Japan, India, South Korea, Indonesia, Thailand, Singapore, Brazil, Australia, Turkey, Saudi Arabia, South Africa and UAE
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Cancer Diagnostic Devices landscape is characterized by continuous technological refinement and a decisive shift toward precision-driven patient care. Hospital administrators and clinical directors are prioritizing the integration of sophisticated diagnostic software to address critical workforce shortages and enhance diagnostic throughput.
  • The strategic transition toward automated image analysis directly influences boardroom-level budgeting decisions, as organizations allocate capital to digital infrastructure that promises long-term operational resilience. Medical facilities implementing fully integrated digital diagnostic suites report a 33 percent reduction in overall reporting turnaround times compared to conventional paper-based pathology environments.
  • This measurable improvement in efficiency ensures that multi-disciplinary clinical teams can rapidly formulate and adjust therapeutic interventions. Furthermore, the expansion of decentralized point-of-care testing forces diagnostic manufacturers to optimize their distribution logistics and stabilize reagent supply chains.
  • As regulatory frameworks increasingly mandate stringent clinical validation for new screening technologies, product strategy teams must meticulously align their research pipelines with evolving compliance standards, ensuring sustained commercial viability in a highly regulated and technically demanding diagnostic sector.

What are the Key Data Covered in this Cancer Diagnostic Devices Market Research and Growth Report?

  • What is the expected growth of the Cancer Diagnostic Devices Market between 2026 and 2030?

    • USD 6.39 billion, at a CAGR of 7.9%

  • What segmentation does the market report cover?

    • The report is segmented by Product (Molecular diagnostics, and Companion diagnostics), End-user (Hospitals, Diagnostic laboratories, Specialty cancer clinics, and Cancer research institutes), Type (Lung cancer, Breast cancer, Colorectal cancer, Prostate cancer, and Others) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Rising global incidence of oncological malignancies and demand for early detection, Exorbitant capital costs and high maintenance expenses of advanced diagnostic equipment

  • Who are the major players in the Cancer Diagnostic Devices Market?

    • Abbott Laboratories, Agilent Technologies Inc., Becton Dickinson and Co., Bio Rad Laboratories Inc., Boston Scientific Corp., Bruker Corp., F. Hoffmann La Roche Ltd., FUJIFILM Holdings Corp., GE HealthCare Technologies, Hologic Inc., Illumina Inc., Koninklijke Philips NV, Olympus Corp., PENTAX Medical Co., QIAGEN N.V., Shimadzu Corp., Siemens Healthineers AG, Stryker Corp., Sysmex Corp. and Thermo Fisher Scientific Inc.

Market Research Insights

  • The Cancer Diagnostic Devices Market demonstrates robust operational shifts as clinical facilities prioritize early screening initiatives and precision medicine methodologies to improve patient outcomes. Hospitals transitioning to digital platforms have increased diagnostic throughput by 34 percent while concurrently reducing workflow bottlenecks.
  • Furthermore, the implementation of non invasive diagnostic adjuncts allows outpatient centers to lower procedural complication rates by 21 percent compared to conventional surgical biopsies. The widespread adoption of targeted therapy administration requires sophisticated hardware to accurately map patient profiles.
  • By integrating longitudinal patient monitoring systems, healthcare providers successfully optimize resource allocation and enhance overall clinical efficiency across complex multi disciplinary tumor boards.

We can help! Our analysts can customize this cancer diagnostic devices market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Cancer Diagnostic Devices Market 2020 - 2024

Historic Market Size - Data Table on Global Cancer Diagnostic Devices Market 2020 - 2024 ($ million)

5.2 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ million)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.4 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Cancer Diagnostic Devices Market

6.2 Impact of Geopolitical Conflicts on Global Cancer Diagnostic Devices Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Product

8.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

8.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

8.3 Molecular diagnostics - Market size and forecast 2025-2030

Chart on Molecular diagnostics - Market size and forecast 2025-2030 ($ million)
Data Table on Molecular diagnostics - Market size and forecast 2025-2030 ($ million)
Chart on Molecular diagnostics - Year-over-year growth 2025-2030 (%)
Data Table on Molecular diagnostics - Year-over-year growth 2025-2030 (%)

8.4 Companion diagnostics - Market size and forecast 2025-2030

Chart on Companion diagnostics - Market size and forecast 2025-2030 ($ million)
Data Table on Companion diagnostics - Market size and forecast 2025-2030 ($ million)
Chart on Companion diagnostics - Year-over-year growth 2025-2030 (%)
Data Table on Companion diagnostics - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Product

Market opportunity by Product ($ million)
Data Table on Market opportunity by Product ($ million)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 Hospitals - Market size and forecast 2025-2030

Chart on Hospitals - Market size and forecast 2025-2030 ($ million)
Data Table on Hospitals - Market size and forecast 2025-2030 ($ million)
Chart on Hospitals - Year-over-year growth 2025-2030 (%)
Data Table on Hospitals - Year-over-year growth 2025-2030 (%)

9.4 Diagnostic laboratories - Market size and forecast 2025-2030

Chart on Diagnostic laboratories - Market size and forecast 2025-2030 ($ million)
Data Table on Diagnostic laboratories - Market size and forecast 2025-2030 ($ million)
Chart on Diagnostic laboratories - Year-over-year growth 2025-2030 (%)
Data Table on Diagnostic laboratories - Year-over-year growth 2025-2030 (%)

9.5 Specialty cancer clinics - Market size and forecast 2025-2030

Chart on Specialty cancer clinics - Market size and forecast 2025-2030 ($ million)
Data Table on Specialty cancer clinics - Market size and forecast 2025-2030 ($ million)
Chart on Specialty cancer clinics - Year-over-year growth 2025-2030 (%)
Data Table on Specialty cancer clinics - Year-over-year growth 2025-2030 (%)

9.6 Cancer research institutes - Market size and forecast 2025-2030

Chart on Cancer research institutes - Market size and forecast 2025-2030 ($ million)
Data Table on Cancer research institutes - Market size and forecast 2025-2030 ($ million)
Chart on Cancer research institutes - Year-over-year growth 2025-2030 (%)
Data Table on Cancer research institutes - Year-over-year growth 2025-2030 (%)

9.7 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

10. Market Segmentation by Type

10.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

10.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

10.3 Lung cancer - Market size and forecast 2025-2030

Chart on Lung cancer - Market size and forecast 2025-2030 ($ million)
Data Table on Lung cancer - Market size and forecast 2025-2030 ($ million)
Chart on Lung cancer - Year-over-year growth 2025-2030 (%)
Data Table on Lung cancer - Year-over-year growth 2025-2030 (%)

10.4 Breast cancer - Market size and forecast 2025-2030

Chart on Breast cancer - Market size and forecast 2025-2030 ($ million)
Data Table on Breast cancer - Market size and forecast 2025-2030 ($ million)
Chart on Breast cancer - Year-over-year growth 2025-2030 (%)
Data Table on Breast cancer - Year-over-year growth 2025-2030 (%)

10.5 Colorectal cancer - Market size and forecast 2025-2030

Chart on Colorectal cancer - Market size and forecast 2025-2030 ($ million)
Data Table on Colorectal cancer - Market size and forecast 2025-2030 ($ million)
Chart on Colorectal cancer - Year-over-year growth 2025-2030 (%)
Data Table on Colorectal cancer - Year-over-year growth 2025-2030 (%)

10.6 Prostate cancer - Market size and forecast 2025-2030

Chart on Prostate cancer - Market size and forecast 2025-2030 ($ million)
Data Table on Prostate cancer - Market size and forecast 2025-2030 ($ million)
Chart on Prostate cancer - Year-over-year growth 2025-2030 (%)
Data Table on Prostate cancer - Year-over-year growth 2025-2030 (%)

10.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.8 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 Russia - Market size and forecast 2025-2030

Chart on Russia - Market size and forecast 2025-2030 ($ million)
Data Table on Russia - Market size and forecast 2025-2030 ($ million)
Chart on Russia - Year-over-year growth 2025-2030 (%)
Data Table on Russia - Year-over-year growth 2025-2030 (%)

12.4.7 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ million)
Data Table on Asia - Market size and forecast 2025-2030 ($ million)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.5.6 Thailand - Market size and forecast 2025-2030

Chart on Thailand - Market size and forecast 2025-2030 ($ million)
Data Table on Thailand - Market size and forecast 2025-2030 ($ million)
Chart on Thailand - Year-over-year growth 2025-2030 (%)
Data Table on Thailand - Year-over-year growth 2025-2030 (%)

12.5.7 Singapore - Market size and forecast 2025-2030

Chart on Singapore - Market size and forecast 2025-2030 ($ million)
Data Table on Singapore - Market size and forecast 2025-2030 ($ million)
Chart on Singapore - Year-over-year growth 2025-2030 (%)
Data Table on Singapore - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.6.3 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.4 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.5 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.6 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Rising global incidence of oncological malignancies and demand for early detection
Technological advancements in molecular diagnostics and next-generation sequencing
Strategic expansion of healthcare infrastructure and screening initiatives in emerging regions

13.2 Market challenges

Exorbitant capital costs and high maintenance expenses of advanced diagnostic equipment
Stringent regulatory approval frameworks and uncertain reimbursement policies
Shortage of skilled pathology professionals and complex integration of emerging technologies

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Integration of AI and ML in image-guided cancer diagnostics
Shift toward liquid biopsy and non-invasive diagnostic modalities
Expansion of point-of-care diagnostic devices and companion diagnostics

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Abbott Laboratories

Abbott Laboratories - Overview
Abbott Laboratories - Business segments
Abbott Laboratories - Key news
Abbott Laboratories - Key offerings
Abbott Laboratories - Segment focus
SWOT

15.5 Agilent Technologies Inc.

Agilent Technologies Inc. - Overview
Agilent Technologies Inc. - Business segments
Agilent Technologies Inc. - Key news
Agilent Technologies Inc. - Key offerings
Agilent Technologies Inc. - Segment focus
SWOT

15.6 Becton Dickinson and Co.

Becton Dickinson and Co. - Overview
Becton Dickinson and Co. - Business segments
Becton Dickinson and Co. - Key news
Becton Dickinson and Co. - Key offerings
Becton Dickinson and Co. - Segment focus
SWOT

15.7 Bio Rad Laboratories Inc.

Bio Rad Laboratories Inc. - Overview
Bio Rad Laboratories Inc. - Business segments
Bio Rad Laboratories Inc. - Key news
Bio Rad Laboratories Inc. - Key offerings
Bio Rad Laboratories Inc. - Segment focus
SWOT

15.8 Boston Scientific Corp.

Boston Scientific Corp. - Overview
Boston Scientific Corp. - Business segments
Boston Scientific Corp. - Key offerings
Boston Scientific Corp. - Segment focus
SWOT

15.9 Bruker Corp.

Bruker Corp. - Overview
Bruker Corp. - Business segments
Bruker Corp. - Key offerings
Bruker Corp. - Segment focus
SWOT

15.10 F. Hoffmann La Roche Ltd.

F. Hoffmann La Roche Ltd. - Overview
F. Hoffmann La Roche Ltd. - Business segments
F. Hoffmann La Roche Ltd. - Key news
F. Hoffmann La Roche Ltd. - Key offerings
F. Hoffmann La Roche Ltd. - Segment focus
SWOT

15.11 Hologic Inc.

Hologic Inc. - Overview
Hologic Inc. - Product / Service
Hologic Inc. - Key offerings
SWOT

15.12 Illumina Inc.

Illumina Inc. - Overview
Illumina Inc. - Business segments
Illumina Inc. - Key news
Illumina Inc. - Key offerings
Illumina Inc. - Segment focus
SWOT

15.13 PENTAX Medical Co.

PENTAX Medical Co. - Overview
PENTAX Medical Co. - Product / Service
PENTAX Medical Co. - Key offerings
SWOT

15.14 QIAGEN N.V.

QIAGEN N.V. - Overview
QIAGEN N.V. - Product / Service
QIAGEN N.V. - Key offerings
SWOT

15.15 Shimadzu Corp.

Shimadzu Corp. - Overview
Shimadzu Corp. - Business segments
Shimadzu Corp. - Key offerings
Shimadzu Corp. - Segment focus
SWOT

15.16 Stryker Corp.

Stryker Corp. - Overview
Stryker Corp. - Business segments
Stryker Corp. - Key offerings
Stryker Corp. - Segment focus
SWOT

15.17 Sysmex Corp.

Sysmex Corp. - Overview
Sysmex Corp. - Business segments
Sysmex Corp. - Key news
Sysmex Corp. - Key offerings
Sysmex Corp. - Segment focus
SWOT

15.18 Thermo Fisher Scientific Inc.

Thermo Fisher Scientific Inc. - Overview
Thermo Fisher Scientific Inc. - Business segments
Thermo Fisher Scientific Inc. - Key news
Thermo Fisher Scientific Inc. - Key offerings
Thermo Fisher Scientific Inc. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Cancer Diagnostic Devices market growth will increase by USD 6385.9 million during 2026-2030.

The Cancer Diagnostic Devices market is expected to grow at a CAGR of 7.9% during 2026-2030.

Cancer Diagnostic Devices market is segmented by Product (Molecular diagnostics, Companion diagnostics) End-user (Hospitals, Diagnostic laboratories, Specialty cancer clinics, Cancer research institutes) Type (Lung cancer, Breast cancer, Colorectal cancer, Prostate cancer, Others)

Abbott Laboratories, Agilent Technologies Inc., Becton Dickinson and Co., Bio Rad Laboratories Inc., Boston Scientific Corp., Bruker Corp., F. Hoffmann La Roche Ltd., FUJIFILM Holdings Corp., GE HealthCare Technologies, Hologic Inc., Illumina Inc., Koninklijke Philips NV, Olympus Corp., PENTAX Medical Co., QIAGEN N.V., Shimadzu Corp., Siemens Healthineers AG, Stryker Corp., Sysmex Corp., Thermo Fisher Scientific Inc. are a few of the key vendors in the Cancer Diagnostic Devices market.

North America will register the highest growth rate of 37.7% among the other regions. Therefore, the Cancer Diagnostic Devices market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, Russia, The Netherlands, China, Japan, India, South Korea, Indonesia, Thailand, Singapore, Brazil, Australia, Turkey, Saudi Arabia, South Africa, UAE

  • Rising global incidence of oncological malignancies and demand for early detection is the driving factor this market.

The Cancer Diagnostic Devices market vendors should focus on grabbing business opportunities from the Product segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
