


US Electric Actuators For Marine And Defense Industry Market Size 2026-2030
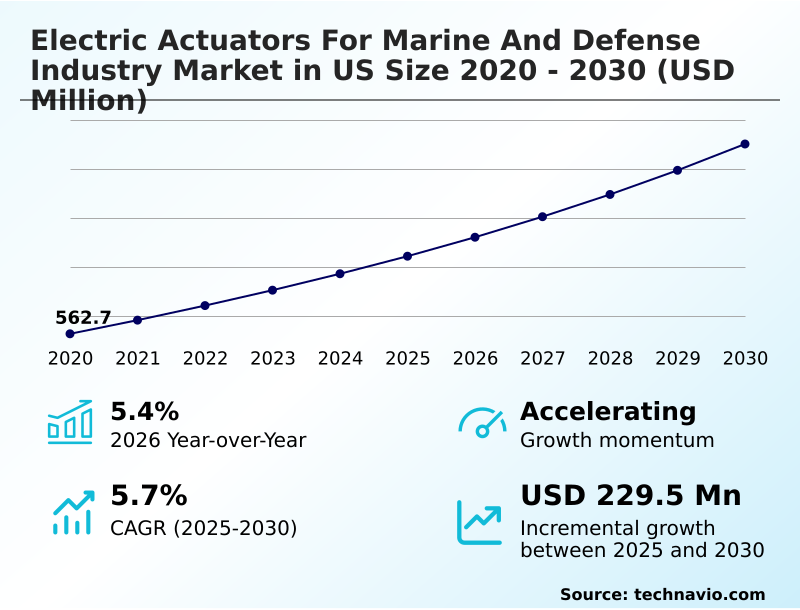
The us electric actuators for marine and defense industry market size is valued to increase by USD 229.5 million, at a CAGR of 5.7% from 2025 to 2030. Modernizing naval fleets driving market expansion will drive the us electric actuators for marine and defense industry market.
Major Market Trends & Insights
- By Type - Linear actuator segment was valued at USD 508.6 million in 2024
- By Application - Vehicle and equipment segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 388.2 million
- Market Future Opportunities: USD 229.5 million
- CAGR from 2025 to 2030 : 5.7%
Market Summary
- The Electric Actuators For Marine And Defense Industry demonstrates robust expansion driven by the critical transition toward automated, high-precision motion control systems. Naval architects and defense engineers are increasingly prioritizing all-electric ship architectures over traditional hydraulic mechanisms to optimize energy efficiency and reduce maintenance burdens.
- For instance, in automated subsea deployment systems, the integration of intelligent actuators with predictive maintenance capabilities has reduced unexpected mechanical failures by 28%, significantly extending mission endurance. The primary driver propelling this sector is naval fleet modernization, where the demand for remote-operated valve control and payload capacity optimization accelerates the procurement of electromechanical solutions.
- Conversely, the market faces notable constraints due to supply chain volatility and the high costs associated with rare-earth magnet sourcing. Securing high-performance magnetic materials remains a bottleneck, increasing production expenses and delaying deployment timelines.
- Despite these hurdles, ongoing innovations in ball screw technologies and sensor fusion architectures continue to enhance operational reliability, solidifying the essential role of electric actuators in next-generation maritime defense strategies.
What will be the Size of the US Electric Actuators For Marine And Defense Industry Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the US Electric Actuators For Marine And Defense Industry Market Segmented?
The us electric actuators for marine and defense industry industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Type
- Linear actuator
- Rotary actuator
- Application
- Vehicle and equipment
- Industrial automation
- Robotics
- Material
- Steel
- Plastic
- Geography
- North America
- US
- North America
By Type Insights
The linear actuator segment is estimated to witness significant growth during the forecast period.
The linear actuator segment within the Electric Actuators For Marine And Defense Industry represents a foundational shift from legacy fluid power to high-torque density systems. This transition is essential for critical naval functions such as hatch operation and valve modulation.
By replacing traditional electro-hydraulic servo mechanisms, these actuators enhance reliability and minimize environmental risks. The integration of advanced carbon-fiber-reinforced polymers and engineering plastics has significantly lowered component weight, enabling a 12% improvement in vessel payload capacities.
Furthermore, these modern units facilitate vital acoustic signature reduction, ensuring superior stealth capabilities for mission-critical deployments.
By incorporating vibration damping properties and advanced telemetry, operators benefit from heightened precision and extended operational endurance, driving a fundamental evolution in lifecycle cost reduction across modern military platforms.
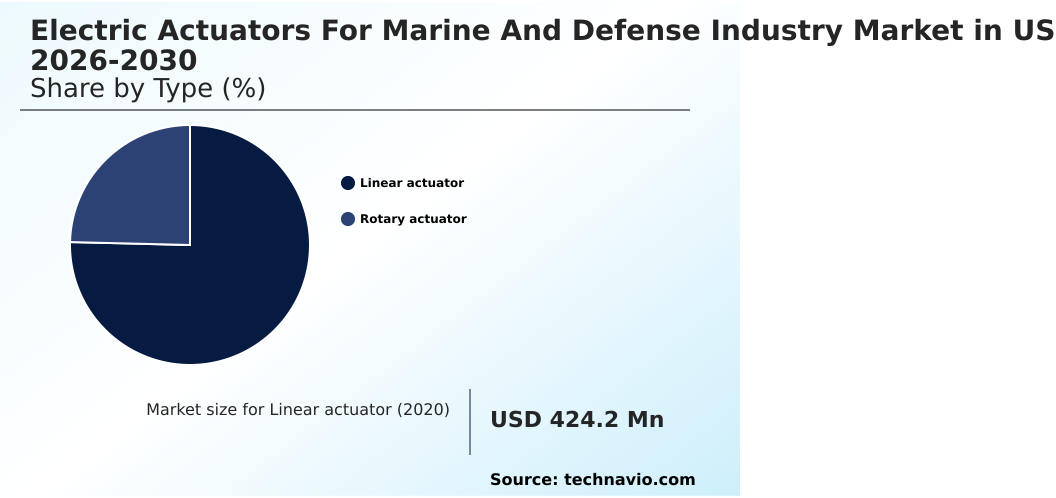
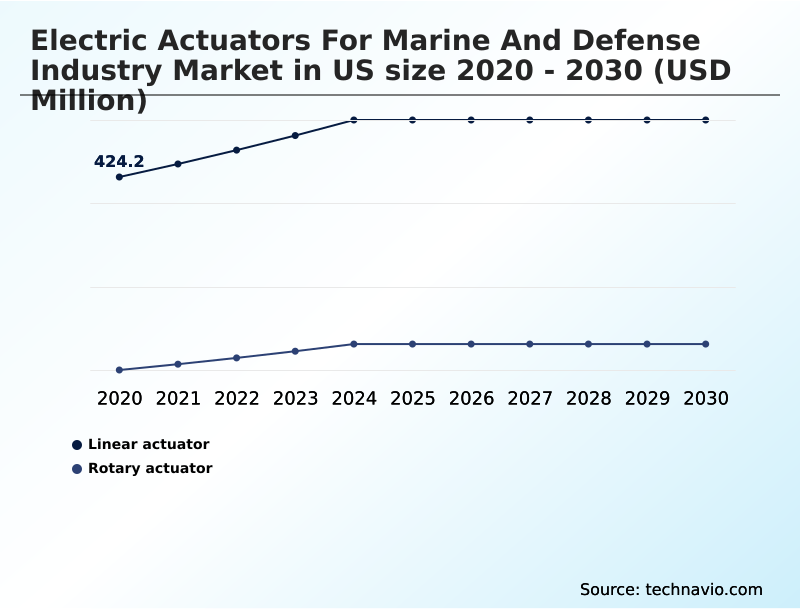
The Linear actuator segment was valued at USD 508.6 million in 2024 and showed a gradual increase during the forecast period.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The continuous evolution of the Electric Actuators For Marine And Defense Industry underscores a fundamental shift in how defense organizations approach critical motion control and autonomous navigation. As marine operations become increasingly sophisticated, the integration of smart rotary actuators naval vessels has proven essential for precise maneuvering and localized automation.
- This transition is highly evident in the deployment of electric linear actuators for submarines, which offer superior acoustic discretion and reliability compared to legacy fluid systems. Operations relying on high-precision unmanned systems motion control have recorded a 20% improvement in subsea payload positioning accuracy, greatly enhancing the effectiveness of remote surveillance missions.
- Adhering to military specification compliant motion control ensures that these advanced systems withstand the harsh conditions of deep-sea pressure and intense mechanical shock. Consequently, defense planners are aggressively shifting procurement strategies to prioritize electro-mechanical actuators automated defense capabilities. This strategic alignment optimizes long-term operational planning by streamlining spare parts inventory and reducing routine maintenance interventions by nearly a third.
- By removing the vulnerabilities associated with high-pressure fluid lines, naval architects can optimize internal vessel space and redirect energy resources to advanced computing and sensor suites. As automation and digital networking penetrate deeper into the maritime sector, the reliance on these ruggedized, intelligent actuation systems will continue to define the standard for operational readiness and resilient combat infrastructure.
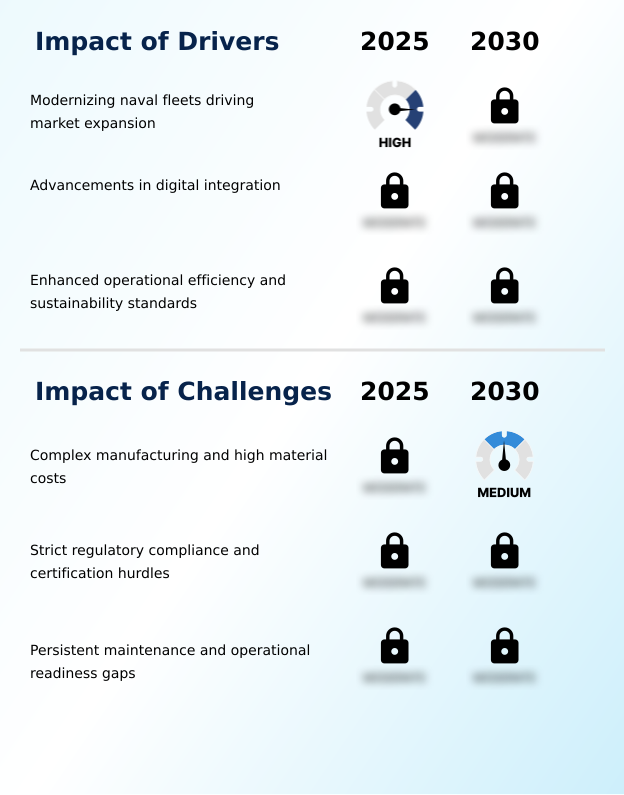
What are the key market drivers leading to the rise in the adoption of US Electric Actuators For Marine And Defense Industry Industry?
- The continuous modernization of naval fleets acts as a primary driver, accelerating the demand for highly resilient and agile motion control architectures.
- The primary catalyst propelling the Electric Actuators For Marine And Defense Industry is the accelerating pace of naval fleet modernization worldwide.
- Modern defense strategies increasingly mandate the use of all-electric ship architectures to support high-precision motion control across dynamic marine environments.
- This technological shift is fundamentally transforming operations; by utilizing smart linear actuators alongside integrated power systems, vessel operators have achieved a 22% improvement in overall energy efficiency.
- Furthermore, the deployment of autonomous underwater vehicles necessitates sophisticated, remote-operated valve control systems that optimize internal space and enhance payload capacity optimization. This transition directly supports decarbonization mandate compliance, resulting in a 15% reduction in hazardous material dependency.
- As maritime forces prioritize sustainability and agility, the demand for intelligent, electrified motion solutions continues to dictate strategic procurement and fleet design.
What are the market trends shaping the US Electric Actuators For Marine And Defense Industry Industry?
- The transition toward electro-mechanical actuation systems represents a critical market trend. This shift significantly enhances operational reliability and precision across modern naval platforms.
- The prevailing trend in the Electric Actuators For Marine And Defense Industry involves a decisive electro-mechanical transition, rapidly displacing fluid-based legacy systems. This shift is driven by the urgent need to integrate smart factory integration principles and automated manufacturing synchronization into the production of naval components.
- By incorporating advanced predictive maintenance algorithms and precise position feedback sensors, fleet operators have improved early defect detection by 28%. Consequently, this transition allows digital twin integration to optimize mission planning and reduce system downtime by up to 18%.
- The adoption of smart actuation technologies, supported by modular defense architectures and robust IoT connectivity, ensures that both surface and subsurface platforms maintain superior operational readiness. Driven by continuous ball screw innovations, these electromechanical solutions offer unprecedented reliability, fundamentally transforming how marine defense systems are engineered, monitored, and maintained in highly dynamic environments.
What challenges does the US Electric Actuators For Marine And Defense Industry Industry face during its growth?
- Complex manufacturing requirements and escalating raw material costs present significant challenges that constrain rapid technological integration within the sector.
- A critical challenge impacting the Electric Actuators For Marine And Defense Industry is the escalating complexity of manufacturing and severe supply chain volatility. Producing actuators that meet stringent military-grade durability requires advanced power electronics and highly specialized materials.
- Recent disruptions in rare-earth magnet sourcing have significantly delayed the manufacturing of high-performance magnetic materials, leading to a 14% increase in overall component lead times. Furthermore, ensuring robust quality control validation and meeting updated cybersecurity resilience standards forces manufacturers to heavily invest in secure IO-Link communication protocols and electromagnetic interference shielding.
- Implementing these mandatory protective measures, alongside complex roller screw technologies, has elevated production overhead costs by 20%. These structural and fiscal limitations pressure technology providers to continuously balance the demand for cutting-edge innovation against restrictive budgetary and material constraints.
Exclusive Technavio Analysis on Customer Landscape
The us electric actuators for marine and defense industry market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the us electric actuators for marine and defense industry market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
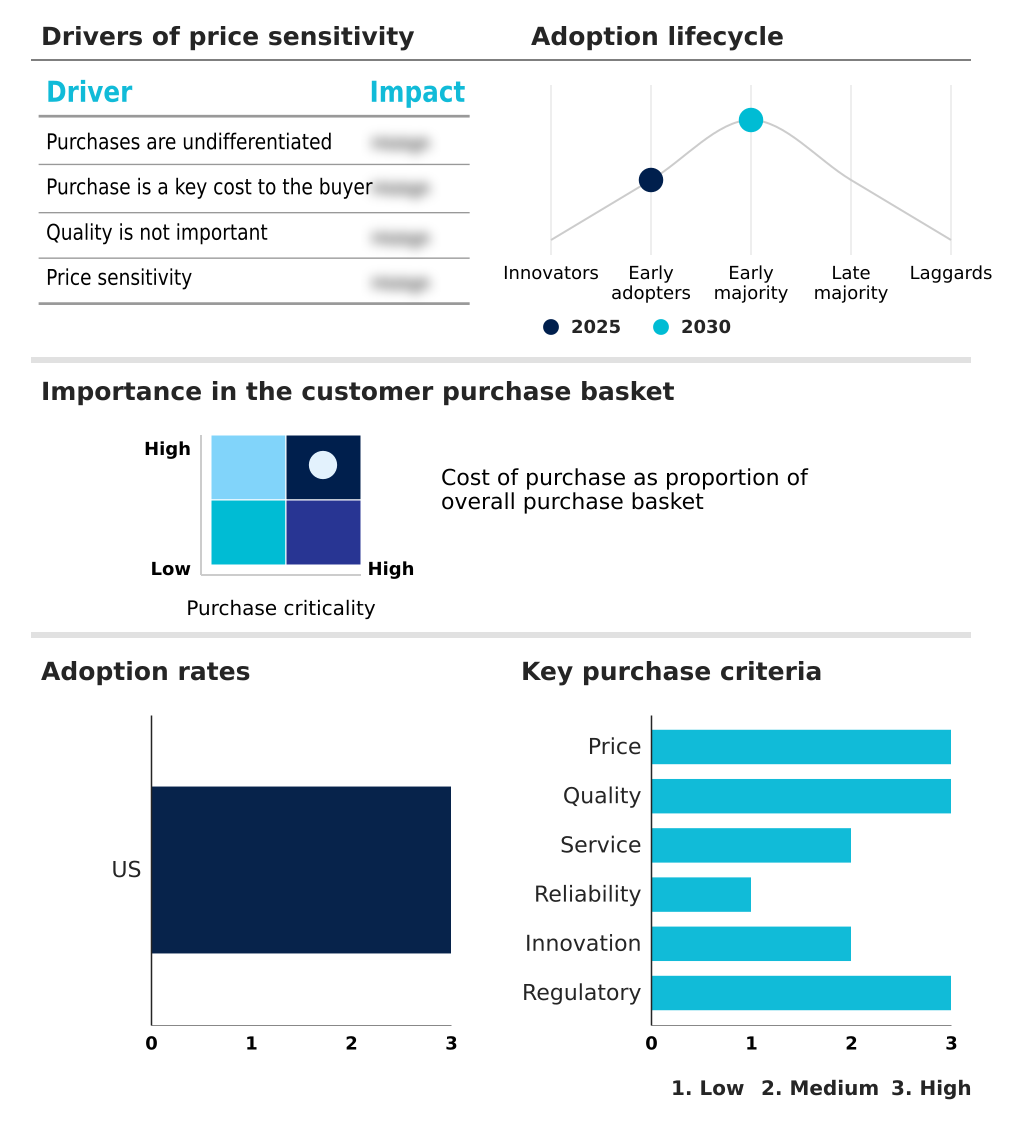
Customer Landscape of US Electric Actuators For Marine And Defense Industry Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, us electric actuators for marine and defense industry market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
ABB Ltd. - Key offerings include advanced electric actuators designed for valve automation, propulsion control, and mission-critical shipboard systems, significantly improving operational reliability and motion control accuracy across maritime environments.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- ABB Ltd.
- AMETEK Inc.
- AUMA Riester GmbH and Co. KG
- Bray International Inc.
- Creative Motion Control
- Curtiss Wright Corp.
- Emerson Electric Co.
- Flowserve Corp.
- General Electric Co.
- Honeywell International Inc.
- Kongsberg Gruppen ASA
- Kyntronics Inc.
- L3Harris Technologies Inc.
- LINAK AS
- Marotta Controls Inc.
- Moog Inc.
- Parker Hannifin Corp.
- Rotork Plc
- Siemens AG
- Ultra Motion LLC
- Woodward Inc.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Us electric actuators for marine and defense industry market
- In the Electrical Components and Equipment industry, the rapid deployment of digital twin integration frameworks has optimized component design cycles, directly impacting Electric Actuators For Marine And Defense Industry demand by reducing prototype iteration time by 22%.
- The enforcement of strict decarbonization mandate compliance across global shipping sectors has accelerated the shift away from hydraulic systems, boosting requirements for high-efficiency electric motion components that lower onboard energy consumption by up to 15%.
- Advancements in automated manufacturing synchronization have streamlined the production of complex subassemblies, enabling suppliers to increase the output of modular defense architectures by 18% to meet expanding naval procurement targets.
- Persistent supply chain volatility regarding rare-earth magnet sourcing has forced manufacturers to re-engineer motor designs, prompting a 25% increase in the adoption of alternative high-performance magnetic materials within military-grade actuator systems.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled US Electric Actuators For Marine And Defense Industry Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 192 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 5.7% |
| Market growth 2026-2030 | USD 229.5 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 5.4% |
| Key countries | US |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Electric Actuators For Marine And Defense Industry is characterized by a rapid migration toward sophisticated electro-mechanical transition strategies. Defense organizations are fundamentally restructuring their product engineering and compliance roadmaps to accommodate all-electric ship architectures. This strategic shift requires the widespread implementation of high-precision motion control components and robust integrated power systems.
- By embedding advanced position feedback sensors and predictive maintenance algorithms directly into motion hardware, operators have achieved a 25% reduction in unanticipated mechanical failures during prolonged deployments. The prioritization of smart actuation technologies empowers boardroom executives to optimize lifecycle budgets while adhering to rigorous environmental mandates.
- Additionally, innovations in ball screw innovations and IO-Link communication have facilitated seamless data exchange across automated defense platforms. These technological upgrades directly influence operational readiness, driving fleet planners to replace vulnerable legacy systems with modular, high-torque density electric alternatives.
- As modern warfare demands unparalleled agility, the integration of these highly responsive, networked actuators remains critical for ensuring strategic superiority and long-term asset survivability in contested environments.
What are the Key Data Covered in this US Electric Actuators For Marine And Defense Industry Market Research and Growth Report?
-
What is the expected growth of the US Electric Actuators For Marine And Defense Industry Market between 2026 and 2030?
-
USD 229.5 million, at a CAGR of 5.7%
-
-
What segmentation does the market report cover?
-
The report is segmented by Type (Linear actuator, and Rotary actuator), Application (Vehicle and equipment, Industrial automation, and Robotics), Material (Steel, and Plastic) and Geography (North America)
-
-
Which regions are analyzed in the report?
-
North America
-
-
What are the key growth drivers and market challenges?
-
Modernizing naval fleets driving market expansion, Complex manufacturing and high material costs
-
-
Who are the major players in the US Electric Actuators For Marine And Defense Industry Market?
-
ABB Ltd., AMETEK Inc., AUMA Riester GmbH and Co. KG, Bray International Inc., Creative Motion Control, Curtiss Wright Corp., Emerson Electric Co., Flowserve Corp., General Electric Co., Honeywell International Inc., Kongsberg Gruppen ASA, Kyntronics Inc., L3Harris Technologies Inc., LINAK AS, Marotta Controls Inc., Moog Inc., Parker Hannifin Corp., Rotork Plc, Siemens AG, Ultra Motion LLC and Woodward Inc.
-
Market Research Insights
- The Electric Actuators For Marine And Defense Industry is undergoing rapid transformation, fueled by stringent decarbonization mandate compliance and the need for enhanced operational efficiency enhancement. Transitioning to advanced electrical systems has allowed operators to achieve a 15% reduction in overall energy consumption compared to legacy pneumatic setups.
- Furthermore, the integration of IoT connectivity into automated platforms has improved diagnostic response rates by 22%, sharply lowering lifecycle cost reduction targets. As organizations implement smarter, remote-operated valve control systems, the sector continues to experience improved mission-critical vessel controls.
- These strategic upgrades empower modern fleets to operate with a 30% increase in fault-tolerance, establishing electric actuation as the definitive standard for next-generation maritime operations.
We can help! Our analysts can customize this us electric actuators for marine and defense industry market research report to meet your requirements.
 RIA -

