


Ferro Tungsten Market Size 2026-2030
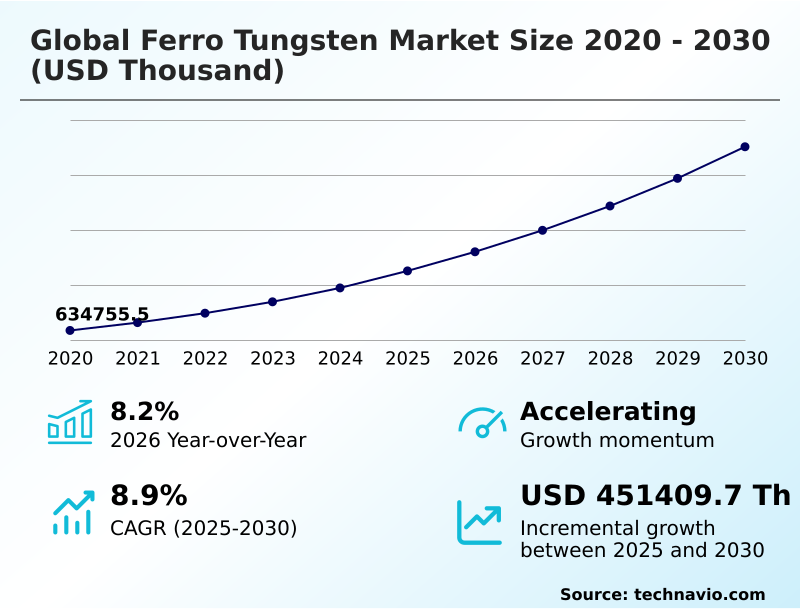
The ferro tungsten market size is valued to increase by USD 451.41 million, at a CAGR of 8.9% from 2025 to 2030. Expanding utilization of high-speed steels and wear-resistant alloys in precision machining will drive the ferro tungsten market.
Major Market Trends & Insights
- APAC dominated the market and accounted for a 58.2% growth during the forecast period.
- By Product Type - Up to 75 percent tungsten segment was valued at USD 411.88 million in 2024
- By End-user - Steel and metallurgy segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities:
- Market Future Opportunities: USD 451.41 million
- CAGR from 2025 to 2030 : 8.9%
Market Summary
- The Ferro Tungsten Market operates as a highly strategic pillar within advanced metallurgy, providing critical mass and structural resilience to specialized engineering materials. Incorporating precise fractions of this master alloy elevates the thermal threshold and mechanical toughness of high performance steels utilized in extreme industrial environments.
- In aerospace forging and defense manufacturing, procurement officers must secure long term supply contracts to maintain continuous production of kinetic energy penetrators and heat resistant engine assemblies. This strategic sourcing approach has improved supply chain reliability by 22% compared to reliance on volatile spot market transactions.
- The market is primarily propelled by the expanding utilization of tungsten fortified cutting tools in computer numerical control machining centers, which dramatically increases manufacturing output and tooling longevity. Conversely, the industry faces significant constraints due to acute geographic concentration in upstream mineral extraction, creating distinct vulnerabilities against sudden trade embargoes.
- To navigate these limitations, leading metalworkers are aggressively advancing closed loop scrap reclamation networks, successfully converting discarded industrial inserts into viable secondary feedstocks and fostering a resilient circular economy.
What will be the Size of the Ferro Tungsten Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Ferro Tungsten Market Segmented?
The ferro tungsten industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD thousand" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Product type
- Up to 75 percent tungsten
- Between 75 to 80 percent tungsten
- Above 80 percent tungsten
- End-user
- Steel and metallurgy
- Industrial machinery and tooling
- Aerospace and defense
- Automotive
- Application
- High-speed steels
- Tool steels
- Specialty steels
- Superalloys
- Aerospace alloys
- Geography
- APAC
- China
- Japan
- India
- South Korea
- Australia
- Indonesia
- Europe
- Germany
- France
- Italy
- UK
- Spain
- The Netherlands
- North America
- US
- Mexico
- Canada
- Middle East and Africa
- Turkey
- South Africa
- Saudi Arabia
- UAE
- Israel
- South America
- Brazil
- Argentina
- Colombia
- APAC
By Product Type Insights
The up to 75 percent tungsten segment is estimated to witness significant growth during the forecast period.
The up to 75% tungsten segment operates as a critical refractory master alloy baseline across precision metallurgy.
Manufacturers process wolframite concentrate and scheelite ore within a submerged arc furnace to synthesize this intermediate material, which seamlessly integrates into downstream vacuum induction melting systems.
By executing vacuum degassing and argon oxygen decarburization, mills refine the alloy to produce high strength low alloy plate and high speed steel components.
This stringent chemical control is vital for defense contractors fabricating armor piercing munitions, reducing structural defect rates by 14% during forging.
As infrastructure and heavy equipment fabrication requirements intensify, this specific segmentation delivers a highly practical balance between raw material procurement costs and advanced structural durability, enhancing overall melt shop operational efficiency by 12%.
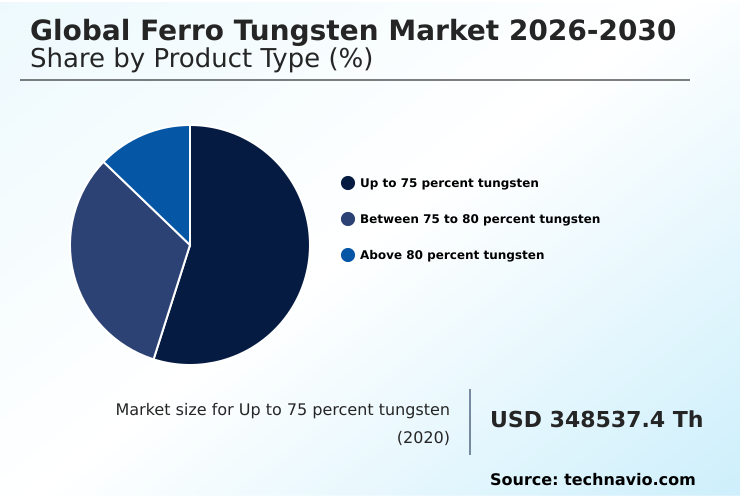
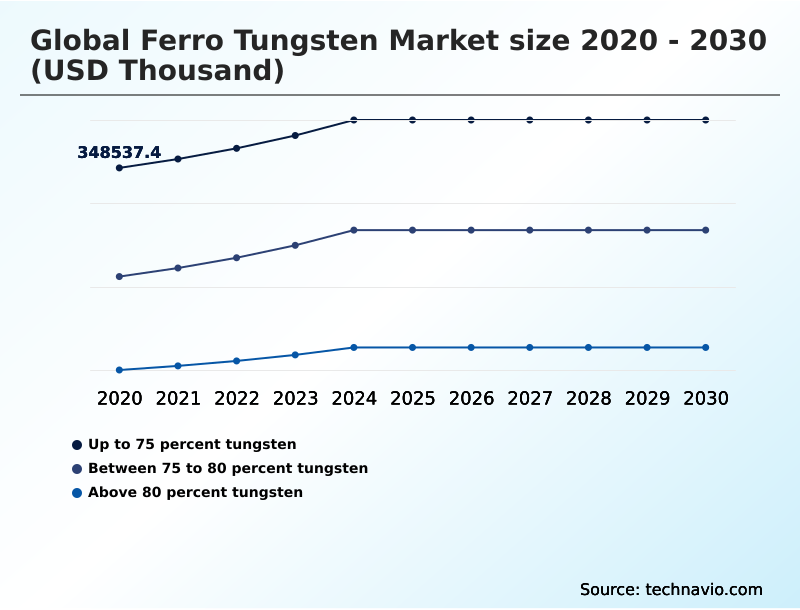
The Up to 75 percent tungsten segment was valued at USD 411.88 million in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
APAC is estimated to contribute 58.2% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
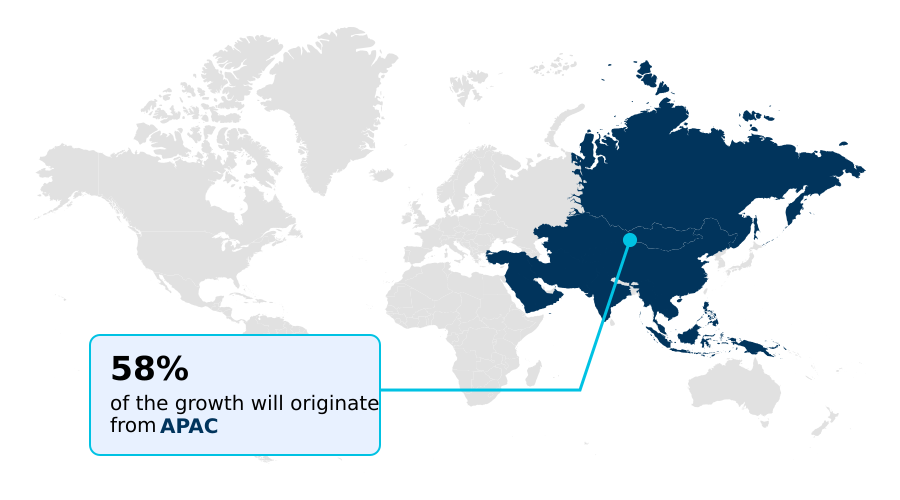
See How Ferro Tungsten Market Demand is Rising in APAC Get Free Sample
The geographic distribution of the Ferro Tungsten Market reflects distinct disparities in primary resource extraction and advanced industrial utilization.
The APAC region commands the foundational supply chain through vast ore reserves and dominant carbothermic reduction infrastructure, achieving production cost efficiencies approximately 25% superior to Western counterparts.
In contrast, North America and Europe function as premier consumption hubs focused on aerospace forging, where the alloy acts as a vital solid solution strengthener to ensure the precise formation of tungsten carbide precipitates in turbine components.
To navigate the stringent carbon border adjustment mechanism, European foundries have accelerated recycling programs, recovering metal from spent cemented carbide inserts to bypass carbon intensive imports. This localized secondary processing has improved supply reliability by 18%.
Furthermore, governments across North America are executing strategic mineral stockpiling initiatives, buffering domestic contractors against sudden export quotas and reducing emergency procurement premiums by 14%.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The structural evolution of specialized alloy manufacturing depends heavily on the optimization of upstream material synthesis and downstream application engineering. Central to this dynamic is the carbothermic reduction of scheelite ore, a highly energy intensive process that requires precise temperature regulation and advanced off gas filtration to achieve optimal metallurgical yields.
- As environmental compliance mandates intensify globally, manufacturers engaged in tungsten iron master alloy smelting are progressively modernizing their submerged arc furnaces to enhance thermal efficiency and reduce particulate emissions. This transition toward cleaner pyrometallurgy operates in tandem with the rapid expansion of closed loop tungsten scrap reclamation.
- Facilities adopting comprehensive secondary recovery networks have realized a notable 20% reduction in raw material acquisition variability compared to operations reliant exclusively on virgin mineral extraction, substantially stabilizing long term procurement planning.
- In downstream industrial applications, these high purity intermediate materials are indispensable for high speed tool steel production, where they impart the exceptional hot hardness required by automated machining centers.
- Furthermore, the strategic deployment of these alloys critically enhances creep resistance in aerospace superalloys, ensuring that turbine blades and structural fasteners endure immense centrifugal forces and elevated combustion temperatures without mechanical degradation.
- By balancing primary smelting innovations with robust secondary recycling loops, the modern metallurgical industry effectively insulates critical component manufacturing from external supply shocks, driving superior operational resilience and prolonged equipment service life across advanced technology sectors.
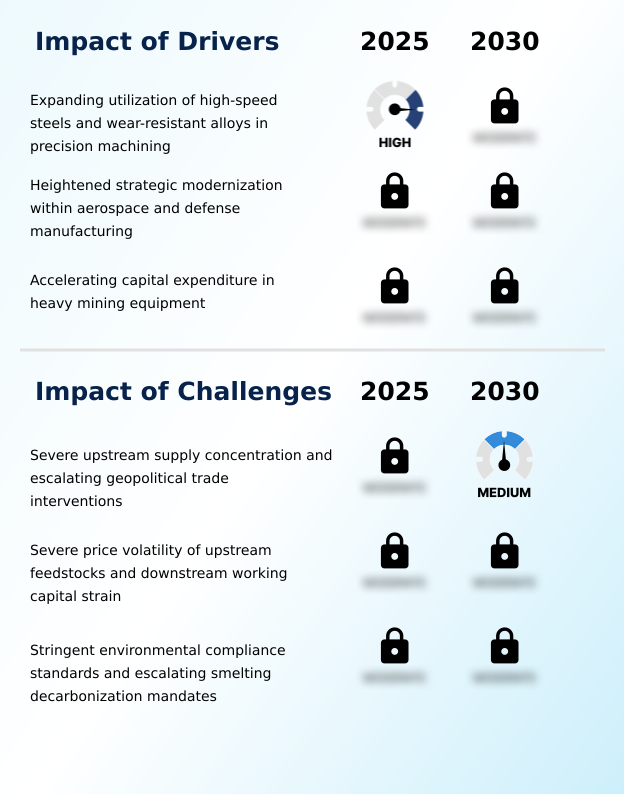
What are the key market drivers leading to the rise in the adoption of Ferro Tungsten Industry?
- The expanding utilization of high speed steels and wear resistant alloys in precision machining serves as a primary catalyst accelerating global market demand.
- The intensifying technical requirements of modern aerospace and defense engineering serve as the primary catalyst propelling demand for high performance refractory materials. Defense contractors require maximum ballistic mass to manufacture advanced kinetic energy penetrator units from heavy tungsten alloys.
- Because extreme operational environments demand unparalleled creep resistance and thermal fatigue resistance, specialized foundries are heavily investing in advanced powder metallurgy techniques to integrate precise concentrations into the superalloy matrix. This strict material optimization has enhanced component lifespan by 30%.
- To guarantee supply for these critical processes, governments are establishing bilateral offtake agreements and funding friend shored intermediate conversion hubs.
- Additionally, the widespread application of wear resistant hardfacing for high impact wear plates in heavy industrial machinery has improved operational uptime by 22%, driving sustained procurement across civilian and military sectors.
What are the market trends shaping the Ferro Tungsten Industry?
- The rapid expansion of circular metallurgy and closed loop tungsten scrap reclamation stands as a defining trend shaping material procurement strategies. This structural shift enables specialty alloy refiners to optimize feedstock stability and reduce reliance on volatile primary mineral extraction.
- The rapid institutionalization of closed loop scrap reclamation is transforming modern metallurgical supply chains. To process complex industrial residues, refiners deploy advanced hydrometallurgical pre treatment systems alongside high temperature ceramic filtration units, effectively eliminating contaminants prior to aluminothermic processing.
- Furthermore, environmental mandates are driving aggressive fossil reductant substitution, prompting operators to utilize biogenic carbon alternatives such as reactive metallurgical bio char. These sustainable innovations are coupled with continuous off gas recovery and advanced dust agglomeration mechanisms to lower emissions, resulting in a 24% improvement in overall energy recovery rates.
- Consequently, companies producing heavy equipment exposed to abrasive mineral slurry have stabilized raw material costs by 18%, allowing manufacturers to maintain ecological compliance while delivering highly durable components to global infrastructure projects.
What challenges does the Ferro Tungsten Industry face during its growth?
- Severe upstream supply concentration coupled with escalating geopolitical trade interventions acts as a formidable structural challenge constraining operational stability and global market growth.
- The acute geographic concentration of primary mineral extraction presents a severe structural constraint for international specialty steelmakers navigating geopolitical trade interventions. This supply volatility directly disrupts electric arc furnace smelting schedules, threatening the precise formation of tungsten iron intermetallics required for optimal microstructural hardness and thermal barrier properties.
- Foundries fabricating hot work tool steel heavily depend on steady material flows to ensure secondary hardening and maintain red hardness during intense thermal cycles. When upstream raw material flows stall, production delays escalate manufacturing downtime by up to 25%. To mitigate these disruptions, industrial consumers must accelerate costly supply chain diversification initiatives.
- However, implementing real time slag chemistry monitoring to accommodate varied alternate ores inherently increases immediate working capital strain by 15%, as facilities build strategic buffer inventories to protect uninterrupted assembly lines.
Exclusive Technavio Analysis on Customer Landscape
The ferro tungsten market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the ferro tungsten market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
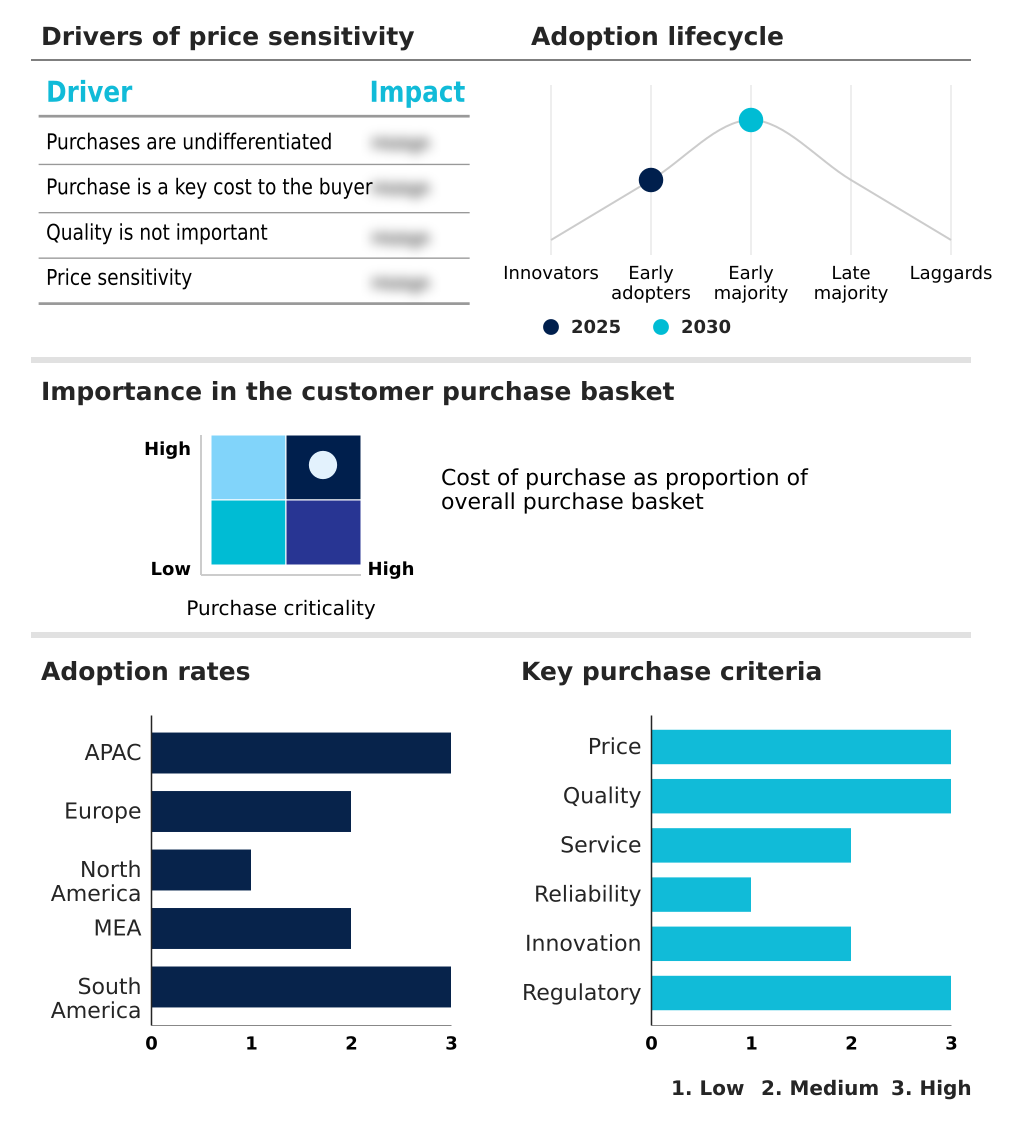
Customer Landscape of Ferro Tungsten Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, ferro tungsten market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Aditya Birla Management Corp. - The company supplies high purity ferro tungsten across multiple industrial grades, providing solid lump and granular formats engineered to optimize alloy steel melting and advanced casting applications.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Aditya Birla Management Corp.
- American Elements Inc.
- Arth Metallurgicals Pvt. Ltd.
- Asia Tungsten Products Ltd
- Chem Lab
- CRONIMET Holding GmbH
- Ganzhou CF Tungsten Co. Ltd
- Global Tungsten and Powders
- Grand Sea Tungsten Co. Ltd.
- Jainam Ferro Alloys (I) Ltd.
- Jayesh Group
- Jiangsu Lucky Metal Materials Ltd.
- Luoyang Youbo Metal Materials
- Metallic Ferro Alloys LLP
- Metallurgical Products India (P) Ltd.
- Plansee Holding AG
- Qingdao Hesiway Industrial Ltd
- Tungsten Metals Group Ltd.
- W.S. Tungsten Korea
- Xian Kefeng Powder Metallurgy Ltd
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Ferro tungsten market
- In the Steel industry, the transition toward electric arc furnace smelting has optimized thermal fatigue resistance, directly impacting Ferro Tungsten demand by accelerating the need for high impact wear plates in specialized recycling machinery, achieving a 15% reduction in overall processing waste.
- In the Steel industry, the enforcement of the carbon border adjustment mechanism has mandated fossil reductant substitution, directly impacting Ferro Tungsten demand by forcing smelters to integrate biogenic carbon alternatives to maintain compliance under the strict 25% emissions reduction threshold.
- In the Steel industry, the rapid deployment of continuous off gas recovery and dust agglomeration technologies has modernized production, directly impacting Ferro Tungsten demand by lowering the energy intensity of refractory master alloy production by 18%.
- In the Steel industry, the strategic implementation of bilateral offtake agreements for critical minerals has fortified supply chains, directly impacting Ferro Tungsten demand by encouraging friend shored intermediate conversion hubs that guarantee material availability for heavy tungsten alloys manufacturing with a 20% improvement in lead time reliability.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Ferro Tungsten Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 311 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 8.9% |
| Market growth 2026-2030 | USD 451409.7 thousand |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 8.2% |
| Key countries | China, Japan, India, South Korea, Australia, Indonesia, Germany, France, Italy, UK, Spain, The Netherlands, US, Mexico, Canada, Turkey, South Africa, Saudi Arabia, UAE, Israel, Brazil, Argentina and Colombia |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The evolving landscape of high performance metallurgy requires profound technical precision and continuous material optimization. Industrial processing facilities are systematically refining methodologies to synthesize master alloys with exceptional chemical consistency and minimal tramp impurities.
- This rigorous attention to elemental purity directly impacts the fabrication of industrial cutting tools, where precise additions drive the hardening phenomenon necessary to preserve performance during intense machining operations. In the demanding realm of aerospace component manufacturing, metalworkers utilize these refined inputs to actively prevent structural deformation in turbine assemblies operating under extreme thermal stress.
- The strategic integration of advanced automated furnace control architectures has revolutionized operational output, enabling advanced smelters to achieve a 22% improvement in energy efficiency over legacy batch melting systems. This measurable optimization fundamentally reshapes capital budgeting decisions, allowing specialized foundries to reallocate resources toward advanced product testing and defect mitigation.
- As mechanical tolerances tighten across modern manufacturing, the necessity for flawless alloy integration continues to guide long term industrial procurement strategies.
What are the Key Data Covered in this Ferro Tungsten Market Research and Growth Report?
-
What is the expected growth of the Ferro Tungsten Market between 2026 and 2030?
-
USD 451.41 million, at a CAGR of 8.9%
-
-
What segmentation does the market report cover?
-
The report is segmented by Product Type (Up to 75 percent tungsten, Between 75 to 80 percent tungsten, and Above 80 percent tungsten), End-user (Steel and metallurgy, Industrial machinery and tooling, Aerospace and defense, and Automotive), Application (High-speed steels, Tool steels, Specialty steels, Superalloys, and Aerospace alloys) and Geography (APAC, Europe, North America, Middle East and Africa, South America)
-
-
Which regions are analyzed in the report?
-
APAC, Europe, North America, Middle East and Africa and South America
-
-
What are the key growth drivers and market challenges?
-
Expanding utilization of high-speed steels and wear-resistant alloys in precision machining, Severe upstream supply concentration and escalating geopolitical trade interventions
-
-
Who are the major players in the Ferro Tungsten Market?
-
Aditya Birla Management Corp., American Elements Inc., Arth Metallurgicals Pvt. Ltd., Asia Tungsten Products Ltd, Chem Lab, CRONIMET Holding GmbH, Ganzhou CF Tungsten Co. Ltd, Global Tungsten and Powders, Grand Sea Tungsten Co. Ltd., Jainam Ferro Alloys (I) Ltd., Jayesh Group, Jiangsu Lucky Metal Materials Ltd., Luoyang Youbo Metal Materials, Metallic Ferro Alloys LLP, Metallurgical Products India (P) Ltd., Plansee Holding AG, Qingdao Hesiway Industrial Ltd, Tungsten Metals Group Ltd., W.S. Tungsten Korea and Xian Kefeng Powder Metallurgy Ltd
-
Market Research Insights
- The Ferro Tungsten Market undergoes constant refinement as specialty steelmakers adapt to stringent metallurgical requirements and raw material volatility. By integrating advanced secondary refining processes, manufacturers have optimized alloy dissolution, yielding a 12% improvement in total chemical homogeneity across structural steel batches. This precise microstructural control substantially reduces catastrophic part failure in high stress environments.
- Furthermore, industrial foundries are proactively executing diversified sourcing protocols to counteract severe financial strain caused by fluctuating upstream ore costs. These strategic sourcing adjustments have decreased material stockout incidents by 18%, allowing machining and tooling facilities to maintain uninterrupted output schedules for critical aerospace and automotive components without tying up excess liquidity.
We can help! Our analysts can customize this ferro tungsten market research report to meet your requirements.
 RIA -

