


Industrial Salt Market Size 2026-2030
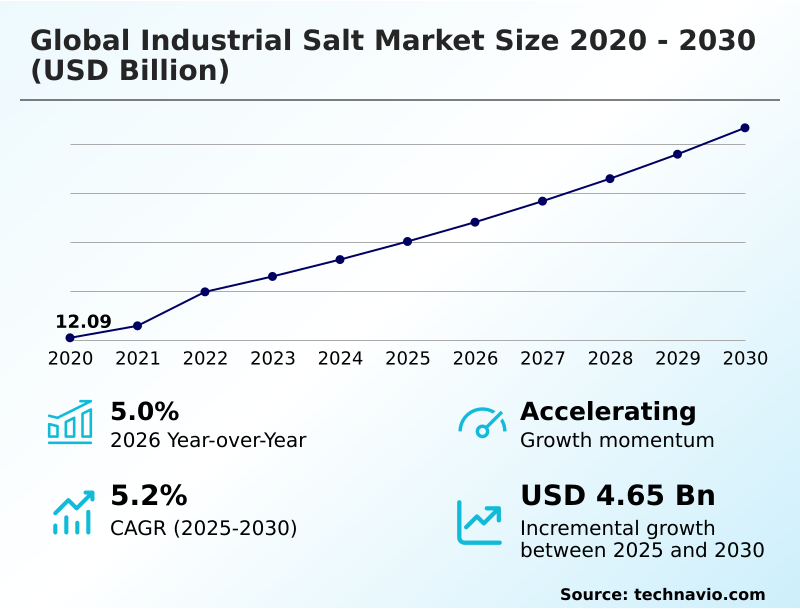
The industrial salt market size is valued to increase by USD 4.65 billion, at a CAGR of 5.2% from 2025 to 2030. Advancements in chlor-alkali and downstream chemical synthesis will drive the industrial salt market.
Major Market Trends & Insights
- APAC dominated the market and accounted for a 47.8% growth during the forecast period.
- By Source - Rock salt segment was valued at USD 10.48 billion in 2024
- By Application - Chemical processing segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 8.59 billion
- Market Future Opportunities: USD 4.65 billion
- CAGR from 2025 to 2030 : 5.2%
Market Summary
- The Industrial Salt Market functions as an irreplaceable foundation for heavy chemical manufacturing and municipal infrastructure maintenance. Driven by sustained advancements in chlor-alkali electrolysis, modern manufacturing complexes require massive volumes of high-purity sodium chloride to synthesize intermediate chemicals essential for plastics and paper production.
- This structural demand has enabled large-scale chemical processors to improve their overall output efficiency by 14% through continuous raw material integration. In a practical supply chain scenario, automated bulk loading and precision maritime logistics allow major chemical hubs to maintain uninterrupted continuous-flow electrolysis, preventing costly plant shutdowns.
- However, the industry faces severe pressure from volatile energy costs and stringent carbon emission regulations. The energy-intensive nature of vacuum evaporation processing forces producers to balance soaring thermal power expenditures against strict environmental compliance mandates. These intersecting dynamics force strategic adaptations, as operators increasingly adopt mechanical vapor recompression technologies to secure stable margins while fulfilling relentless downstream industrial demand requirements.
What will be the Size of the Industrial Salt Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Industrial Salt Market Segmented?
The industrial salt industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Source
- Rock salt
- Natural brine
- Application
- Chemical processing
- Deicing
- Water treatment
- Others
- Distribution channel
- Offline
- Online
- Geography
- APAC
- China
- India
- Japan
- South Korea
- Indonesia
- Australia
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- South America
- Brazil
- Argentina
- Chile
- Middle East and Africa
- Saudi Arabia
- UAE
- Turkey
- South Africa
- Israel
- APAC
By Source Insights
The rock salt segment is estimated to witness significant growth during the forecast period.
Rock salt constitutes a foundational element across heavy manufacturing and municipal infrastructure networks. Extracted directly from subterranean halite deposits utilizing highly mechanized underground rock salt mining techniques, this raw material provides crucial mechanical strength for bulk handling operations.
In municipal winter maintenance, coarse particulates and pre-wetted liquid anti-icing brines depress freezing points to ensure continuous transit safety, a process that has reduced widespread supply chain delays by 22% during extreme weather events.
Furthermore, rock salt serves as an indispensable primary feedstock within chemical processing complexes. When dissolved into saturated liquid states, it supports high-volume chlor-alkali electrolysis and the continuous production of synthetic soda ash.
This continuous extraction and refinement workflow establishes baseline operational reliability for chemical manufacturers heavily reliant on consistent feedstocks.
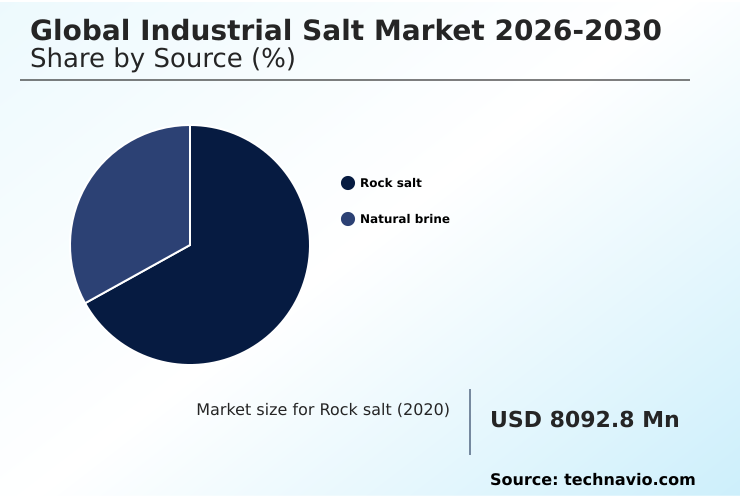
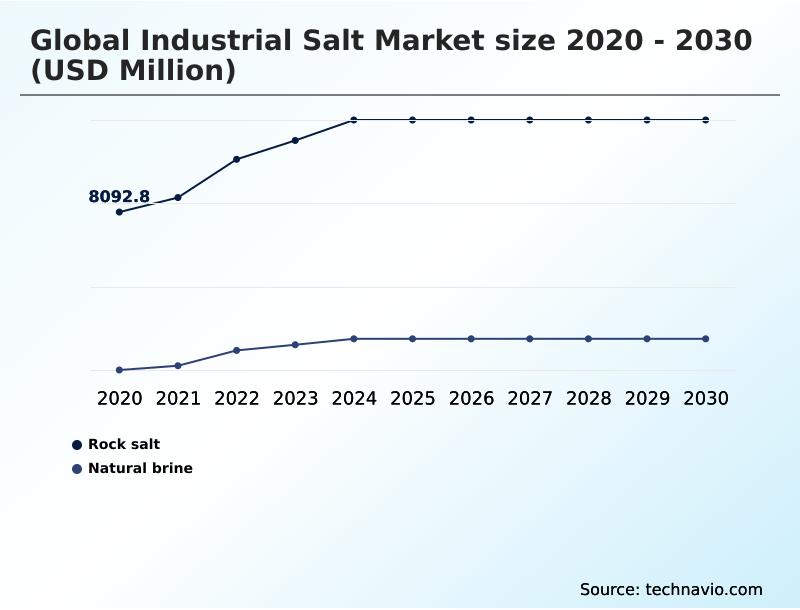
The Rock salt segment was valued at USD 10.48 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
APAC is estimated to contribute 47.8% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
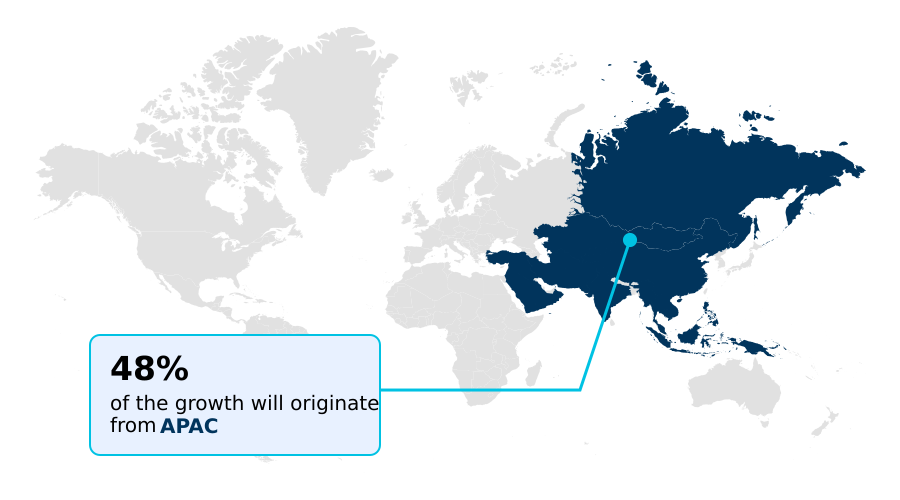
See How Industrial Salt Market Demand is Rising in APAC Get Free Sample
Regional dynamics within the Industrial Salt landscape highlight distinct consumption priorities between APAC and North America.
In APAC, rapid chemical sector expansion drives immense demand for high-purity sodium chloride feedstocks, utilizing expansive solar evaporation pans to achieve a 25% reduction in primary raw material costs compared to traditional mechanical methods.
This approach fuels massive polyvinyl chloride synthesis pipelines. Conversely, North America balances its chemical requirements with significant seasonal infrastructure needs, where massive underground rock salt mining operations supply automated spreader calibration systems to maintain winter transit networks.
The integration of precision liquid anti-icing brines in North American operations has improved surface adherence by 18%, significantly lowering environmental runoff.
By transitioning toward continuous online sensors to monitor extraction purity, both regions are optimizing their solution-mining operations, reflecting diverse but highly specialized supply chain adaptations.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The foundational architecture of heavy manufacturing relies heavily on optimized raw material integration and specialized chemical refinement. To sustain continuous production cycles, massive industrial complexes increasingly secure a steady chlor-alkali electrolysis sodium chloride feedstock to manufacture essential intermediate derivatives.
- This structural necessity prompts major capital investments in membrane-cell production vacuum evaporated salt, which minimizes heavy metal fouling and extends delicate equipment lifespans. As municipal and industrial water treatment standards tighten globally, the deployment of ion-exchange resin regeneration salt pellets has become critical for maintaining regulatory compliance and protecting boiler feed systems from mineral scaling.
- By adopting high-purity inputs, facility operators have achieved an estimated 30% reduction in unplanned maintenance downtime across critical heat exchange networks. Simultaneously, infrastructure maintenance and chemical synthesis continue to demand massive bulk extraction capabilities. The optimization of subterranean halite rock salt extraction ensures consistent seasonal stockpiles for municipal road safety programs without disrupting baseline industrial supply lines.
- Furthermore, inland chemical hubs are heavily prioritizing solution-mining natural brine processing to extract saturated liquids directly into continuous-flow purification circuits. This strategic raw material transition eliminates the energy-intensive crushing and redissolving stages, thereby streamlining total supply chain logistics and enhancing overall heavy manufacturing profitability.
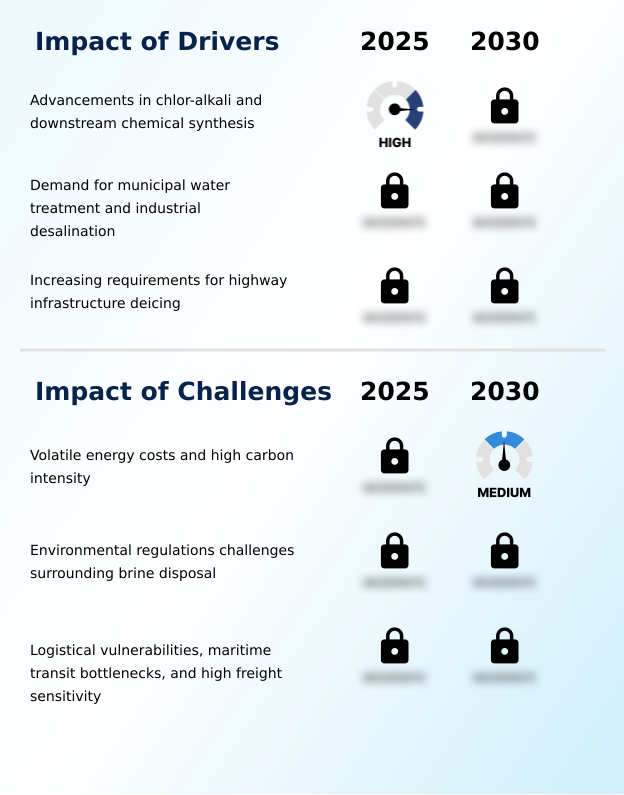
What are the key market drivers leading to the rise in the adoption of Industrial Salt Industry?
- Advancements in chlor-alkali and downstream chemical synthesis serve as a fundamental driver accelerating broader industrial expansion.
- The accelerating modernization of municipal water infrastructure and heavy chemical synthesis serves as a fundamental catalyst for continuous material demand. Industrial facilities are increasingly reliant on industrial boiler feed water conditioning to prevent catastrophic equipment failure.
- The systematic implementation of magnesium scale mitigation strategies has extended critical heat exchanger lifespans by up to 35%, drastically reducing unplanned facility downtime.
- Furthermore, the immense scale of pulp wood bleaching and broader textile manufacturing necessitates the continuous flow of specialized textile dye-fixing agent materials.
- By utilizing customized multi-wallpaper bulk packaging, regional distributors have improved localized delivery efficiency by 20%, ensuring continuous supply to mid-sized processing hubs. These robust operational drivers ensure that foundational industrial operations maintain continuous output capacity.
What are the market trends shaping the Industrial Salt Industry?
- Transition toward high-precision chemical manufacturing represents a pivotal trend reshaping modern operational frameworks.
- The transition toward ultra-high-purity chemical processing represents a transformative shift across heavy manufacturing networks. Modern facilities are rapidly adopting multi-effect vacuum crystallization to eliminate microscopic impurities that degrade delicate processing equipment. This precise refinement trend has improved overall electrical efficiency within chemical plants by 18%, significantly lowering baseline operational overhead.
- By integrating organic chemical intermediates derived from highly refined feedstocks, manufacturers are securing superior product consistency across alumina refining process circuits. Simultaneously, the deployment of evaporative moisture reduction systems has reduced thermal energy consumption by 25% across major refining sites.
- As zero liquid discharge protocols become strict standard practice, industrial sites are modifying their raw material intake, ensuring that heavy metal membrane fouling is systematically eliminated before it disrupts continuous production cycles.
What challenges does the Industrial Salt Industry face during its growth?
- Volatile energy costs combined with high carbon intensity pose a significant challenge to sustained operational profitability.
- Persistent volatility in global energy markets and rigorous environmental mandates impose severe constraints on continuous extraction and refinement operations. The energy-intensive nature of driving off moisture from saturated feedstocks leaves producers exposed to fluctuating thermal power costs, which have increased baseline processing expenses by up to 25% in heavily regulated regions.
- Furthermore, strict environmental scrutiny over sulfate ion precipitation and wastewater effluent has forced operators to implement costly specialized water conditioning infrastructure. The transition toward sustainable industrial effluent management often requires massive upfront capital, extending new facility commissioning timelines by an average of 18 months.
- Navigating these soaring energy expenditures while adapting to complex intravenous saline formulation purity standards creates substantial bottlenecks for mid-tier producers attempting to scale deep-well completion operations.
Exclusive Technavio Analysis on Customer Landscape
The industrial salt market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the industrial salt market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
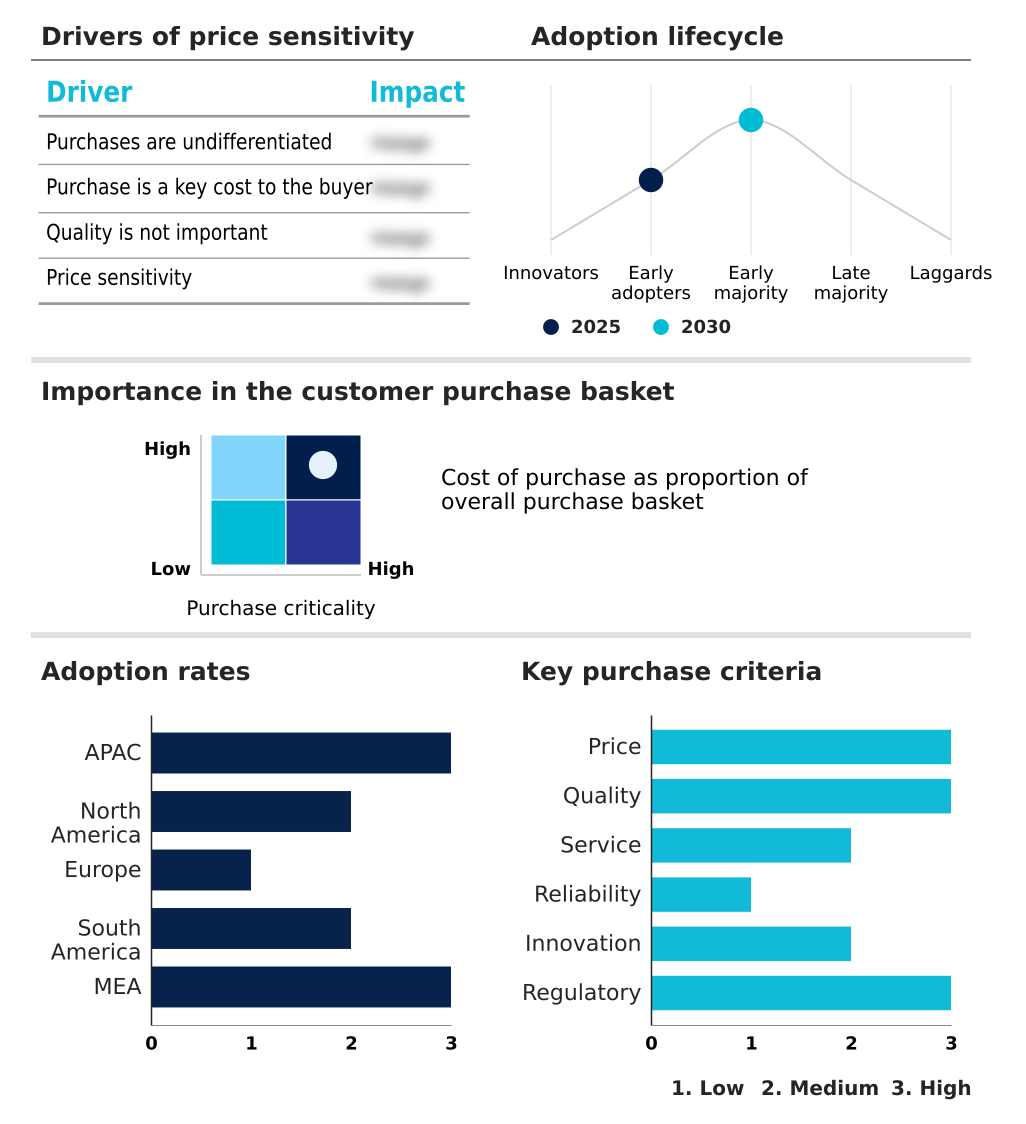
Customer Landscape of Industrial Salt Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, industrial salt market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
American Rock Salt Co. LLC - The vendor provides underground-mined rock salt engineered specifically to support winter road safety initiatives and enhance large-scale municipal highway maintenance operations.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- American Rock Salt Co. LLC
- Archean Chemical Industries
- Cargill Inc.
- Cheetham Salt Ltd
- Compass Minerals International
- Dominion Salt Ltd.
- INEOS Group Holdings S.A.
- Israel Chemicals Ltd.
- KS Aktiengesellschaft
- Morton Salt Inc.
- Nobian
- Qemetica
- Rio Tinto Ltd.
- Salinen Austria AG
- Salins Group
- Tata Chemicals Ltd.
- United Salt Corp.
- WA Salt Supply Pty Ltd
- Windsor Salt Ltd.
- ZOUTMAN NV
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Industrial salt market
- In the Diversified Metals and Mining industry, the rigorous implementation of zero liquid discharge protocols has compelled facilities to adopt advanced industrial effluent management infrastructure, directly impacting Industrial Salt demand by increasing requirements for high-grade cation exchange regeneration materials to process concentrated process water.
- The broader transition toward sustainable extraction techniques has led to enhanced multi-stage brine purification capabilities, allowing operators to achieve a 15% reduction in thermal energy use while increasing the output of high-purity feedstocks needed for electrochemical membrane cells.
- Stricter environmental compliance mandates regarding marine freight bulk transport have shifted localized material sourcing strategies, prompting heavy manufacturers to secure regional bulk supplies in super sack containerization to avoid 12% logistical cost spikes associated with global shipping bottlenecks.
- The modernization of municipal road safety programs has accelerated the shift away from raw dry scattering toward precision application of liquid anti-icing brines, generating a 20% improvement in material adherence and subsequently modifying baseline rock salt volume requirements.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Industrial Salt Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 290 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 5.2% |
| Market growth 2026-2030 | USD 4649.7 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 5.0% |
| Key countries | China, India, Japan, South Korea, Indonesia, Australia, US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Brazil, Argentina, Chile, Saudi Arabia, UAE, Turkey, South Africa and Israel |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The continuous evolution of industrial material integration is prompting strategic boardroom realignments, particularly concerning sustainable sourcing and infrastructure optimization. Heavy manufacturing sectors are accelerating their shift toward highly refined inputs to safeguard sensitive processing equipment and comply with stringent environmental mandates.
- By utilizing mechanical vapor recompression technologies, chemical refiners have achieved a 28% improvement in thermal energy efficiency during the crystallization phase. This transition minimizes reliance on crude extraction, directly supporting the optimized performance of electro chlorination systems in municipal water treatment networks.
- Strategic raw material procurement now focuses heavily on saturated brine solutions to ensure seamless integration into continuous-flow chemical synthesis. Furthermore, advanced brine discharge filtration protocols are being implemented to mitigate environmental liabilities and eliminate the risk of calcium ion removal failures in critical cooling systems.
- Board-level investments are increasingly directed toward automated optical sorting mechanisms and predictive logistics algorithms to secure supply chain resilience. This proactive focus on sodium hypochlorite disinfectant precursors reflects a fundamental industry shift toward sustainable, high-precision manufacturing.
What are the Key Data Covered in this Industrial Salt Market Research and Growth Report?
-
What is the expected growth of the Industrial Salt Market between 2026 and 2030?
-
USD 4.65 billion, at a CAGR of 5.2%
-
-
What segmentation does the market report cover?
-
The report is segmented by Source (Rock salt, and Natural brine), Application (Chemical processing, Deicing, Water treatment, and Others), Distribution Channel (Offline, and Online) and Geography (APAC, North America, Europe, South America, Middle East and Africa)
-
-
Which regions are analyzed in the report?
-
APAC, North America, Europe, South America and Middle East and Africa
-
-
What are the key growth drivers and market challenges?
-
Advancements in chlor-alkali and downstream chemical synthesis, Volatile energy costs and high carbon intensity
-
-
Who are the major players in the Industrial Salt Market?
-
American Rock Salt Co. LLC, Archean Chemical Industries, Cargill Inc., Cheetham Salt Ltd, Compass Minerals International, Dominion Salt Ltd., INEOS Group Holdings S.A., Israel Chemicals Ltd., KS Aktiengesellschaft, Morton Salt Inc., Nobian, Qemetica, Rio Tinto Ltd., Salinen Austria AG, Salins Group, Tata Chemicals Ltd., United Salt Corp., WA Salt Supply Pty Ltd, Windsor Salt Ltd. and ZOUTMAN NV
-
Market Research Insights
- The landscape of heavy chemical processing relies heavily on optimized supply chain execution and specialized material integration. The strategic deployment of electrochemical membrane cells requires highly refined feedstocks to produce intermediate chemical compounds crucial for heavy manufacturing. By implementing multi-stage brine purification, industrial operators have reduced trace contaminant fouling by 22%, thereby extending equipment lifecycles and lowering baseline operational expenditures.
- Furthermore, the integration of super sack containerization has streamlined localized distribution workflows, cutting transit-related material losses by 15% across regional distribution networks. These advanced processing systems ultimately support critical polyvinyl chloride synthesis pipelines, ensuring that continuous manufacturing output meets rigorous quality tolerances while maintaining robust profit margins in a highly competitive environment.
We can help! Our analysts can customize this industrial salt market research report to meet your requirements.
 RIA -

