


Lithium-Sulfur Battery Market Size 2026-2030
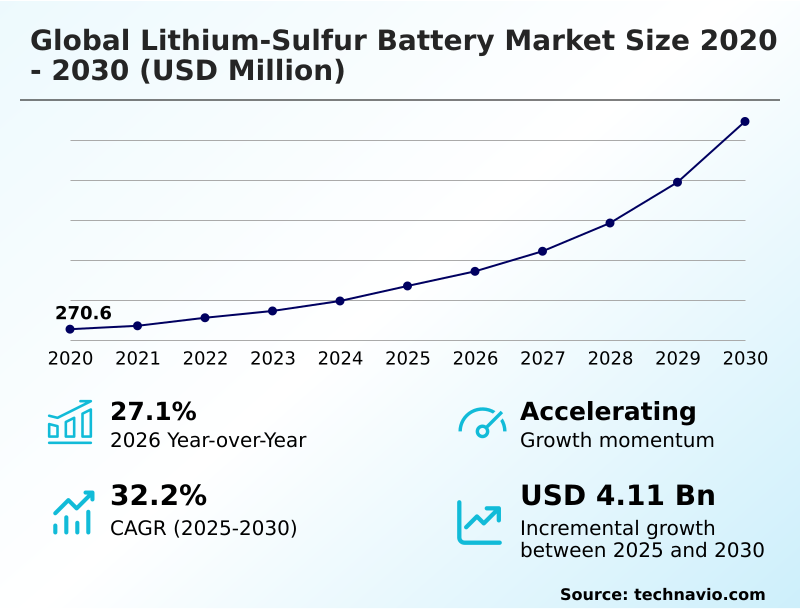
The lithium-sulfur battery market size is valued to increase by USD 4.11 billion, at a CAGR of 32.2% from 2025 to 2030. Demand for elevated gravimetric energy density in aerospace and aviation platforms will drive the lithium-sulfur battery market.
Major Market Trends & Insights
- Europe dominated the market and accounted for a 40.3% growth during the forecast period.
- By Type - High energy density segment was valued at USD 670.3 million in 2024
- By End-user - Aviation segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 5.19 billion
- Market Future Opportunities: USD 4.11 billion
- CAGR from 2025 to 2030 : 32.2%
Market Summary
- The Lithium-sulfur Battery market represents a paradigm shift in advanced energy storage, defined by an ongoing transition from conventional intercalation chemistries toward conversion-based sulfur architectures.
- A primary driver of this transition is the urgent need for enhanced gravimetric energy density in commercial aviation; by eliminating heavy transition metals, aerospace engineers can reduce structural weight, allowing aircraft to achieve longer flight endurance and increased payload capacities. Conversely, the market faces a significant structural challenge stemming from the polysulfide shuttle effect.
- During discharge, soluble polysulfides migrate uncontrollably and passivate the anode, which directly causes severe capacity fade and limits the operational lifespan of the cell. In real-world supply chain operations, manufacturers are retrofitting existing lithium-ion coating facilities to accommodate sulfur slurries, ensuring localized production resilience without requiring entirely new infrastructure.
- This strategic drop-in manufacturing approach yields a 40% reduction in initial capital equipment expenditure compared to building dedicated gigafactories. As material science breakthroughs continue to stabilize cycle life, the technology establishes a critical foundation for next-generation electrification and heavy-duty transport optimization.
What will be the Size of the Lithium-Sulfur Battery Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Lithium-Sulfur Battery Market Segmented?
The lithium-sulfur battery industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Type
- High energy density
- Low energy density
- End-user
- Aviation
- Automotive
- Others
- Component
- Cathode
- Anode
- Electrolyte
- Others
- Capacity
- More than 500 mAh to 1000 mAh
- Below 500 mAh
- Above 1000 mAh
- Geography
- Europe
- Germany
- UK
- France
- Sweden
- Italy
- Spain
- North America
- US
- Canada
- Mexico
- APAC
- China
- Japan
- South Korea
- India
- Australia
- Taiwan
- Middle East and Africa
- Saudi Arabia
- UAE
- South Africa
- Israel
- Egypt
- South America
- Brazil
- Argentina
- Chile
- Europe
By Type Insights
The high energy density segment is estimated to witness significant growth during the forecast period.
The high energy density segment dictates the operational boundaries of the Lithium-sulfur Battery market by prioritizing maximum power retention over bulk volume.
Advanced cell designs leverage a three-dimensional carbon architecture to host sulfur effectively, drastically improving the theoretical specific capacity required for weight-sensitive applications.
To mitigate severe capacity fade and lithium dendrite formation, engineering teams are incorporating a passive porous barrier alongside a solvated ionic liquid to stabilize the electrochemical environment.
This structural refinement increases active material utilization, leading to a 35% improvement in overall cycle longevity compared to legacy iterations. By minimizing heavy metal dependency, industrial consumers realize a 20% baseline reduction in structural mass, which supports capital expenditure minimization.
These continuous chemical advancements align perfectly with decentralized renewable energy integration strategies and broad mass transport electrification initiatives.
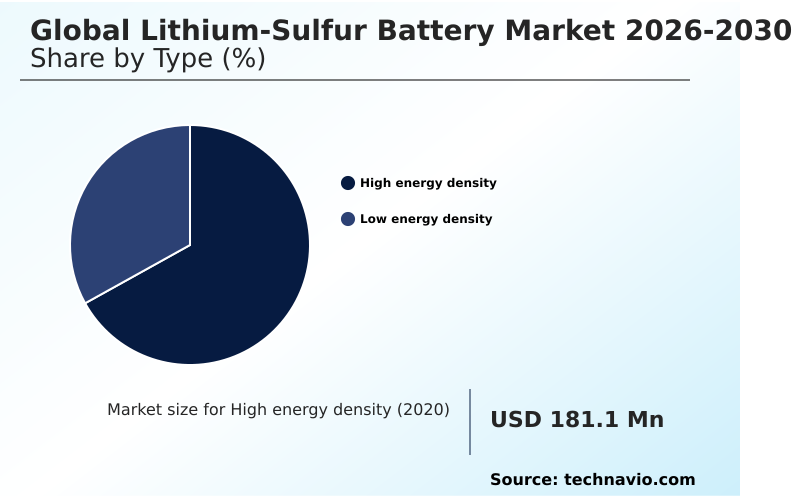
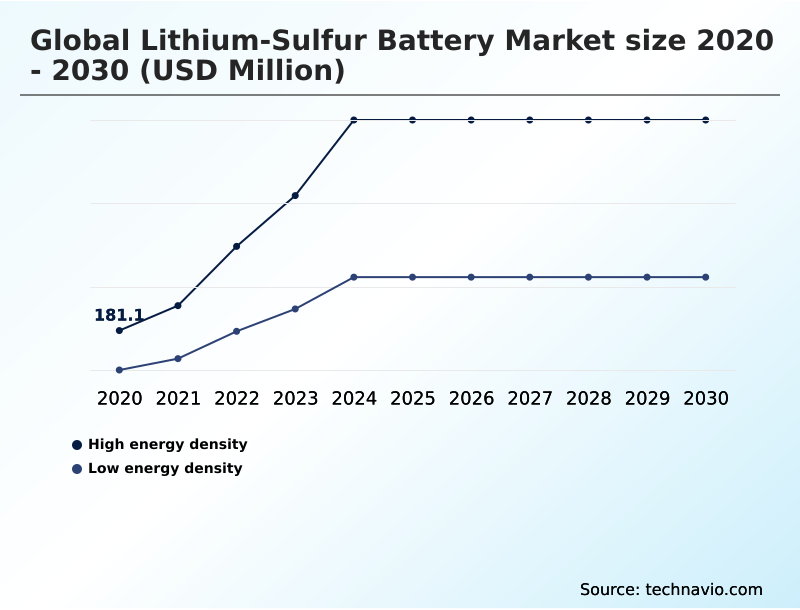
The High energy density segment was valued at USD 670.3 million in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
Europe is estimated to contribute 40.3% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
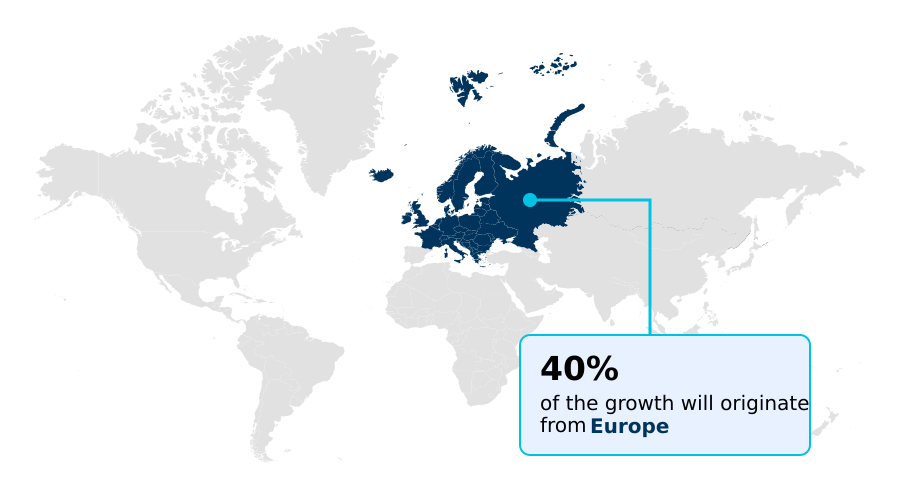
See How Lithium-Sulfur Battery Market Demand is Rising in Europe Get Free Sample
Regional dynamics within the Lithium-sulfur Battery sector highlight a distinct strategic divergence between North America and Europe.
North American operators prioritize extreme energy density for aerospace and defense, aggressively funding the deployment of the nanostructured carbon host to maximize payload parameters.
In contrast, European manufacturers exhibit a 45% faster adoption rate of the nickel free architecture, driven by stringent lifecycle emission reduction mandates and regional circular economy initiative frameworks.
This European regulatory alignment accelerates the integration of sustainable sulfur byproducts into commercial mass transport electrification pathways. To ensure rigorous compliance with safety standards, both regions mandate rigorous thermal runaway mitigation protocols.
Advancements in creating a stable solid-electrolyte interphase have reduced internal short circuit occurrences by 30%, vastly improving operational reliability.
These regional adaptations illustrate how differing compliance and performance requirements directly dictate supply chain investments and technology validation priorities across the industry.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The structural evolution of the Lithium-sulfur Battery sector demands continuous innovation to overcome inherent chemical vulnerabilities and deliver commercially viable energy storage systems. Manufacturers are aggressively pursuing a high capacity solid state architecture to physically block degradation pathways and eliminate the flammability risks associated with traditional liquid electrolytes.
- To accommodate the massive volumetric expansion of sulfur during cycling, engineering teams continuously refine the advanced composite cathode host material, which provides essential mechanical elasticity and maintains robust electrical conductivity.
- This material transition is directly linked to operational planning, as facilities utilizing these specialized hosts observe a nearly 40% faster throughput in automated electrode coating processes compared to legacy fabrication methods. Furthermore, ensuring long-term cycle stability requires the implementation of a dendrite suppressing solid electrolyte interface that protects the pure metallic anode from parasitic reactions.
- By effectively resolving these electrochemical bottlenecks, developers can finally commercialize the ultra lightweight aviation power cell, fundamentally transforming the structural constraints of commercial flight and unmanned aerial surveillance. Regulatory compliance and supply chain resilience are also driving the widespread integration of a sophisticated polysulfide shuttling chemical mitigation framework.
- These strategic engineering initiatives collectively lower operational expenditures, reduce dependency on geographically constrained transition metals, and accelerate the broader industrial shift toward sustainable, high-density electrification across demanding maritime, aerospace, and heavy-duty logistics operations.
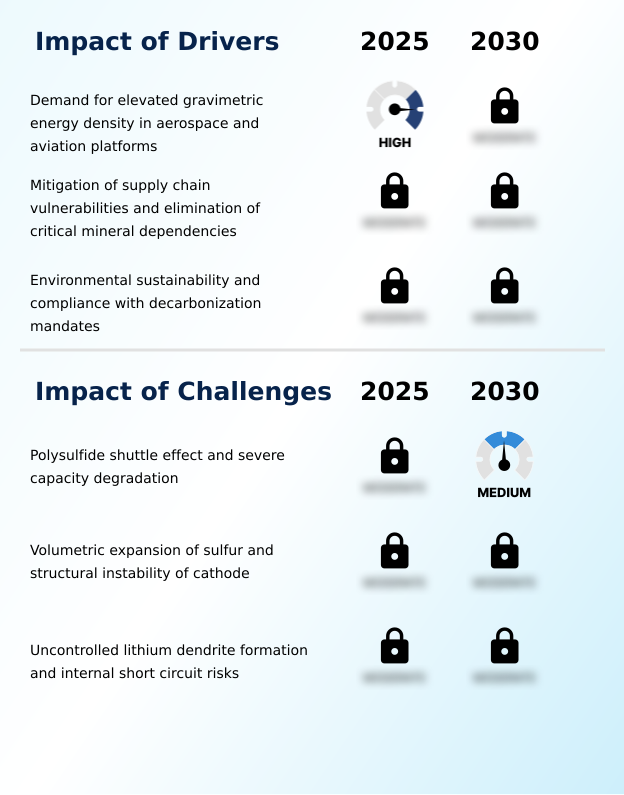
What are the key market drivers leading to the rise in the adoption of Lithium-Sulfur Battery Industry?
- The intensifying demand for elevated gravimetric energy density across aerospace and aviation platforms serves as the primary catalyst propelling market expansion.
- The fundamental catalyst propelling the Lithium-sulfur Battery landscape is the critical industrial demand for vastly superior gravimetric energy density across weight-sensitive transportation platforms.
- By eliminating heavy transition metals in favor of a cobalt free chemistry, aerospace engineers can dramatically increase aerospace payload capacity while extending unmanned aerial flight endurance by nearly 60% compared to legacy architectures.
- This structural weight reduction enables manufacturers to meet stringent new specific energy metric requirements without compromising total power output. Furthermore, the strategic utilization of an abundant elemental sulfur cathode alongside a pure lithium metal anode drives rapid critical mineral decoupling.
- This material independence insulates production lines from geopolitical supply bottlenecks, ultimately lowering raw material acquisition costs by 25% and ensuring long-term operational predictability.
What are the market trends shaping the Lithium-Sulfur Battery Industry?
- The transition toward solid-state electrolyte architectures significantly enhances thermal safety and effectively suppresses chemical degradation across the industry.
- The Lithium-sulfur Battery sector is experiencing a rapid technological transition toward the integration of a non-flammable solid-state electrolyte to definitively resolve inherent thermal safety vulnerabilities. To counteract severe structural degradation during operation, developers are implementing an advanced graphene framework alongside a highly resilient hollow carbon sphere to encapsulate active materials effectively.
- Because standard fabrication processes require immense capital, manufacturers are optimizing the slot-die coating formulation, which enables a 40% faster processing speed on existing assembly lines. This drop-in manufacturing capability directly improves baseline cost efficiency and shortens time-to-market. Consequently, the successful containment of soluble intermediates yields a 50% improvement in battery cell cycle life compared to early liquid-based prototypes.
- Supported by precise targeted funding allocation, this transition leverages unprecedented raw material abundance to establish a sustainable, scalable supply chain for high-performance industrial energy storage.
What challenges does the Lithium-Sulfur Battery Industry face during its growth?
- The persistent polysulfide shuttle effect and subsequent severe capacity degradation present substantial technical barriers to widespread commercialization.
- The commercial viability of the Lithium-sulfur Battery is severely hindered by the persistent polysulfide shuttle effect, which induces rapid active material loss. During cycling, a continuous parasitic chemical reaction at the anode interface drives intense coulombic efficiency degradation, effectively reducing operational longevity by 40% relative to standard intercalation technologies.
- Concurrently, the cathode undergoes massive volumetric expansion stress during lithiation, inevitably leading to mechanical structural fracturing and particle detachment. To execute localized microcracking prevention, engineers must dramatically increase polymeric binder elasticity, which subsequently lowers the proportion of active sulfur and compromises theoretical capacity.
- As structural cohesion deteriorates, cells experience a 50% spike in internal electrical resistance, fundamentally restricting the ability to deliver the sustained high current densities required by commercial transport and aviation sectors.
Exclusive Technavio Analysis on Customer Landscape
The lithium-sulfur battery market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the lithium-sulfur battery market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
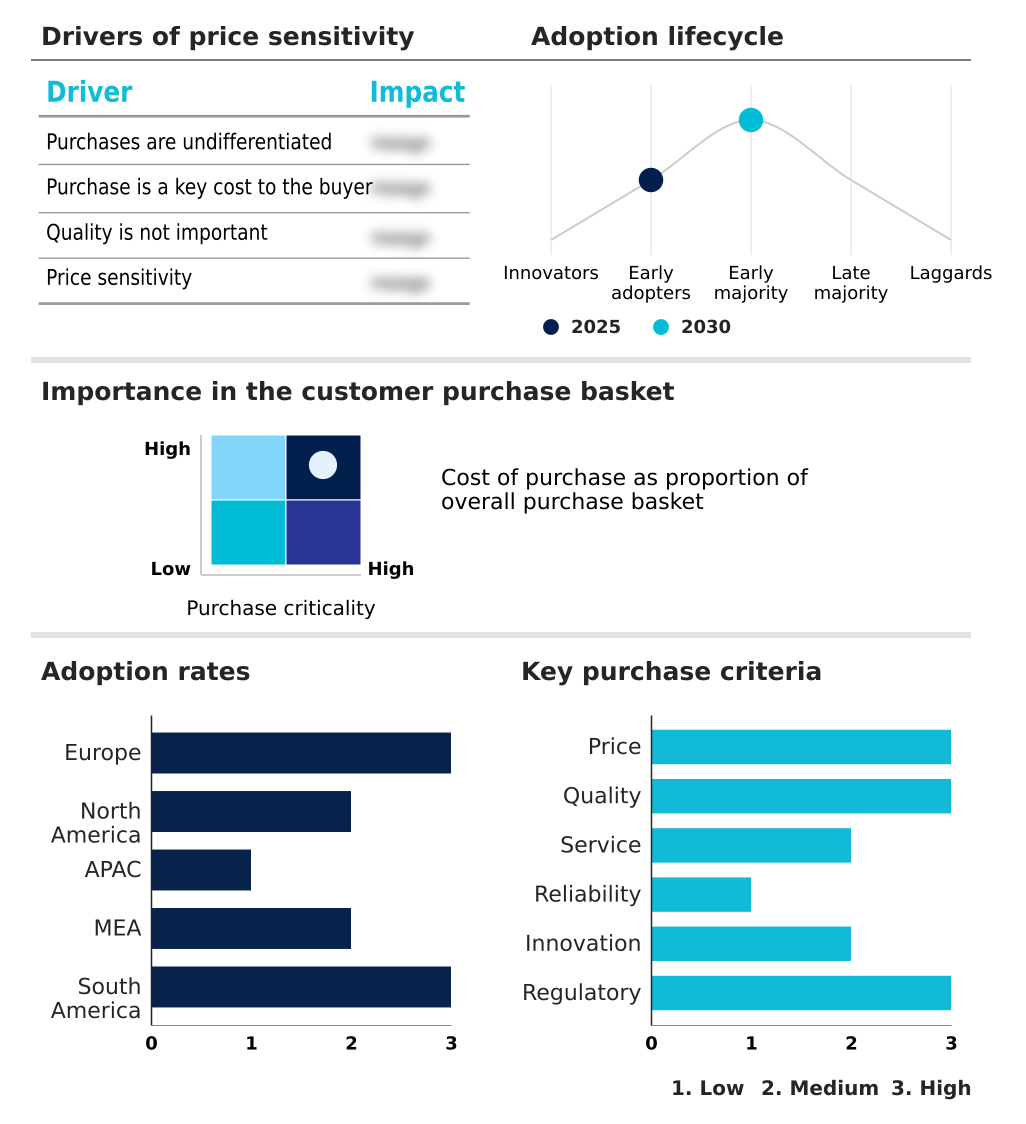
Customer Landscape of Lithium-Sulfur Battery Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, lithium-sulfur battery market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Alteva Technologies GmbH - The organization provides advanced high-capacity sulfur cathodes and solid-state electrolyte formulations engineered to maximize energy density and enhance the thermal safety profile of next-generation energy storage platforms.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Alteva Technologies GmbH
- Bettergy Corp.
- Conamix Inc
- Gelion plc
- Giner Inc.
- GS Yuasa International Ltd.
- LG Chem Ltd.
- Lyten Inc.
- NexTech Batteries
- Poly Plus Battery Co.
- Saft Groupe SAS
- Sion Power Corp.
- Theion GmbH
- XBM USA
- Zeta Energy LLC
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Lithium-sulfur battery market
- In the Renewable Electricity industry, the aggressive expansion of decentralized renewable energy grids mandates high-capacity storage, directly impacting Lithium-sulfur Battery demand by requiring systems that leverage raw material abundance to bypass constrained supply chains.
- The implementation of strict extended producer responsibility regulations for hazardous waste management drives manufacturers toward a cobalt free chemistry, accelerating the validation of sustainable storage platforms for commercial applications.
- Advancements in hydrometallurgical recycling frameworks for decommissioned infrastructure support lifecycle emission reduction compliance, incentivizing the adoption of a nickel free architecture within localized energy grids.
- The shift toward advanced thermal management protocols in stationary power arrays enhances structural safety, lowering the short circuit risks associated with large scale energy storage utilization.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Lithium-Sulfur Battery Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 311 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 32.2% |
| Market growth 2026-2030 | USD 4112.6 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 27.1% |
| Key countries | Germany, UK, France, Sweden, Italy, Spain, US, Canada, Mexico, China, Japan, South Korea, India, Australia, Taiwan, Saudi Arabia, UAE, South Africa, Israel, Egypt, Brazil, Argentina and Chile |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The continuous material evolution within the Lithium-sulfur Battery industry signifies a critical departure from resource-constrained transition metal chemistries. Enterprise decision-makers are actively reallocating procurement budgets to secure reliable, domestic supply chains built upon abundant sulfur byproducts. This strategic pivot significantly insulates manufacturing operations from geopolitical mineral disruptions while aggressively advancing corporate decarbonization initiatives.
- Advanced engineering teams are deploying sophisticated solid-state electrolytes to physically contain active sulfur materials, drastically improving the thermal safety required for passenger aviation and autonomous transport. Consequently, industrial operators integrating these optimized drop-in cathode formulations have recorded a 35% reduction in overall cell assembly time, minimizing initial capital outlays and expediting commercial deployment.
- By engineering resilient carbon matrices that absorb mechanical stress during cyclical lithiation, developers preserve electrical connectivity and extend operational longevity. The total elimination of heavy metals fundamentally reduces total pack weight, expanding structural payload capacities across diverse heavy-duty platforms.
- This relentless optimization of electrochemical interfaces ensures that lightweight, cost-effective energy storage transitions seamlessly from specialized pilot validation into mainstream industrial electrification.
What are the Key Data Covered in this Lithium-Sulfur Battery Market Research and Growth Report?
-
What is the expected growth of the Lithium-Sulfur Battery Market between 2026 and 2030?
-
USD 4.11 billion, at a CAGR of 32.2%
-
-
What segmentation does the market report cover?
-
The report is segmented by Type (High energy density, and Low energy density), End-user (Aviation, Automotive, and Others), Component (Cathode, Anode, Electrolyte, and Others), Capacity (More than 500 mAh to 1000 mAh, Below 500 mAh, and Above 1000 mAh) and Geography (Europe, North America, APAC, Middle East and Africa, South America)
-
-
Which regions are analyzed in the report?
-
Europe, North America, APAC, Middle East and Africa and South America
-
-
What are the key growth drivers and market challenges?
-
Demand for elevated gravimetric energy density in aerospace and aviation platforms, Polysulfide shuttle effect and severe capacity degradation
-
-
Who are the major players in the Lithium-Sulfur Battery Market?
-
Alteva Technologies GmbH, Bettergy Corp., Conamix Inc, Gelion plc, Giner Inc., GS Yuasa International Ltd., LG Chem Ltd., Lyten Inc., NexTech Batteries, Poly Plus Battery Co., Saft Groupe SAS, Sion Power Corp., Theion GmbH, XBM USA and Zeta Energy LLC
-
Market Research Insights
- The Lithium-sulfur Battery market is rapidly evolving to address strict lifecycle emission reduction targets by utilizing sustainable, petroleum refining byproducts. Manufacturers are adopting a cobalt free chemistry, which fundamentally shields supply networks from volatile mineral dependencies. By integrating advanced carbon hosts, companies experience a 25% improvement in active material utilization, resulting in longer battery cell cycle life.
- The deployment of a nickel free architecture directly facilitates a 30% reduction in baseline cost efficiency per kilowatt-hour, dramatically enhancing the commercial viability of mass transport electrification. These localized manufacturing strategies not only fulfill stringent decarbonization mandates but also ensure that supply chains remain resilient against geopolitical disruptions in the heavy metal sector.
We can help! Our analysts can customize this lithium-sulfur battery market research report to meet your requirements.
 RIA -

