
Space-Based Missile Tracking Sensor Systems Market Size and Growth Forecast 2026-2030
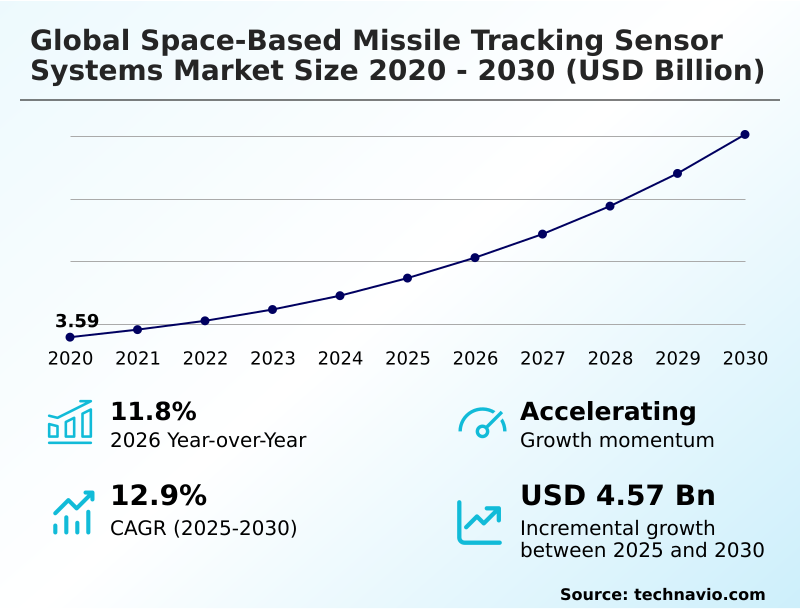
The Space-Based Missile Tracking Sensor Systems Market size was valued at USD 5.47 billion in 2025 growing at a CAGR of 12.9% during the forecast period 2026-2030.
North America accounts for 43% of incremental growth during the forecast period. The Infrared sensors segment by Type was valued at USD 3.15 billion in 2024, while the Satellites segment holds the largest revenue share by Platform.
The market is projected to grow by USD 6.44 billion from 2020 to 2030, with USD 4.57 billion of the growth expected during the forecast period of 2025 to 2030.
Get Key Insights on Market Forecast (PDF) Request Free Sample
Space-Based Missile Tracking Sensor Systems Market Overview
The space-based missile tracking sensor systems market is undergoing a fundamental transformation, driven by the need for persistent surveillance of hypersonic threats. North America accounts for 43% of the market opportunity, with an overall year-over-year growth of 11.8% reflecting the urgency of modernizing legacy early warning systems. This involves a strategic shift from large, geostationary orbit platforms to resilient, proliferated architecture in low earth orbit, leveraging standardized satellite bus designs. A key operational scenario involves a network of satellites using inter-satellite laser links to pass tracking data on a non-ballistic threat, maintaining custody from boost phase tracking to the terminal phase. Within this missile defense architecture, onboard edge computing with radiation-hardened electronics executes neural network calculations to perform real-time target discrimination against atmospheric clutter. This sensor-to-shooter loop, governed by standards like the Open Mission Systems (OMS), enables automated command and control systems to receive fire-control quality data, drastically reducing response times for national security.
Drivers, Trends, and Challenges in the Space-Based Missile Tracking Sensor Systems Market
The strategic shift toward next-generation overhead persistent infrared (OPIR) systems is fundamentally reshaping procurement priorities. The high cost of maintaining GEO-based platforms has accelerated the adoption of proliferated warfighter space architecture, with tracking layer tranche development becoming a central focus.
This involves deploying hundreds of interconnected satellites in LEO, a move that requires rigorous adherence to space traffic management protocols outlined by organizations like the U.S. Space Command to avoid orbital debris.
A key operational consideration is the reduced lifespan of LEO assets—typically 5-7 years compared to over 15 for GEO satellites—necessitating a continuous production and launch cycle for constellation replenishment. This makes the trade-off between small satellite cost vs capability a critical factor in program planning.
For example, a defense agency might leverage commercial satellite bus for defense payloads to reduce upfront CAPEX, integrating its proprietary HBTSS sensor for tracking hypersonic threats.
The architecture's success hinges on secure cross-link communication protocols for on-orbit data processing for threat detection and multi-domain command and control integration, ensuring that data from the resilient LEO constellation for missile tracking provides a tactical advantage.
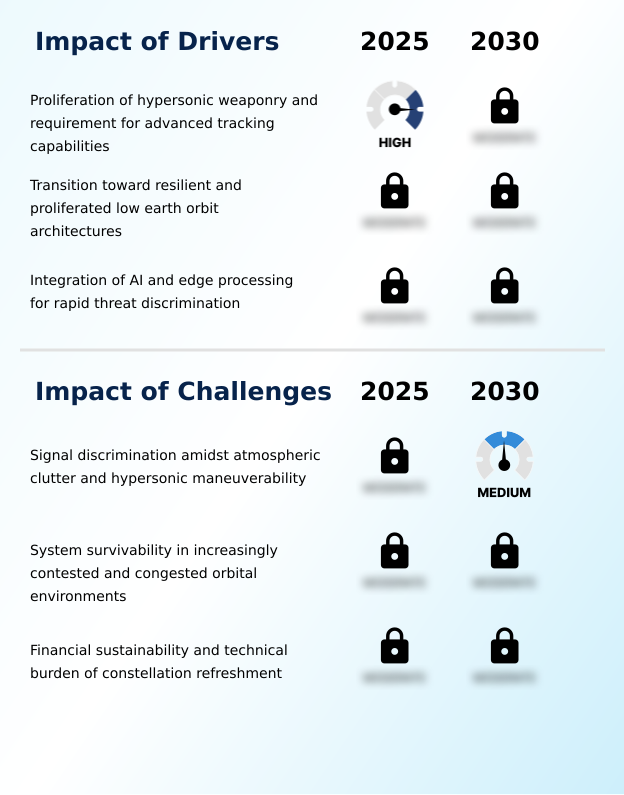
Primary Growth Driver: The proliferation of hypersonic weaponry and the subsequent requirement for advanced tracking capabilities are the primary drivers of market growth for space-based sensor systems.
The primary market driver is the proliferation of advanced non-ballistic threats, particularly hypersonic glide vehicles, which render traditional terrestrial radars ineffective.
This has created an urgent need for space-based sensor payloads that provide a persistent, top-down view for early warning and trajectory prediction.
The strategic shift to multi-layered satellite constellations in low earth orbit (LEO) and medium earth orbit (MEO) is a direct consequence.
Furthermore, the integration of artificial intelligence for on-orbit data fusion and edge computing is essential for reducing the sensor-to-shooter loop.
This technological push is framed by international control regimes like the MTCR, which influence the export and development of dual-use technology critical for these advanced command and control systems.
Emerging Market Trend: The market is evolving toward the use of multi-spectral imaging and hypersonic-specific infrared payloads. This shift aims to enhance target discrimination and provide fire-control quality data against advanced atmospheric threats.
A defining trend is the move toward proliferated architectures in low earth orbit, leveraging smaller, interconnected satellites to form a resilient sensor mesh. This approach, which is becoming standard under frameworks like the Proliferated Warfighter Space Architecture, allows for greater survivability against anti-satellite measures and facilitates more frequent technology refreshes.
This evolution utilizes multi-spectral sensors and advanced infrared sensors to achieve fire-control quality data on dim, maneuvering targets. The integration of autonomous in-orbit processing capabilities, enabled by AI-driven signal processing, allows these satellite constellations to perform threat discrimination at the edge.
This reduces latency and the data burden on ground stations, a critical advantage for tracking time-sensitive hypersonic glide vehicles and ensuring persistent surveillance across global hotspots.
Key Industry Challenge: A key market challenge is achieving reliable signal discrimination to track highly maneuverable hypersonic targets amidst the complex thermal background of atmospheric clutter.
A significant challenge is the technical difficulty of signal processing required for threat discrimination against the complex thermal background of atmospheric clutter. This is compounded by the need for system survivability in an increasingly congested and contested low earth orbit, where orbital debris and anti-satellite measures pose constant risks.
The financial burden of maintaining a proliferated architecture presents another hurdle; the shorter lifespan of LEO satellites necessitates a continuous and costly replenishment cycle.
This strains defense budgets and creates supply chain pressures for specialized components like radiation-hardened electronics and advanced cryocoolers for the focal plane array, impacting long-term financial sustainability and the pace of technological upgrades for the entire missile defense architecture.
Explore Full Market Dynamics Analysis Request Free Sample
Space-Based Missile Tracking Sensor Systems Market Segmentation
The space-based missile tracking sensor systems industry research report provides comprehensive data including region-wise segment analysis, with forecasts and analysis for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
Type Segment Analysis
The infrared sensors segment is estimated to witness significant growth during the forecast period.
Infrared sensors represent the primary technology segment, accounting for a significant portion of the market with a share of over 64%.
These systems are foundational for boost phase tracking of ballistic missiles and detecting the thermal signatures of hypersonic glide vehicles.
The technology is evolving beyond simple thermal detection to advanced multi-spectral sensors, incorporating mid-wave and long-wave infrared capabilities for enhanced target discrimination against atmospheric clutter.
Development is concentrated on high-sensitivity focal plane array technologies and advanced cryocoolers to reduce thermal noise, a critical factor for identifying dimmer thermal signatures from orbital platforms.
These sensor payloads, integrated into satellite constellations, provide the persistent surveillance necessary for modern missile defense architecture, ensuring fire-control quality data is relayed to ground segment support for effective threat neutralization.
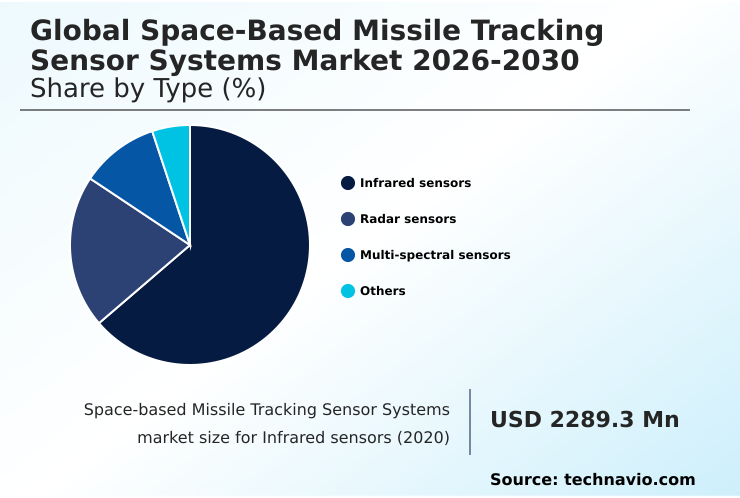
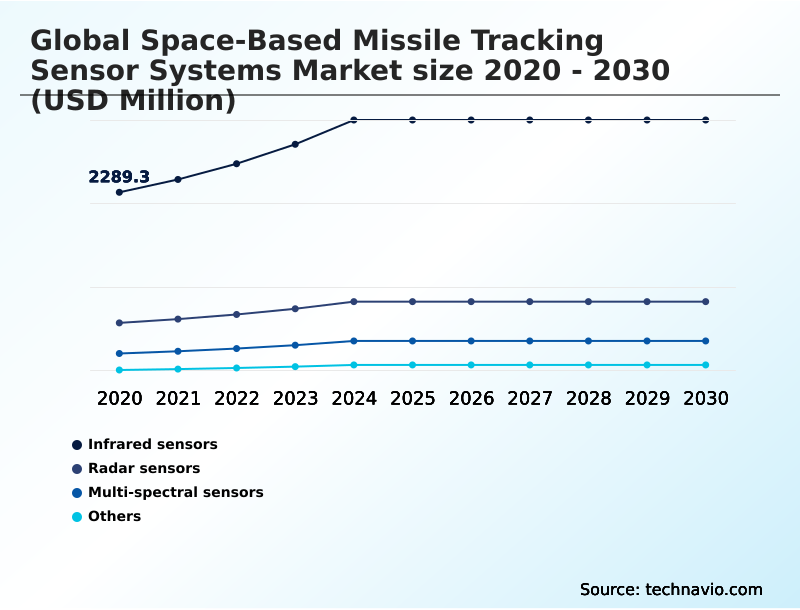
The Infrared sensors segment was valued at USD 3.15 billion in 2024 and showed a gradual increase during the forecast period.
Space-Based Missile Tracking Sensor Systems Market by Region: North America Leads with 43% Growth Share
North America is estimated to contribute 43% to the growth of the global market during the forecast period.
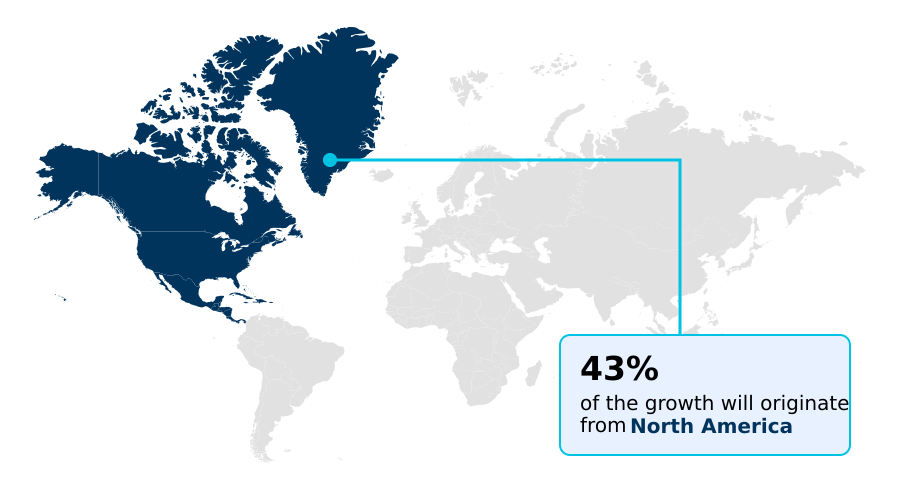
The geographic landscape is dominated by North America, which represents 43% of the incremental growth, driven by investments in next-generation OPIR and proliferated warfighter space architecture.
Europe, contributing nearly 24%, is consolidating its efforts through collaborative programs to establish sovereign sensor payloads and missile defense architecture.
The APAC region follows closely with over 21% of the market opportunity, with nations like Japan and Australia investing heavily in satellite constellations for regional security and space domain awareness.
These regions are focused on deploying wide-field-of-view sensors and advanced signal processing to counter hypersonic glide vehicles.
This global distribution reflects a unified strategic focus on leveraging orbital platforms and ground segment support for persistent surveillance and strategic deterrence against emerging, high-speed threats.
Customer Landscape Analysis for the Space-Based Missile Tracking Sensor Systems Market
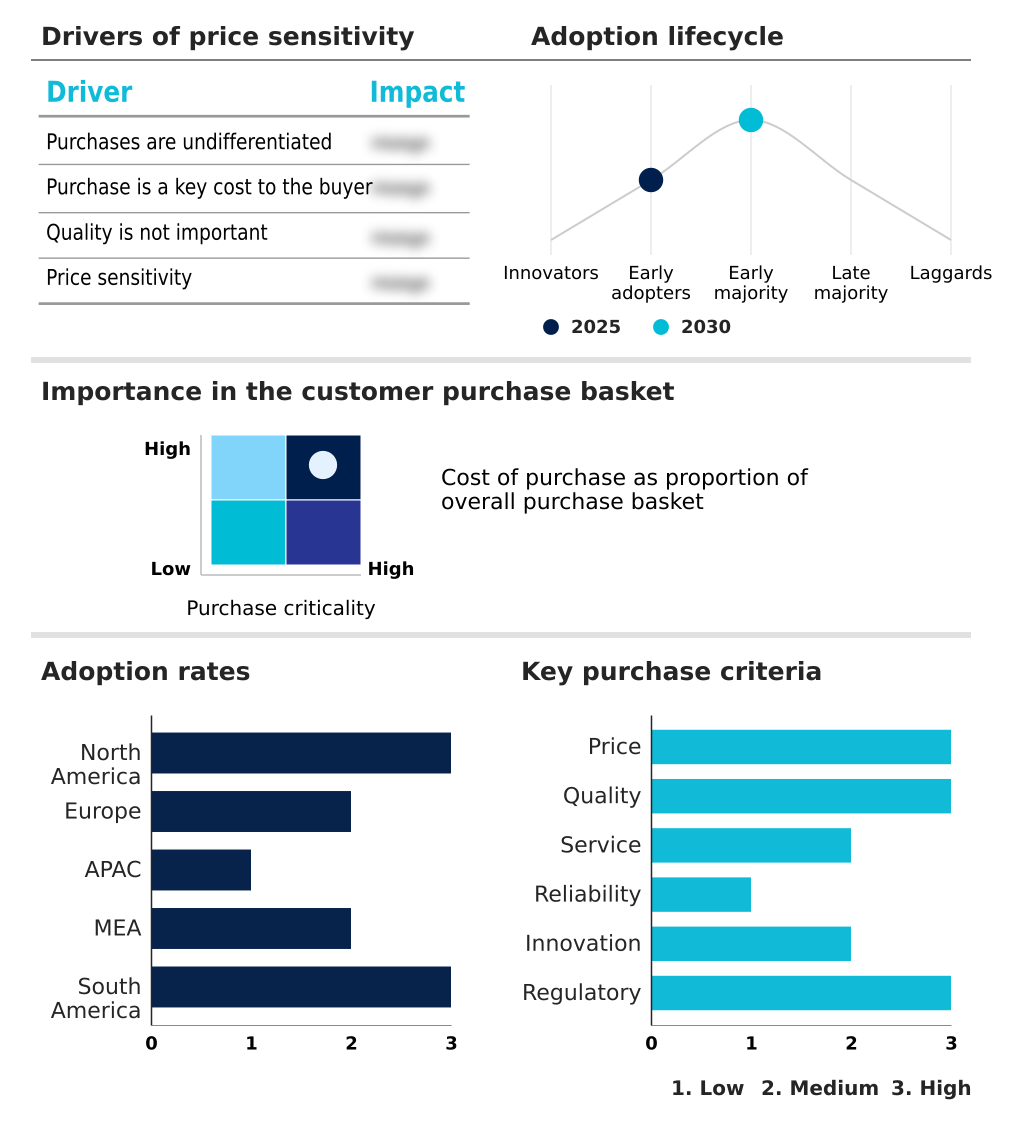
The space-based missile tracking sensor systems market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the space-based missile tracking sensor systems market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
Competitive Landscape of the Space-Based Missile Tracking Sensor Systems Market
Companies are implementing various strategies, such as strategic alliances, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the space-based missile tracking sensor systems market industry.
Airbus SE - Advanced electro-optical and infrared sensing technologies are being offered for hypersonic and ballistic missile tracking, representing a key area of innovation in missile defense architecture.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Airbus SE
- BAE Systems Plc
- General Dynamics Corp.
- HENSOLDT AG
- Honeywell International Inc.
- Kratos Defense and Security Inc
- L3Harris Technologies Inc.
- Leidos Holdings Inc.
- Leonardo S.p.A.
- Lockheed Martin Corp.
- Maxar Technologies Inc.
- Northrop Grumman Corp.
- Parsons Corp.
- RTX Corp.
- Safran SA
- Space Exploration Tech. Corp.
- Teledyne Technologies Inc.
- Terran Orbital Corp.
- Thales Group
- The Boeing Co.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments in the Space-Based Missile Tracking Sensor Systems Market
- In August 2024, RTX Corp. was awarded a contract by the Space Development Agency to deliver seven missile-tracking satellites for the Tranche 3 Tracking Layer, featuring advanced infrared sensor payloads.
- In October 2024, Northrop Grumman Corp. successfully demonstrated a new software-defined payload on-orbit, showcasing its ability to update threat discrimination algorithms remotely for a proliferated LEO constellation.
- In January 2025, L3Harris Technologies Inc. completed the critical design review for its advanced wide-field-of-view sensor, designed to provide fire-control quality data for tracking hypersonic glide vehicles from space.
- In May 2025, Lockheed Martin Corp. announced the successful thermal vacuum testing of its Next Generation OPIR GEO satellite, validating the resilience of its sensor payloads for strategic missile warning missions.
Research Analyst Overview: Space-Based Missile Tracking Sensor Systems Market
The market's accelerating growth momentum is sustained by a strategic pivot from monolithic geostationary orbit satellites to disaggregated satellite constellations in low earth orbit. This move to a proliferated architecture is a direct response to the operational challenge of tracking maneuvering hypersonic glide vehicles.
For boardroom decision-makers at national defense agencies, this trend forces a recalculation of capital expenditure, shifting from high-cost, long-lifespan assets to a continuous procurement model for replenishing a LEO network. The integration of advanced sensor payloads featuring wide-field-of-view sensors and multi-spectral sensors is now standard.
Onboard signal processing and data fusion, governed by standards like the Space Development Agency's data transport layer, are critical for managing the sensor-to-shooter loop. The entire missile defense architecture, from the launch vehicle to ground segment support and payload integration, is being redesigned for resilience and rapid technological refreshment to maintain effective space situational awareness.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Space-Based Missile Tracking Sensor Systems Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 313 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 12.9% |
| Market growth 2026-2030 | USD 4568.5 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 11.8% |
| Key countries | US, Canada, Mexico, UK, France, Germany, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Australia, Indonesia, Israel, Saudi Arabia, UAE, South Africa, Turkey, Brazil, Argentina and Chile |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Space-Based Missile Tracking Sensor Systems Market: Key Questions Answered in This Report
-
What is the expected growth of the Space-Based Missile Tracking Sensor Systems Market between 2026 and 2030?
-
The Space-Based Missile Tracking Sensor Systems Market is expected to grow by USD 4.57 billion during 2026-2030, registering a CAGR of 12.9%. Year-over-year growth in 2026 is estimated at 11.8%%. This acceleration is shaped by proliferation of hypersonic weaponry and requirement for advanced tracking capabilities, which is intensifying demand across multiple end-use verticals covered in the report.
-
-
What segmentation does the market report cover?
-
The report is segmented by Type (Infrared sensors, Radar sensors, Multi-spectral sensors, and Others), Platform (Satellites, Space stations, and Others), End-user (Military, Government agencies, Commercial, and Others) and Geography (North America, Europe, APAC, Middle East and Africa, South America). Among these, the Infrared sensors segment is estimated to witness significant growth during the forecast period, driven by rising adoption across key application areas. Each segment includes detailed qualitative and quantitative analysis, along with historical data from 2020-2024 and forecasts through 2030 with year-over-year growth rates.
-
-
Which regions are analyzed in the report?
-
The report covers North America, Europe, APAC, Middle East and Africa and South America. North America is estimated to contribute 43% to market growth during the forecast period. Country-level analysis includes US, Canada, Mexico, UK, France, Germany, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Australia, Indonesia, Israel, Saudi Arabia, UAE, South Africa, Turkey, Brazil, Argentina and Chile, with dedicated market size tables and year-over-year growth for each.
-
-
What are the key growth drivers and market challenges?
-
The primary driver is proliferation of hypersonic weaponry and requirement for advanced tracking capabilities, which is accelerating investment and industry demand. The main challenge is signal discrimination amidst atmospheric clutter and hypersonic maneuverability, creating operational barriers for key market participants. The report quantifies the impact of each driver and challenge across 2026 and 2030 with comparative analysis.
-
-
Who are the major players in the Space-Based Missile Tracking Sensor Systems Market?
-
Key vendors include Airbus SE, BAE Systems Plc, General Dynamics Corp., HENSOLDT AG, Honeywell International Inc., Kratos Defense and Security Inc, L3Harris Technologies Inc., Leidos Holdings Inc., Leonardo S.p.A., Lockheed Martin Corp., Maxar Technologies Inc., Northrop Grumman Corp., Parsons Corp., RTX Corp., Safran SA, Space Exploration Tech. Corp., Teledyne Technologies Inc., Terran Orbital Corp., Thales Group and The Boeing Co.. The report provides qualitative and quantitative analysis categorizing companies as dominant, leading, strong, tentative, and weak based on their market positioning. Company profiles include business segment analysis, SWOT assessment, key offerings, and recent strategic developments.
-
Space-Based Missile Tracking Sensor Systems Market Research Insights
Market dynamics are increasingly shaped by the imperative for resilient orbital platforms and autonomous in-orbit processing. The shift toward proliferated low earth orbit architectures, leveraging commercial satellite hosting and standardized satellite bus designs, is driven by the need for enhanced space situational awareness against advanced non-ballistic threats.
Compliance with frameworks like the International Traffic in Arms Regulations (ITAR) governs the dual-use technology transfer of critical sensor payloads and signal processing components. In practice, a network of satellites must autonomously perform sensor data fusion and cross-link communication to maintain a persistent track on a target.
This requirement for high-speed, secure data exchange is a primary focus for systems integration, ensuring that trajectory prediction data delivered to command and control systems is both timely and reliable for strategic deterrence.
We can help! Our analysts can customize this space-based missile tracking sensor systems market research report to meet your requirements.
 RIA -