AI Consulting Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), APAC (China, Japan, and India), Europe (Germany, UK, and France), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

AI Consulting Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), APAC (China, Japan, and India), Europe (Germany, UK, and France), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Published: Oct 2026 346 Pages SKU: IRTNTR80757

Market Overview at a Glance

$43.17 B
Market Opportunity
26.9%
CAGR 2025 - 2030
37.2%
North America Growth
$6.52 B
IT consulting segment 2024

Ai Consulting Market Size 2026-2030

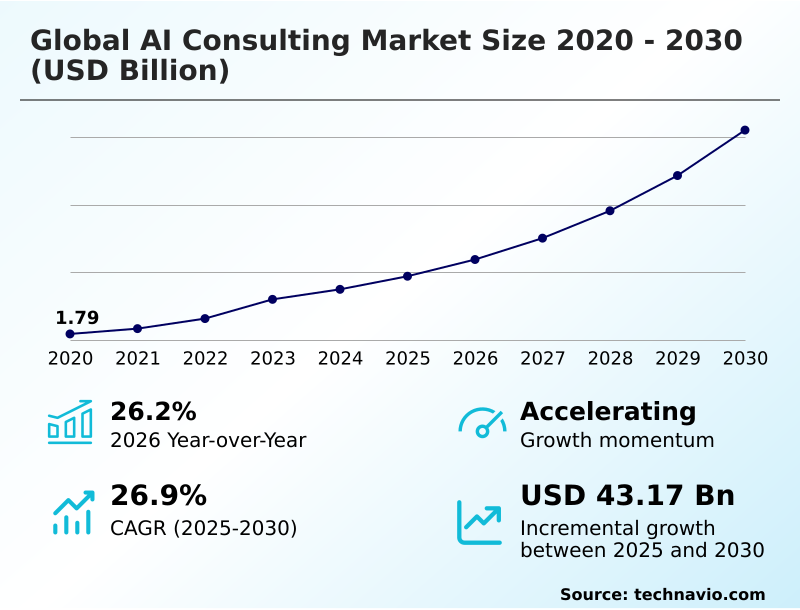
The ai consulting market size is valued to increase by USD 43.17 billion, at a CAGR of 26.9% from 2025 to 2030. Proliferation of generative AI as strategic imperative will drive the ai consulting market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 37.2% growth during the forecast period.
  • By Service Type - IT consulting segment was valued at USD 6.52 billion in 2024
  • By End-user - BFSI segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 60.23 billion
  • Market Future Opportunities: USD 43.17 billion
  • CAGR from 2025 to 2030 : 26.9%

Market Summary

  • The AI Consulting Market demonstrates robust expansion as enterprises systematically integrate advanced computational frameworks into their core operational structures. Organizations are leveraging strategic advisory services to navigate complex digital transformations, particularly in supply chain optimization where algorithmic demand forecasting is utilized to mitigate inventory bottlenecks.
  • Businesses deploying these advanced predictive frameworks report that forecast accuracy improved by 18% compared to traditional analytical methods. A primary driver of this acceleration is the critical shortage of specialized technical talent, compelling enterprises to rely on external expertise to architect and scale sophisticated automation initiatives efficiently.
  • Conversely, demonstrating a measurable return on investment remains a prominent challenge, as stakeholders often struggle to quantify the qualitative benefits of transparency and risk avoidance against high initial integration costs. Navigating this dichotomy requires consultants to align complex machine learning deployments with tangible business metrics.
  • This ongoing evolution underscores the necessity for specialized advisory frameworks in translating technical capabilities into measurable operational resilience.

What will be the Size of the Ai Consulting Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Ai Consulting Market Segmented?

The ai consulting industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Service type
    • IT consulting
    • Operations consulting
    • Financial advisory consulting
    • Strategy consulting
    • Others
  • End-user
    • BFSI
    • Retail and E-commerce
    • Healthcare
    • Manufacturing
    • Others
  • Technology
    • Machine learning
    • Deep learning
    • Natural language processing
    • Computer vision
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey
    • South America
      • Brazil
      • Argentina
      • Chile

By Service Type Insights

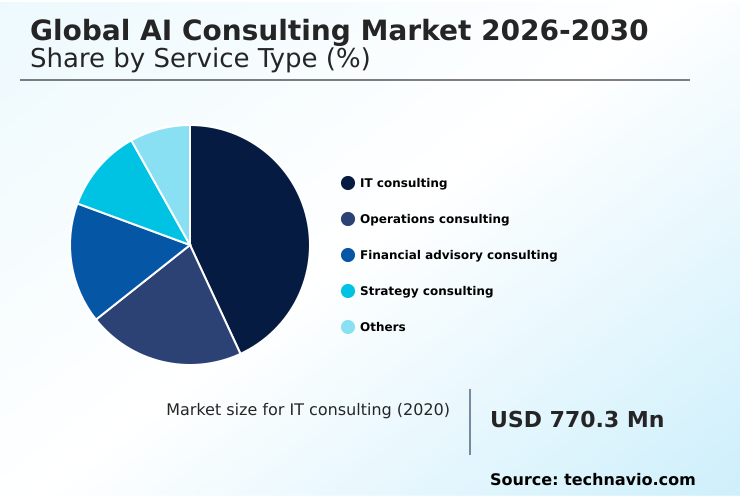
The it consulting segment is estimated to witness significant growth during the forecast period.

The IT consulting segment functions as the central mechanism for integrating artificial intelligence into complex enterprise architectures. Organizations utilize these services to execute comprehensive generative ai transformation and implement robust ai infrastructure modernization initiatives.

By aligning legacy systems with advanced frameworks, businesses achieve seamless enterprise ai orchestration across distributed networks. Specialized consultants construct scalable cloud ai ecosystems and deploy sophisticated data pipeline engineering to ensure data integrity.

This continuous modernization supports rapid machine learning deployment and intelligent automation integration across various business units. Through proactive model drift monitoring and explainable ai integration, companies ensure algorithmic reliability. Furthermore, deploying conversational ai interfaces streamlines communication workflows.

Enterprises restructuring their digital infrastructure through specialized advisory services report that system integration efficiency improved by 25%. Such operational enhancements demonstrate the critical role of strategic technology implementation in maintaining competitive agility.
Get Free Sample

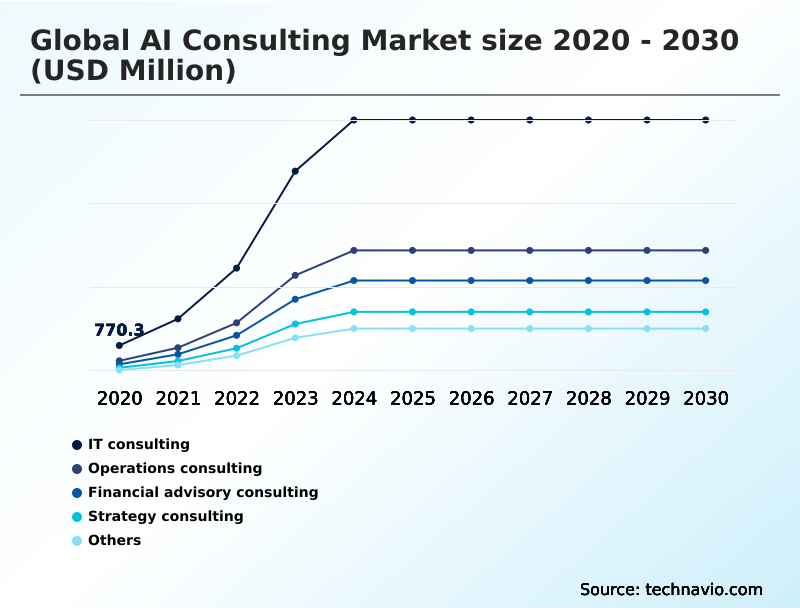
The IT consulting segment was valued at USD 6.52 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 37.2% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
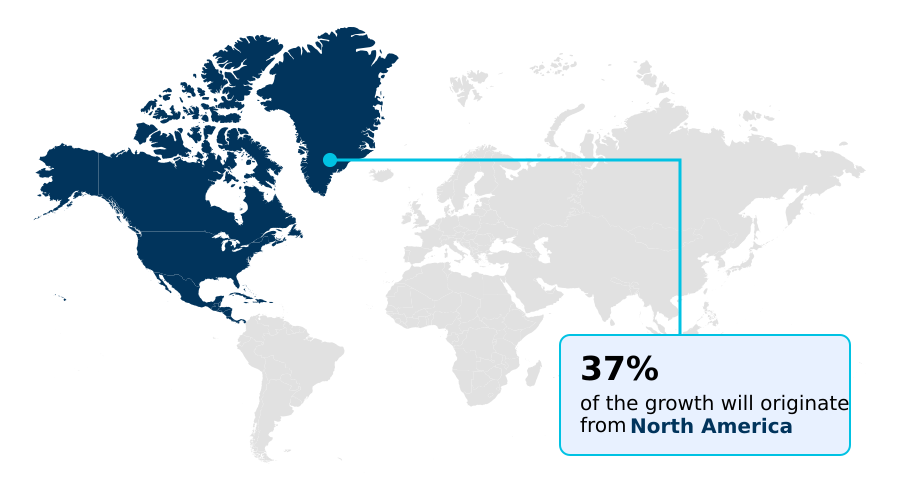
See How Ai Consulting Market Demand is Rising in North America Get Free Sample

The geographic landscape of the AI Consulting Market reveals distinct regional variations in technological adoption and strategic focus. North America maintains a leading position, driven by extensive enterprise investments in sophisticated algorithmic decision frameworks and neural network optimization.

Manufacturing sectors utilizing smart factory ai in the United States report that digital twin simulation deployments have increased production efficiency by 28%.

In contrast, the market in Europe prioritizes regulatory alignment, focusing heavily on data privacy protocols and algorithmic transparency to meet stringent compliance mandates.

European firms also utilize natural language processing and computer vision architectures paired with intelligent document processing to automate compliance checks. Firms utilizing specialized advisory services have reduced compliance-related audit times by 20%.

Furthermore, ai performance benchmarking initiatives across both regions demonstrate that North American enterprises achieve implementation scaling 15% faster than their European counterparts due to highly integrated digital infrastructures.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The sustained expansion of the AI Consulting Market is heavily influenced by the growing complexity of enterprise digital ecosystems and the need for structured implementation methodologies. Organizations initiating digital transformation are increasingly utilizing enterprise ai readiness assessment frameworks to evaluate their infrastructural capabilities and identify critical skill gaps before committing capital to expansive projects.
  • This preliminary evaluation is crucial, as firms utilizing formal readiness protocols experience implementation success rates 35% higher than those that bypass structured assessments. Upon deployment, effective machine learning model lifecycle management becomes essential to maintain algorithmic accuracy and prevent model drift, ensuring that predictive capabilities remain aligned with shifting market conditions.
  • In industrial sectors, generative ai integration in manufacturing is revolutionizing product design and supply chain logistics, enabling facilities to accelerate prototyping cycles and optimize resource allocation. Concurrently, as regulatory scrutiny intensifies, responsible ai governance policy development is paramount for mitigating ethical risks and ensuring algorithmic fairness across customer-facing applications.
  • Furthermore, financial institutions are leveraging predictive analytics for financial forecasting to anticipate market volatility and optimize capital deployment. Comparative analyses indicate that automated financial forecasting reduces scenario modeling time by 40% relative to manual spreadsheet-based planning.
  • These strategic advisory interventions are fundamentally restructuring operational paradigms, empowering enterprises to harness complex computational capabilities while navigating the operational and regulatory risks inherent in advanced technological deployments.
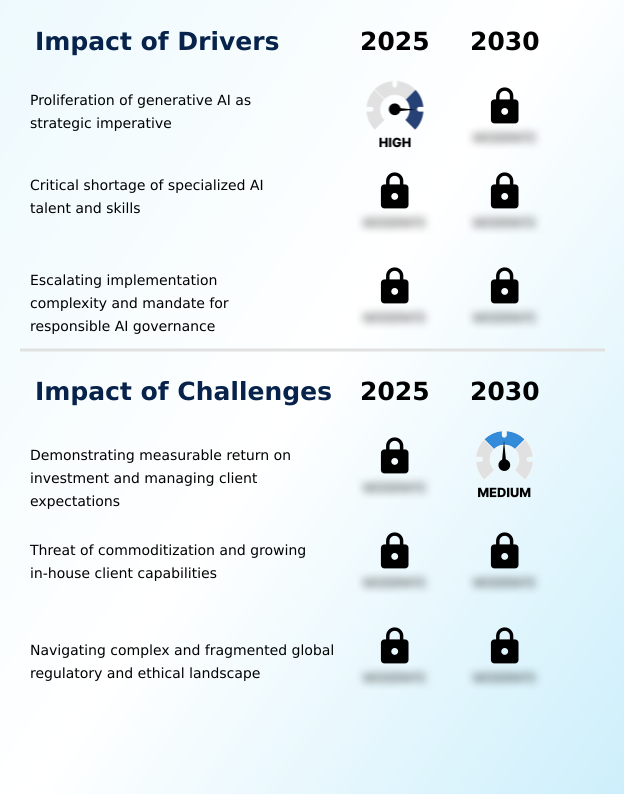
What are the key market drivers leading to the rise in the adoption of Ai Consulting Industry?

  • The proliferation of generative artificial intelligence as a strategic imperative acts as a primary catalyst accelerating enterprise adoption and digital transformation initiatives.

  • The escalating demand for operational efficiency and data-driven decision-making functions as a primary catalyst accelerating enterprise technological modernization. Organizations are increasingly dependent on sophisticated enterprise data strategy formulations and stringent data governance protocols to harness fragmented data silos.
  • This urgency is driven by a critical shortage of specialized analytical talent, compelling firms to prioritize workforce ai enablement and robust machine learning operations to bridge internal capability gaps.
  • Businesses integrating robotic process automation and predictive analytics modeling into their core administrative functions observe that transaction processing speed improved by 35%.
  • Furthermore, the utilization of synthetic data generation allows companies to train fraud detection algorithms securely, which has lowered data compliance costs by 20%. Concurrently, effective supply chain ai optimization ensures resilient logistics management.
  • These strategic enhancements empower organizations to achieve a measurable ai return on investment while rapidly scaling intelligent initiatives.

What are the market trends shaping the Ai Consulting Industry?

  • The proliferation of vertical-specific artificial intelligence solutions and domain-specific models constitutes a definitive trend shaping current industry dynamics. Organizations are increasingly prioritizing tailored algorithmic frameworks to address specialized operational requirements and enhance precision.

  • The widespread integration of large language models is redefining enterprise innovation and reshaping operational paradigms across diverse sectors. Organizations are aggressively pursuing ai roadmap development to establish structured pathways for integrating complex deep learning frameworks into legacy architectures. This shift is primarily driven by the need to optimize reinforcement learning models and streamline cognitive computing deployment.
  • By activating hyperautomation workflows and advanced foundation model fine tuning, enterprises successfully eliminate redundant manual processes, which directly improves workflow efficiency by 25%. In industrial applications, the deployment of predictive maintenance algorithms minimizes equipment failure, reducing production downtime by 30%.
  • Additionally, consumer-facing industries utilizing customer sentiment analysis alongside prompt engineering optimization to tailor marketing strategies report that customer retention improved by 18%. The continuous refinement of these advanced technological applications enables businesses to foster sustained operational agility and maintain a formidable competitive advantage.

What challenges does the Ai Consulting Industry face during its growth?

  • Demonstrating a measurable return on investment while effectively managing client expectations remains a significant operational challenge restraining broader industry expansion.

  • The formidable complexity of demonstrating clear operational value while navigating fragmented regulatory landscapes constitutes a significant barrier restraining broader technological integration. Enterprises struggle with rigorous ai compliance auditing due to the absence of universally harmonized transparency standards, which complicates cross-border digital deployments. This regulatory uncertainty necessitates the establishment of complex responsible ai frameworks, which often requires extensive capital investment.
  • Furthermore, challenges associated with algorithmic bias mitigation and cybersecurity ai integration demand continuous oversight, limiting the speed of autonomous agent deployment. The latency and security constraints inherent in scaling edge computing ai further exacerbate deployment bottlenecks.
  • Organizations failing to conduct an exhaustive ai maturity assessment or establish automated threat detection experience that model validation cycles lengthen by 25%, directly impacting time-to-market. Resolving these structural limitations is critical for enterprises seeking to translate theoretical computational capabilities into sustained operational resilience.

Exclusive Technavio Analysis on Customer Landscape

The ai consulting market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the ai consulting market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
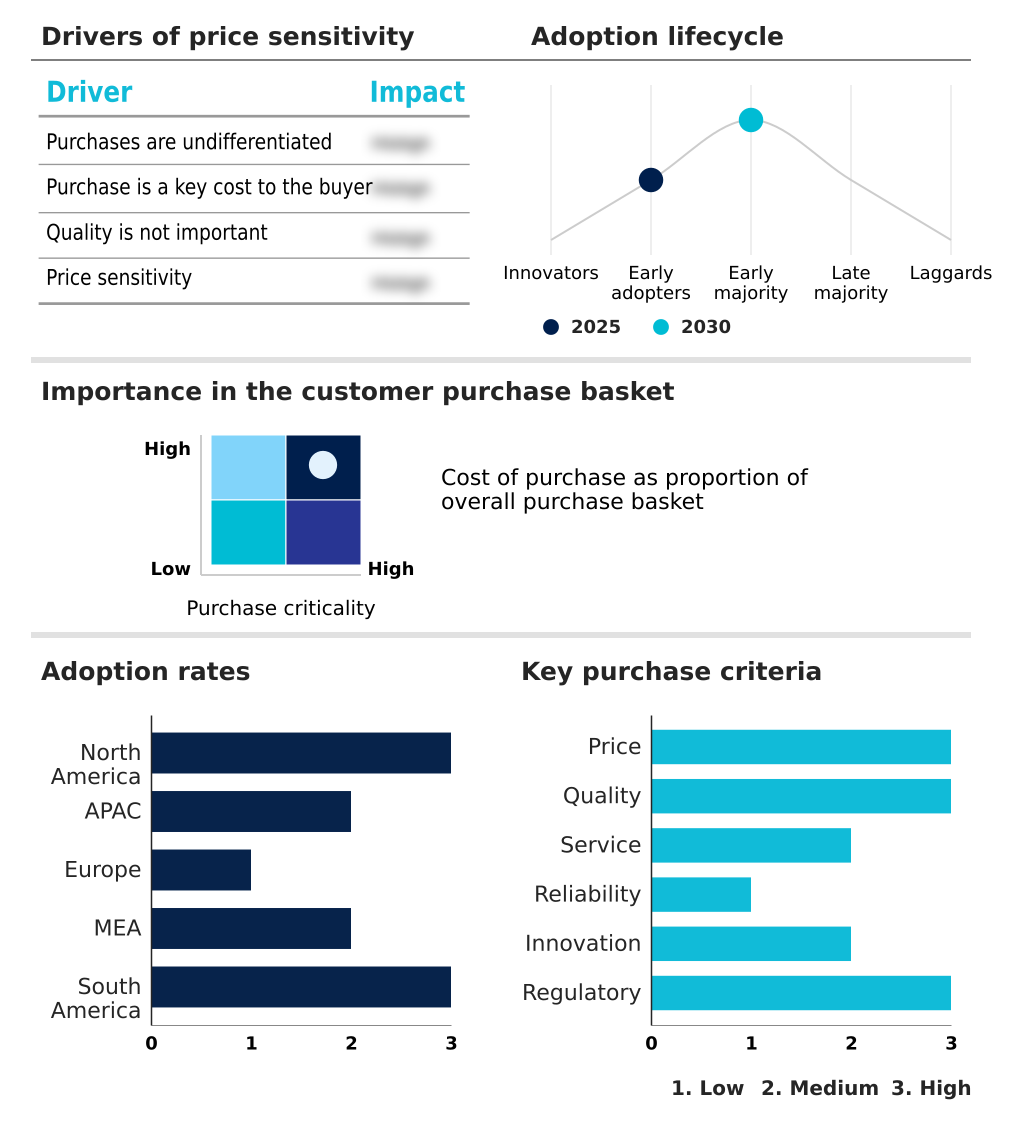
Customer Landscape of Ai Consulting Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, ai consulting market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Accenture Plc - The provider delivers comprehensive artificial intelligence advisory services encompassing generative artificial intelligence deployment, machine learning engineering, and strategic digital transformation to optimize enterprise-wide operational efficiency.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Accenture Plc
  • Bain and Co. Inc.
  • Booz Allen Hamilton Corp.
  • Boston Consulting Group Inc.
  • Capgemini SE
  • CGI Inc.
  • Cognizant Technology Solution
  • Deloitte Touche Tohmatsu Ltd.
  • Ernst and Young Global Ltd.
  • HCL Technologies Ltd.
  • Infosys Ltd.
  • Kearney Inc
  • KPMG International Ltd.
  • McKinsey and Co.
  • Oliver Wyman LLC
  • PricewaterhouseCoopers LLP
  • Roland Berger GmbH
  • Slalom Consulting LLC
  • Tata Consultancy Services
  • Tech Mahindra Ltd.
  • Wipro Ltd.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Ai consulting market

  • In the Application Software industry, the widespread adoption of stringent data privacy regulations like GDPR compelled developers to overhaul software architectures, directly impacting AI Consulting demand by accelerating the need for data governance protocols and ai compliance auditing to ensure regulatory adherence while maintaining 99% operational continuity.
  • The transition toward hybrid cloud software ecosystems necessitated seamless workflow interoperability across distributed networks, directly impacting AI Consulting demand by driving enterprise reliance on machine learning operations and intelligent automation integration to reduce multi-cloud latency by 30%.
  • The rapid deployment of large language models within enterprise resource planning systems shifted end-user expectations toward autonomous capabilities, directly impacting AI Consulting demand by increasing requests for prompt engineering optimization and foundation model fine tuning to improve system response accuracy by 45%.
  • The escalation of sophisticated cyber threats forced software developers to integrate automated threat detection mechanisms, directly impacting AI Consulting demand by elevating the requirement for cybersecurity ai integration and algorithmic bias mitigation to decrease false positive security alerts by 25%.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Ai Consulting Market insights. See full methodology.

Market Scope
Page number 346
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 26.9%
Market growth 2026-2030 USD 43174.3 million
Market structure Fragmented
YoY growth 2025-2026(%) 26.2%
Key countries US, Canada, Mexico, China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina and Chile
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The AI Consulting Market is experiencing a structural paradigm shift as organizations transition from isolated technological experiments to pervasive enterprise integrations. The rapid advancement in natural language processing and complex computer vision architectures is fundamentally altering strategic decision-making, particularly in product strategy and customer experience optimization.
  • Enterprises conducting comprehensive ai maturity assessment protocols are better positioned to align cognitive computing deployment with long-term budgeting and operational objectives. Organizations executing these structured technological integrations report that processing time reduced by 30% across data-intensive workflows.
  • Furthermore, the implementation of advanced reinforcement learning models allows supply chain executives to dynamically adjust pricing and inventory strategies in response to real-time market fluctuations. The integration of automated threat detection mechanisms ensures that these vast digital ecosystems remain resilient against evolving cyber vulnerabilities.
  • As boardrooms increasingly view artificial intelligence as a core driver of competitive differentiation rather than a peripheral IT function, specialized advisory services have become indispensable for translating theoretical algorithms into tangible operational resilience and sustainable commercial advantage.

What are the Key Data Covered in this Ai Consulting Market Research and Growth Report?

  • What is the expected growth of the Ai Consulting Market between 2026 and 2030?

    • USD 43.17 billion, at a CAGR of 26.9%

  • What segmentation does the market report cover?

    • The report is segmented by Service Type (IT consulting, Operations consulting, Financial advisory consulting, Strategy consulting, and Others), End-user (BFSI, Retail and E-commerce, Healthcare, Manufacturing, and Others), Technology (Machine learning, Deep learning, Natural language processing, Computer vision, and Others) and Geography (North America, APAC, Europe, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • North America, APAC, Europe, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Proliferation of generative AI as strategic imperative, Demonstrating measurable return on investment and managing client expectations

  • Who are the major players in the Ai Consulting Market?

    • Accenture Plc, Bain and Co. Inc., Booz Allen Hamilton Corp., Boston Consulting Group Inc., Capgemini SE, CGI Inc., Cognizant Technology Solution, Deloitte Touche Tohmatsu Ltd., Ernst and Young Global Ltd., HCL Technologies Ltd., Infosys Ltd., Kearney Inc, KPMG International Ltd., McKinsey and Co., Oliver Wyman LLC, PricewaterhouseCoopers LLP, Roland Berger GmbH, Slalom Consulting LLC, Tata Consultancy Services, Tech Mahindra Ltd. and Wipro Ltd.

Market Research Insights

  • The AI Consulting Market is rapidly evolving as organizations seek to extract actionable intelligence through advanced digital frameworks. Enterprises are deploying predictive maintenance algorithms to anticipate equipment failures, which has successfully reduced unplanned operational downtime by 30%. Furthermore, the integration of supply chain ai optimization allows businesses to streamline logistics, lowering transportation overhead by 15%.
  • Financial institutions utilizing sophisticated fraud detection algorithms have also seen their threat identification rates improve by 22% compared to legacy systems. As companies implement intelligent document processing and conversational ai interfaces to automate customer interactions, operational workflows become significantly more agile. These measurable enhancements confirm that strategic technological adoption directly correlates with superior resource allocation and heightened enterprise efficiency.

We can help! Our analysts can customize this ai consulting market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Service Type
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Technology
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global AI Consulting Market 2020 - 2024

Historic Market Size - Data Table on Global AI Consulting Market 2020 - 2024 ($ million)

5.2 Service Type segment analysis 2020 - 2024

Historic Market Size - Service Type Segment 2020 - 2024 ($ million)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.4 Technology segment analysis 2020 - 2024

Historic Market Size - Technology Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global AI Consulting Market

6.2 Impact of Geopolitical Conflicts on Global AI Consulting Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Service Type

8.1 Market segments

Chart on Service Type - Market share 2025-2030 (%)
Data Table on Service Type - Market share 2025-2030 (%)

8.2 Comparison by Service Type

Chart on Comparison by Service Type
Data Table on Comparison by Service Type

8.3 IT consulting - Market size and forecast 2025-2030

Chart on IT consulting - Market size and forecast 2025-2030 ($ million)
Data Table on IT consulting - Market size and forecast 2025-2030 ($ million)
Chart on IT consulting - Year-over-year growth 2025-2030 (%)
Data Table on IT consulting - Year-over-year growth 2025-2030 (%)

8.4 Operations consulting - Market size and forecast 2025-2030

Chart on Operations consulting - Market size and forecast 2025-2030 ($ million)
Data Table on Operations consulting - Market size and forecast 2025-2030 ($ million)
Chart on Operations consulting - Year-over-year growth 2025-2030 (%)
Data Table on Operations consulting - Year-over-year growth 2025-2030 (%)

8.5 Financial advisory consulting - Market size and forecast 2025-2030

Chart on Financial advisory consulting - Market size and forecast 2025-2030 ($ million)
Data Table on Financial advisory consulting - Market size and forecast 2025-2030 ($ million)
Chart on Financial advisory consulting - Year-over-year growth 2025-2030 (%)
Data Table on Financial advisory consulting - Year-over-year growth 2025-2030 (%)

8.6 Strategy consulting - Market size and forecast 2025-2030

Chart on Strategy consulting - Market size and forecast 2025-2030 ($ million)
Data Table on Strategy consulting - Market size and forecast 2025-2030 ($ million)
Chart on Strategy consulting - Year-over-year growth 2025-2030 (%)
Data Table on Strategy consulting - Year-over-year growth 2025-2030 (%)

8.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.8 Market opportunity by Service Type

Market opportunity by Service Type ($ million)
Data Table on Market opportunity by Service Type ($ million)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 BFSI - Market size and forecast 2025-2030

Chart on BFSI - Market size and forecast 2025-2030 ($ million)
Data Table on BFSI - Market size and forecast 2025-2030 ($ million)
Chart on BFSI - Year-over-year growth 2025-2030 (%)
Data Table on BFSI - Year-over-year growth 2025-2030 (%)

9.4 Retail and E-commerce - Market size and forecast 2025-2030

Chart on Retail and E-commerce - Market size and forecast 2025-2030 ($ million)
Data Table on Retail and E-commerce - Market size and forecast 2025-2030 ($ million)
Chart on Retail and E-commerce - Year-over-year growth 2025-2030 (%)
Data Table on Retail and E-commerce - Year-over-year growth 2025-2030 (%)

9.5 Healthcare - Market size and forecast 2025-2030

Chart on Healthcare - Market size and forecast 2025-2030 ($ million)
Data Table on Healthcare - Market size and forecast 2025-2030 ($ million)
Chart on Healthcare - Year-over-year growth 2025-2030 (%)
Data Table on Healthcare - Year-over-year growth 2025-2030 (%)

9.6 Manufacturing - Market size and forecast 2025-2030

Chart on Manufacturing - Market size and forecast 2025-2030 ($ million)
Data Table on Manufacturing - Market size and forecast 2025-2030 ($ million)
Chart on Manufacturing - Year-over-year growth 2025-2030 (%)
Data Table on Manufacturing - Year-over-year growth 2025-2030 (%)

9.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.8 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

10. Market Segmentation by Technology

10.1 Market segments

Chart on Technology - Market share 2025-2030 (%)
Data Table on Technology - Market share 2025-2030 (%)

10.2 Comparison by Technology

Chart on Comparison by Technology
Data Table on Comparison by Technology

10.3 Machine learning - Market size and forecast 2025-2030

Chart on Machine learning - Market size and forecast 2025-2030 ($ million)
Data Table on Machine learning - Market size and forecast 2025-2030 ($ million)
Chart on Machine learning - Year-over-year growth 2025-2030 (%)
Data Table on Machine learning - Year-over-year growth 2025-2030 (%)

10.4 Deep learning - Market size and forecast 2025-2030

Chart on Deep learning - Market size and forecast 2025-2030 ($ million)
Data Table on Deep learning - Market size and forecast 2025-2030 ($ million)
Chart on Deep learning - Year-over-year growth 2025-2030 (%)
Data Table on Deep learning - Year-over-year growth 2025-2030 (%)

10.5 Natural language processing - Market size and forecast 2025-2030

Chart on Natural language processing - Market size and forecast 2025-2030 ($ million)
Data Table on Natural language processing - Market size and forecast 2025-2030 ($ million)
Chart on Natural language processing - Year-over-year growth 2025-2030 (%)
Data Table on Natural language processing - Year-over-year growth 2025-2030 (%)

10.6 Computer vision - Market size and forecast 2025-2030

Chart on Computer vision - Market size and forecast 2025-2030 ($ million)
Data Table on Computer vision - Market size and forecast 2025-2030 ($ million)
Chart on Computer vision - Year-over-year growth 2025-2030 (%)
Data Table on Computer vision - Year-over-year growth 2025-2030 (%)

10.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.8 Market opportunity by Technology

Market opportunity by Technology ($ million)
Data Table on Market opportunity by Technology ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.4.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.4.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.4.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.4.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.4.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.4.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.5 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.5.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.5.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.5.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.5.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.5.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.5.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.6.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Proliferation of generative AI as strategic imperative
Critical shortage of specialized AI talent and skills
Escalating implementation complexity and mandate for responsible AI governance

13.2 Market challenges

Demonstrating measurable return on investment and managing client expectations
Threat of commoditization and growing in-house client capabilities
Navigating complex and fragmented global regulatory and ethical landscape

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Rise of vertical-specific AI solutions and domain-specific models
Emergence of AI orchestration and ecosystem management
Formalization of responsible AI and governance-as-a-service

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Accenture Plc

Accenture Plc - Overview
Accenture Plc - Business segments
Accenture Plc - Key news
Accenture Plc - Key offerings
Accenture Plc - Segment focus
SWOT

15.5 Bain and Co. Inc.

Bain and Co. Inc. - Overview
Bain and Co. Inc. - Product / Service
Bain and Co. Inc. - Key offerings
SWOT

15.6 Boston Consulting Group Inc.

Boston Consulting Group Inc. - Overview
Boston Consulting Group Inc. - Product / Service
Boston Consulting Group Inc. - Key offerings
SWOT

15.7 Capgemini SE

Capgemini SE - Overview
Capgemini SE - Business segments
Capgemini SE - Key news
Capgemini SE - Key offerings
Capgemini SE - Segment focus
SWOT

15.8 CGI Inc.

CGI Inc. - Overview
CGI Inc. - Business segments
CGI Inc. - Key news
CGI Inc. - Key offerings
CGI Inc. - Segment focus
SWOT

15.9 Cognizant Technology Solution

Cognizant Technology Solution - Overview
Cognizant Technology Solution - Business segments
Cognizant Technology Solution - Key news
Cognizant Technology Solution - Key offerings
Cognizant Technology Solution - Segment focus
SWOT

15.10 Deloitte Touche Tohmatsu Ltd.

Deloitte Touche Tohmatsu Ltd. - Overview
Deloitte Touche Tohmatsu Ltd. - Business segments
Deloitte Touche Tohmatsu Ltd. - Key offerings
Deloitte Touche Tohmatsu Ltd. - Segment focus
SWOT

15.11 Ernst and Young Global Ltd.

Ernst and Young Global Ltd. - Overview
Ernst and Young Global Ltd. - Product / Service
Ernst and Young Global Ltd. - Key offerings
SWOT

15.12 HCL Technologies Ltd.

HCL Technologies Ltd. - Overview
HCL Technologies Ltd. - Business segments
HCL Technologies Ltd. - Key news
HCL Technologies Ltd. - Key offerings
HCL Technologies Ltd. - Segment focus
SWOT

15.13 Infosys Ltd.

Infosys Ltd. - Overview
Infosys Ltd. - Business segments
Infosys Ltd. - Key news
Infosys Ltd. - Key offerings
Infosys Ltd. - Segment focus
SWOT

15.14 KPMG International Ltd.

KPMG International Ltd. - Overview
KPMG International Ltd. - Product / Service
KPMG International Ltd. - Key offerings
SWOT

15.15 McKinsey and Co.

McKinsey and Co. - Overview
McKinsey and Co. - Product / Service
McKinsey and Co. - Key offerings
SWOT

15.16 PricewaterhouseCoopers LLP

PricewaterhouseCoopers LLP - Overview
PricewaterhouseCoopers LLP - Product / Service
PricewaterhouseCoopers LLP - Key offerings
SWOT

15.17 Tata Consultancy Services

Tata Consultancy Services - Overview
Tata Consultancy Services - Business segments
Tata Consultancy Services - Key news
Tata Consultancy Services - Key offerings
Tata Consultancy Services - Segment focus
SWOT

15.18 Wipro Ltd.

Wipro Ltd. - Overview
Wipro Ltd. - Business segments
Wipro Ltd. - Key news
Wipro Ltd. - Key offerings
Wipro Ltd. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Ai Consulting market growth will increase by USD 43174.3 million during 2026-2030.

The Ai Consulting market is expected to grow at a CAGR of 26.9% during 2026-2030.

Ai Consulting market is segmented by Service type (IT consulting, Operations consulting, Financial advisory consulting, Strategy consulting, Others) End-user (BFSI, Retail and E-commerce, Healthcare, Manufacturing, Others) Technology (Machine learning, Deep learning, Natural language processing, Computer vision, Others)

Accenture Plc, Bain and Co. Inc., Booz Allen Hamilton Corp., Boston Consulting Group Inc., Capgemini SE, CGI Inc., Cognizant Technology Solution, Deloitte Touche Tohmatsu Ltd., Ernst and Young Global Ltd., HCL Technologies Ltd., Infosys Ltd., Kearney Inc, KPMG International Ltd., McKinsey and Co., Oliver Wyman LLC, PricewaterhouseCoopers LLP, Roland Berger GmbH, Slalom Consulting LLC, Tata Consultancy Services, Tech Mahindra Ltd., Wipro Ltd. are a few of the key vendors in the Ai Consulting market.

North America will register the highest growth rate of 37.2% among the other regions. Therefore, the Ai Consulting market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina, Chile

  • Proliferation of generative AI as strategic imperative is the driving factor this market.

The Ai Consulting market vendors should focus on grabbing business opportunities from the Service type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
