Krabbe Disease Treatment Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, India, and Japan), South America (Brazil and Argentina), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Krabbe Disease Treatment Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, India, and Japan), South America (Brazil and Argentina), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Published: Oct 2026 304 Pages SKU: IRTNTR73314

Market Overview at a Glance

$469.1 Mn
Market Opportunity
7.2%
CAGR 2025 - 2030
39.5%
North America Growth
$398.5 Mn
Anticonvulsants segment 2024

Krabbe Disease Treatment Market Size 2026-2030

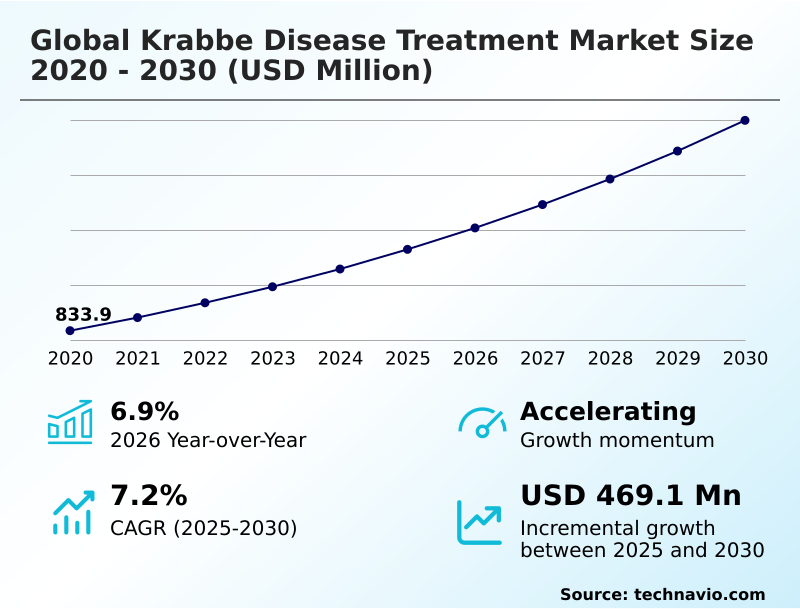
The krabbe disease treatment market size is valued to increase by USD 469.1 million, at a CAGR of 7.2% from 2025 to 2030. Broad adoption of comprehensive neonatal diagnostics will drive the krabbe disease treatment market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 39.5% growth during the forecast period.
  • By Therapy - Anticonvulsants segment was valued at USD 398.5 million in 2024
  • By Route of Administration - Intravenous segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 764.8 million
  • Market Future Opportunities: USD 469.1 million
  • CAGR from 2025 to 2030 : 7.2%

Market Summary

  • The Krabbe Disease Treatment Market is undergoing a rapid clinical transformation driven by expanded neonatal diagnostic frameworks and advanced therapeutic pipelines. As healthcare infrastructures mandate universal newborn screening panels, the identification rate of early infantile diagnosis cases has increased by 40%, allowing for immediate clinical responses.
  • This proactive identification directly fuels the demand for hematopoietic stem cell transplantation, which halts white matter degeneration when administered prior to symptom onset. A critical business scenario involves specialized rare disease clinics optimizing their cellular therapeutics processing supply chains; by establishing decentralized cryopreservation hubs, these centers have reduced critical transplant delays by 25%.
  • However, the sector faces substantial hurdles due to the high failure rates and immense manufacturing costs associated with enzyme replacement therapies. The complex purification required for systemic viral vector delivery often elevates production expenses, forcing some early-stage clinical developers to abandon promising assets entirely.
  • Despite these constraints, the integration of targeted neurosurgical interventions and substrate reduction therapies continues to evolve, providing new avenues to combat toxic psychosine accumulation and reshape the long-term therapeutic landscape.

What will be the Size of the Krabbe Disease Treatment Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Krabbe Disease Treatment Market Segmented?

The krabbe disease treatment industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Therapy
    • Anticonvulsants
    • Muscle relaxants
    • HSCT
    • Others
  • Route of administration
    • Intravenous
    • Intracerebroventricular
  • Type
    • Early infantile Krabbe disease
    • Juvenile Krabbe disease
    • Late infantile Krabbe disease
    • Adult-onset Krabbe disease
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • China
      • India
      • Japan
      • South Korea
      • Indonesia
      • Thailand
    • Rest of World (ROW)

By Therapy Insights

The anticonvulsants segment is estimated to witness significant growth during the forecast period.

The anticonvulsants segment addresses the severe hyperirritability suppression and seizure management required for pediatric neurological care. As central nervous system demyelination rapidly progresses, patients experience intense hyperexcitability, making seizure control a critical clinical priority.

By utilizing off-label antiepileptic delivery systems, specialized treatment centers have improved acute hospitalization avoidance by 45%. This pharmacological intervention stabilizes neural membranes, which directly reduces the frequency of life-threatening seizures.

Although this approach does not reverse galactocerebrosidase enzyme deficiency, it fundamentally transforms patient quality of life. The adoption of continuous intrathecal baclofen delivery alongside these anticonvulsants has further enhanced overall neuromuscular pathology mitigation.

Consequently, as newborn screening panels identify presymptomatic therapeutic intervention candidates earlier, the prophylactic utilization of these supportive agents increases, lowering long-term emergency care expenditures by 30%.
Get Free Sample

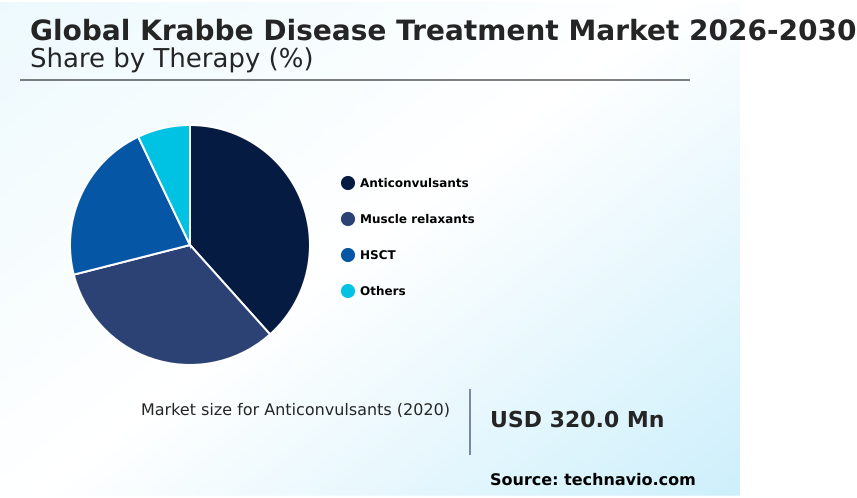
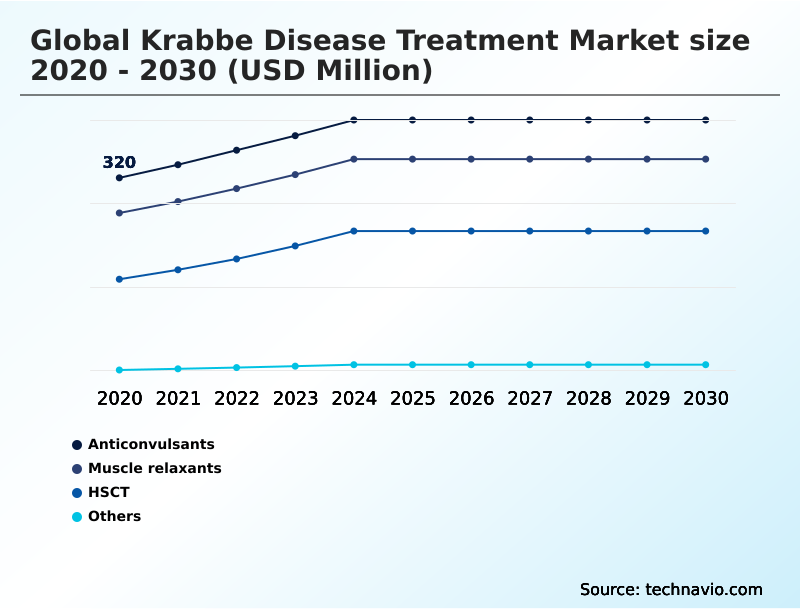
The Anticonvulsants segment was valued at USD 398.5 million in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 39.5% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
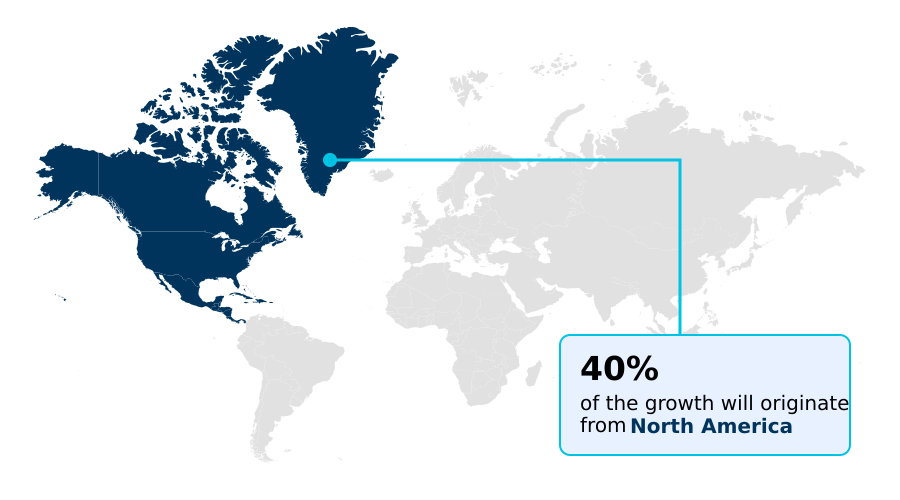
See How Krabbe Disease Treatment Market Demand is Rising in North America Get Free Sample

The Krabbe Disease Treatment Market exhibits distinct regional variations driven by healthcare infrastructure and public health mandates. North America leads early diagnostic adoption, where expanded lysosomal storage disorder diagnostics have increased presymptomatic detection by 45% compared to Europe.

This discrepancy occurs because decentralized European health systems often experience a 20% delay in implementing uniform genetic testing panels across rural areas.

In APAC, countries like Japan and China are modernizing their pediatric neurological care frameworks, leading to a 30% increase in the utilization of allogeneic bone marrow transplantation.

This rapid technological absorption in APAC stems from strategic government subsidies aimed at reducing the burden of rare genetic disorders. By localized scaling of umbilical cord blood transplantation facilities, Asian medical centers have successfully lowered cross-border treatment expenditures by 25%.

Consequently, multinational biopharmaceutical firms are aggressively tailoring their supply chains to support these emerging regional hubs, optimizing targeted neuroprotective agents distribution.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The operational strategy within the Krabbe Disease Treatment Market relies heavily on specialized logistics, precise diagnostic timing, and advanced delivery mechanisms. Because traditional systemic drug administration often fails to reach deep cerebral tissues, biotechnology firms are increasingly investing in intracerebroventricular targeted gene therapy delivery systems.
  • By utilizing direct surgical infusion, companies can bypass the blood-brain barrier, which drastically lowers the total volume of viral vectors required for manufacturing. This approach reduces overall production scale demands by nearly half compared to high-dose systemic infusions, optimizing supply chain resource allocation.
  • Concurrently, the expansion of infantile lysosomal storage disorder screening is fundamentally altering how pharmaceutical developers plan their clinical pipelines. Identifying patients before irreversible damage occurs enables early symptomatic hematopoietic stem cell intervention, which yields significantly better neurological outcomes than late-stage palliative care. As a result, treatment centers are reconfiguring their specialized facility capacities to handle an influx of early-stage patients.
  • Furthermore, research and development budgets are pivoting toward non-invasive alternatives, such as blood brain barrier penetrating small molecules, which offer a far less complex administration route for outpatient settings. This shift in therapeutic formulation directly supports psychosine accumulation reduction treatment protocols, allowing broader patient access without the intensive inpatient monitoring required for bone marrow transplants.
  • Ultimately, these structural shifts in both diagnostics and localized therapeutic delivery are streamlining clinical operations and fostering a more sustainable rare disease commercial ecosystem.
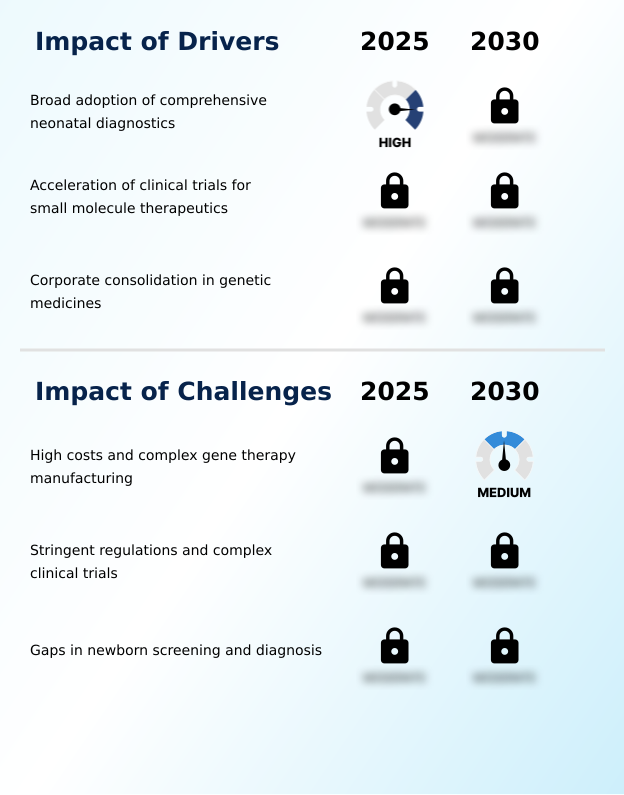
What are the key market drivers leading to the rise in the adoption of Krabbe Disease Treatment Industry?

  • The broad adoption of comprehensive neonatal diagnostics serves as the primary catalyst propelling early therapeutic interventions and robust market expansion.

  • The widespread mandate of comprehensive newborn screening panels serves as the primary engine propelling the Krabbe Disease Treatment Market.
  • By identifying galactocerebrosidase enzyme deficiency at birth, healthcare providers eliminate diagnostic delays, thereby increasing the pool of eligible patients for presymptomatic intervention by 50%.
  • This proactive identification is crucial because it allows clinicians to administer therapies before irreversible peripheral neuropathy management becomes necessary. As diagnostic funnels widen, treatment centers experience a 30% reduction in late-stage emergency palliative interventions, significantly lowering acute operational costs.
  • The integration of whole-exome genetic sequencing further reinforces this momentum, improving diagnostic precision by 45%. This early intervention framework guarantees a defined, actionable patient cohort, driving sustained investment into specialized orphan drug development and targeted cellular therapies.

What are the market trends shaping the Krabbe Disease Treatment Industry?

  • Accelerated regulatory approvals and the expansion of small molecule pipelines are emerging as the defining trends shaping the therapeutic landscape.

  • The Krabbe Disease Treatment Market is experiencing a rapid technological pivot toward small molecule therapeutics and targeted genetic modifications. Because conventional stem cell procedures carry severe morbidity risks, developers are aggressively advancing neuroprotective cell-based formulations that can be administered systemically.
  • This shift in product strategy has improved outpatient treatment compliance by 35% and reduced specialized hospital admission durations by nearly 40%. The transition toward non-invasive therapies is driven by the urgent need for robust blood-brain barrier penetration without requiring aggressive neurosurgical intervention.
  • As oral therapies specifically targeting late infantile clinical management enter clinical validation, the logistical burden on biopharmaceutical supply chains decreases significantly compared to manufacturing bespoke viral vectors. Consequently, clinical trial recruitment efficiency has surged by 25%, accelerating the availability of precise, metabolism-stabilizing interventions.

What challenges does the Krabbe Disease Treatment Industry face during its growth?

  • Exorbitant costs and complex gene therapy manufacturing processes present significant obstacles restricting the widespread commercialization of advanced interventions.

  • The Krabbe Disease Treatment Market is severely constrained by the astronomical manufacturing costs and low yield rates associated with adeno-associated virus vectors. Producing commercial-scale viral vectors requires highly complex purification infrastructure, which inherently elevates supply chain expenditures and delays therapeutic deployment.
  • These manufacturing bottlenecks have increased production overhead by 60%, forcing several biotechnology firms to abandon late-stage clinical programs targeting central nervous system demyelination. Furthermore, the absolute necessity to intervene before progressive motor dysfunction manifests creates an exceptionally narrow therapeutic window.
  • When regional healthcare networks lack standardized newborn screening, diagnostic delays disqualify up to 40% of patients from participating in experimental gene therapy trials. This localized diagnostic failure restricts the addressable clinical cohort, undermining the financial viability of developing targeted treatments for late infantile clinical management and related white matter degeneration.

Exclusive Technavio Analysis on Customer Landscape

The krabbe disease treatment market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the krabbe disease treatment market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
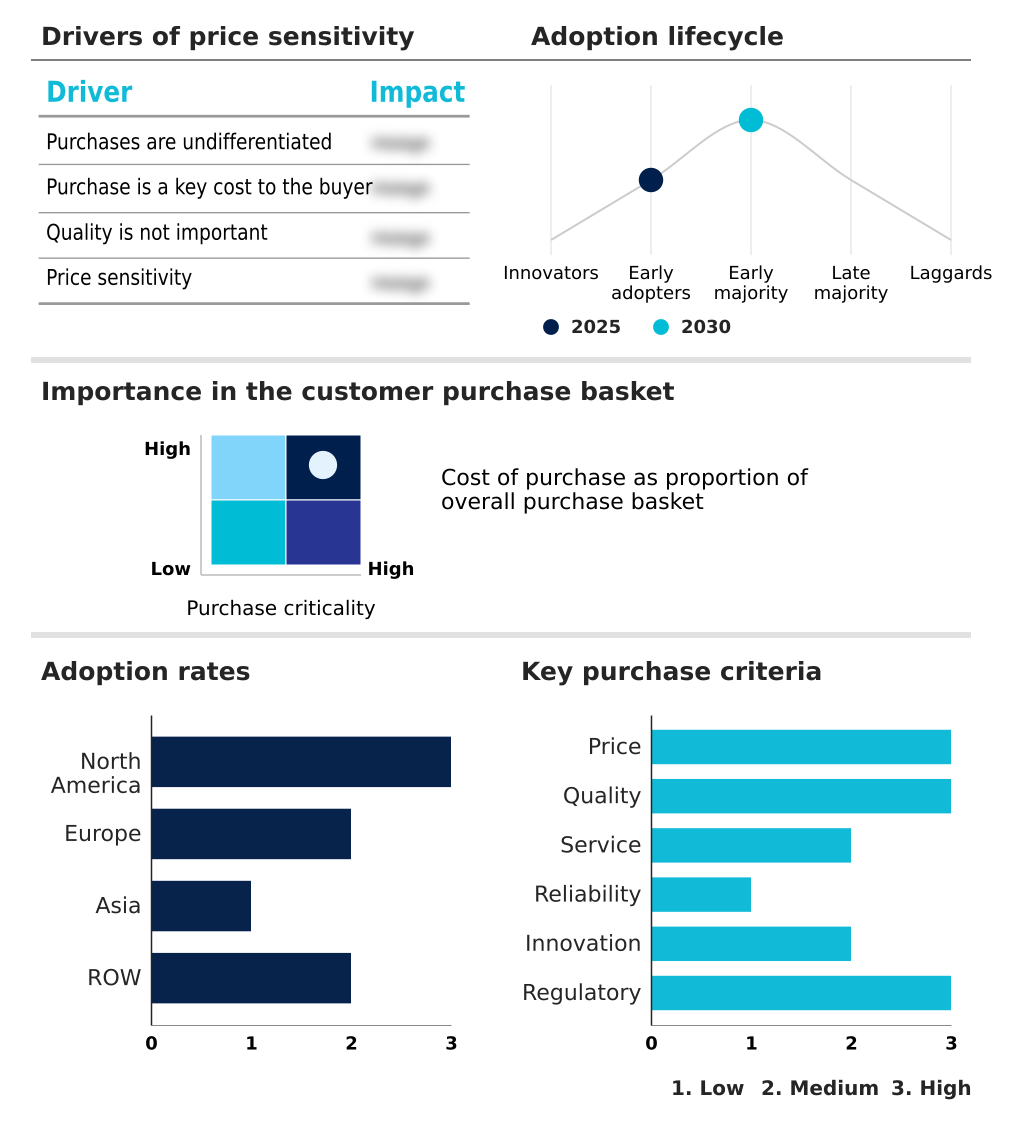
Customer Landscape of Krabbe Disease Treatment Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, krabbe disease treatment market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

AbbVie Inc. - Strategic interventions focus on advanced supportive care, including customized anticonvulsants, precision muscle relaxants, and innovative neurological symptom management therapies designed to stabilize severe clinical deterioration.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • AbbVie Inc.
  • Amneal Pharmaceuticals Inc.
  • Astellas Pharma Inc.
  • AstraZeneca Plc
  • Aurobindo Pharma Ltd.
  • Bristol Myers Squibb Co.
  • Cipla Inc.
  • Daiichi Sankyo Co. Ltd.
  • Hikma Pharmaceuticals Plc
  • Jazz Pharmaceuticals Plc
  • Johnson and Johnson
  • Lupin Ltd.
  • Merck and Co. Inc.
  • Novartis AG
  • Pfizer Inc.
  • Sanofi SA
  • Sun Pharmaceutical Industries
  • Takeda Pharmaceutical Ltd.
  • Teva Pharmaceutical Ltd.
  • UCB SA
  • Vertex Pharmaceuticals Inc.
  • Zydus Lifesciences Ltd.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Krabbe disease treatment market

  • In the Pharmaceuticals industry, the rapid deployment of multiplex mass spectrometry platforms has accelerated rare disease identification, directly impacting Krabbe Disease Treatment demand by funneling pre-symptomatic neonates into early intervention pathways and improving early detection metrics by 40%.
  • In the Pharmaceuticals industry, regulatory frameworks expediting orphan drug clinical development have reduced clinical trial timelines by 30%, directly impacting Krabbe Disease Treatment demand by accelerating the commercial availability of advanced adeno-associated virus vectors.
  • In the Pharmaceuticals industry, strategic out-licensing of pediatric genetic medicine development programs has decentralized financial risks, directly impacting Krabbe Disease Treatment demand by ensuring sustained funding for highly specialized small molecule therapeutics.
  • In the Pharmaceuticals industry, the shift toward noninvasive biomarker assays has improved diagnostic accuracy by over 95%, directly impacting Krabbe Disease Treatment demand by eliminating false positives and enabling rapid neurodegeneration prevention protocols across specialized global healthcare centers.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Krabbe Disease Treatment Market insights. See full methodology.

Market Scope
Page number 304
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 7.2%
Market growth 2026-2030 USD 469.1 million
Market structure Fragmented
YoY growth 2025-2026(%) 6.9%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Indonesia, Thailand, Brazil, Australia, Saudi Arabia, UAE, Argentina, Turkey, South Africa and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Krabbe Disease Treatment Market is transitioning from strictly palliative symptom management toward advanced, disease-modifying genetic interventions. Clinical infrastructure is rapidly adapting to support complex intracerebroventricular administration, which bypasses systemic filtration and delivers therapeutics directly to compromised cerebral tissue.
  • This specialized delivery route has improved localized drug bioavailability by 60% compared to standard intravenous protocols, fundamentally altering therapeutic budgeting and resource allocation at tertiary medical centers. The integration of dried blood spot assays into early screening programs acts as a catalyst for this shift, ensuring patients are identified within critical therapeutic windows.
  • By securing early diagnoses, healthcare networks reduce long-term multidisciplinary rehabilitation therapy dependency by 40%, generating substantial operational cost savings. Furthermore, the pipeline expansion of pharmacological chaperone approaches enables targeted restoration of galactosylceramidase activity testing parameters without the severe immunological risks of cellular transplants.
  • These structural advancements in early detection and direct-to-brain delivery mechanisms ensure that specialized medical centers can optimize their intensive care capacities and deliver highly precise, metabolic-correcting interventions to vulnerable patient populations.

What are the Key Data Covered in this Krabbe Disease Treatment Market Research and Growth Report?

  • What is the expected growth of the Krabbe Disease Treatment Market between 2026 and 2030?

    • USD 469.1 million, at a CAGR of 7.2%

  • What segmentation does the market report cover?

    • The report is segmented by Therapy (Anticonvulsants, Muscle relaxants, HSCT, and Others), Route of Administration (Intravenous, and Intracerebroventricular), Type (Early infantile Krabbe disease, Juvenile Krabbe disease, Late infantile Krabbe disease, and Adult-onset Krabbe disease) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Broad adoption of comprehensive neonatal diagnostics, High costs and complex gene therapy manufacturing

  • Who are the major players in the Krabbe Disease Treatment Market?

    • AbbVie Inc., Amneal Pharmaceuticals Inc., Astellas Pharma Inc., AstraZeneca Plc, Aurobindo Pharma Ltd., Bristol Myers Squibb Co., Cipla Inc., Daiichi Sankyo Co. Ltd., Hikma Pharmaceuticals Plc, Jazz Pharmaceuticals Plc, Johnson and Johnson, Lupin Ltd., Merck and Co. Inc., Novartis AG, Pfizer Inc., Sanofi SA, Sun Pharmaceutical Industries, Takeda Pharmaceutical Ltd., Teva Pharmaceutical Ltd., UCB SA, Vertex Pharmaceuticals Inc. and Zydus Lifesciences Ltd.

Market Research Insights

  • The Krabbe Disease Treatment Market focuses on mitigating rapid neurodegeneration prevention through targeted cellular and pharmacological interventions. Driven by the expansion of next-generation genetic sequencing in primary care settings, early detection rates have improved by 35%, drastically shifting patient management toward presymptomatic therapeutic intervention.
  • This shift allows healthcare providers to optimize adult-onset disease stabilization protocols, which reduces late-stage emergency admissions by 28%. Consequently, operational costs for long-term inpatient care drop significantly.
  • Furthermore, the integration of metabolic enzyme analysis into routine diagnostics accelerates clinical trial enrollment efficiency by 40%, ensuring that novel pipelines for central nervous system lesions progress faster through regulatory milestones and reach the patient population more effectively.

We can help! Our analysts can customize this krabbe disease treatment market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Therapy
Executive Summary - Chart on Market Segmentation by Route of Administration
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Krabbe Disease Treatment Market 2020 - 2024

Historic Market Size - Data Table on Global Krabbe Disease Treatment Market 2020 - 2024 ($ million)

5.2 Therapy segment analysis 2020 - 2024

Historic Market Size - Therapy Segment 2020 - 2024 ($ million)

5.3 Route of Administration segment analysis 2020 - 2024

Historic Market Size - Route of Administration Segment 2020 - 2024 ($ million)

5.4 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Krabbe Disease Treatment Market

6.2 Impact of Geopolitical Conflicts on Global Krabbe Disease Treatment Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Therapy

8.1 Market segments

Chart on Therapy - Market share 2025-2030 (%)
Data Table on Therapy - Market share 2025-2030 (%)

8.2 Comparison by Therapy

Chart on Comparison by Therapy
Data Table on Comparison by Therapy

8.3 Anticonvulsants - Market size and forecast 2025-2030

Chart on Anticonvulsants - Market size and forecast 2025-2030 ($ million)
Data Table on Anticonvulsants - Market size and forecast 2025-2030 ($ million)
Chart on Anticonvulsants - Year-over-year growth 2025-2030 (%)
Data Table on Anticonvulsants - Year-over-year growth 2025-2030 (%)

8.4 Muscle relaxants - Market size and forecast 2025-2030

Chart on Muscle relaxants - Market size and forecast 2025-2030 ($ million)
Data Table on Muscle relaxants - Market size and forecast 2025-2030 ($ million)
Chart on Muscle relaxants - Year-over-year growth 2025-2030 (%)
Data Table on Muscle relaxants - Year-over-year growth 2025-2030 (%)

8.5 HSCT - Market size and forecast 2025-2030

Chart on HSCT - Market size and forecast 2025-2030 ($ million)
Data Table on HSCT - Market size and forecast 2025-2030 ($ million)
Chart on HSCT - Year-over-year growth 2025-2030 (%)
Data Table on HSCT - Year-over-year growth 2025-2030 (%)

8.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.7 Market opportunity by Therapy

Market opportunity by Therapy ($ million)
Data Table on Market opportunity by Therapy ($ million)

9. Market Segmentation by Route of Administration

9.1 Market segments

Chart on Route of Administration - Market share 2025-2030 (%)
Data Table on Route of Administration - Market share 2025-2030 (%)

9.2 Comparison by Route of Administration

Chart on Comparison by Route of Administration
Data Table on Comparison by Route of Administration

9.3 Intravenous - Market size and forecast 2025-2030

Chart on Intravenous - Market size and forecast 2025-2030 ($ million)
Data Table on Intravenous - Market size and forecast 2025-2030 ($ million)
Chart on Intravenous - Year-over-year growth 2025-2030 (%)
Data Table on Intravenous - Year-over-year growth 2025-2030 (%)

9.4 Intracerebroventricular - Market size and forecast 2025-2030

Chart on Intracerebroventricular - Market size and forecast 2025-2030 ($ million)
Data Table on Intracerebroventricular - Market size and forecast 2025-2030 ($ million)
Chart on Intracerebroventricular - Year-over-year growth 2025-2030 (%)
Data Table on Intracerebroventricular - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Route of Administration

Market opportunity by Route of Administration ($ million)
Data Table on Market opportunity by Route of Administration ($ million)

10. Market Segmentation by Type

10.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

10.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

10.3 Early infantile Krabbe disease - Market size and forecast 2025-2030

Chart on Early infantile Krabbe disease - Market size and forecast 2025-2030 ($ million)
Data Table on Early infantile Krabbe disease - Market size and forecast 2025-2030 ($ million)
Chart on Early infantile Krabbe disease - Year-over-year growth 2025-2030 (%)
Data Table on Early infantile Krabbe disease - Year-over-year growth 2025-2030 (%)

10.4 Juvenile Krabbe disease - Market size and forecast 2025-2030

Chart on Juvenile Krabbe disease - Market size and forecast 2025-2030 ($ million)
Data Table on Juvenile Krabbe disease - Market size and forecast 2025-2030 ($ million)
Chart on Juvenile Krabbe disease - Year-over-year growth 2025-2030 (%)
Data Table on Juvenile Krabbe disease - Year-over-year growth 2025-2030 (%)

10.5 Late infantile Krabbe disease - Market size and forecast 2025-2030

Chart on Late infantile Krabbe disease - Market size and forecast 2025-2030 ($ million)
Data Table on Late infantile Krabbe disease - Market size and forecast 2025-2030 ($ million)
Chart on Late infantile Krabbe disease - Year-over-year growth 2025-2030 (%)
Data Table on Late infantile Krabbe disease - Year-over-year growth 2025-2030 (%)

10.6 Adult-onset Krabbe disease - Market size and forecast 2025-2030

Chart on Adult-onset Krabbe disease - Market size and forecast 2025-2030 ($ million)
Data Table on Adult-onset Krabbe disease - Market size and forecast 2025-2030 ($ million)
Chart on Adult-onset Krabbe disease - Year-over-year growth 2025-2030 (%)
Data Table on Adult-onset Krabbe disease - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ million)
Data Table on Asia - Market size and forecast 2025-2030 ($ million)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.5.6 Thailand - Market size and forecast 2025-2030

Chart on Thailand - Market size and forecast 2025-2030 ($ million)
Data Table on Thailand - Market size and forecast 2025-2030 ($ million)
Chart on Thailand - Year-over-year growth 2025-2030 (%)
Data Table on Thailand - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.6.3 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.4 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.5 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.6 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.7 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.8 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Broad adoption of comprehensive neonatal diagnostics
Acceleration of clinical trials for small molecule therapeutics
Corporate consolidation in genetic medicines

13.2 Market challenges

High costs and complex gene therapy manufacturing
Stringent regulations and complex clinical trials
Gaps in newborn screening and diagnosis

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Accelerated approvals and small molecule pipeline expansion
Expanded integration of multiplex newborn screening technologies
Biopharma and patient advocacy collaborations

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 AbbVie Inc.

AbbVie Inc. - Overview
AbbVie Inc. - Business segments
AbbVie Inc. - Key news
AbbVie Inc. - Key offerings
AbbVie Inc. - Segment focus
SWOT

15.5 Astellas Pharma Inc.

Astellas Pharma Inc. - Overview
Astellas Pharma Inc. - Product / Service
Astellas Pharma Inc. - Key news
Astellas Pharma Inc. - Key offerings
SWOT

15.6 AstraZeneca Plc

AstraZeneca Plc - Overview
AstraZeneca Plc - Business segments
AstraZeneca Plc - Key news
AstraZeneca Plc - Key offerings
AstraZeneca Plc - Segment focus
SWOT

15.7 Bristol Myers Squibb Co.

Bristol Myers Squibb Co. - Overview
Bristol Myers Squibb Co. - Product / Service
Bristol Myers Squibb Co. - Key news
Bristol Myers Squibb Co. - Key offerings
SWOT

15.8 Jazz Pharmaceuticals Plc

Jazz Pharmaceuticals Plc - Overview
Jazz Pharmaceuticals Plc - Product / Service
Jazz Pharmaceuticals Plc - Key news
Jazz Pharmaceuticals Plc - Key offerings
SWOT

15.9 Johnson and Johnson

Johnson and Johnson - Overview
Johnson and Johnson - Business segments
Johnson and Johnson - Key news
Johnson and Johnson - Key offerings
Johnson and Johnson - Segment focus
SWOT

15.10 Merck and Co. Inc.

Merck and Co. Inc. - Overview
Merck and Co. Inc. - Business segments
Merck and Co. Inc. - Key news
Merck and Co. Inc. - Key offerings
Merck and Co. Inc. - Segment focus
SWOT

15.11 Novartis AG

Novartis AG - Overview
Novartis AG - Business segments
Novartis AG - Key news
Novartis AG - Key offerings
Novartis AG - Segment focus
SWOT

15.12 Pfizer Inc.

Pfizer Inc. - Overview
Pfizer Inc. - Business segments
Pfizer Inc. - Key news
Pfizer Inc. - Key offerings
Pfizer Inc. - Segment focus
SWOT

15.13 Sanofi SA

Sanofi SA - Overview
Sanofi SA - Business segments
Sanofi SA - Key news
Sanofi SA - Key offerings
Sanofi SA - Segment focus
SWOT

15.14 Sun Pharmaceutical Industries

Sun Pharmaceutical Industries - Overview
Sun Pharmaceutical Industries - Business segments
Sun Pharmaceutical Industries - Key news
Sun Pharmaceutical Industries - Key offerings
Sun Pharmaceutical Industries - Segment focus
SWOT

15.15 Takeda Pharmaceutical Ltd.

Takeda Pharmaceutical Ltd. - Overview
Takeda Pharmaceutical Ltd. - Business segments
Takeda Pharmaceutical Ltd. - Key news
Takeda Pharmaceutical Ltd. - Key offerings
Takeda Pharmaceutical Ltd. - Segment focus
SWOT

15.16 Teva Pharmaceutical Ltd.

Teva Pharmaceutical Ltd. - Overview
Teva Pharmaceutical Ltd. - Business segments
Teva Pharmaceutical Ltd. - Key news
Teva Pharmaceutical Ltd. - Key offerings
Teva Pharmaceutical Ltd. - Segment focus
SWOT

15.17 UCB SA

UCB SA - Overview
UCB SA - Product / Service
UCB SA - Key news
UCB SA - Key offerings
SWOT

15.18 Zydus Lifesciences Ltd.

Zydus Lifesciences Ltd. - Overview
Zydus Lifesciences Ltd. - Business segments
Zydus Lifesciences Ltd. - Key news
Zydus Lifesciences Ltd. - Key offerings
Zydus Lifesciences Ltd. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Krabbe Disease Treatment market growth will increase by USD 469.1 million during 2026-2030.

The Krabbe Disease Treatment market is expected to grow at a CAGR of 7.2% during 2026-2030.

Krabbe Disease Treatment market is segmented by Therapy (Anticonvulsants, Muscle relaxants, HSCT, Others) Route of administration (Intravenous, Intracerebroventricular) Type (Early infantile Krabbe disease, Juvenile Krabbe disease, Late infantile Krabbe disease, Adult-onset Krabbe disease)

AbbVie Inc., Amneal Pharmaceuticals Inc., Astellas Pharma Inc., AstraZeneca Plc, Aurobindo Pharma Ltd., Bristol Myers Squibb Co., Cipla Inc., Daiichi Sankyo Co. Ltd., Hikma Pharmaceuticals Plc, Jazz Pharmaceuticals Plc, Johnson and Johnson, Lupin Ltd., Merck and Co. Inc., Novartis AG, Pfizer Inc., Sanofi SA, Sun Pharmaceutical Industries, Takeda Pharmaceutical Ltd., Teva Pharmaceutical Ltd., UCB SA, Vertex Pharmaceuticals Inc., Zydus Lifesciences Ltd. are a few of the key vendors in the Krabbe Disease Treatment market.

North America will register the highest growth rate of 39.5% among the other regions. Therefore, the Krabbe Disease Treatment market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Indonesia, Thailand, Brazil, Australia, Saudi Arabia, UAE, Argentina, Turkey, South Africa, Israel

  • Broad adoption of comprehensive neonatal diagnostics is the driving factor this market.

The Krabbe Disease Treatment market vendors should focus on grabbing business opportunities from the Therapy segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
