


Photovoltaic (Pv) Inverter Market Size 2021-2030
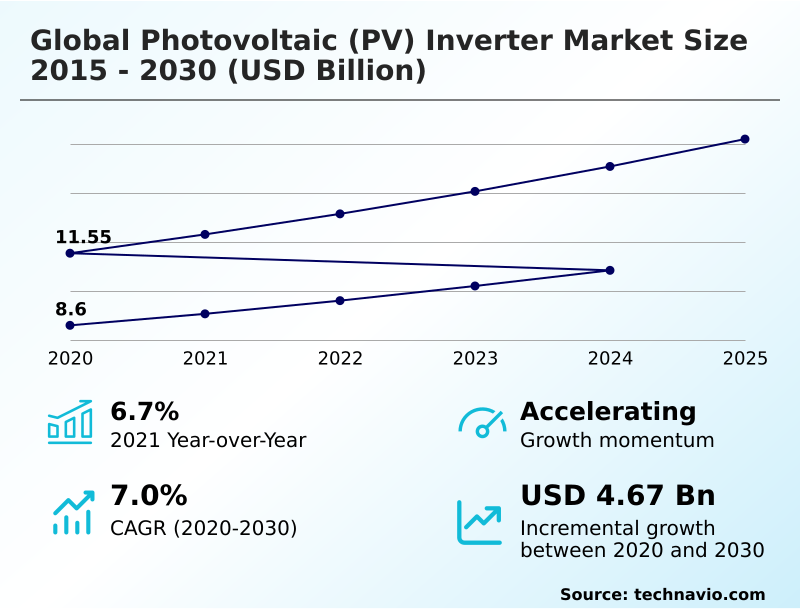
The photovoltaic (pv) inverter market size is valued to increase by USD 4.67 billion, at a CAGR of 7% from 2020 to 2030. Increasing integration of energy storage systems will drive the photovoltaic (pv) inverter market.
Major Market Trends & Insights
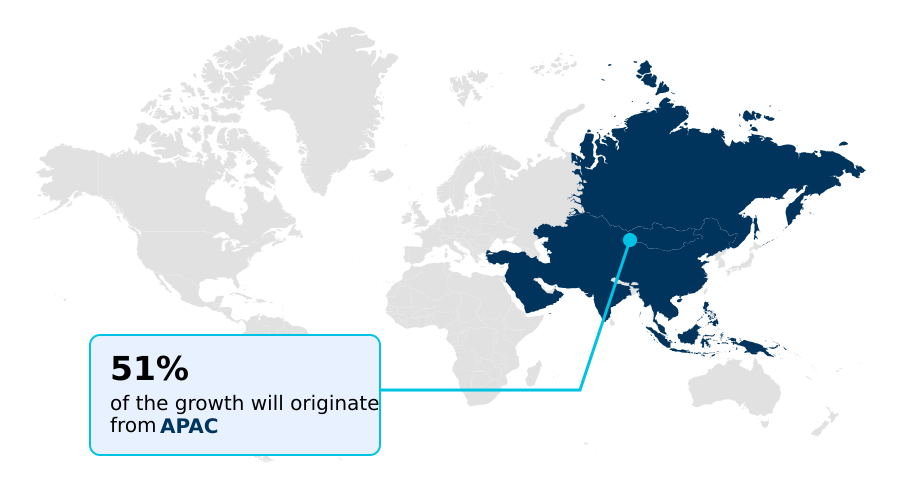
- APAC dominated the market and accounted for a 51.1% growth during the forecast period.
- By Product - String segment was valued at USD 5.65 billion in 2019
- By Type - On-grid segment accounted for the largest market revenue share in 2019
Market Size & Forecast
- Market Opportunities: USD 7.62 billion
- Market Future Opportunities: USD 4.67 billion
- CAGR from 2020 to 2030 : 7%
Market Summary
- The Photovoltaic (PV) Inverter Market operates as the technological linchpin of modern renewable energy infrastructure, directly translating solar generation into usable electrical power. Facility operators managing large-scale solar farms increasingly rely on advanced bi-directional energy flow hardware to optimize tariff structures and reduce reliance on fossil fuels.
- Transitioning to integrated hybrid architectures has yielded a 25% improvement in overall peak demand offset compared to traditional grid-following setups. A critical driver propelling the Photovoltaic (PV) Inverter Market is the rising necessity for energy independence, which compels utilities to deploy sophisticated grid-forming electronics to stabilize variable energy inputs. This shift guarantees seamless industrial operations during transmission fluctuations.
- Conversely, the industry faces severe limitations due to semiconductor supply chain bottlenecks, causing material shortages that directly inflate manufacturing costs and delay project commissioning timelines. Innovations in thermal mitigation fundamentally alter how engineers design high-capacity conversion hubs for extreme climates.
- As regulatory mandates push for stricter safety protocols, the deployment of intelligent power controllers remains absolutely essential for ensuring long-term network resilience.
What will be the Size of the Photovoltaic (Pv) Inverter Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Photovoltaic (Pv) Inverter Market Segmented?
The photovoltaic (pv) inverter industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2021-2030, as well as historical data from 2015-2019 for the following segments.
- Product
- String
- Central
- Micro
- Type
- On-grid
- Off-grid
- Product type
- Three-phase
- Single-phase
- Geography
- APAC
- China
- India
- Japan
- Australia
- South Korea
- Indonesia
- Europe
- Germany
- Spain
- Italy
- The Netherlands
- France
- UK
- North America
- US
- Canada
- Mexico
- Middle East and Africa
- Saudi Arabia
- UAE
- Turkey
- South Africa
- Israel
- South America
- Brazil
- Chile
- Argentina
- APAC
By Product Insights
The string segment is estimated to witness significant growth during the forecast period.
The string configuration establishes a highly versatile architecture within the Photovoltaic (PV) Inverter landscape, effectively balancing deployment costs with robust operational resilience. By directly linking solar module string configurations to a unified inverter, project developers eliminate complex wiring layouts.
This decentralized string inverter topology enables precise maximum power point tracking across diverse arrays, directly ensuring superior energy yield optimization.
Consequently, localized fault isolation improves by 15% compared to legacy centralized conversion units, preventing single-point failures from halting entire generation blocks. As commercial enterprises demand scalable microinverter architecture, the implementation of advanced high-frequency switching components radically enhances thermal stability.
Furthermore, incorporating off-grid battery management into varied agrivoltaic structural arrangements allows facility managers to maximize spatial efficiency and adapt to evolving environmental requirements seamlessly.
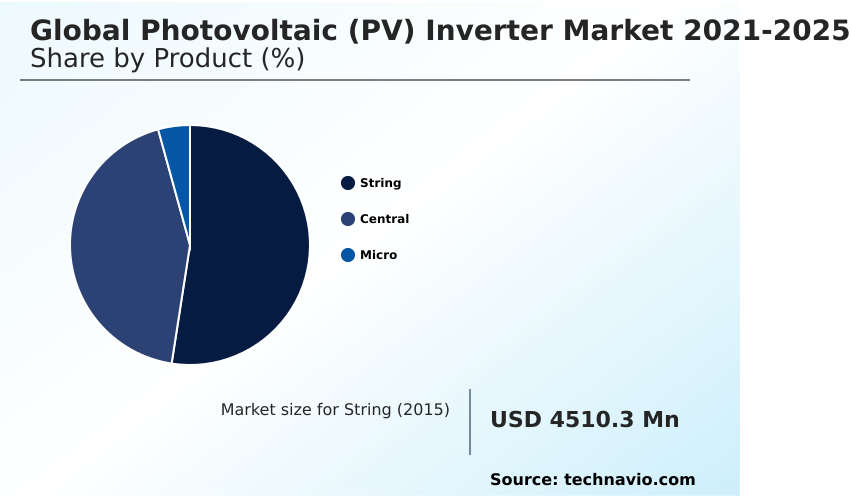
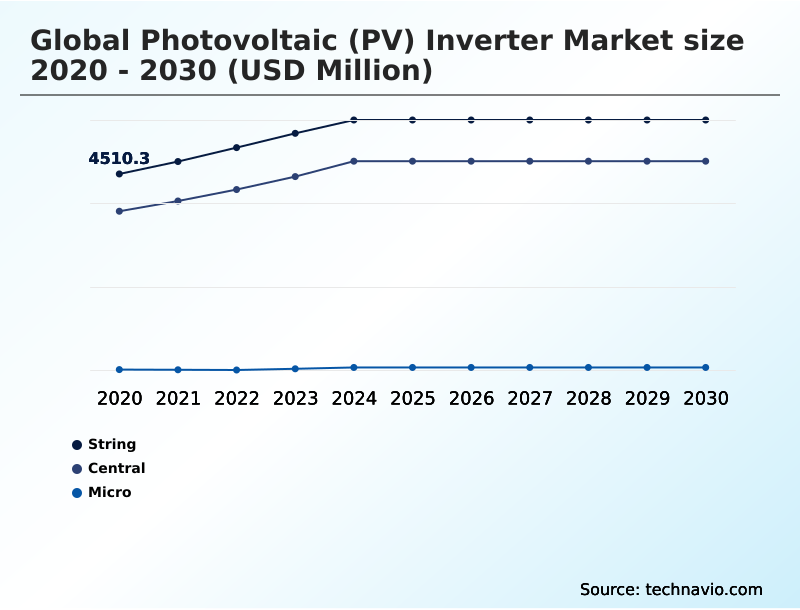
The String segment was valued at USD 5.65 billion in 2019 and showed a gradual increase during the forecast period.
Regional Analysis
APAC is estimated to contribute 51.1% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
See How Photovoltaic (Pv) Inverter Market Demand is Rising in APAC Get Free Sample
The structural demand for the Photovoltaic (PV) Inverter varies distinctly across geographic territories, driven by diverse regulatory frameworks and spatial constraints.
In APAC, expansive utility initiatives face severe climatic stress, prompting operators to adopt wide bandgap semiconductors for optimal thermal derating prevention, reducing heat-related downtime by nearly 20%.
Conversely, European markets prioritize advanced module-level power electronics for complex floating solar installations, achieving 15% higher spatial efficiency than traditional land-based setups. This structural divergence forces businesses to heavily customize their deployment strategies.
To navigate grid instability, European networks strictly enforce phase balancing algorithms and synthetic inertia generation, stabilizing their autonomous energy grids against variable weather.
Simultaneously, APAC installations increasingly leverage peak shaving functionalities alongside precise alternating current synchronization, allowing developers to optimize virtual power plant participation and significantly reduce reliance on fossil-fuel peaker plants during periods of high demand.
Market Dynamics
Our researchers analyzed the data with 2020 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The architectural advancement of the Photovoltaic (PV) Inverter highlights a distinct industry pivot toward maximizing both grid resilience and asset generation density across highly diverse operational environments. For commercial enterprise facilities, the mandate for high-capacity commercial energy storage integration ensures that surplus power is dispatched strategically, cutting peak utility expenditures by roughly 30% compared to standard, grid-reliant models.
- In remote or highly isolated sectors, the deployment of off-grid independent energy generation systems enables absolute operational autonomy, heavily reducing the logistical and financial burdens associated with maintaining traditional diesel fuel supply chains.
- Maximizing utility-scale power conversion efficiency metrics remains a structural priority for massive ground-mounted solar installations, which must continuously process extreme electrical loads to lower the overarching levelized cost of energy. Furthermore, infrastructure placed in arid deserts or coastal zones must strictly incorporate harsh environment thermal degradation prevention to protect sensitive internal components from catastrophic failure and prevent expensive unscheduled downtime.
- As energy networks become increasingly decentralized, facility operators are turning to real-time decentralized power network telemetry to seamlessly monitor asset health and dynamic performance. This profound level of digitalization empowers asset managers to proactively address system anomalies before they escalate, directly optimizing lifetime energy yields and greatly enhancing the long-term financial viability of large-scale renewable investments without inflating maintenance overheads.
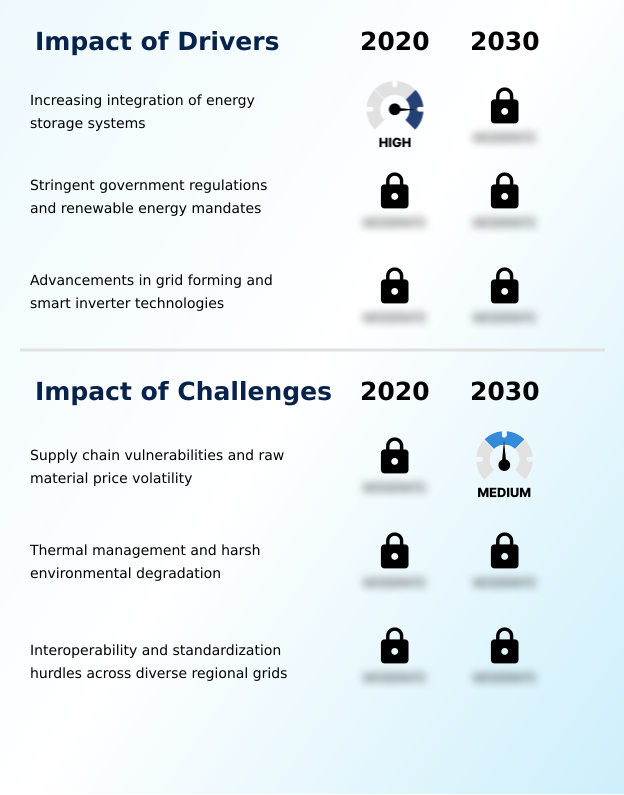
What are the key market drivers leading to the rise in the adoption of Photovoltaic (Pv) Inverter Industry?
- The increasing integration of energy storage systems acts as a primary catalyst for market expansion by ensuring consistent grid stability alongside variable renewable generation.
- Stringent grid resilience mandates fundamentally accelerate the deployment of advanced Photovoltaic (PV) Inverter technologies. As intermittent renewables dominate the energy mix, utilities demand robust grid-forming capability to actively establish stable frequency references, reducing localized power disruptions by up to 30%.
- The commercial urgency to maximize output drives the shift toward comprehensive hybrid energy storage integration, leveraging precise bidirectional power flow management to optimize consumption during peak pricing periods.
- This architectural upgrade utilizes advanced insulated gate bipolar transistors to process immense loads without thermal failure, improving system longevity by 15%.
- To support massive utility scale solar deployment, operators seamlessly incorporate reactive power compensation alongside complex net metering arrangements, ensuring that decentralized power networks maintain structural stability.
- Consequently, implementing superior salt mist corrosion resistance ensures these rapid shutdown mechanisms function flawlessly in harsh coastal environments.
What are the market trends shaping the Photovoltaic (Pv) Inverter Industry?
- The transition toward higher voltage system architectures in utility-scale projects represents a defining trend within the market. This architectural shift significantly enhances transmission efficiency while reducing overall operational costs.
- The structural evolution of the Photovoltaic (PV) Inverter reflects a massive shift toward intelligent grid support and maximized power density. To manage fluctuating inputs, facility operators increasingly rely on dynamic voltage regulation, which successfully decreases equipment trip-offs by 22% during sudden load spikes. Modern networks now require stringent anti-islanding protection to immediately disconnect systems during outages, fundamentally protecting utility personnel.
- By embedding advanced silicon carbide semiconductors, manufacturers have drastically cut conduction losses, elevating overall conversion efficiency by 18%. This technological upgrade enhances multi-mode operational architecture, ensuring seamless direct current handling across complex distributed energy resources.
- Additionally, the widespread deployment of residential rooftop arrays emphasizes rapid grid-tied synchronization, while sophisticated dynamic active power curtailment ensures that generating assets strictly comply with mandatory fault ride-through parameters, safeguarding continuous transmission stability.
What challenges does the Photovoltaic (Pv) Inverter Industry face during its growth?
- Persistent supply chain vulnerabilities and the severe price volatility of critical raw materials present significant structural barriers to continuous industry expansion.
- Managing severe thermal loads and ensuring digital security remain significant structural bottlenecks for Photovoltaic (PV) Inverter deployment. Continuous exposure to extreme temperatures rapidly degrades critical electrolytic capacitors, severely reducing operational lifespans by nearly 20% compared to temperature-controlled environments. To combat this physical degradation, engineering teams must deploy expensive active liquid cooling systems, which heavily inflates initial capital expenditures.
- Furthermore, the integration of complex low-voltage ride-through capabilities requires continuous active frequency response adjustments to prevent cascading network failures. As installations increasingly rely on cloud-based performance monitoring and digital smart grid telemetry, they face elevated maintenance overheads, prolonging development cycles and increasing systemic deployment costs by over 12%.
Exclusive Technavio Analysis on Customer Landscape
The photovoltaic (pv) inverter market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the photovoltaic (pv) inverter market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
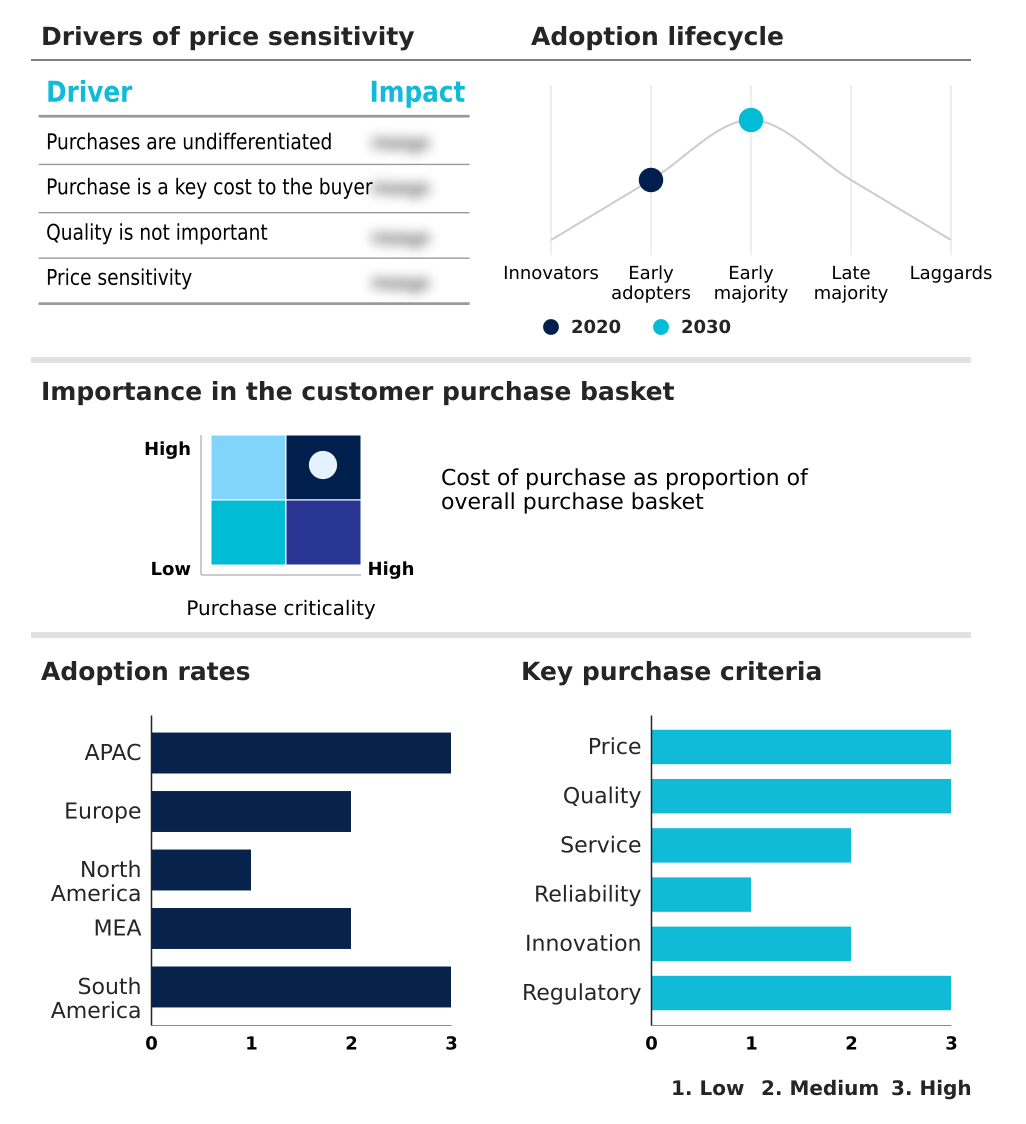
Customer Landscape of Photovoltaic (Pv) Inverter Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, photovoltaic (pv) inverter market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
CHINT Power Systems Co. Ltd. - The product portfolio delivers robust grid-tied hardware and smart energy management capabilities, ensuring optimal direct current processing and seamless integration for utility-scale and commercial renewable infrastructure projects.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- CHINT Power Systems Co. Ltd.
- Delta Electronics Inc.
- Enphase Energy Inc.
- Fimer SpA
- FOXESS CO. LTD.
- Fronius International GmbH
- GoodWe Technologies Co. Ltd.
- Growatt New Energy
- Hoymiles Power Electronics Inc.
- Huawei Technologies Co. Ltd.
- Ingeteam Corp. SA
- Kstar Group
- SAJ Electric
- Shenzhen Hopewind Electric
- Sineng Electric Co. Ltd.
- SMA Solar Technology AG
- SOFAR Solar
- SolarEdge Technologies Inc.
- SolaX Power Network Technology
- Solis
- Sungrow Power Supply Co. Ltd.
- TMEIC Corp.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Photovoltaic (pv) inverter market
- In the Electrical Components and Equipment industry, the regulatory enforcement of the EU Ecodesign Directive mandated higher energy efficiency standards for industrial power electronics, directly impacting Photovoltaic (PV) Inverter demand by requiring upgraded multi-mode conversion architectures.
- The rapid expansion of electric vehicle charging infrastructure necessitated structural grid upgrades across distribution networks, forcing Photovoltaic (PV) Inverter systems to adopt stricter overvoltage protection protocols to prevent localized grid congestion.
- Sustained material shortages in global semiconductor supply chains severely constrained the production of advanced bipolar transistors, forcing Photovoltaic (PV) Inverter manufacturers to redesign hardware platforms using alternative switching components to maintain delivery schedules.
- The widespread adoption of digitalization in heavy manufacturing drove the integration of industrial IoT sensors into factory energy systems, accelerating the demand for Photovoltaic (PV) Inverter solutions capable of seamless remote asset management.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Photovoltaic (Pv) Inverter Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 288 |
| Base year | 2020 |
| Historic period | 2015-2019 |
| Forecast period | 2021-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 7% |
| Market growth 2021-2030 | USD 4671.6 million |
| Market structure | Fragmented |
| YoY growth 2020-2021(%) | 6.7% |
| Key countries | China, India, Japan, Australia, South Korea, Indonesia, Germany, Spain, Italy, The Netherlands, France, UK, US, Canada, Mexico, Saudi Arabia, UAE, Turkey, South Africa, Israel, Brazil, Chile and Argentina |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Photovoltaic (PV) Inverter functions as the critical intelligence hub of contemporary renewable energy infrastructure. The ongoing transition toward complex storage integration allows facility operators to effectively balance variable generation with continuous base load demands.
- This shift directly influences corporate budgetary planning, as integrating bi-directional power flow controllers enables facilities to offset peak utility rates, delivering a 25% reduction in overall energy procurement costs compared to non-storage configurations. To handle increased operational loads, manufacturers rely heavily on advanced switching transistors and premium capacitors, which ensure robust electrical routing under extreme environmental stress.
- Furthermore, the integration of cloud-integrated telemetry and digital monitoring tools fundamentally transforms asset management, empowering operators to conduct predictive maintenance and limit unplanned outages. As grid operators impose stricter interconnection requirements, the inclusion of reactive phase compensation and dynamic frequency response becomes an absolute necessity for compliance.
- By standardizing these advanced technical capabilities, energy stakeholders safeguard critical infrastructure and maximize the operational longevity of large-scale solar generation fleets.
What are the Key Data Covered in this Photovoltaic (Pv) Inverter Market Research and Growth Report?
-
What is the expected growth of the Photovoltaic (Pv) Inverter Market between 2021 and 2030?
-
USD 4.67 billion, at a CAGR of 7%
-
-
What segmentation does the market report cover?
-
The report is segmented by Product (String, Central, and Micro), Type (On-grid, and Off-grid), Product Type (Three-phase, and Single-phase) and Geography (APAC, Europe, North America, Middle East and Africa, South America)
-
-
Which regions are analyzed in the report?
-
APAC, Europe, North America, Middle East and Africa and South America
-
-
What are the key growth drivers and market challenges?
-
Increasing integration of energy storage systems, Supply chain vulnerabilities and raw material price volatility
-
-
Who are the major players in the Photovoltaic (Pv) Inverter Market?
-
CHINT Power Systems Co. Ltd., Delta Electronics Inc., Enphase Energy Inc., Fimer SpA, FOXESS CO. LTD., Fronius International GmbH, GoodWe Technologies Co. Ltd., Growatt New Energy, Hoymiles Power Electronics Inc., Huawei Technologies Co. Ltd., Ingeteam Corp. SA, Kstar Group, SAJ Electric, Shenzhen Hopewind Electric, Sineng Electric Co. Ltd., SMA Solar Technology AG, SOFAR Solar, SolarEdge Technologies Inc., SolaX Power Network Technology, Solis, Sungrow Power Supply Co. Ltd. and TMEIC Corp.
-
Market Research Insights
- The integration of intelligent power conversion technology fundamentally enhances the operational viability of modern renewable energy assets. By leveraging advanced off-grid battery management, facility owners have reduced reliance on external power grids by up to 40%, directly lowering overhead utility costs.
- The widespread adoption of residential rooftop arrays now incorporates precise alternating current synchronization, improving localized energy consumption efficiency by nearly 25%. Furthermore, integrating these advanced systems into floating solar installations has increased spatial yield by 15% compared to land-constrained alternatives, optimizing capital returns. Such technological implementations ensure that decentralized energy generation aligns perfectly with stringent utility compliance codes.
We can help! Our analysts can customize this photovoltaic (pv) inverter market research report to meet your requirements.
 RIA -

