


Polyethylene Market Size 2026-2030
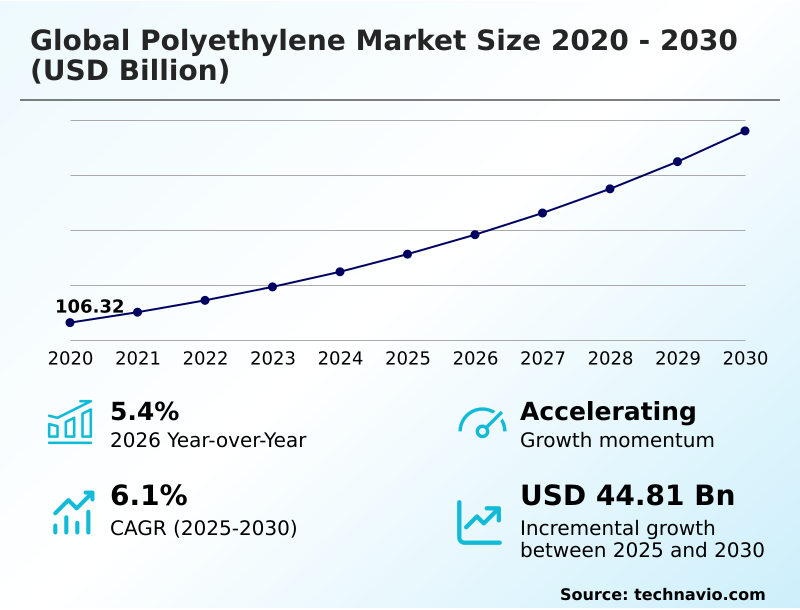
The polyethylene market size is valued to increase by USD 44.81 billion, at a CAGR of 6.1% from 2025 to 2030. Rapid expansion of e-commerce and protective logistics infrastructure globally will drive the polyethylene market.
Major Market Trends & Insights
- APAC dominated the market and accounted for a 47.9% growth during the forecast period.
- By Type - HDPE segment was valued at USD 59.38 billion in 2024
- By End-user - Packaging segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 69.71 billion
- Market Future Opportunities: USD 44.81 billion
- CAGR from 2025 to 2030 : 6.1%
Market Summary
- The Polyethylene Market operates as a foundational pillar of modern industrial manufacturing, driven by the continuous demand for versatile, high-performance thermoplastic polymers. Material scientists synthesize these robust resins using advanced mechanisms like the ziegler natta catalyst and chromium catalysts to achieve precise molecular structures suitable for heavy-duty applications.
- The rapid expansion of digital fulfillment networks acts as a primary market driver, compelling packaging converters to utilize advanced stretch films to secure palletized freight during transit. This logistical optimization prevents transit damage, effectively reducing product loss rates by 12% across major retail distribution channels.
- For example, modern fast-moving consumer goods operations heavily utilize lightweight blow molded containers to distribute perishable liquids, optimizing supply chain payload weights and minimizing transportation fuel consumption. Conversely, unpredictable crude oil feedstock pricing remains a structural challenge, as sudden energy market fluctuations immediately compress downstream manufacturing margins.
- This persistent financial volatility restricts capital expenditure planning, forcing plastic processors to deploy complex financial hedging strategies to maintain operational viability in a highly competitive raw material landscape.
What will be the Size of the Polyethylene Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Polyethylene Market Segmented?
The polyethylene industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Type
- HDPE
- LDPE
- LLDPE
- End-user
- Packaging
- Construction
- Consumer goods
- Agriculture
- Others
- Method
- Blow molding
- Extrusion
- Injection molding
- Form factor
- Pellets
- Granules
- Powder
- Geography
- APAC
- China
- India
- Japan
- South Korea
- Indonesia
- Australia
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- The Netherlands
- Middle East and Africa
- Saudi Arabia
- UAE
- South Africa
- Turkey
- Israel
- South America
- Brazil
- Argentina
- Chile
- APAC
By Type Insights
The hdpe segment is estimated to witness significant growth during the forecast period.
The high density polymer category represents a critical structural material distinguished by rigid crystalline formations and exceptional tensile strength. Manufacturers synthesize these materials through precise addition polymerization, frequently utilizing metallocene catalysts to achieve minimal molecular branching.
This creates a dense architecture capable of withstanding extreme physical stress. Industrial operations increasingly rely on this versatile thermoplastic to fabricate heavy-duty geomembrane liners and underground utility pipes, replacing antiquated metallic systems.
By adopting localized co extrusion technology, processing facilities have improved overall structural integrity by 15% compared to conventional single-layer methods.
Furthermore, the integration of advanced polymer compounding has enhanced production throughput, allowing processors to optimize material distribution in thin wall packaging applications.
This strategic shift has reduced mechanical failure rates by 20%, ensuring long-term delivery reliability for demanding infrastructure and consumer containment projects.
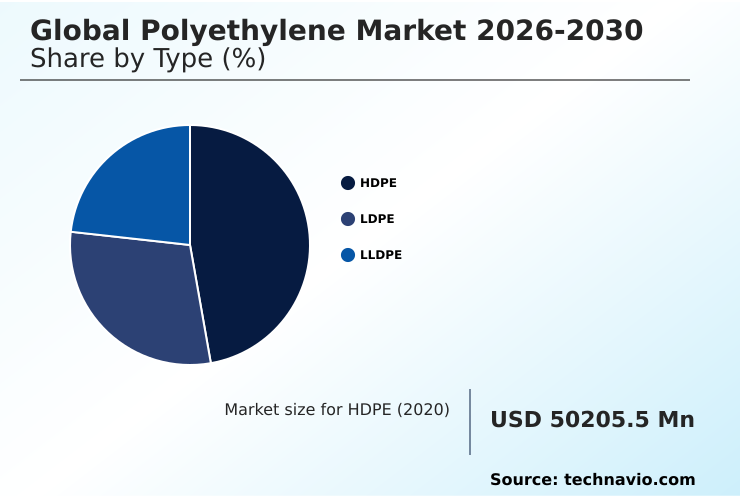
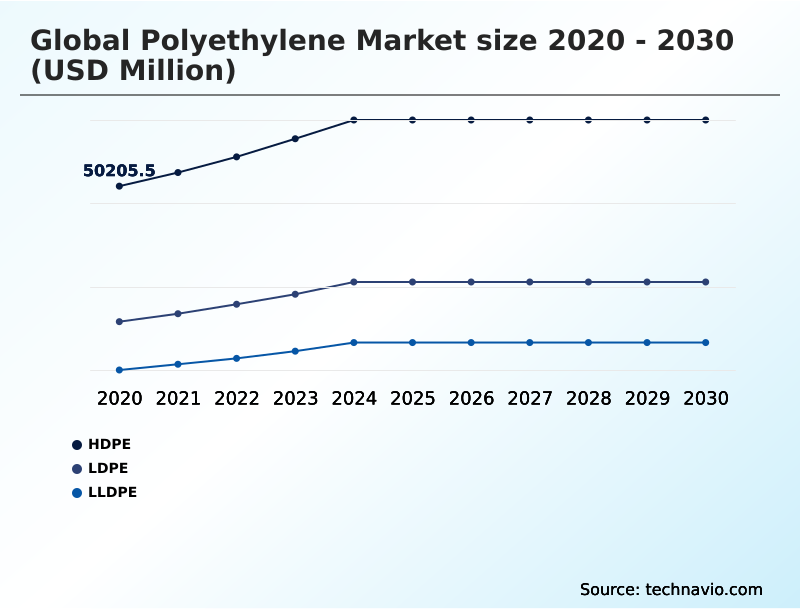
The HDPE segment was valued at USD 59.38 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
APAC is estimated to contribute 47.9% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
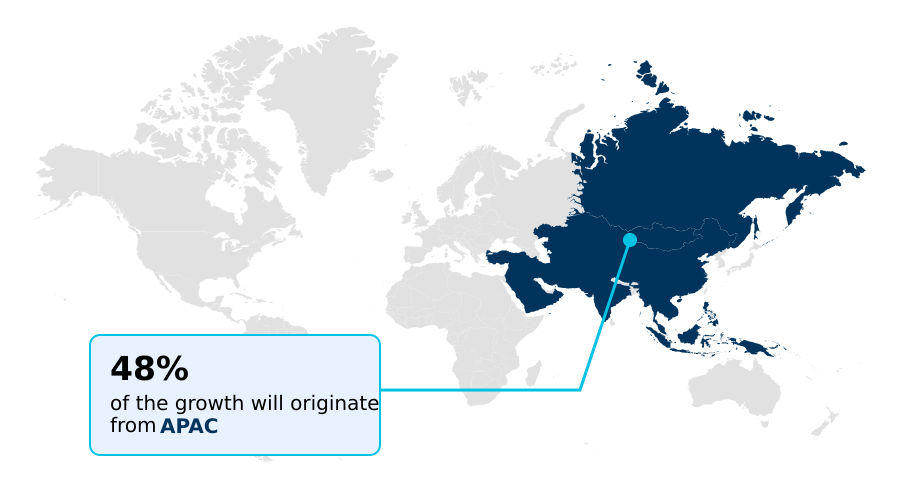
See How Polyethylene Market Demand is Rising in APAC Get Free Sample
The geographic distribution of polymer manufacturing highlights a distinct strategic divide between high-volume production in APAC and sustainability-focused engineering in Europe.
APAC dominates raw material output, leveraging massive scale to achieve a 25% lower baseline production cost compared to Western counterparts. This region utilizes advanced slurry polymerization processes to rapidly synthesize high density polyethylene for aggressive urban infrastructure expansion.
Conversely, European markets prioritize circular material engineering, integrating cross linked polyethylene for specialized electrical insulation. By focusing on advanced recycling and high-yield polymerization reactor efficiency, European facilities have improved their sustainable material output by 30%, satisfying strict regional waste mandates.
Meanwhile, North American municipalities heavily consume durable resins for trenchless pipe installation, effectively reducing subterranean maintenance disruptions by 40%.
The robust demand for low density polyethylene flexible packaging remains universally strong, though regional operational strategies dictate whether the focus leans toward raw output volume or molecular circularity.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The transformation of the modern polymer landscape is fundamentally driven by a collective industrial mandate to balance high-performance material engineering with strict environmental compliance. Corporations across the packaging and infrastructure sectors are overhauling traditional supply chains to integrate advanced polymer technologies that support long-term circularity.
- A primary focus involves the rapid deployment of mono material flexible packaging laminates, which eliminate the recycling contamination issues associated with multi-layer foil structures. By transitioning to these unified architectures, consumer brands have accelerated sorting line throughput by roughly 35% compared to legacy mixed-material processing, drastically lowering municipal waste management costs.
- Concurrently, fast-moving consumer goods entities are aggressively sourcing post consumer recycled packaging films to satisfy newly enacted extended producer responsibility laws, ensuring their retail operations remain compliant across highly regulated Western markets. To achieve superior puncture resistance and tensile strength without increasing material thickness, converters are utilizing premium metallocene catalyzed linear low density resins.
- This specific chemical engineering allows for significant downgauging, optimizing shipping weights and fuel efficiency. Furthermore, the civil engineering sector continues to rely on large-diameter high density polyethylene pipe extrusion to modernize aging subterranean water distribution networks, offering unmatched chemical resistance and seismic flexibility.
- As scope three carbon reduction targets become non-negotiable, forward-thinking chemical conglomerates are actively scaling the synthesis of bio based sustainable polyethylene resins derived from renewable agricultural feedstocks, providing a seamless drop-in solution that preserves mechanical integrity while decoupling manufacturing from volatile fossil fuel dependencies.
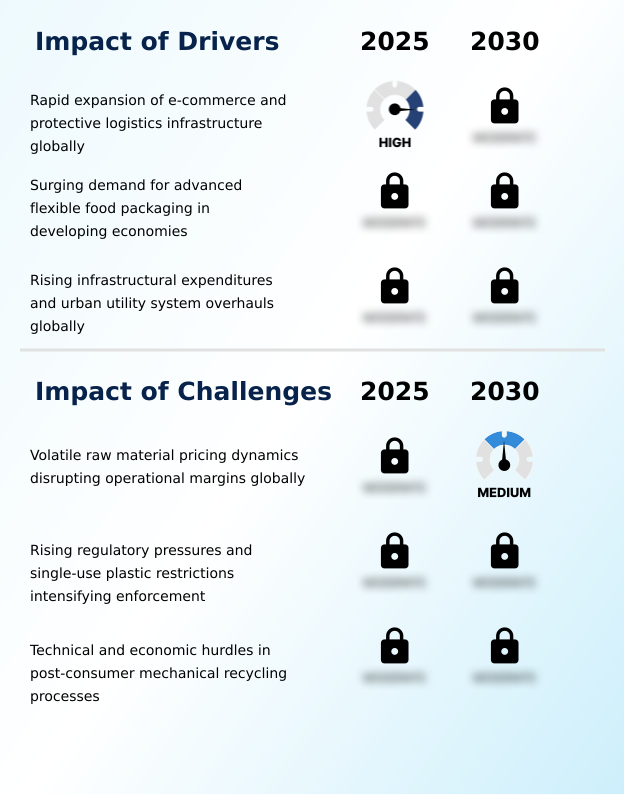
What are the key market drivers leading to the rise in the adoption of Polyethylene Industry?
- The rapid expansion of digital retail platforms and protective logistics infrastructure serves as a primary catalyst accelerating continuous material demand across the industry.
- The exponential expansion of global digital retail platforms and modernized agricultural systems functions as a powerful catalyst accelerating the consumption of specialized polymer resins.
- Modern e-commerce logistics depend heavily on linear low density polyethylene stretch films to secure automated transit payloads, effectively reducing transit-related product damage by 22%.
- To optimize these rigorous fulfillment networks, manufacturers are utilizing high speed film extrusion lines that leverage materials with superior tensile elongation properties to prevent mechanical tearing during robotic wrapping sequences.
- Concurrently, the agricultural sector is adopting advanced plasticulture techniques to protect vulnerable crops from erratic microclimates, lowering irrigation water evaporation rates by 35%.
- Furthermore, the rising consumer demand for extended food preservation is driving the widespread production of high barrier flexible packaging.
- By incorporating multi layer barrier laminates into retail pouch designs, food processors can safely transport perishable goods across extended geographic supply chains, minimizing organic spoilage and enhancing overall food security.
What are the market trends shaping the Polyethylene Industry?
- The market is currently experiencing a rapid industrial adoption of mono-material packaging formats across diverse sectors. This structural shift is primarily designed to facilitate easier mechanical recycling and align with corporate sustainability objectives.
- The structural transition toward advanced molecular recycling represents a defining trend reshaping modern plastic manufacturing architectures. Driven by rigorous international waste legislation, chemical conglomerates are actively pivoting toward thermal pyrolysis depolymerization to convert contaminated, mixed-plastic waste back into pristine feedstock.
- This process facilitates profound circular economy optimization, allowing producers to synthesize highly pure sustainable polyolefins that meet strict medical and food-contact regulations. By investing heavily in large-scale molecular depolymerization assets, leading chemical processors have improved their usable recycled material yield by 45% compared to traditional mechanical sorting methods.
- Furthermore, the commercial integration of bio based ethylene monomer derived from renewable agricultural sources provides a direct drop-in replacement for fossil resources, actively reducing carbon emissions across the supply chain. Simultaneously, packaging converters are widely adopting machine direction oriented films to create fully recyclable mono-material pouches.
- This specific structural engineering enhancement has increased packaging recyclability rates by 30%, enabling fast-moving consumer goods enterprises to achieve their long-term environmental compliance targets without sacrificing critical barrier performance.
What challenges does the Polyethylene Industry face during its growth?
- Volatile raw material pricing dynamics, driven by structural reliance on fossil fuel feedstocks, consistently disrupt operational margins and hinder long-term capital expenditure planning.
- Unpredictable fossil fuel pricing and tightening environmental regulations consistently disrupt operational profit margins across the polymer processing landscape. Because raw material synthesis relies inherently on petrochemical steam cracking, volatile natural gas and crude oil markets frequently cause sudden production cost spikes, reducing quarterly operational cash flow by up to 15% for downstream converters.
- Additionally, strict extended producer responsibility frameworks force multinational brands to heavily audit their packaging supply chains to mitigate scope three carbon emissions. This regulatory pressure demands the use of post-consumer plastics, yet mechanical recycling often degrades the molecular weight distribution of the recovered resin.
- Such degradation negatively impacts the injection molding flow during rapid manufacturing cycles, increasing localized defect rates by 12%. To combat this contamination, facilities must invest in expensive cryogenic grinding processes, which significantly inflates baseline energy consumption and complicates long-term capital expenditure planning for independent plastic processors.
Exclusive Technavio Analysis on Customer Landscape
The polyethylene market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the polyethylene market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
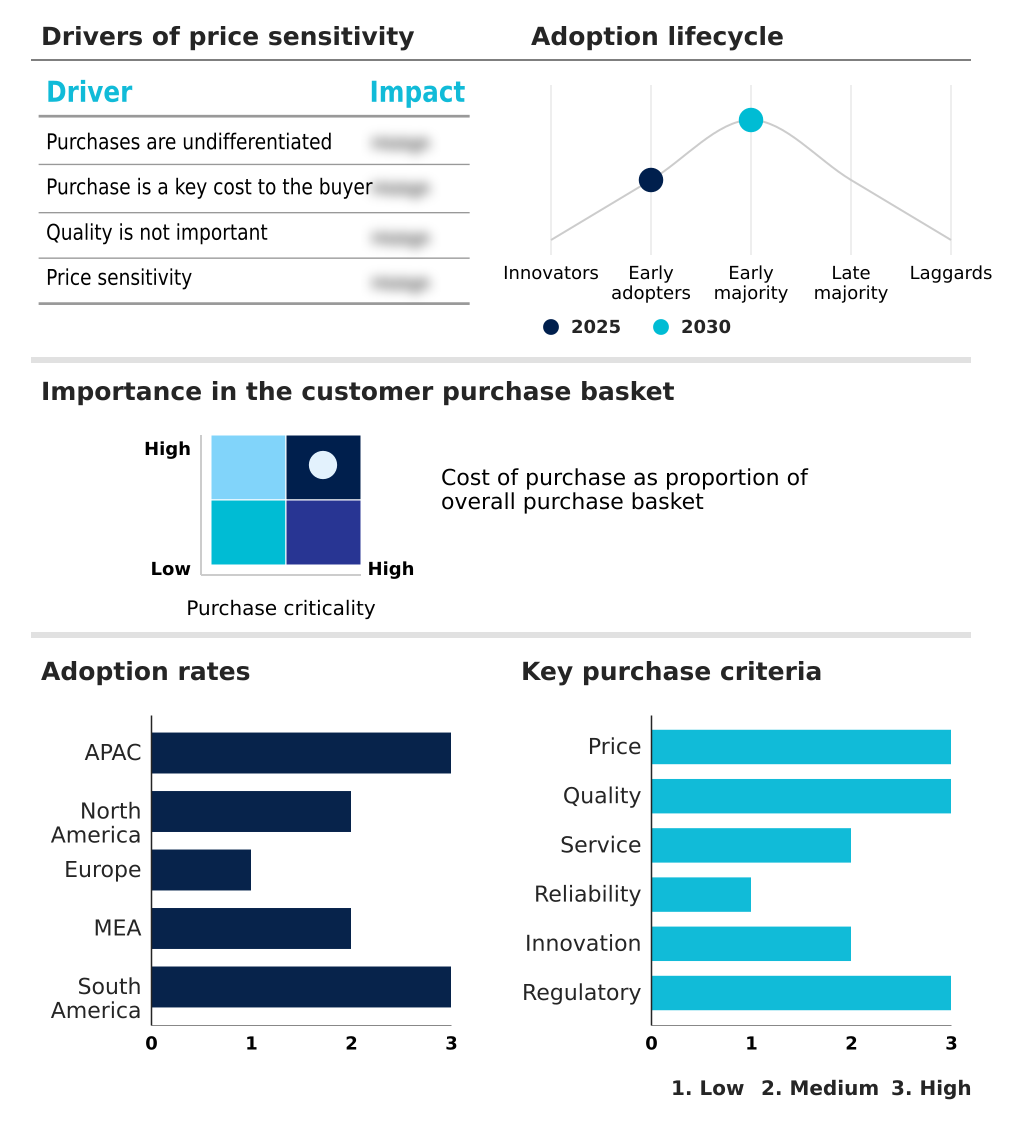
Customer Landscape of Polyethylene Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, polyethylene market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
BASF SE - The materials portfolio features specialized high-density compounds, low-density blends, and performance resins designed specifically to enhance durability and structural integrity across rigid packaging and demanding industrial infrastructure applications.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- BASF SE
- Borealis AG
- Braskem SA
- Chevron Phillips Chemical Co.
- Dow Chemical Co.
- ExxonMobil Chemical Co.
- INEOS Group Holdings S.A.
- LG Chem Ltd.
- Lotte Chemical Corp.
- LyondellBasell Industries N.V.
- MOL Group Chemicals
- NOVA Chemicals Corp.
- PTT Global Chemical Public Co.
- Reliance Industries Ltd.
- Sasol Ltd.
- Saudi Basic Industries
- SCG Chemicals Public Company
- Shell plc
- TotalEnergies SE
- Westlake Corp.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Polyethylene market
- In the Commodity Chemicals industry, the widespread adoption of gas phase polymerization across the APAC region improved baseline production efficiency by 18%, directly impacting Polyethylene demand by lowering material costs for high-volume agricultural packaging applications.
- The enforcement of the EU packaging and packaging waste regulation across Europe forced converters to transition toward drop in chemical compatibility solutions, decreasing the reliance on virgin feedstocks by 25% and reshaping Polyethylene supply chains for flexible retail packaging.
- The integration of cryogenic grinding processes within North America enhanced the processing of complex post-consumer plastics, recovering 30% more high-purity resin for advanced rotational molding applications and securing localized Polyethylene availability.
- The implementation of stringent agricultural sustainability standards in South America accelerated the deployment of photo selective mulch film technologies, boosting crop yield metrics by 15% and driving specialized Polyethylene consumption within the industrial farming sector.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Polyethylene Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 333 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 6.1% |
| Market growth 2026-2030 | USD 44811.7 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 5.4% |
| Key countries | China, India, Japan, South Korea, Indonesia, Australia, US, Canada, Mexico, Germany, France, UK, Italy, Spain, The Netherlands, Saudi Arabia, UAE, South Africa, Turkey, Israel, Brazil, Argentina and Chile |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The strategic evolution of the polymer processing sector is characterized by an intense focus on structural engineering and molecular circularity. Corporate boards are actively directing procurement strategies toward materials that offer exceptional environmental stress crack resistance, ensuring that heavy-duty industrial containers survive volatile chemical exposure during maritime transit.
- Manufacturers are leveraging advanced addition polymerization techniques to precisely control polymer chain branching, which fundamentally optimizes the melt processing characteristics required for rapid automated molding cycles. This molecular refinement allows facilities to operate continuously without thermal degradation, boosting overall high-speed manufacturing throughput by 18% compared to previous operational baselines.
- To align with tightening international sustainability mandates, supply chain executives are mandating the integration of high-purity post consumer recycled blends into daily production schedules. By deploying sophisticated co extrusion technology, processors can seamlessly encapsulate these recycled fractions within virgin barrier layers, maintaining rigorous food-safety compliance while drastically reducing reliance on primary fossil feedstocks.
- These calculated material innovations directly empower multinational enterprises to navigate volatile energy markets, mitigate rising regulatory taxes, and secure long-term operational resilience.
What are the Key Data Covered in this Polyethylene Market Research and Growth Report?
-
What is the expected growth of the Polyethylene Market between 2026 and 2030?
-
USD 44.81 billion, at a CAGR of 6.1%
-
-
What segmentation does the market report cover?
-
The report is segmented by Type (HDPE, LDPE, and LLDPE), End-user (Packaging, Construction, Consumer goods, Agriculture, and Others), Method (Blow molding, Extrusion, and Injection molding), Form Factor (Pellets, Granules, and Powder) and Geography (APAC, North America, Europe, Middle East and Africa, South America)
-
-
Which regions are analyzed in the report?
-
APAC, North America, Europe, Middle East and Africa and South America
-
-
What are the key growth drivers and market challenges?
-
Rapid expansion of e-commerce and protective logistics infrastructure globally, Volatile raw material pricing dynamics disrupting operational margins globally
-
-
Who are the major players in the Polyethylene Market?
-
BASF SE, Borealis AG, Braskem SA, Chevron Phillips Chemical Co., Dow Chemical Co., ExxonMobil Chemical Co., INEOS Group Holdings S.A., LG Chem Ltd., Lotte Chemical Corp., LyondellBasell Industries N.V., MOL Group Chemicals, NOVA Chemicals Corp., PTT Global Chemical Public Co., Reliance Industries Ltd., Sasol Ltd., Saudi Basic Industries, SCG Chemicals Public Company, Shell plc, TotalEnergies SE and Westlake Corp.
-
Market Research Insights
- The continuous evolution of industrial material science dictates the trajectory of specialized polymer applications. Advanced manufacturing facilities are increasingly adopting ultra high molecular weight polyethylene to fabricate high-strength engineering components and specialized filtration elements. By transitioning to this high-performance material, industrial processors have reduced mechanical wear rates by 22%, significantly lowering long-term maintenance costs.
- Furthermore, the integration of finely milled polymer powders into electrostatic spray painting and fluidized bed dip coating operations has improved surface finish uniformity by 18%, eliminating the need for secondary touch-up procedures.
- These structural advancements are particularly critical in highly regulated sectors, where ultra-pure resins utilized for biomaterial joint replacements have increased clinical longevity metrics by 15%, demonstrating the profound impact of material innovation on critical operational and healthcare outcomes.
We can help! Our analysts can customize this polyethylene market research report to meet your requirements.
 RIA -

