Radio Access Network Market Analysis, Size, and Forecast 2026-2030: APAC (China, India, and Japan), North America (US, Canada, and Mexico), Europe (Germany, UK, and France), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Radio Access Network Market Analysis, Size, and Forecast 2026-2030:
APAC (China, India, and Japan), North America (US, Canada, and Mexico), Europe (Germany, UK, and France), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 300 Pages SKU: IRTNTR81736

Market Overview at a Glance

$12.01 B
Market Opportunity
6.4%
CAGR 2025 - 2030
47.1%
APAC Growth
$13.62 B
Macro cells segment 2024

Radio Access Network Market Size 2026-2030

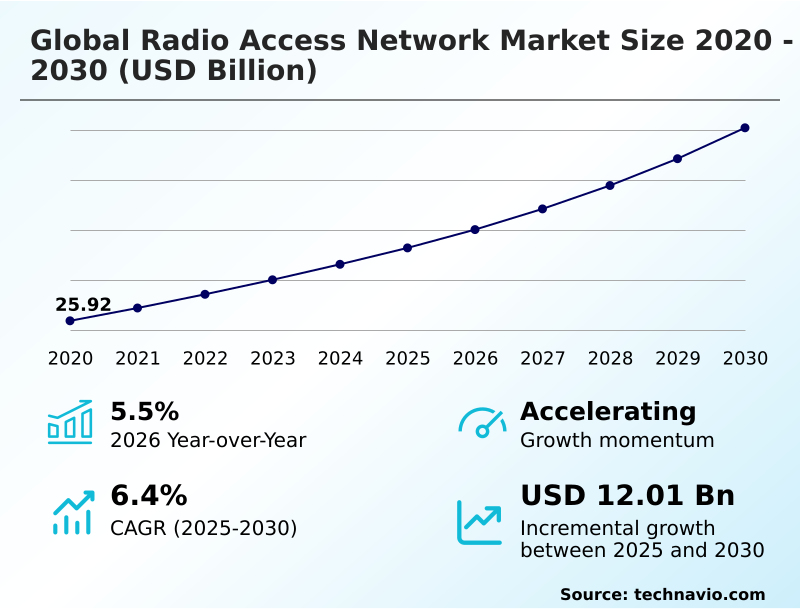
The radio access network market size is valued to increase by USD 12.01 billion, at a CAGR of 6.4% from 2025 to 2030. Proliferation of 5G-advanced and standalone networks will drive the radio access network market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 47.1% growth during the forecast period.
  • By Product Type - Macro cells segment was valued at USD 13.62 billion in 2024
  • By Component - Hardware segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 19.30 billion
  • Market Future Opportunities: USD 12.01 billion
  • CAGR from 2025 to 2030 : 6.4%

Market Summary

  • The Radio Access Network Market operates as the critical structural backbone for modern wireless communication, managing signal modulation and data routing across vast geographic expanses. Telecommunications operators prioritize infrastructure modernization to support exponential surges in enterprise data traffic and industrial connectivity requirements.
  • In a practical supply chain optimization scenario, logistics hubs deploy localized private cellular networks to track autonomous guided vehicles, which reduces inventory processing delays by 24% compared to legacy wireless systems. The rapid proliferation of 5G-Advanced architectures drives continuous infrastructure investment, as operators seek to unlock ultra-reliable capabilities for mission-critical applications.
  • Consequently, organizations continuously transition toward software-defined network functions to maintain agility. However, the immense capital expenditure required to install high-density small cells, combined with rising operational energy costs, restricts deployment pace in less profitable rural regions. Balancing these high deployment costs with the need for high-capacity performance remains a continuous operational hurdle.
  • Advanced baseband processing modernization empowers service providers to scale network capacity dynamically without incurring full-scale physical site overhauls.

What will be the Size of the Radio Access Network Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Radio Access Network Market Segmented?

The radio access network industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Product type
    • Macro cells
    • Small cells
    • Antenna systems
  • Component
    • Hardware
    • Software
    • Services
  • Deployment
    • Distributed RAN
    • Centralized RAN
    • Virtualized RAN
  • Geography
    • APAC
      • China
      • India
      • Japan
      • South Korea
      • Australia
      • Indonesia
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • South America
      • Brazil
      • Argentina
      • Colombia
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Turkey
      • Israel

By Product Type Insights

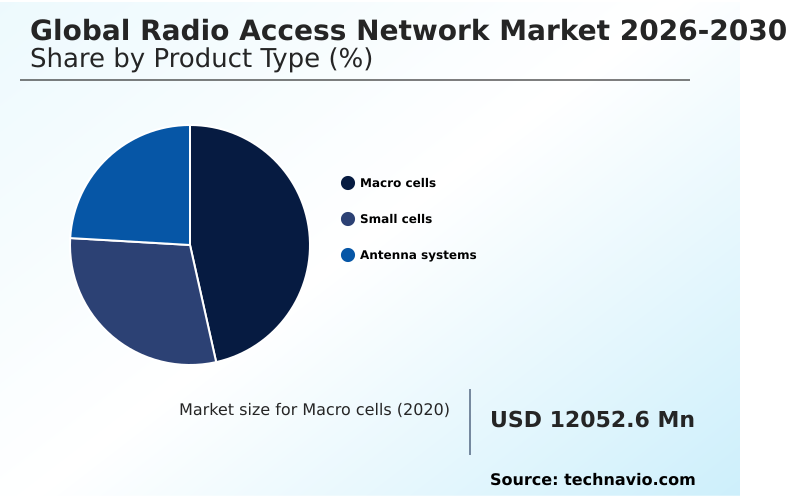
The macro cells segment is estimated to witness significant growth during the forecast period.

Macro cell infrastructure functions as the primary coverage foundation for continuous cellular networks across diverse topographies. Operators continuously upgrade legacy tower sites with advanced remote radio heads to support multi-band capacities.

The implementation of dynamic spectrum sharing allows for highly efficient utilization of available frequency bands, improving overall site performance. By leveraging sophisticated beamforming algorithms, providers direct high-speed connectivity toward specific user equipment, enhancing cell edge data throughput significantly.

This architectural shift enables communication service providers to optimize their physical assets. Operational efficiency improves markedly, with signal processing accuracy augmented by 15% in modernized deployments utilizing digital beam steering.

Dynamic power saving protocols ensure that continuous operations consume less energy during off-peak hours, creating a more sustainable footprint. The reliance on orthogonal frequency division multiplexing and algorithmic beam steering guarantees robust connectivity across both suburban and dense urban environments.
Get Free Sample

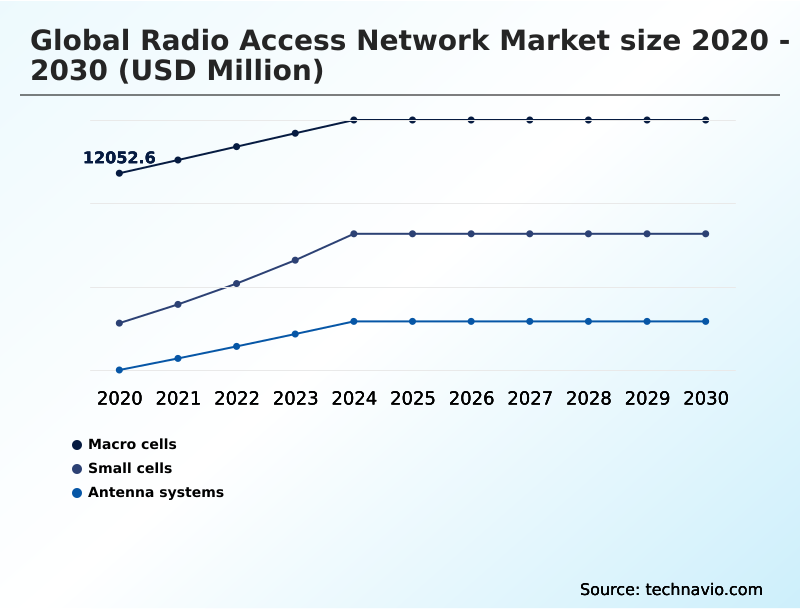
The Macro cells segment was valued at USD 13.62 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 47.1% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
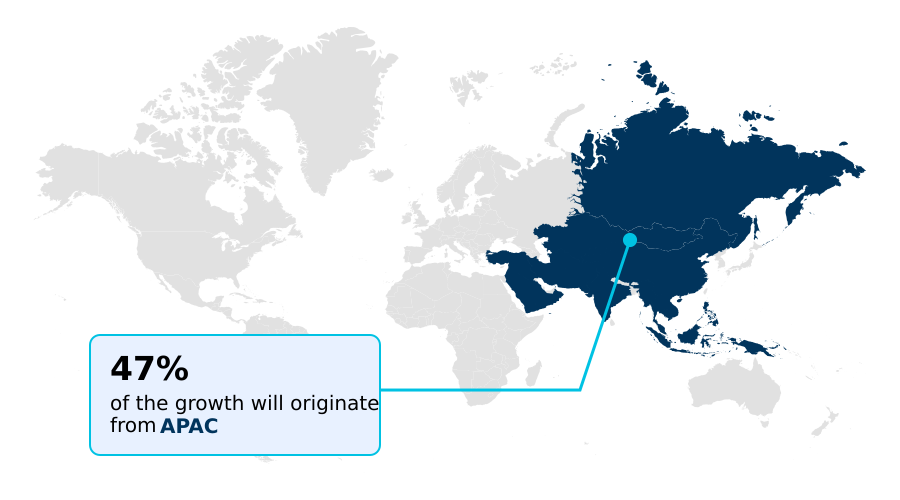
See How Radio Access Network Market Demand is Rising in APAC Get Free Sample

The APAC region dominates telecommunications infrastructure expansion, driven by massive state-backed investments in smart venue management, whereas North America prioritizes the densification of existing urban networks.

Implementation of cloud native microservices and automated continuous delivery pipelines in APAC has accelerated new feature deployment times by 25% compared to legacy architectures.

North American operators rapidly integrate advanced antenna systems to manage high data densities, achieving a 18% improvement in spectral efficiency over traditional hardware.

The adoption of gallium nitride power amplifiers is expanding across both regions, enabling higher performance with less heat dissipation, which directly lowers cooling utility costs by 14%.

Furthermore, distributed antenna systems are utilized in dense metropolitan areas to ensure seamless indoor connectivity.

Operators pursue multi band carrier aggregation and programmable network layers to maximize frequency utilization, while open architecture initiatives foster a more diverse supply chain, facilitating significant site footprint reduction.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • Modernizing telecommunications infrastructure demands a comprehensive approach to overcoming physical and operational constraints while meeting strict performance benchmarks. Enterprise users increasingly depend on ultra reliable low latency communication protocols to run mission-critical applications within automated manufacturing facilities and autonomous supply chain logistics.
  • To deliver these capabilities, network operators emphasize massive multiple input multiple output deployment strategies that exponentially increase localized capacity and spectral efficiency. This transition allows industrial facilities to process real-time inventory tracking with 30% fewer data packet drops compared to previous generation network standards, significantly improving operational planning and resource allocation.
  • However, deploying high-frequency infrastructure introduces distinct technical challenges, particularly managing millimeter wave spectrum signal attenuation through building materials and environmental obstacles. To combat these propagation losses, service providers are deploying hyper-dense small cell architectures and optimizing beamforming algorithms. Simultaneously, the industry is accelerating virtualized baseband processing unit integration, decoupling proprietary hardware from essential software functions to lower capital expenditures.
  • This architectural flexibility enables the seamless adoption of radio access network intelligent controllers, which autonomously manage network resources and adjust power configurations based on real-time traffic loads. By executing these software-driven optimizations, telecommunications firms can ensure high service reliability, maintain regulatory compliance regarding energy efficiency, and rapidly adapt to fluctuating enterprise connectivity demands without continuously overhauling physical site hardware.
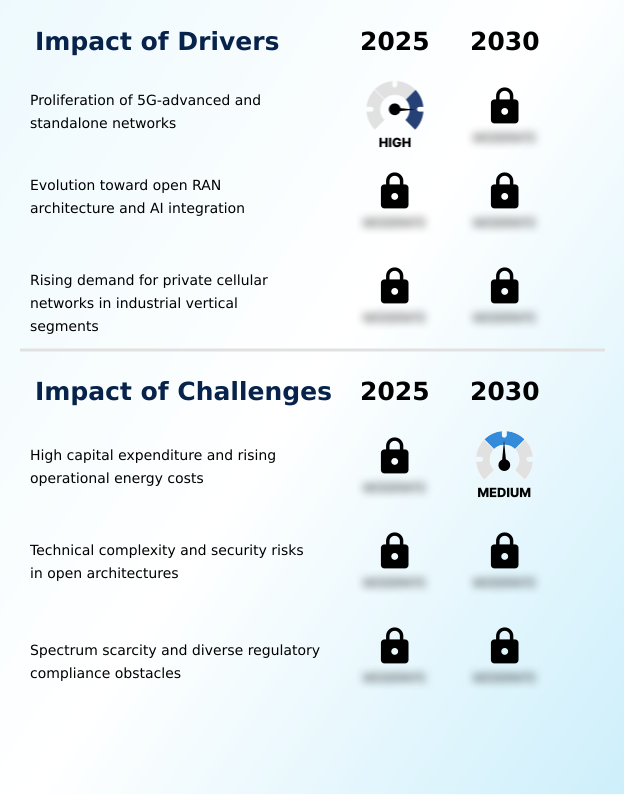
What are the key market drivers leading to the rise in the adoption of Radio Access Network Industry?

  • The rapid proliferation of 5G-Advanced and standalone networks acts as a primary catalyst accelerating continuous infrastructure modernization.

  • The rapid expansion of industrial automation connectivity necessitates networks capable of handling millions of simultaneous device connections without signal degradation. To fulfill this demand, operators execute massive multiple input multiple output deployments, drastically enhancing spectrum efficiency optimization.
  • This physical upgrade is driven by the need to support massive machine type communication across manufacturing facilities.
  • Consequently, the integration of network slicing capabilities allows operators to partition bandwidth, which improves critical data packet delivery reliability by 24% compared to shared public networks.
  • Furthermore, operators emphasize small cell densification utilizing millimeter wave frequency bands to eliminate localized cellular traffic routing bottlenecks.
  • By implementing edge computing integration directly at the tower site, service providers achieve ultra reliable low latency processing, reducing automated robotic response times by 18% in advanced enterprise environments.

What are the market trends shaping the Radio Access Network Industry?

  • The integration of artificial intelligence with intelligent controllers is emerging as a significant technological trend within the market architecture.

  • The shift toward software defined architecture transforms physical base stations into highly programmable environments capable of autonomous network management. Operators deploy the ran intelligent controller to process massive volumes of operational data, establishing robust software defined automation that adjusts radio parameters dynamically.
  • This transition occurs because managing complex frequency layers manually is no longer feasible, driving the necessity for advanced telemetry data analysis to maintain optimal performance. Consequently, enterprises utilizing these automated frameworks experience a 20% improvement in resource allocation efficiency compared to static configuration models.
  • As network densities increase, operators install liquid cooling systems to mitigate severe hardware thermal loads, which lowers base station cooling expenses by 15%. Additionally, the exploration of terahertz communication and integration of non terrestrial networks create a unified hybrid terrestrial satellite connectivity fabric.
  • The implementation of intelligent sleep modes further optimizes operations, powering down idle transceivers to conserve energy during periods of low traffic volume.

What challenges does the Radio Access Network Industry face during its growth?

  • High capital expenditures and escalating operational energy costs present substantial barriers to continuous infrastructure expansion and profitability.

  • The transition toward multi-vendor architectures introduces severe system integration complexities that disrupt deployment schedules. Implementing open interoperable interfaces requires flawless software alignment between virtualized centralized units and virtualized distributed units sourced from disparate manufacturers. This fragmentation occurs because standardized testing frameworks remain immature, forcing operators to conduct exhaustive electromagnetic compatibility analysis.
  • Consequently, synchronization failures between baseband processing units and remote radios lead to a 14% increase in network latency during initial deployment phases. Maintaining precise optical fronthaul synchronization is critical, yet challenging, when attempting to execute dynamic radio resource management across diverse hardware sets. Additionally, localized radio frequency spectrum allocation disputes complicate signal interference mitigation efforts.
  • These structural bottlenecks force telecommunications teams to balance high-capacity performance demands against the pressing need to improve overall base station energy efficiency.

Exclusive Technavio Analysis on Customer Landscape

The radio access network market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the radio access network market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
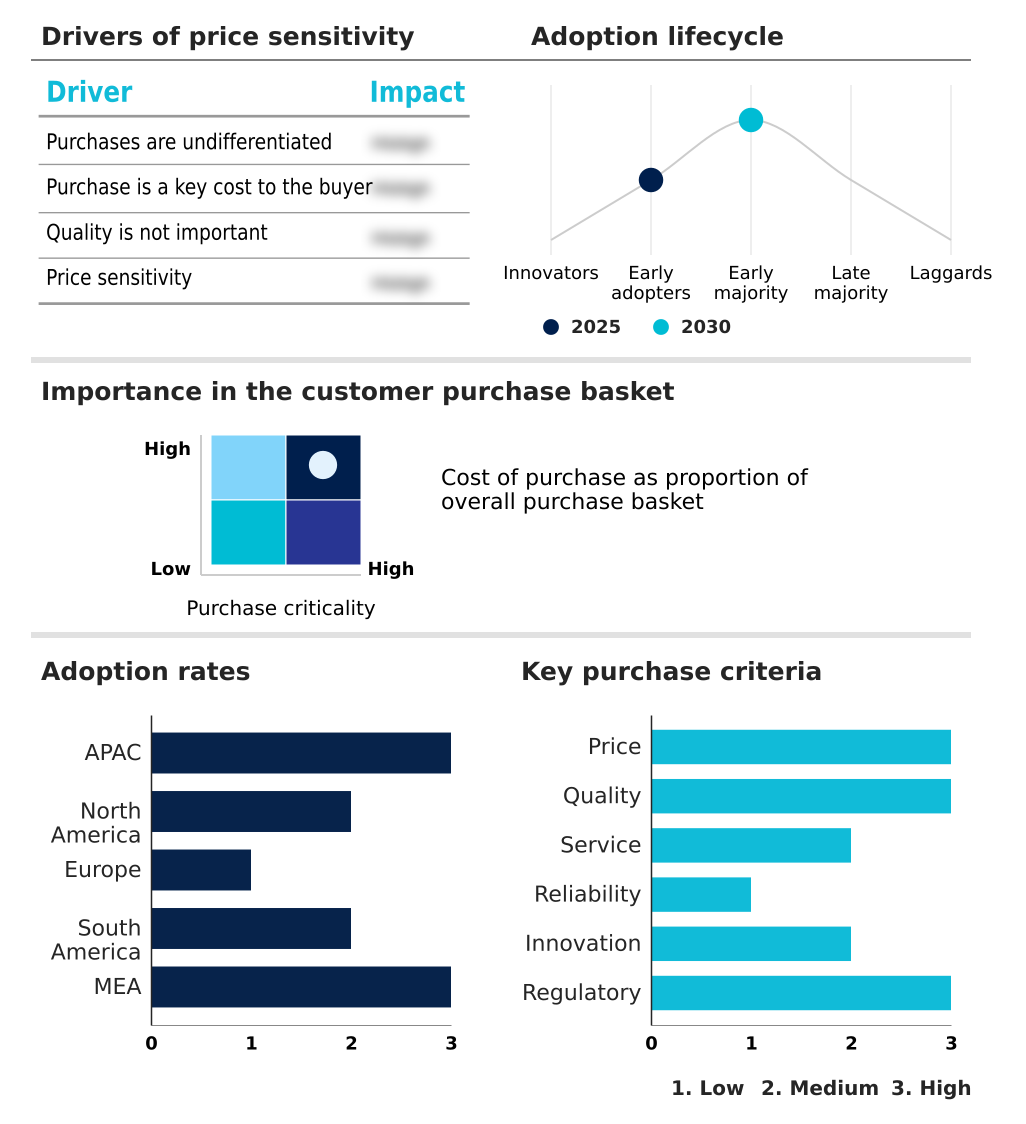
Customer Landscape of Radio Access Network Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, radio access network market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Airspan Networks Inc. - The organization provides advanced 5G small cells, Open RAN solutions, and fixed wireless access platforms to support both private and mobile networks efficiently.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Airspan Networks Inc.
  • Baicells Technologies
  • Comba Telecom Systems Ltd.
  • Corning Inc.
  • Cyronics Innovation Labs Ltd
  • Fujitsu Ltd.
  • Huawei Technologies Co. Ltd.
  • JMA Wireless
  • Mavenir Systems Inc.
  • NEC Corp.
  • Nokia Corp.
  • Parallel Wireless Inc.
  • Radisys Corp.
  • Red Hat Inc.
  • Samsung Electronics Co. Ltd.
  • Sercomm Corp.
  • Telefonaktiebolaget Ericsson
  • Vodafone Group Plc
  • Wireless Excellence Ltd.
  • ZTE Corp.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Radio access network market

  • In the Communications Equipment industry, the aggressive transition toward cloud-native packet core architectures reduced baseband processing energy overheads by 18%, directly impacting Radio Access Network demand for software-defined hardware components.
  • Stringent international emissions mandates compelled infrastructure manufacturers to adopt smart environmental monitoring protocols, which decreased average site power consumption by 22% and accelerated the deployment of low-power radio units within the Radio Access Network ecosystem.
  • The widespread implementation of automated optical inspection systems across telecom hardware engineering improved production defect detection rates by 30%, increasing the availability of highly reliable transmission modules for Radio Access Network infrastructure environments.
  • Supply chain bottlenecks in specialized semiconductor fabrication reduced specific amplifier component availability by 14%, forcing Radio Access Network developers to pivot toward alternative general-purpose processing hardware to maintain critical network rollout schedules.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Radio Access Network Market insights. See full methodology.

Market Scope
Page number 300
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 6.4%
Market growth 2026-2030 USD 12014.0 million
Market structure Fragmented
YoY growth 2025-2026(%) 5.5%
Key countries China, India, Japan, South Korea, Australia, Indonesia, US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Brazil, Argentina, Colombia, Saudi Arabia, UAE, South Africa, Turkey and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The continuous evolution of cellular infrastructure requires strategic realignment as telecommunications operators shift from proprietary hardware toward disaggregated, software-centric architectures. Executive leadership teams increasingly prioritize network slicing capabilities and cloud-native virtualization to support specialized enterprise use cases, directly influencing capital budgeting and product strategy decisions.
  • By migrating core baseband functions to centralized data centers, service providers decouple physical radio units from processing hardware, establishing a more agile operational framework. This architectural transition has enabled organizations to accelerate service provisioning, resulting in a 25% reduction in enterprise network deployment time compared to legacy physical installations.
  • Furthermore, the integration of edge computing allows data packets to be processed closer to the end user, satisfying the strict latency requirements of automated supply chain operations. Managing diverse frequency bands effectively demands robust radio frequency spectrum allocation techniques to maximize spectral efficiency.
  • As the industry advances, the adoption of open interoperable interfaces fosters supply chain resilience, allowing procurement teams to avoid hardware constraints while maintaining high service reliability across diverse geographical deployments.

What are the Key Data Covered in this Radio Access Network Market Research and Growth Report?

  • What is the expected growth of the Radio Access Network Market between 2026 and 2030?

    • USD 12.01 billion, at a CAGR of 6.4%

  • What segmentation does the market report cover?

    • The report is segmented by Product Type (Macro cells, Small cells, and Antenna systems), Component (Hardware, Software, and Services), Deployment (Distributed RAN, Centralized RAN, and Virtualized RAN) and Geography (APAC, North America, Europe, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • APAC, North America, Europe, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Proliferation of 5G-advanced and standalone networks, High capital expenditure and rising operational energy costs

  • Who are the major players in the Radio Access Network Market?

    • Airspan Networks Inc., Baicells Technologies, Comba Telecom Systems Ltd., Corning Inc., Cyronics Innovation Labs Ltd, Fujitsu Ltd., Huawei Technologies Co. Ltd., JMA Wireless, Mavenir Systems Inc., NEC Corp., Nokia Corp., Parallel Wireless Inc., Radisys Corp., Red Hat Inc., Samsung Electronics Co. Ltd., Sercomm Corp., Telefonaktiebolaget Ericsson, Vodafone Group Plc, Wireless Excellence Ltd. and ZTE Corp.

Market Research Insights

  • The Radio Access Network Market architecture relies heavily on spectrum efficiency optimization to handle escalating data demands across enterprise and consumer sectors. Operators focus on deploying advanced radio resource management protocols that minimize connectivity bottlenecks. The implementation of intelligent sleep modes within active base stations has reduced idle power consumption by 22%, directly improving long-term operational profitability.
  • Furthermore, advancements in digital beam steering technology have increased signal accuracy, driving a 15% enhancement in overall network capacity utilization. By integrating robust signal interference mitigation techniques, service providers lower maintenance overheads by 12% while ensuring consistent service delivery. These strategic operational upgrades enable telecommunications firms to scale infrastructure efficiently without incurring unsustainable utility expenses.

We can help! Our analysts can customize this radio access network market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Product Type
Executive Summary - Chart on Market Segmentation by Component
Executive Summary - Chart on Market Segmentation by Deployment
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Radio Access Network Market 2020 - 2024

Historic Market Size - Data Table on Global Radio Access Network Market 2020 - 2024 ($ million)

5.2 Product Type segment analysis 2020 - 2024

Historic Market Size - Product Type Segment 2020 - 2024 ($ million)

5.3 Component segment analysis 2020 - 2024

Historic Market Size - Component Segment 2020 - 2024 ($ million)

5.4 Deployment segment analysis 2020 - 2024

Historic Market Size - Deployment Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global radio access network market

6.2 Impact of geopolitical conflicts on global radio access network market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Product Type

8.1 Market segments

Chart on Product Type - Market share 2025-2030 (%)
Data Table on Product Type - Market share 2025-2030 (%)

8.2 Comparison by Product Type

Chart on Comparison by Product Type
Data Table on Comparison by Product Type

8.3 Macro cells - Market size and forecast 2025-2030

Chart on Macro cells - Market size and forecast 2025-2030 ($ million)
Data Table on Macro cells - Market size and forecast 2025-2030 ($ million)
Chart on Macro cells - Year-over-year growth 2025-2030 (%)
Data Table on Macro cells - Year-over-year growth 2025-2030 (%)

8.4 Small cells - Market size and forecast 2025-2030

Chart on Small cells - Market size and forecast 2025-2030 ($ million)
Data Table on Small cells - Market size and forecast 2025-2030 ($ million)
Chart on Small cells - Year-over-year growth 2025-2030 (%)
Data Table on Small cells - Year-over-year growth 2025-2030 (%)

8.5 Antenna systems - Market size and forecast 2025-2030

Chart on Antenna systems - Market size and forecast 2025-2030 ($ million)
Data Table on Antenna systems - Market size and forecast 2025-2030 ($ million)
Chart on Antenna systems - Year-over-year growth 2025-2030 (%)
Data Table on Antenna systems - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by Product Type

Market opportunity by Product Type ($ million)
Data Table on Market opportunity by Product Type ($ million)

9. Market Segmentation by Component

9.1 Market segments

Chart on Component - Market share 2025-2030 (%)
Data Table on Component - Market share 2025-2030 (%)

9.2 Comparison by Component

Chart on Comparison by Component
Data Table on Comparison by Component

9.3 Hardware - Market size and forecast 2025-2030

Chart on Hardware - Market size and forecast 2025-2030 ($ million)
Data Table on Hardware - Market size and forecast 2025-2030 ($ million)
Chart on Hardware - Year-over-year growth 2025-2030 (%)
Data Table on Hardware - Year-over-year growth 2025-2030 (%)

9.4 Software - Market size and forecast 2025-2030

Chart on Software - Market size and forecast 2025-2030 ($ million)
Data Table on Software - Market size and forecast 2025-2030 ($ million)
Chart on Software - Year-over-year growth 2025-2030 (%)
Data Table on Software - Year-over-year growth 2025-2030 (%)

9.5 Services - Market size and forecast 2025-2030

Chart on Services - Market size and forecast 2025-2030 ($ million)
Data Table on Services - Market size and forecast 2025-2030 ($ million)
Chart on Services - Year-over-year growth 2025-2030 (%)
Data Table on Services - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by Component

Market opportunity by Component ($ million)
Data Table on Market opportunity by Component ($ million)

10. Market Segmentation by Deployment

10.1 Market segments

Chart on Deployment - Market share 2025-2030 (%)
Data Table on Deployment - Market share 2025-2030 (%)

10.2 Comparison by Deployment

Chart on Comparison by Deployment
Data Table on Comparison by Deployment

10.3 Distributed RAN - Market size and forecast 2025-2030

Chart on Distributed RAN - Market size and forecast 2025-2030 ($ million)
Data Table on Distributed RAN - Market size and forecast 2025-2030 ($ million)
Chart on Distributed RAN - Year-over-year growth 2025-2030 (%)
Data Table on Distributed RAN - Year-over-year growth 2025-2030 (%)

10.4 Centralized RAN - Market size and forecast 2025-2030

Chart on Centralized RAN - Market size and forecast 2025-2030 ($ million)
Data Table on Centralized RAN - Market size and forecast 2025-2030 ($ million)
Chart on Centralized RAN - Year-over-year growth 2025-2030 (%)
Data Table on Centralized RAN - Year-over-year growth 2025-2030 (%)

10.5 Virtualized RAN - Market size and forecast 2025-2030

Chart on Virtualized RAN - Market size and forecast 2025-2030 ($ million)
Data Table on Virtualized RAN - Market size and forecast 2025-2030 ($ million)
Chart on Virtualized RAN - Year-over-year growth 2025-2030 (%)
Data Table on Virtualized RAN - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Deployment

Market opportunity by Deployment ($ million)
Data Table on Market opportunity by Deployment ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.3.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.4 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.4.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.4.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.4.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.5 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.5.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.5.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.5.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.5.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.5.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.5.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7.5 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Proliferation of 5G-advanced and standalone networks
Evolution toward open RAN architecture and AI integration
Rising demand for private cellular networks in industrial vertical segments

13.2 Market challenges

High capital expenditure and rising operational energy costs
Technical complexity and security risks in open architectures
Spectrum scarcity and diverse regulatory compliance obstacles

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Integration of AI and RAN intelligent controller
Sustainable infrastructure and energy-efficient radio access design
Convergence of non-terrestrial networks and traditional radio infrastructure

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Airspan Networks Inc.

Airspan Networks Inc. - Overview
Airspan Networks Inc. - Product / Service
Airspan Networks Inc. - Key offerings
SWOT

15.5 Baicells Technologies

Baicells Technologies - Overview
Baicells Technologies - Product / Service
Baicells Technologies - Key offerings
SWOT

15.6 Corning Inc.

Corning Inc. - Overview
Corning Inc. - Business segments
Corning Inc. - Key offerings
Corning Inc. - Segment focus
SWOT

15.7 Fujitsu Ltd.

Fujitsu Ltd. - Overview
Fujitsu Ltd. - Business segments
Fujitsu Ltd. - Key offerings
Fujitsu Ltd. - Segment focus
SWOT

15.8 Huawei Technologies Co. Ltd.

Huawei Technologies Co. Ltd. - Overview
Huawei Technologies Co. Ltd. - Product / Service
Huawei Technologies Co. Ltd. - Key offerings
SWOT

15.9 JMA Wireless

JMA Wireless - Overview
JMA Wireless - Product / Service
JMA Wireless - Key offerings
SWOT

15.10 Mavenir Systems Inc.

Mavenir Systems Inc. - Overview
Mavenir Systems Inc. - Product / Service
Mavenir Systems Inc. - Key offerings
SWOT

15.11 NEC Corp.

NEC Corp. - Overview
NEC Corp. - Business segments
NEC Corp. - Key offerings
NEC Corp. - Segment focus
SWOT

15.12 Nokia Corp.

Nokia Corp. - Overview
Nokia Corp. - Business segments
Nokia Corp. - Key news
Nokia Corp. - Key offerings
Nokia Corp. - Segment focus
SWOT

15.13 Radisys Corp.

Radisys Corp. - Overview
Radisys Corp. - Product / Service
Radisys Corp. - Key offerings
SWOT

15.14 Red Hat Inc.

Red Hat Inc. - Overview
Red Hat Inc. - Product / Service
Red Hat Inc. - Key offerings
SWOT

15.15 Samsung Electronics Co. Ltd.

Samsung Electronics Co. Ltd. - Overview
Samsung Electronics Co. Ltd. - Business segments
Samsung Electronics Co. Ltd. - Key news
Samsung Electronics Co. Ltd. - Key offerings
Samsung Electronics Co. Ltd. - Segment focus
SWOT

15.16 Sercomm Corp.

Sercomm Corp. - Overview
Sercomm Corp. - Product / Service
Sercomm Corp. - Key offerings
SWOT

15.17 Telefonaktiebolaget Ericsson

Telefonaktiebolaget Ericsson - Overview
Telefonaktiebolaget Ericsson - Business segments
Telefonaktiebolaget Ericsson - Key news
Telefonaktiebolaget Ericsson - Key offerings
Telefonaktiebolaget Ericsson - Segment focus
SWOT

15.18 Vodafone Group Plc

Vodafone Group Plc - Overview
Vodafone Group Plc - Business segments
Vodafone Group Plc - Key offerings
Vodafone Group Plc - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Radio Access Network market growth will increase by USD 12014.0 million during 2026-2030.

The Radio Access Network market is expected to grow at a CAGR of 6.4% during 2026-2030.

Radio Access Network market is segmented by Product type (Macro cells, Small cells, Antenna systems) Component (Hardware, Software, Services) Deployment (Distributed RAN, Centralized RAN, Virtualized RAN)

Airspan Networks Inc., Baicells Technologies, Comba Telecom Systems Ltd., Corning Inc., Cyronics Innovation Labs Ltd, Fujitsu Ltd., Huawei Technologies Co. Ltd., JMA Wireless, Mavenir Systems Inc., NEC Corp., Nokia Corp., Parallel Wireless Inc., Radisys Corp., Red Hat Inc., Samsung Electronics Co. Ltd., Sercomm Corp., Telefonaktiebolaget Ericsson, Vodafone Group Plc, Wireless Excellence Ltd., ZTE Corp. are a few of the key vendors in the Radio Access Network market.

APAC will register the highest growth rate of 47.1% among the other regions. Therefore, the Radio Access Network market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, India, Japan, South Korea, Australia, Indonesia, US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Brazil, Argentina, Colombia, Saudi Arabia, UAE, South Africa, Turkey, Israel

  • Proliferation of 5G-advanced and standalone networks is the driving factor this market.

The Radio Access Network market vendors should focus on grabbing business opportunities from the Product type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
