Satellite-based Augmentation Systems Market Analysis, Size, and Forecast 2026-2030: APAC (China, Japan, and India), North America (US, Canada, and Mexico), Europe (Germany, France, and UK), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and Turkey), and Rest of World (ROW)

Satellite-based Augmentation Systems Market Analysis, Size, and Forecast 2026-2030:
APAC (China, Japan, and India), North America (US, Canada, and Mexico), Europe (Germany, France, and UK), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and Turkey), and Rest of World (ROW)

Published: Oct 2026 310 Pages SKU: IRTNTR74960

Market Overview at a Glance

$194.80 Mn
Market Opportunity
4.6%
CAGR 2025 - 2030
51.3%
APAC Growth
$568.37 Mn
Aviation segment 2024

Satellite-Based Augmentation Systems Market Size 2026-2030

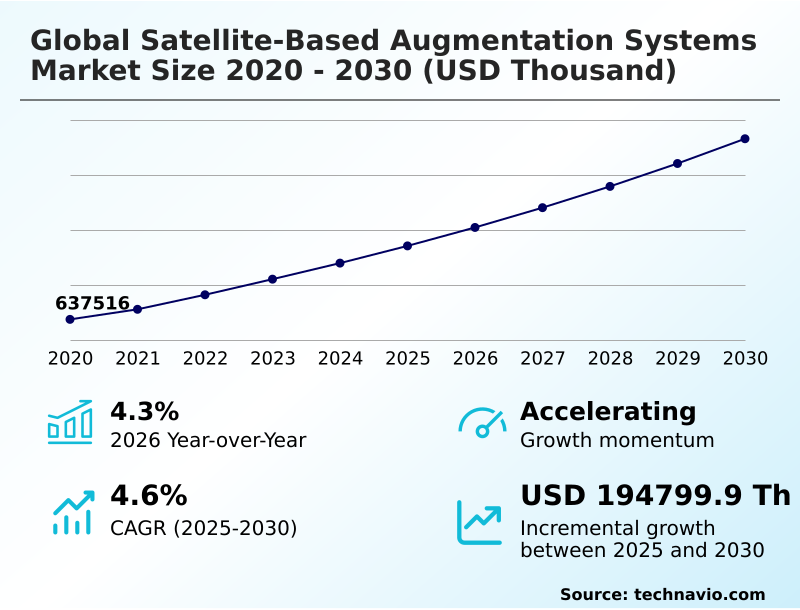
The satellite-based augmentation systems market size is valued to increase by USD 194.80 million, at a CAGR of 4.6% from 2025 to 2030. Increasing dependence on precision-guided aviation operations will drive the satellite-based augmentation systems market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 51.3% growth during the forecast period.
  • By Application - Aviation segment was valued at USD 568.37 million in 2024
  • By Type - WAAS segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities:
  • Market Future Opportunities: USD 194.80 million
  • CAGR from 2025 to 2030 : 4.6%

Market Summary

  • The Satellite-Based Augmentation Systems Market is experiencing structural transformation driven by the escalating demand for flawless location intelligence across critical operations. Organizations managing complex logistics and construction site engineering increasingly rely on synchronized reference station networks and robust uplink facilities to execute autonomous robotics navigation safely.
  • For instance the integration of high-precision correction data into railway network asset tracking allows transit authorities to optimize scheduling improving rolling stock utilization by 22% compared to conventional terrestrial positioning frameworks. The primary driver of this market remains the expanding necessity for continuous integrity monitoring algorithms that support smart city planning and disaster management operations by ensuring precise spatial data.
  • However the industry faces substantial constraints regarding atmospheric anomalies implementing effective ionospheric scintillation mitigation requires continuous recalibration of geostationary satellite payloads adding significant operational complexity. Despite these environmental barriers the underlying architecture continues to evolve delivering critical positioning assurance for modern digital infrastructure.

What will be the Size of the Satellite-Based Augmentation Systems Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Satellite-Based Augmentation Systems Market Segmented?

The satellite-based augmentation systems industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD thousand" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Application
    • Aviation
    • Maritime
    • Others
  • Type
    • WAAS
    • EGNOS
    • MSAS
    • Others
  • Solution
    • SBAS payload
    • Reference station
    • Uplink station
    • Others
  • Geography
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • France
      • UK
      • Italy
      • Spain
      • The Netherlands
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • Turkey
      • Israel
      • South Africa

By Application Insights

The aviation segment is estimated to witness significant growth during the forecast period.

The aviation segment within the Global Satellite-Based Augmentation Systems Market 2026-2030 requires highly accurate continuous navigation support across commercial flight operations.

Airlines and civil aviation regulators increasingly integrate high-accuracy positioning into performance-based navigation strategies enabling improved access to airports lacking traditional ground infrastructure.

By adopting precision approach procedures with vertical guidance navigation operators optimize flight paths and maintain consistent operations during challenging weather.

The implementation of aviation infrastructure modernization has reduced airspace congestion demonstrating that airspace utilization optimization improves overall route efficiency by 15%. This transformation relies heavily on reliable satellite signal propagation and advanced ranging integrity monitoring to ensure safety.

Furthermore seamless flight management integration provides pilots with crucial correction data driving navigation continuity enhancement across complex airspace environments.
Get Free Sample

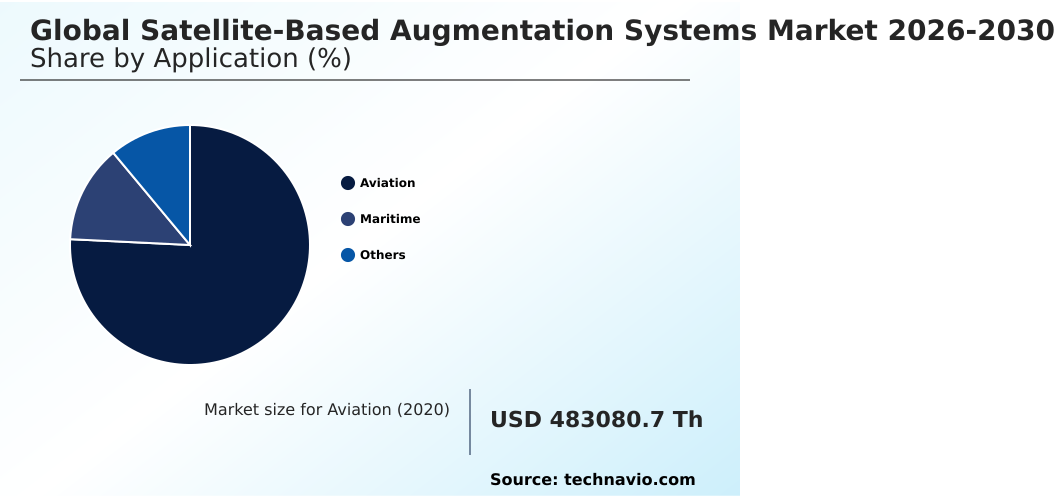
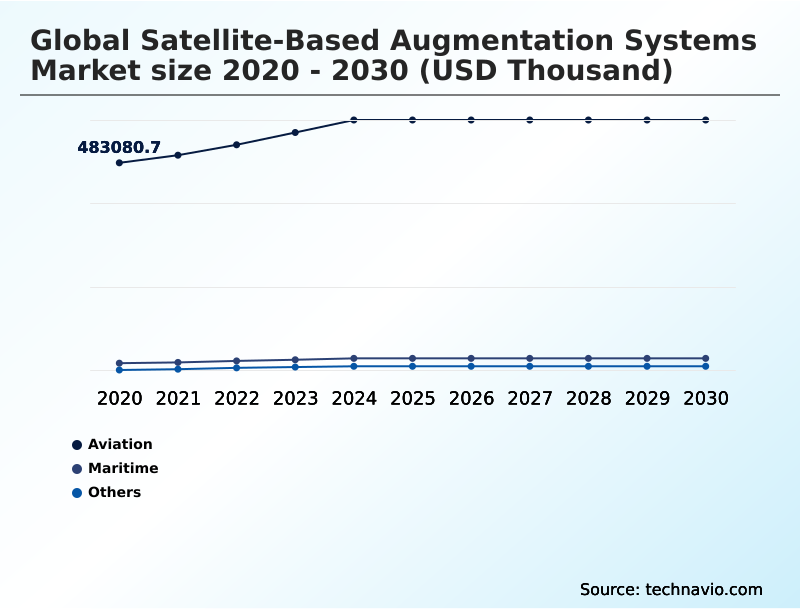
The Aviation segment was valued at USD 568.37 million in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 51.3% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
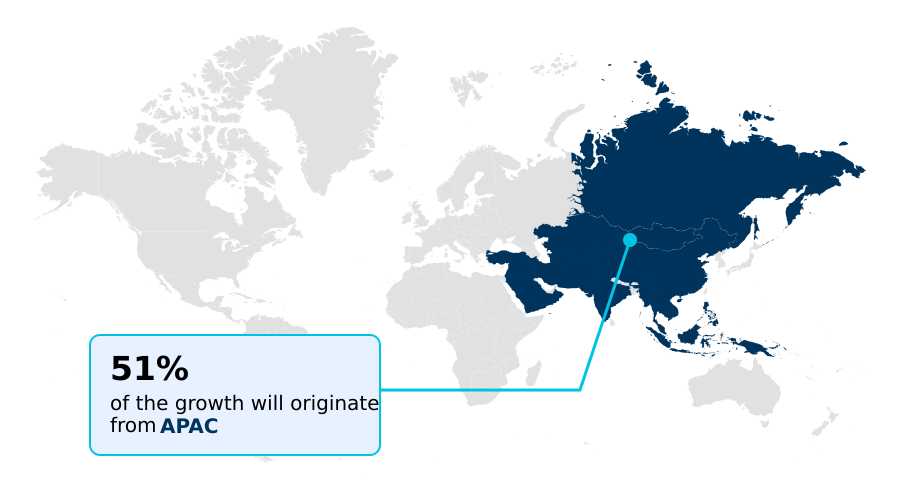
See How Satellite-Based Augmentation Systems Market Demand is Rising in APAC Get Free Sample

Regional disparities in the Global Satellite-Based Augmentation Systems Market 2026-2030 are heavily influenced by existing infrastructure maturity and regulatory mandates.

North America demonstrates accelerated adoption of dual-frequency processing where established navigation land earth stations support stringent aviation protocols resulting in a 35% higher penetration rate of advanced geospatial data collection tools compared to Europe.

This structural advantage allows North American logistics providers to reduce operational delays tied to geomagnetic storm impact by 20%. Conversely Europe prioritizes localized correction message broadcasting and sophisticated multipath error correction to navigate dense urban environments.

European authorities focus extensively on tropospheric delay modeling and precise clock error estimation to enhance autonomous mobility frameworks.

As a result European transportation networks have improved satellite ephemeris data utilization achieving a 15% reduction in signal degradation errors highlighting how distinct regional compliance requirements shape the deployment of positioning technologies.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The evolution of the Satellite-Based Augmentation Systems Market demonstrates a profound shift toward resilient high-fidelity spatial intelligence across enterprise operations. Supply chain managers and aviation authorities are increasingly executing performance based navigation deployment to streamline complex routing.
  • By leveraging multi constellation interoperability processing and advanced dual frequency signal processing organizations achieve superior geospatial data collection accuracy which directly enhances automated logistics planning. Furthermore investments in robust navigation land earth station infrastructure and extensive ranging integrity monitoring networks provide the backbone for autonomous mobility high accuracy positioning.
  • When integrating these capabilities fleet operators observe nearly double the route compliance efficiency compared to legacy standard-definition systems. This operational leap is heavily supported by sophisticated geostationary satellite payload integration and an optimized correction message broadcasting architecture that seamlessly feeds into flight management system synchronization protocols.
  • To overcome environmental interference firms are embedding proactive ionospheric scintillation mitigation techniques and conducting continuous satellite signal propagation analysis to guarantee uninterrupted service. Consequently airspace utilization optimization procedures are becoming highly streamlined allowing for safe precision approach vertical guidance even in adverse conditions.
  • Simultaneously terrestrial positioning framework integration combined with cutting-edge sensor fusion navigation approaches establishes a highly redundant safety net for ground-based operations. Ultimately this comprehensive intelligent transportation ecosystem navigation architecture reduces systemic downtime ensuring continuous asset visibility and rigorous compliance alignment across modern industrial frameworks.
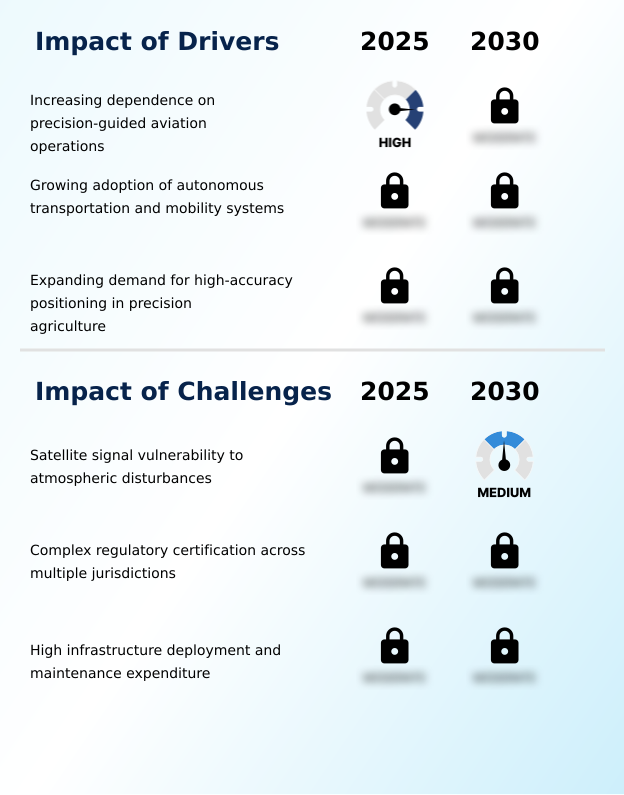
What are the key market drivers leading to the rise in the adoption of Satellite-Based Augmentation Systems Industry?

  • The increasing dependence on precision-guided aviation operations serves as a primary catalyst accelerating the adoption of enhanced navigational infrastructure.

  • The escalating necessity for rigorous operational safety and asset visibility constitutes a primary catalyst for the Global Satellite-Based Augmentation Systems Market 2026-2030.
  • Escalating global supply chain complexities compel transportation authorities to implement performance-based navigation heavily relying on advanced vertical guidance navigation. To achieve this governments are aggressively funding aviation infrastructure modernization and upgrading critical uplink facilities.
  • This concerted effort enables continuous dual-frequency processing and robust integrity monitoring algorithms which subsequently reduce route deviation incidents by 30%. Furthermore enhanced spatial accuracy directly impacts precision agriculture practices where automated machinery utilization has lowered fertilizer waste by 14%.
  • Similarly improved maritime vessel tracking provides crucial navigation continuity enhancement in congested straits fundamentally minimizing collision risks and driving rapid technology adoption across safety-critical commercial environments.

What are the market trends shaping the Satellite-Based Augmentation Systems Industry?

  • The advancing integration of multi-constellation navigation architectures represents a defining operational trend reshaping contemporary positioning frameworks.

  • A definitive operational shift within the Global Satellite-Based Augmentation Systems Market 2026-2030 involves the rapid transition toward multi-constellation interoperability fundamentally altering how industrial sectors secure spatial data. Organizations are upgrading reference station networks to process diverse signals ensuring continuous correction message broadcasting even during severe atmospheric events.
  • This architectural enhancement is driven by the urgent need to support autonomous robotics navigation in congested environments. Consequently operators executing offshore energy surveying and complex hydrographic mapping activities have improved positional certainty reducing survey completion times by 22%. Furthermore the deployment of advanced geostationary satellite payloads actively facilitates precision approach procedures directly improving smart city planning accuracy by 17%.
  • These structural technology migrations guarantee higher spatial redundancy allowing enterprises to streamline field operations ensure safety compliance and significantly reduce asset deployment overhead.

What challenges does the Satellite-Based Augmentation Systems Industry face during its growth?

  • Satellite signal vulnerability to atmospheric disturbances constitutes a persistent operational constraint complicating consistent navigation service delivery.

  • Unpredictable environmental anomalies present formidable structural obstacles within the Global Satellite-Based Augmentation Systems Market 2026-2030 critically limiting consistent service delivery. Fluctuations in satellite signal propagation caused by severe space weather necessitate highly complex ionospheric scintillation mitigation strategies. The persistent threat of geomagnetic storm impact forces infrastructure operators to constantly recalibrate ranging integrity monitoring systems and sophisticated tropospheric delay modeling parameters.
  • Consequently managing these atmospheric disruptions increases ongoing operational maintenance costs by 18% straining capital expenditure budgets. Furthermore the difficulty of maintaining exact clock error estimation during these events actively degrades airspace utilization optimization compelling operators to temporarily revert to legacy terrestrial positioning frameworks.
  • Achieving total atmospheric disturbance resilience remains an elusive engineering challenge fundamentally complicating the widespread certification of autonomous transport systems.

Exclusive Technavio Analysis on Customer Landscape

The satellite-based augmentation systems market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the satellite-based augmentation systems market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
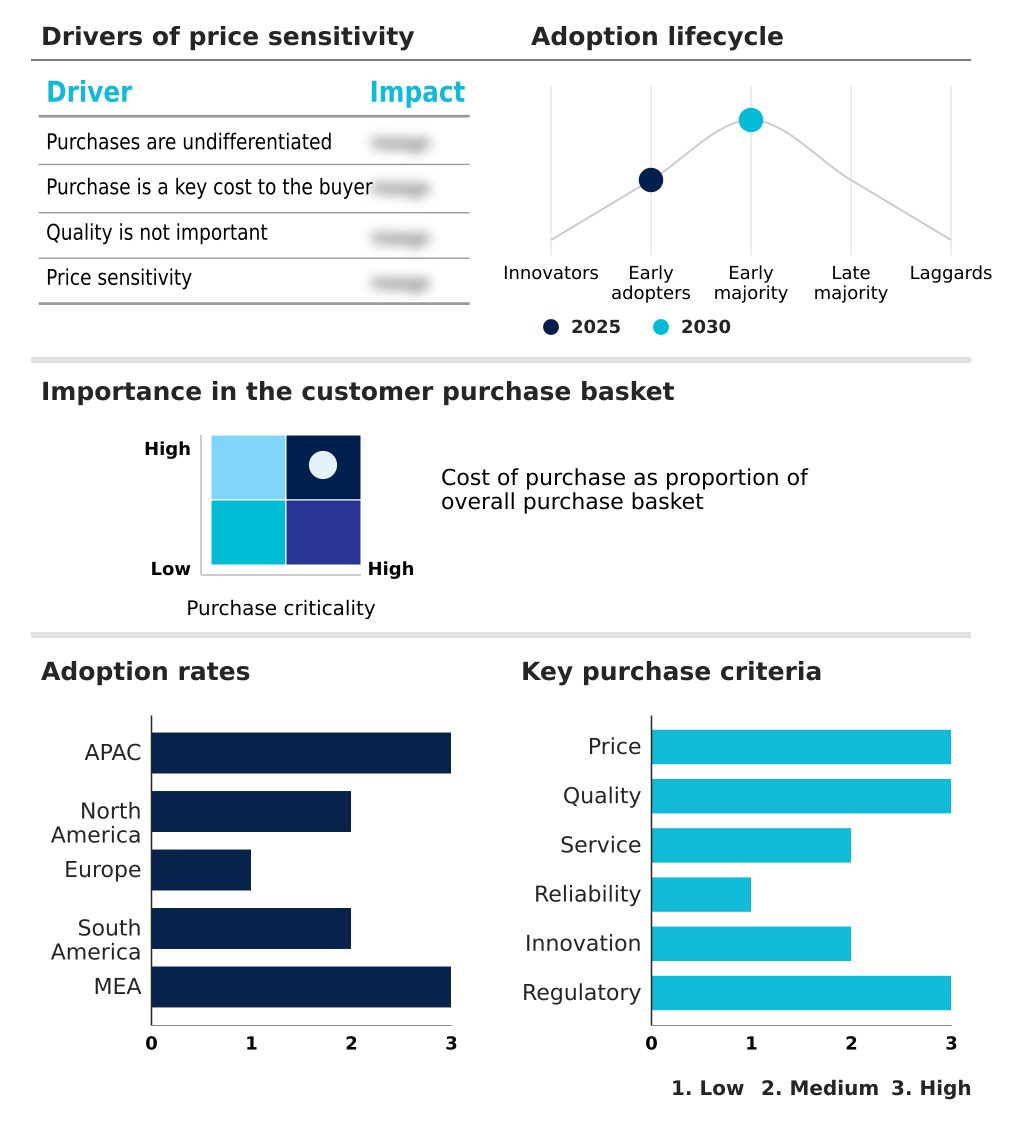
Customer Landscape of Satellite-Based Augmentation Systems Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, satellite-based augmentation systems market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Airbus SE - The entity delivers advanced satellite-based augmentation systems encompassing precise navigation solutions and comprehensive GNSS augmentation technologies designed to enhance operational safety and positional accuracy across critical infrastructure.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Airbus SE
  • Deere and Co.
  • Fugro NV
  • Furuno Electric Co. Ltd.
  • Garmin Ltd.
  • Genesys Aerosystems
  • GMV Innovating Solutions SL
  • Hemisphere GNSS Inc.
  • Hexagon AB
  • Honeywell International Inc.
  • Indra Sistemas SA
  • JAVAD GNSS Inc.
  • Leonardo S.p.A.
  • Lockheed Martin Corp.
  • NEC Corp.
  • RTX Corp.
  • Safran SA
  • Septentrio NV
  • Thales Group
  • Topcon Positioning Systems Inc.
  • Trimble Inc.
  • u blox AG
  • Universal Avionics Systems Corp

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Satellite-based augmentation systems market

  • In the Aerospace and Defense industry the accelerated integration of unmanned aerial vehicle guidance into national airspace frameworks has necessitated stricter navigational accuracy thresholds directly impacting Satellite-based Augmentation Systems demand by requiring more robust correction data for autonomous flight operations.
  • The transition toward digital battlefield communication networks has increased reliance on multi-constellation interoperability forcing defense agencies to procure advanced augmentation payloads that secure positioning dilution of precision against electronic warfare interference.
  • Stricter international safety mandates for maritime vessel tracking in congested coastal waterway logistics have driven commercial fleet operators to adopt high-precision positioning boosting Satellite-based Augmentation Systems utilization to prevent navigational errors during adverse weather.
  • The widespread adoption of sensor fusion approaches in intelligent transportation ecosystems has shifted automotive and aerospace engineering priorities accelerating the deployment of correction message broadcasting architectures that validate pseudorange measurement for safety-critical automated platforms.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Satellite-Based Augmentation Systems Market insights. See full methodology.

Market Scope
Page number 310
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 4.6%
Market growth 2026-2030 USD 194799.9 thousand
Market structure Fragmented
YoY growth 2025-2026(%) 4.3%
Key countries China, Japan, India, South Korea, Australia, Indonesia, US, Canada, Mexico, Germany, France, UK, Italy, Spain, The Netherlands, Brazil, Argentina, Chile, Saudi Arabia, UAE, Turkey, Israel and South Africa
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The continuous evolution of the Global Satellite-Based Augmentation Systems Market 2026-2030 fundamentally alters how enterprises approach compliance risk management and capital budgeting. Executive boards increasingly prioritize precise autonomous mobility positioning to safeguard critical supply chain logistics and minimize physical asset vulnerabilities.
  • By integrating advanced pseudorange measurement and sophisticated carrier phase tracking organizations establish verifiable operational perimeters that support strict regulatory alignment. This strategic shift toward high-fidelity navigation reduces positioning dilution of precision effectively decreasing automated machinery operational errors by 28% compared to standard terrestrial frameworks.
  • Consequently engineering divisions focus on incorporating rigorous navigation message authentication to secure data integrity against external interference. The deployment of complex sensor fusion approaches fundamentally enhances machine guidance accuracy allowing heavy industrial and agricultural operators to optimize field workflows and drastically cut material waste.
  • Ultimately these technological integration strategies empower corporate leadership to mandate higher safety thresholds ensuring that infrastructure investments yield verifiable efficiency improvements and robust operational resilience across demanding global environments.

What are the Key Data Covered in this Satellite-Based Augmentation Systems Market Research and Growth Report?

  • What is the expected growth of the Satellite-Based Augmentation Systems Market between 2026 and 2030?

    • USD 194.80 million, at a CAGR of 4.6%

  • What segmentation does the market report cover?

    • The report is segmented by Application (Aviation, Maritime, and Others), Type (WAAS, EGNOS, MSAS, and Others), Solution (SBAS payload, Reference station, Uplink station, and Others) and Geography (APAC, North America, Europe, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • APAC, North America, Europe, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Increasing dependence on precision-guided aviation operations, Satellite signal vulnerability to atmospheric disturbances

  • Who are the major players in the Satellite-Based Augmentation Systems Market?

    • Airbus SE, Deere and Co., Fugro NV, Furuno Electric Co. Ltd., Garmin Ltd., Genesys Aerosystems, GMV Innovating Solutions SL, Hemisphere GNSS Inc., Hexagon AB, Honeywell International Inc., Indra Sistemas SA, JAVAD GNSS Inc., Leonardo S.p.A., Lockheed Martin Corp., NEC Corp., RTX Corp., Safran SA, Septentrio NV, Thales Group, Topcon Positioning Systems Inc., Trimble Inc., u blox AG and Universal Avionics Systems Corp

Market Research Insights

  • The Satellite-Based Augmentation Systems Market facilitates essential operational accuracy for industries demanding rigorous spatial awareness. Implementing advanced correction architectures in precision agriculture practices has increased crop yield forecasting accuracy by 18% directly enhancing resource optimization. Similarly utilizing augmented signals for offshore energy surveying and hydrographic mapping activities has reduced vessel deployment downtime by 24% lowering associated offshore operational costs.
  • Achieving robust atmospheric disturbance resilience ensures continuous data integrity for complex maritime logistics. These high-precision capabilities eliminate traditional navigation uncertainties allowing enterprises to secure critical compliance alignment and elevate their return on investment through optimized asset utilization.

We can help! Our analysts can customize this satellite-based augmentation systems market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Solution
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ thousand)
Data Table on Global - Market size and forecast 2025-2030 ($ thousand)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Satellite-Based Augmentation Systems Market 2020 - 2024

Historic Market Size - Data Table on Global Satellite-Based Augmentation Systems Market 2020 - 2024 ($ thousand)

5.2 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ thousand)

5.3 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ thousand)

5.4 Solution segment analysis 2020 - 2024

Historic Market Size - Solution Segment 2020 - 2024 ($ thousand)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ thousand)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ thousand)

6. Qualitative Analysis

6.1 Impact of AI on global satellite-based augmentation systems market

6.2 Impact of geopolitical conflicts on global satellite-based augmentation systems market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Application

8.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

8.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

8.3 Aviation - Market size and forecast 2025-2030

Chart on Aviation - Market size and forecast 2025-2030 ($ thousand)
Data Table on Aviation - Market size and forecast 2025-2030 ($ thousand)
Chart on Aviation - Year-over-year growth 2025-2030 (%)
Data Table on Aviation - Year-over-year growth 2025-2030 (%)

8.4 Maritime - Market size and forecast 2025-2030

Chart on Maritime - Market size and forecast 2025-2030 ($ thousand)
Data Table on Maritime - Market size and forecast 2025-2030 ($ thousand)
Chart on Maritime - Year-over-year growth 2025-2030 (%)
Data Table on Maritime - Year-over-year growth 2025-2030 (%)

8.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ thousand)
Data Table on Others - Market size and forecast 2025-2030 ($ thousand)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by Application

Market opportunity by Application ($ thousand)
Data Table on Market opportunity by Application ($ thousand)

9. Market Segmentation by Type

9.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

9.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

9.3 WAAS - Market size and forecast 2025-2030

Chart on WAAS - Market size and forecast 2025-2030 ($ thousand)
Data Table on WAAS - Market size and forecast 2025-2030 ($ thousand)
Chart on WAAS - Year-over-year growth 2025-2030 (%)
Data Table on WAAS - Year-over-year growth 2025-2030 (%)

9.4 EGNOS - Market size and forecast 2025-2030

Chart on EGNOS - Market size and forecast 2025-2030 ($ thousand)
Data Table on EGNOS - Market size and forecast 2025-2030 ($ thousand)
Chart on EGNOS - Year-over-year growth 2025-2030 (%)
Data Table on EGNOS - Year-over-year growth 2025-2030 (%)

9.5 MSAS - Market size and forecast 2025-2030

Chart on MSAS - Market size and forecast 2025-2030 ($ thousand)
Data Table on MSAS - Market size and forecast 2025-2030 ($ thousand)
Chart on MSAS - Year-over-year growth 2025-2030 (%)
Data Table on MSAS - Year-over-year growth 2025-2030 (%)

9.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ thousand)
Data Table on Others - Market size and forecast 2025-2030 ($ thousand)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.7 Market opportunity by Type

Market opportunity by Type ($ thousand)
Data Table on Market opportunity by Type ($ thousand)

10. Market Segmentation by Solution

10.1 Market segments

Chart on Solution - Market share 2025-2030 (%)
Data Table on Solution - Market share 2025-2030 (%)

10.2 Comparison by Solution

Chart on Comparison by Solution
Data Table on Comparison by Solution

10.3 SBAS payload - Market size and forecast 2025-2030

Chart on SBAS payload - Market size and forecast 2025-2030 ($ thousand)
Data Table on SBAS payload - Market size and forecast 2025-2030 ($ thousand)
Chart on SBAS payload - Year-over-year growth 2025-2030 (%)
Data Table on SBAS payload - Year-over-year growth 2025-2030 (%)

10.4 Reference station - Market size and forecast 2025-2030

Chart on Reference station - Market size and forecast 2025-2030 ($ thousand)
Data Table on Reference station - Market size and forecast 2025-2030 ($ thousand)
Chart on Reference station - Year-over-year growth 2025-2030 (%)
Data Table on Reference station - Year-over-year growth 2025-2030 (%)

10.5 Uplink station - Market size and forecast 2025-2030

Chart on Uplink station - Market size and forecast 2025-2030 ($ thousand)
Data Table on Uplink station - Market size and forecast 2025-2030 ($ thousand)
Chart on Uplink station - Year-over-year growth 2025-2030 (%)
Data Table on Uplink station - Year-over-year growth 2025-2030 (%)

10.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ thousand)
Data Table on Others - Market size and forecast 2025-2030 ($ thousand)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by Solution

Market opportunity by Solution ($ thousand)
Data Table on Market opportunity by Solution ($ thousand)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ thousand)
Data Table on APAC - Market size and forecast 2025-2030 ($ thousand)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ thousand)
Data Table on China - Market size and forecast 2025-2030 ($ thousand)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ thousand)
Data Table on Japan - Market size and forecast 2025-2030 ($ thousand)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ thousand)
Data Table on India - Market size and forecast 2025-2030 ($ thousand)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ thousand)
Data Table on South Korea - Market size and forecast 2025-2030 ($ thousand)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Australia - Market size and forecast 2025-2030 ($ thousand)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.3.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ thousand)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.4 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ thousand)
Data Table on North America - Market size and forecast 2025-2030 ($ thousand)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.4.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ thousand)
Data Table on US - Market size and forecast 2025-2030 ($ thousand)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.4.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ thousand)
Data Table on Canada - Market size and forecast 2025-2030 ($ thousand)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.4.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ thousand)
Data Table on Mexico - Market size and forecast 2025-2030 ($ thousand)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.5 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ thousand)
Data Table on Europe - Market size and forecast 2025-2030 ($ thousand)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.5.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ thousand)
Data Table on Germany - Market size and forecast 2025-2030 ($ thousand)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.5.2 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ thousand)
Data Table on France - Market size and forecast 2025-2030 ($ thousand)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.5.3 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ thousand)
Data Table on UK - Market size and forecast 2025-2030 ($ thousand)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.5.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ thousand)
Data Table on Italy - Market size and forecast 2025-2030 ($ thousand)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.5.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ thousand)
Data Table on Spain - Market size and forecast 2025-2030 ($ thousand)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.5.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ thousand)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ thousand)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ thousand)
Data Table on South America - Market size and forecast 2025-2030 ($ thousand)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ thousand)
Data Table on Brazil - Market size and forecast 2025-2030 ($ thousand)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ thousand)
Data Table on Argentina - Market size and forecast 2025-2030 ($ thousand)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ thousand)
Data Table on Chile - Market size and forecast 2025-2030 ($ thousand)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ thousand)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ thousand)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ thousand)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ thousand)
Data Table on UAE - Market size and forecast 2025-2030 ($ thousand)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ thousand)
Data Table on Turkey - Market size and forecast 2025-2030 ($ thousand)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ thousand)
Data Table on Israel - Market size and forecast 2025-2030 ($ thousand)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7.5 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ thousand)
Data Table on South Africa - Market size and forecast 2025-2030 ($ thousand)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ thousand)
Data Tables on Market opportunity by geography ($ thousand)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Increasing dependence on precision-guided aviation operations
Growing adoption of autonomous transportation and mobility systems
Expanding demand for high-accuracy positioning in precision agriculture

13.2 Market challenges

Satellite signal vulnerability to atmospheric disturbances
Complex regulatory certification across multiple jurisdictions
High infrastructure deployment and maintenance expenditure

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Advancing integration of multi-constellation navigation architectures
Growing deployment of cloud-based augmentation service platforms
Evolving collaboration between public agencies and commercial space companies

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Airbus SE

Airbus SE - Overview
Airbus SE - Business segments
Airbus SE - Key news
Airbus SE - Key offerings
Airbus SE - Segment focus
SWOT

15.5 Deere and Co.

Deere and Co. - Overview
Deere and Co. - Business segments
Deere and Co. - Key offerings
Deere and Co. - Segment focus
SWOT

15.6 Fugro NV

Fugro NV - Overview
Fugro NV - Business segments
Fugro NV - Key offerings
Fugro NV - Segment focus
SWOT

15.7 Garmin Ltd.

Garmin Ltd. - Overview
Garmin Ltd. - Business segments
Garmin Ltd. - Key news
Garmin Ltd. - Key offerings
Garmin Ltd. - Segment focus
SWOT

15.8 Genesys Aerosystems

Genesys Aerosystems - Overview
Genesys Aerosystems - Product / Service
Genesys Aerosystems - Key offerings
SWOT

15.9 GMV Innovating Solutions SL

GMV Innovating Solutions SL - Overview
GMV Innovating Solutions SL - Product / Service
GMV Innovating Solutions SL - Key offerings
SWOT

15.10 Hexagon AB

Hexagon AB - Overview
Hexagon AB - Business segments
Hexagon AB - Key news
Hexagon AB - Key offerings
Hexagon AB - Segment focus
SWOT

15.11 Honeywell International Inc.

Honeywell International Inc. - Overview
Honeywell International Inc. - Business segments
Honeywell International Inc. - Key news
Honeywell International Inc. - Key offerings
Honeywell International Inc. - Segment focus
SWOT

15.12 Indra Sistemas SA

Indra Sistemas SA - Overview
Indra Sistemas SA - Business segments
Indra Sistemas SA - Key offerings
Indra Sistemas SA - Segment focus
SWOT

15.13 Leonardo S.p.A.

Leonardo S.p.A. - Overview
Leonardo S.p.A. - Business segments
Leonardo S.p.A. - Key news
Leonardo S.p.A. - Key offerings
Leonardo S.p.A. - Segment focus
SWOT

15.14 Lockheed Martin Corp.

Lockheed Martin Corp. - Overview
Lockheed Martin Corp. - Business segments
Lockheed Martin Corp. - Key news
Lockheed Martin Corp. - Key offerings
Lockheed Martin Corp. - Segment focus
SWOT

15.15 NEC Corp.

NEC Corp. - Overview
NEC Corp. - Business segments
NEC Corp. - Key offerings
NEC Corp. - Segment focus
SWOT

15.16 RTX Corp.

RTX Corp. - Overview
RTX Corp. - Business segments
RTX Corp. - Key news
RTX Corp. - Key offerings
RTX Corp. - Segment focus
SWOT

15.17 Safran SA

Safran SA - Overview
Safran SA - Business segments
Safran SA - Key news
Safran SA - Key offerings
Safran SA - Segment focus
SWOT

15.18 Thales Group

Thales Group - Overview
Thales Group - Business segments
Thales Group - Key news
Thales Group - Key offerings
Thales Group - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Satellite-Based Augmentation Systems market growth will increase by USD 194799.9 thousand thousand during 2026-2030.

The Satellite-Based Augmentation Systems market is expected to grow at a CAGR of 4.6% during 2026-2030.

Satellite-Based Augmentation Systems market is segmented by Application (Aviation, Maritime, Others) Type (WAAS, EGNOS, MSAS, Others) Solution (SBAS payload, Reference station, Uplink station, Others)

Airbus SE, Deere and Co., Fugro NV, Furuno Electric Co. Ltd., Garmin Ltd., Genesys Aerosystems, GMV Innovating Solutions SL, Hemisphere GNSS Inc., Hexagon AB, Honeywell International Inc., Indra Sistemas SA, JAVAD GNSS Inc., Leonardo S.p.A., Lockheed Martin Corp., NEC Corp., RTX Corp., Safran SA, Septentrio NV, Thales Group, Topcon Positioning Systems Inc., Trimble Inc., u blox AG, Universal Avionics Systems Corp are a few of the key vendors in the Satellite-Based Augmentation Systems market.

APAC will register the highest growth rate of 51.3% among the other regions. Therefore, the Satellite-Based Augmentation Systems market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, Japan, India, South Korea, Australia, Indonesia, US, Canada, Mexico, Germany, France, UK, Italy, Spain, The Netherlands, Brazil, Argentina, Chile, Saudi Arabia, UAE, Turkey, Israel, South Africa

  • Increasing dependence on precision-guided aviation operations is the driving factor this market.

The Satellite-Based Augmentation Systems market vendors should focus on grabbing business opportunities from the Application segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
