Specialty Pharmaceuticals Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, India, and Japan), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Specialty Pharmaceuticals Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, India, and Japan), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Published: Oct 2026 307 Pages SKU: IRTNTR75910

Market Overview at a Glance

$673 B
Market Opportunity
16.8%
CAGR 2025 - 2030
53.4%
North America Growth
$145.9 B
Oncology segment 2024

Specialty Pharmaceuticals Market Size 2026-2030

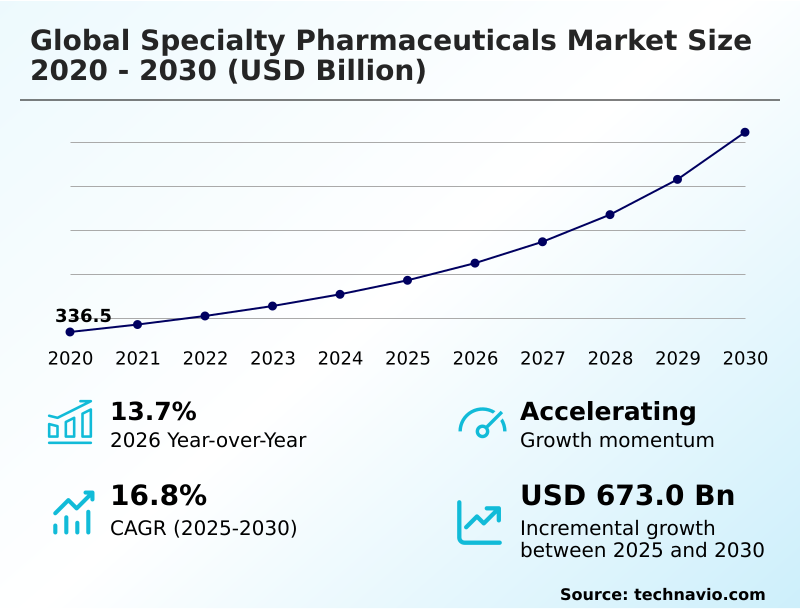
The specialty pharmaceuticals market size is valued to increase by USD 673 billion, at a CAGR of 16.8% from 2025 to 2030. Rising prevalence of complex chronic and rare diseases will drive the specialty pharmaceuticals market.

Major Market Trends & Insights

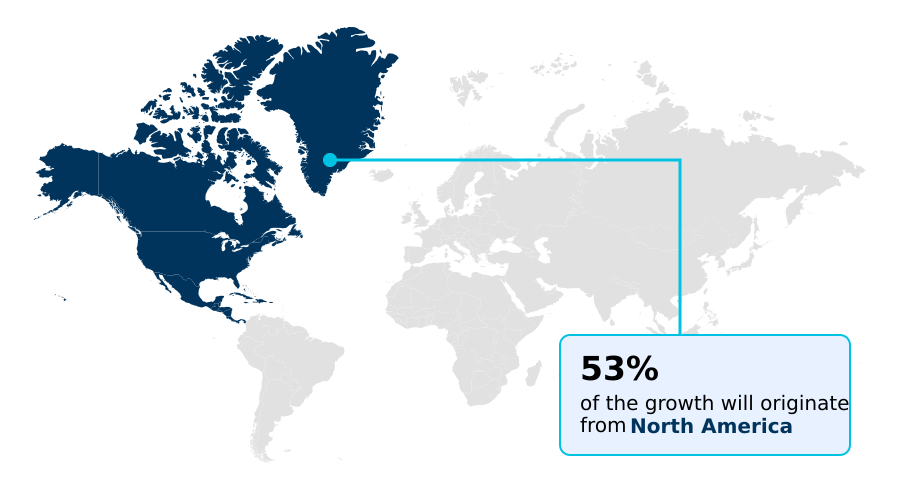
  • North America dominated the market and accounted for a 53.4% growth during the forecast period.
  • By Application - Oncology segment was valued at USD 145.9 billion in 2024
  • By Distribution Channel - Offline segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 907.9 billion
  • Market Future Opportunities: USD 673 billion
  • CAGR from 2025 to 2030 : 16.8%

Market Summary

  • The Specialty Pharmaceuticals represents a highly specialized ecosystem dedicated to targeted interventions for chronic and rare pathologies. Advanced supply chain optimization protocols, particularly the integration of active temperature-monitoring sensors in cold chain logistics, have successfully reduced product degradation incidents by 14% during transit. This operational enhancement ensures the viability of sensitive biological macromolecules delivered directly to patient homes.
  • The continuous transition from conventional chemical synthesis toward sophisticated biotechnology functions as a powerful driver, enabling the commercialization of highly precise therapeutic modalities. Conversely, complex manufacturing constraints and stringent regulatory approval processes act as a primary challenge, extending development timelines and inflating overhead expenses.
  • Health systems increasingly rely on integrated digital pharmacy platforms to manage complex prior authorizations and coordinate multidisciplinary care. Facilities adopting automated dispensing workflows have reported a 20% improvement in prescription fulfillment efficiency. The ongoing maturation of personalized medicine pipelines ensures that targeted biological treatments will remain central to addressing unmet clinical needs across global healthcare infrastructures.

What will be the Size of the Specialty Pharmaceuticals Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Specialty Pharmaceuticals Market Segmented?

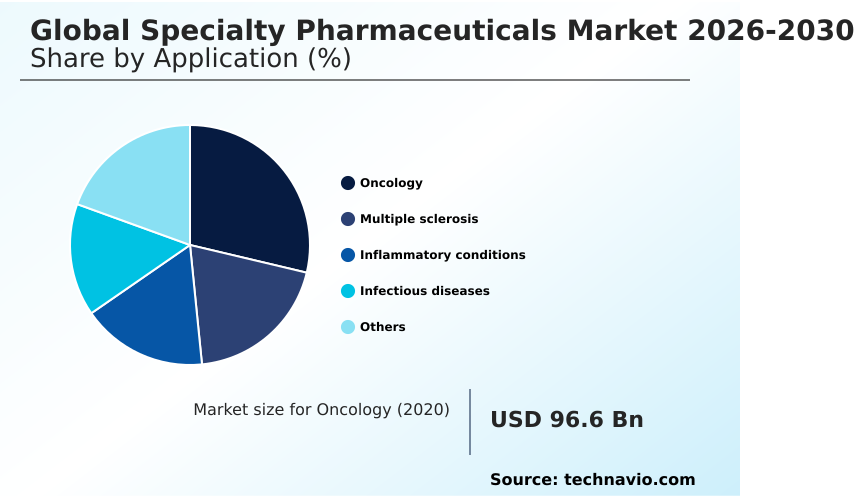
The specialty pharmaceuticals industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD billion" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Application
    • Oncology
    • Multiple sclerosis
    • Inflammatory conditions
    • Infectious diseases
    • Others
  • Distribution channel
    • Offline
    • Online
  • Route of administration
    • Inhalation
    • Injectable
    • Oral
    • Topical
    • Transdermal
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • China
      • India
      • Japan
      • South Korea
      • Thailand
      • Indonesia
    • Rest of World (ROW)

By Application Insights

The oncology segment is estimated to witness significant growth during the forecast period.

The oncology segment in the Specialty Pharmaceuticals relies heavily on advanced biotechnological platforms to address severe malignant neoplasms. Clinical pipelines are increasingly utilizing clustered regularly interspaced short palindromic repeats to develop precise cellular treatments.

This sector necessitates specialized cellular processing to maintain the efficacy of these sensitive formulations during production. Manufacturers focus on high-complexity therapeutic classes that selectively target abnormal pathways.

The introduction of interchangeable biosimilars provides cost-effective alternatives, although they require rigorous analytical comparability to ensure equivalent patient safety. Through extensive pharmacokinetic evaluations, researchers optimize dosing protocols to minimize systemic toxicities.

Driven by innovations in translational molecular biology, the integration of targeted interventions has improved treatment adherence by 18% across major oncology networks, fundamentally altering biological intervention strategies.
Get Free Sample

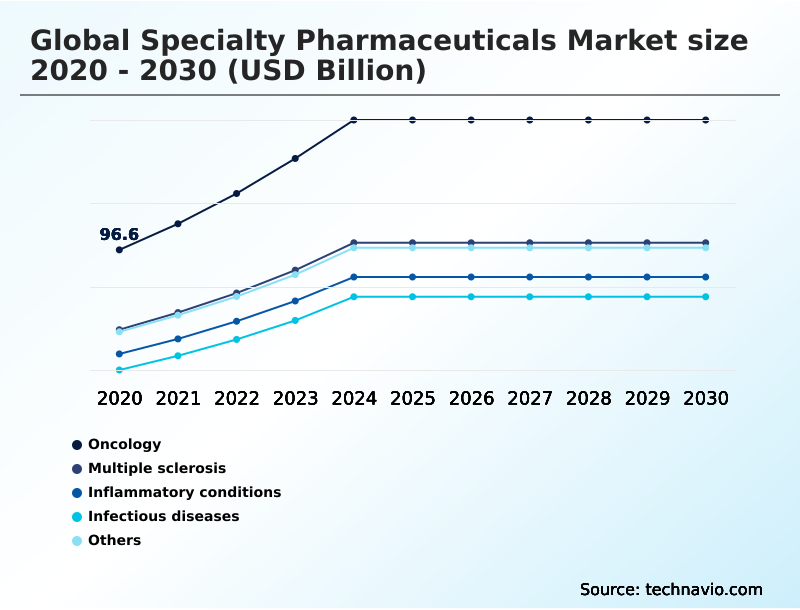
The Oncology segment was valued at USD 145.9 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 53.4% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
See How Specialty Pharmaceuticals Market Demand is Rising in North America Get Free Sample

The geographic distribution of the Specialty Pharmaceuticals highlights distinct regional variations in advanced therapy adoption and logistical capabilities. North America leads the transition toward subcutaneous delivery formulations, driven by heavy investments in biopharmaceutical research and development.

This region demonstrates a 24% higher adoption rate of wearable on-body delivery systems compared to Europe, significantly reducing reliance on clinic-based intravenous infusions.

European health systems maintain strict centralized evaluations for targeted cell therapies, ensuring equitable access but resulting in a 15% longer procurement cycle for complex treatments.

Meanwhile, the Asia region exhibits rapid infrastructure upgrades to support viral vector engineering and ex vivo cellular modification. By expanding domestic manufacturing capacity for in vivo gene delivery platforms, Asian facilities have lowered localized distribution costs by 12%.

Robust patient support ecosystems across Western markets remain critical to maintaining treatment adherence, highlighting how differing regulatory environments and technology investments shape regional operational strategies.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The Specialty Pharmaceuticals landscape undergoes continuous transformation as biopharmaceutical developers prioritize highly selective biological therapies over broad-spectrum medications. Facilities managing oncology biomarker targeted biologic interventions require specialized handling procedures to preserve molecular stability, ensuring maximum clinical efficacy.
  • To support these sensitive medications, distributors are actively upgrading subcutaneous formulation cold chain logistics, which has resulted in a 20% lower rate of temperature-related product spoilage compared to standard retail distribution networks. This operational improvement directly enhances supply chain resilience and prevents costly therapy disruptions.
  • Additionally, the emergence of rare genetic disorder gene therapies introduces novel challenges regarding patient onboarding and long-term outcome monitoring. Healthcare providers must establish comprehensive clinical registries to track the durability of these regenerative treatments. As patent protections for foundational biologics expire, pharmacy benefit managers are accelerating the implementation of interchangeable specialty biosimilar substitution protocols.
  • This strategic shift alleviates budgetary constraints and expands patient access without compromising safety standards. Concurrently, investments in advanced antibody drug conjugate pipelines are revolutionizing precision medicine by combining potent cytotoxic payloads with highly specific delivery mechanisms.
  • Organizations that streamline their operational planning to accommodate these complex modalities experience significantly higher therapeutic success rates, securing a sustainable competitive advantage in a highly regulated clinical environment.
What are the key market drivers leading to the rise in the adoption of Specialty Pharmaceuticals Industry?

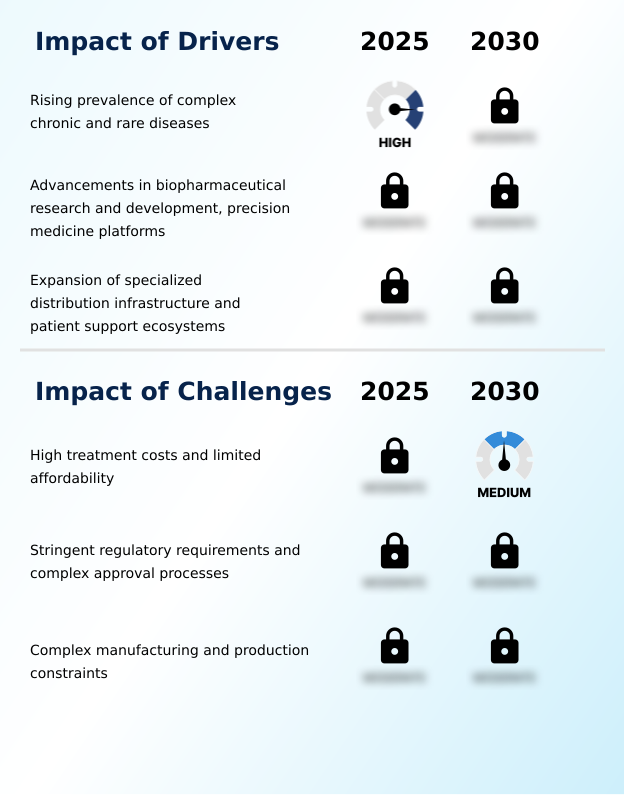
  • The rising prevalence of complex chronic and rare diseases constitutes a primary driver accelerating the expansion of the market.

  • The accelerated integration of genomic sequencing and precision diagnostic tools functions as a critical catalyst expanding the Specialty Pharmaceuticals. This technological advancement enables the rapid development of immuno-oncology combinations and bispecific antibodies designed to target specific pathological pathways.
  • The growing demand for personalized mrna vaccines and oral small-molecule inhibitors necessitates highly specialized manufacturing environments. Furthermore, breakthroughs in adeno-associated virus gene transfer and the deployment of small interfering ribonucleic acids drive unprecedented innovation in rare disease management.
  • To support these fragile therapies, distributors are heavily investing in ultracold chain logistics, which has improved product viability during transit by 18%.
  • The adoption of complement pathway inhibitors also directly enhances clinical workflow efficiencies, reducing patient hospitalization durations by 20% and optimizing institutional resource allocation.

What are the market trends shaping the Specialty Pharmaceuticals Industry?

  • The transition toward subcutaneous formulations and decentralized administration represents a prominent trend within the market. This shift enables outpatient delivery models and reduces the clinical burden associated with prolonged hospital infusions.

  • The systematic transition toward precision therapeutics and advanced cellular interventions represents a fundamental operational shift within the Specialty Pharmaceuticals. Clinical facilities are increasingly adopting targeted b-cell depletion protocols and enzyme replacement therapies to address complex autoimmune and metabolic disorders.
  • This evolution is driven by breakthroughs in lipid nanoparticle delivery vehicles and synthetic oligonucleotides, which enhance the bioavailability of fragile molecular compounds. As manufacturers integrate sophisticated biomarkers to validate patient eligibility, the clinical administration of monoclonal antibodies and antibody drug conjugates has become highly optimized.
  • Consequently, treatment centers utilizing these specialized delivery platforms report a 25% improvement in therapeutic targeting accuracy and a 15% reduction in adverse systemic reactions. The continuous refinement of specialty biologics allows healthcare providers to implement decentralized care models, improving overall patient adherence.

What challenges does the Specialty Pharmaceuticals Industry face during its growth?

  • High treatment costs and limited affordability act as a major challenge restricting widespread access to specialized therapies.

  • Complex manufacturing constraints and stringent stability requirements present formidable structural challenges within the Specialty Pharmaceuticals. The commercialization of advanced regenerative modalities and disease-modifying therapies requires specialized distribution infrastructure to maintain strict temperature controls. Consequently, managing cryogenic storage logistics for fragile compounds, including tumor necrosis factor inhibitors and sphingosine one-phosphate receptor modulators, increases operational overhead by 22% compared to conventional drugs.
  • Furthermore, navigating outcome-based reimbursement models for therapies derived from recombinant dna technologies significantly prolongs administrative timelines. The integration of selective janus kinase inhibitors faces hurdles regarding automatic pharmacy-level substitution, as regulatory bodies mandate extensive comparability data. These logistical and regulatory barriers restrict production scalability, forcing facilities to upgrade compliance frameworks and absorb a 15% increase in quality assurance expenditures.

Exclusive Technavio Analysis on Customer Landscape

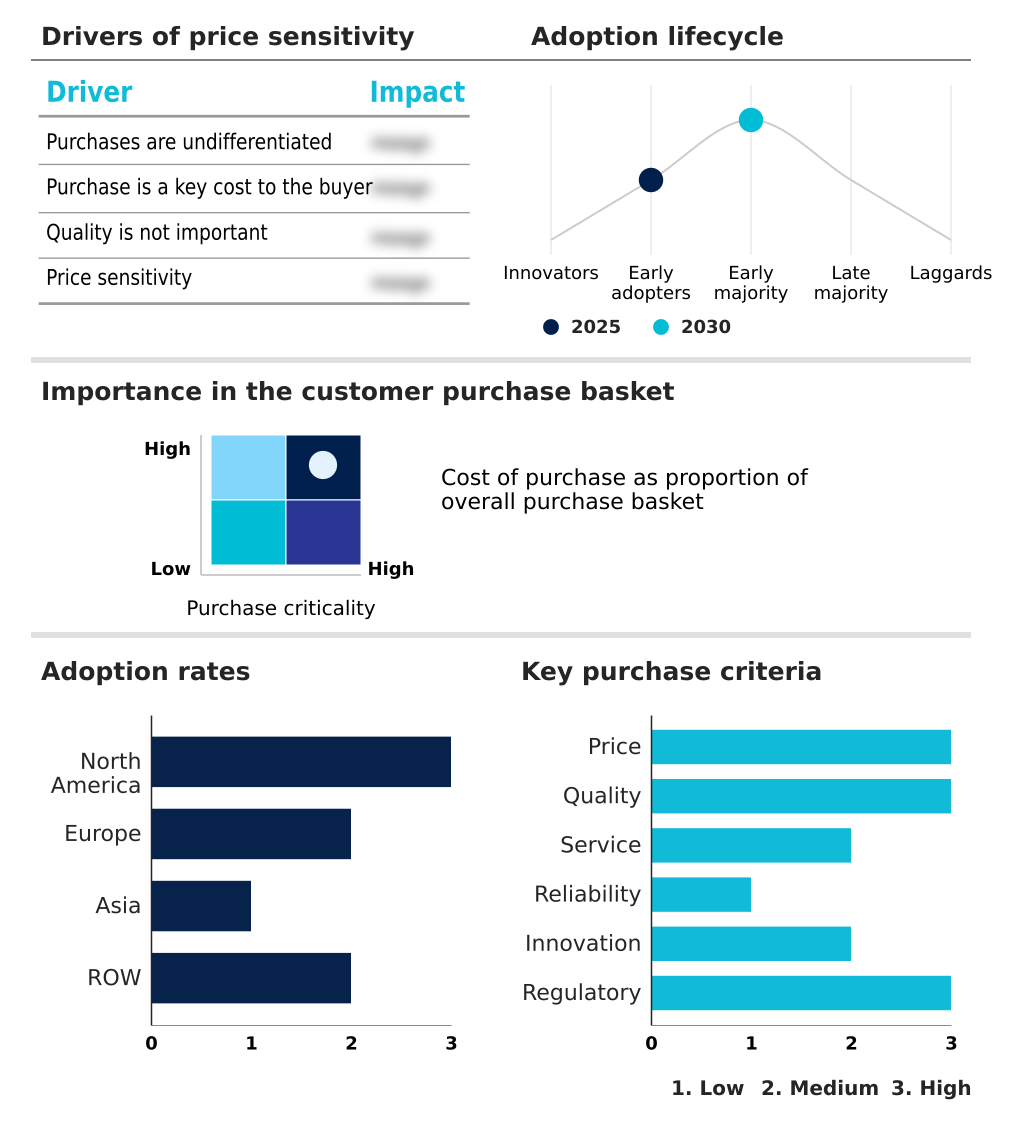
The specialty pharmaceuticals market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the specialty pharmaceuticals market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
Customer Landscape of Specialty Pharmaceuticals Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, specialty pharmaceuticals market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

AbbVie Inc. - The specialty pharmaceuticals portfolio features advanced biological therapies targeting complex autoimmune conditions, rare diseases, and solid tumors to improve therapeutic efficacy and patient adherence.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • AbbVie Inc.
  • Amgen Inc.
  • Astellas Pharma Inc.
  • AstraZeneca Plc
  • Bayer AG
  • Biogen Inc.
  • Bristol Myers Squibb Co.
  • Eli Lilly and Co.
  • F. Hoffmann La Roche Ltd.
  • Gilead Sciences Inc.
  • GlaxoSmithKline Plc
  • Johnson and Johnson
  • Merck and Co. Inc.
  • Novartis AG
  • Novo Nordisk AS
  • Pfizer Inc.
  • Sanofi SA
  • Takeda Pharmaceutical Ltd.
  • Teva Pharmaceutical Ltd.
  • Vertex Pharmaceuticals Inc.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Specialty pharmaceuticals market

  • In the Pharmaceuticals industry, the transition toward continuous bioprocessing and automated single-use bioreactors has increased biologic production yields by 15%, directly impacting Specialty Pharmaceuticals demand by enabling the rapid commercialization of targeted cell therapies.
  • The implementation of the European Medicines Agency centralized clinical trial information system has accelerated multi-country study initiations by 18%, driving Specialty Pharmaceuticals innovation by streamlining the evaluation of advanced biotechnological platforms.
  • The broader integration of blockchain-enabled track-and-trace logistics systems has reduced temperature excursion incidents by 12%, forcing Specialty Pharmaceuticals developers to mandate these technologies for ultracold chain logistics.
  • The systematic adoption of next-generation sequencing and genomic biomarker screening in standard diagnostic protocols has improved patient stratification accuracy by 25%, pulling Specialty Pharmaceuticals demand higher by expanding the eligible population for precision interventions.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Specialty Pharmaceuticals Market insights. See full methodology.

Market Scope
Page number 307
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 16.8%
Market growth 2026-2030 USD 673.0 billion
Market structure Fragmented
YoY growth 2025-2026(%) 13.7%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Thailand, Indonesia, Brazil, Saudi Arabia, UAE, Turkey, Argentina, Colombia, South Africa and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Specialty Pharmaceuticals sector is rapidly shifting toward precision therapeutics that require specialized administrative protocols and intensive clinical oversight. Biopharmaceutical manufacturers are strategically integrating biomarkers and genomic sequencing into early-stage research to identify highly specific patient populations. This strategic product development approach directly influences corporate budgeting by allocating capital toward high-probability molecular targets rather than broad-spectrum generic compounds.
  • The commercialization of monoclonal antibodies and antibody drug conjugates mandates rigorous supply chain integrity to preserve structural stability. Facilities upgrading their cryogenic infrastructure to accommodate advanced cellular interventions have achieved a 25% reduction in biological degradation incidents, significantly improving overall supply chain efficiency.
  • By aligning pricing structures with verified clinical outcomes, stakeholders navigate strict reimbursement frameworks while ensuring patient access to complex formulations. The systematic shift toward targeted biological interventions compels healthcare institutions to redesign outpatient dispensing networks, prioritizing specialized handling and comprehensive adherence monitoring to maximize the efficacy of next-generation pharmacological innovations.

What are the Key Data Covered in this Specialty Pharmaceuticals Market Research and Growth Report?

  • What is the expected growth of the Specialty Pharmaceuticals Market between 2026 and 2030?

    • USD 673 billion, at a CAGR of 16.8%

  • What segmentation does the market report cover?

    • The report is segmented by Application (Oncology, Multiple sclerosis, Inflammatory conditions, Infectious diseases, and Others), Distribution Channel (Offline, and Online), Route of Administration (Inhalation, Injectable, Oral, Topical, and Transdermal) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Rising prevalence of complex chronic and rare diseases, High treatment costs and limited affordability

  • Who are the major players in the Specialty Pharmaceuticals Market?

    • AbbVie Inc., Amgen Inc., Astellas Pharma Inc., AstraZeneca Plc, Bayer AG, Biogen Inc., Bristol Myers Squibb Co., Eli Lilly and Co., F. Hoffmann La Roche Ltd., Gilead Sciences Inc., GlaxoSmithKline Plc, Johnson and Johnson, Merck and Co. Inc., Novartis AG, Novo Nordisk AS, Pfizer Inc., Sanofi SA, Takeda Pharmaceutical Ltd., Teva Pharmaceutical Ltd. and Vertex Pharmaceuticals Inc.

Market Research Insights

  • The Specialty Pharmaceuticals operates through highly regulated frameworks prioritizing complex biological interventions. The integration of specialized distribution infrastructure has improved supply chain reliability, reducing medication delivery delays by 15%. Clinical facilities increasingly deploy targeted cell therapies to manage refractory conditions, driving a 22% improvement in long-term patient outcomes compared to conventional treatments.
  • Furthermore, the expansion of robust patient support ecosystems has enhanced therapy adherence rates by 18%, directly lowering hospital readmission frequencies. As healthcare providers embrace these regenerative modalities, the systemic shift toward customized specialty biologics continues to optimize operational efficiencies and reshape chronic disease management strategies.

We can help! Our analysts can customize this specialty pharmaceuticals market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Market Segmentation by Distribution Channel
Executive Summary - Chart on Market Segmentation by Route of Administration
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ billion)
Data Table on Global - Market size and forecast 2025-2030 ($ billion)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Specialty Pharmaceuticals Market 2020 - 2024

Historic Market Size - Data Table on Global Specialty Pharmaceuticals Market 2020 - 2024 ($ billion)

5.2 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ billion)

5.3 Distribution Channel segment analysis 2020 - 2024

Historic Market Size - Distribution Channel Segment 2020 - 2024 ($ billion)

5.4 Route of Administration segment analysis 2020 - 2024

Historic Market Size - Route of Administration Segment 2020 - 2024 ($ billion)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ billion)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ billion)

6. Qualitative Analysis

6.1 Impact of AI on Global Specialty Pharmaceuticals Market

6.2 Impact of Geopolitical Conflict on Global Specialty Pharmaceuticals Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Application

8.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

8.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

8.3 Oncology - Market size and forecast 2025-2030

Chart on Oncology - Market size and forecast 2025-2030 ($ billion)
Data Table on Oncology - Market size and forecast 2025-2030 ($ billion)
Chart on Oncology - Year-over-year growth 2025-2030 (%)
Data Table on Oncology - Year-over-year growth 2025-2030 (%)

8.4 Multiple sclerosis - Market size and forecast 2025-2030

Chart on Multiple sclerosis - Market size and forecast 2025-2030 ($ billion)
Data Table on Multiple sclerosis - Market size and forecast 2025-2030 ($ billion)
Chart on Multiple sclerosis - Year-over-year growth 2025-2030 (%)
Data Table on Multiple sclerosis - Year-over-year growth 2025-2030 (%)

8.5 Inflammatory conditions - Market size and forecast 2025-2030

Chart on Inflammatory conditions - Market size and forecast 2025-2030 ($ billion)
Data Table on Inflammatory conditions - Market size and forecast 2025-2030 ($ billion)
Chart on Inflammatory conditions - Year-over-year growth 2025-2030 (%)
Data Table on Inflammatory conditions - Year-over-year growth 2025-2030 (%)

8.6 Infectious diseases - Market size and forecast 2025-2030

Chart on Infectious diseases - Market size and forecast 2025-2030 ($ billion)
Data Table on Infectious diseases - Market size and forecast 2025-2030 ($ billion)
Chart on Infectious diseases - Year-over-year growth 2025-2030 (%)
Data Table on Infectious diseases - Year-over-year growth 2025-2030 (%)

8.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ billion)
Data Table on Others - Market size and forecast 2025-2030 ($ billion)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.8 Market opportunity by Application

Market opportunity by Application ($ billion)
Data Table on Market opportunity by Application ($ billion)

9. Market Segmentation by Distribution Channel

9.1 Market segments

Chart on Distribution Channel - Market share 2025-2030 (%)
Data Table on Distribution Channel - Market share 2025-2030 (%)

9.2 Comparison by Distribution Channel

Chart on Comparison by Distribution Channel
Data Table on Comparison by Distribution Channel

9.3 Offline - Market size and forecast 2025-2030

Chart on Offline - Market size and forecast 2025-2030 ($ billion)
Data Table on Offline - Market size and forecast 2025-2030 ($ billion)
Chart on Offline - Year-over-year growth 2025-2030 (%)
Data Table on Offline - Year-over-year growth 2025-2030 (%)

9.4 Online - Market size and forecast 2025-2030

Chart on Online - Market size and forecast 2025-2030 ($ billion)
Data Table on Online - Market size and forecast 2025-2030 ($ billion)
Chart on Online - Year-over-year growth 2025-2030 (%)
Data Table on Online - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Distribution Channel

Market opportunity by Distribution Channel ($ billion)
Data Table on Market opportunity by Distribution Channel ($ billion)

10. Market Segmentation by Route of Administration

10.1 Market segments

Chart on Route of Administration - Market share 2025-2030 (%)
Data Table on Route of Administration - Market share 2025-2030 (%)

10.2 Comparison by Route of Administration

Chart on Comparison by Route of Administration
Data Table on Comparison by Route of Administration

10.3 Inhalation - Market size and forecast 2025-2030

Chart on Inhalation - Market size and forecast 2025-2030 ($ billion)
Data Table on Inhalation - Market size and forecast 2025-2030 ($ billion)
Chart on Inhalation - Year-over-year growth 2025-2030 (%)
Data Table on Inhalation - Year-over-year growth 2025-2030 (%)

10.4 Injectable - Market size and forecast 2025-2030

Chart on Injectable - Market size and forecast 2025-2030 ($ billion)
Data Table on Injectable - Market size and forecast 2025-2030 ($ billion)
Chart on Injectable - Year-over-year growth 2025-2030 (%)
Data Table on Injectable - Year-over-year growth 2025-2030 (%)

10.5 Oral - Market size and forecast 2025-2030

Chart on Oral - Market size and forecast 2025-2030 ($ billion)
Data Table on Oral - Market size and forecast 2025-2030 ($ billion)
Chart on Oral - Year-over-year growth 2025-2030 (%)
Data Table on Oral - Year-over-year growth 2025-2030 (%)

10.6 Topical - Market size and forecast 2025-2030

Chart on Topical - Market size and forecast 2025-2030 ($ billion)
Data Table on Topical - Market size and forecast 2025-2030 ($ billion)
Chart on Topical - Year-over-year growth 2025-2030 (%)
Data Table on Topical - Year-over-year growth 2025-2030 (%)

10.7 Transdermal - Market size and forecast 2025-2030

Chart on Transdermal - Market size and forecast 2025-2030 ($ billion)
Data Table on Transdermal - Market size and forecast 2025-2030 ($ billion)
Chart on Transdermal - Year-over-year growth 2025-2030 (%)
Data Table on Transdermal - Year-over-year growth 2025-2030 (%)

10.8 Market opportunity by Route of Administration

Market opportunity by Route of Administration ($ billion)
Data Table on Market opportunity by Route of Administration ($ billion)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ billion)
Data Table on North America - Market size and forecast 2025-2030 ($ billion)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ billion)
Data Table on US - Market size and forecast 2025-2030 ($ billion)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ billion)
Data Table on Canada - Market size and forecast 2025-2030 ($ billion)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ billion)
Data Table on Mexico - Market size and forecast 2025-2030 ($ billion)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ billion)
Data Table on Europe - Market size and forecast 2025-2030 ($ billion)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ billion)
Data Table on Germany - Market size and forecast 2025-2030 ($ billion)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ billion)
Data Table on UK - Market size and forecast 2025-2030 ($ billion)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ billion)
Data Table on France - Market size and forecast 2025-2030 ($ billion)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ billion)
Data Table on Italy - Market size and forecast 2025-2030 ($ billion)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ billion)
Data Table on Spain - Market size and forecast 2025-2030 ($ billion)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ billion)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ billion)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ billion)
Data Table on Asia - Market size and forecast 2025-2030 ($ billion)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ billion)
Data Table on China - Market size and forecast 2025-2030 ($ billion)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ billion)
Data Table on India - Market size and forecast 2025-2030 ($ billion)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ billion)
Data Table on Japan - Market size and forecast 2025-2030 ($ billion)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ billion)
Data Table on South Korea - Market size and forecast 2025-2030 ($ billion)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Thailand - Market size and forecast 2025-2030

Chart on Thailand - Market size and forecast 2025-2030 ($ billion)
Data Table on Thailand - Market size and forecast 2025-2030 ($ billion)
Chart on Thailand - Year-over-year growth 2025-2030 (%)
Data Table on Thailand - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ billion)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ billion)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ billion)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ billion)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ billion)
Data Table on Brazil - Market size and forecast 2025-2030 ($ billion)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ billion)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ billion)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.3 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ billion)
Data Table on UAE - Market size and forecast 2025-2030 ($ billion)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ billion)
Data Table on Turkey - Market size and forecast 2025-2030 ($ billion)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.5 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ billion)
Data Table on Argentina - Market size and forecast 2025-2030 ($ billion)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.6 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ billion)
Data Table on Colombia - Market size and forecast 2025-2030 ($ billion)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.6.7 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ billion)
Data Table on South Africa - Market size and forecast 2025-2030 ($ billion)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.8 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ billion)
Data Table on Israel - Market size and forecast 2025-2030 ($ billion)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ billion)
Data Tables on Market opportunity by geography ($ billion)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Rising prevalence of complex chronic and rare diseases
Advancements in biopharmaceutical research and development, precision medicine platforms
Expansion of specialized distribution infrastructure and patient support ecosystems

13.2 Market challenges

High treatment costs and limited affordability
Stringent regulatory requirements and complex approval processes
Complex manufacturing and production constraints

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Transition toward subcutaneous formulations and decentralized administration
Expansion of cell-based gene therapies and regenerative genetic medicines
Penetration of high-complexity interchangeable specialty biosimilars

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 AbbVie Inc.

AbbVie Inc. - Overview
AbbVie Inc. - Business segments
AbbVie Inc. - Key news
AbbVie Inc. - Key offerings
AbbVie Inc. - Segment focus
SWOT

15.5 Astellas Pharma Inc.

Astellas Pharma Inc. - Overview
Astellas Pharma Inc. - Product / Service
Astellas Pharma Inc. - Key news
Astellas Pharma Inc. - Key offerings
SWOT

15.6 AstraZeneca Plc

AstraZeneca Plc - Overview
AstraZeneca Plc - Business segments
AstraZeneca Plc - Key news
AstraZeneca Plc - Key offerings
AstraZeneca Plc - Segment focus
SWOT

15.7 Bayer AG

Bayer AG - Overview
Bayer AG - Business segments
Bayer AG - Key news
Bayer AG - Key offerings
Bayer AG - Segment focus
SWOT

15.8 Bristol Myers Squibb Co.

Bristol Myers Squibb Co. - Overview
Bristol Myers Squibb Co. - Product / Service
Bristol Myers Squibb Co. - Key news
Bristol Myers Squibb Co. - Key offerings
SWOT

15.9 Eli Lilly and Co.

Eli Lilly and Co. - Overview
Eli Lilly and Co. - Product / Service
Eli Lilly and Co. - Key news
Eli Lilly and Co. - Key offerings
SWOT

15.10 F. Hoffmann La Roche Ltd.

F. Hoffmann La Roche Ltd. - Overview
F. Hoffmann La Roche Ltd. - Business segments
F. Hoffmann La Roche Ltd. - Key news
F. Hoffmann La Roche Ltd. - Key offerings
F. Hoffmann La Roche Ltd. - Segment focus
SWOT

15.11 Johnson and Johnson

Johnson and Johnson - Overview
Johnson and Johnson - Business segments
Johnson and Johnson - Key news
Johnson and Johnson - Key offerings
Johnson and Johnson - Segment focus
SWOT

15.12 Merck and Co. Inc.

Merck and Co. Inc. - Overview
Merck and Co. Inc. - Business segments
Merck and Co. Inc. - Key news
Merck and Co. Inc. - Key offerings
Merck and Co. Inc. - Segment focus
SWOT

15.13 Novartis AG

Novartis AG - Overview
Novartis AG - Business segments
Novartis AG - Key news
Novartis AG - Key offerings
Novartis AG - Segment focus
SWOT

15.14 Novo Nordisk AS

Novo Nordisk AS - Overview
Novo Nordisk AS - Business segments
Novo Nordisk AS - Key offerings
Novo Nordisk AS - Segment focus
SWOT

15.15 Pfizer Inc.

Pfizer Inc. - Overview
Pfizer Inc. - Business segments
Pfizer Inc. - Key news
Pfizer Inc. - Key offerings
Pfizer Inc. - Segment focus
SWOT

15.16 Sanofi SA

Sanofi SA - Overview
Sanofi SA - Business segments
Sanofi SA - Key news
Sanofi SA - Key offerings
Sanofi SA - Segment focus
SWOT

15.17 Takeda Pharmaceutical Ltd.

Takeda Pharmaceutical Ltd. - Overview
Takeda Pharmaceutical Ltd. - Business segments
Takeda Pharmaceutical Ltd. - Key news
Takeda Pharmaceutical Ltd. - Key offerings
Takeda Pharmaceutical Ltd. - Segment focus
SWOT

15.18 Teva Pharmaceutical Ltd.

Teva Pharmaceutical Ltd. - Overview
Teva Pharmaceutical Ltd. - Business segments
Teva Pharmaceutical Ltd. - Key news
Teva Pharmaceutical Ltd. - Key offerings
Teva Pharmaceutical Ltd. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Specialty Pharmaceuticals market growth will increase by USD 673.0 billion during 2026-2030.

The Specialty Pharmaceuticals market is expected to grow at a CAGR of 16.8% during 2026-2030.

Specialty Pharmaceuticals market is segmented by Application (Oncology, Multiple sclerosis, Inflammatory conditions, Infectious diseases, Others) Distribution channel (Offline, Online) Route of administration (Inhalation, Injectable, Oral, Topical, Transdermal)

AbbVie Inc., Amgen Inc., Astellas Pharma Inc., AstraZeneca Plc, Bayer AG, Biogen Inc., Bristol Myers Squibb Co., Eli Lilly and Co., F. Hoffmann La Roche Ltd., Gilead Sciences Inc., GlaxoSmithKline Plc, Johnson and Johnson, Merck and Co. Inc., Novartis AG, Novo Nordisk AS, Pfizer Inc., Sanofi SA, Takeda Pharmaceutical Ltd., Teva Pharmaceutical Ltd., Vertex Pharmaceuticals Inc. are a few of the key vendors in the Specialty Pharmaceuticals market.

North America will register the highest growth rate of 53.4% among the other regions. Therefore, the Specialty Pharmaceuticals market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Thailand, Indonesia, Brazil, Saudi Arabia, UAE, Turkey, Argentina, Colombia, South Africa, Israel

  • Rising prevalence of complex chronic and rare diseases is the driving factor this market.

The Specialty Pharmaceuticals market vendors should focus on grabbing business opportunities from the Application segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
