Aircraft Engine MRO Market Analysis, Size, and Forecast 2026-2030: APAC (China, Japan, and India), Europe (UK, Germany, and France), North America (US, Canada, and Mexico), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Colombia), and Rest of World (ROW)

Aircraft Engine MRO Market Analysis, Size, and Forecast 2026-2030:
APAC (China, Japan, and India), Europe (UK, Germany, and France), North America (US, Canada, and Mexico), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Colombia), and Rest of World (ROW)

Published: Oct 2026 293 Pages SKU: IRTNTR46479

Market Overview at a Glance

$11.55 B
Market Opportunity
5.4%
CAGR 2025 - 2030
36.6%
North America Growth
$27.76 B
Commercial aviation segment 2024

Aircraft Engine Mro Market Size 2026-2030

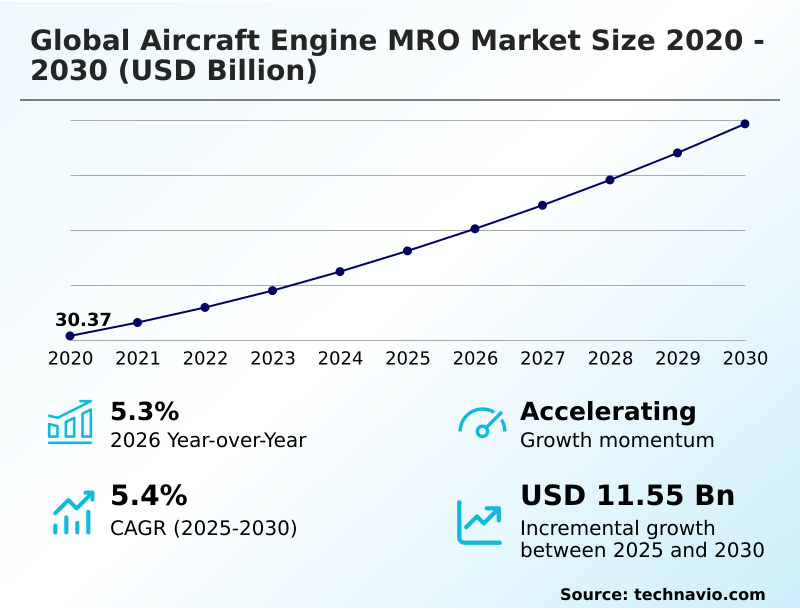
The aircraft engine mro market size is valued to increase by USD 11.55 billion, at a CAGR of 5.4% from 2025 to 2030. Surging expansion of global fleet and escalating air passenger travel demand will drive the aircraft engine mro market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 36.6% growth during the forecast period.
  • By Application - Commercial aviation segment was valued at USD 27.76 billion in 2024
  • By Type - Turbofan and turbojet segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 19.28 billion
  • Market Future Opportunities: USD 11.55 billion
  • CAGR from 2025 to 2030 : 5.4%

Market Summary

  • The Aircraft Engine MRO Market is undergoing a rapid technological evolution driven by unprecedented fleet utilization and the transition to predictive lifecycle management. Commercial airlines actively leverage real-time telemetry analysis and digital twin software to optimize supply chain inventory, ensuring replacement parts are staged before a scheduled teardown occurs.
  • This data-driven supply chain optimization has reduced aircraft-on-ground delays by 28%, significantly improving daily revenue generation for fleet operators. The primary driver accelerating sector expansion is the massive global backlog of new aircraft deliveries, which forces commercial carriers to maximize the operational lifespan of legacy propulsion systems through intensive structural restorations.
  • Conversely, the market faces a severe challenge regarding deepening deficits of licensed technical labor, which restricts hangar throughput and artificially elongates standard overhaul schedules. Expanding maintenance networks must continuously invest in automated robotic inspection tools to offset this workforce attrition while preserving absolute regulatory compliance. Advanced component repair technologies ensure critical assets remain safely operational across high-demand transit routes.

What will be the Size of the Aircraft Engine Mro Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Aircraft Engine Mro Market Segmented?

The aircraft engine mro industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Application
    • Commercial aviation
    • Military aviation
    • General aviation
  • Type
    • Turbofan and turbojet
    • Turboprop
  • Service
    • Engine overhaul
    • Engine repair
    • Engine modification and upgrades
  • Geography
    • APAC
      • China
      • Japan
      • India
      • Singapore
      • South Korea
      • Australia
    • Europe
      • UK
      • Germany
      • France
      • The Netherlands
      • Italy
      • Spain
    • North America
      • US
      • Canada
      • Mexico
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Qatar
      • Turkey
    • South America
      • Brazil
      • Argentina
      • Colombia

By Application Insights

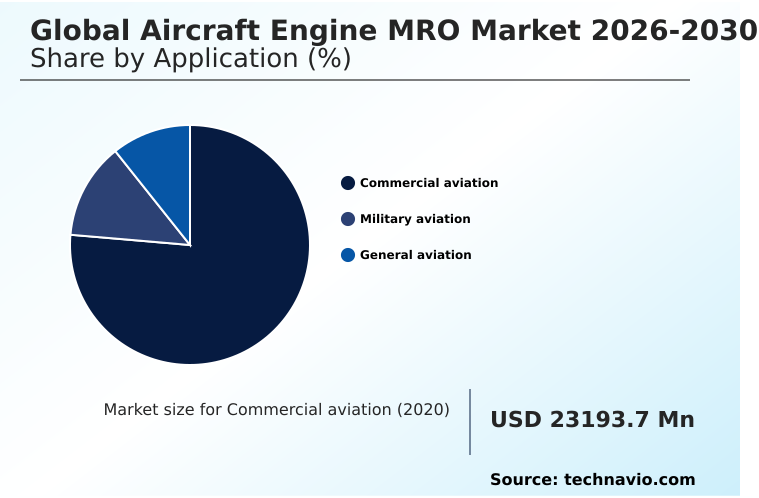
The commercial aviation segment is estimated to witness significant growth during the forecast period.

The commercial aviation segment dictates primary demand frameworks within the Aircraft Engine MRO due to intensive operational utilization and high flight cycle accumulation. Continuous passenger transport mandates rigorous adherence to scheduled maintenance intervals to prevent catastrophic mechanical failures.

Operators are extending the lifecycles of legacy propulsion assets, increasing the frequency of heavy shop visits and deep engine teardown protocols.

Simultaneously, the integration of advanced next-generation powerplants introduces complex requirements such as the maintenance of ceramic matrix composites and sophisticated commercial turbofan thermal barrier restoration.

By shifting from reactive service to predictive digital monitoring, airlines have improved engine defect detection by 22%, directly extending time-on-wing performance. This proactive structural alignment minimizes costly unscheduled groundings and optimizes overall fleet availability across high-density global flight networks.
Get Free Sample

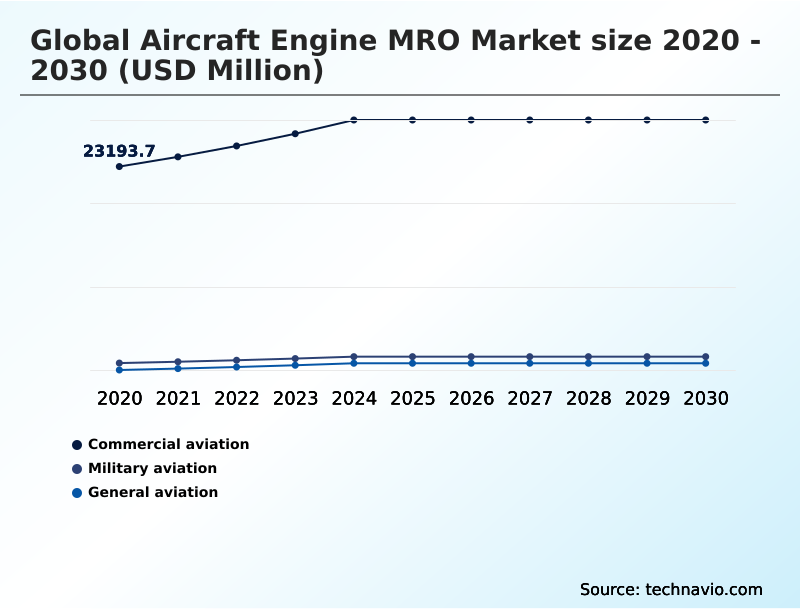
The Commercial aviation segment was valued at USD 27.76 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 36.6% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
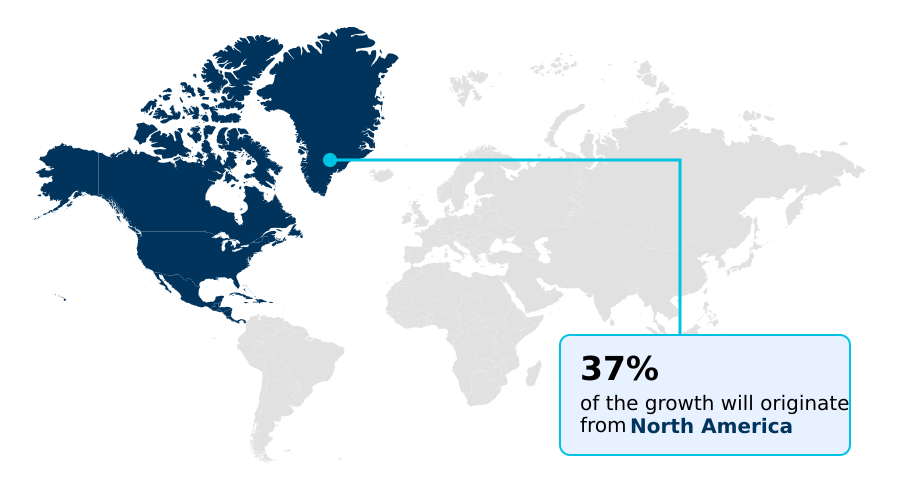
See How Aircraft Engine Mro Market Demand is Rising in North America Get Free Sample

The geographic distribution of the Aircraft Engine MRO reveals distinct operational disparities between mature and emerging aviation hubs.

North America demonstrates a 35% higher adoption rate of digital twin analytics compared to Latin America, allowing regional operators to precisely monitor thermal stress degradation and prolong propulsion asset lifecycles proactively.

This advanced predictive capability enables North American facilities to execute targeted component reliability enhancement, reducing overall hangar processing times by 18%.

In contrast, APAC is expanding physical capacity to handle massive narrow-body fleet accumulations, increasing localized overhaul throughput by 40% to bypass European supply chain bottlenecks.

Facilities across APAC are aggressively investing in sophisticated eddy current inspections and specialized automated restorations for high-pressure compressor blades.

These regional adaptations illustrate how airlines modify maintenance logistics; mature markets prioritize algorithmic efficiency and precision diagnostics, while high-growth territories focus heavily on scaling localized infrastructure to sustain absolute airworthiness compliance.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The operational intricacies of the Aircraft Engine MRO necessitate sophisticated intervention strategies to maximize fleet uptime and minimize mechanical failures. As global air carriers push equipment to absolute thermal and physical limits, executing precise next generation engine teardown procedures becomes a critical necessity for preserving compliance and structural integrity.
  • Service providers face compounding material scarcity, prompting them to refine used serviceable material procurement strategies to secure viable replacement components without enduring lengthy OEM delays. This supply chain recalibration effectively lowers part acquisition costs by up to 35% compared to sourcing exclusively brand-new forged components.
  • Furthermore, managing the intense heat loads generated by advanced propulsion requires specialized commercial turbofan thermal barrier restoration, a highly technical process that prevents premature casing erosion. Maintaining optimal internal airflow also demands rigorous high pressure compressor blade replacement during heavy shop visits to restore aerodynamic efficiency.
  • To transition away from reactive servicing frameworks, leading aviation maintenance hubs are integrating predictive aircraft engine health analytics. This digital pivot provides maintenance planners with real-time operational insights, allowing them to schedule deep interventions precisely when material fatigue reaches critical thresholds.
  • By shifting to proactive engine management, airlines improve asset reliability, streamline labor allocation, and prevent catastrophic inflight shutdowns, ensuring seamless continuity across the global aviation ecosystem.
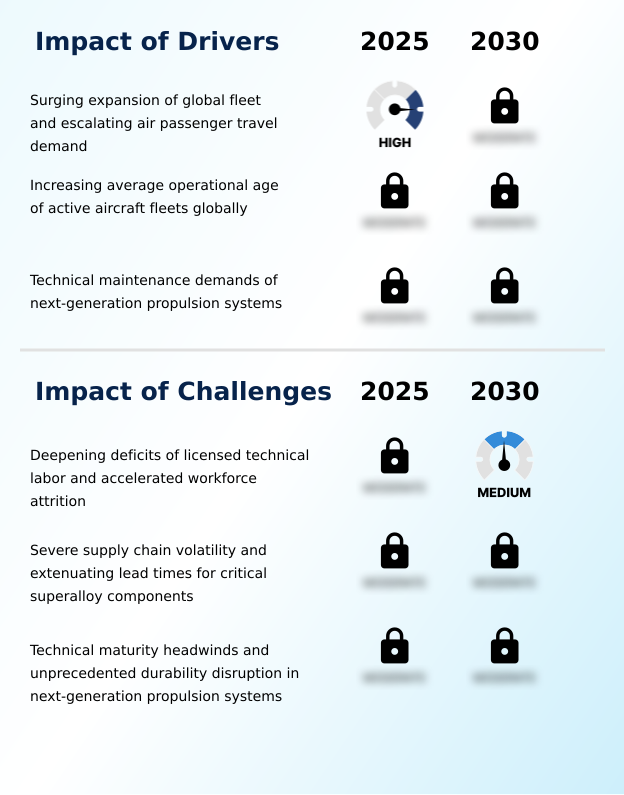
What are the key market drivers leading to the rise in the adoption of Aircraft Engine Mro Industry?

  • The surging expansion of the global fleet and escalating air passenger travel demand serve as primary drivers accelerating market expansion.

  • The rapid aging of the active global commercial fleet functions as the primary driver propelling expansion across the Aircraft Engine MRO.
  • Because production backlogs severely delay the delivery of new replacement aircraft, commercial operators are forced to extend the service lives of legacy propulsion systems through intensive mechanical interventions.
  • This operational necessity drives massive demand for specialized compressor drum repairs and complex hot-section coating restorations to counteract severe thermal fatigue.
  • By utilizing advanced additive manufacturing restorations and high-temperature plasma spray coatings, maintenance facilities have improved component durability by up to 28%, significantly extending time-on-wing performance.
  • This sustained reliance on rotable module exchanges allows airlines to minimize capital expenditure on brand-new parts, ultimately optimizing fleet maintenance budgets by 22% while ensuring absolute compliance with international aviation safety mandates.

What are the market trends shaping the Aircraft Engine Mro Industry?

  • The proliferation of digitalization and data-driven predictive maintenance systems represents a critical trend shaping the market. This technological integration significantly enhances operational reliability and forecasting precision.

  • A paramount trend reshaping the Aircraft Engine MRO involves the universal transition toward digitized diagnostic frameworks and advanced material recovery processes. The integration of complex geared turbofan architecture demands unprecedented mechanical precision, compelling facilities to adopt sophisticated digital borescope technologies to detect microscopic internal stress fractures.
  • Because new manufacturing lead times for nickel-superalloy turbine blades have extended drastically, MRO providers are utilizing advanced metallurgical reclamation processes to salvage existing components. This intense focus on localized material recovery has improved overall parts availability by 25%, allowing service centers to bypass constrained international supply chains.
  • Consequently, targeted interventions across core powerplants and auxiliary power units have reduced average hangar turnaround times by 18%. This technological evolution directly empowers airline operators to maintain high-density flight schedules without enduring the severe financial penalties associated with prolonged equipment grounding.

What challenges does the Aircraft Engine Mro Industry face during its growth?

  • Deepening deficits of licensed technical labor and accelerated workforce attrition pose significant challenges that restrict operational capacity.

  • The Aircraft Engine MRO faces acute operational challenges stemming from a severe, structural shortage of licensed technical labor and global supply chain volatility. An aging workforce and insufficient recruitment pipelines severely limit the execution of complex engine overhaul procedures, forcing facilities to operate with constrained hangar throughput.
  • Because modern powerplants require highly specialized nondestructive flaw detection and precise turbine blade replacements, the lack of certified mechanics directly increases heavy shop visit durations by an average of 35 days. Furthermore, unpredictable delays in procuring raw materials disrupt established scheduled maintenance intervals, severely hampering proactive component fatigue mitigation strategies.
  • These compounding bottlenecks force commercial airlines to increase active spare engine inventories by 15%, significantly elevating total operating costs and threatening the seamless continuity of high-density global flight schedules.

Exclusive Technavio Analysis on Customer Landscape

The aircraft engine mro market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the aircraft engine mro market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
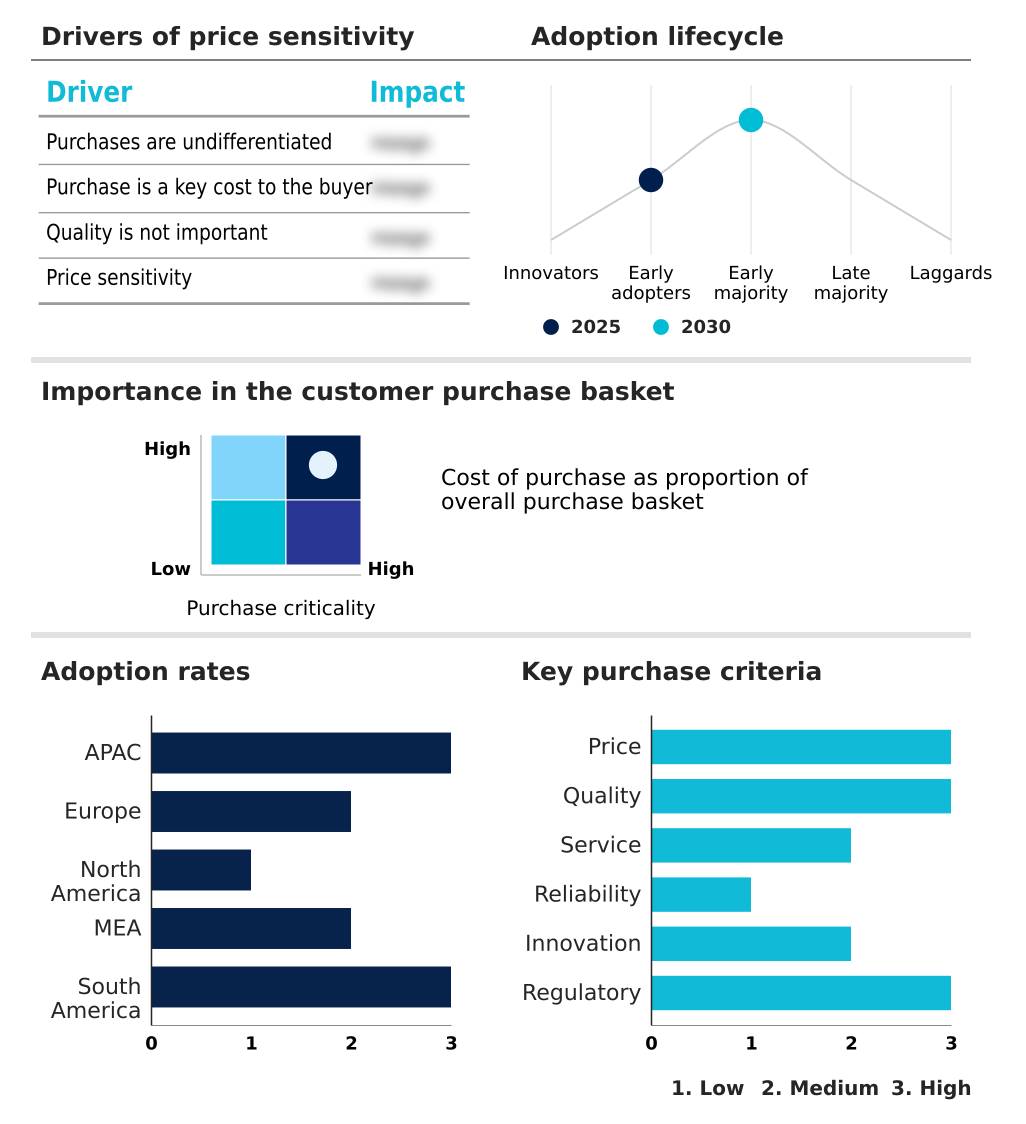
Customer Landscape of Aircraft Engine Mro Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, aircraft engine mro market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

AAR Corp. - Delivering comprehensive aircraft engine MRO, the portfolio features integrated maintenance, repair, overhaul, rigorous inspection protocols, and specialized component support services optimizing commercial and government aviation fleet readiness.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • AAR Corp.
  • Aero Norway
  • Air France KLM
  • Chromalloy Gas Turbine LLC
  • Delta TechOps
  • General Electric Co.
  • Hong Kong Aircraft Engineering
  • Iberia Maintenance
  • ITP Aero
  • Lufthansa Technik
  • MTU Aero Engines AG
  • Pratt and Whitney
  • Rolls Royce Holdings Plc
  • Safran SA
  • Sanad
  • SIA Engineering Co
  • SR Technics Switzerland Ltd.
  • ST Engineering Ltd.
  • StandardAero Inc.
  • Turkish Technic Inc.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Aircraft engine mro market

  • In the Aerospace and Defense industry, the widespread adoption of stringent carbon emission regulations mandates the integration of high-efficiency propulsion designs, directly impacting Aircraft Engine MRO demand by requiring facilities to upgrade sustainable aviation integration practices and reduce shop visit frequencies by 15% through precision tuning.
  • Global supply chain bottlenecks for critical raw materials have restricted the availability of new OEM components, compelling maintenance providers to increase the utilization of certified used serviceable material and execute life-limited parts exchanges with a 25% higher frequency to avoid extended aircraft groundings.
  • The deployment of real-time telemetry sensors across military and commercial fleets enhances component degradation forecasting capabilities, shifting maintenance from reactive protocols to predictive models that decrease unplanned engine removals by up to 30% and significantly compress overall maintenance turnaround times.
  • Strict international safety mandates addressing early material wear in next-generation powerplants enforce rigorous airworthiness directive compliance, requiring advanced non-destructive inspections and specialized engine run-up testing that elevate technical overhaul requirements and increase service intensity by 20% per shop visit.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Aircraft Engine Mro Market insights. See full methodology.

Market Scope
Page number 293
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 5.4%
Market growth 2026-2030 USD 11549.6 million
Market structure Fragmented
YoY growth 2025-2026(%) 5.3%
Key countries China, Japan, India, Singapore, South Korea, Australia, UK, Germany, France, The Netherlands, Italy, Spain, US, Canada, Mexico, Saudi Arabia, UAE, South Africa, Qatar, Turkey, Brazil, Argentina and Colombia
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Aircraft Engine MRO functions as the critical technical foundation for the global aviation industry, ensuring fleets maintain absolute safety and mechanical efficiency. A dominant shift toward predictive engine health monitoring now directly influences boardroom-level budgeting decisions, allowing airline executives to transition from reactive capital expenditures to highly optimized, condition-based maintenance schedules.
  • By leveraging advanced analytics, fleet operators have achieved a 30% reduction in unscheduled engine removals, radically improving daily asset utilization and operational profitability. This data-driven environment supports highly complex propulsion system restorations, necessitating advanced diagnostic capabilities for planetary gear inspections and deep combustion chamber overhauls.
  • Due to persistent global material shortages, maintenance facilities are heavily investing in specialized laser cladding repairs to salvage expensive single-crystal castings rather than waiting for new OEM deliveries. Furthermore, the meticulous re-profiling of aerodynamic fan blades ensures maximum thermodynamic efficiency and fuel economy.
  • These highly specialized mechanical interventions guarantee that aging commercial fleets continue adhering to stringent international airworthiness directives while controlling the escalating logistical costs associated with continuous flight operations.

What are the Key Data Covered in this Aircraft Engine Mro Market Research and Growth Report?

  • What is the expected growth of the Aircraft Engine Mro Market between 2026 and 2030?

    • USD 11.55 billion, at a CAGR of 5.4%

  • What segmentation does the market report cover?

    • The report is segmented by Application (Commercial aviation, Military aviation, and General aviation), Type (Turbofan and turbojet, and Turboprop), Service (Engine overhaul, Engine repair, and Engine modification and upgrades) and Geography (APAC, Europe, North America, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • APAC, Europe, North America, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Surging expansion of global fleet and escalating air passenger travel demand, Deepening deficits of licensed technical labor and accelerated workforce attrition

  • Who are the major players in the Aircraft Engine Mro Market?

    • AAR Corp., Aero Norway, Air France KLM, Chromalloy Gas Turbine LLC, Delta TechOps, General Electric Co., Hong Kong Aircraft Engineering, Iberia Maintenance, ITP Aero, Lufthansa Technik, MTU Aero Engines AG, Pratt and Whitney, Rolls Royce Holdings Plc, Safran SA, Sanad, SIA Engineering Co, SR Technics Switzerland Ltd., ST Engineering Ltd., StandardAero Inc. and Turkish Technic Inc.

Market Research Insights

  • The Aircraft Engine MRO Market operates as an essential technical framework securing global aviation safety and operational efficiency. By heavily integrating predictive maintenance software and rigorous flight cycle tracking, modern airline operators have successfully enhanced early defect detection rates by 34%, actively preventing catastrophic mechanical failures.
  • Furthermore, the deployment of real-time telemetry analysis allows engineering teams to optimize modular engine maintenance schedules based on actual component fatigue rather than rigid calendar limits. This targeted maintenance strategy reduces overall labor expenditures by 19% while accelerating turnaround times for critical engine performance restorations.
  • Through these proactive technological adaptations, service providers deliver absolute regulatory compliance, minimize expensive unscheduled groundings, and maximize daily fleet availability across high-density international transit networks.

We can help! Our analysts can customize this aircraft engine mro market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Service
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Aircraft Engine MRO Market 2020 - 2024

Historic Market Size - Data Table on Global Aircraft Engine MRO Market 2020 - 2024 ($ million)

5.2 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.3 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.4 Service segment analysis 2020 - 2024

Historic Market Size - Service Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global aircraft engine MRO market

6.2 Impact of geopolitical conflicts on global aircraft engine MRO market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Application

8.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

8.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

8.3 Commercial aviation - Market size and forecast 2025-2030

Chart on Commercial aviation - Market size and forecast 2025-2030 ($ million)
Data Table on Commercial aviation - Market size and forecast 2025-2030 ($ million)
Chart on Commercial aviation - Year-over-year growth 2025-2030 (%)
Data Table on Commercial aviation - Year-over-year growth 2025-2030 (%)

8.4 Military aviation - Market size and forecast 2025-2030

Chart on Military aviation - Market size and forecast 2025-2030 ($ million)
Data Table on Military aviation - Market size and forecast 2025-2030 ($ million)
Chart on Military aviation - Year-over-year growth 2025-2030 (%)
Data Table on Military aviation - Year-over-year growth 2025-2030 (%)

8.5 General aviation - Market size and forecast 2025-2030

Chart on General aviation - Market size and forecast 2025-2030 ($ million)
Data Table on General aviation - Market size and forecast 2025-2030 ($ million)
Chart on General aviation - Year-over-year growth 2025-2030 (%)
Data Table on General aviation - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

9. Market Segmentation by Type

9.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

9.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

9.3 Turbofan and turbojet - Market size and forecast 2025-2030

Chart on Turbofan and turbojet - Market size and forecast 2025-2030 ($ million)
Data Table on Turbofan and turbojet - Market size and forecast 2025-2030 ($ million)
Chart on Turbofan and turbojet - Year-over-year growth 2025-2030 (%)
Data Table on Turbofan and turbojet - Year-over-year growth 2025-2030 (%)

9.4 Turboprop - Market size and forecast 2025-2030

Chart on Turboprop - Market size and forecast 2025-2030 ($ million)
Data Table on Turboprop - Market size and forecast 2025-2030 ($ million)
Chart on Turboprop - Year-over-year growth 2025-2030 (%)
Data Table on Turboprop - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

10. Market Segmentation by Service

10.1 Market segments

Chart on Service - Market share 2025-2030 (%)
Data Table on Service - Market share 2025-2030 (%)

10.2 Comparison by Service

Chart on Comparison by Service
Data Table on Comparison by Service

10.3 Engine overhaul - Market size and forecast 2025-2030

Chart on Engine overhaul - Market size and forecast 2025-2030 ($ million)
Data Table on Engine overhaul - Market size and forecast 2025-2030 ($ million)
Chart on Engine overhaul - Year-over-year growth 2025-2030 (%)
Data Table on Engine overhaul - Year-over-year growth 2025-2030 (%)

10.4 Engine repair - Market size and forecast 2025-2030

Chart on Engine repair - Market size and forecast 2025-2030 ($ million)
Data Table on Engine repair - Market size and forecast 2025-2030 ($ million)
Chart on Engine repair - Year-over-year growth 2025-2030 (%)
Data Table on Engine repair - Year-over-year growth 2025-2030 (%)

10.5 Engine modification and upgrades - Market size and forecast 2025-2030

Chart on Engine modification and upgrades - Market size and forecast 2025-2030 ($ million)
Data Table on Engine modification and upgrades - Market size and forecast 2025-2030 ($ million)
Chart on Engine modification and upgrades - Year-over-year growth 2025-2030 (%)
Data Table on Engine modification and upgrades - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Service

Market opportunity by Service ($ million)
Data Table on Market opportunity by Service ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.4 Singapore - Market size and forecast 2025-2030

Chart on Singapore - Market size and forecast 2025-2030 ($ million)
Data Table on Singapore - Market size and forecast 2025-2030 ($ million)
Chart on Singapore - Year-over-year growth 2025-2030 (%)
Data Table on Singapore - Year-over-year growth 2025-2030 (%)

12.3.5 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.6 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.2 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.4.5 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.6 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.5 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.5.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.5.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.5.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 Qatar - Market size and forecast 2025-2030

Chart on Qatar - Market size and forecast 2025-2030 ($ million)
Data Table on Qatar - Market size and forecast 2025-2030 ($ million)
Chart on Qatar - Year-over-year growth 2025-2030 (%)
Data Table on Qatar - Year-over-year growth 2025-2030 (%)

12.6.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Surging expansion of global fleet and escalating air passenger travel demand
Increasing average operational age of active aircraft fleets globally
Technical maintenance demands of next-generation propulsion systems

13.2 Market challenges

Deepening deficits of licensed technical labor and accelerated workforce attrition
Severe supply chain volatility and extenuating lead times for critical superalloy components
Technical maturity headwinds and unprecedented durability disruption in next-generation propulsion systems

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Proliferation of digitalization and data-driven predictive maintenance systems
Escalating integration of used serviceable material and alternative material sourcing strategies
Structural expansion of collaborative joint ventures and open aftermarket ecosystems

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 AAR Corp.

AAR Corp. - Overview
AAR Corp. - Business segments
AAR Corp. - Key offerings
AAR Corp. - Segment focus
SWOT

15.5 Chromalloy Gas Turbine LLC

Chromalloy Gas Turbine LLC - Overview
Chromalloy Gas Turbine LLC - Product / Service
Chromalloy Gas Turbine LLC - Key offerings
SWOT

15.6 Delta TechOps

Delta TechOps - Overview
Delta TechOps - Product / Service
Delta TechOps - Key offerings
SWOT

15.7 General Electric Co.

General Electric Co. - Overview
General Electric Co. - Business segments
General Electric Co. - Key offerings
General Electric Co. - Segment focus
SWOT

15.8 Hong Kong Aircraft Engineering

Hong Kong Aircraft Engineering - Overview
Hong Kong Aircraft Engineering - Product / Service
Hong Kong Aircraft Engineering - Key offerings
SWOT

15.9 Lufthansa Technik

Lufthansa Technik - Overview
Lufthansa Technik - Product / Service
Lufthansa Technik - Key offerings
SWOT

15.10 MTU Aero Engines AG

MTU Aero Engines AG - Overview
MTU Aero Engines AG - Business segments
MTU Aero Engines AG - Key offerings
MTU Aero Engines AG - Segment focus
SWOT

15.11 Pratt and Whitney

Pratt and Whitney - Overview
Pratt and Whitney - Product / Service
Pratt and Whitney - Key offerings
SWOT

15.12 Rolls Royce Holdings Plc

Rolls Royce Holdings Plc - Overview
Rolls Royce Holdings Plc - Business segments
Rolls Royce Holdings Plc - Key offerings
Rolls Royce Holdings Plc - Segment focus
SWOT

15.13 Safran SA

Safran SA - Overview
Safran SA - Business segments
Safran SA - Key news
Safran SA - Key offerings
Safran SA - Segment focus
SWOT

15.14 SIA Engineering Co

SIA Engineering Co - Overview
SIA Engineering Co - Product / Service
SIA Engineering Co - Key offerings
SWOT

15.15 SR Technics Switzerland Ltd.

SR Technics Switzerland Ltd. - Overview
SR Technics Switzerland Ltd. - Product / Service
SR Technics Switzerland Ltd. - Key offerings
SWOT

15.16 ST Engineering Ltd.

ST Engineering Ltd. - Overview
ST Engineering Ltd. - Business segments
ST Engineering Ltd. - Key offerings
ST Engineering Ltd. - Segment focus
SWOT

15.17 StandardAero Inc.

StandardAero Inc. - Overview
StandardAero Inc. - Product / Service
StandardAero Inc. - Key offerings
SWOT

15.18 Turkish Technic Inc.

Turkish Technic Inc. - Overview
Turkish Technic Inc. - Product / Service
Turkish Technic Inc. - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Aircraft Engine Mro market growth will increase by USD 11549.6 million during 2026-2030.

The Aircraft Engine Mro market is expected to grow at a CAGR of 5.4% during 2026-2030.

Aircraft Engine Mro market is segmented by Application (Commercial aviation, Military aviation, General aviation) Type (Turbofan and turbojet, Turboprop) Service (Engine overhaul, Engine repair, Engine modification and upgrades)

AAR Corp., Aero Norway, Air France KLM, Chromalloy Gas Turbine LLC, Delta TechOps, General Electric Co., Hong Kong Aircraft Engineering, Iberia Maintenance, ITP Aero, Lufthansa Technik, MTU Aero Engines AG, Pratt and Whitney, Rolls Royce Holdings Plc, Safran SA, Sanad, SIA Engineering Co, SR Technics Switzerland Ltd., ST Engineering Ltd., StandardAero Inc., Turkish Technic Inc. are a few of the key vendors in the Aircraft Engine Mro market.

North America will register the highest growth rate of 36.6% among the other regions. Therefore, the Aircraft Engine Mro market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

China, Japan, India, Singapore, South Korea, Australia, UK, Germany, France, The Netherlands, Italy, Spain, US, Canada, Mexico, Saudi Arabia, UAE, South Africa, Qatar, Turkey, Brazil, Argentina, Colombia

  • Surging expansion of global fleet and escalating air passenger travel demand is the driving factor this market.

The Aircraft Engine Mro market vendors should focus on grabbing business opportunities from the Application segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
