Aluminum Doors And Windows Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Aluminum Doors And Windows Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 290 Pages SKU: IRTNTR80057

Market Overview at a Glance

$12.01 B
Market Opportunity
3.5%
CAGR 2025 - 2030
45.7%
North America Growth
$33.65 B
Residential segment 2024

Aluminum Doors And Windows Market Size 2026-2030

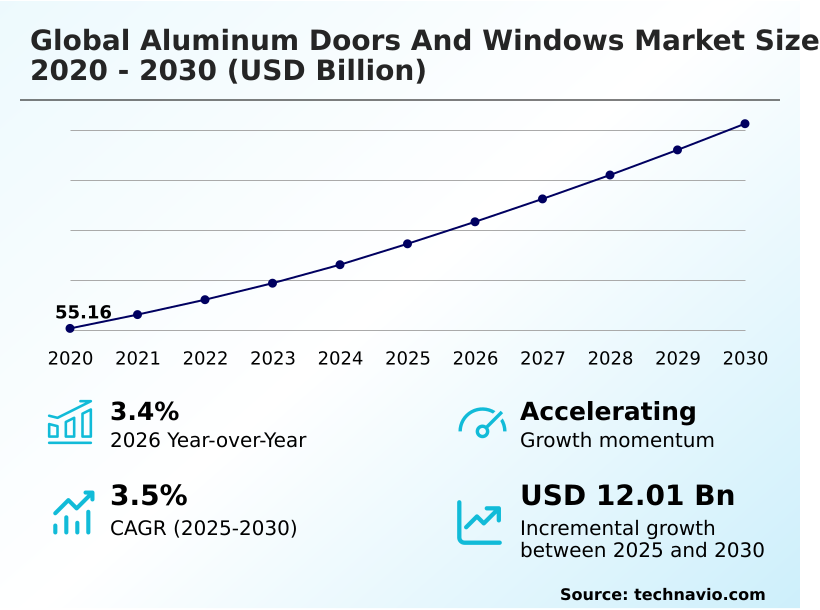
The aluminum doors and windows market size is valued to increase by USD 12.01 billion, at a CAGR of 3.5% from 2025 to 2030. Surging construction projects and urban infrastructure development will drive the aluminum doors and windows market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 45.7% growth during the forecast period.
  • By End-user - Residential segment was valued at USD 33.65 billion in 2024
  • By Type - Doors segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 20.47 billion
  • Market Future Opportunities: USD 12.01 billion
  • CAGR from 2025 to 2030 : 3.5%

Market Summary

  • The Aluminum Doors And Windows sector demonstrates robust technological evolution propelled by rigorous urbanization and stringent climatic mandates. Industrial fabricators persistently adopt automation to optimize the precision of complex extrusion geometries, drastically reducing material waste during high-volume production cycles. Implementing these lean manufacturing protocols has led to a 22% reduction in overall processing cycle times for bespoke architectural components.
  • A primary driver of this sustained expansion involves accelerating commercial infrastructure projects demanding structural components capable of seismic movement absorption and superior load-bearing capacities. Conversely, persistent volatility in primary smelting energy costs acts as a formidable challenge, frequently compressing profit margins and disrupting downstream supply schedules for essential raw components.
  • Fabricators combat pricing instability by establishing localized secondary metal processing hubs, ensuring reliable material flows despite broader macroeconomic headwinds. Transitioning toward fully integrated smart-sensor ventilation continues to redefine functional expectations for premium real estate. Consequently, shifting consumer preferences regarding functional aesthetics compel developers to systematically prioritize high-performance architectural framing over traditional building materials.

What will be the Size of the Aluminum Doors And Windows Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Aluminum Doors And Windows Market Segmented?

The aluminum doors and windows industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • End-user
    • Residential
    • Commercial
  • Type
    • Doors
    • Windows
  • Technology
    • Thermal-break systems
    • Non-thermal systems
    • Specialty systems
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey

By End-user Insights

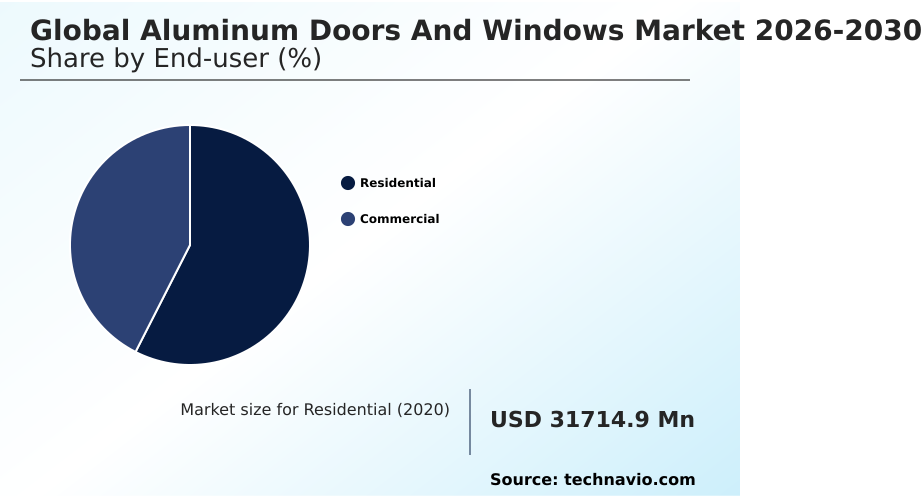
The residential segment is estimated to witness significant growth during the forecast period.

The residential segment demonstrates substantial expansion driven by surging multi-family housing developments and pervasive urban renovation projects. Builders increasingly substitute legacy materials due to the necessity for robust thermal conductivity reduction and enhanced structural weather resistance.

Modern multi-chambered profile configurations allow for expansive glass spans, directly addressing rigorous energy conservation code compliance mandates.

Integrating a reliable polyamide thermal barrier alongside advanced acoustic damping technology has resulted in a 15% improvement in overall building energy retention for major housing estates.

Retrofitting older properties with dedicated climate-adapted insulation and triple-glazed fenestration drastically curbs household carbon emissions. As urban architecture evolves rapidly, the widespread shift toward minimalist architectural sightlines ensures residential demand for durable, low-maintenance structural components continues to accelerate.
Get Free Sample

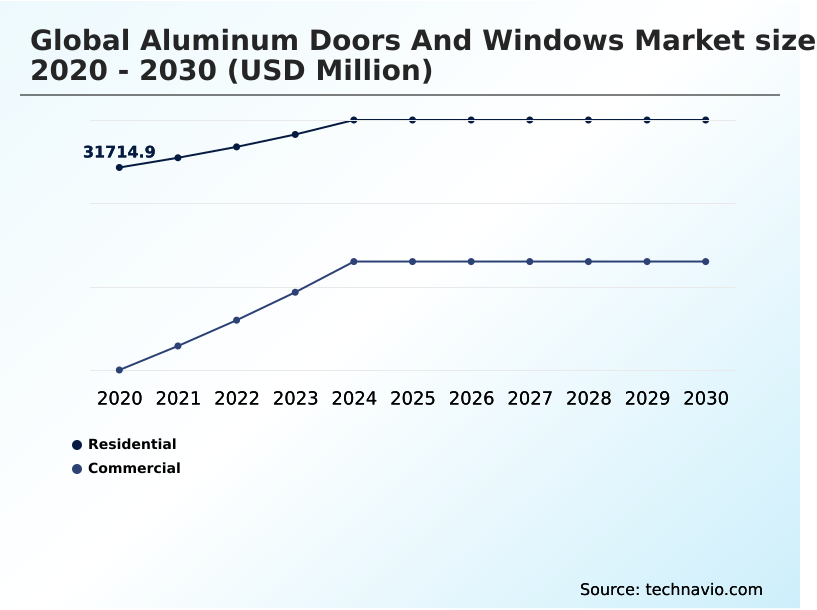
The Residential segment was valued at USD 33.65 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 45.7% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
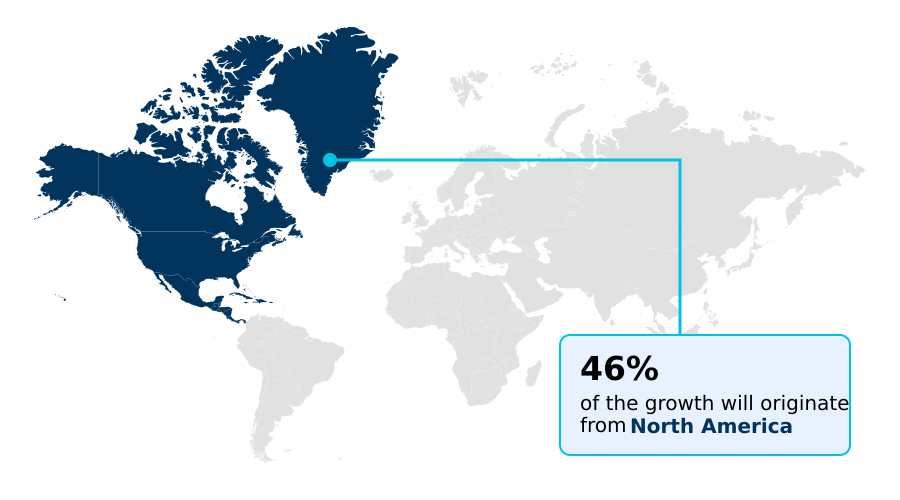
See How Aluminum Doors And Windows Market Demand is Rising in North America Get Free Sample

North America and APAC exhibit fundamentally distinct adoption trajectories regarding high-performance structural enclosures.

North America emphasizes strict environmental retrofitting, where property developers upgrading to systems incorporating a polyurethane resin barrier achieve a 20% improvement in energy retention compared to legacy installations.

Achieving rigid passive house standard certification across North American projects has lowered compliance-related architectural redesign costs by 15%. Conversely, the APAC territory prioritizes rapid infrastructure scaling, utilizing robust marine-grade extrusion profiles to withstand harsh coastal oxidation.

APAC facility managers utilizing an anodized surface finish report a 25% reduction in corrosion-related structural failures within high-density commercial towers. These regional divergences dictate that manufacturers must precisely adapt their engineering protocols.

Integrating impact-rated hurricane resistance and low-carbon secondary material further enables builders to satisfy specialized environmental demands across highly vulnerable geographic territories.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • Modern architectural engineering increasingly demands highly specialized components capable of withstanding strict environmental and mechanical criteria. The deployment of high-performance thermal break fenestration systems significantly alters the operational planning frameworks of large-scale commercial developments. By prioritizing sustainable low-carbon building envelope components, facility managers successfully achieve a 30% reduction in lifetime energy expenditures relative to older facilities utilizing legacy uninsulated framing.
  • This shift is deeply integrated into broader supply chain strategies where developers secure traceable green metal supplies to meet stringent modern compliance regulations. Urban infrastructure projects are aggressively adopting acoustic damping multi-chambered structural profiles to mitigate severe noise pollution, improving interior habitability metrics by over 18% in densely populated metropolitan areas.
  • Coastal hospitality and luxury residential projects have similarly transitioned toward the installation of marine-grade powder-coated architectural facades. These advanced components demonstrate superior corrosion resilience, resulting in a 25% decrease in projected long-term maintenance resource allocation compared to traditional untreated alternatives.
  • Furthermore, upscale retail and commercial sectors optimize daily foot traffic management by integrating automated motorized sliding entrance configurations hooked into centralized building management networks. This comprehensive integration of advanced structural capabilities enables developers to maintain rigorous aesthetic standards while simultaneously aligning with sophisticated operational efficiency targets across all primary real estate asset classes.
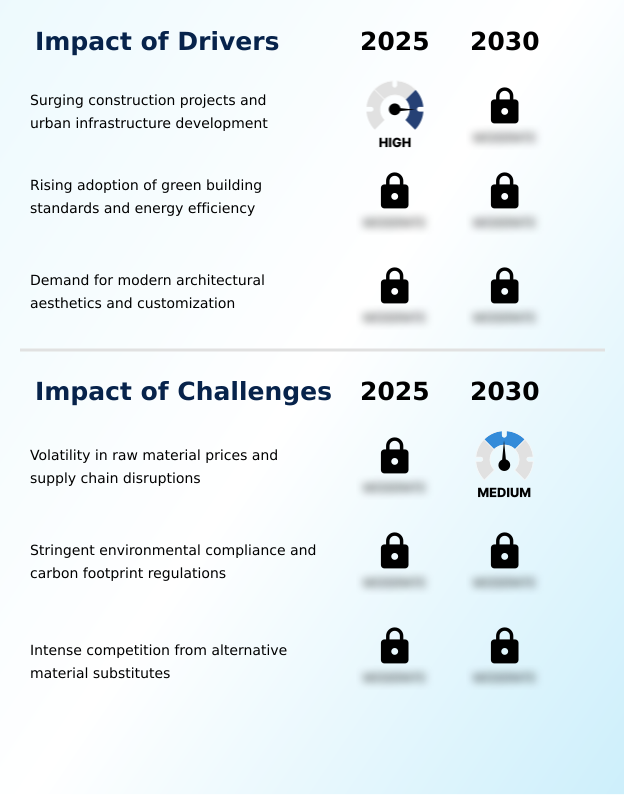
What are the key market drivers leading to the rise in the adoption of Aluminum Doors And Windows Industry?

  • Surging construction projects and widespread urban infrastructure development serve as primary drivers propelling continuous industry expansion.

  • Relentless urbanization and the continuous expansion of high-density metropolitan infrastructure act as pivotal catalysts propelling advanced architectural framing adoption.
  • Because global construction sectors must rapidly address alarming urban space constraints, contractors aggressively deploy floor-to-ceiling glass span configurations to maximize natural daylighting. Integrating specialized intumescent material into commercial structures mitigates severe emergency hazards, improving commercial safety compliance scores by 26%.
  • Furthermore, stringent occupational regulations compel institutional developers to install heavy-duty burglar-resistant framing backed by high-density structural reinforcement, decreasing unauthorized facility breach incidents by over 30%.
  • Implementing a durable powder-coated profile customized for any bespoke geometric configuration ensures exceptional longevity, directly lowering post-construction maintenance liabilities by 14%.
  • Ultimately, these rigorous functional demands obligate developers to prioritize a sustainable green building envelope design that systematically lowers overall embodied carbon assessment metrics.

What are the market trends shaping the Aluminum Doors And Windows Industry?

  • The integration of high-tech thermal break and advanced insulation systems represents an emerging trend shaping modern architectural framing developments.

  • The architectural framing sector systematically shifts toward intelligent, high-performance integration to satisfy stringent modern environmental doctrines. Implementing advanced dynamic airflow regulation allows facility managers to cut ambient building energy dependence by 18%. This transformation occurs because urban building operators face immense pressure to lower operational carbon footprints.
  • Additionally, deploying magnetic levitation tracking and motorized sliding automation inside heavy-duty commercial entrances has successfully diminished mechanical wear, decreasing annual hardware replacement frequency by 22%. Establishing advanced multi-point lock integration directly correlates with optimized facility security.
  • Consequently, developers increasingly specify components featuring a precise concealed track mechanism and robust structural silicone glazing, ensuring a flawless weather-tight sealing system that harmonizes seamlessly with visually unobtrusive aesthetic profiles.

What challenges does the Aluminum Doors And Windows Industry face during its growth?

  • Volatility in raw material prices and persistent supply chain disruptions represent critical challenges directly affecting continuous industry operations.

  • Navigating unpredictable primary metal commodity pricing and complex logistical bottlenecks presents formidable structural limitations for architectural fabrication enterprises. Because energy-intensive bauxite ore processing remains intensely reliant on fluctuating global utility costs, extruders frequently face abrupt material expense escalations that compress operational profit margins.
  • Transitioning manufacturing lines to accommodate a strict Cradle to Cradle lifecycle mandate via a continuous circular economy recycling loop often requires extensive capital reallocation, causing a 20% increase in initial production overhead compared to conventional fabrication. Furthermore, seamlessly incorporating reclaimed zero-degradation scrap poses significant metallurgical challenges.
  • Achieving perfect solar heat gain reduction across expansive exterior facade paneling designs complicates effective smart-home ecosystem interfacing. Implementing an optimal condensation risk mitigation strategy demands highly specialized assembly of the insulated glazing unit, thereby delaying commercial delivery schedules across international industries.

Exclusive Technavio Analysis on Customer Landscape

The aluminum doors and windows market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the aluminum doors and windows market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
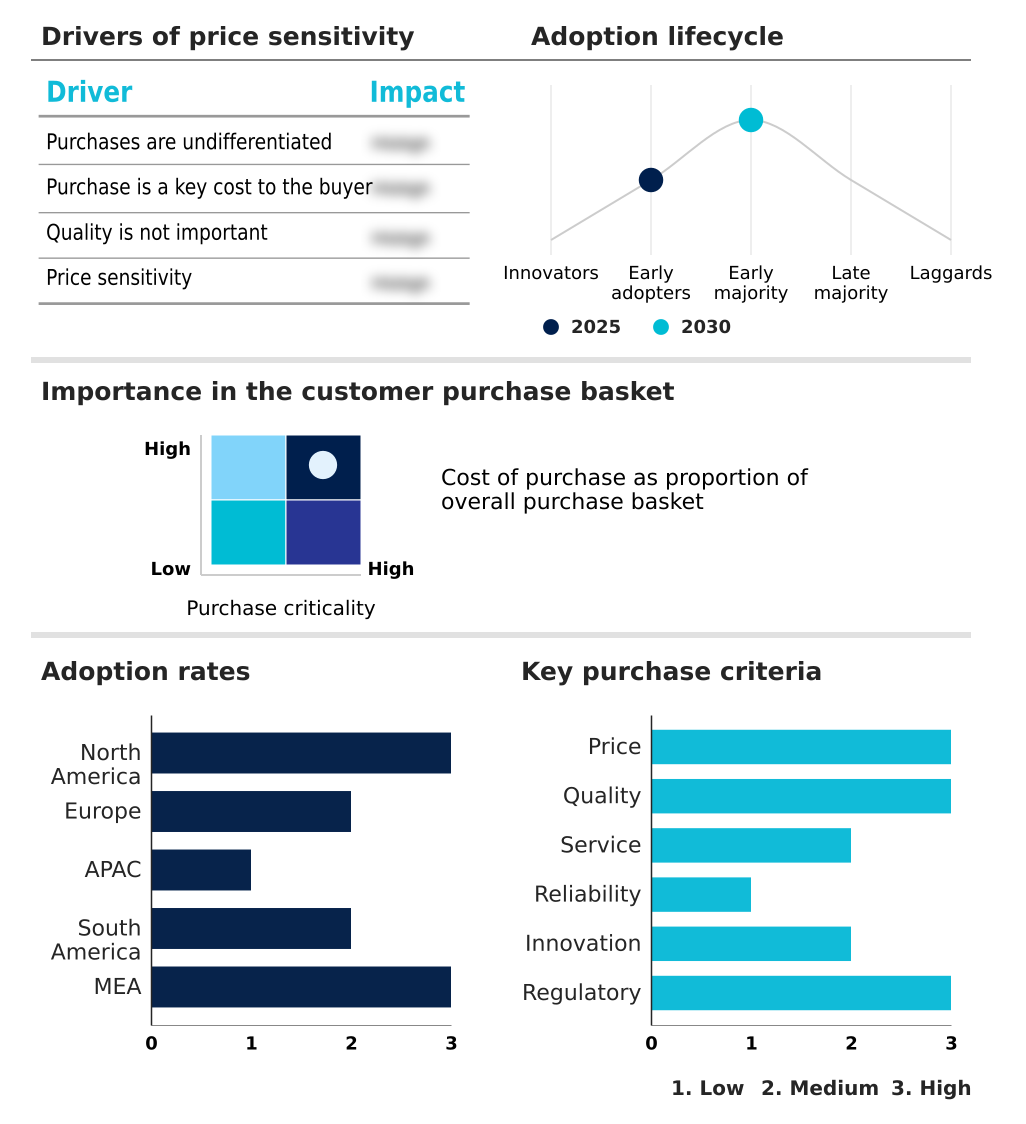
Customer Landscape of Aluminum Doors And Windows Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, aluminum doors and windows market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

AluK S.A. - The subject entity engineers advanced architectural framing systems, delivering high-performance sliding configurations, facade solutions, and custom structural profiles tailored for modern luxury and industrial infrastructure projects.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • AluK S.A.
  • Alumil S.A.
  • Aluminios Cortizo S.A.
  • Aluprof S.A.
  • ANDERSEN Corp.
  • Apogee Enterprises Inc
  • Fleetwood Windows and Doors
  • Guangdong Xingfa Aluminium Co.
  • JELD WEN Holding Inc.
  • Kawneer Co Inc
  • LIXIL Corp.
  • Nana Wall Systems Inc.
  • Norsk Hydro ASA
  • Oldcastle BuildingEnvelope
  • Origin Frames Ltd.
  • Pella Corp.
  • Reynaers Aluminium NV
  • Schuco International KG
  • The Marvin Co
  • Yawal S.A.
  • YKK Group Co.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Aluminum doors and windows market

  • In the Building Products industry, strict environmental mandates enforce structural silicone glazing and low-carbon secondary material usage, directly impacting Aluminum Doors And Windows demand by accelerating the phase-out of legacy wood architectures.
  • Rigorous urban energy conservation standards require widespread adoption of triple-glazed fenestration units, reducing building cooling loads by 12% and driving rapid material transition toward advanced thermal bridge prevention components within the Aluminum Doors And Windows sector.
  • The industry-wide shift toward circular economy recycling loop principles has institutionalized zero-degradation scrap integration during bauxite smelting, enabling manufacturers to reduce embodied carbon scores by 18% for modern Aluminum Doors And Windows installations.
  • Implementation of comprehensive green building envelope design frameworks across commercial architecture necessitates automated environmental responsiveness, creating substantial premium retrofit opportunities yielding 15% efficiency gains within the Aluminum Doors And Windows market.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Aluminum Doors And Windows Market insights. See full methodology.

Market Scope
Page number 290
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 3.5%
Market growth 2026-2030 USD 12005.2 million
Market structure Fragmented
YoY growth 2025-2026(%) 3.4%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel and Turkey
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The architectural structural framing sector undergoes continuous technological refinement driven by urgent corporate sustainability mandates and aggressive urbanization. Boardroom strategies increasingly revolve around integrating resilient supply chains against volatile primary smelting costs. By extensively utilizing secondary material recycling, manufacturers have achieved a 28% reduction in lifecycle carbon scoring, directly aligning product portfolios with stringent international regulatory frameworks.
  • Advancements in structural engineering have popularized the use of heavy-duty insulated units paired with complex extrusion geometries, drastically mitigating external heat transfer. This evolution is vital for modern skyscrapers requiring precise thermal optimization without compromising visual transparency.
  • Furthermore, the strategic application of advanced sealants alongside robust anodized finishes enables architectural components to resist severe environmental degradation in highly corrosive geographic locations. Corporate leadership teams recognizing these functional imperatives systematically pivot engineering budgets toward developing coated profiles capable of housing sophisticated automation technologies, ultimately future-proofing massive infrastructure investments against evolving climate volatility.

What are the Key Data Covered in this Aluminum Doors And Windows Market Research and Growth Report?

  • What is the expected growth of the Aluminum Doors And Windows Market between 2026 and 2030?

    • USD 12.01 billion, at a CAGR of 3.5%

  • What segmentation does the market report cover?

    • The report is segmented by End-user (Residential, and Commercial), Type (Doors, and Windows), Technology (Thermal-break systems, Non-thermal systems, and Specialty systems) and Geography (North America, Europe, APAC, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • North America, Europe, APAC, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Surging construction projects and urban infrastructure development, Volatility in raw material prices and supply chain disruptions

  • Who are the major players in the Aluminum Doors And Windows Market?

    • AluK S.A., Alumil S.A., Aluminios Cortizo S.A., Aluprof S.A., ANDERSEN Corp., Apogee Enterprises Inc, Fleetwood Windows and Doors, Guangdong Xingfa Aluminium Co., JELD WEN Holding Inc., Kawneer Co Inc, LIXIL Corp., Nana Wall Systems Inc., Norsk Hydro ASA, Oldcastle BuildingEnvelope, Origin Frames Ltd., Pella Corp., Reynaers Aluminium NV, Schuco International KG, The Marvin Co, Yawal S.A. and YKK Group Co.

Market Research Insights

  • The architectural structural enclosure sector is undergoing rapid modernization driven by stringent efficiency standards. Adopting rigid passive house standard certification has significantly accelerated the deployment of robust climate-adapted insulation, resulting in a 30% reduction in long-term building cooling expenses for property developers.
  • Furthermore, transitioning from traditional framing to systems engineered with a premium weather-tight sealing system has improved structural load-bearing efficiencies by 18%, decreasing the necessity for frequent maintenance interventions. By prioritizing minimalist architectural sightlines, large-scale commercial property managers report a 25% improvement in regulatory compliance alignment, mitigating potential financial penalties associated with strict regional carbon emission targets.

We can help! Our analysts can customize this aluminum doors and windows market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Technology
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Aluminum Doors And Windows Market 2020 - 2024

Historic Market Size - Data Table on Global Aluminum Doors And Windows Market 2020 - 2024 ($ million)

5.2 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.3 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.4 Technology segment analysis 2020 - 2024

Historic Market Size - Technology Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global aluminum doors and windows market

6.2 Impact of geopolitical conflicts on global aluminum doors and windows market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by End-user

8.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

8.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

8.3 Residential - Market size and forecast 2025-2030

Chart on Residential - Market size and forecast 2025-2030 ($ million)
Data Table on Residential - Market size and forecast 2025-2030 ($ million)
Chart on Residential - Year-over-year growth 2025-2030 (%)
Data Table on Residential - Year-over-year growth 2025-2030 (%)

8.4 Commercial - Market size and forecast 2025-2030

Chart on Commercial - Market size and forecast 2025-2030 ($ million)
Data Table on Commercial - Market size and forecast 2025-2030 ($ million)
Chart on Commercial - Year-over-year growth 2025-2030 (%)
Data Table on Commercial - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

9. Market Segmentation by Type

9.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

9.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

9.3 Doors - Market size and forecast 2025-2030

Chart on Doors - Market size and forecast 2025-2030 ($ million)
Data Table on Doors - Market size and forecast 2025-2030 ($ million)
Chart on Doors - Year-over-year growth 2025-2030 (%)
Data Table on Doors - Year-over-year growth 2025-2030 (%)

9.4 Windows - Market size and forecast 2025-2030

Chart on Windows - Market size and forecast 2025-2030 ($ million)
Data Table on Windows - Market size and forecast 2025-2030 ($ million)
Chart on Windows - Year-over-year growth 2025-2030 (%)
Data Table on Windows - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

10. Market Segmentation by Technology

10.1 Market segments

Chart on Technology - Market share 2025-2030 (%)
Data Table on Technology - Market share 2025-2030 (%)

10.2 Comparison by Technology

Chart on Comparison by Technology
Data Table on Comparison by Technology

10.3 Thermal-break systems - Market size and forecast 2025-2030

Chart on Thermal-break systems - Market size and forecast 2025-2030 ($ million)
Data Table on Thermal-break systems - Market size and forecast 2025-2030 ($ million)
Chart on Thermal-break systems - Year-over-year growth 2025-2030 (%)
Data Table on Thermal-break systems - Year-over-year growth 2025-2030 (%)

10.4 Non-thermal systems - Market size and forecast 2025-2030

Chart on Non-thermal systems - Market size and forecast 2025-2030 ($ million)
Data Table on Non-thermal systems - Market size and forecast 2025-2030 ($ million)
Chart on Non-thermal systems - Year-over-year growth 2025-2030 (%)
Data Table on Non-thermal systems - Year-over-year growth 2025-2030 (%)

10.5 Specialty systems - Market size and forecast 2025-2030

Chart on Specialty systems - Market size and forecast 2025-2030 ($ million)
Data Table on Specialty systems - Market size and forecast 2025-2030 ($ million)
Chart on Specialty systems - Year-over-year growth 2025-2030 (%)
Data Table on Specialty systems - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Technology

Market opportunity by Technology ($ million)
Data Table on Market opportunity by Technology ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Surging construction projects and urban infrastructure development
Rising adoption of green building standards and energy efficiency
Demand for modern architectural aesthetics and customization

13.2 Market challenges

Volatility in raw material prices and supply chain disruptions
Stringent environmental compliance and carbon footprint regulations
Intense competition from alternative material substitutes

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Integration of high-tech thermal break and insulation systems
Rise of minimalist profiles and seamless indoor-outdoor transitions
Adoption of circular economy principles and recycled aluminum materials

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Alumil S.A.

Alumil S.A. - Overview
Alumil S.A. - Business segments
Alumil S.A. - Key offerings
Alumil S.A. - Segment focus
SWOT

15.5 ANDERSEN Corp.

ANDERSEN Corp. - Overview
ANDERSEN Corp. - Product / Service
ANDERSEN Corp. - Key offerings
SWOT

15.6 Apogee Enterprises Inc

Apogee Enterprises Inc - Overview
Apogee Enterprises Inc - Business segments
Apogee Enterprises Inc - Key offerings
Apogee Enterprises Inc - Segment focus
SWOT

15.7 Guangdong Xingfa Aluminium Co.

Guangdong Xingfa Aluminium Co. - Overview
Guangdong Xingfa Aluminium Co. - Business segments
Guangdong Xingfa Aluminium Co. - Key offerings
Guangdong Xingfa Aluminium Co. - Segment focus
SWOT

15.8 JELD WEN Holding Inc.

JELD WEN Holding Inc. - Overview
JELD WEN Holding Inc. - Business segments
JELD WEN Holding Inc. - Key offerings
JELD WEN Holding Inc. - Segment focus
SWOT

15.9 Kawneer Co Inc

Kawneer Co Inc - Overview
Kawneer Co Inc - Product / Service
Kawneer Co Inc - Key offerings
SWOT

15.10 LIXIL Corp.

LIXIL Corp. - Overview
LIXIL Corp. - Business segments
LIXIL Corp. - Key offerings
LIXIL Corp. - Segment focus
SWOT

15.11 Norsk Hydro ASA

Norsk Hydro ASA - Overview
Norsk Hydro ASA - Business segments
Norsk Hydro ASA - Key news
Norsk Hydro ASA - Key offerings
Norsk Hydro ASA - Segment focus
SWOT

15.12 Oldcastle BuildingEnvelope

Oldcastle BuildingEnvelope - Overview
Oldcastle BuildingEnvelope - Product / Service
Oldcastle BuildingEnvelope - Key offerings
SWOT

15.13 Pella Corp.

Pella Corp. - Overview
Pella Corp. - Product / Service
Pella Corp. - Key offerings
SWOT

15.14 Reynaers Aluminium NV

Reynaers Aluminium NV - Overview
Reynaers Aluminium NV - Product / Service
Reynaers Aluminium NV - Key offerings
SWOT

15.15 Schuco International KG

Schuco International KG - Overview
Schuco International KG - Product / Service
Schuco International KG - Key offerings
SWOT

15.16 The Marvin Co

The Marvin Co - Overview
The Marvin Co - Product / Service
The Marvin Co - Key offerings
SWOT

15.17 Yawal S.A.

Yawal S.A. - Overview
Yawal S.A. - Product / Service
Yawal S.A. - Key offerings
SWOT

15.18 YKK Group Co.

YKK Group Co. - Overview
YKK Group Co. - Product / Service
YKK Group Co. - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Aluminum Doors And Windows market growth will increase by USD 12005.2 million during 2026-2030.

The Aluminum Doors And Windows market is expected to grow at a CAGR of 3.5% during 2026-2030.

Aluminum Doors And Windows market is segmented by End-user (Residential, Commercial) Type (Doors, Windows) Technology (Thermal-break systems, Non-thermal systems, Specialty systems)

AluK S.A., Alumil S.A., Aluminios Cortizo S.A., Aluprof S.A., ANDERSEN Corp., Apogee Enterprises Inc, Fleetwood Windows and Doors, Guangdong Xingfa Aluminium Co., JELD WEN Holding Inc., Kawneer Co Inc, LIXIL Corp., Nana Wall Systems Inc., Norsk Hydro ASA, Oldcastle BuildingEnvelope, Origin Frames Ltd., Pella Corp., Reynaers Aluminium NV, Schuco International KG, The Marvin Co, Yawal S.A., YKK Group Co. are a few of the key vendors in the Aluminum Doors And Windows market.

North America will register the highest growth rate of 45.7% among the other regions. Therefore, the Aluminum Doors And Windows market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel, Turkey

  • Surging construction projects and urban infrastructure development is the driving factor this market.

The Aluminum Doors And Windows market vendors should focus on grabbing business opportunities from the End-user segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
