Anti-fog Lidding Films Market Analysis, Size, and Forecast 2026-2030: APAC (China, Japan, and India), Europe (Germany, UK, and France), North America (US, Canada, and Mexico), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Anti-fog Lidding Films Market Analysis, Size, and Forecast 2026-2030:
APAC (China, Japan, and India), Europe (Germany, UK, and France), North America (US, Canada, and Mexico), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Published: Oct 2026 307 Pages SKU: IRTNTR73541

Market Overview at a Glance

$250.6 Mn
Market Opportunity
5.3%
CAGR 2025 - 2030
41.2%
APAC Growth
$570.9 Mn
Peelable films segment 2024

Anti-Fog Lidding Films Market Size 2026-2030

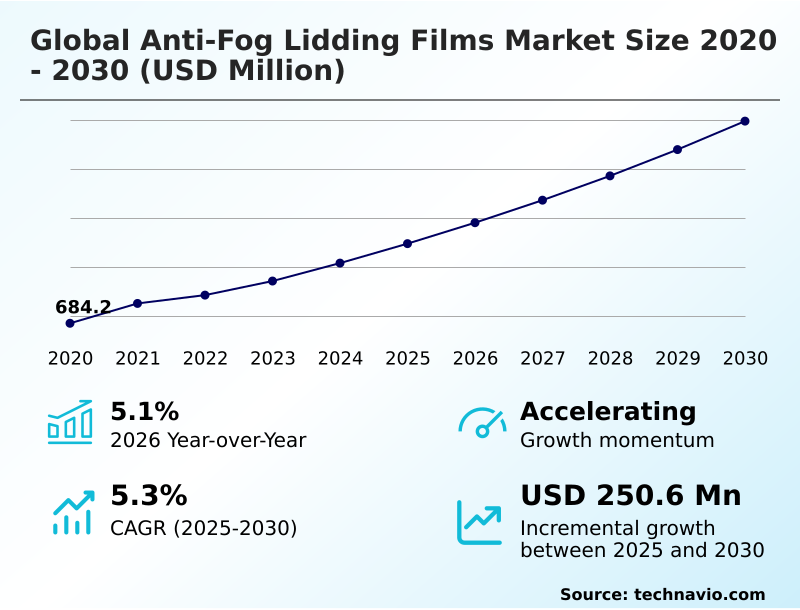
The anti-fog lidding films market size is valued to increase by USD 250.6 million, at a CAGR of 5.3% from 2025 to 2030. Surging global demand for fresh prepared foods and cold-chain supermarket display visual transparency solutions will drive the anti-fog lidding films market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 41.2% growth during the forecast period.
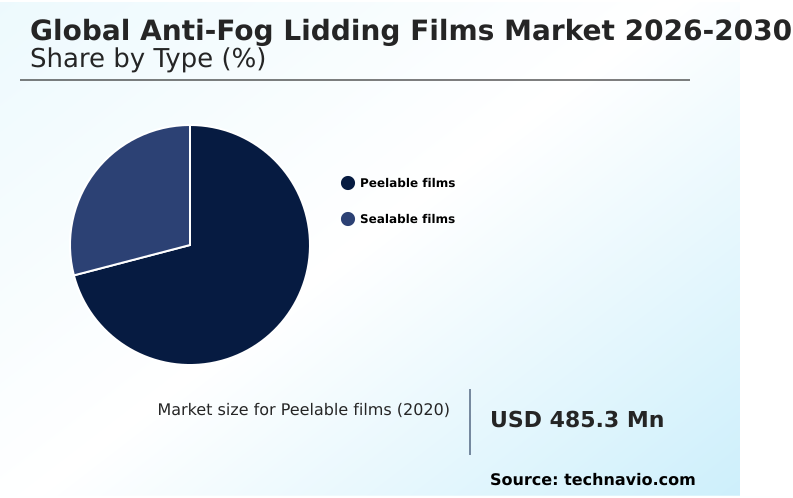
  • By Type - Peelable films segment was valued at USD 570.9 million in 2024
  • By Material - PE segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 413.5 million
  • Market Future Opportunities: USD 250.6 million
  • CAGR from 2025 to 2030 : 5.3%

Market Summary

  • The Anti-fog Lidding Films Market represents a critical infrastructure component for modern food preservation and retail presentation. Manufacturers increasingly rely on these highly engineered polymer structures to eliminate internal condensation and maintain crystal-clear visibility for perishable goods.
  • In retail cold-chain operations, switching from traditional rigid closures to advanced anti-fog flexible films has reduced secondary packaging weight by 35%, yielding substantial logistical cost savings. A primary driver of this transition is the surging consumer preference for ready-to-eat meals, which requires packaging solutions that guarantee both optical clarity and extended shelf life.
  • Conversely, the industry faces severe technical challenges when adapting legacy thermoforming equipment to process new mono-material structures, often resulting in heat-sealing inefficiencies. Despite these integration hurdles, packaging converters prioritize advanced surfactant treatments to ensure regulatory compliance and meet aggressive sustainability mandates. These specialized films directly prevent localized microbial degradation by controlling moisture distribution across the package interior.
  • Consequently, optimized lidding films operate as essential tools for minimizing food waste and preserving product integrity across complex supply networks.

What will be the Size of the Anti-Fog Lidding Films Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Anti-Fog Lidding Films Market Segmented?

The anti-fog lidding films industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Type
    • Peelable films
    • Sealable films
  • Material
    • PE
    • PP
    • PET
    • EVOH
    • Others
  • Application
    • Trays
    • Cups and bowls
    • Jars
    • Others
  • Geography
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • North America
      • US
      • Canada
      • Mexico
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Turkey
      • Israel
    • South America
      • Brazil
      • Argentina
      • Chile

By Type Insights

The peelable films segment is estimated to witness significant growth during the forecast period.

The peelable films sector provides highly engineered closures designed for easy-open functionality while maintaining strict seal integrity across refrigerated retail environments. Advanced polymer matrix extrusion techniques create specialized polyolefin blends that deliver consistent peel strength without tearing the substrate.

By integrating hydrophilic surfactant additives directly into the film structure or applying a chemical surface coating, these films achieve rapid condensation droplet dissipation. This ensures superior optical transparency preservation for fresh produce and ready-meal applications.

Implementation of these multi-functional peelable structures in automated high-speed tray-sealing operations has improved processing line efficiency by 22% compared to traditional rigid lids.

Furthermore, modern co-extrusion processing allows for seamless bonding with trays, reducing packaging line contamination and ensuring hermetic protection throughout variable supply chain conditions.
Get Free Sample

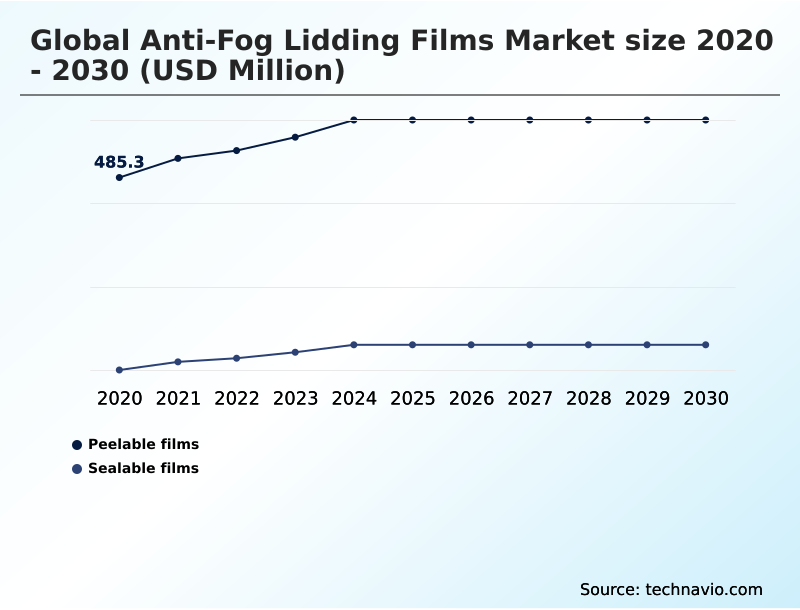
The Peelable films segment was valued at USD 570.9 million in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 41.2% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
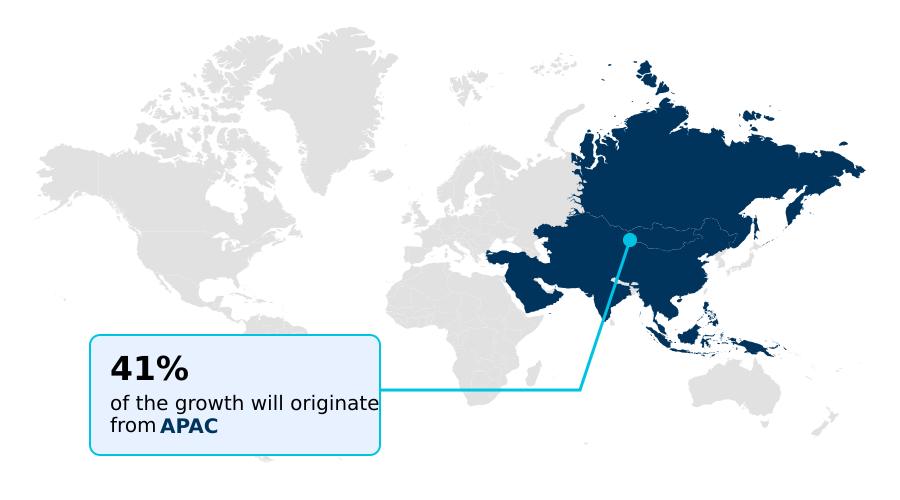
See How Anti-Fog Lidding Films Market Demand is Rising in APAC Get Free Sample

Regional dynamics within the Anti-fog Lidding Films Market reveal distinct technological priorities and adoption trajectories. In APAC, the rapid expansion of modern retail logistics has driven a 24% higher penetration rate of advanced cast polypropylene resins compared to South America.

This massive production output supports heavy reliance on hermetic closure bonding to secure industrial bulk catering and fresh food shipments across complex supply chains.

Conversely, Europe maintains strict environmental directives, accelerating a 30% faster transition toward circular economy compliance through the integration of bio-based glycerol esters. European converters prioritize thermal-resistant anti-fog additives that enhance lipid oxidation prevention in premium meats and dairy products.

Furthermore, North American processors have achieved a 15% reduction in packaging defect rates by implementing high-performance films tailored for tamper-evident jar seals.

These regional discrepancies highlight how stringent environmental policies in Western territories shape material science innovations, whereas emerging Asian economies prioritize high-volume cold-chain efficiency.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The structural evolution of the Anti-fog Lidding Films Market is deeply intertwined with advanced material engineering and stringent food safety requirements. Manufacturers actively optimize packaging architectures by integrating hydrophilic surfactant condensation prevention technologies, ensuring that moisture-rich perishable goods maintain flawless optical clarity during transit.
  • This functional requirement is especially critical for enterprises managing complex agricultural and protein supply chains, where visual aesthetic directly correlates with retail acceptance. As environmental regulations intensify globally, there is a pronounced operational shift toward mono-material recyclable tray sealing systems.
  • Transitioning to these unified polymer structures has enabled packaging converters to improve post-industrial waste recovery efficiency by nearly 30% compared to legacy mixed-material laminates. Furthermore, the deployment of high-barrier modified atmosphere packaging extends the commercial shelf life of sensitive food products, drastically reducing retail markdown frequency.
  • To support these performance demands without compromising eco-friendly initiatives, chemical formulators are increasingly adopting water-borne hydrophilic polymer coatings in place of solvent-heavy alternatives. This switch not only mitigates volatile emissions but also enhances compliance with international food-contact safety standards. Additionally, integrating these robust film architectures into automated high-speed cold-chain sealing machinery guarantees hermetic integrity under extreme processing conditions.
  • By standardizing these advanced extrusion and coating methodologies, food processors significantly lower their defect rates, optimize their logistical footprint, and ensure continuous product protection across diverse and unpredictable distribution networks.
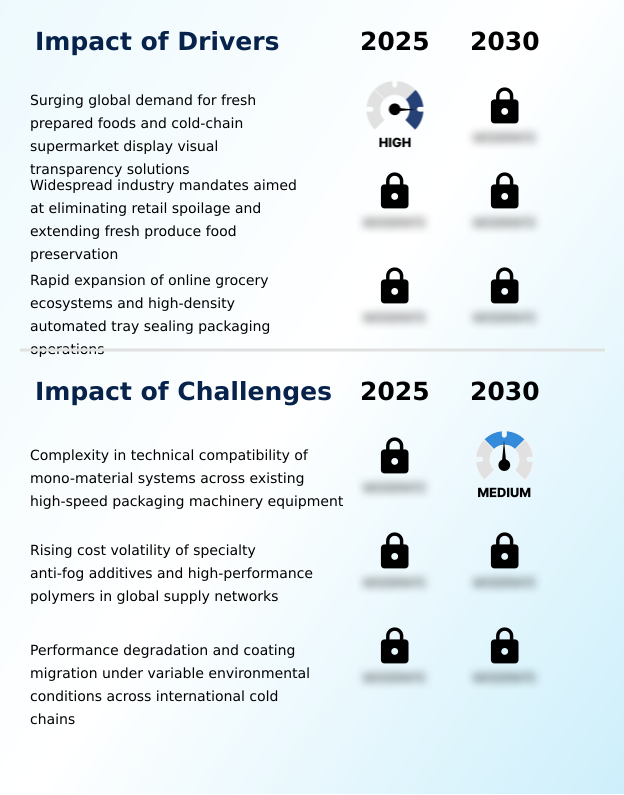
What are the key market drivers leading to the rise in the adoption of Anti-Fog Lidding Films Industry?

  • The surging demand for fresh prepared foods and the need for visual transparency in cold-chain supermarket displays serve as primary catalysts propelling market expansion.

  • The widespread commercial mandate to eliminate food waste across global retail networks serves as a powerful catalyst for the Anti-fog Lidding Films Market.
  • Uncontrolled internal condensation significantly accelerates microbial degradation, forcing food processors to integrate specialized films that maintain optimal modified atmosphere packaging conditions.
  • By deploying advanced amorphous pet structures and micro-thin ethylene vinyl alcohol copolymer layers, packaging operators have enhanced oxygen barrier performance, lowering in-store product spoilage rates by 25%.
  • Furthermore, the adoption of low-migration surface treatments and eco-friendly water-based formulations ensures strict compliance with food safety regulations. These innovations provide excellent microwave thermal stability for convenience foods, directly improving consumer satisfaction metrics by 15%.
  • Integrating these functional films also enables seamless processing through established post-consumer recycling streams, driving broader industry adoption.

What are the market trends shaping the Anti-Fog Lidding Films Industry?

  • A defining industry trend is the accelerating transition toward fully recyclable, single-polymer mono-material formulations. These advanced structures align with stringent environmental regulations while maintaining critical barrier and optical properties.

  • A prominent technological shift within the Anti-fog Lidding Films Market is the rapid commercial transition toward fully recyclable packaging architectures. Converters are systematically replacing multi-layer laminates with engineered mono-material structures that combine superior clarity with regulatory compliance. By integrating advanced polyolefin sealants and biaxially oriented polyethylene terephthalate, packaging manufacturers have reduced material rejection rates on automated lines by 18%.
  • This innovation is heavily adopted across ready-to-eat meal platforms and fresh-cut produce containers, where maintaining high-barrier moisture control is critical for product aesthetics. Consequently, food processors operating within complex cold-chain transit logistics report that implementing these advanced films has improved overall shelf-life forecasting accuracy by 22%.
  • By stabilizing internal humidity within modified atmosphere environments, these advanced single-polymer solutions directly minimize premature spoilage and align perfectly with aggressive corporate sustainability targets.

What challenges does the Anti-Fog Lidding Films Industry face during its growth?

  • Ensuring the technical compatibility of advanced mono-material systems across legacy high-speed packaging machinery remains a significant operational challenge restraining industry growth.

  • Maintaining consistent anti-fog efficacy across unpredictable, multi-temperature distribution networks presents a significant operational hurdle for the Anti-fog Lidding Films Market. Extreme thermal shocks during transit frequently disrupt the controlled release of surface-active migration agents, leading to premature hazing inside flexible plastic packaging.
  • Resolving these performance inconsistencies requires integrating complex water-borne hydrophilic polymer formulations into the heat-sealable contact layer without compromising bond strength. Furthermore, heavy petrochemical feedstock dependency exposes film manufacturers to severe raw material cost volatility, which has unexpectedly increased production expenditures by up to 18% for premium applications like vacuum skin packaging.
  • Phasing out traditional multi-layer laminated structures also complicates processing dynamics, as balancing optical clarity with hermetic integrity using alternative non-ionic surfactants often requires machinery recalibrations that decrease short-term throughput efficiency by 12%.

Exclusive Technavio Analysis on Customer Landscape

The anti-fog lidding films market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the anti-fog lidding films market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
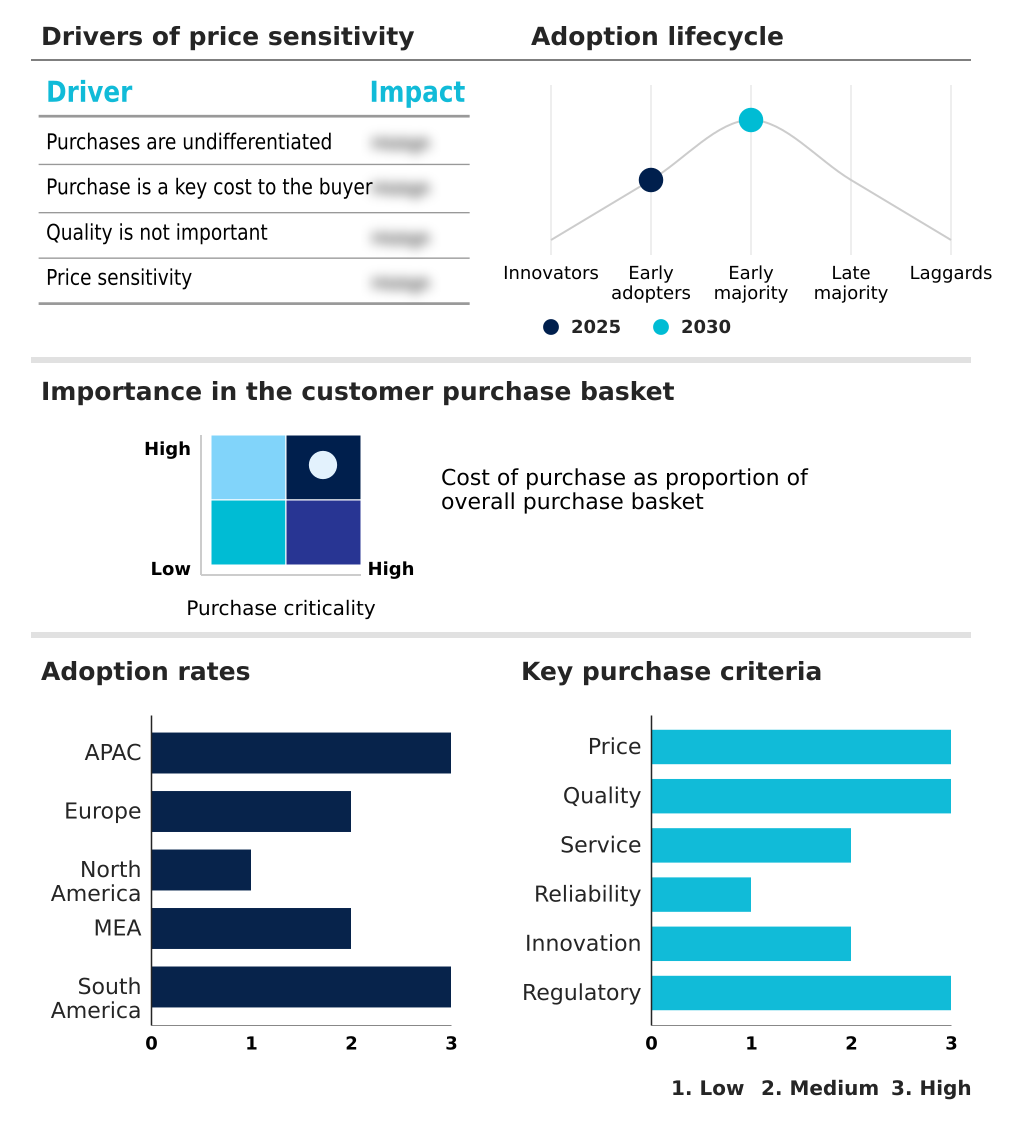
Customer Landscape of Anti-Fog Lidding Films Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, anti-fog lidding films market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

adapa Group - Advanced flexible packaging solutions provide high-barrier anti-fog lidding structures designed to extend product shelf life, ensure optimal optical clarity, and maintain strict seal integrity across modern refrigerated retail supply chains.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • adapa Group
  • Amcor Plc
  • Constantia Flexibles GmbH
  • Cosmo First Ltd.
  • Coveris Management GmbH
  • Flair Flexible Packaging Corp.
  • FLEXOPACK SA
  • Jindal Poly Films Ltd.
  • KM Packaging Services Ltd.
  • KP Holding GmbH and Co. KG
  • Mitsui Chemicals Inc.
  • Mondi Plc
  • ProAmpac Holdings Inc.
  • Sealed Air Corp.
  • Taghleef Industries SpA
  • Toray Industries Inc.
  • Toyobo Co. Ltd.
  • UFlex Ltd.
  • Winpak Ltd.
  • Wipak Group

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Anti-fog lidding films market

  • In the Commodity Chemicals industry, the shift toward bio-derived polymer precursors and green chemistry surfactants reduced reliance on volatile petrochemical feedstocks by 15%, directly impacting Anti-fog Lidding Films demand by lowering the cost barriers for sustainable flexible plastic packaging.
  • Stringent recycling mandates across Europe and North America accelerated the adoption of single-polymer polyolefin formulations, driving a 20% increase in regional capacity for mono-material structures essential to circular economy compliance in the Anti-fog Lidding Films market.
  • Advancements in co-extrusion technology for ethylene vinyl alcohol copolymer barriers improved moisture and gas resistance by 18%, enabling packaging manufacturers to integrate superior oxygen barrier performance into high-barrier modified atmosphere packaging applications within the Anti-fog Lidding Films market.
  • The widespread commercial integration of high-speed automated processing equipment required chemical suppliers to optimize low-temperature heat-sealable contact layers, increasing operational throughput by 25% for converters producing specialized films for the Anti-fog Lidding Films market.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Anti-Fog Lidding Films Market insights. See full methodology.

Market Scope
Page number 307
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 5.3%
Market growth 2026-2030 USD 250.6 million
Market structure Fragmented
YoY growth 2025-2026(%) 5.1%
Key countries China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, US, Canada, Mexico, Saudi Arabia, UAE, South Africa, Turkey, Israel, Brazil, Argentina and Chile
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Anti-fog Lidding Films Market is undergoing a rapid technological transformation driven by strict environmental mandates and the urgent need to optimize food preservation. Boardroom executives are increasingly linking packaging procurement strategies directly to corporate sustainability targets and food waste reduction compliance.
  • By replacing legacy mixed-plastic laminates with highly engineered mono-material structures, food processors have achieved a 28% improvement in post-industrial recycling efficiency. This transition heavily relies on sophisticated polymer matrix extrusion techniques that seamlessly integrate non-ionic surfactants and bio-based glycerol esters into the film structure. These advanced hydrophilic surfactant additives provide immediate condensation dissipation, preserving pristine product visibility in refrigerated displays.
  • Furthermore, incorporating ultra-thin layers of ethylene vinyl alcohol copolymer ensures exceptional gas resistance, which is vital for high-performance modified atmosphere packaging. Executives prioritize these advanced formulations to guarantee reliable hermetic closure bonding across automated production lines. Ultimately, standardizing these high-clarity, moisture-controlling films reduces localized microbial spoilage and strengthens retail distribution capabilities, making advanced lidding solutions a cornerstone of resilient cold-chain operations.

What are the Key Data Covered in this Anti-Fog Lidding Films Market Research and Growth Report?

  • What is the expected growth of the Anti-Fog Lidding Films Market between 2026 and 2030?

    • USD 250.6 million, at a CAGR of 5.3%

  • What segmentation does the market report cover?

    • The report is segmented by Type (Peelable films, and Sealable films), Material (PE, PP, PET, EVOH, and Others), Application (Trays, Cups and bowls, Jars, and Others) and Geography (APAC, Europe, North America, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • APAC, Europe, North America, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Surging global demand for fresh prepared foods and cold-chain supermarket display visual transparency solutions, Complexity in technical compatibility of mono-material systems across existing high-speed packaging machinery equipment

  • Who are the major players in the Anti-Fog Lidding Films Market?

    • adapa Group, Amcor Plc, Constantia Flexibles GmbH, Cosmo First Ltd., Coveris Management GmbH, Flair Flexible Packaging Corp., FLEXOPACK SA, Jindal Poly Films Ltd., KM Packaging Services Ltd., KP Holding GmbH and Co. KG, Mitsui Chemicals Inc., Mondi Plc, ProAmpac Holdings Inc., Sealed Air Corp., Taghleef Industries SpA, Toray Industries Inc., Toyobo Co. Ltd., UFlex Ltd., Winpak Ltd. and Wipak Group

Market Research Insights

  • The Anti-fog Lidding Films Market operates as a highly technical segment dedicated to optimizing food preservation and retail visibility. By deploying advanced moisture-control films across fresh-cut produce containers and industrial bulk catering applications, processors have reduced in-transit spoilage rates by 18%.
  • Furthermore, the integration of heat-resistant films offering high microwave thermal stability has increased the adoption of premium ready-meal formats by 25% among urban consumers. Upgrading traditional rigid closures to flexible tamper-evident jar seals has also decreased overall packaging material costs by 15% while improving logistics efficiency.
  • As regulatory frameworks increasingly demand circular packaging architectures, manufacturers are aggressively optimizing film structures to ensure seamless compatibility with established post-consumer recycling streams.

We can help! Our analysts can customize this anti-fog lidding films market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Material
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Anti-Fog Lidding Films Market 2020 - 2024

Historic Market Size - Data Table on Global Anti-Fog Lidding Films Market 2020 - 2024 ($ million)

5.2 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.3 Material segment analysis 2020 - 2024

Historic Market Size - Material Segment 2020 - 2024 ($ million)

5.4 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global anti-fog lidding films market

6.2 Impact of geopolitical conflicts on global anti-fog lidding films market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Type

8.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

8.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

8.3 Peelable films - Market size and forecast 2025-2030

Chart on Peelable films - Market size and forecast 2025-2030 ($ million)
Data Table on Peelable films - Market size and forecast 2025-2030 ($ million)
Chart on Peelable films - Year-over-year growth 2025-2030 (%)
Data Table on Peelable films - Year-over-year growth 2025-2030 (%)

8.4 Sealable films - Market size and forecast 2025-2030

Chart on Sealable films - Market size and forecast 2025-2030 ($ million)
Data Table on Sealable films - Market size and forecast 2025-2030 ($ million)
Chart on Sealable films - Year-over-year growth 2025-2030 (%)
Data Table on Sealable films - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

9. Market Segmentation by Material

9.1 Market segments

Chart on Material - Market share 2025-2030 (%)
Data Table on Material - Market share 2025-2030 (%)

9.2 Comparison by Material

Chart on Comparison by Material
Data Table on Comparison by Material

9.3 PE - Market size and forecast 2025-2030

Chart on PE - Market size and forecast 2025-2030 ($ million)
Data Table on PE - Market size and forecast 2025-2030 ($ million)
Chart on PE - Year-over-year growth 2025-2030 (%)
Data Table on PE - Year-over-year growth 2025-2030 (%)

9.4 PP - Market size and forecast 2025-2030

Chart on PP - Market size and forecast 2025-2030 ($ million)
Data Table on PP - Market size and forecast 2025-2030 ($ million)
Chart on PP - Year-over-year growth 2025-2030 (%)
Data Table on PP - Year-over-year growth 2025-2030 (%)

9.5 PET - Market size and forecast 2025-2030

Chart on PET - Market size and forecast 2025-2030 ($ million)
Data Table on PET - Market size and forecast 2025-2030 ($ million)
Chart on PET - Year-over-year growth 2025-2030 (%)
Data Table on PET - Year-over-year growth 2025-2030 (%)

9.6 EVOH - Market size and forecast 2025-2030

Chart on EVOH - Market size and forecast 2025-2030 ($ million)
Data Table on EVOH - Market size and forecast 2025-2030 ($ million)
Chart on EVOH - Year-over-year growth 2025-2030 (%)
Data Table on EVOH - Year-over-year growth 2025-2030 (%)

9.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.8 Market opportunity by Material

Market opportunity by Material ($ million)
Data Table on Market opportunity by Material ($ million)

10. Market Segmentation by Application

10.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

10.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

10.3 Trays - Market size and forecast 2025-2030

Chart on Trays - Market size and forecast 2025-2030 ($ million)
Data Table on Trays - Market size and forecast 2025-2030 ($ million)
Chart on Trays - Year-over-year growth 2025-2030 (%)
Data Table on Trays - Year-over-year growth 2025-2030 (%)

10.4 Cups and bowls - Market size and forecast 2025-2030

Chart on Cups and bowls - Market size and forecast 2025-2030 ($ million)
Data Table on Cups and bowls - Market size and forecast 2025-2030 ($ million)
Chart on Cups and bowls - Year-over-year growth 2025-2030 (%)
Data Table on Cups and bowls - Year-over-year growth 2025-2030 (%)

10.5 Jars - Market size and forecast 2025-2030

Chart on Jars - Market size and forecast 2025-2030 ($ million)
Data Table on Jars - Market size and forecast 2025-2030 ($ million)
Chart on Jars - Year-over-year growth 2025-2030 (%)
Data Table on Jars - Year-over-year growth 2025-2030 (%)

10.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.3.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.5.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.5.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.5.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.5 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Surging global demand for fresh prepared foods and cold-chain supermarket display visual transparency solutions
Widespread industry mandates aimed at eliminating retail spoilage and extending fresh produce food preservation
Rapid expansion of online grocery ecosystems and high-density automated tray sealing packaging operations

13.2 Market challenges

Complexity in technical compatibility of mono-material systems across existing high-speed packaging machinery equipment
Rising cost volatility of specialty anti-fog additives and high-performance polymers in global supply networks
Performance degradation and coating migration under variable environmental conditions across international cold chains

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Accelerating transition toward fully recyclable single-polymer mono-material anti-fog lidding film formulations
Integration of multi-functional anti-fog chemistry with universal peelable sealing layers across multi-substrate trays
Commercial adoption of advanced water-based and bio-derived hydrophilic coatings for sustainable package clarity

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 adapa Group

adapa Group - Overview
adapa Group - Product / Service
adapa Group - Key offerings
SWOT

15.5 Amcor Plc

Amcor Plc - Overview
Amcor Plc - Business segments
Amcor Plc - Key news
Amcor Plc - Key offerings
Amcor Plc - Segment focus
SWOT

15.6 Cosmo First Ltd.

Cosmo First Ltd. - Overview
Cosmo First Ltd. - Product / Service
Cosmo First Ltd. - Key offerings
SWOT

15.7 Coveris Management GmbH

Coveris Management GmbH - Overview
Coveris Management GmbH - Product / Service
Coveris Management GmbH - Key offerings
SWOT

15.8 Flair Flexible Packaging Corp.

Flair Flexible Packaging Corp. - Overview
Flair Flexible Packaging Corp. - Product / Service
Flair Flexible Packaging Corp. - Key offerings
SWOT

15.9 FLEXOPACK SA

FLEXOPACK SA - Overview
FLEXOPACK SA - Product / Service
FLEXOPACK SA - Key offerings
SWOT

15.10 Jindal Poly Films Ltd.

Jindal Poly Films Ltd. - Overview
Jindal Poly Films Ltd. - Business segments
Jindal Poly Films Ltd. - Key offerings
Jindal Poly Films Ltd. - Segment focus
SWOT

15.11 Mitsui Chemicals Inc.

Mitsui Chemicals Inc. - Overview
Mitsui Chemicals Inc. - Business segments
Mitsui Chemicals Inc. - Key offerings
Mitsui Chemicals Inc. - Segment focus
SWOT

15.12 Mondi Plc

Mondi Plc - Overview
Mondi Plc - Business segments
Mondi Plc - Key news
Mondi Plc - Key offerings
Mondi Plc - Segment focus
SWOT

15.13 ProAmpac Holdings Inc.

ProAmpac Holdings Inc. - Overview
ProAmpac Holdings Inc. - Product / Service
ProAmpac Holdings Inc. - Key offerings
SWOT

15.14 Sealed Air Corp.

Sealed Air Corp. - Overview
Sealed Air Corp. - Business segments
Sealed Air Corp. - Key offerings
Sealed Air Corp. - Segment focus
SWOT

15.15 Toray Industries Inc.

Toray Industries Inc. - Overview
Toray Industries Inc. - Business segments
Toray Industries Inc. - Key news
Toray Industries Inc. - Key offerings
Toray Industries Inc. - Segment focus
SWOT

15.16 Toyobo Co. Ltd.

Toyobo Co. Ltd. - Overview
Toyobo Co. Ltd. - Business segments
Toyobo Co. Ltd. - Key news
Toyobo Co. Ltd. - Key offerings
Toyobo Co. Ltd. - Segment focus
SWOT

15.17 UFlex Ltd.

UFlex Ltd. - Overview
UFlex Ltd. - Business segments
UFlex Ltd. - Key offerings
UFlex Ltd. - Segment focus
SWOT

15.18 Winpak Ltd.

Winpak Ltd. - Overview
Winpak Ltd. - Business segments
Winpak Ltd. - Key offerings
Winpak Ltd. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Anti-Fog Lidding Films market growth will increase by USD 250.6 million during 2026-2030.

The Anti-Fog Lidding Films market is expected to grow at a CAGR of 5.3% during 2026-2030.

Anti-Fog Lidding Films market is segmented by Type (Peelable films, Sealable films) Material (PE, PP, PET, EVOH, Others) Application (Trays, Cups and bowls, Jars, Others)

adapa Group, Amcor Plc, Constantia Flexibles GmbH, Cosmo First Ltd., Coveris Management GmbH, Flair Flexible Packaging Corp., FLEXOPACK SA, Jindal Poly Films Ltd., KM Packaging Services Ltd., KP Holding GmbH and Co. KG, Mitsui Chemicals Inc., Mondi Plc, ProAmpac Holdings Inc., Sealed Air Corp., Taghleef Industries SpA, Toray Industries Inc., Toyobo Co. Ltd., UFlex Ltd., Winpak Ltd., Wipak Group are a few of the key vendors in the Anti-Fog Lidding Films market.

APAC will register the highest growth rate of 41.2% among the other regions. Therefore, the Anti-Fog Lidding Films market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, US, Canada, Mexico, Saudi Arabia, UAE, South Africa, Turkey, Israel, Brazil, Argentina, Chile

  • Surging global demand for fresh prepared foods and cold-chain supermarket display visual transparency solutions is the driving factor this market.

The Anti-Fog Lidding Films market vendors should focus on grabbing business opportunities from the Type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
