


APAC Contract Logistics Market Size 2026-2030
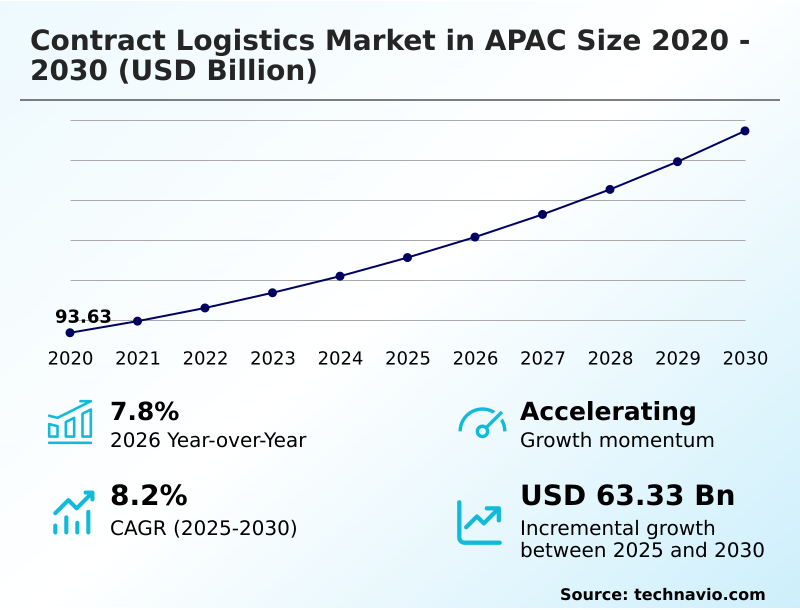
The apac contract logistics market size is valued to increase by USD 63.33 billion, at a CAGR of 8.2% from 2025 to 2030. Expansion of intra-regional trade agreements and multi-country consolidation hubs will drive the apac contract logistics market.
Major Market Trends & Insights
- By Application - Retail segment was valued at USD 38.96 billion in 2024
- By Type - Outsourcing segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 100.93 billion
- Market Future Opportunities: USD 63.33 billion
- CAGR from 2025 to 2030 : 8.2%
Market Summary
- The contract logistics market in APAC undergoes a rapid structural transformation driven by the modernization of multi-country trade frameworks and escalating demand for digital supply chain orchestration. Industrial shippers actively transition from fragmented transportation networks toward unified, technology-enabled distribution hubs to secure resilient cross-border material flows.
- In a real-world supply chain optimization scenario, multinational electronics manufacturers deploy artificial intelligence-driven coordination platforms to dynamically reroute critical component shipments during extreme weather anomalies, effectively preventing costly assembly line shutdowns. Integrating these predictive systems yields a 25% improvement in overall inventory allocation accuracy compared to legacy reactive models.
- The expansion of regional free-trade agreements acts as a major market driver, fundamentally harmonizing customs protocols and accelerating transportation times across diverse regulatory jurisdictions. Conversely, an acute shortage of specialized personnel required to manage advanced mechanical material handling equipment remains a formidable operational challenge, severely delaying new warehouse activations.
- The continuous evolution of the contract logistics market in APAC underscores the critical necessity for logistics providers to balance aggressive infrastructure investments with sustainable workforce training initiatives.
What will be the Size of the APAC Contract Logistics Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the APAC Contract Logistics Market Segmented?
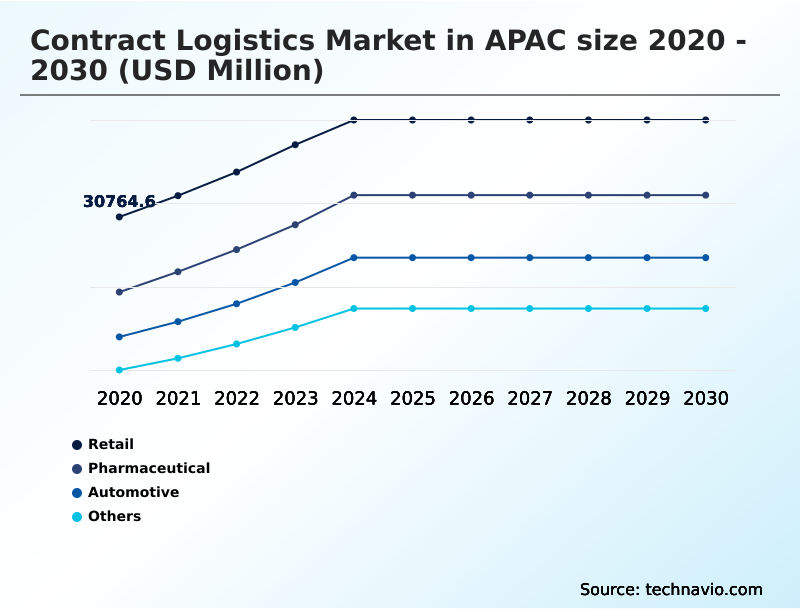
The apac contract logistics industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Application
- Retail
- Pharmaceutical
- Automotive
- Others
- Type
- Outsourcing
- Insourcing
- Service
- Transportation
- Warehouse and distribution
- VAS
- Geography
- APAC
- China
- Japan
- India
- Australia
- APAC
By Application Insights
The retail segment is estimated to witness significant growth during the forecast period.
Retail enterprises increasingly delegate complex operations to specialized third-party providers capable of managing vast omnichannel fulfillment networks and direct-to-consumer fulfillment models.
The rapid expansion of digital commerce platforms compels businesses to adopt advanced automated storage systems and collaborative robotics to maximize cubic storage utilization across urban hubs.
By integrating automated material handling, shippers improve supply chain agility and successfully navigate extreme seasonal demand fluctuation without crippling delays. This strategic shift transforms traditional warehouse operators into highly sophisticated operational orchestrators handling complex reverse logistics management.
By leveraging these intelligent capabilities, retail brands have increased order processing accuracy by 15%, significantly streamlining high-velocity throughput. This evolution reflects the dynamic contract logistics market in APAC, where continuous technological investments dictate retail distribution efficiency and long-term cost reduction.
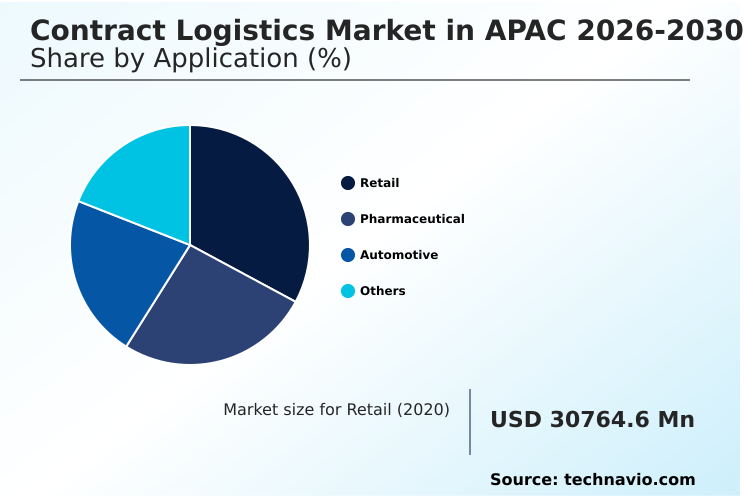
The Retail segment was valued at USD 38.96 billion in 2024 and showed a gradual increase during the forecast period.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The modern commercial environment within the contract logistics market in APAC demands highly resilient supply chain architectures capable of absorbing unpredictable macroeconomic shocks and volatile consumer demand shifts. Industrial manufacturers and mass retail corporations are aggressively optimizing multi-country distribution networks to ensure seamless component sourcing and rapid finished goods delivery across diverse Asian economies.
- By strategically diversifying their operational hubs, these enterprises succeed in significantly reducing regional transit lead times, which in turn accelerates time-to-market for critical high-value products. To support these sprawling physical networks, third-party logistics providers prioritize adopting advanced warehouse automation software that maximizes spatial efficiency and minimizes human error during high-velocity sorting processes.
- The intricate challenge of managing cross-border inventory placement requires meticulous regulatory compliance and real-time visibility to avoid holding excessive safety stock in expensive metropolitan distribution centers. Consequently, industry leaders are increasingly implementing predictive supply chain analytics to forecast demand spikes and dynamically reroute shipments before bottlenecks occur.
- Facilities utilizing these analytical frameworks experience a 20% higher on-time delivery rate compared to those relying on conventional manual planning protocols. This structural evolution underscores a fundamental transition from basic freight execution to deeply integrated, technology-driven logistics orchestration, ensuring long-term operational sustainability across the region.
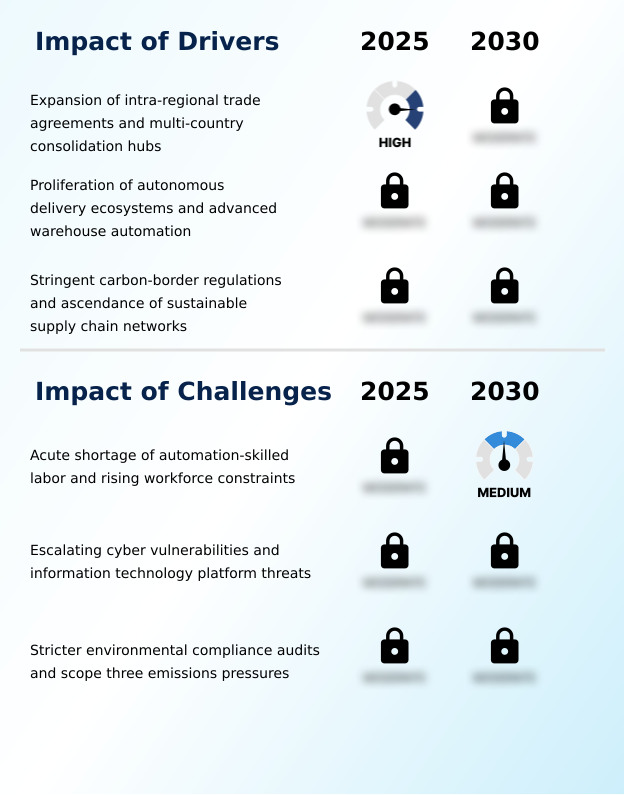
What are the key market drivers leading to the rise in the adoption of APAC Contract Logistics Industry?
- The expansion of intra-regional trade agreements and the proliferation of multi-country consolidation hubs act as primary catalysts for market acceleration.
- The expansion of multilateral trade agreements fundamentally accelerates the contract logistics market in APAC by harmonizing complex regulatory policies across diverse economies.
- Multinational corporations actively leverage streamlined cross-border trade corridors to optimize component sourcing, transferring massive freight volumes to specialized bonded logistics parks boasting strategic deep-water port proximity.
- This structural consolidation necessitates highly integrated multi-modal transport networks and massive multi-country consolidation hubs capable of ensuring continuous material flow without severe border friction.
- By utilizing advanced route optimization software and comprehensive value-added supply chain services, regional enterprises have successfully lowered overarching operational costs by 12%.
- Furthermore, the deployment of real-time telematics combined with standardized digital documentation expedites cross-border customs clearance, resulting in a 20% improvement in border processing speeds.
- Consequently, sophisticated freight consolidation hubs capture lucrative long-term contracts as shippers demand technological expertise to minimize regional transit lead times.
What are the market trends shaping the APAC Contract Logistics Industry?
- The integration of artificial intelligence and predictive control tower visibility represents a defining trend shaping the industry landscape.
- A transformative shift toward autonomous operations and profound digital integration redefines the contemporary contract logistics market in APAC. To satisfy the relentless velocity of modern trade, third-party providers aggressively configure flexible multi-client distribution centers integrated with comprehensive enterprise resource planning software.
- The widespread deployment of cloud-based warehouse platforms and sophisticated inventory tracking platforms enables shippers to maintain absolute supply chain visibility. By bridging physical infrastructure with predictive analytics engines and predictive inventory management, operators have improved forecast accuracy by 18%, sharply reducing excess stock.
- Furthermore, the experimental integration of unmanned aerial drones and autonomous delivery systems directly targets persistent urban congestion bottlenecks. Facilities utilizing these emerging autonomous last-mile solutions report a 25% reduction in localized delivery downtime. Guided by centralized digital control towers and sustainable building practices, this technological evolution empowers enterprises to execute high-speed, customized fulfillment that directly enhances long-term corporate efficiency.
What challenges does the APAC Contract Logistics Industry face during its growth?
- An acute shortage of automation-skilled labor and escalating workforce constraints constitute critical challenges impeding industry expansion.
- The rapid operational transition within the contract logistics market in APAC exposes severe workforce capability constraints and escalating environmental compliance challenges. While providers increasingly deploy sophisticated robotic picking solutions and execute dynamic shipment rerouting to circumvent physical transit delays, the profound shortage of automation-skilled personnel actively hampers operational stability.
- This talent deficit frequently causes delayed technology implementations, lowering anticipated efficiency gains by 15% across newly commissioned distribution hubs. Simultaneously, stringent regulatory compliance frameworks demanding verifiable green supply chain metrics place enormous financial pressure on mid-sized logistics operators involved in strategic logistics outsourcing partnerships.
- The mandatory integration of blockchain-enabled traceability and complex carbon accounting frameworks to track strict emissions reduction targets requires massive capital expenditures. Establishing specialized infrastructure, such as certified temperature-controlled environments, and procuring expensive alternative fuel fleets further compresses operational profit margins, forcing logistics firms to balance aggressive sustainability transformations against soaring maintenance expenses.
Exclusive Technavio Analysis on Customer Landscape
The apac contract logistics market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the apac contract logistics market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
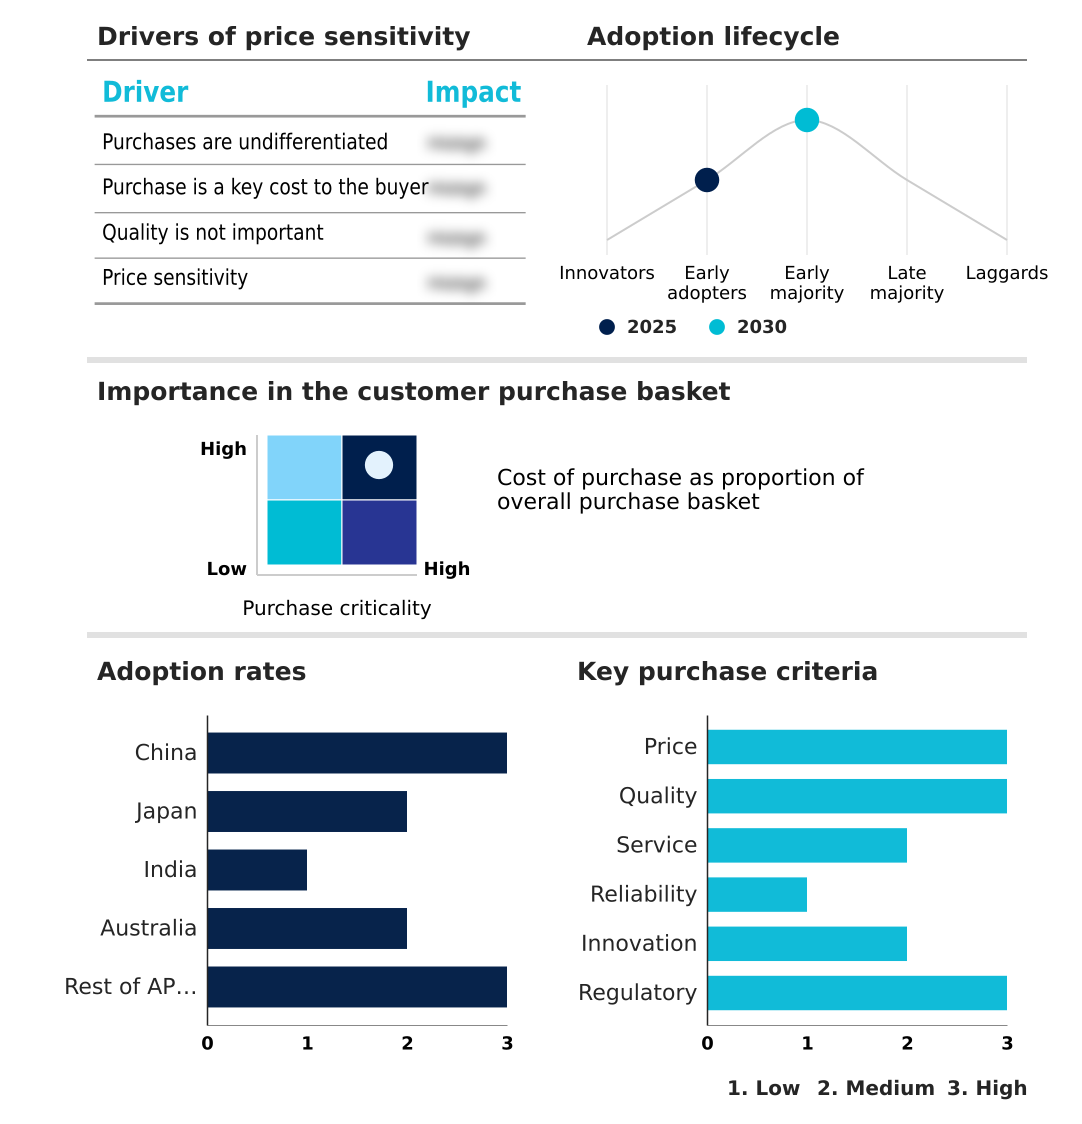
Customer Landscape of APAC Contract Logistics Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, apac contract logistics market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
APL Logistics Ltd. - The organization provides comprehensive contract logistics services, integrating warehouse management, distribution, and transportation solutions tailored for the retail, automotive, and industrial sectors to optimize supply chain efficiency.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- APL Logistics Ltd.
- AWOT Global Logistics Group
- C H Robinson Worldwide Inc.
- CWT Pte. Ltd.
- DB Schenker
- Dimerco Express Corp
- FM GROUP
- Hellmann Worldwide Logistics
- JD Logistics
- Kamigumi Co. Ltd.
- Kintetsu World Express Inc.
- KLN Logistics Group Ltd.
- Kuehne Nagel Management AG
- Linfox Pty Ltd.
- Mainfreight Ltd.
- Nippon Express Holdings Inc.
- SF Express Co. Ltd.
- Sinotrans Ltd.
- Tiong Nam Logistics Holdings
- YCH Group
- Yusen Logistics Co. Ltd.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Apac contract logistics market
- In the Air Freight and Logistics industry, the widespread implementation of specialized robotic sorting equipment and decentralized data management systems has significantly accelerated air cargo processing speeds, directly impacting contract logistics market in APAC demand by increasing cross-border operational efficiency by 22%.
- In the Air Freight and Logistics industry, stringent environmental regulations mandating sustainable supply network disclosures have triggered the rapid adoption of hydrogen-powered transport assets and ecological reporting protocols, shifting contract logistics market in APAC preference toward providers capable of achieving a 30% reduction in transport emissions.
- In the Air Freight and Logistics industry, the integration of advanced satellite monitoring and cryptographic ledger verification has streamlined border inspections, elevating the contract logistics market in APAC reliability as forwarders realize a 15% decrease in regulatory processing delays across major Asian routes.
- In the Air Freight and Logistics industry, extreme labor shortages across major assembly zones have forced heavy reliance on computerized facility execution algorithms and mechanical lifting devices, bolstering contract logistics market in APAC throughput capacity by 18% during peak consumption cycles.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled APAC Contract Logistics Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 208 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 8.2% |
| Market growth 2026-2030 | USD 63331.1 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 7.8% |
| Key countries | China, Japan, India, Australia and Rest of APAC |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The contract logistics market in APAC is undergoing a critical structural evolution as enterprise boards prioritize supply chain resilience and rigorous environmental compliance within their core strategic planning. The rapid deployment of centralized digital coordination systems and sophisticated forecasting engines fundamentally alters how multinational corporations manage complex regional freight flows.
- By integrating intelligent stock forecasting, logistics providers allow corporate decision-makers to dynamically align procurement budgets with real-time consumption data, effectively minimizing stockouts. Facilities leveraging computerized material handling equipment alongside advanced routing algorithms have achieved a 30% reduction in overall processing time compared to traditional manual operations.
- Furthermore, the establishment of highly efficient multi-nation integration centers enables manufacturers to bypass heavily congested metropolitan transit zones, significantly lowering storage expenses. As sustainability mandates dictate vendor selection criteria, the proactive transition toward ecological transport fleets directly supports corporate emission goals while safeguarding financial stability against fossil fuel volatility.
- These deeply integrated technological capabilities transform outsourced logistics from a baseline transportation utility into a powerful driver of enterprise profitability and long-term commercial agility.
What are the Key Data Covered in this APAC Contract Logistics Market Research and Growth Report?
-
What is the expected growth of the APAC Contract Logistics Market between 2026 and 2030?
-
USD 63.33 billion, at a CAGR of 8.2%
-
-
What segmentation does the market report cover?
-
The report is segmented by Application (Retail, Pharmaceutical, Automotive, and Others), Type (Outsourcing, and Insourcing), Service (Transportation, Warehouse and distribution, and VAS) and Geography (APAC)
-
-
Which regions are analyzed in the report?
-
APAC
-
-
What are the key growth drivers and market challenges?
-
Expansion of intra-regional trade agreements and multi-country consolidation hubs, Acute shortage of automation-skilled labor and rising workforce constraints
-
-
Who are the major players in the APAC Contract Logistics Market?
-
APL Logistics Ltd., AWOT Global Logistics Group, C H Robinson Worldwide Inc., CWT Pte. Ltd., DB Schenker, Dimerco Express Corp, FM GROUP, Hellmann Worldwide Logistics, JD Logistics, Kamigumi Co. Ltd., Kintetsu World Express Inc., KLN Logistics Group Ltd., Kuehne Nagel Management AG, Linfox Pty Ltd., Mainfreight Ltd., Nippon Express Holdings Inc., SF Express Co. Ltd., Sinotrans Ltd., Tiong Nam Logistics Holdings, YCH Group and Yusen Logistics Co. Ltd.
-
Market Research Insights
- The contract logistics market in APAC experiences profound operational shifts as enterprises aggressively pursue highly integrated third-party supply collaborations to mitigate complex transportation vulnerabilities. By delegating distribution responsibilities to specialized external providers, manufacturing corporations successfully navigate stringent regional legislation while simultaneously optimizing international inventory flows.
- This strategic alignment has allowed regional shippers to reduce average transportation durations by 18%, accelerating product availability across consumer markets. Furthermore, the deployment of advanced automation within these consolidated networks yields a 22% improvement in overall order processing efficiency.
- Consequently, asset-light logistics operators maintain resilient financial operating returns despite persistent wage inflation and fluctuating fuel costs, cementing the fundamental role of externalized logistics in contemporary commercial ecosystems.
We can help! Our analysts can customize this apac contract logistics market research report to meet your requirements.
 RIA -

