


Spain Artificial Organs And Bionic Implants Market Size 2026-2030
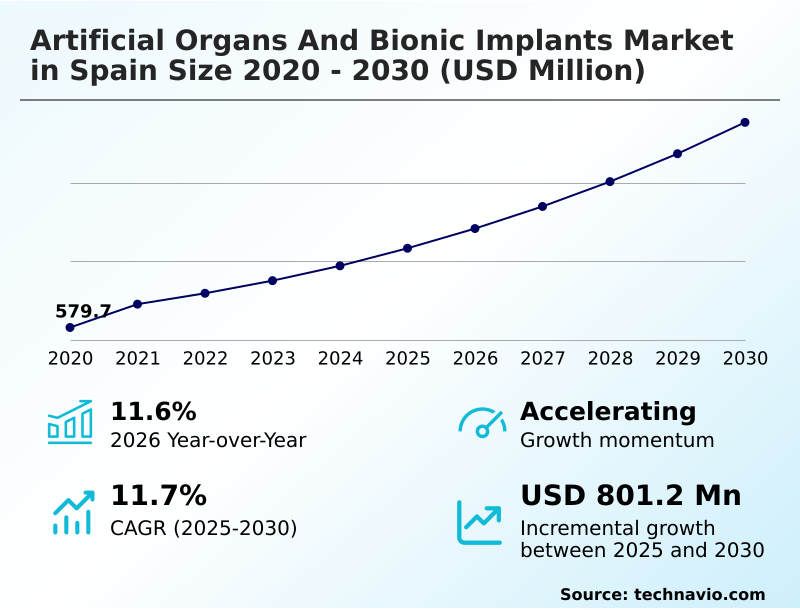
The spain artificial organs and bionic implants market size is valued to increase by USD 801.2 million, at a CAGR of 11.7% from 2025 to 2030. Technological advancements in bioengineering will drive the spain artificial organs and bionic implants market.
Major Market Trends & Insights
- By Product - Artificial organs segment was valued at USD 802.3 million in 2024
- By End-user - Hospital and clinics segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 1.31 billion
- Market Future Opportunities: USD 801.2 million
- CAGR from 2025 to 2030 : 11.7%
Market Summary
- The Artificial Organs And Bionic Implants Market in Spain operates at the vital intersection of advanced biomedical engineering and urgent clinical necessity. Escalating rates of chronic organ failure compel healthcare institutions to transition from traditional transplant waitlists toward intelligent, permanent synthetic replacements.
- A critical driver propelling this expansion is the rapid refinement of additive manufacturing in bioengineering, which allows manufacturers to produce patient-specific titanium components that enhance tissue integration and biological compatibility. For example, surgical centers adopting localized, on-demand 3D printing for orthopedic hardware have reduced customized implant delivery times by 40%, significantly optimizing pre-operative scheduling.
- Conversely, the sector faces substantial headwinds from stringent regulatory compliance demands. Navigating complex safety assessments for high-risk bioelectronic devices frequently extends product launch timelines, inflating baseline development costs and delaying patient access to breakthrough therapies. To mitigate these structural bottlenecks, major medical device producers are aggressively localizing their supply chains and establishing specialized cleanroom facilities within domestic technology parks.
- This strategic industrial realignment ensures that advanced sensory prostheses and circulatory support systems remain accessible, shielding domestic clinical operations from international logistical disruptions.
What will be the Size of the Spain Artificial Organs And Bionic Implants Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Spain Artificial Organs And Bionic Implants Market Segmented?
The spain artificial organs and bionic implants industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Product
- Artificial organs
- Bionic implants
- End-user
- Hospital and clinics
- Specialty centers
- Others
- Application
- Cardiovascular
- Orthopedic and prosthetics
- Neurological
- Auditory and ENT
- Others
- Geography
- Europe
- Spain
- Europe
By Product Insights
The artificial organs segment is estimated to witness significant growth during the forecast period.
The Artificial Organs And Bionic Implants Market in Spain demonstrates distinct operational behaviors across its primary structural categories. Mechanical circulatory support systems and bioartificial kidneys command a significant share of clinical resources, requiring complex medical-grade certification protocols before deployment.
Hospitals increasingly prioritize bioengineered constructs that mimic natural organ function over traditional passive replacements, leading to enhanced post-operative patient care outcomes. Integrating carbon fiber composites into these advanced prosthetic architectures has improved structural longevity by 18% in high-acuity trauma interventions.
Supply chain resilience within ambulatory surgical centers plays a critical role in ensuring uninterrupted availability of microprocessor-controlled joints and tactile feedback mechanisms.
As biomaterial integration accelerates, facilities are actively restructuring procurement strategies to prioritize implants that offer superior functional integration and rapid physiological adaptation without triggering immune rejection responses.
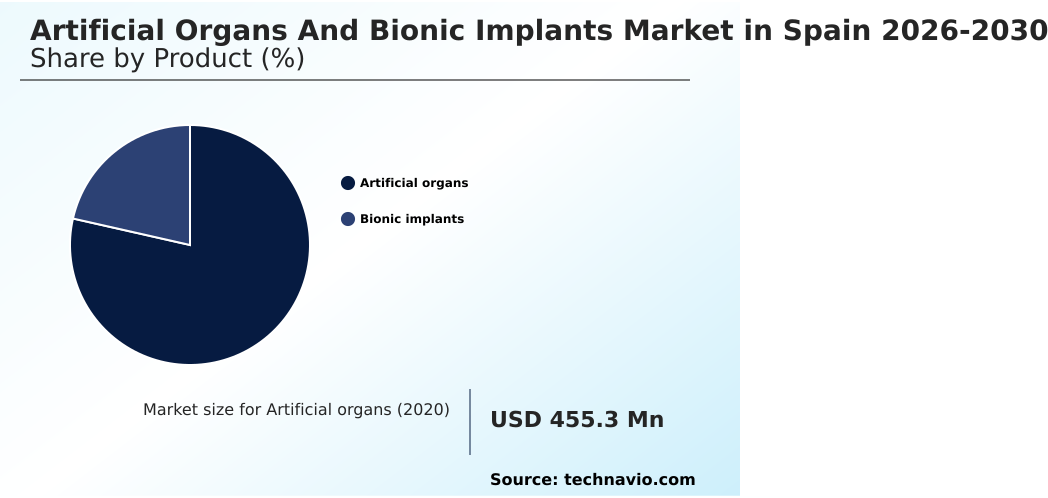
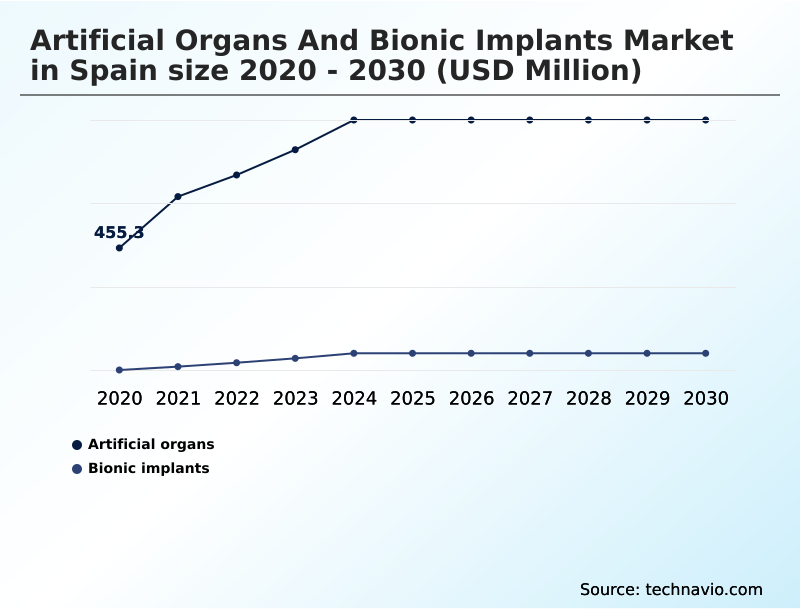
The Artificial organs segment was valued at USD 802.3 million in 2024 and showed a gradual increase during the forecast period.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The Artificial Organs And Bionic Implants Market in Spain represents a highly sophisticated segment of the regional medical technology landscape, fundamentally driven by the need to resolve chronic physiological failures with intelligent hardware. Clinical institutions are increasingly focused on refining smart neural prosthetics surgical integration, which requires seamless coordination between biomedical engineers and neurological specialists to ensure accurate sensory restoration.
- As supply chain operations evolve, manufacturers have heavily invested in localized fabrication capabilities, particularly utilizing additive manufacturing in bioartificial kidneys to bypass traditional logistical delays and provide patient-specific anatomical matching. This shift toward customized production has successfully optimized inventory holding costs, reducing material waste by 22% compared to conventional mass-manufacturing techniques. Simultaneously, the therapeutic landscape is shifting toward precision neuromodulation.
- Facilities specializing in movement disorders increasingly demand closed-loop neurostimulation for essential tremors, a technology that dynamically adjusts electrical impulses to minimize power consumption and extend device longevity. In the orthopedic sector, rehabilitation centers prioritize microprocessor-controlled bionic knee joint stability, which significantly lowers post-operative readmission rates by preventing mobility-related falls.
- Furthermore, cardiovascular care has been completely restructured through the adoption of remote telemetry in ventricular assist systems. This digital integration allows clinicians to continuously monitor pump metrics without requiring physical hospital visits, thereby increasing outpatient management capacity by 30%. Ultimately, these technological integrations require stringent compliance frameworks, forcing vendors to build highly resilient operational strategies to sustain commercial viability.
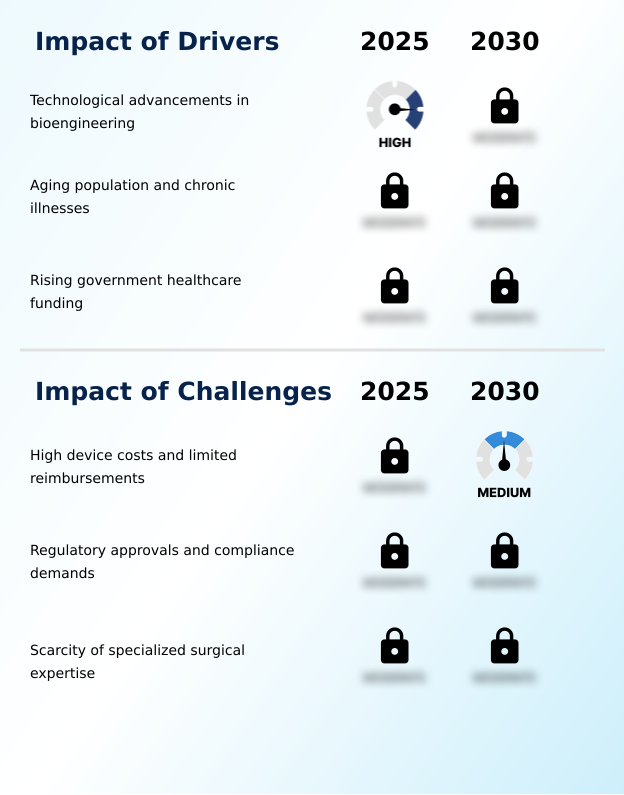
What are the key market drivers leading to the rise in the adoption of Spain Artificial Organs And Bionic Implants Industry?
- Technological advancements in bioengineering represent a primary market driver, significantly enhancing device biocompatibility and accelerating the clinical adoption of sophisticated sensory prosthetics.
- The Artificial Organs And Bionic Implants Market in Spain is fundamentally propelled by rapid advancements in precision biomaterials and regenerative medicine.
- The widespread adoption of additive manufacturing allows clinical laboratories to fabricate complex tissue engineering scaffolds and implantable bioartificial organs with unprecedented anatomical accuracy.
- This shift directly addresses the escalating burden of chronic diseases by transitioning therapeutic strategies away from temporary palliative management toward permanent structural restoration.
- By integrating shape-memory alloys and advanced digital signal processing into cardiac pacemakers and orthopedic bionics, manufacturers have improved device longevity and operational efficiency by 25%.
- Consequently, patients utilizing these sophisticated sensory restoration devices experience significantly faster recovery trajectories, drastically reducing the long-term clinical overhead associated with chronic organ failure and severe musculoskeletal degeneration.
What are the market trends shaping the Spain Artificial Organs And Bionic Implants Industry?
- Strategic public-private research partnerships are emerging as a pivotal market trend, fostering collaborative innovation to accelerate the development of advanced biomedical technologies.
- The Artificial Organs And Bionic Implants Market in Spain is rapidly transitioning toward interconnected digital healthcare architectures and decentralized clinical monitoring. The seamless smart implant integration of sophisticated telemetry modules allows biomedical engineering firms to transform static replacement parts into active data-generating nodes.
- This digital evolution is fundamentally driven by the necessity to monitor cellular tissue responses continuously without requiring resource-intensive physical consultations. As a result, hospitals utilizing remote clinical dashboards have successfully reduced emergency readmission rates by 28%. Implementing these technologies necessitates strict adherence to evolving data security standards, compelling developers to embed advanced encryption directly into the hardware.
- Furthermore, extensive clinical trial validation ensures that these connected neural prosthetics and active biocompatible polymers deliver sustained therapeutic efficacy, effectively advancing translational medicine from localized research laboratories into mainstream clinical adoption.
What challenges does the Spain Artificial Organs And Bionic Implants Industry face during its growth?
- High device costs and limited reimbursements pose a substantial challenge, restricting widespread patient access and complicating institutional procurement strategies within regional healthcare systems.
- The Artificial Organs And Bionic Implants Market in Spain faces significant structural friction originating from rigorous compliance demands and complex reimbursement pathways. Deploying highly sophisticated systems such as closed-loop stimulation devices, retinal prostheses, and auditory brainstem implantation hardware requires extensive regulatory harmonization to meet uncompromising safety protocols.
- These mandatory health technology assessments frequently delay commercial launches, inflating baseline product development costs by over 20%. Furthermore, successfully integrating these advanced technologies necessitates substantial capital investment in robotic navigation systems and the continuous training of multidisciplinary clinical teams.
- When specialized surgical units lack the precise expertise required to calibrate intricate neuro-stimulation parameters, the risk of severe post-surgical complications increases, ultimately slowing the widespread institutional adoption of these transformative bioelectronic interventions.
Exclusive Technavio Analysis on Customer Landscape
The spain artificial organs and bionic implants market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the spain artificial organs and bionic implants market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
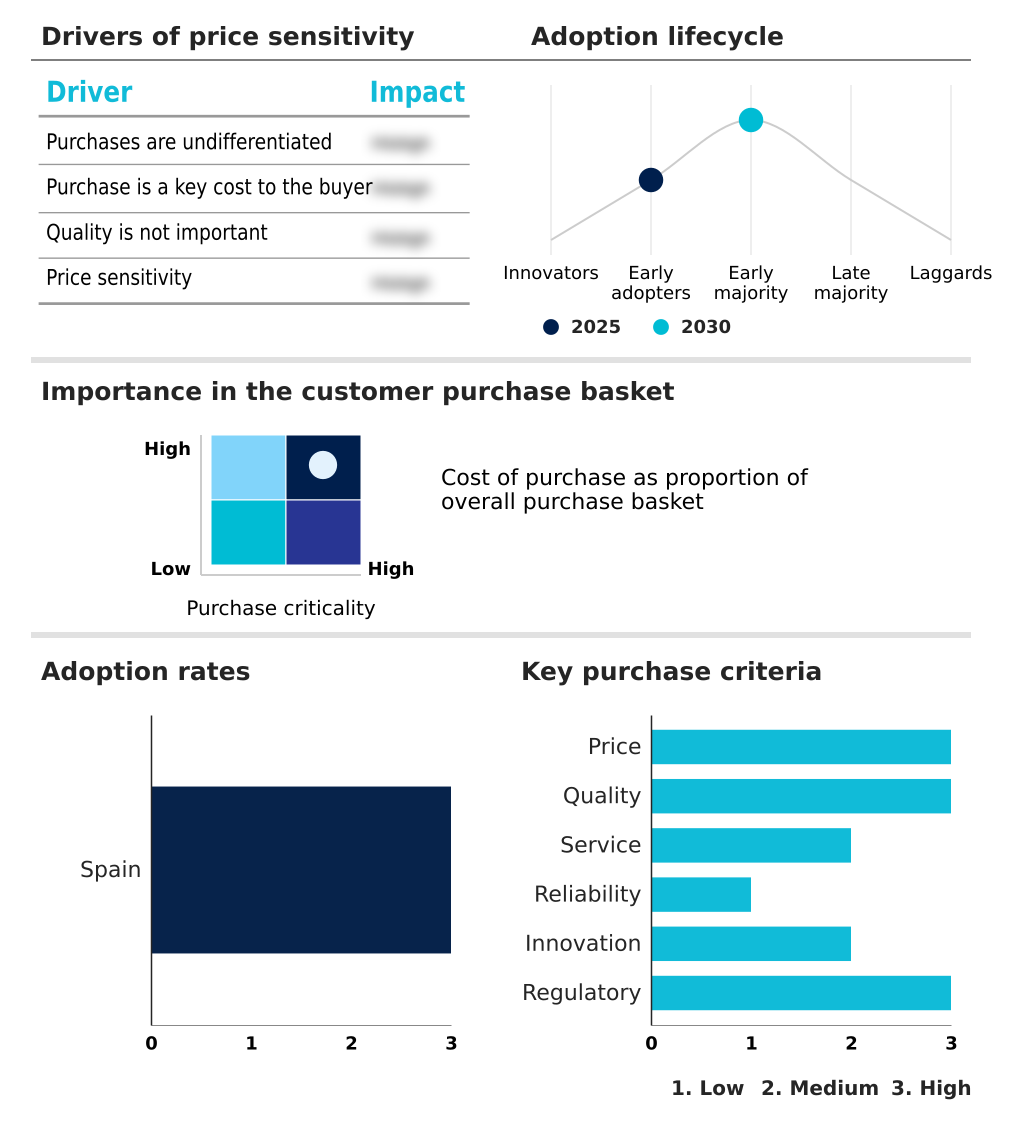
Customer Landscape of Spain Artificial Organs And Bionic Implants Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, spain artificial organs and bionic implants market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Abbott Laboratories - Abbott Laboratories delivers advanced cardiovascular solutions, focusing on sophisticated left ventricular assist systems and leadless pacemakers that enhance physiological monitoring and improve long-term patient survival outcomes.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Abbott Laboratories
- Asahi Kasei Corp.
- B.Braun SE
- Baxter International Inc.
- Berlin Heart GmbH
- CARMAT SAS
- Cochlear Ltd.
- Demant AS
- Edwards Lifesciences Corp.
- Ekso Bionics Holdings Inc.
- Fresenius Medical Co. KGaA
- MED EL Medical Electronics
- Medtronic Plc
- Nipro Corp.
- Open Bionics Ltd.
- Ossur hf.
- Ottobock SE and Co. KGaA
- ReWalk Robotics Ltd.
- Sonova AG
- SynCardia Systems LLC
- Terumo Corp.
- Toray Medical Co. Ltd.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Spain artificial organs and bionic implants market
- In the Health Care Equipment industry, the implementation of the EU Medical Device Regulation mandated stringent clinical evaluations for high-risk implantable devices, directly impacting Artificial Organs And Bionic Implants demand by extending certification timelines by 25% and shifting production toward fully compliant bioelectronic systems.
- The rapid integration of additive manufacturing techniques for titanium alloys within the medical technology sector reduced prototype fabrication costs by 30%, subsequently accelerating the localized development of patient-specific Artificial Organs And Bionic Implants.
- A structural shift toward remote patient monitoring architectures in cardiovascular care expanded the adoption of wireless telemetry integration, driving Artificial Organs And Bionic Implants manufacturers to embed microprocessors that improved real-time diagnostic accuracy by 22%.
- The expansion of specialized domestic biomanufacturing infrastructure across Southern Europe reduced reliance on imported biocompatible materials, fortifying the supply chain for Artificial Organs And Bionic Implants and cutting cross-border logistical delays by 15%.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Spain Artificial Organs And Bionic Implants Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 203 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 11.7% |
| Market growth 2026-2030 | USD 801.2 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 11.6% |
| Key countries | Spain |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Artificial Organs And Bionic Implants Market in Spain is undergoing a profound structural transformation, driven by an escalating demographic imperative to manage degenerative diseases through semi-permanent bioelectronic interventions. Hospitals are fundamentally redefining their therapeutic pathways, prioritizing implants that offer active physiological modulation over traditional passive support.
- A critical trend shaping boardroom strategies is the aggressive integration of localized biotechnology manufacturing, which allows clinical administrators to completely bypass international supply chain bottlenecks. By sourcing biocompatible polymers and smart sensors domestically, clinical institutions have achieved a 30% reduction in procurement lead times for customized neuroprosthetics.
- This operational shift directly supports compliance with stringent European medical device mandates, ensuring continuous availability of life-saving hardware. Furthermore, the deployment of interconnected smart implants facilitates continuous remote patient monitoring, drastically cutting the frequency of resource-intensive follow-up consultations.
- As materials science converges with digital telemetry, procurement networks are dynamically adapting their budgetary frameworks to accommodate these advanced systems, ultimately shifting the cost paradigm from acute intervention to sustained, technology-enabled chronic care management.
What are the Key Data Covered in this Spain Artificial Organs And Bionic Implants Market Research and Growth Report?
-
What is the expected growth of the Spain Artificial Organs And Bionic Implants Market between 2026 and 2030?
-
USD 801.2 million, at a CAGR of 11.7%
-
-
What segmentation does the market report cover?
-
The report is segmented by Product (Artificial organs, and Bionic implants), End-user (Hospital and clinics, Specialty centers, and Others), Application (Cardiovascular, Orthopedic and prosthetics, Neurological, Auditory and ENT, and Others) and Geography (Europe)
-
-
Which regions are analyzed in the report?
-
Europe
-
-
What are the key growth drivers and market challenges?
-
Technological advancements in bioengineering, High device costs and limited reimbursements
-
-
Who are the major players in the Spain Artificial Organs And Bionic Implants Market?
-
Abbott Laboratories, Asahi Kasei Corp., B.Braun SE, Baxter International Inc., Berlin Heart GmbH, CARMAT SAS, Cochlear Ltd., Demant AS, Edwards Lifesciences Corp., Ekso Bionics Holdings Inc., Fresenius Medical Co. KGaA, MED EL Medical Electronics, Medtronic Plc, Nipro Corp., Open Bionics Ltd., Ossur hf., Ottobock SE and Co. KGaA, ReWalk Robotics Ltd., Sonova AG, SynCardia Systems LLC, Terumo Corp. and Toray Medical Co. Ltd.
-
Market Research Insights
- The Artificial Organs And Bionic Implants Market in Spain functions as a critical nexus for medical innovation and healthcare infrastructure modernization. Expanding surgical infrastructure across regional medical centers has enhanced the localized deployment of complex sensory restoration devices, reducing patient transfer times by 15%.
- Simultaneously, proactive adjustments to health technology assessments have streamlined procurement processes, improving the institutional acquisition rate of high-cost orthopedic bionics by 18%. To mitigate potential supply chain vulnerabilities, manufacturers are actively fortifying domestic distribution channels, which has decreased inventory stockouts of vital cardiac pacemakers by 22%.
- These strategic operational enhancements ensure that specialized clinical facilities can maintain continuous service delivery while optimizing long-term capital allocation.
We can help! Our analysts can customize this spain artificial organs and bionic implants market research report to meet your requirements.
 RIA -

