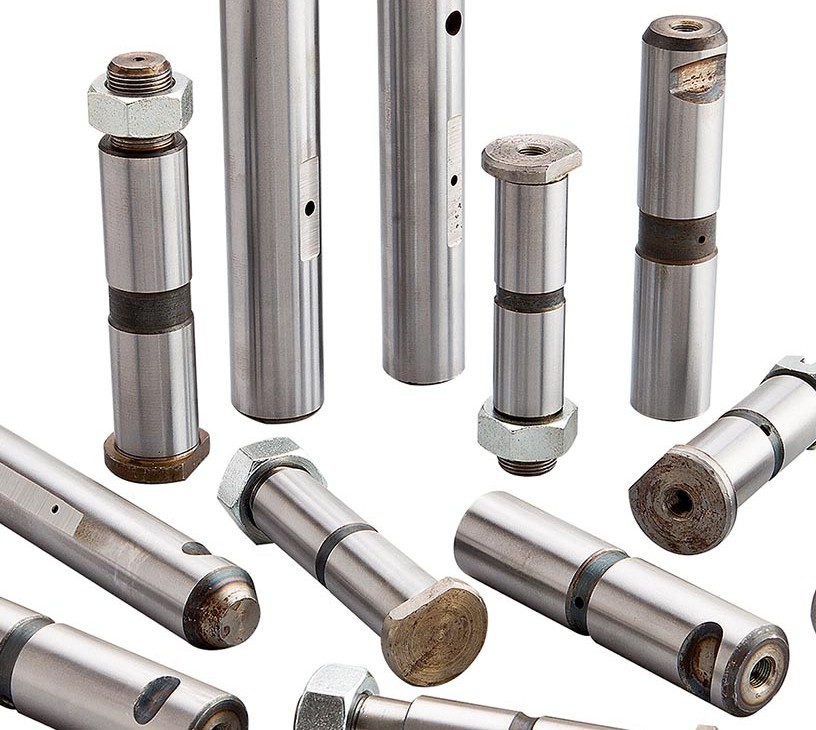
Automotive Fasteners Market Analysis, Size, and Forecast 2026-2030: APAC (China, Japan, and India), North America (US, Canada, and Mexico), Europe (Germany, France, and UK), South America (Brazil, Argentina, and Chile), Middle East and Africa (Turkey, South Africa, and Saudi Arabia), and Rest of World (ROW)

Automotive Fasteners Market Analysis, Size, and Forecast 2026-2030:
APAC (China, Japan, and India), North America (US, Canada, and Mexico), Europe (Germany, France, and UK), South America (Brazil, Argentina, and Chile), Middle East and Africa (Turkey, South Africa, and Saudi Arabia), and Rest of World (ROW)

Published: Oct 2026 329 Pages SKU: IRTNTR44977

Market Overview at a Glance

$10.86 B
Market Opportunity
8.4%
CAGR 2025 - 2030
56.9%
APAC Growth
$15.68 B
OEM segment 2024

Automotive Fasteners Market Size 2026-2030

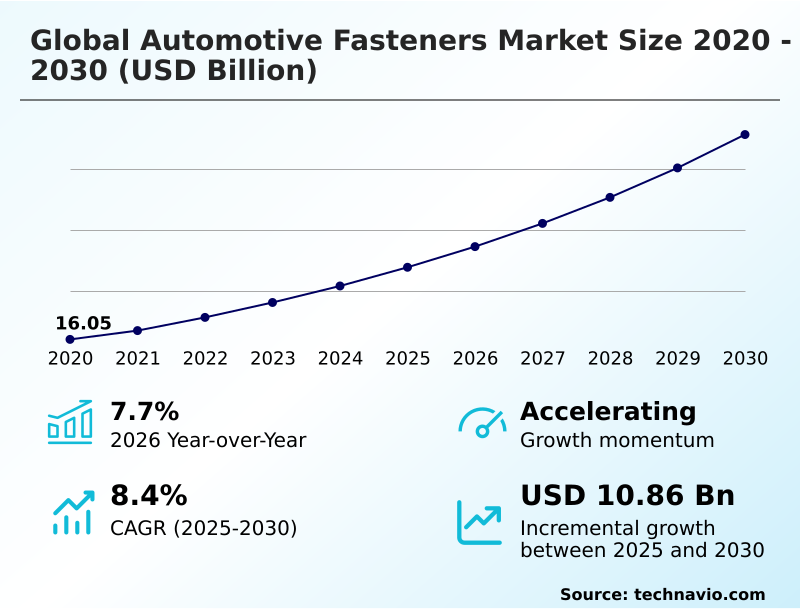
The automotive fasteners market size is valued to increase by USD 10.86 billion, at a CAGR of 8.4% from 2025 to 2030. Engineering requirements for vehicle lightweighting and multi-material joining will drive the automotive fasteners market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 56.9% growth during the forecast period.
  • By End-user - OEM segment was valued at USD 15.68 billion in 2024
  • By Vehicle Type - Passenger cars segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 16.76 billion
  • Market Future Opportunities: USD 10.86 billion
  • CAGR from 2025 to 2030 : 8.4%

Market Summary

  • The Automotive Fasteners Market is undergoing a rapid structural transformation driven by the comprehensive redesign of modern vehicle architectures. As automakers pivot toward multi-material chassis constructions, the demand for highly engineered, specialized joining solutions has intensified.
  • A prominent business scenario involves major assembly plants upgrading their procurement strategies to include ultra-high-strength aluminum rivets and insulated battery mounts, shifting away from standard heavy steel bolts. This operational pivot has allowed leading manufacturers to reduce overall vehicle curb weight, improving energy efficiency by an estimated 12% across new passenger fleets.
  • The market is propelled by stringent lightweighting mandates that force the integration of diverse substrates without compromising crashworthiness. Conversely, severe margin compression caused by volatile raw material pricing and high industrial energy costs acts as a major challenge, limiting the profit margins of component forging facilities.
  • Advanced optical sorting systems and automated quality control loops have become essential to meet strict zero-defect mandates. Consequently, specialized mechanical joining technologies are entirely replacing conventional commodity hardware within automated production environments.

What will be the Size of the Automotive Fasteners Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Automotive Fasteners Market Segmented?

The automotive fasteners industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • End-user
    • OEM
    • Aftermarket
  • Vehicle type
    • Passenger cars
    • Commercial vehicles
  • Material
    • Stainless steel
    • Plastic
    • Aluminum
  • Type
    • Threaded
    • Non-threaded
  • Application
    • Engine
    • Chassis
    • Interior trim
    • Front
    • Others
  • Geography
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Indonesia
      • Australia
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • France
      • UK
      • Spain
      • Italy
      • The Netherlands
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Turkey
      • South Africa
      • Saudi Arabia
      • UAE
      • Israel

By End-user Insights

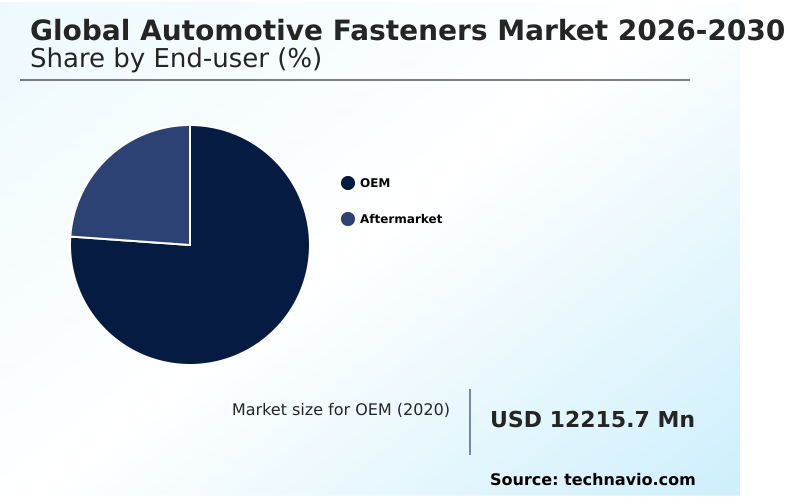
The oem segment is estimated to witness significant growth during the forecast period.

The OEM channel within the Automotive Fasteners landscape operates as the primary procurement engine, demanding precise engineering to support modern vehicle assembly.

As manufacturers shift toward electrified platforms, the requirement for components featuring high-frequency vibration resistance and non-magnetic insulated fasteners has intensified to ensure electric drive unit protection. Original equipment buyers mandate strict dimensional tolerance validation, directly impacting production efficiency.

Implementing advanced quality protocols has improved automated assembly error detection by 15%, reducing structural failure rates in safety-critical applications. Thread-forming fasteners and components featuring multi-layered electroplating are increasingly sourced to secure structural chassis linkages while preventing metallurgical degradation.

Predictive maintenance software integrated into the procurement and testing phase ensures that massive volumes of mechanical joints meet exact safety standards, sustaining continuous, high-volume automotive manufacturing operations without localized disruptions.
Get Free Sample

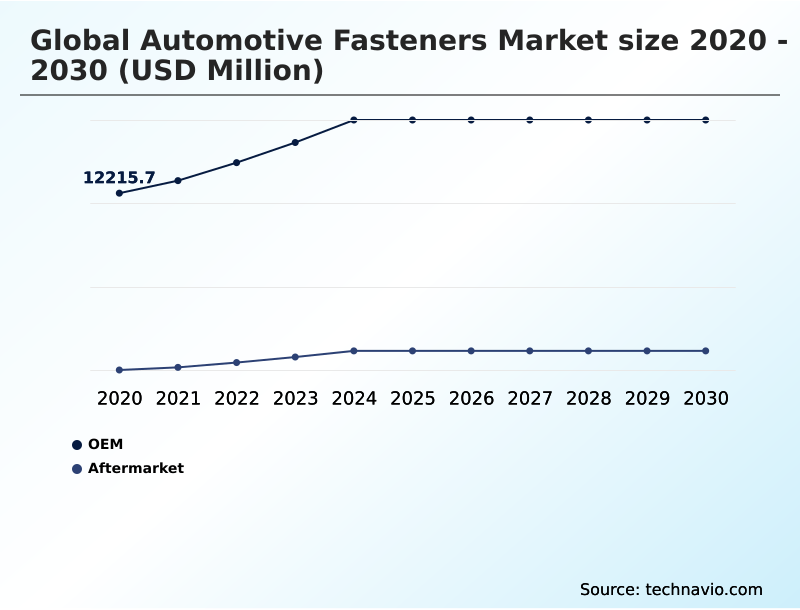
The OEM segment was valued at USD 15.68 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 56.9% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
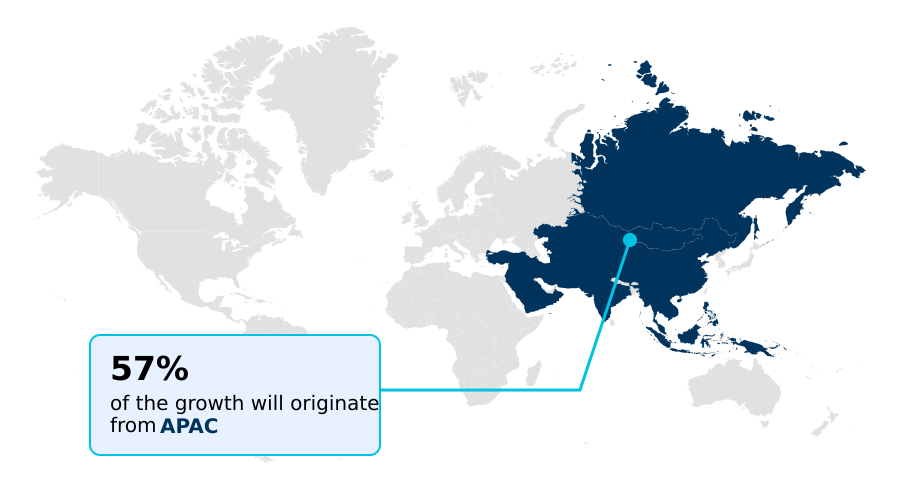
See How Automotive Fasteners Market Demand is Rising in APAC Get Free Sample

The geographic landscape of the Automotive Fasteners sector reveals distinct operational disparities between APAC and Europe. Assembly hubs in APAC prioritize high-speed, high-volume production, utilizing high-speed multi-station headers to achieve unparalleled manufacturing scale.

In contrast, European manufacturers heavily emphasize advanced metallurgical purity and stringent batch traceability protocols to align with rigid environmental directives.

European facilities have integrated automated optical sorting systems and eddy-current testing loops, resulting in a 22% improvement in defect identification compared to legacy inspection methods. This technological upgrade reduces costly assembly line halts and guarantees zero-defect quality levels.

Meanwhile, the APAC supply chain benefits from lower raw material costs and rapid domestic expansion, driving a 15% higher adoption rate of thermal management systems and blind mechanical fastening hardware tailored for the surging electric vehicle segment.

Zinc-flake surface coatings are increasingly deployed across both regions to maximize joint longevity.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The transformation of modern vehicular assembly requires sophisticated engineering solutions that adapt to complex structural demands. As automotive designers prioritize weight reduction to meet stringent fuel economy standards, the procurement of multi material joining fasteners has become a critical operational priority.
  • Supply chain managers are actively realigning vendor contracts to secure specialized components capable of binding aluminum and carbon fiber without compromising structural integrity. Concurrently, the rapid electrification of passenger fleets has triggered an unprecedented demand for high-strength electric vehicle battery pack bolts that provide exceptional insulation and sheer resistance under extreme thermal conditions.
  • To mitigate the risks of joint relaxation during prolonged operation, manufacturers are increasingly integrating advanced anti vibration locking mechanisms directly into the chassis assembly process. This strategic enhancement has yielded a 30% reduction in long-term warranty claims related to mechanical loosening, directly improving post-sale profitability.
  • Furthermore, components treated with galvanic corrosion resistant coatings are being aggressively sourced to extend the operational lifespan of dissimilar metal joints exposed to harsh environmental factors. To ensure absolute compliance with international safety protocols, production facilities are deploying automated optical defect sorting systems.
  • This technology significantly optimizes the quality assurance workflow, enabling assembly plants to achieve near-zero defect rates while processing millions of joining components, ultimately fortifying the reliability of the global automotive manufacturing ecosystem.
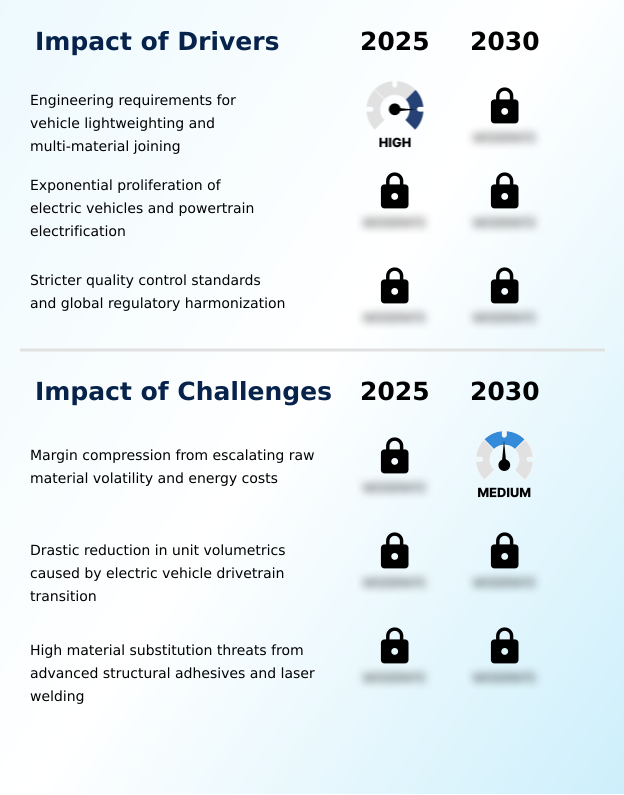
What are the key market drivers leading to the rise in the adoption of Automotive Fasteners Industry?

  • Stringent engineering requirements for vehicle lightweighting and the subsequent necessity for multi-material joining represent primary drivers propelling industry expansion.

  • Stringent corporate average fuel economy guidelines are compelling automotive manufacturers to aggressively implement vehicle lightweighting strategies, directly accelerating the demand for sophisticated joining technologies.
  • The rapid adoption of multi-material vehicle architectures requires specialized self-piercing rivets and high-tensile specialty screws to secure disparate substrates.
  • By utilizing advanced carbon-fiber composite joining techniques, assembly plants have reduced total chassis weight by 14%, significantly extending the operational range of electrified fleets.
  • Furthermore, aluminum alloy substitution in semi-structural panels has enhanced dynamic stress endurance and improved clamp force retention by 22% under extreme vibrations.
  • This materials evolution guarantees crashworthiness structural integrity while eliminating the galvanic corrosion risks associated with traditional welding, making high-performance mechanical fasteners an indispensable requirement for next-generation vehicle manufacturing.

What are the market trends shaping the Automotive Fasteners Industry?

  • An accelerated transition toward electric vehicle platforms and battery-specific solutions represents a defining trend within the industry. This structural shift requires highly specialized joining components designed to secure electric drivetrains safely.

  • The widespread integration of modular fastening systems is fundamentally altering assembly line operations across the automotive manufacturing landscape. As the powertrain electrification shift accelerates, producers are completely re-engineering joint configurations to accommodate battery electric vehicle drivetrains. By deploying micro-threaded fasteners within delicate sensor housings, assembly plants have improved component seating accuracy by 25% and reduced electrical short-circuit incidents by 18%.
  • The push toward carbon footprint reduction and strict circular economy mandates has incentivized the adoption of highly efficient automated robotic assembly protocols. These smart factory automation initiatives utilize real-time torque monitoring to ensure precise installation, driving a 30% decrease in overall equipment downtime.
  • Consequently, securing high-voltage power electronics with these specialized, trackable components is now a standard operational prerequisite, ensuring long-term vehicle reliability and drastically streamlining complex manufacturing workflows.

What challenges does the Automotive Fasteners Industry face during its growth?

  • Severe margin compression resulting from escalating raw material price volatility and rising industrial energy costs remains a significant challenge restricting operational profitability.

  • Volatile raw material price volatility and escalating industrial energy expenditure are heavily compressing the operational margins of traditional cold forging operations. To reduce vehicular curb weight, manufacturers are increasingly substituting traditional mechanical joints with advanced structural adhesives and robotic adhesive dispensing systems.
  • This substitution trend has reduced the volume of threaded fasteners used in non-critical body-in-white applications by approximately 18%, forcing hardware suppliers to pivot their production capacities. The absolute necessity for galvanic corrosion prevention and complex galvanic insulation layers in multi-material designs further elevates manufacturing costs.
  • Strict cross-border supply frameworks and the demand for absolute supply chain traceability require massive capital investments in digital tracking, increasing overall production overheads by 15% and placing immense financial pressure on specialized component fabricators attempting to maintain profitability.

Exclusive Technavio Analysis on Customer Landscape

The automotive fasteners market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the automotive fasteners market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
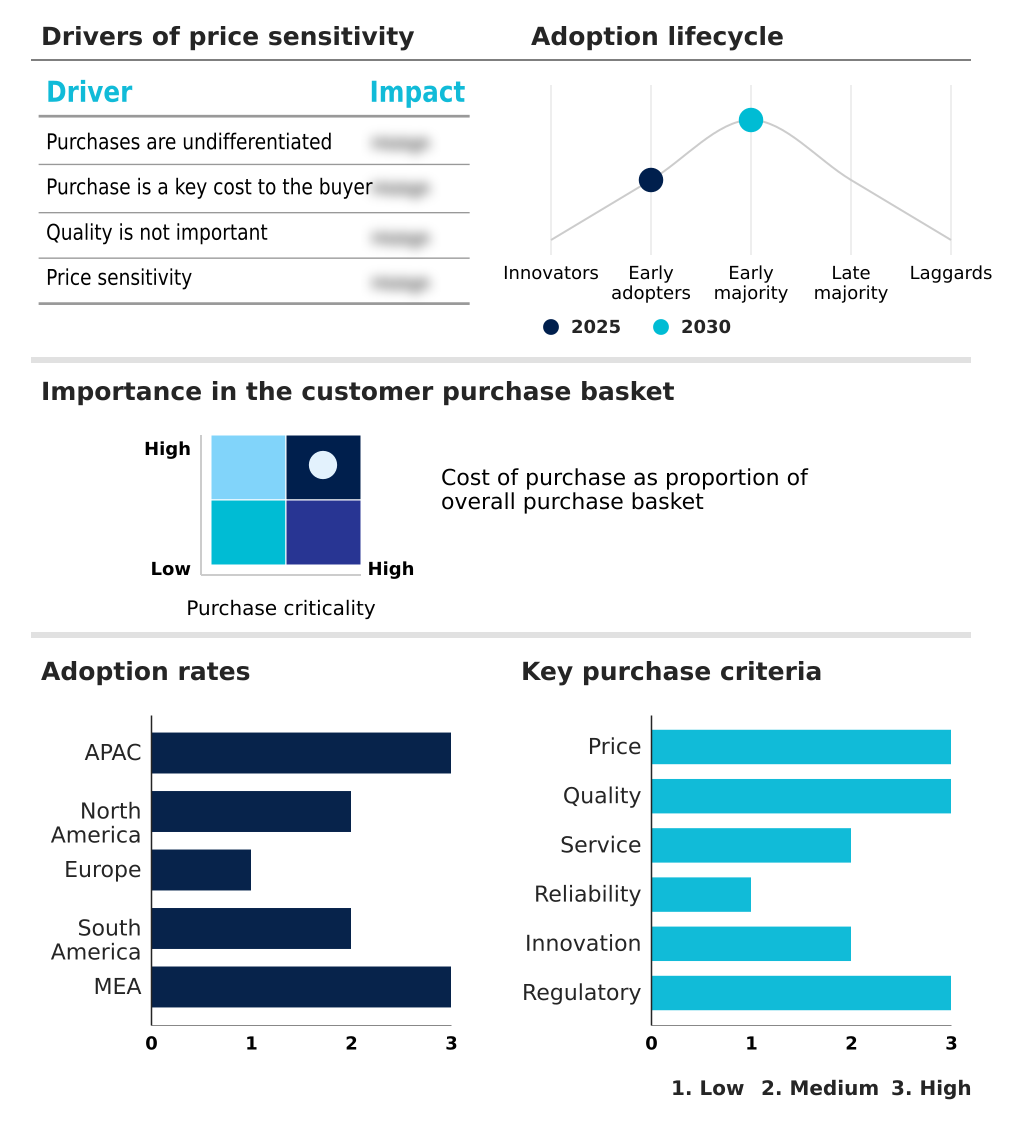
Customer Landscape of Automotive Fasteners Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, automotive fasteners market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

A.AGRATI Spa - The vendor provides specialized automotive fastening components, including high-strength bolts, advanced screws, and thread-forming hardware, engineered to meet stringent mechanical joining requirements in modern vehicular assembly lines.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • A.AGRATI Spa
  • Acument Global Technologies Inc.
  • Aoyama Seisakusho Co. Ltd.
  • EJOT HOLDING GmbH and Co. KG
  • Fontana Gruppo
  • Illinois Tool Works Inc.
  • Koninklijke Nedschroef Holding
  • Meidoh Co. Ltd.
  • MEIRA Corp.
  • Nifco Inc.
  • NORMA Group SE
  • Penn Engineering
  • Phillips Screw Co.
  • Piolax Inc.
  • Raygroup SASU
  • SFS Group AG
  • Stanley Engineered Fastening
  • Sundram Fasteners Ltd.
  • Topura Co. Ltd.
  • Trifast plc

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Automotive fasteners market

  • In the Automotive Parts and Equipment industry, the aggressive transition toward electric vehicle architectures eliminated legacy exhaust components and introduced stringent requirements for high-voltage power electronics, directly impacting Automotive Fasteners demand by necessitating non-magnetic insulated fasteners capable of protecting sensitive circuitry.
  • The implementation of stricter global safety testing protocols and zero-defect quality levels mandated by international safety oversight entities forced component suppliers to integrate multi-camera inline monitoring, enhancing Automotive Fasteners supply chain traceability and ensuring absolute metallurgical purity across high-volume production batches.
  • Rising industrial energy expenditure and raw material price volatility heavily compressed operational margins for tier-one automotive forging facilities, driving Automotive Fasteners manufacturers to adopt smart factory automation and advanced eddy-current testing loops to reduce scrap rates by approximately twelve percent.
  • Accelerated adoption of robotic adhesive dispensing techniques and advanced structural adhesives in non-critical body-in-white applications effectively replaced traditional mechanical joints in specific lightweight vehicle frames, shifting Automotive Fasteners demand toward specialized self-piercing rivets required for multi-material vehicle architectures.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Automotive Fasteners Market insights. See full methodology.

Market Scope
Page number 329
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 8.4%
Market growth 2026-2030 USD 10862.5 million
Market structure Fragmented
YoY growth 2025-2026(%) 7.7%
Key countries China, Japan, India, South Korea, Indonesia, Australia, US, Canada, Mexico, Germany, France, UK, Spain, Italy, The Netherlands, Brazil, Argentina, Chile, Turkey, South Africa, Saudi Arabia, UAE and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Automotive Fasteners sector is experiencing a profound engineering shift dictated by the rapid electrification and lightweighting of modern vehicle platforms. Boardroom executives are strategically revising procurement budgets to secure high-tensile specialty screws and self-piercing rivets, moving decisively away from traditional thermal welding methods. This strategic pivot is essential for successfully assembling multi-material vehicle architectures without compromising structural crashworthiness.
  • By integrating specialized thread-forming fasteners, manufacturing facilities have achieved a 28% reduction in assembly cycle times, directly enhancing operational throughput. The transition toward battery electric vehicle drivetrains requires components treated with advanced zinc-flake surface coatings to prevent environmental degradation and galvanic reactions.
  • Companies investing heavily in modernized cold forging operations are successfully insulating themselves against supply chain volatility while meeting stringent zero-defect mandates. This technological realignment ensures that original equipment manufacturers can maintain uninterrupted production lines while satisfying complex regulatory safety standards.
  • Advanced fastening solutions have evolved from basic commodity hardware into critical, highly engineered assets that dictate the long-term reliability and performance of next-generation automotive platforms.

What are the Key Data Covered in this Automotive Fasteners Market Research and Growth Report?

  • What is the expected growth of the Automotive Fasteners Market between 2026 and 2030?

    • USD 10.86 billion, at a CAGR of 8.4%

  • What segmentation does the market report cover?

    • The report is segmented by End-user (OEM, and Aftermarket), Vehicle Type (Passenger cars, and Commercial vehicles), Material (Stainless steel, Plastic, and Aluminum), Type (Threaded, and Non-threaded), Application (Engine, Chassis, Interior trim, Front, and Others) and Geography (APAC, North America, Europe, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • APAC, North America, Europe, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Engineering requirements for vehicle lightweighting and multi-material joining, Margin compression from escalating raw material volatility and energy costs

  • Who are the major players in the Automotive Fasteners Market?

    • A.AGRATI Spa, Acument Global Technologies Inc., Aoyama Seisakusho Co. Ltd., EJOT HOLDING GmbH and Co. KG, Fontana Gruppo, Illinois Tool Works Inc., Koninklijke Nedschroef Holding, Meidoh Co. Ltd., MEIRA Corp., Nifco Inc., NORMA Group SE, Penn Engineering, Phillips Screw Co., Piolax Inc., Raygroup SASU, SFS Group AG, Stanley Engineered Fastening, Sundram Fasteners Ltd., Topura Co. Ltd. and Trifast plc

Market Research Insights

  • The Automotive Fasteners environment is defined by the critical need for precision-engineered hardware capable of securing complex modern vehicular architectures. As manufacturers pursue aggressive vehicle lightweighting strategies to comply with strict corporate average fuel economy guidelines, the demand for specialized mechanical joints has surged.
  • Facilities adopting advanced locking threads report a 24% improvement in clamp force retention over prolonged operational cycles, drastically lowering structural failure risks. Furthermore, utilizing high-performance alloys has enhanced dynamic stress endurance, resulting in an 18% decrease in warranty-related maintenance costs.
  • These advanced hardware solutions are fundamentally shifting procurement models, as automotive brands prioritize long-term joint reliability and assembly automation over conventional, low-cost commodity components to secure resilient manufacturing outputs.

We can help! Our analysts can customize this automotive fasteners market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Vehicle Type
Executive Summary - Chart on Market Segmentation by Material
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Automotive Fasteners Market 2020 - 2024

Historic Market Size - Data Table on Global Automotive Fasteners Market 2020 - 2024 ($ million)

5.2 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.3 Vehicle Type segment analysis 2020 - 2024

Historic Market Size - Vehicle Type Segment 2020 - 2024 ($ million)

5.4 Material segment analysis 2020 - 2024

Historic Market Size - Material Segment 2020 - 2024 ($ million)

5.5 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.6 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.7 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.8 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Automotive Fasteners Market

6.2 Impact of geopolitical conflicts on Global Automotive Fasteners Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by End-user

8.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

8.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

8.3 OEM - Market size and forecast 2025-2030

Chart on OEM - Market size and forecast 2025-2030 ($ million)
Data Table on OEM - Market size and forecast 2025-2030 ($ million)
Chart on OEM - Year-over-year growth 2025-2030 (%)
Data Table on OEM - Year-over-year growth 2025-2030 (%)

8.4 Aftermarket - Market size and forecast 2025-2030

Chart on Aftermarket - Market size and forecast 2025-2030 ($ million)
Data Table on Aftermarket - Market size and forecast 2025-2030 ($ million)
Chart on Aftermarket - Year-over-year growth 2025-2030 (%)
Data Table on Aftermarket - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

9. Market Segmentation by Vehicle Type

9.1 Market segments

Chart on Vehicle Type - Market share 2025-2030 (%)
Data Table on Vehicle Type - Market share 2025-2030 (%)

9.2 Comparison by Vehicle Type

Chart on Comparison by Vehicle Type
Data Table on Comparison by Vehicle Type

9.3 Passenger cars - Market size and forecast 2025-2030

Chart on Passenger cars - Market size and forecast 2025-2030 ($ million)
Data Table on Passenger cars - Market size and forecast 2025-2030 ($ million)
Chart on Passenger cars - Year-over-year growth 2025-2030 (%)
Data Table on Passenger cars - Year-over-year growth 2025-2030 (%)

9.4 Commercial vehicles - Market size and forecast 2025-2030

Chart on Commercial vehicles - Market size and forecast 2025-2030 ($ million)
Data Table on Commercial vehicles - Market size and forecast 2025-2030 ($ million)
Chart on Commercial vehicles - Year-over-year growth 2025-2030 (%)
Data Table on Commercial vehicles - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Vehicle Type

Market opportunity by Vehicle Type ($ million)
Data Table on Market opportunity by Vehicle Type ($ million)

10. Market Segmentation by Material

10.1 Market segments

Chart on Material - Market share 2025-2030 (%)
Data Table on Material - Market share 2025-2030 (%)

10.2 Comparison by Material

Chart on Comparison by Material
Data Table on Comparison by Material

10.3 Stainless steel - Market size and forecast 2025-2030

Chart on Stainless steel - Market size and forecast 2025-2030 ($ million)
Data Table on Stainless steel - Market size and forecast 2025-2030 ($ million)
Chart on Stainless steel - Year-over-year growth 2025-2030 (%)
Data Table on Stainless steel - Year-over-year growth 2025-2030 (%)

10.4 Plastic - Market size and forecast 2025-2030

Chart on Plastic - Market size and forecast 2025-2030 ($ million)
Data Table on Plastic - Market size and forecast 2025-2030 ($ million)
Chart on Plastic - Year-over-year growth 2025-2030 (%)
Data Table on Plastic - Year-over-year growth 2025-2030 (%)

10.5 Aluminum - Market size and forecast 2025-2030

Chart on Aluminum - Market size and forecast 2025-2030 ($ million)
Data Table on Aluminum - Market size and forecast 2025-2030 ($ million)
Chart on Aluminum - Year-over-year growth 2025-2030 (%)
Data Table on Aluminum - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Material

Market opportunity by Material ($ million)
Data Table on Market opportunity by Material ($ million)

11. Market Segmentation by Type

11.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

11.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

11.3 Threaded - Market size and forecast 2025-2030

Chart on Threaded - Market size and forecast 2025-2030 ($ million)
Data Table on Threaded - Market size and forecast 2025-2030 ($ million)
Chart on Threaded - Year-over-year growth 2025-2030 (%)
Data Table on Threaded - Year-over-year growth 2025-2030 (%)

11.4 Non-threaded - Market size and forecast 2025-2030

Chart on Non-threaded - Market size and forecast 2025-2030 ($ million)
Data Table on Non-threaded - Market size and forecast 2025-2030 ($ million)
Chart on Non-threaded - Year-over-year growth 2025-2030 (%)
Data Table on Non-threaded - Year-over-year growth 2025-2030 (%)

11.5 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

12. Market Segmentation by Application

12.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

12.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

12.3 Engine - Market size and forecast 2025-2030

Chart on Engine - Market size and forecast 2025-2030 ($ million)
Data Table on Engine - Market size and forecast 2025-2030 ($ million)
Chart on Engine - Year-over-year growth 2025-2030 (%)
Data Table on Engine - Year-over-year growth 2025-2030 (%)

12.4 Chassis - Market size and forecast 2025-2030

Chart on Chassis - Market size and forecast 2025-2030 ($ million)
Data Table on Chassis - Market size and forecast 2025-2030 ($ million)
Chart on Chassis - Year-over-year growth 2025-2030 (%)
Data Table on Chassis - Year-over-year growth 2025-2030 (%)

12.5 Interior trim - Market size and forecast 2025-2030

Chart on Interior trim - Market size and forecast 2025-2030 ($ million)
Data Table on Interior trim - Market size and forecast 2025-2030 ($ million)
Chart on Interior trim - Year-over-year growth 2025-2030 (%)
Data Table on Interior trim - Year-over-year growth 2025-2030 (%)

12.6 Front - Market size and forecast 2025-2030

Chart on Front - Market size and forecast 2025-2030 ($ million)
Data Table on Front - Market size and forecast 2025-2030 ($ million)
Chart on Front - Year-over-year growth 2025-2030 (%)
Data Table on Front - Year-over-year growth 2025-2030 (%)

12.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

13. Customer Landscape

13.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

14. Geographic Landscape

14.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

14.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

14.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

14.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

14.3.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

14.3.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

14.3.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

14.3.5 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

14.3.6 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

14.4 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

14.4.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

14.4.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

14.4.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

14.5 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

14.5.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

14.5.2 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

14.5.3 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

14.5.4 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

14.5.5 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

14.5.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

14.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

14.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

14.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

14.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

14.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

14.7.1 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

14.7.2 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

14.7.3 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

14.7.4 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

14.7.5 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

14.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

15. Drivers, Challenges, and Opportunity

15.1 Market drivers

Engineering requirements for vehicle lightweighting and multi-material joining
Exponential proliferation of electric vehicles and powertrain electrification
Stricter quality control standards and global regulatory harmonization

15.2 Market challenges

Margin compression from escalating raw material volatility and energy costs
Drastic reduction in unit volumetrics caused by electric vehicle drivetrain transition
High material substitution threats from advanced structural adhesives and laser welding

15.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

15.4 Market opportunities

Accelerated transition toward electric vehicle platforms and battery-specific solutions
Comprehensive lightweighting strategies and material substitution initiatives
Rising demand for advanced anti-vibration and corrosion-resistant technologies

16. Competitive Landscape

16.1 Overview

16.2

Overview on criticality of inputs and factors of differentiation

16.3 Landscape disruption

Overview on factors of disruption

16.4 Industry risks

Impact of key risks on business

17. Competitive Analysis

17.1 Companies profiled

Companies covered

17.2 Company ranking index

17.3 Market positioning of companies

Matrix on companies position and classification

17.4 Acument Global Technologies Inc.

Acument Global Technologies Inc. - Overview
Acument Global Technologies Inc. - Product / Service
Acument Global Technologies Inc. - Key offerings
SWOT

17.5 Aoyama Seisakusho Co. Ltd.

Aoyama Seisakusho Co. Ltd. - Overview
Aoyama Seisakusho Co. Ltd. - Product / Service
Aoyama Seisakusho Co. Ltd. - Key offerings
SWOT

17.6 Fontana Gruppo

Fontana Gruppo - Overview
Fontana Gruppo - Product / Service
Fontana Gruppo - Key offerings
SWOT

17.7 Illinois Tool Works Inc.

Illinois Tool Works Inc. - Overview
Illinois Tool Works Inc. - Business segments
Illinois Tool Works Inc. - Key offerings
Illinois Tool Works Inc. - Segment focus
SWOT

17.8 Koninklijke Nedschroef Holding

Koninklijke Nedschroef Holding - Overview
Koninklijke Nedschroef Holding - Product / Service
Koninklijke Nedschroef Holding - Key offerings
SWOT

17.9 Meidoh Co. Ltd.

Meidoh Co. Ltd. - Overview
Meidoh Co. Ltd. - Product / Service
Meidoh Co. Ltd. - Key offerings
SWOT

17.10 MEIRA Corp.

MEIRA Corp. - Overview
MEIRA Corp. - Product / Service
MEIRA Corp. - Key offerings
SWOT

17.11 Nifco Inc.

Nifco Inc. - Overview
Nifco Inc. - Business segments
Nifco Inc. - Key offerings
Nifco Inc. - Segment focus
SWOT

17.12 NORMA Group SE

NORMA Group SE - Overview
NORMA Group SE - Business segments
NORMA Group SE - Key offerings
NORMA Group SE - Segment focus
SWOT

17.13 Penn Engineering

Penn Engineering - Overview
Penn Engineering - Product / Service
Penn Engineering - Key offerings
SWOT

17.14 Piolax Inc.

Piolax Inc. - Overview
Piolax Inc. - Business segments
Piolax Inc. - Key offerings
Piolax Inc. - Segment focus
SWOT

17.15 Raygroup SASU

Raygroup SASU - Overview
Raygroup SASU - Product / Service
Raygroup SASU - Key offerings
SWOT

17.16 SFS Group AG

SFS Group AG - Overview
SFS Group AG - Business segments
SFS Group AG - Key offerings
SFS Group AG - Segment focus
SWOT

17.17 Sundram Fasteners Ltd.

Sundram Fasteners Ltd. - Overview
Sundram Fasteners Ltd. - Product / Service
Sundram Fasteners Ltd. - Key offerings
SWOT

17.18 Topura Co. Ltd.

Topura Co. Ltd. - Overview
Topura Co. Ltd. - Product / Service
Topura Co. Ltd. - Key offerings
SWOT

18. Appendix

18.1 Scope of the report

Market definition
Objectives
Notes and caveats

18.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

18.3 Currency conversion rates for US$

18.4 Research methodology

18.5 Data procurement

Information sources

18.6 Data validation

18.7 Validation techniques employed for market sizing

18.8 Data synthesis

18.9 360 degree market analysis

18.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Automotive Fasteners market growth will increase by USD 10862.5 million during 2026-2030.

The Automotive Fasteners market is expected to grow at a CAGR of 8.4% during 2026-2030.

Automotive Fasteners market is segmented by End-user (OEM, Aftermarket) Vehicle type (Passenger cars, Commercial vehicles) Material (Stainless steel, Plastic, Aluminum) Type (Threaded, Non-threaded) Application (Engine, Chassis, Interior trim, Front, Others)

A.AGRATI Spa, Acument Global Technologies Inc., Aoyama Seisakusho Co. Ltd., EJOT HOLDING GmbH and Co. KG, Fontana Gruppo, Illinois Tool Works Inc., Koninklijke Nedschroef Holding, Meidoh Co. Ltd., MEIRA Corp., Nifco Inc., NORMA Group SE, Penn Engineering, Phillips Screw Co., Piolax Inc., Raygroup SASU, SFS Group AG, Stanley Engineered Fastening, Sundram Fasteners Ltd., Topura Co. Ltd., Trifast plc are a few of the key vendors in the Automotive Fasteners market.

APAC will register the highest growth rate of 56.9% among the other regions. Therefore, the Automotive Fasteners market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, Japan, India, South Korea, Indonesia, Australia, US, Canada, Mexico, Germany, France, UK, Spain, Italy, The Netherlands, Brazil, Argentina, Chile, Turkey, South Africa, Saudi Arabia, UAE, Israel

  • Engineering requirements for vehicle lightweighting and multi-material joining is the driving factor this market.

The Automotive Fasteners market vendors should focus on grabbing business opportunities from the End-user segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
