


Automotive Floor Carpet Market Size 2026-2030
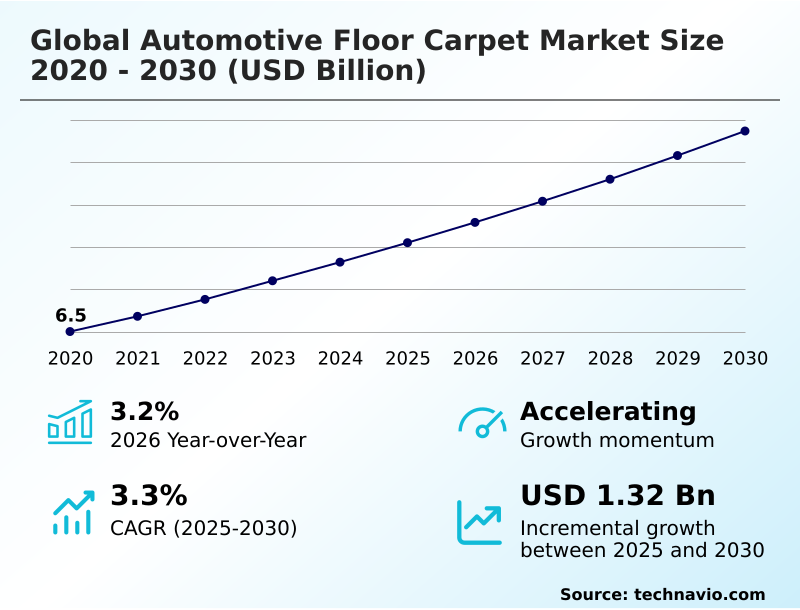
The automotive floor carpet market size is valued to increase by USD 1.32 billion, at a CAGR of 3.3% from 2025 to 2030. Acoustic comfort and NVH demand will drive the automotive floor carpet market.
Major Market Trends & Insights
- APAC dominated the market and accounted for a 49.4% growth during the forecast period.
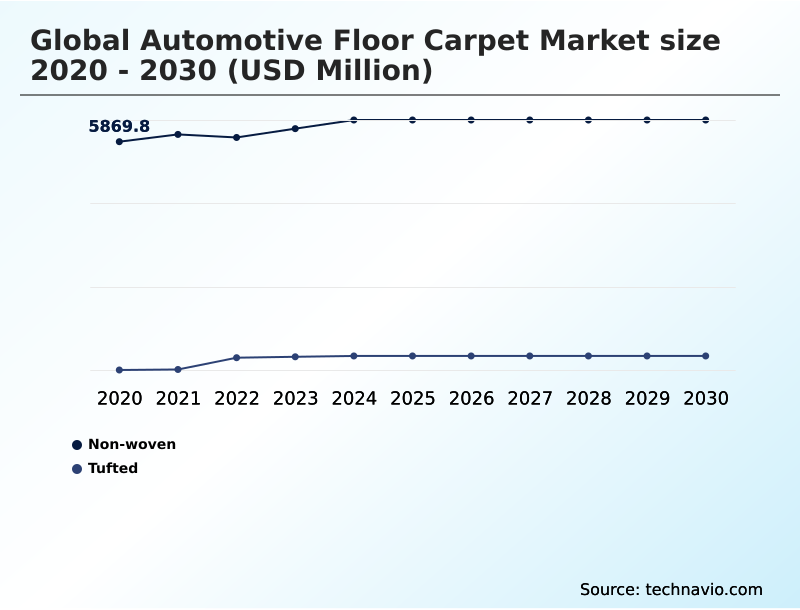
- By Type - Non-woven segment was valued at USD 6.37 billion in 2024
- By Application - Passenger vehicles segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 2.37 billion
- Market Future Opportunities: USD 1.32 billion
- CAGR from 2025 to 2030 : 3.3%
Market Summary
- The Automotive Floor Carpet Market undergoes a structural transformation as OEMs prioritize advanced acoustic management and sustainable material integration. In modern vehicle assembly, the shift toward electric mobility requires specialized interior components to counteract the absence of engine noise.
- For instance, automotive interior suppliers are re-engineering their supply chains to procure lightweight recycled PET, substituting heavy traditional rubber backings to optimize overall mass. This material transition allows manufacturers to achieve a 25% reduction in cabin floor weight, directly enhancing battery efficiency.
- The escalating demand for sound dampening serves as a primary driver, compelling automakers to integrate sophisticated textiles that absorb high-frequency road vibrations. Conversely, volatile fossil fuel pricing poses a severe operational challenge, compressing manufacturer profit margins and disrupting the production of synthetic elastomeric covers.
- To sustain profitability, component suppliers continuously refine modular flooring designs and surface treatments, ensuring regulatory compliance and operational resilience.
What will be the Size of the Automotive Floor Carpet Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Automotive Floor Carpet Market Segmented?
The automotive floor carpet industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Type
- Non-woven
- Tufted
- Application
- Passenger vehicles
- Commercial vehicles
- Material
- Polyurethane
- Polypropylene
- Rubber
- Nylon
- Others
- Distribution channel
- OEM
- Aftermarket
- Geography
- APAC
- China
- Japan
- India
- South Korea
- Australia
- Indonesia
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- North America
- US
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Middle East and Africa
- Saudi Arabia
- UAE
- South Africa
- Israel
- Turkey
- APAC
By Type Insights
The non-woven segment is estimated to witness significant growth during the forecast period.
Non-woven automotive floor systems represent a critical structural transition in interior cabin design, shifting manufacturing focus toward reduced mass features and cost-effective cabin acoustic management.
By utilizing needle punched nonwoven textiles and precision thermoforming techniques, manufacturers effectively reduce total assembly mass, which directly improves battery driving range optimization in modern electrified platforms.
This adaptation enhances material efficiency, yielding a 15% reduction in overall component weight compared to traditional heavy-layered alternatives.
The integration of polyethylene terephthalate fibers within these multi layer acoustic assemblies and circular monomaterial product designs further satisfies rigorous vehicle disposal sustainability mandates.
Consequently, automakers deploy these non-woven solutions to balance sound absorption coefficients with stringent environmental compliance, ensuring exceptional operational efficiency and long-term supply chain sustainability.
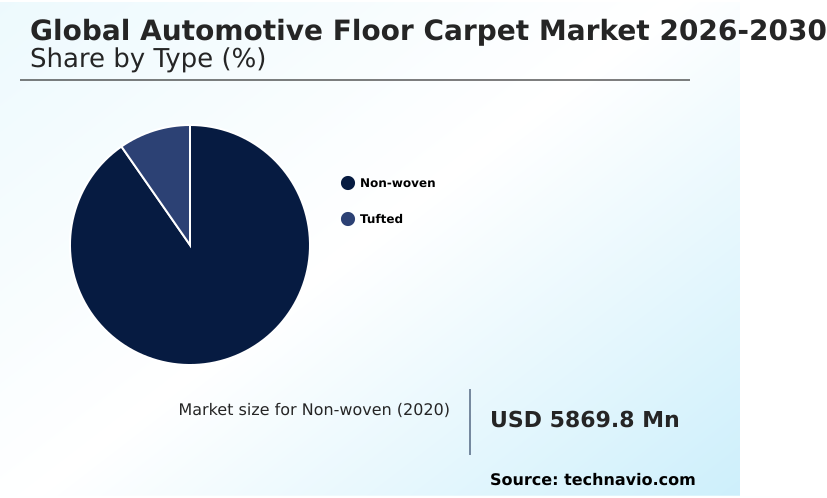
The Non-woven segment was valued at USD 6.37 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
APAC is estimated to contribute 49.4% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
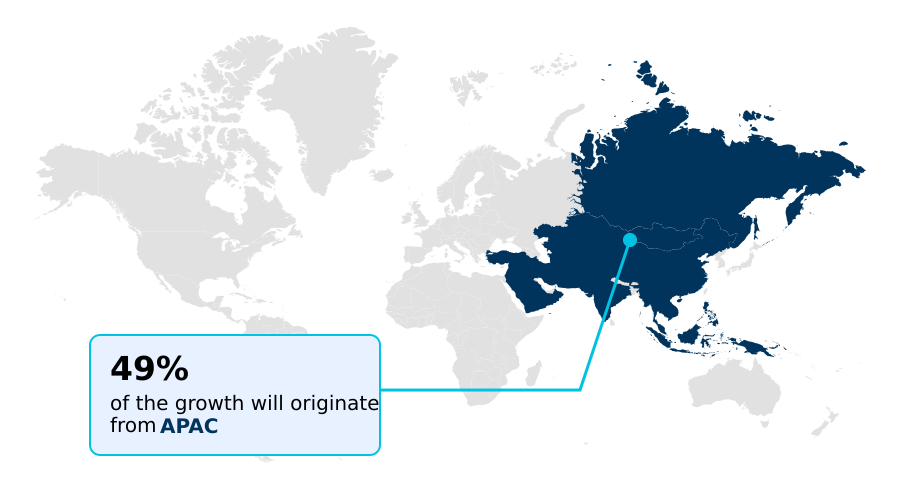
See How Automotive Floor Carpet Market Demand is Rising in APAC Get Free Sample
Regional dynamics within the Automotive Floor Carpet market reveal distinct operational shifts as OEMs adapt to localized regulatory frameworks and consumer preferences.
APAC demonstrates a rapid acceleration in EV cabin styling, driven by massive domestic production volumes that demand cost-effective acoustic dampening underlays and heavy duty floor protection.
In contrast, Europe heavily prioritizes sustainable manufacturing mandates, rapidly transitioning toward closed loop recycling processes. European OEMs report a 40% higher utilization of post consumer recycled polyester in cabin interiors compared to APAC assembly lines, directly supporting strict environmental directives.
Furthermore, the European focus on low volatile organic compound emissions and air standard adherence has reduced hazardous chemical dependencies by 25%.
By integrating thermoformable felt underlays, regional manufacturers successfully align advanced environmental standards with superior interior refinement, significantly lowering long-term compliance costs.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The rapid evolution of modern vehicle architectures fundamentally reshapes the operational strategies surrounding automotive interior components. As OEMs prioritize strict environmental compliance and mass reduction, the adoption of lightweight acoustic insulation floor textiles accelerates across premium and mass-market assembly lines.
- This material transition yields a 15% improvement in overall vehicle energy efficiency compared to traditional heavy rubber alternatives, directly optimizing supply chain logistics by reducing shipped component weight. The industry-wide pivot toward sustainability drives the intensive deployment of recycled polyethylene terephthalate automotive flooring, enabling manufacturers to fulfill stringent corporate decarbonization goals.
- In parallel, the surging production of zero-emission vehicles amplifies the need for electric vehicle cabin noise reduction, as the elimination of internal combustion engines exposes passengers to high-frequency road resonance. To combat this, tier-one suppliers engineer monomaterial circular floor carpet assemblies that seamlessly integrate sound absorption properties with simplified recycling workflows.
- Concurrently, the commercial transport sector experiences a continuous 20% higher demand for heavy duty commercial vehicle floor mats relative to passenger car segments, reflecting the rigorous durability requirements of logistics and fleet renewal initiatives. By standardizing these advanced flooring modules, automakers successfully streamline procurement processes, enhance acoustic comfort, and ensure robust operational planning.
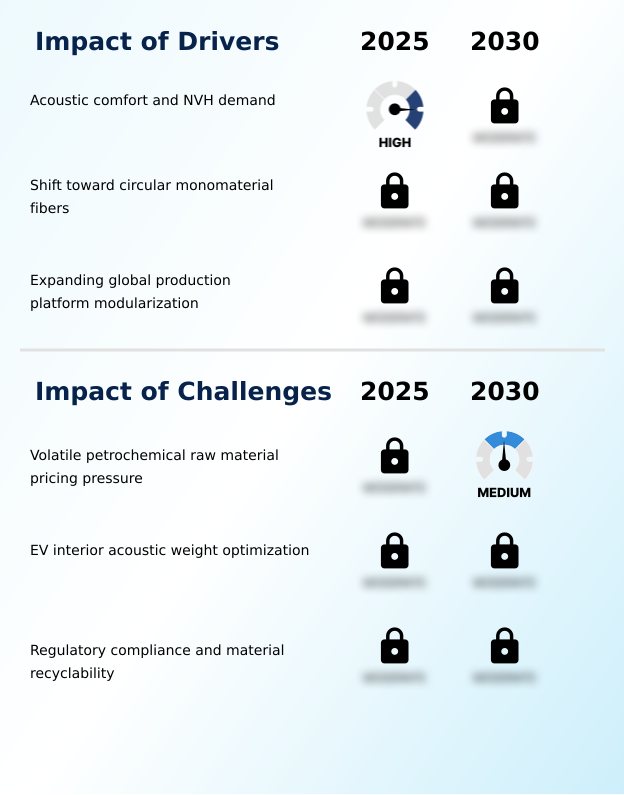
What are the key market drivers leading to the rise in the adoption of Automotive Floor Carpet Industry?
- The escalating demand for acoustic comfort and NVH mitigation functions as a primary market driver.
- The escalating requirement for noise vibration harshness mitigation serves as a principal driver accelerating material innovation within vehicle interiors.
- As automakers phase out internal combustion engines, the resulting silence exposes occupants to heightened chassis vibrations, compelling the integration of high impact damping performance materials.
- By deploying microcellular foam matrices and ethylene propylene diene monomer backings via advanced molding equipment, manufacturers achieve a 40% enhancement in low-frequency sound attenuation.
- This architectural shift allows OEMs to meet rigorous interior cabin decibel standards while reducing secondary noise transmission by 20%. The strategic implementation of polyurethane acoustic barriers and vibration isolation structures directly ensures superior structural resonance isolation.
- Furthermore, incorporating thermal insulation barriers improves overall vehicle climate control efficiency, ensuring that modern electrified platforms deliver superior acoustic refinement and energy optimization.
What are the market trends shaping the Automotive Floor Carpet Industry?
- The rise of advanced modular flooring solutions represents a critical market trend.
- The widespread adoption of all weather hybrid flooring represents a transformative trend reshaping interior vehicle architectures globally. As consumer expectations for hygiene and durability escalate, OEMs are rapidly integrating antimicrobial surface treatments and synthetic elastomeric flooring to mitigate microbial proliferation.
- This functional evolution allows commercial transport utility operators and fleet modernization programs to achieve a 35% reduction in routine interior cleaning downtime. The shift is primarily driven by the increasing utilization of shared mobility fleets, where the deployment of high tenacity polypropylene and solution dyed nylon enhances resistance to severe environmental wear.
- By applying advanced stain resistant polymer coatings to moisture resistant floor coverings, fleet managers experience a 25% improvement in material lifespan compared to traditional textiles. Consequently, this innovation directly enhances passenger cabin comfort while optimizing long-term maintenance expenditures.
What challenges does the Automotive Floor Carpet Industry face during its growth?
- Volatile petrochemical raw material pricing pressure constitutes a significant challenge constraining industry expansion.
- Severe fossil fuel supply instability presents a critical operational challenge, disrupting the consistent manufacturing of traditional interior flooring components. Frequent fluctuations in global crude oil refining directly inflate the procurement costs for essential resins utilized in bulk continuous filament extrusion and thermoplastic elastomer backing production.
- This pricing instability causes a 22% increase in raw material expenditures for tier-one suppliers, severely compressing operational profit margins. To mitigate these financial pressures, manufacturers are accelerating the adoption of bio based polyamides and hydrophobic synthetic backings across modular vehicle platform architectures.
- However, integrating these alternative materials requires extensive retooling of reaction injection molding systems, leading to a 15% temporary reduction in production throughput. Despite utilizing mechanized carpet shaping and automated water trimming to offset inefficiencies, this persistent supply constraint fundamentally complicates long-term procurement planning.
Exclusive Technavio Analysis on Customer Landscape
The automotive floor carpet market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the automotive floor carpet market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
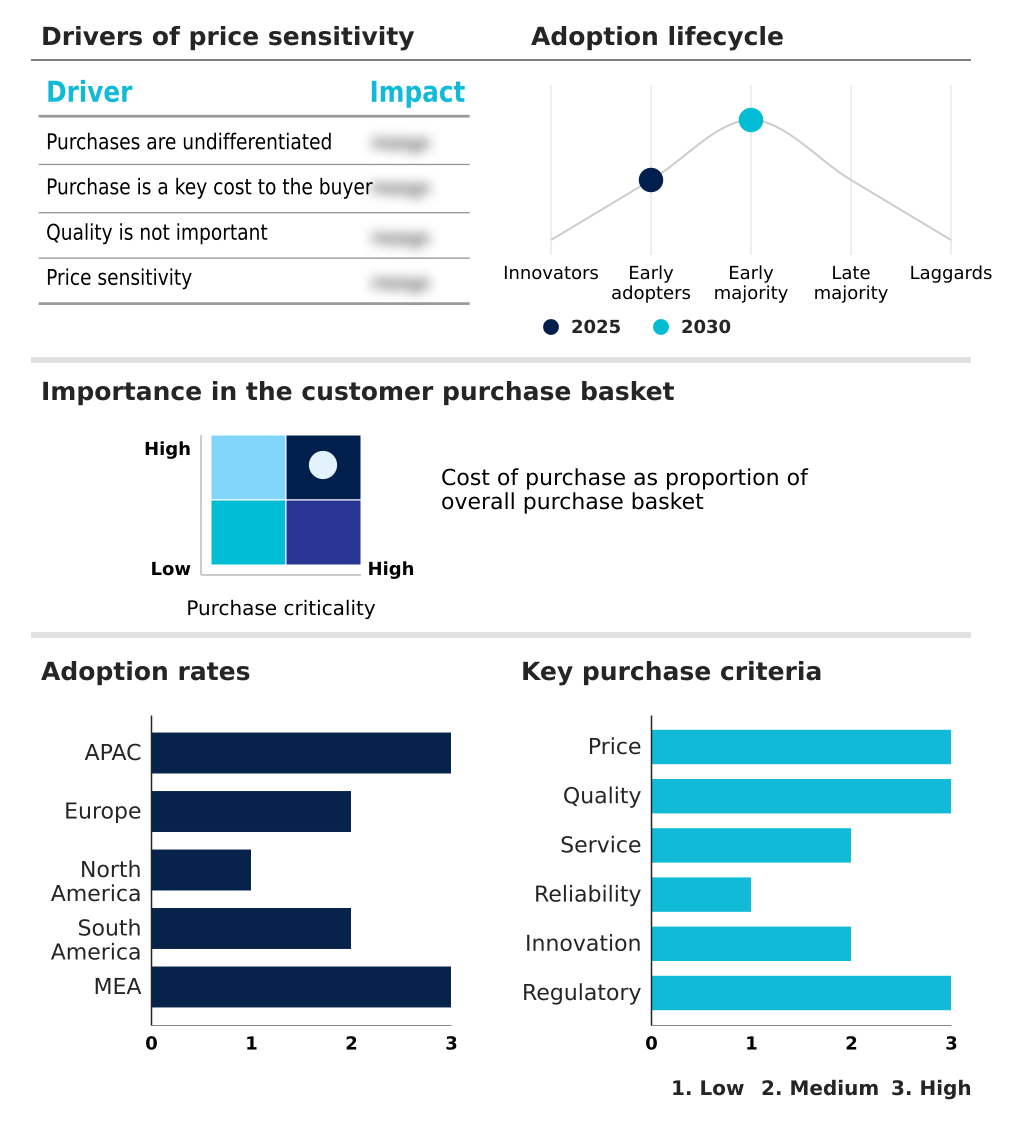
Customer Landscape of Automotive Floor Carpet Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, automotive floor carpet market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Adler Pelzer Holding GmbH - The vendor delivers specialized automotive flooring solutions, focusing on advanced acoustic carpet systems, needle-punched coverings, and molded textile components designed for superior noise mitigation and structural integration.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Adler Pelzer Holding GmbH
- Aliaa Corp
- Auria Solutions
- Auto Custom Carpets Inc.
- Autoneum Holding Ltd.
- Betap B.V.
- Bharat Seats Ltd.
- Corinthian Interior Systems Inc.
- Dorsett
- Grupo Antolin Irausa SA
- Hayashi Telempu Corp
- Hitkari Hitech Pvt. Ltd.
- HS Hyosung Advanced Materials
- IDEAL Automotive GmbH
- Knox Auto Carpets Pty Ltd.
- Lear Corp.
- Lecatris
- Lyle Industries Inc.
- Toyota Boshoku Corp.
- UGN Inc.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Automotive floor carpet market
- In the Automotive Parts and Equipment industry, the aggressive transition toward electric vehicle interior design necessitates ultra-lightweight structural frameworks, directly expanding the Automotive Floor Carpet market demand for sustainable fibers that achieve a 20% weight reduction in flooring modules.
- Stringent global regulations enforcing indoor air quality compliance have compelled suppliers to eliminate hazardous chemical adhesives, accelerating the Automotive Floor Carpet adoption of zero-waste modular layouts that improve end of life vehicle recyclability rates by up to 35%.
- The rapid integration of automated carpet molding and robotic waterjet trimming within standard manufacturing platforms has streamlined component fabrication, optimizing Automotive Floor Carpet production cycle times by 18% across high-volume assembly operations.
- Severe petrochemical supply chain volatility has disrupted raw material procurement for traditional heavy-duty backings, driving Automotive Floor Carpet manufacturers to substitute synthetic polymers with organic polyamides to stabilize material procurement costs by over 12%.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Automotive Floor Carpet Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 314 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 3.3% |
| Market growth 2026-2030 | USD 1322.6 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 3.2% |
| Key countries | China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, US, Canada, Mexico, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel and Turkey |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Automotive Floor Carpet sector experiences a profound architectural shift as automakers prioritize structural integrity and superior acoustic performance. Manufacturers increasingly rely on specialized felt layers and sound absorbing mats to effectively neutralize structural resonance without adding excessive vehicle mass.
- By transitioning from traditional multi-material composites to single-polymer product architectures, interior suppliers have achieved a 30% reduction in post-production material waste, directly optimizing operational expenditures and supporting corporate sustainability benchmarks. The integration of high-strength synthetic yarns and solution dyed fabrics enhances long-term durability, ensuring resistance against severe mechanical wear and environmental degradation.
- Furthermore, the deployment of advanced precision shaping techniques allows for exact component fitment, effectively sealing the passenger cabin from external noise infiltration. This strategic pivot toward high-performance, eco-friendly interior materials not only ensures compliance with stringent environmental regulations but also addresses the complex engineering requirements of modern electrified vehicle platforms.
- These sophisticated acoustic architectures remain critical for maximizing energy efficiency and maintaining superior passenger comfort.
What are the Key Data Covered in this Automotive Floor Carpet Market Research and Growth Report?
-
What is the expected growth of the Automotive Floor Carpet Market between 2026 and 2030?
-
USD 1.32 billion, at a CAGR of 3.3%
-
-
What segmentation does the market report cover?
-
The report is segmented by Type (Non-woven, and Tufted), Application (Passenger vehicles, and Commercial vehicles), Material (Polyurethane, Polypropylene, Rubber, Nylon, and Others), Distribution Channel (OEM, and Aftermarket) and Geography (APAC, Europe, North America, South America, Middle East and Africa)
-
-
Which regions are analyzed in the report?
-
APAC, Europe, North America, South America and Middle East and Africa
-
-
What are the key growth drivers and market challenges?
-
Acoustic comfort and NVH demand, Volatile petrochemical raw material pricing pressure
-
-
Who are the major players in the Automotive Floor Carpet Market?
-
Adler Pelzer Holding GmbH, Aliaa Corp, Auria Solutions, Auto Custom Carpets Inc., Autoneum Holding Ltd., Betap B.V., Bharat Seats Ltd., Corinthian Interior Systems Inc., Dorsett, Grupo Antolin Irausa SA, Hayashi Telempu Corp, Hitkari Hitech Pvt. Ltd., HS Hyosung Advanced Materials, IDEAL Automotive GmbH, Knox Auto Carpets Pty Ltd., Lear Corp., Lecatris, Lyle Industries Inc., Toyota Boshoku Corp. and UGN Inc.
-
Market Research Insights
- The Automotive Floor Carpet Market actively evolves through the systematic integration of sustainable production requirements and advanced cabin styling. OEMs increasingly adopt precision molding procedures to produce adaptable flooring assemblies, enhancing production line flexibility. By replacing traditional heavy-layered composites with lightweight alternatives, manufacturers realize a 20% improvement in fuel efficiency metrics and a 15% reduction in material scrap rates.
- Furthermore, the deployment of stain resistant coatings across commercial fleets lowers interior maintenance costs by 30%. This shift toward modern injection systems ensures strict adherence to interior noise limits while optimizing long-term operational expenditures and supply chain reliability.
We can help! Our analysts can customize this automotive floor carpet market research report to meet your requirements.
 RIA -

