


Automotive Projector Headlamps Market Size 2026-2030
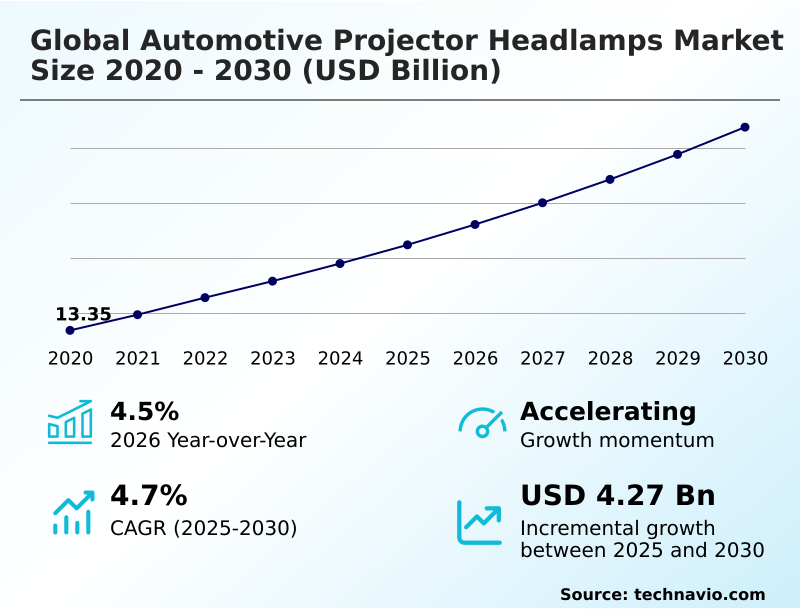
The automotive projector headlamps market size is valued to increase by USD 4.27 billion, at a CAGR of 4.7% from 2025 to 2030. Surging demand for advanced safety will drive the automotive projector headlamps market.
Major Market Trends & Insights
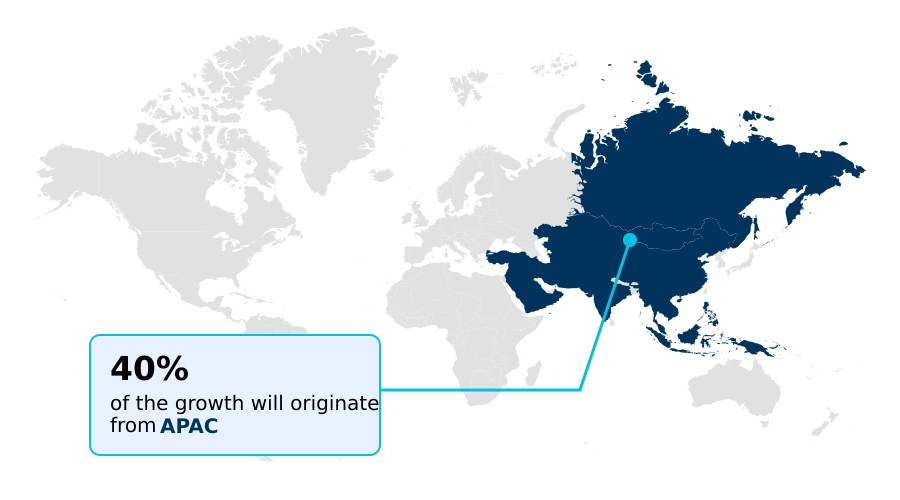
- APAC dominated the market and accounted for a 39.5% growth during the forecast period.
- By Type - Halogen segment was valued at USD 12.29 billion in 2024
- By Channel - OEMs segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 7.39 billion
- Market Future Opportunities: USD 4.27 billion
- CAGR from 2025 to 2030 : 4.7%
Market Summary
- The Automotive Projector Headlamps Market is undergoing a rapid architectural evolution driven by the convergence of solid-state illumination and intelligent vehicle networks. Original equipment manufacturers are systematically replacing traditional parabolic reflectors with highly engineered projector optics to deliver superior beam concentration and forward visibility.
- The primary driver of this transition is the escalating demand for enhanced nighttime safety; precise projector cut-off shields direct light efficiently onto the roadway, providing drivers with crucial hazard reaction time while preventing dangerous glare for oncoming traffic. Conversely, the sector faces severe engineering challenges related to extreme thermal accumulation.
- High-density light engines generate immense localized heat, requiring complex, space-consuming cooling mechanisms that elevate assembly vulnerability. In a practical supply chain scenario, a major automotive assembly plant redesigned its component procurement matrix, shifting from fragmented multi-vendor sourcing to pre-validated, modular projector light engines. This consolidated sourcing strategy accelerated production throughput by 18% compared to the legacy iterative assembly approach.
- By streamlining the integration of these advanced optical suites, automakers successfully balance stringent regulatory compliance with the aesthetic demands of modern software-defined mobility.
What will be the Size of the Automotive Projector Headlamps Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Automotive Projector Headlamps Market Segmented?
The automotive projector headlamps industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Type
- Halogen
- LED
- Others
- Channel
- OEMs
- Aftermarket
- Vehicle type
- Passenger vehicles
- Commercial vehicles
- Geography
- APAC
- China
- Japan
- India
- South Korea
- Australia
- Indonesia
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- North America
- US
- Mexico
- Canada
- South America
- Brazil
- Argentina
- Chile
- Middle East and Africa
- South Africa
- Saudi Arabia
- UAE
- Turkey
- Israel
- APAC
By Type Insights
The halogen segment is estimated to witness significant growth during the forecast period.
The halogen segment within the Automotive Projector Headlamps landscape maintains a critical role in high-volume, cost-sensitive vehicle production lines. Manufacturers continuously refine elliptical reflector geometry to focus light efficiently, ensuring adequate nighttime visibility for entry-level automotive fleets.
By utilizing high transmittance optical glass, these systems project a defined cut-off line that significantly improves peripheral illumination performance without blinding oncoming traffic.
The integration of advanced bulb enclosures minimizes chromatic aberration reduction requirements, allowing automotive engineers to lower the overall component bill of materials. Maintaining stringent active glare control is essential for international compliance.
Utilizing optimized halogen projector setups allows automakers to reduce baseline front-end manufacturing costs by 22% compared to premium solid-state variants, preserving crucial profit margins across budget passenger and commercial vehicle architectures.
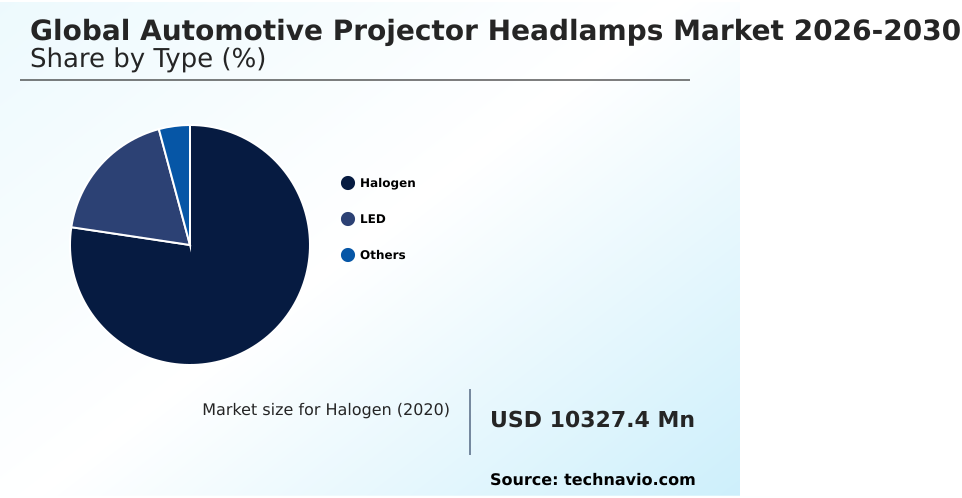
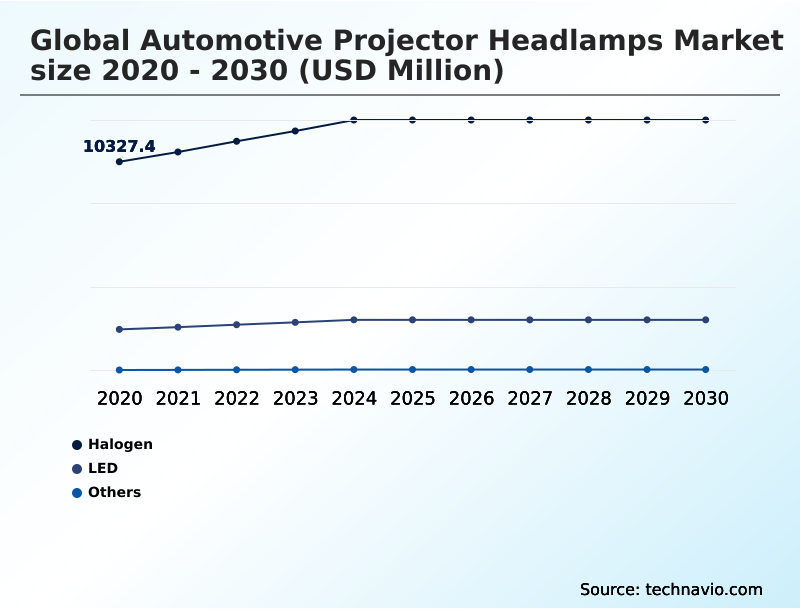
The Halogen segment was valued at USD 12.29 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
APAC is estimated to contribute 39.5% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
See How Automotive Projector Headlamps Market Demand is Rising in APAC Get Free Sample
Regional adoption dynamics within the Automotive Projector Headlamps sector highlight a distinct technological divergence between APAC and Europe.
European automotive assembly hubs maintain a 35% higher penetration rate of advanced adaptive driving beam systems, heavily incentivized by stringent regional safety frameworks that mandate automated glare mitigation.
Consequently, European manufacturers heavily invest in complex hardware validation matrix testing to ensure high luminous flux density complies with precise pedestrian safety standards.
In contrast, the APAC region exhibits explosive volume expansion driven by electric vehicle mass production, where maximizing range through electrical load reduction is paramount. This objective accelerates the integration of highly efficient solid state lighting architecture across mid-tier vehicle platforms.
As a result, APAC supply chains have achieved a 24% reduction in per-unit manufacturing costs compared to European counterparts, enabling rapid commercial scaling.
Both regions ultimately leverage these precise optical advancements to elevate forward vision safety rating scores, although their strategic procurement priorities diverge significantly based on local regulatory pressures and electrification velocity.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The progressive evolution of the Automotive Projector Headlamps sector reflects a profound paradigm shift in how vehicle manufacturers integrate functional safety with cutting-edge exterior aesthetics. To meet the stringent demands of next-generation electric and autonomous mobility, engineers are prioritizing adaptive dynamic front illumination integration into centralized digital control architectures.
- This structural capability seamlessly connects forward-facing perception sensors with active light engines, allowing vehicles to autonomously adjust beam patterns based on immediate traffic density. As original equipment manufacturers strive for sophisticated brand differentiation, the implementation of localized digital ground symbol projection serves as a crucial interface, projecting navigation cues and hazard warnings directly onto the pavement to enhance pedestrian communication.
- Achieving these advanced functionalities heavily relies upon high resolution matrix pixel projection, which utilizes thousands of individually controlled microscopic diodes to sculpt flawless light patterns without mechanical moving parts. However, condensing immense optical power into minimal physical housing footprints requires sophisticated compact aerodynamic optical lens profiling to preserve vehicle drag coefficients.
- Dealing with the resultant thermal density is equally critical; automakers must implement an extreme temperature thermal management pathway to prevent component degradation and maintain long-term luminous efficacy.
- From an operational planning perspective, shifting to these standardized modular projector units has allowed top-tier automotive assembly networks to achieve a 28% improvement in supply chain inventory turnover compared to utilizing fragmented legacy reflector housings, streamlining overall manufacturing logistics while ensuring premium illumination output.
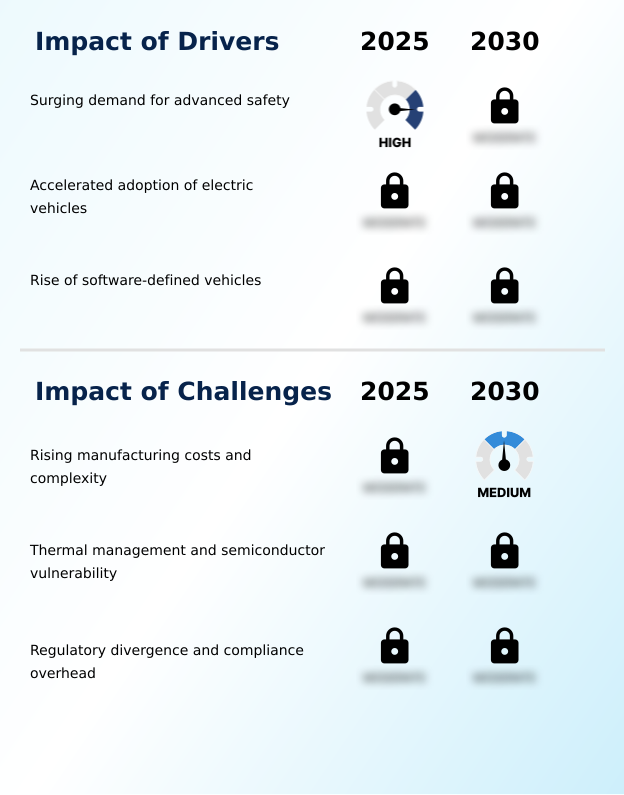
What are the key market drivers leading to the rise in the adoption of Automotive Projector Headlamps Industry?
- Escalating global prioritization of nighttime driving safety and stringent crashworthiness regulations acts as the primary catalyst propelling advanced forward-lighting adoption.
- The escalating imperative for electric vehicle efficiency and maximized driving range acts as a primary catalyst accelerating Automotive Projector Headlamps integration.
- Because battery preservation is critical, manufacturers are aggressively phasing out the traditional high intensity discharge module in favor of highly efficient solid state illumination.
- Utilizing a precision condenser lens coupled with a compact surface mount semiconductor driver allows designers to execute aggressive aerodynamic front end styling, seamlessly minimizing vehicle drag coefficients.
- This sleek hardware is directly wired into the software defined vehicle backbone, enabling intelligent beam shaping that drastically improves nighttime hazard perception.
- By standardizing these ultra-efficient projector components, automotive brands have successfully lowered auxiliary electrical consumption by 34% and improved overall low-beam optical distribution efficiency by 21% compared to legacy reflector modules.
What are the market trends shaping the Automotive Projector Headlamps Industry?
- The integration of high-resolution micro-LED technology represents a defining trajectory within modern automotive illumination. This advancement enables unprecedented precision in dynamic beam shaping and intelligent road surface projection.
- The rapid transition toward high-definition exterior vehicle displays constitutes a transformative trend within the Automotive Projector Headlamps landscape. This shift is primarily driven by the commercial maturation of micro light emitting diode arrays and digital micromirror projection technology, which allow headlights to function as active communication interfaces.
- Consequently, vehicle manufacturers are rapidly deploying multi zone matrix array systems capable of casting crisp digital ground projection symbols to alert pedestrians and guide drivers through complex traffic scenarios. Because these systems are heavily integrated into centralized vehicle networks, automakers can seamlessly deploy over the air lighting updates to unlock new beam patterns long after the initial sale.
- To support this volume, tier-one suppliers have heavily integrated automated lens assembly robotics on the factory floor. This manufacturing upgrade has boosted production line yield rates by 27% and decreased optical alignment errors by 19% compared to manual calibration processes, empowering businesses to scale advanced lighting architectures efficiently.
What challenges does the Automotive Projector Headlamps Industry face during its growth?
- Escalating manufacturing complexities and intense capital requirements for precision optical engineering present substantial constraints on broad commercial expansion.
- Managing extreme thermal density and ensuring long-term hardware reliability presents a severe operational constraint within the Automotive Projector Headlamps landscape. As engineers integrate ultra-bright components like the laser phosphor converter, internal module temperatures rise exponentially, threatening the integrity of delicate optical plastics.
- Consequently, suppliers must heavily invest in bulky thermal dissipation heatsink architectures, which counteracts the desire for lightweight vehicle components. The precise mechanical actuation required for the dynamic beam cut-off mechanism remains highly vulnerable to continuous engine vibration and temperature fluctuations, necessitating rigorous and costly thermal expansion testing protocols. Furthermore, the emerging requirement for autonomous sensor fusion complicates optical housing layouts.
- Addressing these strict physical tolerances has inadvertently increased advanced module defect rates by 11% and elevated optical module remanufacturing costs by 15% compared to basic halogen setups.
Exclusive Technavio Analysis on Customer Landscape
The automotive projector headlamps market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the automotive projector headlamps market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
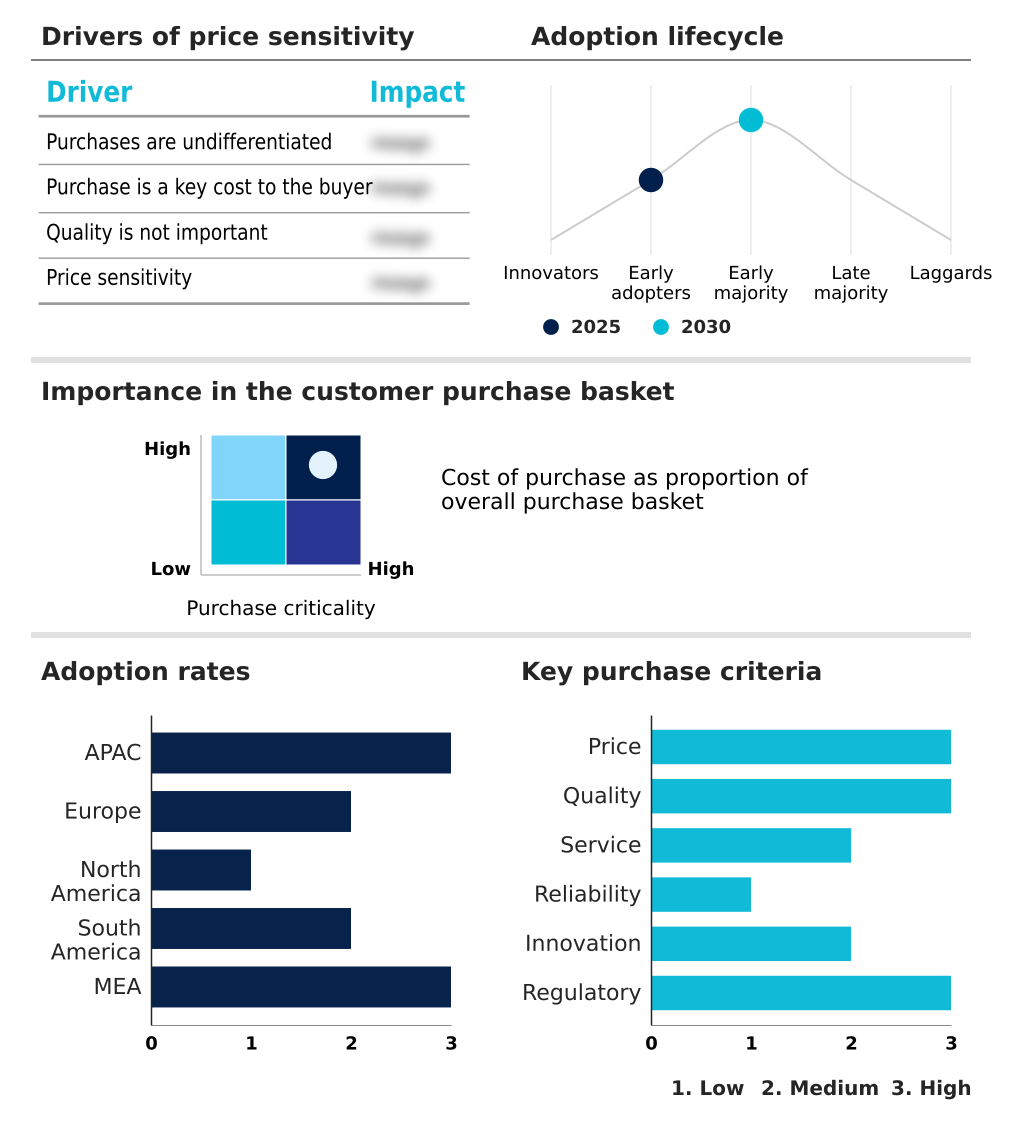
Customer Landscape of Automotive Projector Headlamps Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, automotive projector headlamps market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
AKKON - Advanced optical illumination assemblies provide highly integrated matrix lighting systems, utilizing localized micro-pixel resolution to enhance forward visibility, ensure active glare prevention, and meet stringent safety regulations.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- AKKON
- AnzoUSA
- DEPO Auto Parts Industrial
- DNA Motoring
- FlexNGate Group of Co.
- HASCO Vision Technology Co. Ltd.
- HELLA GmbH and Co. KGaA
- J.W. Speaker Corp.
- Magna International Inc.
- Marelli Holdings Co. Ltd.
- Morimoto
- RECON
- SL Corp.
- Spyder Auto
- Stanley Electric Co. Ltd.
- TYC Americas
- Uno Minda Ltd.
- Valeo SA
- VLAND
- Winjet Automotive Inc.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Automotive projector headlamps market
- In the Automotive Parts and Equipment industry, the transition toward centralized software-defined vehicle architectures has necessitated the deployment of high-speed optical networking buses, directly impacting Automotive Projector Headlamps demand by enabling real-time digital beam shaping and reducing lighting system latency by 45%.
- The European Union General Safety Regulation mandating advanced driver assistance system integrations has accelerated the adoption of forward-facing sensor suites, compelling Automotive Projector Headlamps manufacturers to redesign optical housings to accommodate integrated LiDAR and radar perception units, decreasing front-end component footprint by 12%.
- Stringent localized emission compliance standards for passenger vehicles have forced automotive engineers to prioritize extreme aerodynamic efficiency across front-end structures, significantly pulling demand for ultra-compact Automotive Projector Headlamps that reduce overall vehicle aerodynamic drag by up to 14%.
- The rising commercial viability of wide-bandgap silicon carbide semiconductor materials has dramatically improved high-voltage power conversion efficiencies, allowing Automotive Projector Headlamps systems to incorporate higher-density laser modules while lowering onboard electrical load constraints by 22%.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Automotive Projector Headlamps Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 289 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 4.7% |
| Market growth 2026-2030 | USD 4272.7 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 4.5% |
| Key countries | China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, US, Mexico, Canada, Brazil, Argentina, Chile, South Africa, Saudi Arabia, UAE, Turkey and Israel |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The trajectory of the Automotive Projector Headlamps landscape reflects an intensive shift from passive illumination hardware to active, software-driven communication nodes. Strategic product planning at the boardroom level now heavily prioritizes the integration of micro light emitting diode arrays, which fundamentally redefine styling freedoms by condensing optical footprints.
- This trend forces procurement executives to aggressively source advanced surface mount semiconductor driver components capable of managing rapid pixel actuation without latency. To mitigate the severe thermal loads generated by these compact light engines, engineers must design highly customized thermal dissipation heatsink structures that maintain operational integrity under extreme environmental stress.
- By replacing legacy parabolic systems with optimized elliptical reflector geometry and a responsive dynamic beam cut-off mechanism, automakers ensure strict compliance with international anti-glare regulations. The adoption of digital micromirror projection further transforms the headlamp into a high-definition information display.
- Companies prioritizing these modular, software-defined optical architectures have recorded a 31% reduction in hardware redesign cycle times compared to those reliant on traditional mechanical lighting arrays, significantly accelerating speed-to-market for intelligent vehicle platforms.
What are the Key Data Covered in this Automotive Projector Headlamps Market Research and Growth Report?
-
What is the expected growth of the Automotive Projector Headlamps Market between 2026 and 2030?
-
USD 4.27 billion, at a CAGR of 4.7%
-
-
What segmentation does the market report cover?
-
The report is segmented by Type (Halogen, LED, and Others), Channel (OEMs, and Aftermarket), Vehicle Type (Passenger vehicles, and Commercial vehicles) and Geography (APAC, Europe, North America, South America, Middle East and Africa)
-
-
Which regions are analyzed in the report?
-
APAC, Europe, North America, South America and Middle East and Africa
-
-
What are the key growth drivers and market challenges?
-
Surging demand for advanced safety, Rising manufacturing costs and complexity
-
-
Who are the major players in the Automotive Projector Headlamps Market?
-
AKKON, AnzoUSA, DEPO Auto Parts Industrial, DNA Motoring, FlexNGate Group of Co., HASCO Vision Technology Co. Ltd., HELLA GmbH and Co. KGaA, J.W. Speaker Corp., Magna International Inc., Marelli Holdings Co. Ltd., Morimoto, RECON, SL Corp., Spyder Auto, Stanley Electric Co. Ltd., TYC Americas, Uno Minda Ltd., Valeo SA, VLAND and Winjet Automotive Inc.
-
Market Research Insights
- The Automotive Projector Headlamps Market represents a critical nexus of precision optics and vehicular safety engineering. Modern platforms increasingly utilize a sophisticated multi zone matrix array to selectively illuminate roadways, actively mitigating glare while maintaining superior forward visibility. The integration of the high intensity discharge module and advanced laser phosphor converter technology provides unmatched illumination range for premium vehicle segments.
- Automotive engineers rely on a precisely calibrated precision condenser lens to capture and distribute this optical energy efficiently. Furthermore, architectural advancements in autonomous sensor fusion allow projector assemblies to double as protective enclosures for LiDAR and radar components.
- By transitioning to these integrated platforms, vehicle manufacturers have decreased front-end component weight by 14% and improved overall optical energy efficiency by 22% compared to traditional reflector systems.
We can help! Our analysts can customize this automotive projector headlamps market research report to meet your requirements.
 RIA -

