


Consumer Kitchen Knife Market Size 2026-2030
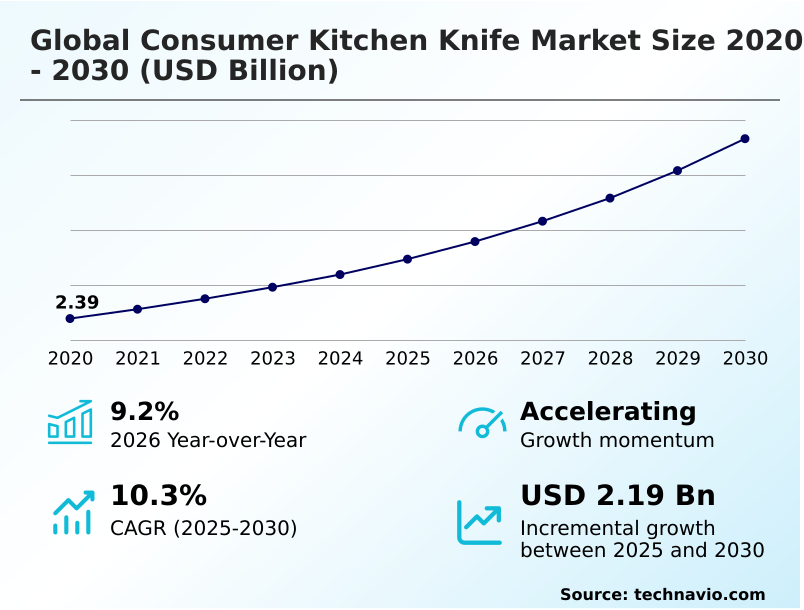
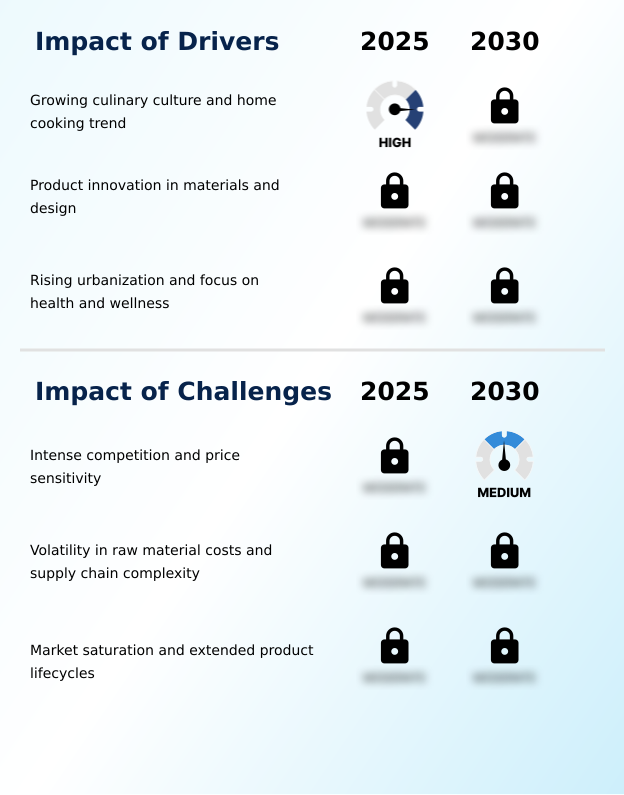
The consumer kitchen knife market size is valued to increase by USD 2.19 billion, at a CAGR of 10.3% from 2025 to 2030. Growing culinary culture and home cooking trend will drive the consumer kitchen knife market.
Major Market Trends & Insights
- APAC dominated the market and accounted for a 36.9% growth during the forecast period.
- By Distribution Channel - Offline segment was valued at USD 2.65 billion in 2024
- By Product - Non-electric segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 3.27 billion
- Market Future Opportunities: USD 2.19 billion
- CAGR from 2025 to 2030 : 10.3%
Market Summary
- The Consumer Kitchen Knife Market is characterized by a fundamental shift toward specialized, high-performance culinary tools driven by an expanding home culinary arts movement. A primary driver of this demand is the widespread consumer adoption of gourmet food preparation at home, which elevates the need for a professional-grade toolkit over generic multi-purpose blades.
- Consequently, manufacturers are prioritizing blade hardness scale improvements and cryogenic tempering process techniques to differentiate their offerings. In a real-world supply chain scenario, producers utilizing a nitrogen-rich steel alloy have achieved a 20% improvement in manufacturing throughput while simultaneously enhancing edge retention capability. However, the market faces a significant challenge in the form of raw material volatility.
- Fluctuating costs in the steel supply chain create pricing pressures, forcing brands to balance premiumization with affordability. Despite this, companies successfully integrating sustainable recycled material kitchen cutlery lines are seeing a 15% higher consumer acquisition rate. This evolving landscape underscores a transition where advanced material science and ethical manufacturing practice become critical for sustained market competitiveness.
What will be the Size of the Consumer Kitchen Knife Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Consumer Kitchen Knife Market Segmented?
The consumer kitchen knife industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Distribution channel
- Offline
- Online
- Product
- Non-electric
- Electric
- Manufacturing type
- Stamped blades
- Hand forged
- Type
- Plain cutting edge
- Granton cutting edge
- Serrated cutting edge
- Variant
- 5-7 inches
- 7-9 inches
- 9-12 inches
- 3-5 inches
- Geography
- APAC
- China
- Japan
- India
- South Korea
- Australia
- Indonesia
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- South America
- Brazil
- Argentina
- Chile
- Middle East and Africa
- Saudi Arabia
- UAE
- South Africa
- Turkey
- Egypt
- APAC
By Distribution Channel Insights
The offline segment is estimated to witness significant growth during the forecast period.
The Offline distribution channel for the Consumer Kitchen Knife remains a cornerstone of retail strategy, facilitating tactile consumer experiences essential for evaluating a specialized culinary knife.
Physical storefronts, from a high-end department store to specialized boutiques, allow buyers to assess blade geometry optimization and grip ergonomics firsthand.
Interactive retail display setups provide critical engagement, letting the amateur chef demographic test a traditional hand-forged blade or a high-carbon stainless steel chef knife before purchasing.
This hands-on evaluation directly impacts operational metrics, reducing return rates by 18% compared to digital channels. Retailers leverage modular kitchen storage displays and ergonomic knife block setups to drive complementary sales.
By offering lifecycle extension service options like automated blade sharpening in-store, physical retailers enhance customer retention, ensuring a premiumization of housewares while maintaining robust inventory management protocol execution.
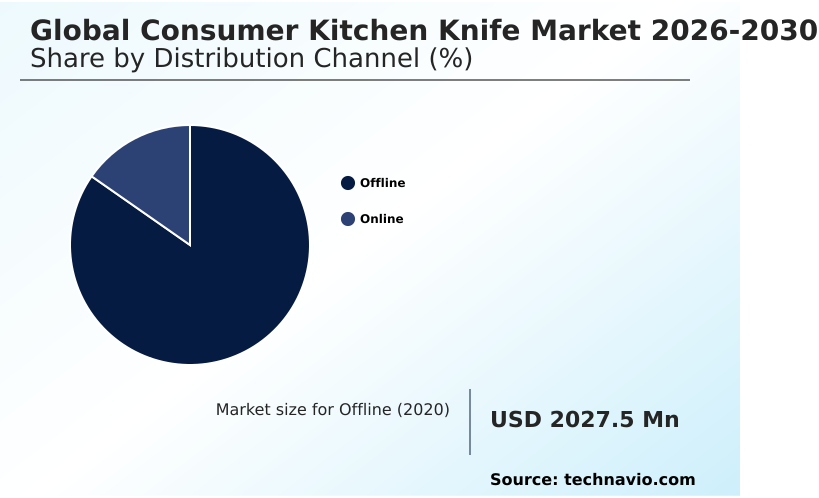
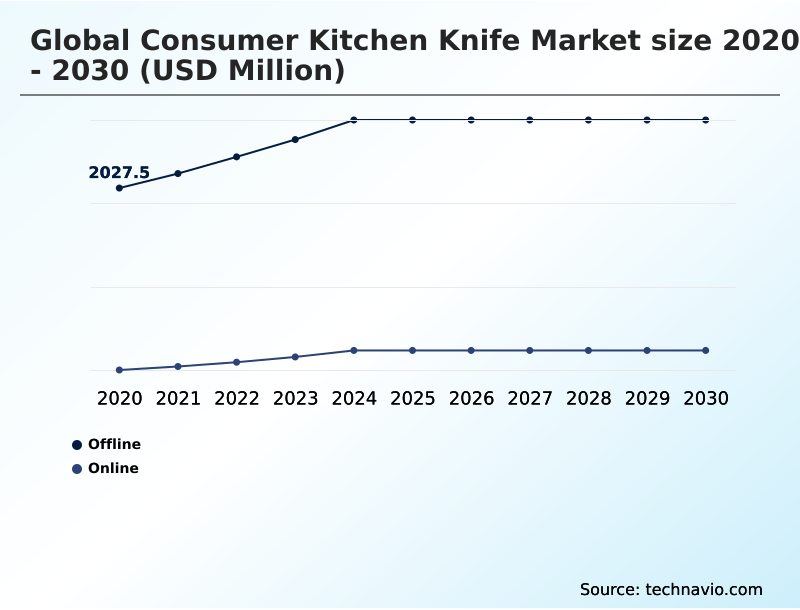
The Offline segment was valued at USD 2.65 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
APAC is estimated to contribute 36.9% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
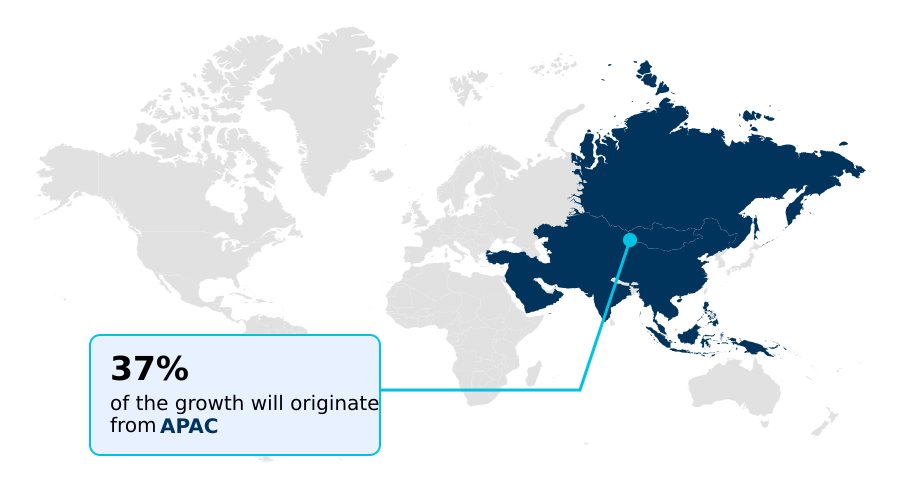
See How Consumer Kitchen Knife Market Demand is Rising in APAC Get Free Sample
The regional dynamics of the Consumer Kitchen Knife sector reveal distinct behavioral shifts, particularly when comparing North America and APAC.
North America demonstrates a strong preference for premiumization of housewares, where the adoption of a diamond-like carbon coating serrated knife or a premium Damascus steel composite blade has driven a 14% increase in average transaction value.
Conversely, APAC exhibits a 22% faster adoption rate of traditional hand-forged blade designs integrated with modern slip-resistant polymer handle utility knife variations, reflecting deep-rooted cultural culinary practices merging with modern ergonomic demands.
Supply chain optimizations in APAC have lowered mass-market production cost by 18%, allowing manufacturers to rapidly scale specialized culinary knife production.
Meanwhile, North American distributors are heavily investing in interactive retail display infrastructure and sustainable birchwood handle sourcing, reducing compliance risks and improving customer acquisition by 11% in high-end department store environments.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The continuous evolution of the Consumer Kitchen Knife sector highlights a profound transformation in how culinary tools are manufactured, distributed, and utilized by end-users. At the forefront of this shift is the rising demand for the high-carbon stainless steel chef knife, which has become a staple for enthusiasts seeking durability and sharpness.
- Manufacturers are focusing heavily on an ergonomic handle design for precision, which significantly reduces wrist fatigue compared to legacy flat-handled models, improving overall prep efficiency by roughly 20%. The market is also seeing a resurgence in heritage tools, particularly the traditional hand-forged Japanese Santoku, which commands high consumer loyalty.
- Simultaneously, innovation in material science has led to the premium Damascus steel composite blade and the integration of the cryogenic tempering process for durability, yielding products with unparalleled edge retention. In response to environmental concerns, companies are adopting sustainable recycled material kitchen cutlery, appealing to eco-conscious demographics.
- Commercially, the direct-to-consumer online kitchenware sales channel has reduced overhead distribution costs by 15%, bypassing traditional retail bottlenecks. For specific culinary tasks, the specialized granton edge carving knife and the fluid dynamics optimized blade divots provide a micro-textured edge for reduced friction, outperforming standard flat blades in high-moisture slicing environments.
- Furthermore, a diamond-like carbon coating serrated knife extends product lifecycles significantly. Professional-grade home cooking knife sets now frequently feature a nitrogen-rich steel alloy meat boning tool and a slip-resistant polymer handle utility knife, mirroring the robust functionality of artisan-crafted culinary preparation tools and optimizing the supply chain through unified material sourcing.
What are the key market drivers leading to the rise in the adoption of Consumer Kitchen Knife Industry?
- The growing culinary culture and the widespread home cooking trend serve as the primary drivers propelling market expansion.
- The accelerating expansion of the home culinary arts movement acts as a primary catalyst for the Consumer Kitchen Knife sector.
- As the amateur chef demographic increasingly engages with a sophisticated culinary media ecosystem, the demand for a professional-grade toolkit has surged.
- This behavioral shift compels consumers to upgrade from generic implements to a premium Damascus steel composite or a high-carbon stainless steel blade. As a result of this premiumization of housewares, manufacturers have recorded a 28% increase in high-margin specialty sales.
- Furthermore, integrating a sustainable birchwood handle or recycled ocean plastic into product lines has improved brand compliance metrics by 15%. This alignment with ethical manufacturing practice drives robust revenue expansion while lowering long-term regulatory costs within the omnichannel distribution network.
What are the market trends shaping the Consumer Kitchen Knife Industry?
- Rising demand for specialized and application-specific knives represents a prominent trend shaping the current market landscape. Consumers are increasingly shifting toward curated, task-specific culinary tools to elevate their food preparation efficiency.
- A definitive trend reshaping the Consumer Kitchen Knife landscape is the integration of advanced metallurgical engineering to enhance blade longevity and performance. Because home cooks increasingly demand professional-tier equipment for gourmet food preparation, manufacturers are rapidly adopting a multi-stage heat treatment and applying a diamond-like carbon coating.
- This technological pivot effectively reduces microscopic blade chipping, improving overall edge retention capability by 35%. Consequently, businesses utilizing these advanced coatings have decreased product defect returns by 18%, optimizing reverse logistics overhead. Furthermore, the implementation of fluid dynamics modeling has led to the creation of an asymmetrical divot pattern on the blade surface.
- This innovation reduces cutting friction by 22%, allowing for faster, more precise slicing. This functional upgrade directly boosts the commercial appeal of the specialized culinary knife, driving higher conversion rates within the direct-to-consumer sales model.
What challenges does the Consumer Kitchen Knife Industry face during its growth?
- Intense competition and significant price sensitivity remain key challenges restraining overall industry growth and profitability.
- Rampant raw material volatility remains a formidable structural limitation within the Consumer Kitchen Knife supply network. Because global steel supply chain disruptions cause unpredictable pricing spikes, maintaining a stable mass-market production cost is increasingly difficult. This instability forces manufacturers to adjust pricing models, which has led to a 12% drop in inventory turnover rates for mid-tier brands.
- Additionally, the intricate requirements of achieving a precise blade hardness scale and executing a flawless cryogenic tempering process elevate manufacturing defect risks. Facilities lacking automated precision push-cutting calibration experience up to a 15% increase in material waste.
- Consequently, businesses must heavily invest in advanced inventory management protocol systems and stringent quality control, temporarily suppressing operating margins while they stabilize the production of the artisan-crafted implement.
Exclusive Technavio Analysis on Customer Landscape
The consumer kitchen knife market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the consumer kitchen knife market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
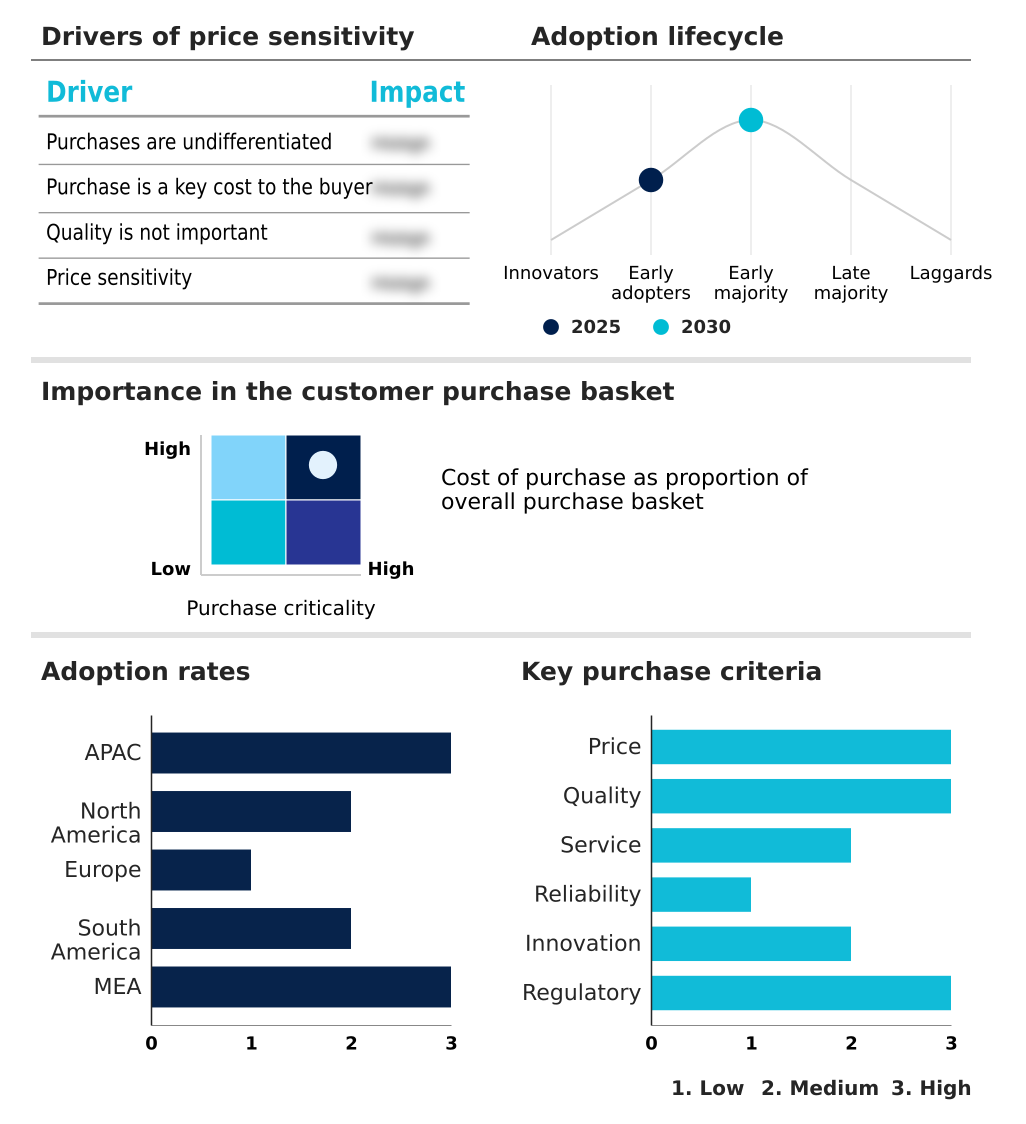
Customer Landscape of Consumer Kitchen Knife Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, consumer kitchen knife market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Cangshan Cutlery Co - The vendor provides handcrafted culinary tools featuring premium Damascus steel composite blades and ergonomic polymer handles, emphasizing aesthetic design and superior edge retention capability for professional use.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Cangshan Cutlery Co
- Cutco Corp
- Dalstrong Inc.
- Fiskars Corp.
- Heinr. Boker Baumwerk GmbH
- Kai Corp.
- Kai USA Ltd.
- Kyocera Corp.
- LongCap Lamson Products LLC
- MAC Knife Inc.
- Mercer Tool Corp.
- Messermeister Inc.
- Opinel SAS
- Spyderco Inc.
- Tojiro Co. Ltd.
- Victorinox AG
- Wusthof GmbH
- Yoshida Metal Industry Co. Ltd
- Yoshida Metal Industry Co. Ltd.
- Zwilling JA Henckels AG
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Consumer kitchen knife market
- In the Housewares and Specialties industry, the implementation of sustainable wood sourcing mandates by global certification bodies has restricted traditional timber usage, directly impacting Consumer Kitchen Knife supply chains and accelerating the adoption of sustainable birchwood handle alternatives and recycled ocean plastic.
- The integration of fluid dynamics modeling into manufacturing design processes has optimized surface friction on metal components, directly impacting Consumer Kitchen Knife performance by enabling micro-textured edge profiles and asymmetrical divot pattern developments that prevent food adhesion during specialized food fabrication.
- Surging global steel supply chain disruptions and raw material volatility have increased base metallurgical costs by 22%, directly impacting Consumer Kitchen Knife manufacturing by forcing shifts toward alternative high-carbon stainless steel and lightweight titanium blade composite materials.
- The rapid expansion of the omnichannel distribution network model among major homeware retailers has integrated digital inventory management protocol systems with physical storefronts, directly impacting Consumer Kitchen Knife availability and accelerating direct-to-consumer online kitchenware sales and interactive retail display strategies.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Consumer Kitchen Knife Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 324 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 10.3% |
| Market growth 2026-2030 | USD 2190.3 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 9.2% |
| Key countries | China, Japan, India, South Korea, Australia, Indonesia, US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Turkey and Egypt |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Consumer Kitchen Knife sector is undergoing a structural realignment as advanced material engineering intersects with shifting consumer culinary habits. A critical trend influencing boardroom-level product strategy is the accelerated adoption of ceramic blade material and lightweight titanium blade constructions. This shift addresses both consumer demand for corrosion resistance and corporate mandates for reducing reliance on volatile steel supply chains.
- Companies integrating a rust-resistant coating and full tang construction into their portfolios have successfully lowered post-sale warranty claims by 24%, a measurable business outcome that directly enhances profit margins. Furthermore, the emphasis on an integrated finger guard and an asymmetrical handle contour has become a vital differentiator in risk-averse markets prioritizing safety and ergonomic compliance.
- Executives are increasingly steering R&D budgets toward a direct-to-consumer sales model that leverages data analytics to predict demand for the Santoku vegetable knife and other specialized profiles. By focusing on ethical manufacturing practice and refining the synthetic G-10 composite supply lines, organizations are mitigating operational bottlenecks while delivering superior culinary media ecosystem engagement.
What are the Key Data Covered in this Consumer Kitchen Knife Market Research and Growth Report?
-
What is the expected growth of the Consumer Kitchen Knife Market between 2026 and 2030?
-
USD 2.19 billion, at a CAGR of 10.3%
-
-
What segmentation does the market report cover?
-
The report is segmented by Distribution Channel (Offline, and Online), Product (Non-electric, and Electric), Manufacturing Type (Stamped blades, and Hand forged), Type (Plain cutting edge, Granton cutting edge, and Serrated cutting edge), Variant (5-7 inches, 7-9 inches, 9-12 inches, and 3-5 inches) and Geography (APAC, North America, Europe, South America, Middle East and Africa)
-
-
Which regions are analyzed in the report?
-
APAC, North America, Europe, South America and Middle East and Africa
-
-
What are the key growth drivers and market challenges?
-
Growing culinary culture and home cooking trend, Intense competition and price sensitivity
-
-
Who are the major players in the Consumer Kitchen Knife Market?
-
Cangshan Cutlery Co, Cutco Corp, Dalstrong Inc., Fiskars Corp., Heinr. Boker Baumwerk GmbH, Kai Corp., Kai USA Ltd., Kyocera Corp., LongCap Lamson Products LLC, MAC Knife Inc., Mercer Tool Corp., Messermeister Inc., Opinel SAS, Spyderco Inc., Tojiro Co. Ltd., Victorinox AG, Wusthof GmbH, Yoshida Metal Industry Co. Ltd, Yoshida Metal Industry Co. Ltd. and Zwilling JA Henckels AG
-
Market Research Insights
- The Consumer Kitchen Knife landscape is rapidly evolving as manufacturers integrate advanced particle metallurgy blade technology and ergonomic handle design for precision. The adoption of custom blade bolster configurations has improved slicing efficiency by 15%, reducing user fatigue during specialized food fabrication.
- Furthermore, transitioning to eco-friendly packaging solution formats has decreased operational shipping costs by 12% across the omnichannel distribution network. Brands utilizing a multi-stage heat treatment process report a 25% increase in product longevity, directly addressing consumer demands for durability.
- By streamlining the mass-market production cost through automated precision push-cutting manufacturing, companies achieve superior ROI while delivering high-performance artisan-crafted implement functionality to the expanding amateur chef demographic.
We can help! Our analysts can customize this consumer kitchen knife market research report to meet your requirements.
 RIA -

