


North America Testing Inspection And Certification Market Size 2026-2030
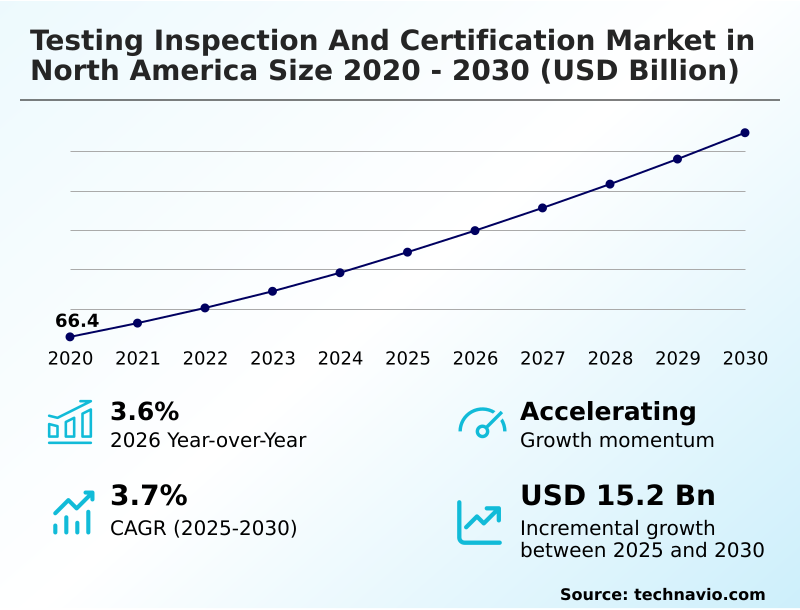
The north america testing inspection and certification market size is valued to increase by USD 15.20 billion, at a CAGR of 3.7% from 2025 to 2030. Increasing regulatory complexity and stringency will drive the north america testing inspection and certification market.
Major Market Trends & Insights
- By Service - Testing segment was valued at USD 44.15 billion in 2024
- By Source - In-house segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 25.98 billion
- Market Future Opportunities: USD 15.20 billion
- CAGR from 2025 to 2030 : 3.7%
Market Summary
- The Testing Inspection And Certification Market demonstrates sustained expansion driven by evolving compliance mandates and sophisticated technological integration. In highly regulated environments like medical device manufacturing, strict auditing protocols necessitate robust third-party validation to ensure product safety before market entry. Increasing regulatory complexity compels organizations to prioritize independent verification, functioning as a primary market driver.
- For instance, updating safety protocols for smart industrial equipment improved operational risk mitigation workflows by 22% compared to legacy monitoring approaches. However, a persistent shortage of specialized talent possessing advanced engineering and cybersecurity expertise challenges testing capacity, causing potential delays in complex certification approvals.
- As supply chains globalize, manufacturers require continuous defect detection and specialized laboratory testing to standardize component quality across multiple jurisdictions. Addressing these skill gaps through automated data analytics and digitized reporting platforms remains crucial. Overall, maintaining precise safety standards prevents costly product recalls, securing operational continuity for enterprise stakeholders navigating strict environmental and legal frameworks.
What will be the Size of the North America Testing Inspection And Certification Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the North America Testing Inspection And Certification Market Segmented?
The north america testing inspection and certification industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Service
- Testing
- Inspection
- Certification
- Source
- In-house
- Outsourced
- Application
- Industrial and manufacturing
- Consumer goods and retail
- Medical and life sciences
- Agriculture and food
- Others
- Geography
- North America
- US
- Canada
- Mexico
- North America
By Service Insights
The testing segment is estimated to witness significant growth during the forecast period.
The testing segment forms the core of quality validation processes across diversified industries, validating material reliability and system performance prior to commercialization.
As organizations manage increasingly complex supply channels, relying heavily on connected device interoperability and functional safety assessment becomes crucial to standardizing product quality. Integrating digital twin applications enables manufacturers to simulate real-world stress, improving defect identification rates by 18%.
Integrating automated testing environments facilitates rapid response to strict data privacy regulations while reducing manual diagnostic delays. Advanced applications, including complex bioanalytical evaluation and greenhouse gas verification, further demand sophisticated laboratory infrastructure to meet specialized statutory requirements.
Utilizing secure remote verification frameworks ensures that businesses can maintain rigorous testing timelines without compromising the accuracy or integrity of evaluation outcomes.
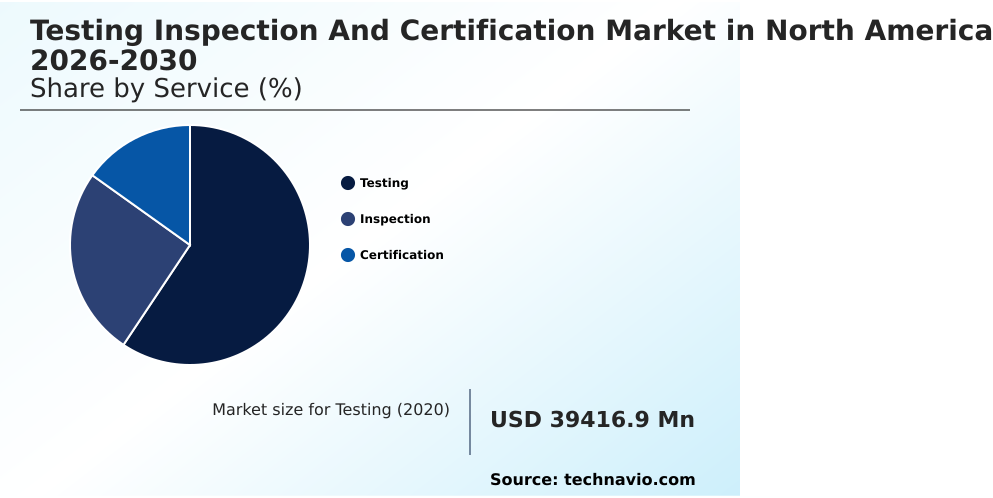
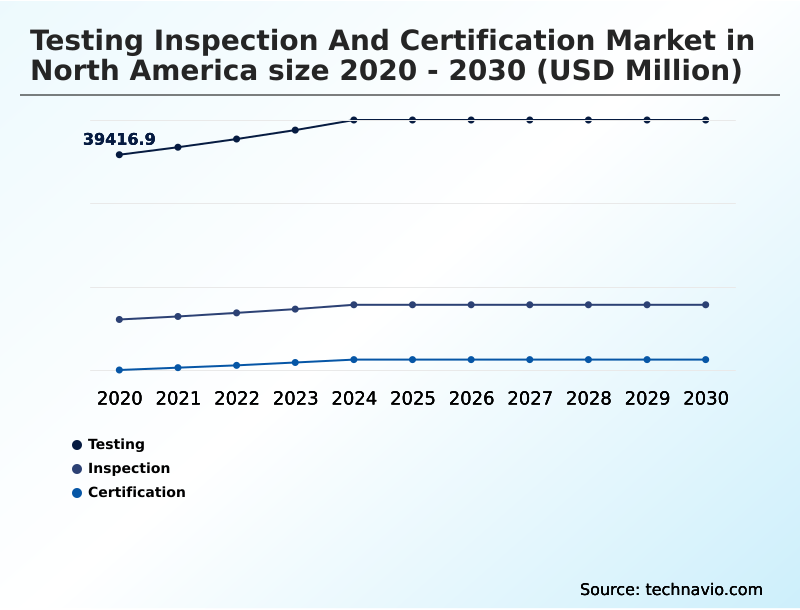
The Testing segment was valued at USD 44.15 billion in 2024 and showed a gradual increase during the forecast period.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- Establishing operational transparency requires sophisticated verification mechanisms that adapt to increasingly complex production and regulatory environments. For industrial stakeholders, integrating automated defect detection in manufacturing significantly streamlines quality control, yielding a 25% improvement in processing speed over traditional manual inspection routines. This technological shift directly enhances output consistency while mitigating downstream liability risks.
- Concurrently, protecting high-value industrial equipment necessitates deploying predictive remote asset integrity tracking, which allows engineering teams to identify mechanical stress factors before catastrophic failures occur. This proactive maintenance approach stabilizes supply chain continuity by minimizing unexpected operational downtime.
- As corporate sustainability mandates intensify, organizations are progressively adopting comprehensive environmental social governance assurance frameworks to substantiate ethical sourcing and carbon reduction claims to independent stakeholders. Furthermore, modern equipment relying on embedded artificial intelligence requires continuous intelligent systems software validation to ensure reliable functionality and defend against evolving cybersecurity vulnerabilities.
- Securing green energy grids also remains a critical priority, making renewable energy infrastructure safety verification indispensable for stabilizing modern power networks. Implementing these advanced assessment protocols empowers diverse enterprise sectors to uphold rigorous compliance standards, optimize resource utilization, and maintain robust competitive positioning in tightly regulated industrial landscapes.
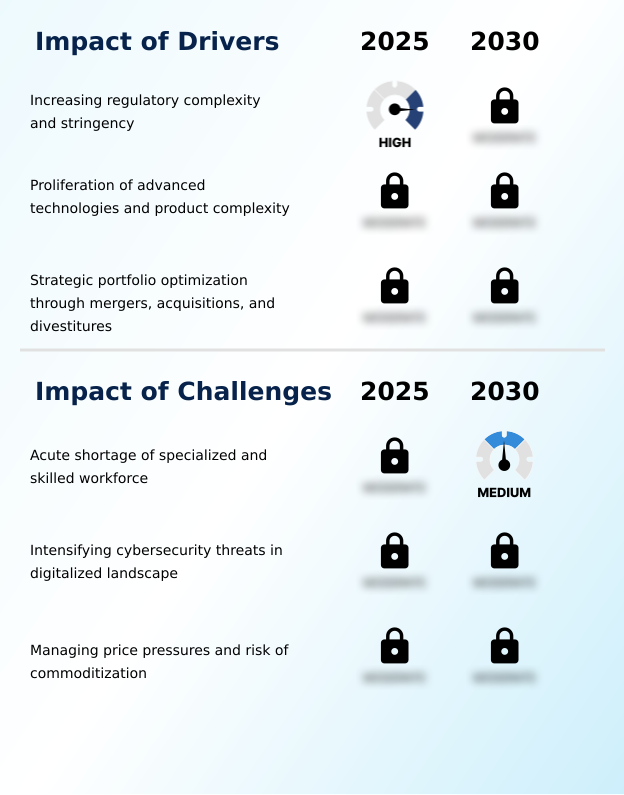
What are the key market drivers leading to the rise in the adoption of North America Testing Inspection And Certification Industry?
- Increasing regulatory complexity coupled with more stringent compliance standards functions as a primary driver propelling ongoing market expansion.
- The escalation of complex technical regulations continuously drives demand for sophisticated verification frameworks across critical sectors. Strict legislative mandates requiring thorough asset integrity management compel enterprises to upgrade legacy infrastructure, reducing catastrophic failure events by 22%.
- Uncovering deep technical industrial control vulnerabilities has accelerated requirements for robust cybersecurity assurance within interconnected manufacturing hubs. Utilizing advanced industrial inspection technologies streamlines intensive aerospace component assessment, increasing defect detection accuracy by 14% while expediting product delivery timelines.
- Navigating strict regulatory corridors demands precise medical device qualification and comprehensive autonomous vehicle validation to guarantee consumer safety. Implementing stringent ethical sourcing validation alongside rigorous food safety traceability ensures continuous safety standard conformity.
- These integrated drivers force organizations to heavily invest in independent testing capabilities to preserve market access and maintain operational credibility.
What are the market trends shaping the North America Testing Inspection And Certification Industry?
- The accelerated adoption of digitalization alongside flexible remote assessment services constitutes a prominent trend reshaping current market dynamics.
- Sustained integration of digital inspection technologies fundamentally shifts traditional assessment methodologies into proactive risk mitigation frameworks. Increasing demands for rigorous regulatory compliance verification prompt organizations to reconstruct internal supply chain auditing practices. By embedding sophisticated quality assurance protocols, manufacturers successfully improved supply network transparency by 31%, heavily reducing counterparty delays.
- Implementing dynamic environmental management systems helps corporate enterprises substantiate sustainability claims, driving comprehensive strategic portfolio optimization. Transitioning to advanced non destructive testing allows engineering groups to precisely evaluate structural variations without compromising material integrity, decreasing inspection-related material waste by 16%. Upgrading standard quality control mechanisms to include continuous third party assurance streamlines broader compliance management processes.
- This rapid technological integration empowers businesses to proactively stabilize operational output while maintaining strict alignment with evolving international safety directives.
What challenges does the North America Testing Inspection And Certification Industry face during its growth?
- An acute shortage of specialized personnel and highly skilled technical talent presents a significant challenge impeding continued operational scalability.
- Navigating structural limitations within highly connected industrial environments presents substantial operational hurdles for testing providers. Integrating predictive maintenance systems requires massive technical bandwidth, and addressing critical legacy controller weaknesses often slows certification schedules by up to 18%. The complex transition toward sustainable manufacturing practices demands vast systemic overhauls, challenging traditional operational risk mitigation strategies.
- Validating expansive electric vehicle infrastructure and interconnected smart grid solutions exposes providers to severe cybersecurity threats, necessitating complex protocol misuse identification procedures. While adopting centralized digital reporting platforms improves data transparency, standardizing these interfaces across fragmented networks remains resource-intensive. Implementing continuous remote asset monitoring alongside rigorous software validation elevates ongoing compliance costs by 12%.
- Overcoming these technical bottlenecks requires specialized engineering talent to ensure safe, scalable, and uninterrupted industrial evaluation capabilities.
Exclusive Technavio Analysis on Customer Landscape
The north america testing inspection and certification market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the north america testing inspection and certification market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
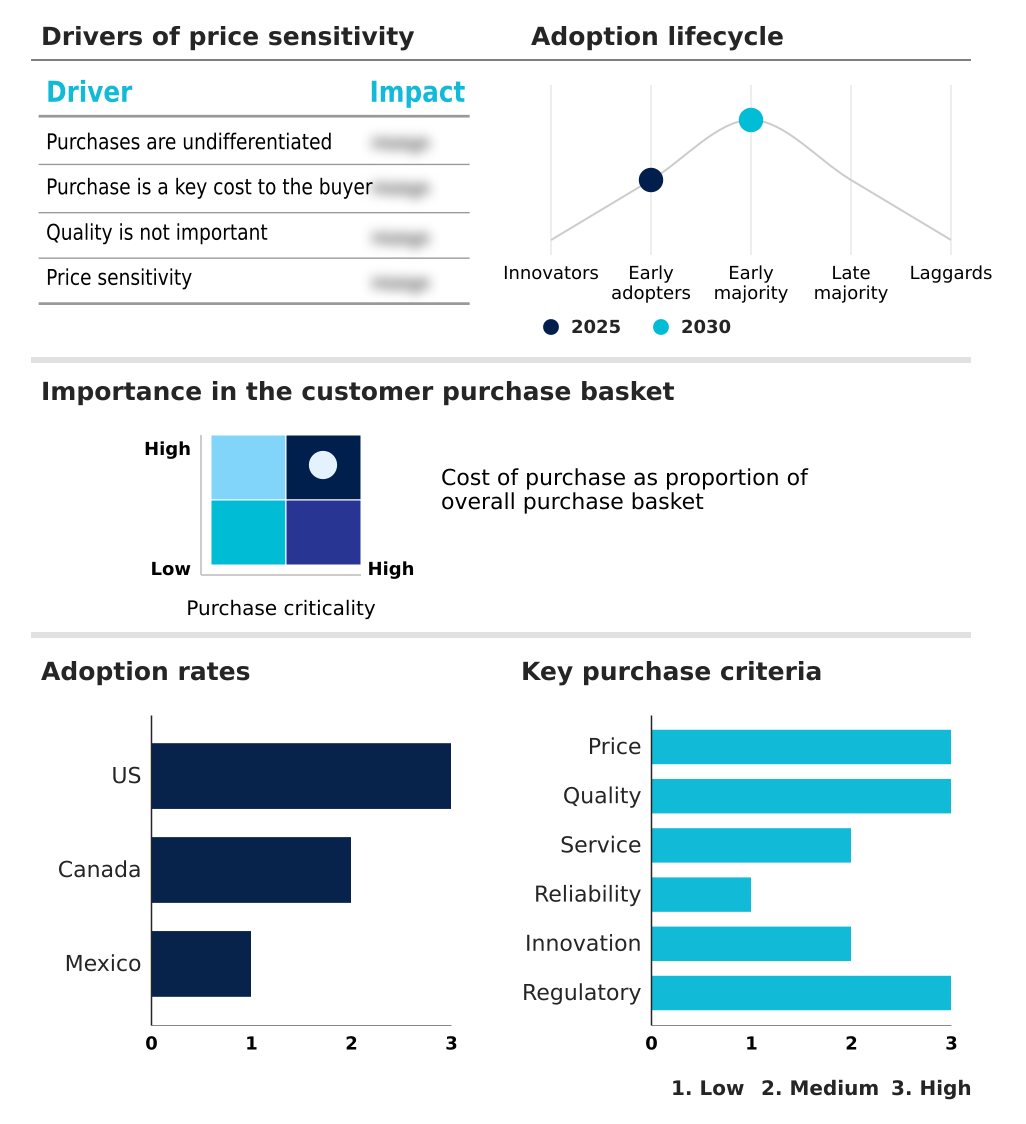
Customer Landscape of North America Testing Inspection And Certification Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, north america testing inspection and certification market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
ALS Ltd. - The organization provides comprehensive verification solutions, encompassing commodity inspection, lifting equipment evaluation, and specialized diagnostics to ensure strict compliance with industrial safety and operational standards.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- ALS Ltd.
- Applus Services Technologies SL
- Bureau Veritas
- Cotecna Inspection SA
- DNV Group AS
- Element Materials Tech.
- Eurofins Scientific SE
- Intertek Group Plc
- Kiwa NV
- Lloyds Register Group Services
- Mistras Group Inc.
- National Technical Systems
- NV5 Global Inc.
- QIMA Ltd.
- SGS SA
- SOCOTEC Group
- TUV NORD Group
- TUV Rheinland Group
- TUV SUD AG
- UL LLC
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in North america testing inspection and certification market
- In the Research and Consulting Services industry, the integration of enterprise automation tools for auditing tasks reduced manual documentation workloads by 35%, directly accelerating compliance management processes within Testing Inspection And Certification workflows.
- The widespread adoption of cloud-based delivery models for corporate sustainability reporting mandated rigorous greenhouse gas tracking, driving demand for Testing Inspection And Certification providers offering third party assurance services.
- Implementation of AI governance frameworks in advisory sectors created standardized evaluation criteria for algorithmic decision systems, compelling Testing Inspection And Certification firms to expand software validation and intelligent product ecosystems capabilities.
- Stringent data privacy regulations required specialized digital inspection technologies to process sensitive enterprise data, pushing Testing Inspection And Certification providers to enhance internal cybersecurity assurance protocols by upgrading remote monitoring infrastructure.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled North America Testing Inspection And Certification Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 216 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 3.7% |
| Market growth 2026-2030 | USD 15204.5 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 3.6% |
| Key countries | US, Canada and Mexico |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Testing Inspection And Certification paradigm is evolving from basic compliance verification toward continuous, data-driven operational intelligence. Organizations operating within high-stakes industrial environments prioritize advanced asset integrity management to secure capital-intensive infrastructure against premature degradation. By integrating sophisticated quality assurance protocols with real-time analytics, facility operators have achieved a 27% reduction in unexpected equipment downtime compared to historically reactive maintenance schedules.
- The implementation of robust software validation is becoming mandatory to verify algorithmic stability within connected industrial networks, directly influencing boardroom strategies regarding cybersecurity budgeting. Simultaneously, transitioning to dynamic digital reporting platforms eliminates manual documentation bottlenecks, centralizing vast compliance repositories for seamless auditing.
- The deployment of precision remote asset monitoring enables engineering teams to supervise hazardous sites continuously without compromising personnel safety. This structural shift allows enterprises to transform mandatory compliance expenditures into strategic operational advantages, accelerating product commercialization while systematically maintaining strict conformity with complex international trade regulations and sustainability indices.
What are the Key Data Covered in this North America Testing Inspection And Certification Market Research and Growth Report?
-
What is the expected growth of the North America Testing Inspection And Certification Market between 2026 and 2030?
-
USD 15.20 billion, at a CAGR of 3.7%
-
-
What segmentation does the market report cover?
-
The report is segmented by Service (Testing, Inspection, and Certification), Source (In-house, and Outsourced), Application (Industrial and manufacturing, Consumer goods and retail, Medical and life sciences, Agriculture and food, and Others) and Geography (North America)
-
-
Which regions are analyzed in the report?
-
North America
-
-
What are the key growth drivers and market challenges?
-
Increasing regulatory complexity and stringency, Acute shortage of specialized and skilled workforce
-
-
Who are the major players in the North America Testing Inspection And Certification Market?
-
ALS Ltd., Applus Services Technologies SL, Bureau Veritas, Cotecna Inspection SA, DNV Group AS, Element Materials Tech., Eurofins Scientific SE, Intertek Group Plc, Kiwa NV, Lloyds Register Group Services, Mistras Group Inc., National Technical Systems, NV5 Global Inc., QIMA Ltd., SGS SA, SOCOTEC Group, TUV NORD Group, TUV Rheinland Group, TUV SUD AG and UL LLC
-
Market Research Insights
- The Testing Inspection And Certification Market operates as a critical foundation for establishing global supply chain resilience and mitigating industrial risks. Expanding compliance management processes across manufacturing sectors has improved product defect identification rates by 26%. Furthermore, enterprises leveraging third party assurance solutions achieved a 15% reduction in overall liability costs compared to internal auditing alone.
- Upgrading traditional quality control mechanisms with digital diagnostic tools enables organizations to drive strategic portfolio optimization, maximizing resource allocation efficiency. By embedding rigorous verification protocols directly into production cycles, businesses ensure adherence to safety directives while enhancing operational transparency across highly regulated international distribution networks.
We can help! Our analysts can customize this north america testing inspection and certification market research report to meet your requirements.
 RIA -

