


Oil And Gas Upstream Equipment Market Size 2026-2030
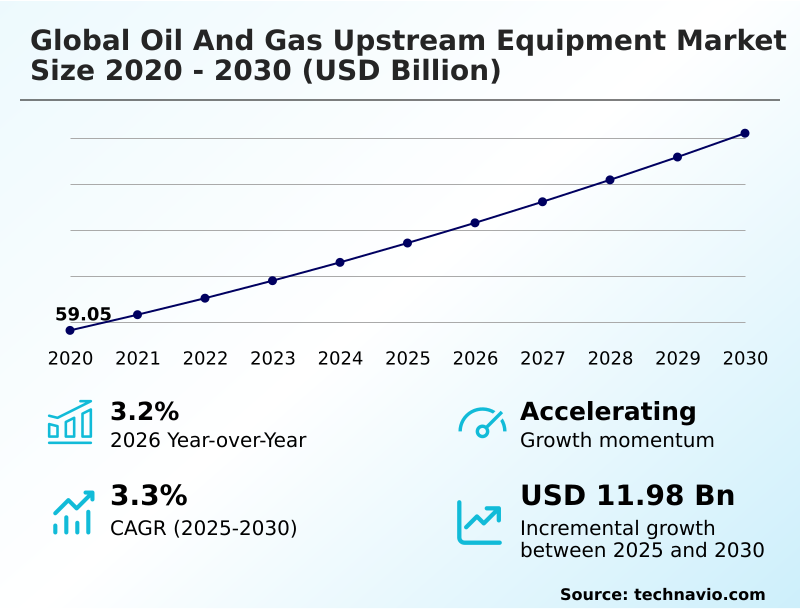
The oil and gas upstream equipment market size is valued to increase by USD 11.98 billion, at a CAGR of 3.3% from 2025 to 2030. Deepwater and ultra-deepwater offshore exploration activities will drive the oil and gas upstream equipment market.
Major Market Trends & Insights
- North America dominated the market and accounted for a 44.5% growth during the forecast period.
- By Application - Exploration and drilling segment was valued at USD 43.47 billion in 2024
- By Deployment - Onshore segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 21.51 billion
- Market Future Opportunities: USD 11.98 billion
- CAGR from 2025 to 2030 : 3.3%
Market Summary
- The Oil And Gas Upstream Equipment market is undergoing a structural transformation driven by the necessity to extract hydrocarbons from increasingly complex geological formations. Operations in deepwater and unconventional shale environments demand highly resilient hardware capable of withstanding extreme pressure and corrosive conditions.
- For instance, the deployment of automated surface drilling rigs integrated with predictive maintenance sensors has allowed operators to improve equipment utilization and reduce unplanned operational downtime by 24% compared to legacy mechanical setups. A primary driver of this market is the aggressive capital allocation toward ultra-deepwater offshore exploration, which guarantees sustained demand for advanced blowout preventers and subsea production architecture.
- Conversely, unpredictable volatility in crude oil commodity pricing poses a significant challenge, often forcing exploration enterprises to defer major capital expenditures on heavy-duty rig packages and completion tools. Consequently, equipment manufacturers are pivoting toward modular, electrified extraction hardware to provide scalable and cost-effective solutions for end-users. These strategic adaptations ensure operational continuity and bolster extraction efficiency across remote field assets.
What will be the Size of the Oil And Gas Upstream Equipment Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Oil And Gas Upstream Equipment Market Segmented?
The oil and gas upstream equipment industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Application
- Exploration and drilling
- Completion and procedure
- Others
- Deployment
- Onshore
- Offshore
- Type
- Drilling equipment
- Production equipment
- Well intervention equipment
- Pressure control equipment
- Others
- Geography
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- The Netherlands
- APAC
- China
- Japan
- India
- South Korea
- Australia
- Indonesia
- South America
- Brazil
- Venezuela
- Argentina
- Middle East and Africa
- Saudi Arabia
- UAE
- Nigeria
- Egypt
- North America
By Application Insights
The exploration and drilling segment is estimated to witness significant growth during the forecast period.
The exploration and drilling phases dictate the foundational infrastructure requirements for onshore and offshore hydrocarbon extraction, functioning as the primary operational gateway for the Oil And Gas Upstream Equipment market.
Advanced deployment of wireline logging tools and intelligent downhole measurement enables operators to achieve precise reservoir navigation in severe geological environments.
By integrating subsea boosting pumps and automated gathering manifolds, upstream operators have reduced non-productive downtime by 22% during complex well construction.
Operations in high-salinity and extreme pressure zones heavily rely on corrosion resistant alloy tubing and multiphase pumping infrastructure to maintain wellbore integrity management. Furthermore, the strategic application of coiled tubing systems and hydraulic workover units facilitates highly efficient lateral interventions.
This structural segmentation allows extraction companies to optimize hardware procurement and deploy specialized equipment suites capable of managing extreme hydrostatic pressure.
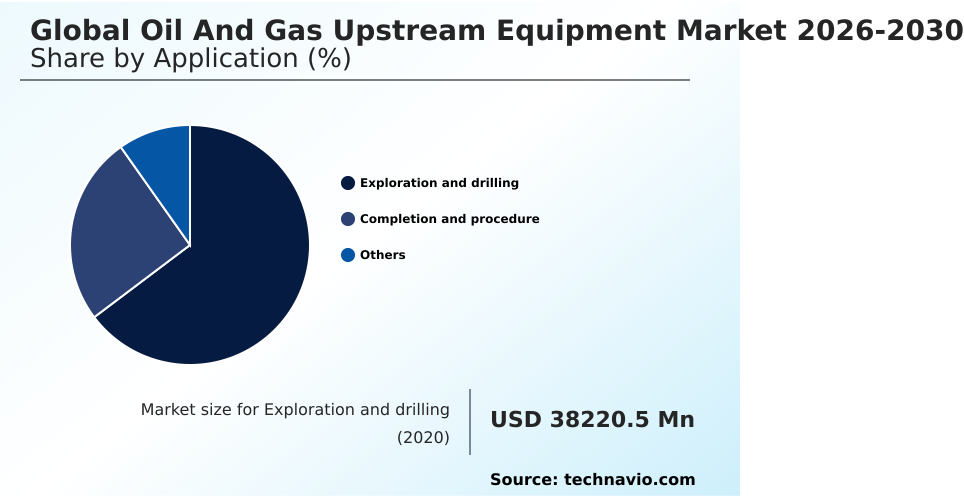
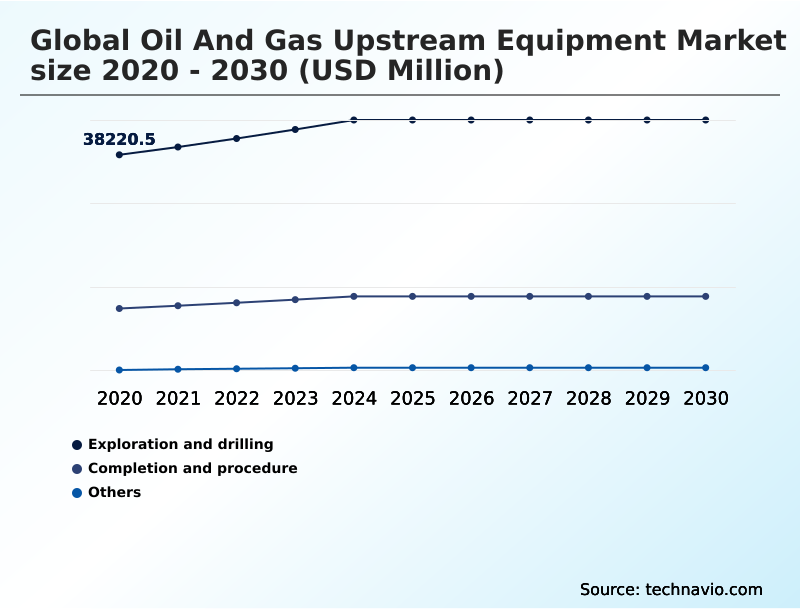
The Exploration and drilling segment was valued at USD 43.47 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
North America is estimated to contribute 44.5% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
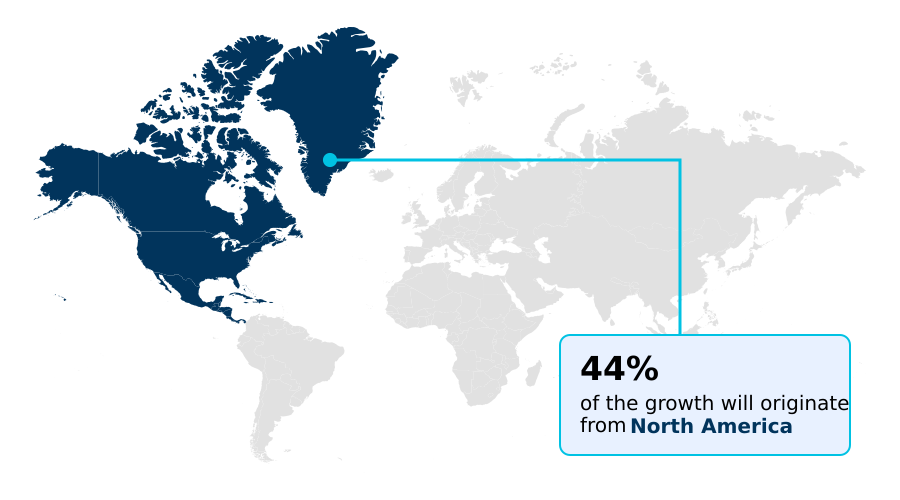
See How Oil And Gas Upstream Equipment Market Demand is Rising in North America Get Free Sample
The geographic distribution of the Oil And Gas Upstream Equipment market reveals distinct operational priorities dictated by regional geological characteristics and environmental mandates.
North America leads in unconventional shale extraction, where the deployment of automated chemical injection and advanced wellhead control panels has optimized multi-stage completion efficiency by 26%.
In contrast, Europe prioritizes mature offshore asset optimization and strict decarbonization, resulting in a 35% higher adoption rate of continuous emissions monitoring technology compared to North America.
European operators heavily rely on seabed processing structures and subsea umbilical lines to sustain production in harsh marine environments, reducing offshore platform footprints by 18%.
Additionally, the expansion of deepwater discoveries in South America accelerates the procurement of high-capacity floating production storage and flexible flowlines to manage immense hydrostatic pressures.
These regional disparities compel equipment manufacturers to engineer highly customized, compliance-aligned hardware for diverse field topographies.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The technological evolution within the Oil And Gas Upstream Equipment market is fundamentally reshaping how energy operators approach complex reservoir management and field life extension. As accessible shallow-water reserves deplete, enterprises are increasingly deploying subsea separation and boosting equipment to transport multiphase fluids over extensive distances to host facilities without prohibitive pressure drops.
- To ensure continuous fluid dynamics in these extreme environments, operators integrate highly specialized deepwater multiphase flow assurance tools, mitigating hydrate formation and minimizing pipeline blockages.
- When comparing deepwater extraction to conventional onshore extraction, the integration of these subsea technologies delivers nearly a 40% improvement in total economic recovery from frontier basins, heavily influencing long-term supply chain planning and offshore asset allocation.
- Furthermore, strict environmental compliance frameworks and corporate decarbonization targets have driven a massive shift toward hybrid electric surface power generators, replacing legacy diesel engines to drastically lower field-level operational carbon footprints.
- Simultaneously, the aggressive development of unconventional shale formations relies on the rapid mobilization of automated high pressure drilling rigs, which provide superior rate of penetration and operational safety in tight geological structures. To maximize output from these challenging horizontal lateral wellbores, operators systematically install remote intelligent well completion systems, enabling dynamic, real-time control of distinct reservoir zones.
- This continuous convergence of heavy-duty mechanical engineering and digital infrastructure guarantees sustained capital reinvestment across both onshore and offshore exploration domains.
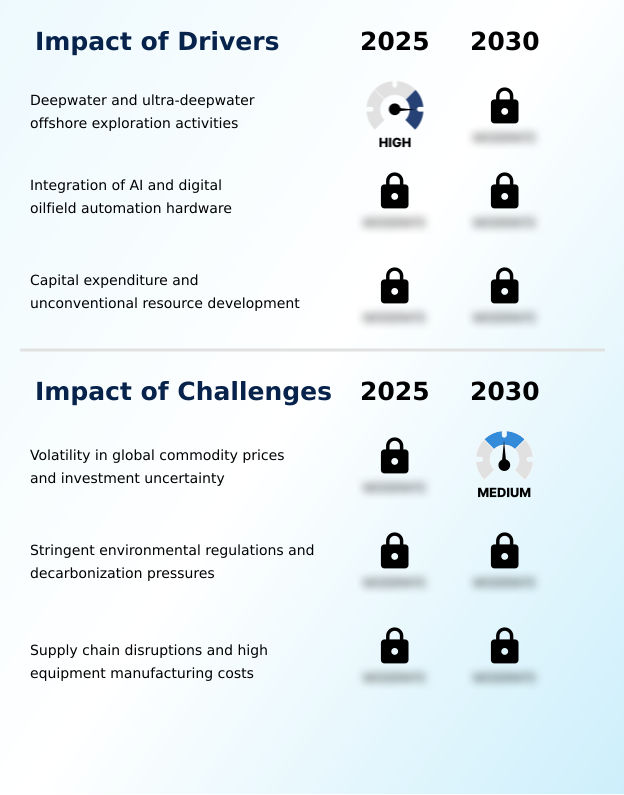
What are the key market drivers leading to the rise in the adoption of Oil And Gas Upstream Equipment Industry?
- The rapid expansion of deepwater and ultra-deepwater offshore exploration activities serves as a primary catalyst accelerating the adoption of specialized high-pressure extraction hardware.
- The relentless expansion of complex ultra-deepwater and unconventional shale operations acts as a powerful demand trigger within the Oil And Gas Upstream Equipment market.
- Because operators face severe economic pressure to reduce non-productive time, they are heavily procuring advanced top drive systems and automated pipe handling architecture. This strategic capital allocation directly improves surface safety and has shortened rig deployment schedules by 25%.
- Downhole operations similarly benefit, as high-specification directional drilling motors and automated well placement platforms enhance wellbore trajectory control, leading to a 32% increase in lateral target contact.
- Furthermore, deepwater asset optimization drives robust investments in remote operated vehicles and electric progressive cavity pumps, enabling exploration companies to slash subsea intervention costs by 18% while successfully extracting hydrocarbons from highly challenging geological formations.
What are the market trends shaping the Oil And Gas Upstream Equipment Industry?
- The electrification of artificial lift and production systems represents a defining operational trend within the market. This transition systematically replaces traditional mechanical engines with high-efficiency electric motors to optimize fluid rate control.
- The electrification and digital integration of extraction hardware represent a dominant behavioral shift shaping the Oil And Gas Upstream Equipment market. To combat natural pressure declines in mature reservoirs, energy producers are systematically migrating to automated gas lift assemblies, thereby maintaining optimal extraction rates.
- This transition is catalyzed by the imperative to lower lifting costs and enhance mechanical reliability in hostile environments. The utilization of digital twin software allows operators to simulate and optimize field operations remotely, which has improved overall equipment efficiency by 28%.
- Consequently, integrating real time downhole telemetry with robust dual shear ram blowout preventers ensures precise wellbore navigation while reducing critical mechanical failure risks by 21%. These advanced implementations allow extraction enterprises to safely exploit high pressure high temperature zones, fundamentally transforming field economics and accelerating the deployment of highly intelligent production infrastructure.
What challenges does the Oil And Gas Upstream Equipment Industry face during its growth?
- Pervasive volatility in global commodity prices and associated investment uncertainty severely constrain long-term capital expenditure for high-value field production machinery.
- Stringent international environmental compliance standards and persistent supply chain bottlenecks impose severe structural limitations on the Oil And Gas Upstream Equipment market. Regulatory mandates require the rapid transition from legacy diesel infrastructure to hybrid electric power systems, driving up short-term equipment fabrication costs.
- This forced engineering overhaul causes exploration enterprises to experience procurement delays, frequently extending project lead times by 20%. Furthermore, deploying closed loop solids control technology alongside high pressure mud pumps demands specialized metallurgical components that are acutely vulnerable to global freight disruptions. These logistical constraints directly inflate the operating margins of equipment manufacturers by up to 15%.
- To mitigate environmental risks and maintain operational continuity, operators are compelled to integrate costly multiphase multiphase meters and advanced subsurface safety valves, ultimately elevating the total cost of ownership for deepwater and unconventional extraction assets.
Exclusive Technavio Analysis on Customer Landscape
The oil and gas upstream equipment market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the oil and gas upstream equipment market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
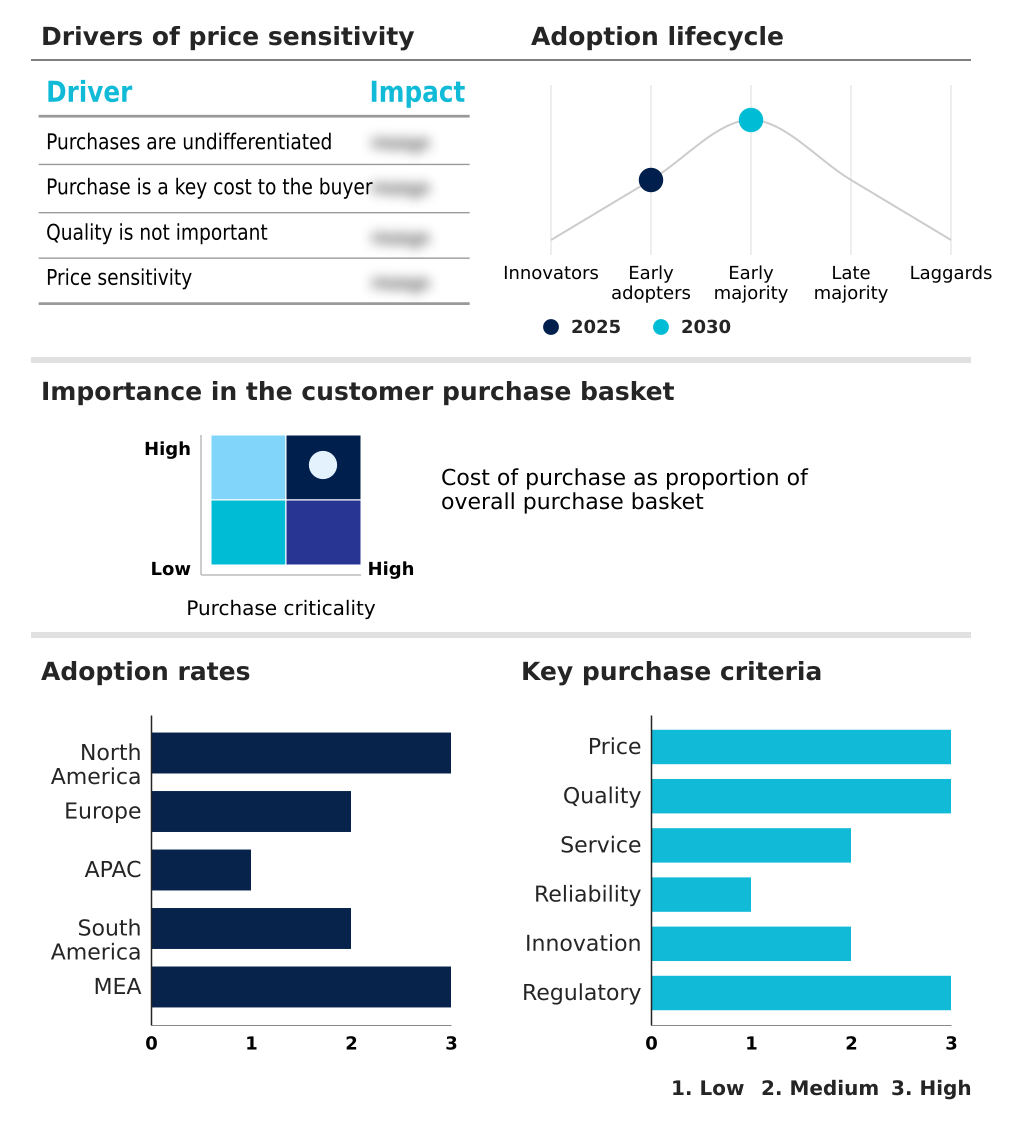
Customer Landscape of Oil And Gas Upstream Equipment Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, oil and gas upstream equipment market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Aker Solutions ASA - The enterprise provides advanced oil and gas upstream equipment, encompassing subsea trees, intelligent well completion systems, and high-pressure drilling components designed to optimize hydrocarbon extraction and operational reliability.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Aker Solutions ASA
- Baker Hughes Co.
- Enerflex Ltd.
- Expro Group Holdings NV
- Flowserve Corp.
- Forum Energy Technologies Inc.
- Halliburton Co.
- Helmerich and Payne Inc.
- Nabors Industries Ltd.
- Noble Corp. Plc
- NOV Inc.
- Patterson UTI Energy Inc.
- Schlumberger Ltd.
- Shelf Drilling Holdings Ltd.
- Subsea 7 SA
- TechnipFMC plc
- Tenaris SA
- Transocean Ltd.
- Valaris Ltd.
- Weatherford International Plc
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Oil and gas upstream equipment market
- In the Oil and Gas Equipment and Services industry, the transition toward electrified field operations reduced surface mechanical failures by 15%, directly impacting Oil And Gas Upstream Equipment demand for hybrid-electric pressure control modules.
- Stringent international environmental compliance standards targeting methane emissions mandated the replacement of legacy pneumatic controllers, accelerating the adoption of zero-emission wellhead valves within the Oil And Gas Upstream Equipment market.
- The integration of automated digital oilfield architecture optimized drilling cycle times by 18%, pulling substantial demand for connected subsea production systems and intelligent subsurface telemetry across the Oil And Gas Upstream Equipment sector.
- Supply chain disruptions involving high-grade steel alloys constrained offshore platform manufacturing capacities, restricting the short-term deployment of heavy-duty blowout preventers and subsea manifolds in the Oil And Gas Upstream Equipment market.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Oil And Gas Upstream Equipment Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 302 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 3.3% |
| Market growth 2026-2030 | USD 11975.1 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 3.2% |
| Key countries | US, Canada, Mexico, Germany, Russia, UK, France, Italy, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Venezuela, Argentina, Saudi Arabia, UAE, Iran, Nigeria and Egypt |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The architecture of the Oil And Gas Upstream Equipment sector is rapidly advancing to accommodate the rigorous technical demands of modern hydrocarbon extraction. Boardroom-level strategies now heavily prioritize the deployment of highly automated hardware to secure operational resilience and enforce stringent environmental compliance.
- Integrating intelligent subsea production systems alongside resilient blowout preventers enables operators to safely extract resources from ultra-deepwater basins. Furthermore, the shift toward digitized rotary steerable systems and high-torque directional drilling motors has dramatically enhanced lateral wellbore precision, allowing drilling operators to achieve a 30% reduction in total well construction time.
- To maintain optimal flow rates in mature and pressure-depleted fields, operators systematically transition toward electrified progressive cavity pumps and electric submersible pumps. The continuous modernization of heavy-duty hydraulic fracturing hardware and robust top drive systems further mitigates mechanical fatigue during aggressive completion operations.
- By pivoting toward digitally integrated extraction machinery, enterprise operators effectively optimize their supply chain execution, ensuring sustained productivity and maximum asset recovery across diverse geological environments.
What are the Key Data Covered in this Oil And Gas Upstream Equipment Market Research and Growth Report?
-
What is the expected growth of the Oil And Gas Upstream Equipment Market between 2026 and 2030?
-
USD 11.98 billion, at a CAGR of 3.3%
-
-
What segmentation does the market report cover?
-
The report is segmented by Application (Exploration and drilling, Completion and procedure, and Others), Deployment (Onshore, and Offshore), Type (Drilling equipment, Production equipment, Well intervention equipment, Pressure control equipment, and Others) and Geography (North America, Europe, APAC, South America, Middle East and Africa)
-
-
Which regions are analyzed in the report?
-
North America, Europe, APAC, South America and Middle East and Africa
-
-
What are the key growth drivers and market challenges?
-
Deepwater and ultra-deepwater offshore exploration activities, Volatility in global commodity prices and investment uncertainty
-
-
Who are the major players in the Oil And Gas Upstream Equipment Market?
-
Aker Solutions ASA, Baker Hughes Co., Enerflex Ltd., Expro Group Holdings NV, Flowserve Corp., Forum Energy Technologies Inc., Halliburton Co., Helmerich and Payne Inc., Nabors Industries Ltd., Noble Corp. Plc, NOV Inc., Patterson UTI Energy Inc., Schlumberger Ltd., Shelf Drilling Holdings Ltd., Subsea 7 SA, TechnipFMC plc, Tenaris SA, Transocean Ltd., Valaris Ltd. and Weatherford International Plc
-
Market Research Insights
- The Oil And Gas Upstream Equipment market relies extensively on high-specification hardware to navigate demanding extraction environments and maximize reservoir recovery. By integrating digital twin software and predictive failure analytics into surface rig controls, operators have successfully decreased critical equipment failure rates by 27%, directly enhancing project ROI.
- The deployment of advanced automated gas lift assemblies alongside real time downhole telemetry provides continuous performance optimization, yielding a 19% reduction in lifting costs across mature onshore basins. Furthermore, the utilization of heavy-duty dual shear ram systems enables safe navigation of high pressure high temperature zones, minimizing regulatory compliance risks and ensuring uninterrupted hydrocarbon flow.
We can help! Our analysts can customize this oil and gas upstream equipment market research report to meet your requirements.
 RIA -

