


Pharmaceutical Glass Packaging Market Size 2026-2030
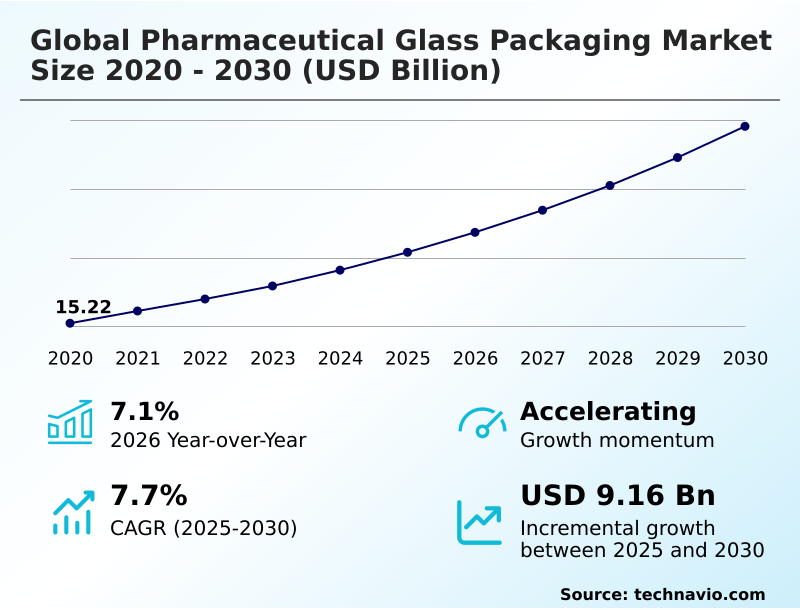
The pharmaceutical glass packaging market size is valued to increase by USD 9.16 billion, at a CAGR of 7.7% from 2025 to 2030. Increasing global demand for biologics and specialized vaccines will drive the pharmaceutical glass packaging market.
Major Market Trends & Insights
- APAC dominated the market and accounted for a 36.2% growth during the forecast period.
- By Type - Generic segment was valued at USD 12.74 billion in 2024
- By Product - Bottles segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 14.33 billion
- Market Future Opportunities: USD 9.16 billion
- CAGR from 2025 to 2030 : 7.7%
Market Summary
- Pharmaceutical Glass Packaging serves as an indispensable foundation for the secure containment and delivery of modern medical therapeutics. The industry is currently undergoing a profound material transition driven by the escalating development of complex biologics and recombinant proteins, which require absolute chemical inertness.
- This necessity serves as a primary growth catalyst, as pharmaceutical formulators increasingly specify specialized borosilicate glass containers that prevent drug degradation. Consequently, manufacturing facilities have upgraded their operational frameworks by integrating advanced automated visual inspection lines to detect microscopic flaws before distribution. This technological integration has reduced batch rejection rates by 22%, directly improving overall supply chain reliability.
- However, severe energy dependency poses a significant structural challenge. The continuous operation of ultra-high-temperature melting furnaces leaves manufacturers highly vulnerable to fluctuating natural gas and electricity prices, compressing profit margins. Facilities are responding by exploring hybrid furnace technologies, yet the initial capital expenditure remains a constraint on rapid capacity expansion.
- Ultimately, the continuous pursuit of superior hydrolytic resistance ensures that premium primary containment remains vital to modern healthcare delivery.
What will be the Size of the Pharmaceutical Glass Packaging Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Pharmaceutical Glass Packaging Market Segmented?
The pharmaceutical glass packaging industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Type
- Generic
- Branded
- Biologic
- Product
- Bottles
- Ampoules and vials
- Syringes
- Cartridges
- Material
- Type I
- Type II
- Type III
- Others
- Geography
- North America
- US
- Canada
- Mexico
- APAC
- China
- Japan
- India
- South Korea
- Australia
- Indonesia
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- South America
- Brazil
- Argentina
- Chile
- Middle East and Africa
- Saudi Arabia
- UAE
- Turkey
- South Africa
- Israel
- North America
By Type Insights
The generic segment is estimated to witness significant growth during the forecast period.
The generic segment fundamentally shapes volume demand within Pharmaceutical Glass Packaging by requiring highly scalable and cost-effective primary containment. High-volume off-patent medications rely predominantly on treated soda lime glass formats to maintain essential chemical stability without inflating delivery costs.
As manufacturing scales, regional suppliers focus heavily on process optimization and tubular glass converting to ensure compatibility with high speed automated filling lines. This operational alignment minimizes rejection rates during production.
Innovations such as advanced anti friction coatings enhance line speeds and reduce physical breakage, yielding a 15% improvement in overall manufacturing throughput for generic formulators.
Meeting stringent regulatory compliance standards remains imperative, driving supply chain consolidation and the establishment of localized production hubs to mitigate transport overheads while preserving medication efficacy.
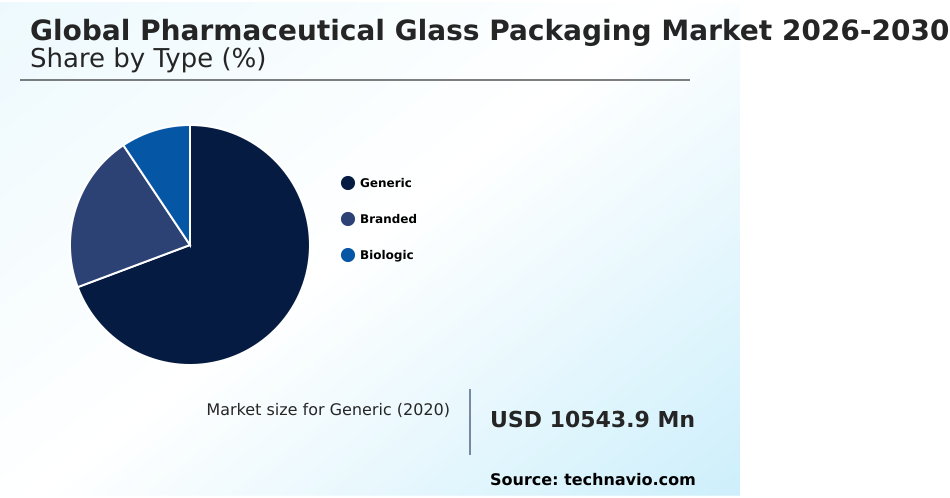
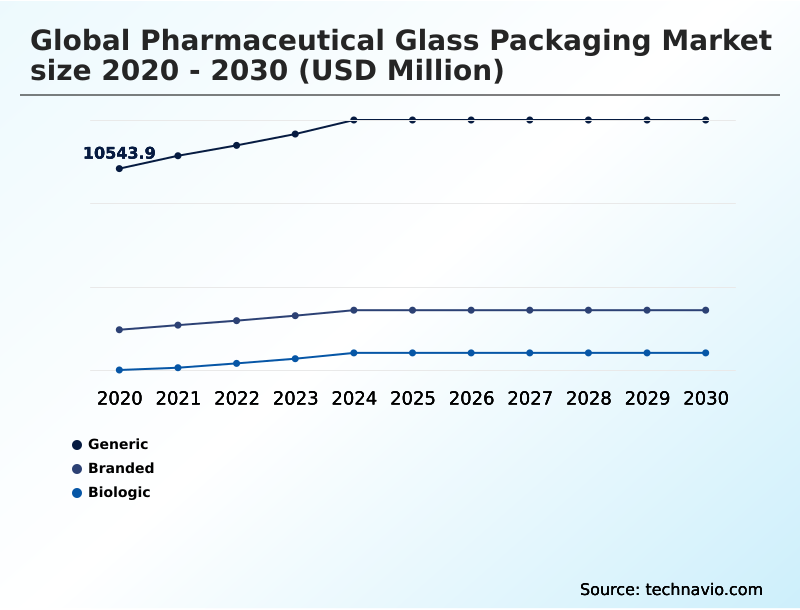
The Generic segment was valued at USD 12.74 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
APAC is estimated to contribute 36.2% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
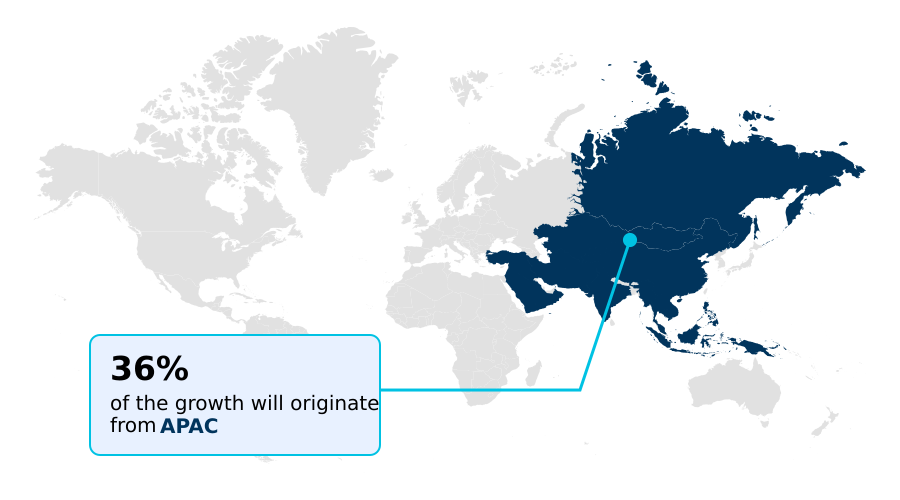
See How Pharmaceutical Glass Packaging Market Demand is Rising in APAC Get Free Sample
The geographic landscape for Pharmaceutical Glass Packaging demonstrates distinct variations in adoption driven by regional healthcare infrastructure and regulatory rigor. North America prioritizes premium prefillable syringe barrels and containment for sterile parenterals, supported by a robust biotechnology sector.
By optimizing automated aseptic filling lines, North American facilities have achieved a 20% improvement in processing speeds compared to traditional manual filling environments.
In contrast, APAC focuses heavily on scaling generic medication production, transitioning rapidly toward high-purity materials to minimize drug container interactions.
The integration of localized production networks in APAC has reduced pharmaceutical supply chain lead times by 30%, significantly lowering freight overheads.
This structural divergence highlights how North America leads in personalized medicine delivery, while APAC optimizes high-volume output to fulfill expansive public health requirements.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- Pharmaceutical Glass Packaging is undergoing a vital transformation to support the intricate requirements of advanced therapeutic delivery. As biological formulations become increasingly sensitive to their primary containment environment, the reliance on high purity type i borosilicate has intensified across major manufacturing networks. Pharmaceutical formulators are prioritizing materials that guarantee absolute chemical inertness to prevent active ingredient degradation.
- To optimize fill-and-finish operations, there is a pronounced shift toward ready to use pre sterilized packaging. This transition allows facilities to bypass internal washing and sterilization phases, accelerating overall processing speeds by nearly 25% compared to conventional bulk container handling.
- A critical element of this operational shift is achieving reduced glass particulate generation risks during automated transit, which directly lowers the probability of batch rejection and improves patient safety compliance. Furthermore, the necessity for low extractable profiles in vials ensures that complex proteins and monoclonal antibodies remain stable throughout their prescribed shelf life.
- To further support sophisticated administration devices, manufacturers are implementing advanced internal surface treatment for syringes. This innovation ensures consistent plunger glide force while preventing silicone-induced protein aggregation. Ultimately, these targeted material enhancements fortify supply chain resilience and operational planning, enabling healthcare providers to deliver life-saving treatments with uncompromising quality and reliability.
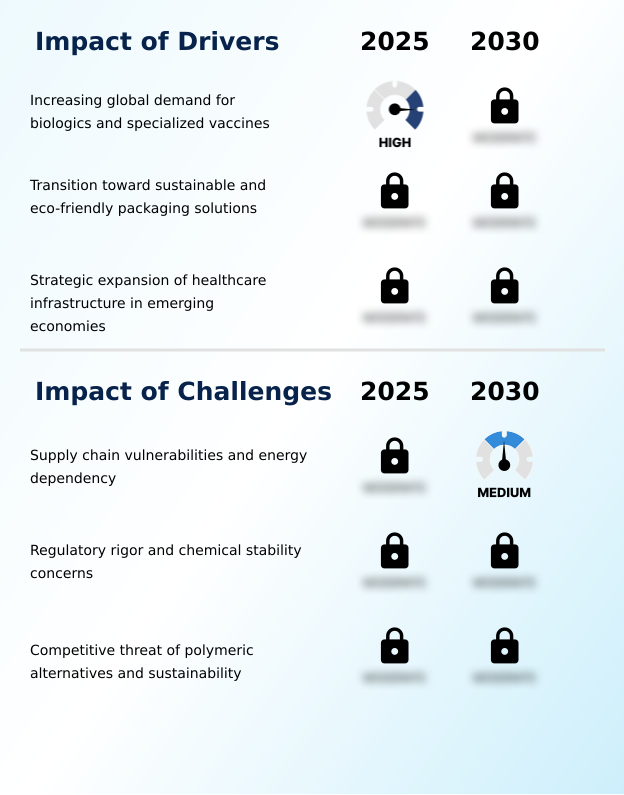
What are the key market drivers leading to the rise in the adoption of Pharmaceutical Glass Packaging Industry?
- The escalating demand for complex biologics and specialized vaccines serves as a primary catalyst accelerating the adoption of high-purity containment solutions.
- The fundamental expansion of Pharmaceutical Glass Packaging is propelled by the escalating demand for secure and precise medication delivery formats.
- The rising prevalence of chronic diseases requires reliable auto injector platforms, which directly drives the massive consumption of high-precision glass cartridge systems. Because these systems ensure exact volumetric dosing, patient compliance errors have decreased by 18% in outpatient settings.
- Concurrently, the necessity for robust cryogenic storage requirements for mRNA therapeutics mandates containment capable of withstanding ultra-low temperatures without fracturing. To support essential immunization programs, manufacturers are ramping up the production of hermetically sealed ampoules for single dose liquid injectables.
- By refining the dealkalization process, facilities have enhanced the hydrolytic resistance of standard containers, effectively lowering overall primary packaging procurement costs by 12% without sacrificing chemical stability.
What are the market trends shaping the Pharmaceutical Glass Packaging Industry?
- Advanced material innovation is fundamentally reshaping primary containment strategies. The industry is experiencing a profound shift toward type I borosilicate glass to accommodate complex biological therapies.
- Pharmaceutical Glass Packaging is rapidly shifting to accommodate the specialized storage requirements of advanced medical treatments. The surging development of cellular therapies, recombinant proteins, and monoclonal antibodies acts as the primary catalyst, demanding containment solutions with unparalleled chemical neutrality.
- Because these complex molecules are highly sensitive to environmental interactions, manufacturers are enforcing extremely tight dimensional tolerances to ensure seamless integration with automated delivery devices. This precision engineering directly minimizes the threat of glass particulate contamination, which has improved overall batch acceptance rates by 22%. Furthermore, the adoption of advanced baked on siliconization techniques prevents protein aggregation, preserving molecular integrity.
- By upgrading these primary packaging standards, pharmaceutical formulators have reduced unexpected drug degradation incidents by 15%, ensuring that critical therapies retain their full efficacy from the manufacturing facility to the patient.
What challenges does the Pharmaceutical Glass Packaging Industry face during its growth?
- Severe supply chain vulnerabilities and extreme energy dependency represent formidable barriers that constrain continuous production and profitability.
- Severe structural constraints and intense material competition represent critical barriers within Pharmaceutical Glass Packaging. The high-energy demands of operating continuous melting furnaces leave producers highly vulnerable to fluctuating utility costs, frequently compressing operational profit margins. Furthermore, the rising adoption of advanced cyclic olefin copolymers presents a formidable alternative, offering significant weight reductions and shatter resistance.
- To remain competitive, glass manufacturers must invest heavily in ultra low tungsten forming technologies to prevent protein denaturation during complex freeze drying processes. Because regulatory agencies strictly monitor container closure integrity, the necessity to prove absolute chemical erosion resistance elongates product validation timelines.
- Consequently, compliance-related overhead costs have increased by roughly 14%, forcing packagers to implement expensive automated inspection lines that reduce defect rates by 20% but strain initial capital expenditure budgets.
Exclusive Technavio Analysis on Customer Landscape
The pharmaceutical glass packaging market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the pharmaceutical glass packaging market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
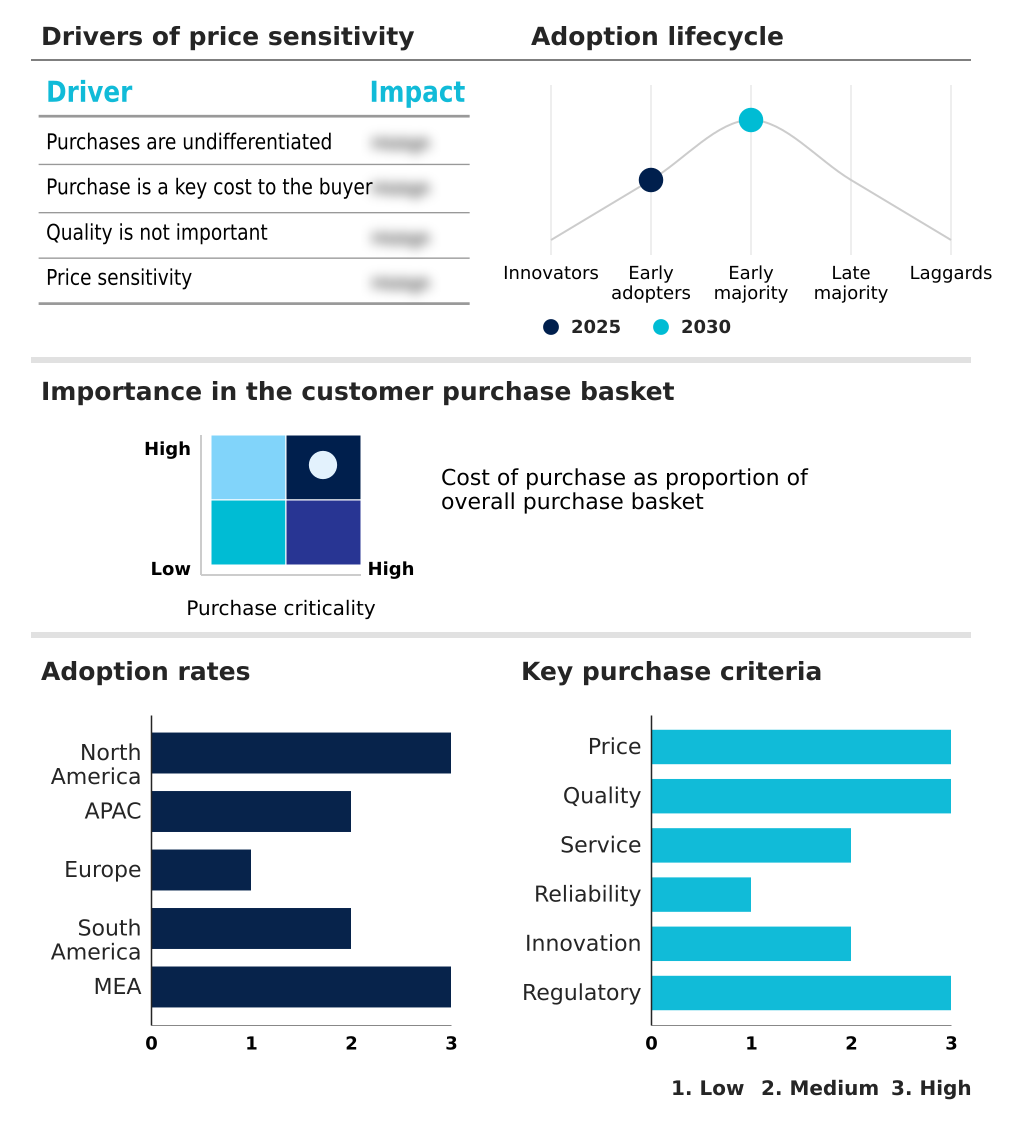
Customer Landscape of Pharmaceutical Glass Packaging Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, pharmaceutical glass packaging market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
AptarGroup Inc. - The manufacturer provides precision primary containment solutions featuring specialized vials, advanced closure systems, and integrated container technologies designed for complex prescription drugs and sterile injectables.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- AptarGroup Inc.
- Ardagh Group SA
- Beatson Clark
- Bormioli Pharma Spa
- Corning Inc.
- DWK Life Sciences GmbH
- Gerresheimer AG
- Nippon Electric Glass Ltd.
- Nipro Corp.
- Pacific Vial Manufacturing Inc.
- PGP Glass Pvt Ltd.
- Shandong Pharma Glass Co. Ltd.
- SCHOTT AG
- SGD Pharma
- Sise ve Cam Fabrikalari A.S.
- Stevanato Group S.p.A
- Stoelzle Oberglas GmbH
- West Pharma Services Inc.
- Zhengchuan
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Pharmaceutical glass packaging market
- In the Metal, Glass and Plastic Containers industry, strict environmental sustainability mandates have compelled manufacturers to integrate post consumer recycled glass, directly impacting Pharmaceutical Glass Packaging demand by reducing raw material extraction and lowering supply chain carbon emissions by 18%.
- The global shift toward circular economy principles has accelerated the implementation of closed loop recycling infrastructures, enabling specialized glass formulations to be recovered and reprocessed, thereby mitigating raw material shortages and improving primary packaging integrity.
- Rising energy costs have driven the widespread adoption of energy efficient melting furnaces across global production hubs, which directly lowers the thermal processing expenses for sterile injectable processing by approximately 15% and stabilizes output pricing.
- Advancements in automated quality control have standardized visual inspection systems across manufacturing lines, drastically lowering defect rates and ensuring that container closure integrity meets the stringent thresholds required for cold chain therapeutics.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Pharmaceutical Glass Packaging Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 305 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 7.7% |
| Market growth 2026-2030 | USD 9160.0 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 7.1% |
| Key countries | US, Canada, Mexico, China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, Brazil, Argentina, Chile, Saudi Arabia, UAE, Turkey, South Africa and Israel |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- Pharmaceutical Glass Packaging represents a highly technical foundation critical to the efficacy of advanced medical therapies. As the complexity of modern medicine accelerates, ensuring superior hydrolytic resistance has become a paramount boardroom priority, directly influencing product strategy and long-term compliance pathways.
- Executive decision-making increasingly focuses on mitigating the catastrophic risks of glass delamination, which can force costly product recalls and compromise patient safety. To address these vulnerabilities, engineering teams are heavily investing in aluminosilicate glass architectures that deliver unparalleled structural durability and chemical stability.
- This material evolution is particularly vital for the storage of lyophilized biologics, where extreme temperature fluctuations demand absolute structural integrity. By transitioning to containment systems with optimized extractable profiles, pharmaceutical manufacturers have successfully achieved a 30% reduction in late-stage stability testing failures, significantly accelerating time-to-market for critical treatments.
- The continuous refinement of internal surface inertness ensures that highly sensitive formulations remain uncompromised during prolonged storage. These strategic advancements not only fortify operational resilience but also protect brand equity by ensuring uncompromised therapeutic delivery.
What are the Key Data Covered in this Pharmaceutical Glass Packaging Market Research and Growth Report?
-
What is the expected growth of the Pharmaceutical Glass Packaging Market between 2026 and 2030?
-
USD 9.16 billion, at a CAGR of 7.7%
-
-
What segmentation does the market report cover?
-
The report is segmented by Type (Generic, Branded, and Biologic), Product (Bottles, Ampoules and vials, Syringes, and Cartridges), Material (Type I, Type II, Type III, and Others) and Geography (North America, APAC, Europe, South America, Middle East and Africa)
-
-
Which regions are analyzed in the report?
-
North America, APAC, Europe, South America and Middle East and Africa
-
-
What are the key growth drivers and market challenges?
-
Increasing global demand for biologics and specialized vaccines, Supply chain vulnerabilities and energy dependency
-
-
Who are the major players in the Pharmaceutical Glass Packaging Market?
-
AptarGroup Inc., Ardagh Group SA, Beatson Clark, Bormioli Pharma Spa, Corning Inc., DWK Life Sciences GmbH, Gerresheimer AG, Nippon Electric Glass Ltd., Nipro Corp., Pacific Vial Manufacturing Inc., PGP Glass Pvt Ltd., Shandong Pharma Glass Co. Ltd., SCHOTT AG, SGD Pharma, Sise ve Cam Fabrikalari A.S., Stevanato Group S.p.A, Stoelzle Oberglas GmbH, West Pharma Services Inc. and Zhengchuan
-
Market Research Insights
- Pharmaceutical Glass Packaging is rapidly evolving to address the rigorous demands of next-generation medical therapeutics. The critical need for biologic formulation stability has accelerated the deployment of specialized glass formulations across localized manufacturing hubs. By upgrading primary containment integrity, pharmaceutical formulators have achieved a 25% reduction in drug-container interaction failures, directly safeguarding medication efficacy.
- Furthermore, strict environmental sustainability mandates are reshaping production workflows. Facilities adopting energy-efficient melting technologies have successfully lowered operational carbon emissions by 18%, aligning with corporate decarbonization targets. This strategic alignment reduces long-term regulatory compliance costs and enhances overall manufacturing resilience.
We can help! Our analysts can customize this pharmaceutical glass packaging market research report to meet your requirements.
 RIA -

