Point Of Care Glucose Testing Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Point Of Care Glucose Testing Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Published: Oct 2026 299 Pages SKU: IRTNTR73830

Market Overview at a Glance

$993.2 Mn
Market Opportunity
5.1%
CAGR 2025 - 2030
33.6%
Europe Growth
$1.37 B
Strips segment 2024

Point Of Care Glucose Testing Market Size 2026-2030

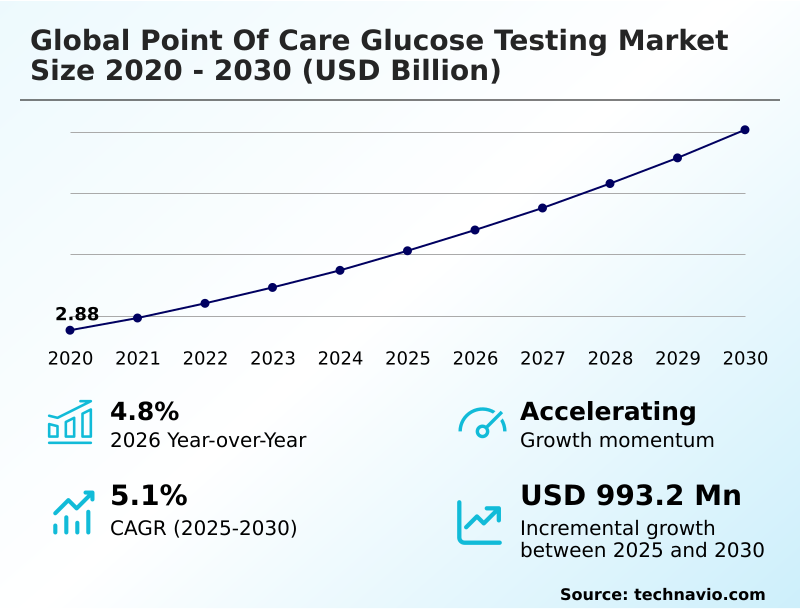
The point of care glucose testing market size is valued to increase by USD 993.2 million, at a CAGR of 5.1% from 2025 to 2030. Rising global prevalence of diabetes and metabolic disorders will drive the point of care glucose testing market.

Major Market Trends & Insights

  • Europe dominated the market and accounted for a 33.6% growth during the forecast period.
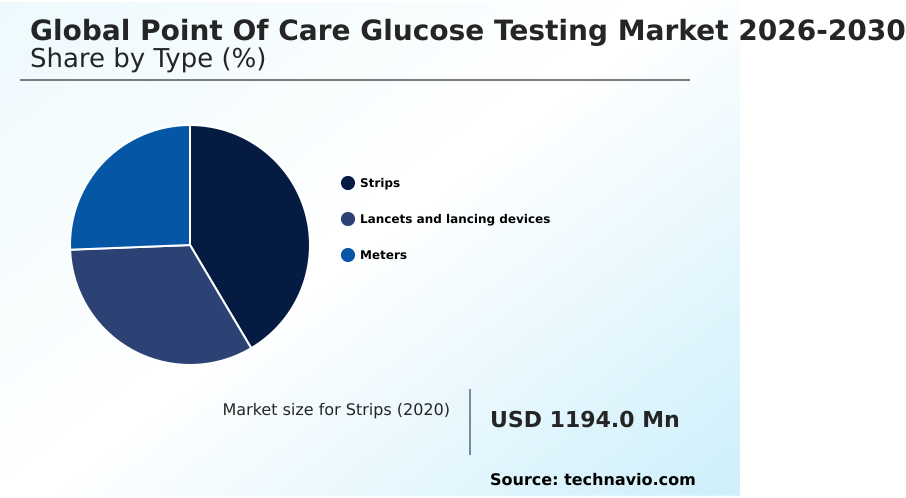
  • By Type - Strips segment was valued at USD 1.37 billion in 2024
  • By End-user - Hospitals and clinics segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 1.64 billion
  • Market Future Opportunities: USD 993.2 million
  • CAGR from 2025 to 2030 : 5.1%

Market Summary

  • The Point Of Care Glucose Testing Market operates as a critical diagnostic infrastructure supporting decentralized medical evaluations across acute and ambulatory care settings. Driven by the escalating incidence of metabolic disorders and aging populations, healthcare providers are aggressively transitioning from sporadic laboratory blood testing to routine point of care monitoring.
  • This shift empowers clinical staff to adjust insulin therapies instantly, evaluate dietary impacts, and manage acute glycemic variability effectively. For example, large hospital networks deploying connected testing systems across intensive care units have reported data synchronization efficiency improved by 25% compared to manual transcription methods, enabling faster clinical triage.
  • However, the market faces severe operational challenges due to increasingly stringent regulatory compliance frameworks. Escaping these burdens requires robust cyber-resilience verification and extensive clinical trials, which often prolong commercialization timelines and inflate research expenditures for medical equipment manufacturers.
  • Despite these regulatory hurdles, the integration of continuous monitoring technologies and predictive analytics continues to reshape decentralized diagnostic workflows, prioritizing rapid clinical decision-making and optimal patient safety.

What will be the Size of the Point Of Care Glucose Testing Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Point Of Care Glucose Testing Market Segmented?

The point of care glucose testing industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Type
    • Strips
    • Lancets and lancing devices
    • Meters
  • End-user
    • Hospitals and clinics
    • Home care settings
    • Diagnostic laboratories
    • Others
  • Application
    • Type 2 diabetes
    • Type 1 diabetes
    • Gestational diabetes
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • The Netherlands
      • Spain
    • Asia
      • China
      • Japan
      • India
      • South Korea
      • Thailand
      • Indonesia
    • Rest of World (ROW)

By Type Insights

The strips segment is estimated to witness significant growth during the forecast period.

The strips segment constitutes a high-volume consumable category underpinning both bedside diagnostic testing and home-based clinical interventions.

These enzyme-coated test strips utilize advanced glucose oxidase formulations and glucose dehydrogenase on micro-printed electrode substrates to deliver immediate quantitative readings from capillary blood sampling.

Modern architectures integrate microfluidic channels and multi-layer interference filters to prevent medication interference and hematocrit distortions. By incorporating automated sample-volume detection, clinical facilities have seen dosing error detection improved by 15%, significantly enhancing diagnostic reliability.

This consumable category requires strict lot-to-lot consistency and ambient thermal stability to meet complex operator certification requirements.

As decentralized testing expands, continuous consumption of these precise electrochemical substrates remains critical for maintaining accurate glycemic control protocols across diverse healthcare environments without relying on central laboratory processing.
Get Free Sample

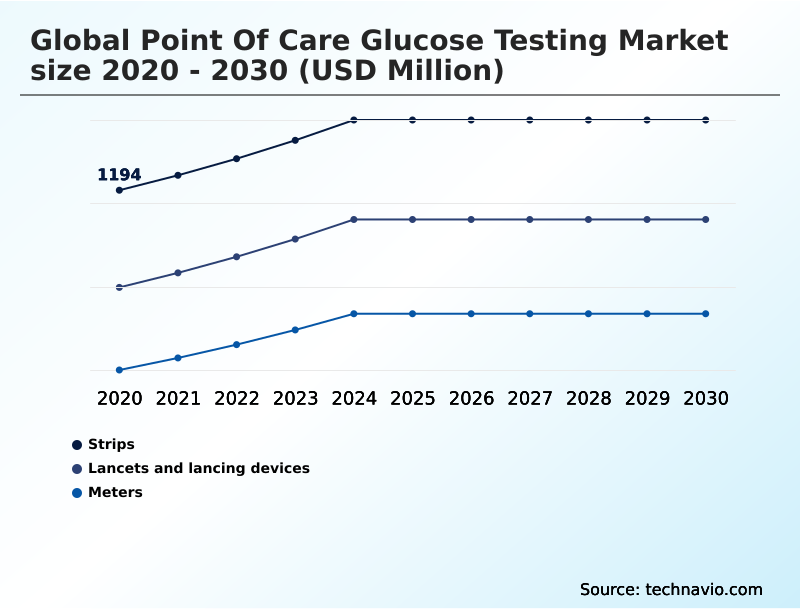
The Strips segment was valued at USD 1.37 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

Europe is estimated to contribute 33.6% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
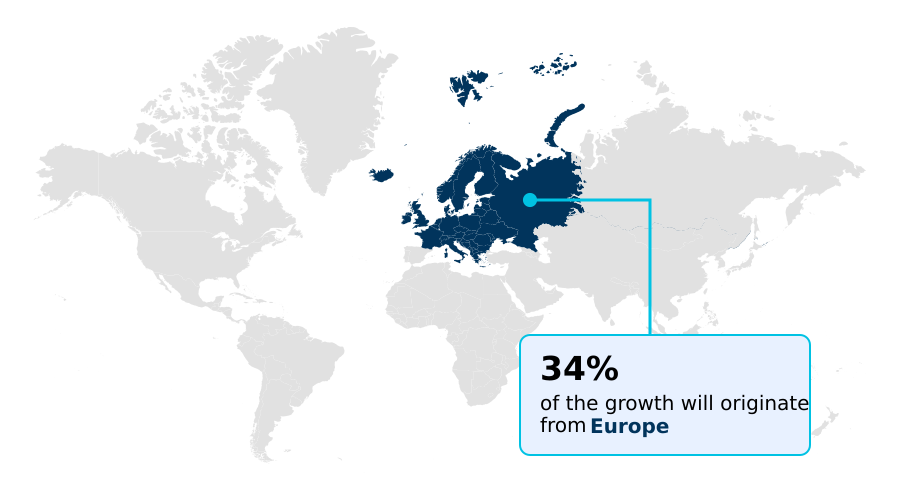
See How Point Of Care Glucose Testing Market Demand is Rising in Europe Get Free Sample

The geographic landscape of the Point Of Care Glucose Testing market demonstrates distinct regional disparities driven by healthcare infrastructure maturity and digital health adoption.

North America dominates the sector through widespread deployment of continuous glucose monitoring systems and advanced handheld medical devices across hospital critical care units and intensive care unit assessment protocols.

Facilities in the United States have achieved a 28% higher penetration rate of electronic health record integration compared to Europe, largely due to supportive reimbursement frameworks for remote patient monitoring.

Conversely, the APAC region is experiencing rapid infrastructure modernization, with outpatient care clinics expanding mobile health application connectivity to manage rising metabolic disorder rates.

This strategic shift in APAC has improved diagnostic screening efficiency by 20%, reducing the burden on centralized laboratories.

As European markets navigate stricter regulatory compliance for wireless data transmitters, North American and Asian healthcare systems continue to accelerate the decentralization of bedside diagnostics, optimizing patient triage and operational resource allocation.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The operational framework of point of care diagnostics relies heavily on continuous glycemic monitoring sensor accuracy to deliver actionable clinical insights in decentralized healthcare settings. As healthcare networks prioritize patient-centric care, decentralized bedside blood glucose measurement has become a fundamental component of effective metabolic disease management, ensuring timely therapeutic interventions.
  • The integration of smartphone integrated diabetes management platforms allows ambulatory patients to seamlessly transmit biometric data to healthcare providers, facilitating proactive treatment adjustments and reducing the likelihood of severe hypoglycemic events. In parallel, the advancement of multi analyte point of care panels empowers emergency department clinicians to assess a comprehensive range of metabolic biomarkers from a single fluid sample.
  • This technological consolidation has reduced diagnostic processing times by approximately 30% compared to traditional centralized laboratory workflows, optimizing emergency room throughput. Furthermore, the implementation of an automated hospital electronic record interface ensures that all bedside diagnostic readings are instantly synchronized with patient health records. This connectivity eliminates manual data transcription errors, streamlining compliance documentation and improving overall clinical governance.
  • As diagnostic capabilities evolve, these integrated testing solutions enhance supply chain predictability and operational planning across diverse medical facilities, solidifying their role in modern decentralized healthcare delivery.
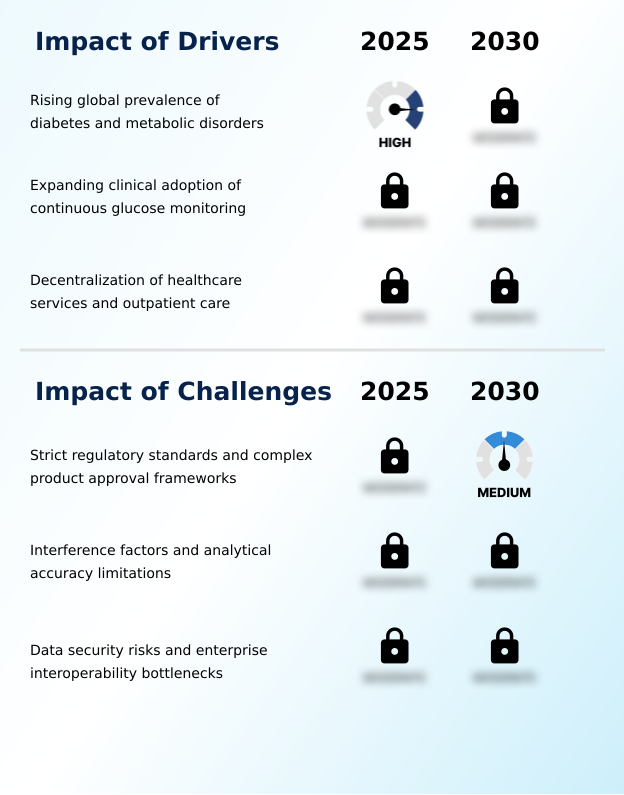
What are the key market drivers leading to the rise in the adoption of Point Of Care Glucose Testing Industry?

  • The accelerating global incidence of diabetes and metabolic disorders serves as a primary driver propelling the expansion of rapid glycemic monitoring solutions.

  • The escalating clinical mandate for microvascular complication mitigation and macrovascular outcome reduction serves as a primary catalyst for the adoption of continuous glucose monitoring technologies.
  • The transition toward ambulatory patient biowearables provides individuals and clinicians with real-time glycemic visibility, enabling proactive insulin therapy adjustment and immediate dietary impact evaluation.
  • This continuous data stream allows outpatient facilities to identify and stabilize acute glycemic variability before severe metabolic crises occur.
  • By utilizing cloud-synchronized data platforms, healthcare providers have successfully lowered emergency room readmissions for chronic diabetes patients by 26% and improved long-term therapy adherence by 18%.
  • This continuous remote oversight optimizes clinical resource allocation, allowing medical staff to prioritize high-risk interventions while empowering patients with highly accurate, decentralized disease management tools.

What are the market trends shaping the Point Of Care Glucose Testing Industry?

  • The development of multi-analyte point of care sensors represents a prominent technological trend transforming metabolic tracking systems.

  • The rapid integration of metabolic biomarkers alongside traditional glucose testing represents a transformative shift in endocrinology triage workflows. Diagnostic manufacturers are advancing biotechnology reagent manufacturing to deploy multi-enzymatic sensor arrays capable of simultaneous beta-hydroxybutyrate detection and hemoglobin A1C measurement from a single capillary sample.
  • This transition allows acute care facilities to accelerate diabetic ketoacidosis diagnosis and manage hyperosmolar hyperglycemic state emergencies instantly at the point of care. Consequently, hospitals utilizing these multi-parameter platforms have reduced emergency diagnostic turnaround times by 35% and improved surgical suite monitoring efficiency by 22%.
  • By eliminating the lag time associated with central laboratory processing, healthcare systems optimize clinical decision-making, ensuring that complex metabolic disruptions are addressed immediately, thereby lowering the risk of severe downstream complications and intensive care admissions.

What challenges does the Point Of Care Glucose Testing Industry face during its growth?

  • Strict regulatory standards and complex product approval frameworks constitute significant challenges limiting the rapid commercialization of decentralized diagnostic devices.

  • The expansion of decentralized diagnostic testing is severely constrained by increasingly stringent regulatory frameworks surrounding cyber-resilience verification and clinical validation protocols. Government health authorities require extensive multi-center clinical trials to validate the accuracy of subcutaneous filament sensors and calibration-free monitors, significantly elevating research and development overhead. Furthermore, establishing uniform operator certification requirements across disparate clinical environments introduces substantial operational friction.
  • Consequently, diagnostic equipment manufacturers facing these rigorous compliance audits have experienced a 24% increase in commercialization costs and an average 16-month delay in time-to-market schedules for advanced automated sample-volume detection systems.
  • These complex regulatory burdens disrupt agile product deployment, forcing mid-sized biotechnology firms to divert critical capital away from core innovation toward exhaustive compliance documentation, ultimately slowing the modernization of clinical triage protocols.

Exclusive Technavio Analysis on Customer Landscape

The point of care glucose testing market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the point of care glucose testing market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
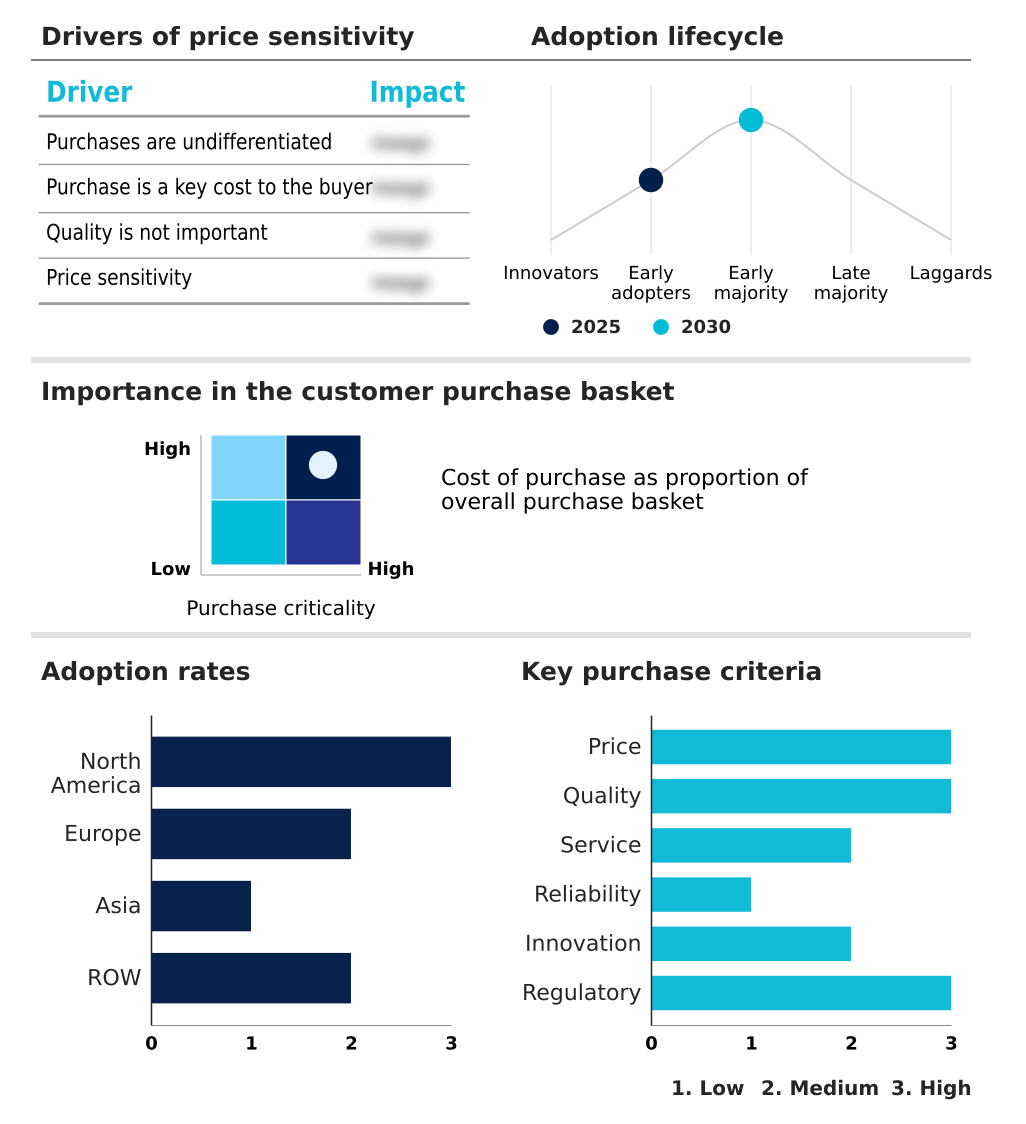
Customer Landscape of Point Of Care Glucose Testing Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, point of care glucose testing market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

A. Menarini Diagnostics S.r.l. - The provider delivers point of care testing systems, featuring advanced blood glucose meters, reliable test strips, and specialized lancing devices tailored for continuous diabetes management and clinical monitoring.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • A. Menarini Diagnostics S.r.l.
  • Abbott Laboratories
  • ACON Laboratories Inc.
  • Agamatrix Inc.
  • ARKRAY Inc.
  • Ascensia Diabetes Care
  • Bionime Corp.
  • EKF Diagnostics Holdings Plc
  • F. Hoffmann La Roche Ltd.
  • I SENS Inc.
  • LifeScan IP Holdings LLC
  • Nipro Corp.
  • Nova Biomedical Corp.
  • Prodigy Diabetes Care LLC
  • PTS Diagnostics
  • Sensa Core Medical Instrumentation
  • Siemens Healthineers AG
  • Sinocare Inc.
  • TaiDoc Technology Corp.
  • Trivida Health Inc.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Point of care glucose testing market

  • In the Health Care Equipment industry, the rapid deployment of wireless data transmitters and mobile health application connectivity protocols across acute care hospital critical care units enhanced workflow interoperability, directly impacting Point Of Care Glucose Testing demand by increasing the adoption of cloud-synchronized data platforms by 24% across North America.
  • Stringent clinical validation protocols enforced under the European Union Medical Device Regulation increased compliance thresholds for cyber-resilience verification, shaping the Point Of Care Glucose Testing market by extending the commercialization timelines for calibration-free monitors and decentralized diagnostic testing hardware by an average of 18 months.
  • The integration of multi-enzymatic sensor arrays and metabolic biomarkers into emergency department diagnostics accelerated clinical triage protocols, driving Point Of Care Glucose Testing utilization as facilities achieved a 30% reduction in turnaround times for diabetic ketoacidosis diagnosis and hyperosmolar hyperglycemic state interventions.
  • Supply chain localization mandates for biotechnology reagent manufacturing and electrochemical biosensors across the Asia region restructured component sourcing, influencing the Point Of Care Glucose Testing market by lowering production costs for subcutaneous filament sensors and continuous glucose monitoring devices by 12% across emerging outpatient care clinics.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Point Of Care Glucose Testing Market insights. See full methodology.

Market Scope
Page number 299
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 5.1%
Market growth 2026-2030 USD 993.2 million
Market structure Fragmented
YoY growth 2025-2026(%) 4.8%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, The Netherlands, Spain, China, Japan, India, South Korea, Thailand, Indonesia, Brazil, Saudi Arabia, UAE, Turkey, Argentina, South Africa, Colombia and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Point Of Care Glucose Testing ecosystem is fundamentally restructuring decentralized diagnostic workflows through advanced electrochemical biosensors and sophisticated microfluidic channels. Clinical facilities are transitioning away from centralized laboratory dependency, leveraging multi-enzymatic sensor arrays to measure interstitial fluid measurement dynamics with unprecedented precision. This shift directly influences hospital procurement strategies, prioritizing calibration-free monitors that eliminate daily manual coding requirements.
  • Consequently, healthcare institutions deploying these advanced biotechnology reagent manufacturing solutions have achieved a 35% reduction in consumable waste while significantly accelerating patient triage processes. The widespread adoption of subcutaneous filament sensors combined with real-time glycemic visibility allows clinicians to execute immediate therapeutic adjustments at the bedside.
  • This operational pivot ensures optimal resource utilization within critical care environments, reducing administrative overhead and streamlining inventory management for enzyme-coated test strips. By integrating these high-performance diagnostic tools into daily clinical protocols, healthcare providers effectively optimize capital expenditure while maintaining rigorous compliance with evolving institutional safety mandates and quality control standards.

What are the Key Data Covered in this Point Of Care Glucose Testing Market Research and Growth Report?

  • What is the expected growth of the Point Of Care Glucose Testing Market between 2026 and 2030?

    • USD 993.2 million, at a CAGR of 5.1%

  • What segmentation does the market report cover?

    • The report is segmented by Type (Strips, Lancets and lancing devices, and Meters), End-user (Hospitals and clinics, Home care settings, Diagnostic laboratories, and Others), Application (Type 2 diabetes, Type 1 diabetes, Gestational diabetes, and Others) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Rising global prevalence of diabetes and metabolic disorders, Strict regulatory standards and complex product approval frameworks

  • Who are the major players in the Point Of Care Glucose Testing Market?

    • A. Menarini Diagnostics S.r.l., Abbott Laboratories, ACON Laboratories Inc., Agamatrix Inc., ARKRAY Inc., Ascensia Diabetes Care, Bionime Corp., EKF Diagnostics Holdings Plc, F. Hoffmann La Roche Ltd., I SENS Inc., LifeScan IP Holdings LLC, Nipro Corp., Nova Biomedical Corp., Prodigy Diabetes Care LLC, PTS Diagnostics, Sensa Core Medical Instrumentation, Siemens Healthineers AG, Sinocare Inc., TaiDoc Technology Corp. and Trivida Health Inc.

Market Research Insights

  • The Point Of Care Glucose Testing Market is undergoing a rapid digital transformation characterized by the integration of remote patient monitoring and automated dosage adjustment algorithms. By embedding mobile health application connectivity into handheld diagnostic devices, outpatient care clinics have improved patient compliance tracking by 22%.
  • Furthermore, the deployment of metabolic tracking systems in long-term care facilities has reduced emergency readmissions related to acute glycemic variability by 18%. This strategic shift toward decentralized bedside diagnostic testing enables healthcare providers to minimize administrative bottlenecks while ensuring precise insulin therapy adjustment, ultimately optimizing resource allocation and clinical intervention efficiency.

We can help! Our analysts can customize this point of care glucose testing market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Point Of Care Glucose Testing Market 2020 - 2024

Historic Market Size - Data Table on Global Point Of Care Glucose Testing Market 2020 - 2024 ($ million)

5.2 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.4 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global point of care glucose testing market

6.2 Impact of geopolitical conflicts on global point of care glucose testing market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Type

8.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

8.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

8.3 Strips - Market size and forecast 2025-2030

Chart on Strips - Market size and forecast 2025-2030 ($ million)
Data Table on Strips - Market size and forecast 2025-2030 ($ million)
Chart on Strips - Year-over-year growth 2025-2030 (%)
Data Table on Strips - Year-over-year growth 2025-2030 (%)

8.4 Lancets and lancing devices - Market size and forecast 2025-2030

Chart on Lancets and lancing devices - Market size and forecast 2025-2030 ($ million)
Data Table on Lancets and lancing devices - Market size and forecast 2025-2030 ($ million)
Chart on Lancets and lancing devices - Year-over-year growth 2025-2030 (%)
Data Table on Lancets and lancing devices - Year-over-year growth 2025-2030 (%)

8.5 Meters - Market size and forecast 2025-2030

Chart on Meters - Market size and forecast 2025-2030 ($ million)
Data Table on Meters - Market size and forecast 2025-2030 ($ million)
Chart on Meters - Year-over-year growth 2025-2030 (%)
Data Table on Meters - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 Hospitals and clinics - Market size and forecast 2025-2030

Chart on Hospitals and clinics - Market size and forecast 2025-2030 ($ million)
Data Table on Hospitals and clinics - Market size and forecast 2025-2030 ($ million)
Chart on Hospitals and clinics - Year-over-year growth 2025-2030 (%)
Data Table on Hospitals and clinics - Year-over-year growth 2025-2030 (%)

9.4 Home care settings - Market size and forecast 2025-2030

Chart on Home care settings - Market size and forecast 2025-2030 ($ million)
Data Table on Home care settings - Market size and forecast 2025-2030 ($ million)
Chart on Home care settings - Year-over-year growth 2025-2030 (%)
Data Table on Home care settings - Year-over-year growth 2025-2030 (%)

9.5 Diagnostic laboratories - Market size and forecast 2025-2030

Chart on Diagnostic laboratories - Market size and forecast 2025-2030 ($ million)
Data Table on Diagnostic laboratories - Market size and forecast 2025-2030 ($ million)
Chart on Diagnostic laboratories - Year-over-year growth 2025-2030 (%)
Data Table on Diagnostic laboratories - Year-over-year growth 2025-2030 (%)

9.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.7 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

10. Market Segmentation by Application

10.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

10.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

10.3 Type 2 diabetes - Market size and forecast 2025-2030

Chart on Type 2 diabetes - Market size and forecast 2025-2030 ($ million)
Data Table on Type 2 diabetes - Market size and forecast 2025-2030 ($ million)
Chart on Type 2 diabetes - Year-over-year growth 2025-2030 (%)
Data Table on Type 2 diabetes - Year-over-year growth 2025-2030 (%)

10.4 Type 1 diabetes - Market size and forecast 2025-2030

Chart on Type 1 diabetes - Market size and forecast 2025-2030 ($ million)
Data Table on Type 1 diabetes - Market size and forecast 2025-2030 ($ million)
Chart on Type 1 diabetes - Year-over-year growth 2025-2030 (%)
Data Table on Type 1 diabetes - Year-over-year growth 2025-2030 (%)

10.5 Gestational diabetes - Market size and forecast 2025-2030

Chart on Gestational diabetes - Market size and forecast 2025-2030 ($ million)
Data Table on Gestational diabetes - Market size and forecast 2025-2030 ($ million)
Chart on Gestational diabetes - Year-over-year growth 2025-2030 (%)
Data Table on Gestational diabetes - Year-over-year growth 2025-2030 (%)

10.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.4.6 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ million)
Data Table on Asia - Market size and forecast 2025-2030 ($ million)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Thailand - Market size and forecast 2025-2030

Chart on Thailand - Market size and forecast 2025-2030 ($ million)
Data Table on Thailand - Market size and forecast 2025-2030 ($ million)
Chart on Thailand - Year-over-year growth 2025-2030 (%)
Data Table on Thailand - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.3 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.5 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.6 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.7 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.6.8 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Rising global prevalence of diabetes and metabolic disorders
Expanding clinical adoption of continuous glucose monitoring
Decentralization of healthcare services and outpatient care

13.2 Market challenges

Strict regulatory standards and complex product approval frameworks
Interference factors and analytical accuracy limitations
Data security risks and enterprise interoperability bottlenecks

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Development of multi-analyte point of care sensors
Integration of predictive AI and analytics
Shift toward fully automated closed-loop delivery ecosystems

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 A. Menarini Diagnostics S.r.l.

A. Menarini Diagnostics S.r.l. - Overview
A. Menarini Diagnostics S.r.l. - Product / Service
A. Menarini Diagnostics S.r.l. - Key offerings
SWOT

15.5 Abbott Laboratories

Abbott Laboratories - Overview
Abbott Laboratories - Business segments
Abbott Laboratories - Key news
Abbott Laboratories - Key offerings
Abbott Laboratories - Segment focus
SWOT

15.6 ACON Laboratories Inc.

ACON Laboratories Inc. - Overview
ACON Laboratories Inc. - Product / Service
ACON Laboratories Inc. - Key offerings
SWOT

15.7 ARKRAY Inc.

ARKRAY Inc. - Overview
ARKRAY Inc. - Product / Service
ARKRAY Inc. - Key offerings
SWOT

15.8 Ascensia Diabetes Care

Ascensia Diabetes Care - Overview
Ascensia Diabetes Care - Product / Service
Ascensia Diabetes Care - Key offerings
SWOT

15.9 Bionime Corp.

Bionime Corp. - Overview
Bionime Corp. - Product / Service
Bionime Corp. - Key offerings
SWOT

15.10 EKF Diagnostics Holdings Plc

EKF Diagnostics Holdings Plc - Overview
EKF Diagnostics Holdings Plc - Business segments
EKF Diagnostics Holdings Plc - Key offerings
EKF Diagnostics Holdings Plc - Segment focus
SWOT

15.11 F. Hoffmann La Roche Ltd.

F. Hoffmann La Roche Ltd. - Overview
F. Hoffmann La Roche Ltd. - Business segments
F. Hoffmann La Roche Ltd. - Key news
F. Hoffmann La Roche Ltd. - Key offerings
F. Hoffmann La Roche Ltd. - Segment focus
SWOT

15.12 I SENS Inc.

I SENS Inc. - Overview
I SENS Inc. - Product / Service
I SENS Inc. - Key offerings
SWOT

15.13 LifeScan IP Holdings LLC

LifeScan IP Holdings LLC - Overview
LifeScan IP Holdings LLC - Product / Service
LifeScan IP Holdings LLC - Key offerings
SWOT

15.14 Nipro Corp.

Nipro Corp. - Overview
Nipro Corp. - Business segments
Nipro Corp. - Key offerings
Nipro Corp. - Segment focus
SWOT

15.15 Nova Biomedical Corp.

Nova Biomedical Corp. - Overview
Nova Biomedical Corp. - Product / Service
Nova Biomedical Corp. - Key offerings
SWOT

15.16 Prodigy Diabetes Care LLC

Prodigy Diabetes Care LLC - Overview
Prodigy Diabetes Care LLC - Product / Service
Prodigy Diabetes Care LLC - Key offerings
SWOT

15.17 Siemens Healthineers AG

Siemens Healthineers AG - Overview
Siemens Healthineers AG - Business segments
Siemens Healthineers AG - Key offerings
Siemens Healthineers AG - Segment focus
SWOT

15.18 Sinocare Inc.

Sinocare Inc. - Overview
Sinocare Inc. - Product / Service
Sinocare Inc. - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Point Of Care Glucose Testing market growth will increase by USD 993.2 million during 2026-2030.

The Point Of Care Glucose Testing market is expected to grow at a CAGR of 5.1% during 2026-2030.

Point Of Care Glucose Testing market is segmented by Type (Strips, Lancets and lancing devices, Meters) End-user (Hospitals and clinics, Home care settings, Diagnostic laboratories, Others) Application (Type 2 diabetes, Type 1 diabetes, Gestational diabetes, Others)

A. Menarini Diagnostics S.r.l., Abbott Laboratories, ACON Laboratories Inc., Agamatrix Inc., ARKRAY Inc., Ascensia Diabetes Care, Bionime Corp., EKF Diagnostics Holdings Plc, F. Hoffmann La Roche Ltd., I SENS Inc., LifeScan IP Holdings LLC, Nipro Corp., Nova Biomedical Corp., Prodigy Diabetes Care LLC, PTS Diagnostics, Sensa Core Medical Instrumentation, Siemens Healthineers AG, Sinocare Inc., TaiDoc Technology Corp., Trivida Health Inc. are a few of the key vendors in the Point Of Care Glucose Testing market.

Europe will register the highest growth rate of 33.6% among the other regions. Therefore, the Point Of Care Glucose Testing market in Europe is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, The Netherlands, Spain, China, Japan, India, South Korea, Thailand, Indonesia, Brazil, Saudi Arabia, UAE, Turkey, Argentina, South Africa, Colombia, Israel

  • Rising global prevalence of diabetes and metabolic disorders is the driving factor this market.

The Point Of Care Glucose Testing market vendors should focus on grabbing business opportunities from the Type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
