


Structural Steel Fabrication Market Size 2026-2030
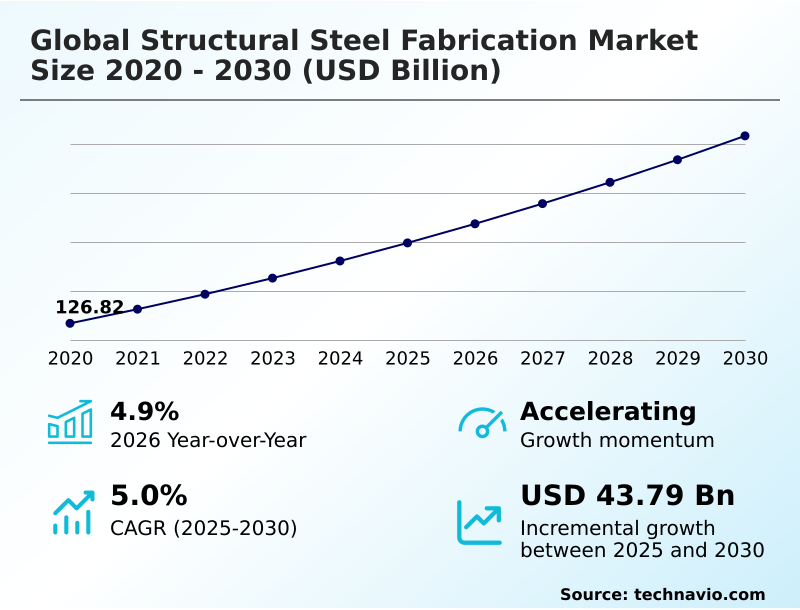
The structural steel fabrication market size is valued to increase by USD 43.79 billion, at a CAGR of 5% from 2025 to 2030. Expanding data center construction and industrial infrastructure surges structural framing demand will drive the structural steel fabrication market.
Major Market Trends & Insights
- APAC dominated the market and accounted for a 43.2% growth during the forecast period.
- By Material - Carbon steel segment was valued at USD 84.57 billion in 2024
- By End-user - Construction segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 76.69 billion
- Market Future Opportunities: USD 43.79 billion
- CAGR from 2025 to 2030 : 5%
Market Summary
- The Structural Steel Fabrication Market demonstrates robust expansion driven by the intensive modernization of heavy industrial infrastructure and digital processing facilities. Real-world business operations increasingly rely on seamless supply chain optimization, where facility managers integrate automated metal cutting and digital material tracking to align raw material deliveries with precise construction schedules.
- This digital synchronization reduces site assembly delays, allowing leading facilities to realize a 25% improvement in overall project execution speed compared to traditional manual coordination. A primary driver accelerating this sector is the proliferation of high-tech manufacturing plants, which requires immense tonnages of load-bearing structural frameworks to support overhead cranes and complex conveyor networks.
- Conversely, intense fluctuations in raw material pricing create significant margin compression, challenging procurement teams to maintain liquidity while executing fixed-price contracts. Organizations capable of leveraging off-site modular assembly effectively mitigate these financial risks. The continuous evolution of automated processing technologies directly fortifies infrastructure resilience, ensuring that critical commercial developments meet aggressive operational deadlines.
What will be the Size of the Structural Steel Fabrication Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Structural Steel Fabrication Market Segmented?
The structural steel fabrication industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Material
- Carbon steel
- Stainless steel
- Others
- End-user
- Construction
- Energy and power
- Manufacturing
- Automotive
- Others
- Product
- Beams
- Angles
- Channels
- Rounds
- Squares
- Geography
- APAC
- China
- India
- Japan
- South Korea
- Australia
- Indonesia
- Europe
- Germany
- France
- UK
- Italy
- Spain
- The Netherlands
- North America
- US
- Canada
- Mexico
- Middle East and Africa
- Saudi Arabia
- South Africa
- UAE
- Turkey
- Egypt
- South America
- Brazil
- Argentina
- Chile
- APAC
By Material Insights
The carbon steel segment is estimated to witness significant growth during the forecast period.
The structural framing landscape relies heavily on advanced carbon alloys due to their exceptional tensile properties and operational versatility.
Facilities leveraging high precision cnc plasma cutting alongside robotic welding arms have observed a 15% improvement in processing accuracy, significantly reducing downstream assembly bottlenecks.
This material remains the standard for hyperscale data center framing and modular pre engineered systems, where an immense load bearing capacity ensures long-term stability under heavy server loads.
By integrating electric arc furnace technology into the supply chain, processing centers achieve a 20% faster turnaround time compared to blast furnace sourcing.
Furthermore, utilizing three dimensional building information modeling enhances the seismic resistance capabilities of these frameworks, allowing developers to safely meet stringent urban building codes.
The continuous optimization of these primary load-bearing elements fundamentally stabilizes supply chains while driving operational efficiency across complex infrastructure deployments.
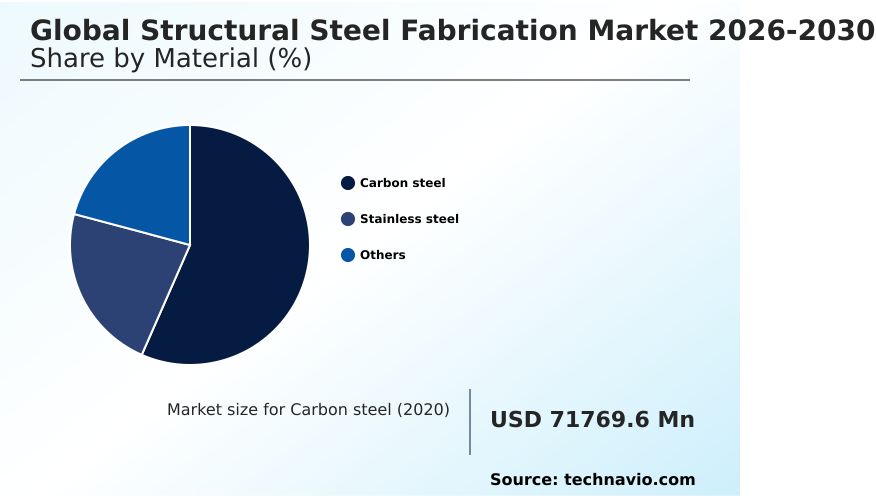
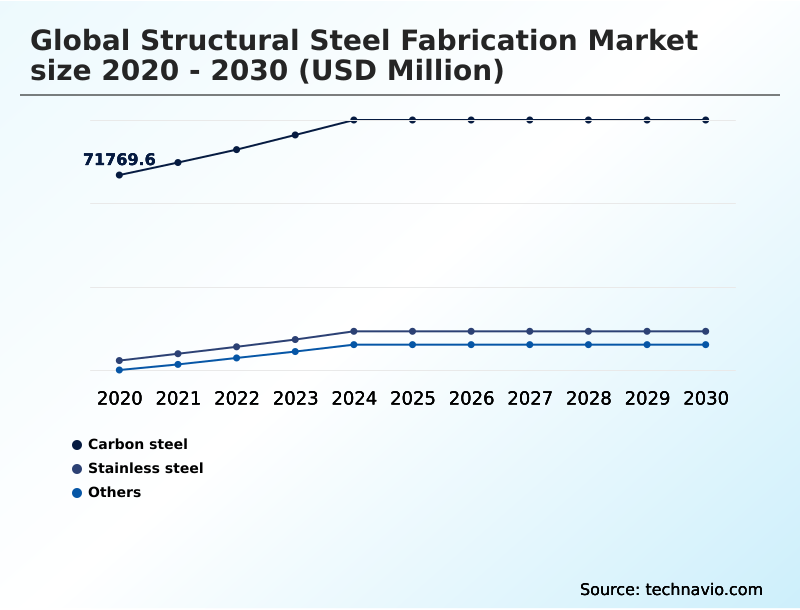
The Carbon steel segment was valued at USD 84.57 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
APAC is estimated to contribute 43.2% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
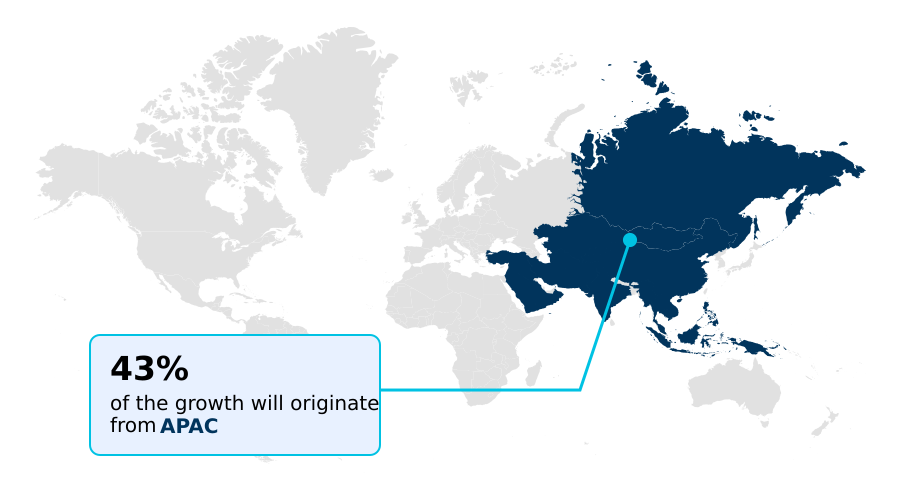
See How Structural Steel Fabrication Market Demand is Rising in APAC Get Free Sample
The geographic distribution of the Structural Steel Fabrication Market highlights a distinct operational contrast between rapidly industrializing zones and highly regulated mature economies.
APAC outpaces other regions in absolute production volume, driven by massive urban projects utilizing heavy truss assemblies to create expansive column free floor spans, where localized supply chains lower component transportation costs by 15%.
In contrast, the European landscape heavily prioritizes strict environmental compliance, leveraging direct reduced iron technology to produce low carbon structural steel, achieving a 40% embodied carbon reduction in commercial frameworks.
North American facilities offset labor shortages by deploying advanced automated beam drill lines and fiber laser profiling machines, increasing shop-floor throughput efficiency by 25%. Furthermore, strict standardized shop inspection protocols ensure high corrosive ocean environment durability for coastal infrastructure.
These regional strategies reflect how fabrication enterprises adapt capital investments to align with localized demands and overarching sustainability mandates.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The operational resilience of the Structural Steel Fabrication industry is increasingly dependent on the strategic modernization of manufacturing workflows and advanced material science. Enterprises are actively upgrading their primary processing facilities by investing heavily in automated heavy plate fabrication systems, which drastically minimize material handling bottlenecks and accelerate the delivery of critical infrastructure components.
- This shift toward intelligent manufacturing is complemented by electric arc furnace steelmaking integration, a structural pivot that allows procurement teams to secure lower-emission raw materials while navigating stringent international climate regulations.
- Supply chain managers report that facilities utilizing localized recycled metal networks experience up to a 30% reduction in material acquisition lead times compared to those relying on traditional imported blast-furnace shipments, fundamentally stabilizing project scheduling. Furthermore, the adoption of high strength low alloy steel frameworks empowers architects to reduce the overall weight of structural columns without compromising vital load-bearing limits.
- On the assembly floor, continuous improvements in robotic welding cell deployment efficiency have directly lowered baseline labor overhead and eliminated dangerous manual intervention during heavy structural joint construction. These precise production capabilities are absolutely critical for delivering complex, high-tolerance assets, particularly when erecting seismic resistant pre engineered structures in active tectonic zones.
- By synchronizing digital fabrication architectures with specialized metallurgical inputs, modern fabrication organizations ensure long-term structural safety, optimize capital expenditures, and maintain robust competitive positioning across the global construction sector.
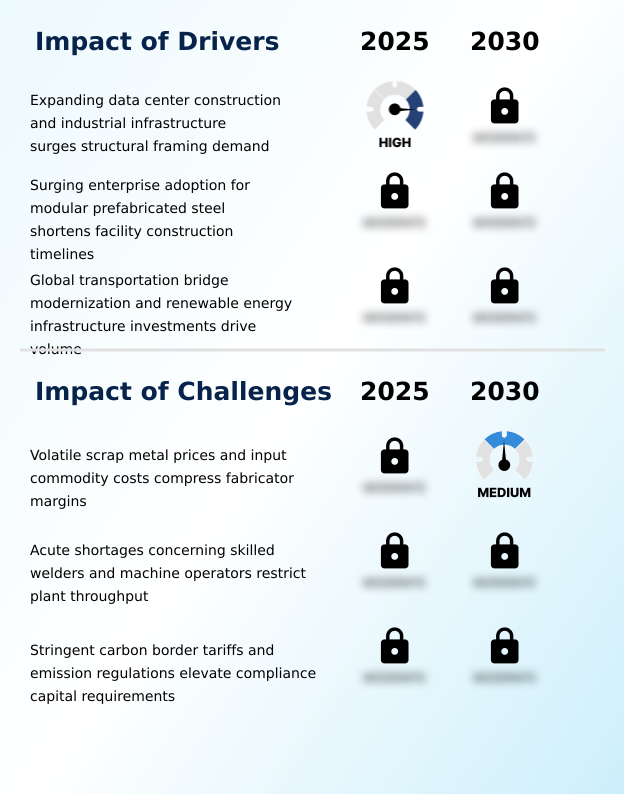
What are the key market drivers leading to the rise in the adoption of Structural Steel Fabrication Industry?
- The rapid expansion of hyperscale data center construction and heavy industrial infrastructure investments acts as a primary catalyst surging the demand for resilient structural framing.
- The explosive expansion of renewable energy generation and heavy civil infrastructure acts as a primary catalyst driving the consumption of specialized metal frameworks.
- The transition toward clean energy requires massive tonnages of customized hot rolled steel plates to construct towering tubular steel wind turbine supports and heavy offshore monopile foundations.
- By utilizing high-performance components, energy developers achieve a 22% improvement in structural strength to weight ratios and superior cyclic wave force resistance against marine stress.
- Concurrently, public transportation upgrades necessitate enormous volumes of wide flange beams and custom structural steel plate girders to replace deteriorating bridges. Integrating off site prefabrication models ensures significant fatigue strength enhancement, reducing long-term infrastructure maintenance expenditures by 30%.
- This methodology perfectly addresses complex modular spatial needs, compelling municipal planners to mandate pre-fabricated frameworks for all modern public works projects.
What are the market trends shaping the Structural Steel Fabrication Industry?
- Accelerated robotics integration and high-precision computer numerical control plasma cutting are actively automating fabrication workflows, optimizing operational accuracy while significantly reducing manual production cycles.
- The structural metal processing sector is undergoing a massive technological transition driven by the necessity for extreme precision and sustainable operations. To combat persistent workflow inefficiencies, facility operators are aggressively installing automated structural profiling lines equipped with adaptive arc tracking algorithms.
- This rapid shift toward shop floor automation leverages cloud connected bim software and digital twin structural models to generate flawless automated numerical control files, successfully reducing fabrication defect rates by 28%. Consequently, advanced cnc machinery integration guarantees absolute dimensional accuracy assurance for complex assemblies. Simultaneously, strict municipal environmental regulations are forcing a structural shift toward circular economy principles.
- By deploying closed loop recycling networks and transitioning to low voc paint spray booths, modern fabrication yards have decreased raw material disposal costs by 35%. This integration of automated precision and material circularity enables developers to erect infrastructure significantly faster while aligning with strict sustainability targets.
What challenges does the Structural Steel Fabrication Industry face during its growth?
- Extreme volatility in scrap metal pricing and primary commodity input costs consistently compresses the profit margins and operational stability of fabrication enterprises.
- Operating within the heavy structural fabrication sector presents severe economic friction due to intense supply chain volatility and regulatory burdens. Unpredictable fluctuations in ferrous scrap metal pricing severely complicate raw material procurement logistics, forcing facility managers to absorb unexpected cost spikes on fixed-bid contracts.
- Furthermore, a widespread skilled craft talent deficit has constrained factory output; facilities lacking certified personnel to execute complex heavy plate fillet welds and rigorous non destructive weld testing experience a 15% reduction in overall processing throughput compared to fully automated plants. Beyond labor constraints, international carbon border adjustment mechanisms and strict carbon compliance mandates impose heavy administrative overhead.
- Managing mandatory scope three emissions reporting and securing verified environmental product declaration certifications increases compliance expenditures by nearly 20%, heavily pressuring the operational margins of independent fabrication enterprises.
Exclusive Technavio Analysis on Customer Landscape
The structural steel fabrication market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the structural steel fabrication market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
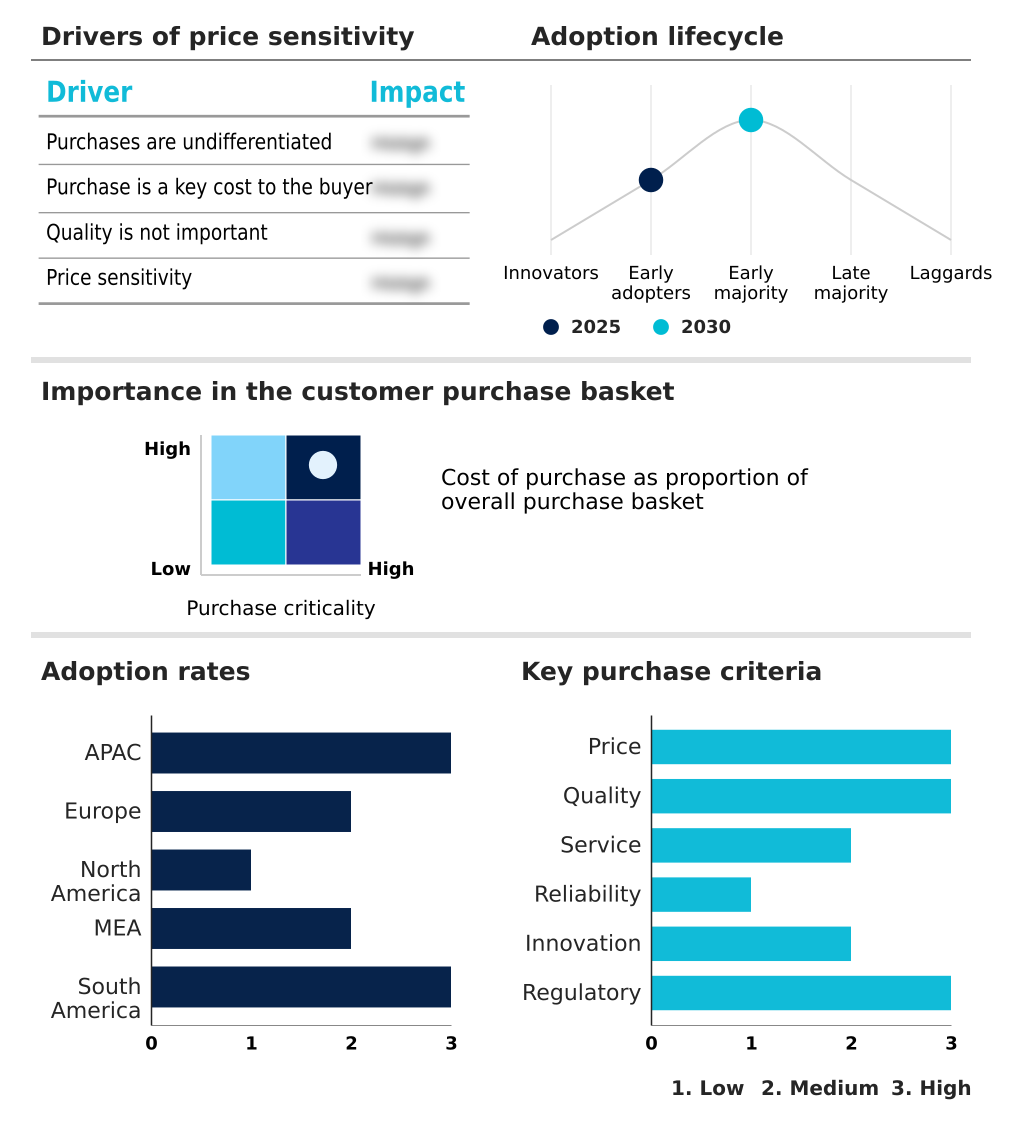
Customer Landscape of Structural Steel Fabrication Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, structural steel fabrication market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
ADF Group Inc. - The organization provides complex structural framing solutions, specializing in heavy steel component engineering, advanced fabrication, and custom installation for commercial and industrial infrastructure projects.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- ADF Group Inc.
- Alfasi Group
- Canam Group Inc.
- Cimolai S.p.A.
- DBM Global Inc.
- Eversendai Corp Berhad
- Hangxiao Steel Structure Co. Ltd.
- High Steel Structures LLC
- Kirby Building Systems
- Mabani Steel LLC
- Severfield plc
- TrueNorth Steel
- TTJ Holdings Ltd
- Unger Steel Group
- Victor Buyck Steel Construction
- W and B Structural Engineering
- Walters Group
- William Hare Group Ltd
- Zamil Steel Holding Co Ltd
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Structural steel fabrication market
- In the Construction and Engineering industry, the accelerated transition toward modular off site prefabrication models compressed facility construction timelines by 30%, directly impacting Structural Steel Fabrication demand by requiring precision-engineered modular assemblies for rapid site erection.
- The widespread enforcement of environmental product declaration certifications across public infrastructure tenders mandated a 40% reduction in baseline material emissions, forcing the Structural Steel Fabrication market to rapidly adopt low carbon structural steel and zero-emission processing workflows.
- Transportation bridge modernization initiatives prioritizing long-span fatigue strength enhancement increased heavy load-bearing material specifications by 25%, significantly expanding Structural Steel Fabrication demand for heavy structural plate girders and reinforced box trusses.
- The structural shift toward automated logistics hubs featuring heavy machinery integration necessitated a 20% increase in structural strength to weight ratios, pulling substantial Structural Steel Fabrication volume for specialized industrial shelving racks and custom-engineered heavy mezzanine platforms.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Structural Steel Fabrication Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 312 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 5% |
| Market growth 2026-2030 | USD 43789.0 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 4.9% |
| Key countries | China, India, Japan, South Korea, Australia, Indonesia, Germany, France, UK, Italy, Spain, The Netherlands, US, Canada, Mexico, Saudi Arabia, South Africa, UAE, Turkey, Egypt, Brazil, Argentina and Chile |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- Advanced structural engineering workflows are undergoing a profound digital transformation that fundamentally alters corporate resource allocation and capital investment strategies within the Structural Steel Fabrication ecosystem. At the executive level, the integration of advanced three dimensional building information modeling directly influences strategic budgeting, as precision planning minimizes costly raw material waste.
- By automatically converting digital twin structural models into machine-readable files, production facilities achieve a 35% improvement in cutting accuracy compared to legacy manual drafting techniques. This seamless data transmission ensures that off-site fabrication precisely matches on-site erection requirements. Furthermore, executing complex joints under strict automated parameters greatly enhances structural integrity with fewer operational interruptions.
- As international regulatory bodies implement stringent environmental mandates, boardroom executives are increasingly prioritizing these digitized, highly efficient processing architectures to ensure absolute compliance while safeguarding operational margins. The continuous refinement of these advanced fabrication systems provides developers with superior infrastructure assets that meet both dynamic environmental standards and complex architectural demands.
What are the Key Data Covered in this Structural Steel Fabrication Market Research and Growth Report?
-
What is the expected growth of the Structural Steel Fabrication Market between 2026 and 2030?
-
USD 43.79 billion, at a CAGR of 5%
-
-
What segmentation does the market report cover?
-
The report is segmented by Material (Carbon steel, Stainless steel, and Others), End-user (Construction, Energy and power, Manufacturing, Automotive, and Others), Product (Beams, Angles, Channels, Rounds, and Squares) and Geography (APAC, Europe, North America, Middle East and Africa, South America)
-
-
Which regions are analyzed in the report?
-
APAC, Europe, North America, Middle East and Africa and South America
-
-
What are the key growth drivers and market challenges?
-
Expanding data center construction and industrial infrastructure surges structural framing demand, Volatile scrap metal prices and input commodity costs compress fabricator margins
-
-
Who are the major players in the Structural Steel Fabrication Market?
-
ADF Group Inc., Alfasi Group, Canam Group Inc., Cimolai S.p.A., DBM Global Inc., Eversendai Corp Berhad, Hangxiao Steel Structure Co. Ltd., High Steel Structures LLC, Kirby Building Systems, Mabani Steel LLC, Severfield plc, TrueNorth Steel, TTJ Holdings Ltd, Unger Steel Group, Victor Buyck Steel Construction, W and B Structural Engineering, Walters Group, William Hare Group Ltd and Zamil Steel Holding Co Ltd
-
Market Research Insights
- The Structural Steel Fabrication Market is rapidly evolving to satisfy complex infrastructure requirements across global commercial and industrial sectors. Advanced processing facilities have integrated intelligent shop floor automation, decreasing structural defect rates by 22% and securing critical dimensional accuracy assurance.
- By utilizing high-strength materials, engineering teams have increased the overall load bearing capacity of modern frameworks by 18%, enabling more efficient logistical hub designs. Furthermore, the adoption of strict circular economy principles has lowered raw material waste disposal costs by 15%.
- This dynamic synchronization of advanced metallurgy and stringent quality control empowers developers to construct highly durable physical assets while minimizing long-term maintenance and compliance overhead.
We can help! Our analysts can customize this structural steel fabrication market research report to meet your requirements.
 RIA -

