


US Biochar Market Size 2026-2030
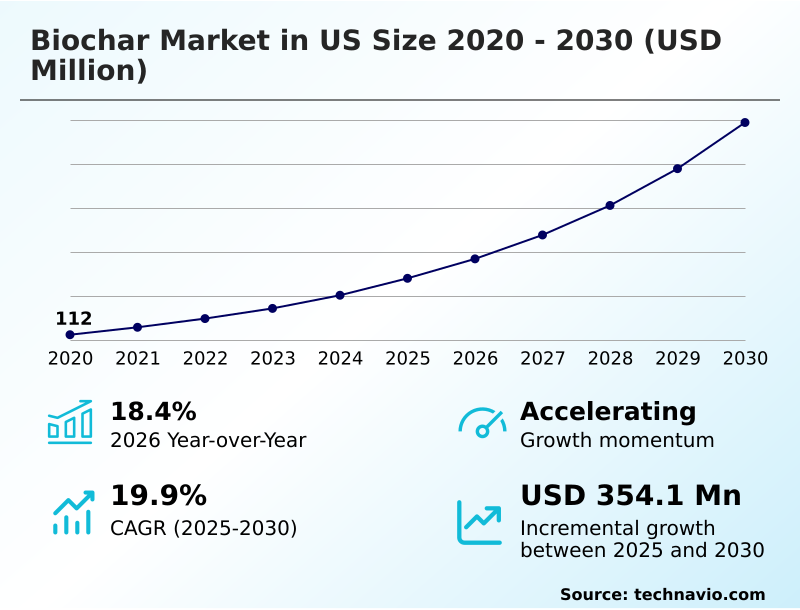
The us biochar market size is valued to increase by USD 354.1 million, at a CAGR of 19.9% from 2025 to 2030. Expanding agricultural sector demand for long term soil moisture retention enhancements will drive the us biochar market.
Major Market Trends & Insights
- By Technology - Pyrolysis segment was valued at USD 123.9 million in 2024
- By Application - Farming segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 482.3 million
- Market Future Opportunities: USD 354.1 million
- CAGR from 2025 to 2030 : 19.9%
Market Summary
- The Biochar Market in US operates as a critical intersection of agricultural optimization and environmental sustainability, systematically converting organic liabilities into high-integrity carbon assets. Expanding agricultural sector demand for long-term soil moisture retention enhancements acts as a primary catalyst for capacity expansion.
- Changing meteorological patterns force corporate farming enterprises to integrate highly porous carbon structures into topsoil, which act as microscopic sponges to capture water that would otherwise drain away. Consequently, large-scale commercial farming operations have registered a 25% improvement in overall irrigation efficiency when integrating these advanced soil amendments compared to untreated baselines.
- However, high initial capital expenditures for advanced pyrolysis infrastructure deployment operations severely restrict rapid capacity scaling. Installing commercial-scale reactors and comprehensive emission controls requires substantial upfront financing, effectively barring smaller agricultural cooperatives from market entry.
- In response to these financial pressures, major technology developers are optimizing supply chain logistics by co-locating modular thermal processing units directly adjacent to high-volume agricultural milling zones, completely eliminating long-distance feedstock transportation expenses.
What will be the Size of the US Biochar Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the US Biochar Market Segmented?
The us biochar industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Technology
- Pyrolysis
- Gasification
- Others
- Application
- Farming
- Power generation
- Others
- Feedstock
- Woody biomass
- Agricultural waste
- Animal manure
- Others
- Geography
- North America
- US
- North America
By Technology Insights
The pyrolysis segment is estimated to witness significant growth during the forecast period.
The pyrolysis segment leads operational adoption by transforming organic liabilities into high-value assets through precise thermal control mechanisms. By deploying machinery equipped with automated feedstock sorting, facilities operate without oxygen to prevent combustion.
This localized infrastructure retrofit consistently converts raw agricultural residues into a stable output, enhancing critical soil nutrient cycling properties. Operational efficiency metrics indicate that modern systems reduce external thermal energy dependency by 40%.
The resulting outputs significantly improve agricultural runoff mitigation while functioning as a powerful compost conditioning additive. Through such advanced biomass waste to value conversion, operators achieve zero reversal permanence, locking carbon reliably into subterranean matrices.
This engineered stability directly supports measurable crop resilience enhancement across degraded agricultural lands, solidifying pyrolysis as the dominant and most commercially viable segment.
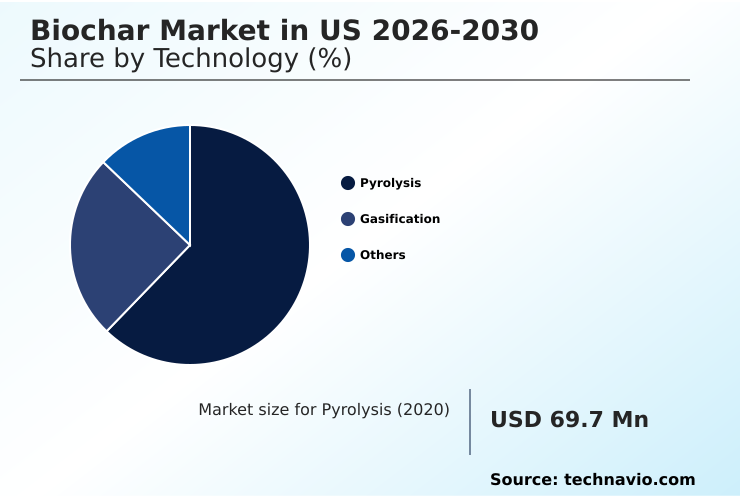
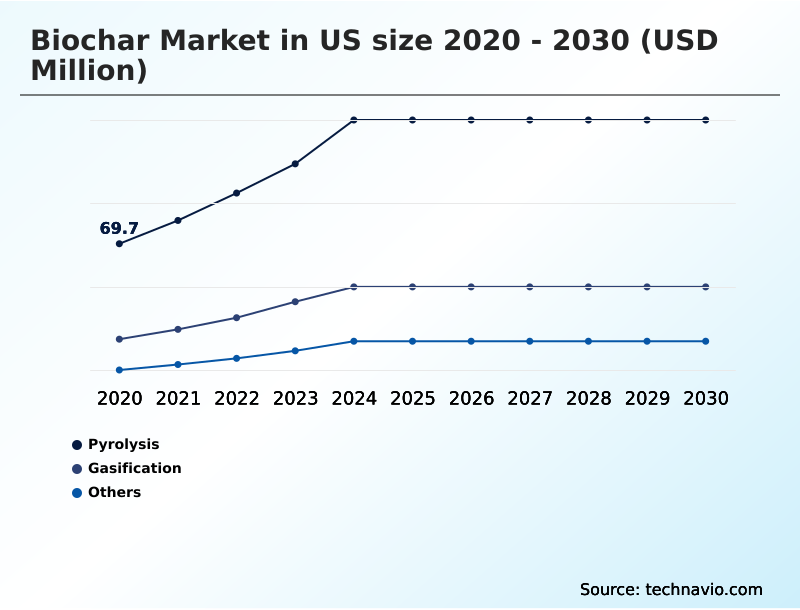
The Pyrolysis segment was valued at USD 123.9 million in 2024 and showed a gradual increase during the forecast period.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The strategic optimization of soil management and carbon abatement strategies heavily relies on deploying a high stability carbon rich material across diverse agronomic landscapes. Industrial-scale processors are increasingly focused on refining agricultural waste thermal decomposition to produce highly consistent, standardized carbon assets.
- By implementing advanced closed loop pyrolysis technology, facility operators not only eliminate external energy dependencies but also drastically reduce the ambient emission footprints of their manufacturing sites. This operational shift yields a superior product engineered specifically for biogenic carbon dioxide removal, allowing corporate farming networks and sustainability-focused municipalities to secure verified carbon offset certificates.
- Furthermore, the structural integration of these carbon matrices into degraded topsoil provides a reliable mechanism for long term soil moisture retention, insulating vulnerable crops against severe seasonal drought stress. When comparing precision-engineered carbon amendments to traditional organic compost applications, modern commercial farms achieve an approximately 40% improvement in irrigation water utilization efficiency.
- This significant efficiency gain directly impacts supply chain water logistics, drastically lowering the operational pumping costs required to sustain high-yield crop production during arid months. As environmental compliance regulations become increasingly stringent, the ability to trace and verify carbon permanence through precise manufacturing protocols has become a paramount business requirement.
- Agricultural managers and institutional investors alike recognize that standardizing these thermal conversion techniques secures both immediate agronomic resilience and long-term regulatory alignment within emerging carbon trading frameworks.
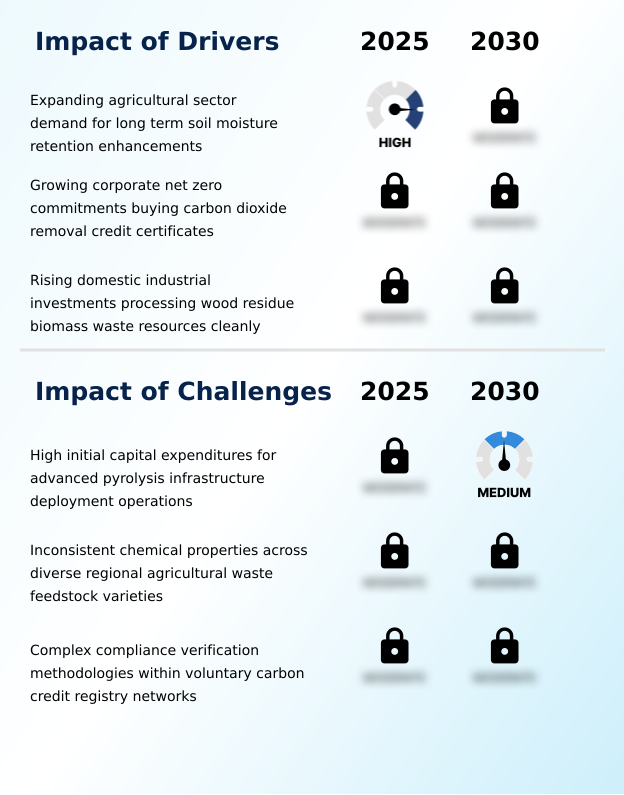
What are the key market drivers leading to the rise in the adoption of US Biochar Industry?
- The sustained expansion of the market is powerfully driven by expanding agricultural sector demand for long-term soil moisture retention enhancements.
- The escalating frequency of severe drought forces enterprises to adopt solutions maximizing nutrient immobilization capacity and water preservation.
- Utilizing a highly optimized rotary kiln pyrolyzer, manufacturers control the thermal decomposition profile to transform organic waste into a durable biogenic silica structure. This organic waste valorization creates a microscopic subterranean sponge that actively supports a robust mycorrhizal fungi network.
- Such engineered porosity directly enables large-scale commercial environmental remediation operations, allowing farms to sustain yields during dry spells. Field metrics reveal a 35% improvement in root moisture retention.
- By integrating a modular gasification unit, operators simultaneously capitalize on thermal energy recovery, reducing synthetic input costs by 25%. This dual-purpose mechanism ensures strict compliance while generating a lucrative carbon dioxide removal certificate for advanced offset trading.
What are the market trends shaping the US Biochar Industry?
- A prominent emerging trend is the strategic construction of specialized manufacturing facilities adjacent to high-volume regional rice processing zones. This localized deployment model optimizes supply chain logistics and accelerates commercial scalability.
- Industrial operators are rapidly pivoting toward decentralized thermochemical biomass conversion to mitigate raw material transportation constraints. This structural shift prioritizes a specialized slow pyrolysis reactor combined with a syngas recycling system, generating self-sustaining thermal dynamics. Localized processing hubs demonstrated a 45% reduction in overall facility energy expenditures compared to off-site models.
- This approach significantly optimizes sustainable biomass sourcing and closed loop thermal processing, securing consistent raw material volumes at a 20% lower cost. These facilities output a highly recalcitrant carbon matrix that guarantees verifiable carbon permanence for institutional carbon buyers. When distributed to neighboring farms, these products dramatically elevate the soil cation exchange capacity and create an ideal soil microbiome habitat.
- Such integrated regenerative agriculture protocol implementations establish a highly efficient regional economy that continuously bolsters commercial sustainability metrics without relying on external fossil fuels.
What challenges does the US Biochar Industry face during its growth?
- High initial capital expenditures for advanced pyrolysis infrastructure deployment operations constitute a primary challenge constraining rapid industrial capacity expansion.
- Advanced biomass conversion faces headwinds due to immense capital expenditures required to produce specialized outputs like carbon negative concrete and premium biogenic carbon additive. Establishing safe facilities demands sophisticated emission controls, severely limiting the establishment of a sustainable regional circular economy.
- Furthermore, processing variable organic inputs disrupts the thermal engineering necessary to optimize root zone structural porosity and consistent soil moisture retention. This inconsistency forces a 15% reduction in throughput efficiency, hindering topsoil erosion prevention. Supplying an effective structural soil amendment is vital for fertilizer leaching reduction and minimizing crop dehydration stress, yet scaling heavy metal filtration media remains cost-prohibitive.
- Consequently, securing institutional debt financing remains difficult, forcing developers to rely on 30% higher volumes of dilutive capital.
Exclusive Technavio Analysis on Customer Landscape
The us biochar market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the us biochar market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
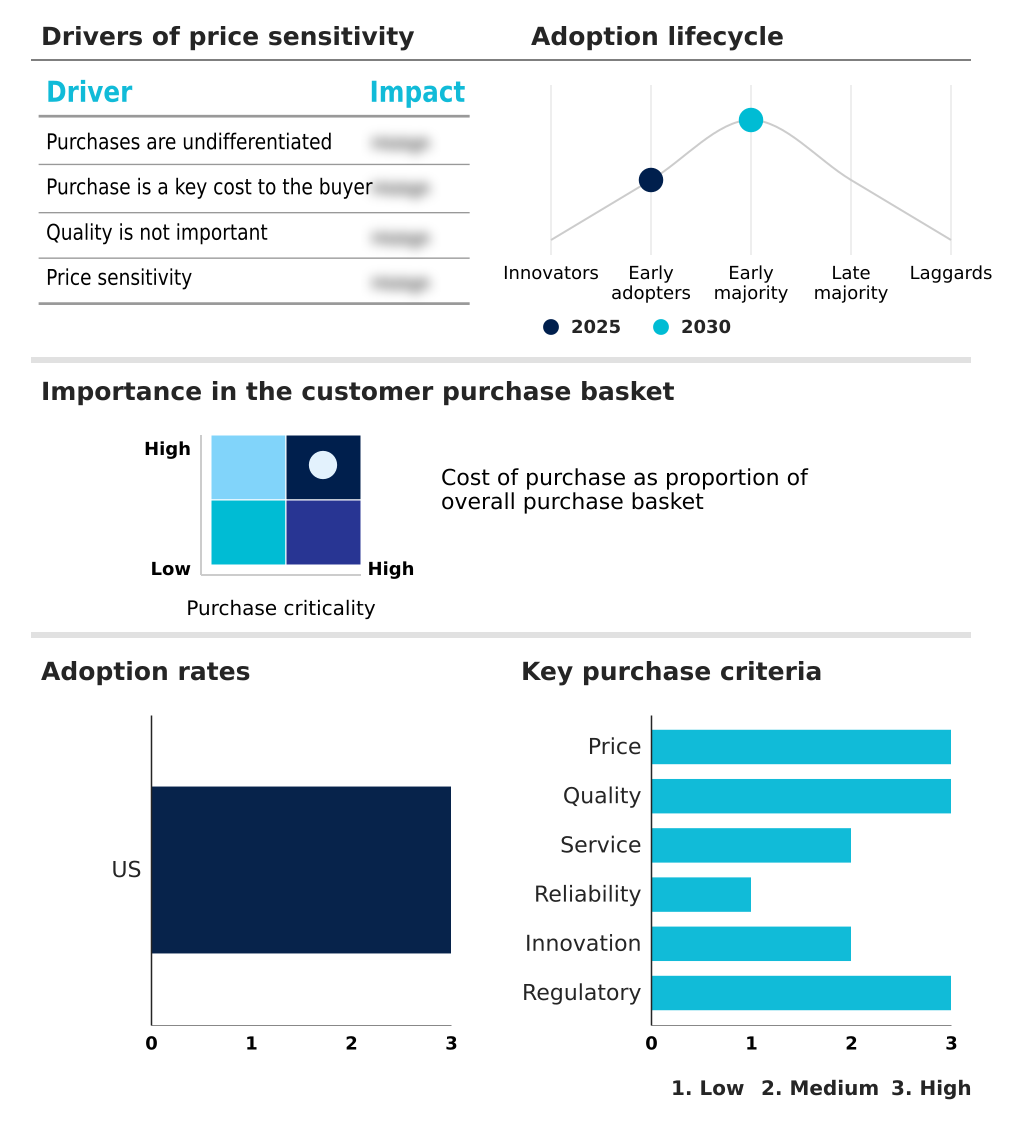
Customer Landscape of US Biochar Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, us biochar market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
ALL Power Labs - Leading industry providers specialize in delivering high-purity biomass conversion solutions, including advanced carbon removal products and engineered soil amendments designed to optimize moisture retention and long-term carbon sequestration.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- ALL Power Labs
- Aries Clean Technologies LLC
- Avello Bioenergy Inc.
- Biochar Now LLC
- Biochar Supreme LLC
- Bioforcetech Corp.
- Blue Sky Biochar
- Carbo Culture co
- Char Direct LLC
- CharGrow LLC
- Coaltec Energy USA
- Ecotone Inc.
- Glanris Biocarbon Biochar
- High Plains Biochar LLC
- Karr Group
- Lewis Bamboo
- Pacific Biochar Benefit Corp.
- Seneca Farms Biochar LLC
- Standard Biocarbon Inc.
- VGrid Energy Systems Inc.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Us biochar market
- In the Oil and Gas Refining and Marketing industry, the accelerated transition toward decentralized biofuel production and syngas processing increased the deployment of thermochemical biomass conversion technologies, directly expanding the technical infrastructure available for concurrent biogenic carbon production.
- The tightening of industrial emission standards governing refinery flare systems prompted downstream operators to integrate closed loop thermal processing units, effectively validating the large-scale equipment frameworks required for commercial environmental remediation through stable carbon sequestration.
- The shift from conventional fossil fuel extraction to renewable feedstock refining reduced the availability of low-cost petroleum-based agricultural inputs, directly amplifying the demand for regenerative agriculture protocol alternatives like highly porous structural soil amendments.
- Stringent carbon intensity tracking mandates implemented across petroleum supply chains accelerated the adoption of rigorous emission monitoring system frameworks, standardizing the verification methodologies now utilized to authenticate verifiable carbon permanence in agricultural residue utilization.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled US Biochar Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 187 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 19.9% |
| Market growth 2026-2030 | USD 354.1 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 18.4% |
| Key countries | US |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The continuous evolution of thermal biomass conversion directly addresses the pressing operational needs of commercial agriculture and heavy industry infrastructure. Processors utilizing a precise slow pyrolysis reactor design achieve superior control over the thermal decomposition profile, generating a highly recalcitrant carbon matrix that resists microbial degradation.
- This structural resilience ensures that captured atmospheric carbon remains securely locked within subterranean layers for centuries. In large-scale farming applications, the incorporation of this biogenic carbon additive significantly elevates the base cation exchange capacity of depleted soils, effectively establishing a robust mycorrhizal fungi network that accelerates nutrient uptake in commercial crops.
- Agronomic data indicates that commercial growers deploying these advanced carbon matrices achieve a 30% reduction in synthetic fertilizer application requirements compared to traditional soil management practices. This measurable efficiency gain directly impacts corporate budgeting and environmental compliance by minimizing costly chemical inputs.
- Additionally, emerging engineering trials demonstrate that integrating these porous structures into carbon negative concrete formulations permanently traps volatile emissions while maintaining structural load-bearing integrity, presenting a viable decarbonization pathway for modern construction material supply chains.
What are the Key Data Covered in this US Biochar Market Research and Growth Report?
-
What is the expected growth of the US Biochar Market between 2026 and 2030?
-
USD 354.1 million, at a CAGR of 19.9%
-
-
What segmentation does the market report cover?
-
The report is segmented by Technology (Pyrolysis, Gasification, and Others), Application (Farming, Power generation, and Others), Feedstock (Woody biomass, Agricultural waste, Animal manure, and Others) and Geography (North America)
-
-
Which regions are analyzed in the report?
-
North America
-
-
What are the key growth drivers and market challenges?
-
Expanding agricultural sector demand for long term soil moisture retention enhancements, High initial capital expenditures for advanced pyrolysis infrastructure deployment operations
-
-
Who are the major players in the US Biochar Market?
-
ALL Power Labs, Aries Clean Technologies LLC, Avello Bioenergy Inc., Biochar Now LLC, Biochar Supreme LLC, Bioforcetech Corp., Blue Sky Biochar, Carbo Culture co, Char Direct LLC, CharGrow LLC, Coaltec Energy USA, Ecotone Inc., Glanris Biocarbon Biochar, High Plains Biochar LLC, Karr Group, Lewis Bamboo, Pacific Biochar Benefit Corp., Seneca Farms Biochar LLC, Standard Biocarbon Inc. and VGrid Energy Systems Inc.
-
Market Research Insights
- The Biochar Market in US demonstrates accelerated structural maturity as operators transition toward verified, high-permanence carbon dioxide removal methodologies. Facilities implementing closed loop thermal processing have reduced raw material transportation expenses by 35% through strategic co-location with agricultural processing hubs.
- By prioritizing verifiable carbon permanence, commercial producers have increased their successful enrollment in voluntary carbon registry programs by 40% compared to legacy open-burn disposal practices. The integration of modular gasification unit technology enables distributed agricultural networks to achieve a 20% reduction in external energy costs by capitalizing on localized thermal energy recovery.
- This systemic shift actively supports organic waste valorization, establishing a robust framework for large-scale carbon containment and enhanced agronomic performance.
We can help! Our analysts can customize this us biochar market research report to meet your requirements.
 RIA -

