Wood Coatings Market Analysis, Size, and Forecast 2026-2030: APAC (China, Japan, and India), Europe (Germany, UK, and France), North America (US, Canada, and Mexico), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Wood Coatings Market Analysis, Size, and Forecast 2026-2030:
APAC (China, Japan, and India), Europe (Germany, UK, and France), North America (US, Canada, and Mexico), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 310 Pages SKU: IRTNTR45158

Market Overview at a Glance

$4.05 B
Market Opportunity
5.4%
CAGR 2025 - 2030
46.3%
APAC Growth
$7.95 B
Stains and varnishes segment 2024

Wood Coatings Market Size 2026-2030

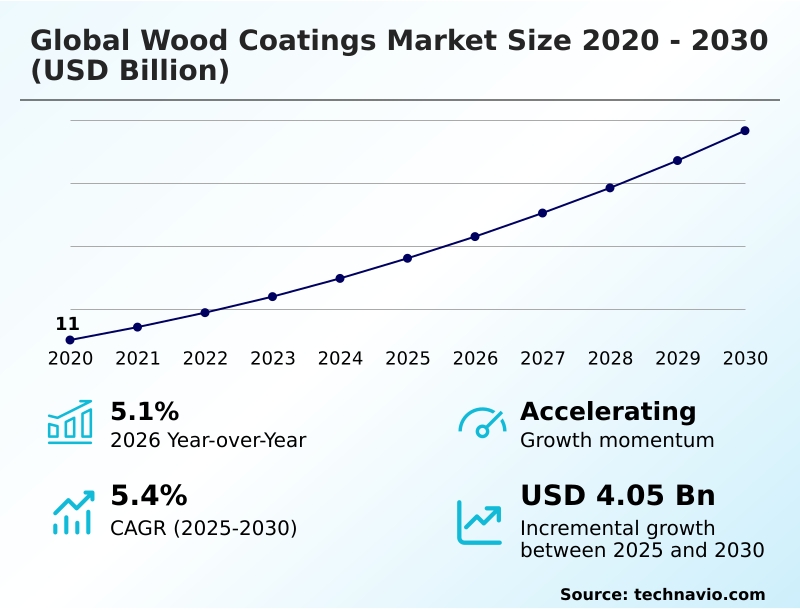
The wood coatings market size is valued to increase by USD 4.05 billion, at a CAGR of 5.4% from 2025 to 2030. Rising demand for wood coatings from developing countries will drive the wood coatings market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 46.3% growth during the forecast period.
  • By Product - Stains and varnishes segment was valued at USD 7.95 billion in 2024
  • By Technology - Solvent-based segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 6.66 billion
  • Market Future Opportunities: USD 4.05 billion
  • CAGR from 2025 to 2030 : 5.4%

Market Summary

  • The Wood Coatings Market is experiencing robust structural shifts as industrial manufacturers prioritize both aesthetic durability and regulatory alignment. Escalating demand from the expanding commercial construction sector acts as a primary driver, compelling producers to adopt advanced uv cured formulations that accelerate production lines.
  • For example, large-scale cabinet manufacturers implementing automated spray application wood coatings have realized a 20% reduction in material waste, significantly optimizing their operational overhead. Conversely, stringent environmental mandates limiting volatile organic emission levels present a persistent challenge, forcing companies to reformulate legacy solvent based varnishes into compliant alternatives. This compliance-driven reformulation often requires capital-intensive adjustments to existing curtain coating lines.
  • Navigating these regulatory bottlenecks while maintaining high gloss retention requires substantial investment in research and development. Ultimately, the transition toward waterborne wood coating system efficiency ensures that modern protective film formation meets both rigorous sustainability criteria and the high-performance demands of heavy foot traffic environments.

What will be the Size of the Wood Coatings Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Wood Coatings Market Segmented?

The wood coatings industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Product
    • Stains and varnishes
    • Wood preservatives
    • Shellacs
    • Others
  • Technology
    • Solvent-based
    • Water-based
    • Others
  • Application
    • Furniture and fixtures
    • Cabinets
    • Doors and windows
    • Others
  • Geography
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • North America
      • US
      • Canada
      • Mexico
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey

By Product Insights

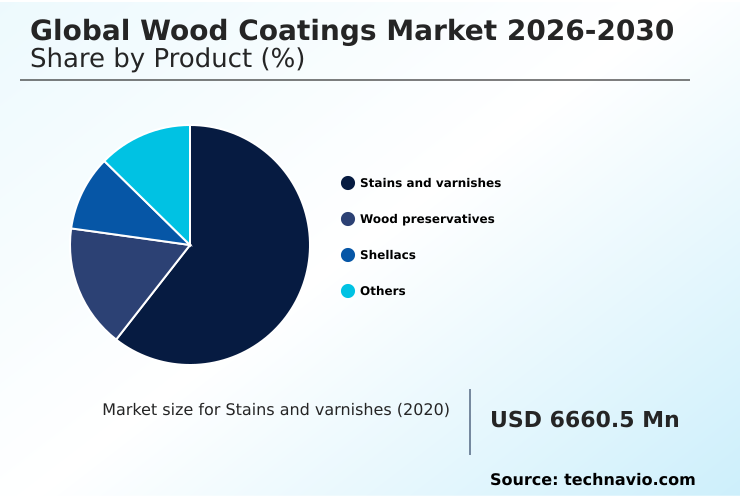
The stains and varnishes segment is estimated to witness significant growth during the forecast period.

The stains and varnishes segment commands significant operational influence within the Wood Coatings industry by providing essential decorative wood protection and structural integrity.

Formulations are shifting rapidly as industrial users transition from traditional solvent based varnishes to advanced waterborne coating technology, driven by rigorous environmental compliance standards.

This strategic migration has enabled manufacturers to reduce curing times by 15%, directly enhancing production throughput in high-volume furniture manufacturing. These coatings deliver superior wood grain enhancement while forming a durable moisture barrier creation that extends product lifespans.

As businesses prioritize sustainability, the integration of low emission resins and moisture resistant sealers minimizes volatile organic emission profiles without sacrificing surface adhesion strength. Consequently, production facilities experience fewer application defects, improving overall material yield and operational cost efficiency.
Get Free Sample

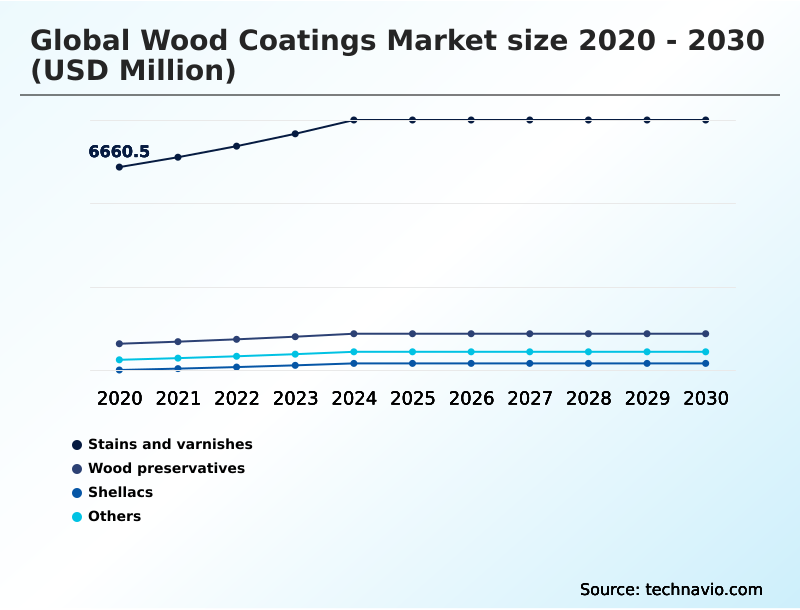
The Stains and varnishes segment was valued at USD 7.95 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 46.3% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
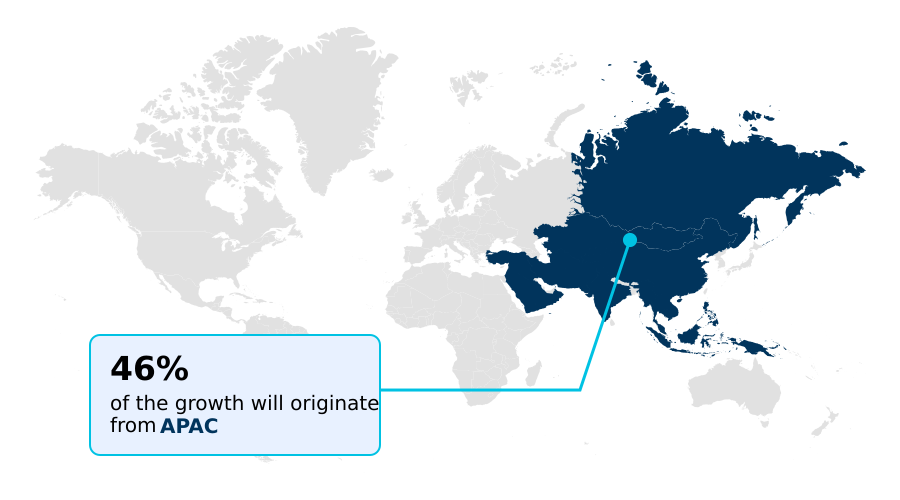
See How Wood Coatings Market Demand is Rising in APAC Get Free Sample

The regional dynamics of Wood Coatings highlight distinct strategic priorities across global manufacturing hubs. APAC leads adoption through massive furniture export volumes, demonstrating a 25% higher integration rate of automated spray systems compared to Europe.

This rapid industrialization in APAC reduces unit processing times by 18%, optimizing high-volume modular kitchen cabinetry production. Conversely, Europe prioritizes stringent environmental compliance standards, driving a 30% faster transition toward bio based resin wood preservatives than North American counterparts.

European facilities focus heavily on sustainable circular economy wood finishing, yielding a 12% improvement in lifecycle resource efficiency. While APAC maximizes throughput with fast-curing synthetic resin binders, Europe invests in low emission resins to secure green building certifications.

These divergent regional strategies illustrate how businesses continuously adapt their supply chains, balancing high-speed structural timber preservation with rigorous emission mandates to maintain global competitiveness.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • Strategic shifts in the Wood Coatings sector are fundamentally altering how manufacturers approach surface protection and environmental compliance. The optimization of waterborne wood coating system efficiency is becoming a baseline requirement for modern production facilities, yielding a 20% improvement in application speed compared to legacy solvent techniques.
  • This operational pivot heavily supports the demand for low emission wood furniture finishes, which are now critical for maintaining indoor air quality standards in commercial spaces. Furthermore, the integration of uv cured industrial coating applications allows assembly lines to accelerate throughput while reducing energy consumption.
  • Innovation is extending into specialized protective segments, where bio based resin wood preservatives and high performance exterior decking stains deliver superior weathering resistance without relying on toxic petrochemicals. As facilities upgrade their infrastructure, automated spray application wood coatings ensure uniform coverage, dramatically reducing material waste.
  • Simultaneously, the deployment of scratch resistant transparent wood varnishes and environmentally friendly interior cabinet coatings addresses consumer demand for aesthetic longevity. Heavy-duty construction elements also benefit from flame retardant structural timber finishes and moisture resistant architectural wood sealers, enhancing building safety.
  • The industry is increasingly guided by sustainable circular economy wood finishing principles, which parallel the adoption of smart manufacturing iot wood coatings for predictive maintenance. By utilizing advanced crosslinking agents in wood lacquers, producers achieve robust finish adhesion.
  • Ultimately, the development of weather resistant outdoor furniture finishes and high solids polyurethane wood coatings ensures that long-term structural integrity aligns with modern efficiency and ecological mandates.
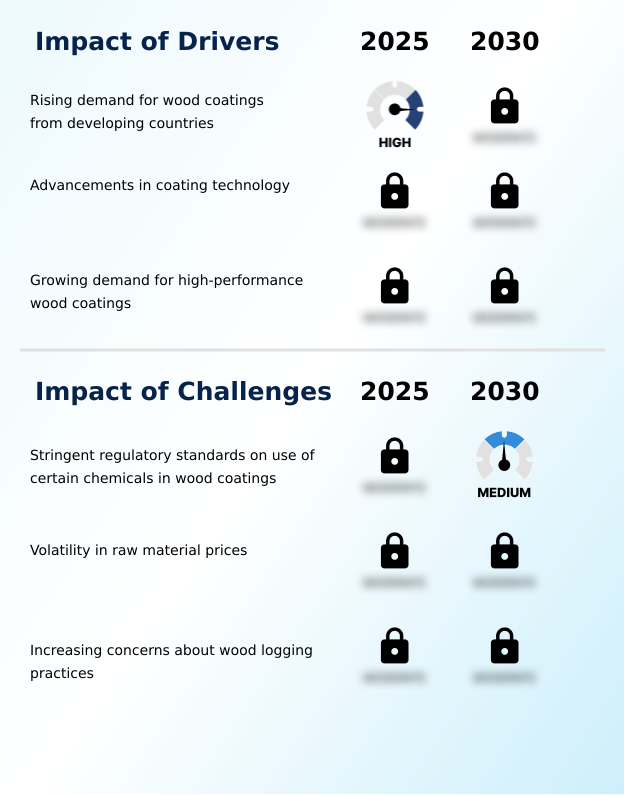
What are the key market drivers leading to the rise in the adoption of Wood Coatings Industry?

  • The escalating demand for durable wood coatings across developing nations, driven by rapid urbanization and expanding infrastructure construction, acts as a primary catalyst for market expansion.

  • The escalating enforcement of strict environmental compliance standards is a primary catalyst propelling the Wood Coatings sector toward sustainable innovation. Regulatory bodies are aggressively limiting volatile organic compounds, forcing manufacturers to phase out legacy formulations.
  • This legislative pressure causes a rapid transition toward waterborne coating technology and bio based resins. As a direct effect, businesses adopting these compliant formulations have improved their material utilization rates by 15% while avoiding severe regulatory penalties.
  • The deployment of low emission resins and advanced rheology additives ensures that aesthetic appeal enhancement is maintained without compromising worker safety.
  • Ultimately, this compliance-driven shift empowers producers to secure green building certifications, thereby accessing lucrative new commercial channels while delivering superior moisture barrier creation for modern architectural projects.

What are the market trends shaping the Wood Coatings Industry?

  • The increasing focus on circular economy frameworks and advanced recycling principles is emerging as a definitive trend shaping the market. Stakeholders are strategically adopting sustainable production models to minimize material waste and enhance overall resource efficiency.

  • The rapid integration of predictive maintenance analytics is fundamentally restructuring production methodologies within the Wood Coatings sector. This technological shift is caused by the urgent need to eliminate costly unplanned downtime in continuous manufacturing environments. By utilizing smart manufacturing sensors to monitor fluid dynamics and equipment health in real time, facilities have successfully reduced application equipment failures by 24%.
  • This proactive approach directly impacts businesses by improving the consistency of protective film formation and accelerating overall curing times. Furthermore, the precise control enabled by these digital tools optimizes the deployment of synthetic resin binders and crosslinking agents.
  • Consequently, manufacturers achieve superior high gloss retention and flawless decorative wood protection, ensuring that high-volume output perfectly aligns with rigorous quality parameters and operational cost efficiency targets.

What challenges does the Wood Coatings Industry face during its growth?

  • The implementation of stringent regulatory standards regarding the use of specific volatile chemicals in formulations presents a significant operational hurdle for market participants.

  • The inherent volatility of raw material supply chains presents a formidable operational bottleneck for the Wood Coatings sector. Fluctuations in the availability of petrochemical derivatives cause severe disruptions in the synthesis of polyurethane dispersion formulations and acrylic monomers. This instability directly impacts businesses by inflating input costs, which subsequently compresses profit margins and delays the fulfillment of large-scale industrial orders.
  • Facilities attempting to substitute materials often experience a 12% drop in first-pass yield rates due to inconsistent finish adhesion strength. Maintaining exterior cladding durability and specialized weather resistance becomes increasingly difficult when core surface pretreatment chemicals are rationed. To navigate these constraints, manufacturers must heavily invest in alternative renewable raw materials, temporarily straining operational budgets and complicating inventory management protocols.

Exclusive Technavio Analysis on Customer Landscape

The wood coatings market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the wood coatings market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
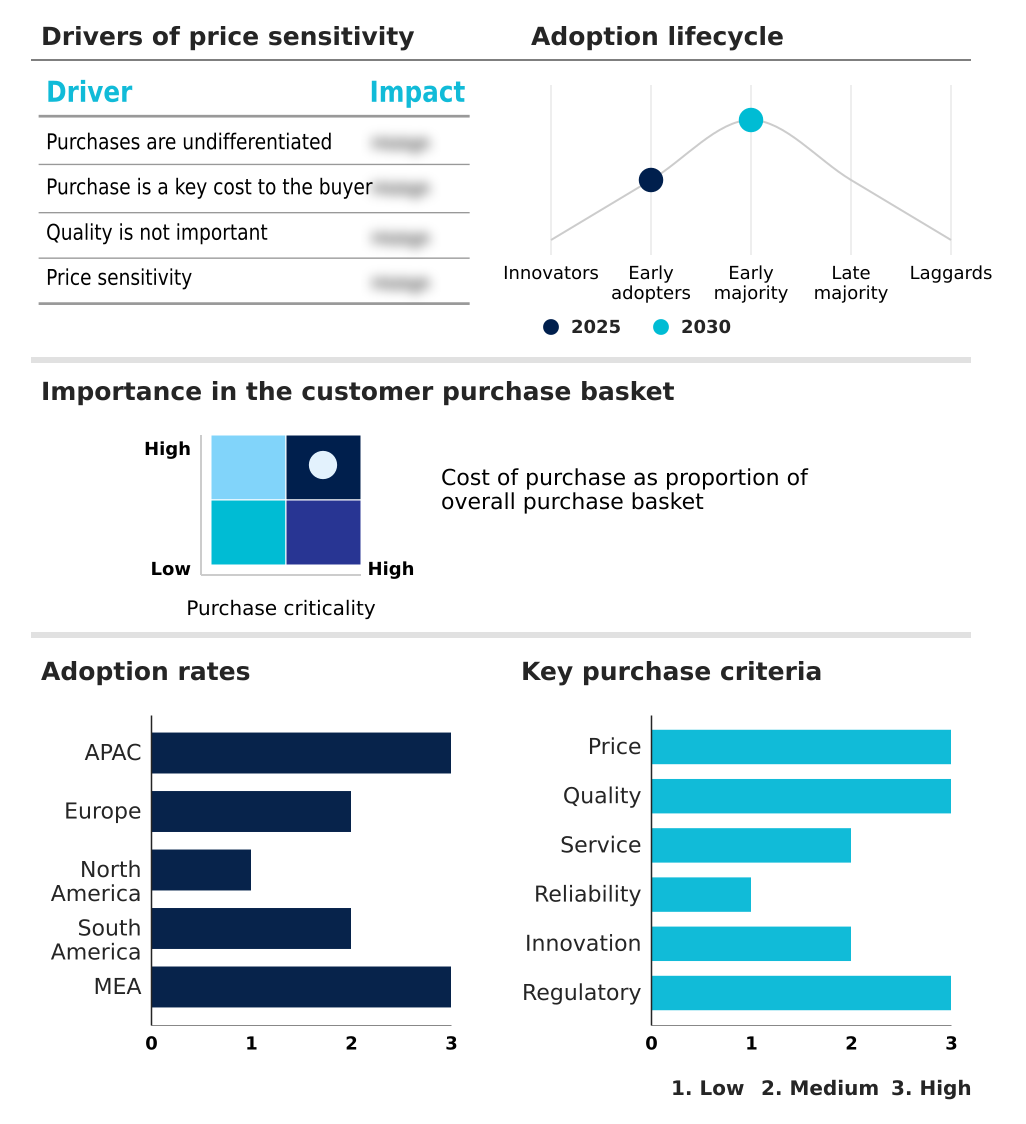
Customer Landscape of Wood Coatings Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, wood coatings market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Akzo Nobel NV - The vendor provides advanced wood coatings including specialized stains, varnishes, and low emission resins that deliver superior decorative wood protection and enhanced scratch resistance finishes for diverse industrial applications.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Akzo Nobel NV
  • Arkema Group
  • Asian Paints Ltd.
  • Axalta Coating Systems Ltd.
  • BASF SE
  • Berger Paints India Ltd.
  • Diamond Vogel
  • Dow Chemical Co.
  • Hempel AS
  • IVM Chemicals Srl
  • National Paints Factories
  • Nippon Paint Holdings Co Ltd.
  • Osmo Holz und Color GmbH
  • PPG Industries Inc.
  • Remmers GmbH
  • Renner Italia S.p.A.
  • Sika AG
  • Sylac S.A.
  • Teknos Group Oy
  • The Sherwin Williams Co.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Wood coatings market

  • In the Commodity Chemicals industry, the rapid shift toward bio-based feedstock processing has accelerated the availability of renewable raw materials, directly impacting Wood Coatings demand by enabling the production of sustainable bio based resins for premium furniture manufacturing.
  • Strict regulatory limits on volatile organic compounds across industrial chemical manufacturing have forced a broad transition toward water-soluble acrylic monomers, significantly driving the adoption of waterborne coating technology within the Wood Coatings sector.
  • The integration of smart manufacturing sensors in bulk chemical production has optimized the synthesis of rheology additives, reducing batch variability by 18% and ensuring highly consistent finish adhesion strength for industrial wood finishing applications.
  • Advancements in closed loop systems for solvent recovery in petrochemical derivatives have lowered the base cost of high solids systems, thereby improving the operational cost efficiency of producing heavy duty exterior decking stains in the Wood Coatings supply chain.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Wood Coatings Market insights. See full methodology.

Market Scope
Page number 310
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 5.4%
Market growth 2026-2030 USD 4053.6 million
Market structure Fragmented
YoY growth 2025-2026(%) 5.1%
Key countries China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, US, Canada, Mexico, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel and Turkey
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Wood Coatings landscape is undergoing a rigorous transformation driven by the intersection of material science and environmental mandates. Boardrooms are increasingly prioritizing the integration of low emission resins and halogen free technology to align product strategies with stringent regulatory frameworks.
  • This strategic pivot toward sustainable forestry practices has enabled forward-thinking manufacturers to reduce hazardous waste disposal costs by 28%, significantly optimizing long-term operational budgets. The adoption of smart manufacturing sensors within curtain coating lines facilitates real-time viscosity adjustments, ensuring consistent wood grain enhancement and superior finish adhesion strength.
  • Furthermore, the accelerated deployment of aliphatic polyurethanes and moisture resistant sealers addresses the durability requirements of heavy foot traffic areas and heritage building restoration projects. By upgrading to closed loop systems, facilities mitigate volatile organic compounds while maintaining high production throughput.
  • The continuous evolution of surface pretreatment chemicals and rheology additives ensures that decorative wood protection remains resilient against severe climatic degradation, anchoring future product viability in advanced technological compliance.

What are the Key Data Covered in this Wood Coatings Market Research and Growth Report?

  • What is the expected growth of the Wood Coatings Market between 2026 and 2030?

    • USD 4.05 billion, at a CAGR of 5.4%

  • What segmentation does the market report cover?

    • The report is segmented by Product (Stains and varnishes, Wood preservatives, Shellacs, and Others), Technology (Solvent-based, Water-based, and Others), Application (Furniture and fixtures, Cabinets, Doors and windows, and Others) and Geography (APAC, Europe, North America, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • APAC, Europe, North America, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Rising demand for wood coatings from developing countries, Stringent regulatory standards on use of certain chemicals in wood coatings

  • Who are the major players in the Wood Coatings Market?

    • Akzo Nobel NV, Arkema Group, Asian Paints Ltd., Axalta Coating Systems Ltd., BASF SE, Berger Paints India Ltd., Diamond Vogel, Dow Chemical Co., Hempel AS, IVM Chemicals Srl, National Paints Factories, Nippon Paint Holdings Co Ltd., Osmo Holz und Color GmbH, PPG Industries Inc., Remmers GmbH, Renner Italia S.p.A., Sika AG, Sylac S.A., Teknos Group Oy and The Sherwin Williams Co.

Market Research Insights

  • The Wood Coatings landscape is rapidly evolving as producers embrace automated application techniques to streamline industrial output. Facilities upgrading to precision spraying systems have improved chemical resistance testing pass rates by 22%, drastically reducing rework delays.
  • Furthermore, the strategic shift toward sustainable forestry practices has increased the adoption of premium architectural finishes, cutting volatile organic emission levels by 30% across modernized production lines. By focusing on green building certifications, manufacturers are efficiently optimizing their supply chains.
  • This alignment with rigorous environmental compliance standards enables companies to achieve a 15% enhancement in overall energy efficiency, ensuring decorative wood protection meets modern sustainability mandates while driving measurable operational cost reductions.

We can help! Our analysts can customize this wood coatings market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Market Segmentation by Technology
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Wood Coatings Market 2020 - 2024

Historic Market Size - Data Table on Global Wood Coatings Market 2020 - 2024 ($ million)

5.2 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ million)

5.3 Technology segment analysis 2020 - 2024

Historic Market Size - Technology Segment 2020 - 2024 ($ million)

5.4 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Wood Coatings Market

6.2 Impact of Geopolitical Conflicts on Global Wood Coatings Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Product

8.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

8.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

8.3 Stains and varnishes - Market size and forecast 2025-2030

Chart on Stains and varnishes - Market size and forecast 2025-2030 ($ million)
Data Table on Stains and varnishes - Market size and forecast 2025-2030 ($ million)
Chart on Stains and varnishes - Year-over-year growth 2025-2030 (%)
Data Table on Stains and varnishes - Year-over-year growth 2025-2030 (%)

8.4 Wood preservatives - Market size and forecast 2025-2030

Chart on Wood preservatives - Market size and forecast 2025-2030 ($ million)
Data Table on Wood preservatives - Market size and forecast 2025-2030 ($ million)
Chart on Wood preservatives - Year-over-year growth 2025-2030 (%)
Data Table on Wood preservatives - Year-over-year growth 2025-2030 (%)

8.5 Shellacs - Market size and forecast 2025-2030

Chart on Shellacs - Market size and forecast 2025-2030 ($ million)
Data Table on Shellacs - Market size and forecast 2025-2030 ($ million)
Chart on Shellacs - Year-over-year growth 2025-2030 (%)
Data Table on Shellacs - Year-over-year growth 2025-2030 (%)

8.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.7 Market opportunity by Product

Market opportunity by Product ($ million)
Data Table on Market opportunity by Product ($ million)

9. Market Segmentation by Technology

9.1 Market segments

Chart on Technology - Market share 2025-2030 (%)
Data Table on Technology - Market share 2025-2030 (%)

9.2 Comparison by Technology

Chart on Comparison by Technology
Data Table on Comparison by Technology

9.3 Solvent-based - Market size and forecast 2025-2030

Chart on Solvent-based - Market size and forecast 2025-2030 ($ million)
Data Table on Solvent-based - Market size and forecast 2025-2030 ($ million)
Chart on Solvent-based - Year-over-year growth 2025-2030 (%)
Data Table on Solvent-based - Year-over-year growth 2025-2030 (%)

9.4 Water-based - Market size and forecast 2025-2030

Chart on Water-based - Market size and forecast 2025-2030 ($ million)
Data Table on Water-based - Market size and forecast 2025-2030 ($ million)
Chart on Water-based - Year-over-year growth 2025-2030 (%)
Data Table on Water-based - Year-over-year growth 2025-2030 (%)

9.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by Technology

Market opportunity by Technology ($ million)
Data Table on Market opportunity by Technology ($ million)

10. Market Segmentation by Application

10.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

10.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

10.3 Furniture and fixtures - Market size and forecast 2025-2030

Chart on Furniture and fixtures - Market size and forecast 2025-2030 ($ million)
Data Table on Furniture and fixtures - Market size and forecast 2025-2030 ($ million)
Chart on Furniture and fixtures - Year-over-year growth 2025-2030 (%)
Data Table on Furniture and fixtures - Year-over-year growth 2025-2030 (%)

10.4 Cabinets - Market size and forecast 2025-2030

Chart on Cabinets - Market size and forecast 2025-2030 ($ million)
Data Table on Cabinets - Market size and forecast 2025-2030 ($ million)
Chart on Cabinets - Year-over-year growth 2025-2030 (%)
Data Table on Cabinets - Year-over-year growth 2025-2030 (%)

10.5 Doors and windows - Market size and forecast 2025-2030

Chart on Doors and windows - Market size and forecast 2025-2030 ($ million)
Data Table on Doors and windows - Market size and forecast 2025-2030 ($ million)
Chart on Doors and windows - Year-over-year growth 2025-2030 (%)
Data Table on Doors and windows - Year-over-year growth 2025-2030 (%)

10.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.3.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.5.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.5.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.5.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Rising demand for wood coatings from developing countries
Advancements in coating technology
Growing demand for high-performance wood coatings

13.2 Market challenges

Stringent regulatory standards on use of certain chemicals in wood coatings
Volatility in raw material prices
Increasing concerns about wood logging practices

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Focus on circular economy and recycling principles
Integration of IoT and smart manufacturing in wood coatings
Rising number of product launches by reputed organizations

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Akzo Nobel NV

Akzo Nobel NV - Overview
Akzo Nobel NV - Business segments
Akzo Nobel NV - Key offerings
Akzo Nobel NV - Segment focus
SWOT

15.5 Arkema Group

Arkema Group - Overview
Arkema Group - Business segments
Arkema Group - Key news
Arkema Group - Key offerings
Arkema Group - Segment focus
SWOT

15.6 Asian Paints Ltd.

Asian Paints Ltd. - Overview
Asian Paints Ltd. - Business segments
Asian Paints Ltd. - Key offerings
Asian Paints Ltd. - Segment focus
SWOT

15.7 Axalta Coating Systems Ltd.

Axalta Coating Systems Ltd. - Overview
Axalta Coating Systems Ltd. - Business segments
Axalta Coating Systems Ltd. - Key offerings
Axalta Coating Systems Ltd. - Segment focus
SWOT

15.8 BASF SE

BASF SE - Overview
BASF SE - Business segments
BASF SE - Key news
BASF SE - Key offerings
BASF SE - Segment focus
SWOT

15.9 Berger Paints India Ltd.

Berger Paints India Ltd. - Overview
Berger Paints India Ltd. - Product / Service
Berger Paints India Ltd. - Key offerings
SWOT

15.10 Dow Chemical Co.

Dow Chemical Co. - Overview
Dow Chemical Co. - Business segments
Dow Chemical Co. - Key offerings
Dow Chemical Co. - Segment focus
SWOT

15.11 Hempel AS

Hempel AS - Overview
Hempel AS - Product / Service
Hempel AS - Key offerings
SWOT

15.12 National Paints Factories

National Paints Factories - Overview
National Paints Factories - Product / Service
National Paints Factories - Key offerings
SWOT

15.13 Nippon Paint Holdings Co Ltd.

Nippon Paint Holdings Co Ltd. - Overview
Nippon Paint Holdings Co Ltd. - Business segments
Nippon Paint Holdings Co Ltd. - Key offerings
Nippon Paint Holdings Co Ltd. - Segment focus
SWOT

15.14 PPG Industries Inc.

PPG Industries Inc. - Overview
PPG Industries Inc. - Business segments
PPG Industries Inc. - Key offerings
PPG Industries Inc. - Segment focus
SWOT

15.15 Remmers GmbH

Remmers GmbH - Overview
Remmers GmbH - Product / Service
Remmers GmbH - Key offerings
SWOT

15.16 Sika AG

Sika AG - Overview
Sika AG - Business segments
Sika AG - Key news
Sika AG - Key offerings
Sika AG - Segment focus
SWOT

15.17 Teknos Group Oy

Teknos Group Oy - Overview
Teknos Group Oy - Product / Service
Teknos Group Oy - Key offerings
SWOT

15.18 The Sherwin Williams Co.

The Sherwin Williams Co. - Overview
The Sherwin Williams Co. - Business segments
The Sherwin Williams Co. - Key offerings
The Sherwin Williams Co. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Wood Coatings market growth will increase by USD 4053.6 million during 2026-2030.

The Wood Coatings market is expected to grow at a CAGR of 5.4% during 2026-2030.

Wood Coatings market is segmented by Product (Stains and varnishes, Wood preservatives, Shellacs, Others) Technology (Solvent-based, Water-based, Others) Application (Furniture and fixtures, Cabinets, Doors and windows, Others)

Akzo Nobel NV, Arkema Group, Asian Paints Ltd., Axalta Coating Systems Ltd., BASF SE, Berger Paints India Ltd., Diamond Vogel, Dow Chemical Co., Hempel AS, IVM Chemicals Srl, National Paints Factories, Nippon Paint Holdings Co Ltd., Osmo Holz und Color GmbH, PPG Industries Inc., Remmers GmbH, Renner Italia S.p.A., Sika AG, Sylac S.A., Teknos Group Oy, The Sherwin Williams Co. are a few of the key vendors in the Wood Coatings market.

APAC will register the highest growth rate of 46.3% among the other regions. Therefore, the Wood Coatings market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, US, Canada, Mexico, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel, Turkey

  • Rising demand for wood coatings from developing countries is the driving factor this market.

The Wood Coatings market vendors should focus on grabbing business opportunities from the Product segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
