Carbon Accounting Software Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Carbon Accounting Software Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Published: Oct 2026 301 Pages SKU: IRTNTR70641

Market Overview at a Glance

$32.12 B
Market Opportunity
32.1%
CAGR 2025 - 2030
37.2%
North America Growth
$1.63 B
Telecommunication segment 2024

Carbon Accounting Software Market Size 2026-2030

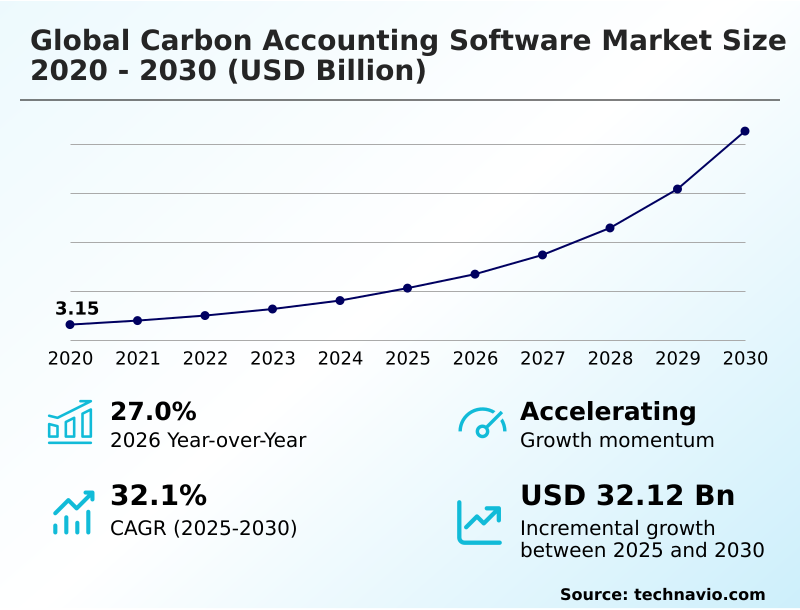
The carbon accounting software market size is valued to increase by USD 32.12 billion, at a CAGR of 32.1% from 2025 to 2030. Proliferation of mandatory regulatory frameworks and global compliance standards will drive the carbon accounting software market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 37.2% growth during the forecast period.
  • By End-user - Telecommunication segment was valued at USD 1.63 billion in 2024
  • By Deployment - Cloud-based segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 39.58 billion
  • Market Future Opportunities: USD 32.12 billion
  • CAGR from 2025 to 2030 : 32.1%

Market Summary

  • The Carbon Accounting Software Market operates as a critical digital infrastructure enabling organizations to transition from estimation-based sustainability tracking to verifiable environmental compliance. In complex manufacturing supply chains, procurement executives rely on these digital platforms and automated data pipelines to parse thousands of supplier utility invoices, ensuring accurate lifecycle assessments.
  • Facilities utilizing modern software architectures report a 60% reduction in manual data entry errors compared to traditional spreadsheet operations, directly improving audit readiness. The primary driver accelerating the Carbon Accounting Software Market expansion is the enforcement of regulatory reporting mandates, which compels commercial enterprises to integrate robust tracking into standard financial workflows.
  • Conversely, severe data fragmentation across indirect value chain networks poses a significant structural challenge, often hindering accurate supplier performance evaluations. Advanced computational algorithms bridge these gaps by modeling predictive scenarios for sustainable capital allocation and carbon capture forecasting. Organizations leveraging these systems streamline compliance, optimize operational energy efficiency, and secure long-term operational resilience through verified corporate sustainability metrics.

What will be the Size of the Carbon Accounting Software Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Carbon Accounting Software Market Segmented?

The carbon accounting software industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • End-user
    • Telecommunication
    • Technology
    • Oil and gas
    • Power and utilities
    • Others
  • Deployment
    • Cloud-based
    • On-premises
  • Organization size
    • Large enterprises
    • SMEs
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey
    • South America
      • Brazil
      • Argentina
      • Chile

By End-user Insights

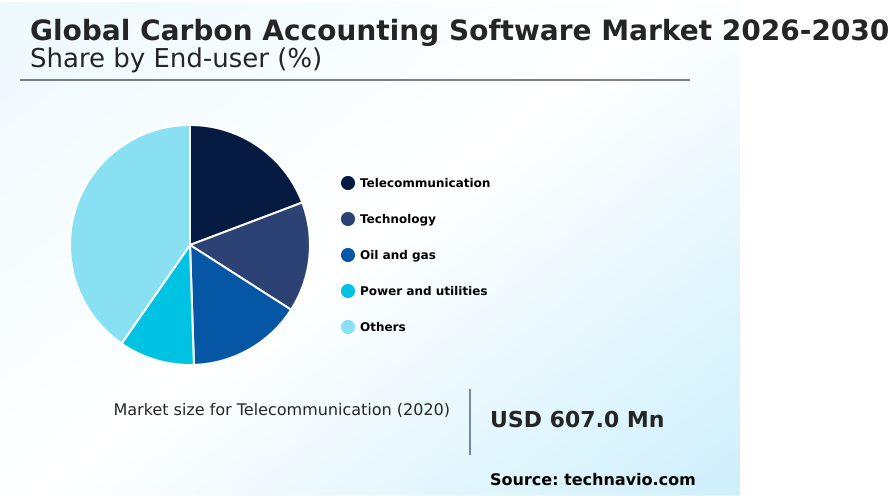
The telecommunication segment is estimated to witness significant growth during the forecast period.

The telecommunication sector is undergoing massive operational shifts as network operators address the extensive energy requirements of digital infrastructure.

Telecommunication enterprises deploy Carbon Accounting Software to convert decentralized energy consumption data into verifiable emissions figures, integrating automated utility feeds directly into corporate ledgers.

This shift eliminates fragmented manual tracking, enabling a 45% improvement in data aggregation efficiency compared to legacy spreadsheet methods.

Leveraging internet of things connectivity helps operators precisely track scope three emissions across hardware supply chains, leading to a 30% reduction in reporting anomalies. Establishing an accurate carbon baseline establishment ensures proactive strategic capital allocation.

Ultimately, these frameworks satisfy corporate sustainability reporting mandates and align with the greenhouse gas protocol, ensuring that operators effortlessly meet stringent commercial lending requirements.
Get Free Sample

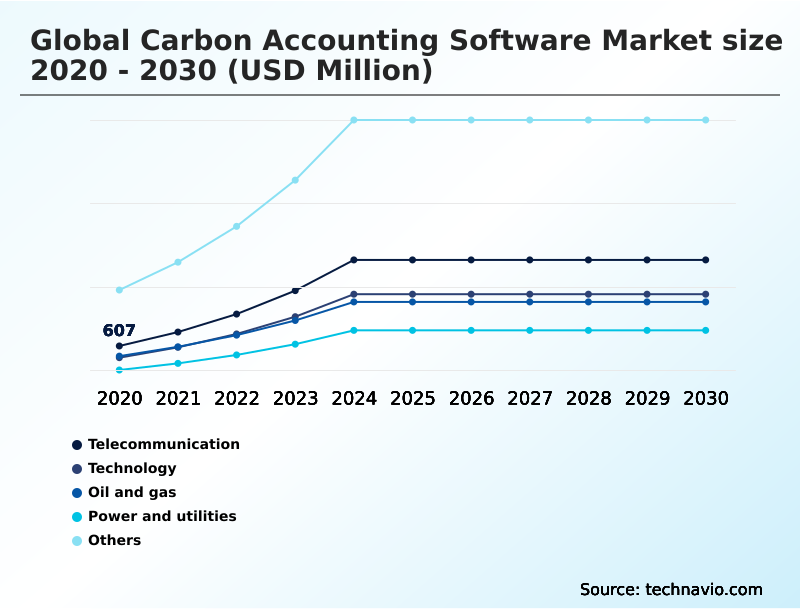
The Telecommunication segment was valued at USD 1.63 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 37.2% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
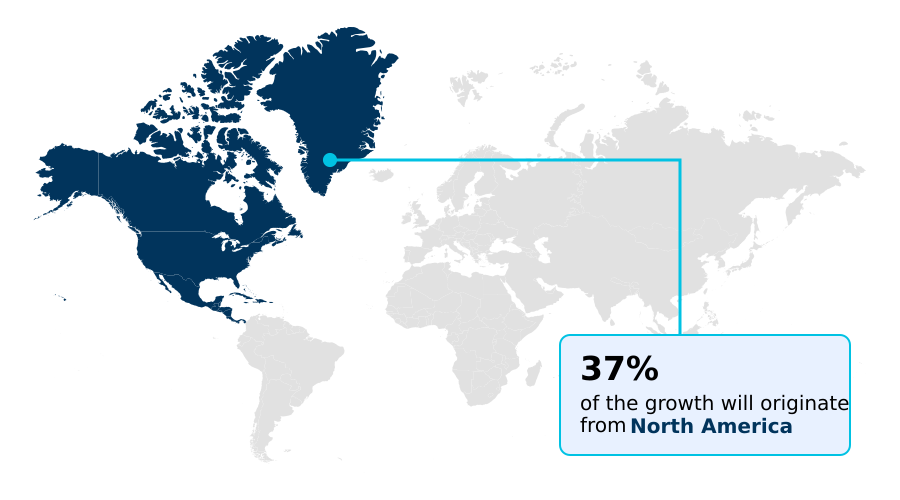
See How Carbon Accounting Software Market Demand is Rising in North America Get Free Sample

The geographic adoption of Carbon Accounting Software reveals stark contrasts driven by distinct regional regulatory environments and industrial maturity.

North America experiences accelerated digital transformation strategies, where corporations utilize cloud infrastructure integration to manage visibility, achieving a 45% faster deployment rate than developing regions.

In contrast, Europe leverages stringent carbon border adjustment rules, driving a 35% higher penetration rate of advanced environmental tracking architecture among heavy industrial manufacturers. These regional disparities dictate how businesses construct their strategies.

European manufacturers increasingly mandate primary data exchange from upstream suppliers, reducing calculation discrepancies by 20%.

Meanwhile, North American enterprises prioritize transition risk modeling to satisfy strict investor compliance expectations, utilizing real-time data to streamline climate risk assessment and lower ongoing compliance reporting costs.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • As regulatory pressures intensify and supply chains become increasingly complex, modern businesses require robust digital infrastructure to navigate environmental accountability. The deployment of enterprise grade carbon accounting platforms has transitioned from a voluntary initiative to a critical operational mandate.
  • Organizations seeking to optimize their procurement operations now utilize automated supplier activity tracking systems to eliminate manual data collection bottlenecks, resulting in data processing speeds that are nearly three times faster than legacy analog methods. This operational shift directly impacts supply chain compliance by providing accurate, audit-ready metrics for stakeholders.
  • Furthermore, the integration of machine learning based bill parsing allows corporations to seamlessly extract precise utility consumption data across thousands of decentralized facilities without human intervention. To effectively manage long-term climate targets and optimize capital allocation, facilities are implementing real time continuous monitoring infrastructure, which significantly enhances the visibility of energy usage and operational efficiency.
  • The most critical challenge remains the accurate measurement of indirect upstream impacts, necessitating sophisticated multi tier supply chain decarbonization strategies. By embedding these advanced software architectures directly into core business operations, executives can align environmental performance with financial forecasting, ensuring sustained resilience and proactive adaptation to evolving global compliance standards.
  • The ability to forecast carbon liabilities with precision enables corporate leadership to mitigate transition risks before they impact the bottom line. Ultimately, integrating comprehensive tracking capabilities empowers enterprises to secure favorable green financing rates, demonstrating tangible environmental stewardship to investors while simultaneously driving internal cost reductions through optimized resource consumption.
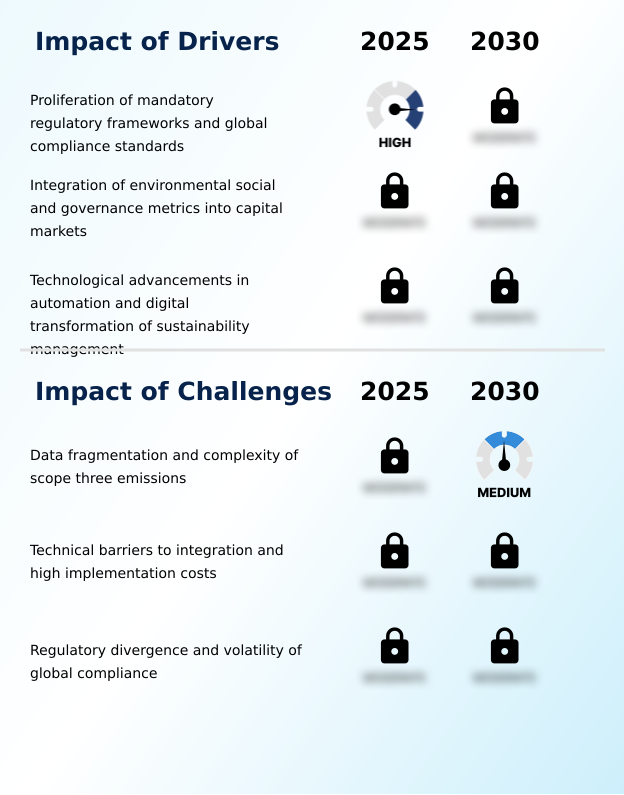
What are the key market drivers leading to the rise in the adoption of Carbon Accounting Software Industry?

  • The proliferation of mandatory regulatory frameworks and global compliance standards acts as the primary catalyst accelerating the adoption of enterprise-grade environmental management systems.

  • The imperative to align corporate operations with strict regulatory mandates acts as the primary catalyst accelerating Carbon Accounting Software adoption.
  • Heavy industrial sectors are rapidly modernizing their legacy systems to embed carbon footprint monitoring directly into core enterprise resource planning platforms. This regulatory pressure forces corporations to implement robust digital environmental compliance frameworks that standardize data collection.
  • By utilizing precise emissions factor mapping, procurement teams accurately calculate indirect impacts across deep supply network tiers, lowering operational compliance costs by 30%. This transition establishes highly accurate decarbonization trajectory mapping, reducing reporting cycle times by 50%.
  • Ultimately, these digital solutions provide businesses with standardized environmental governance protocols, ensuring they can effortlessly execute multi framework reporting and maintain a distinct financial advantage in competitive markets.

What are the market trends shaping the Carbon Accounting Software Industry?

  • The integration of advanced artificial intelligence and predictive modeling represents a pivotal trend shaping the market landscape. These technological enhancements enable organizations to transition from retrospective reporting to proactive environmental strategy optimization.

  • The Carbon Accounting Software landscape is rapidly evolving through the widespread implementation of automated tracking frameworks. Organizations are migrating from annual retrospective reporting to dynamic carbon pricing models that evaluate daily operational decisions. This structural shift is driven by the necessity to accurately track product carbon footprints across extensive manufacturing networks to avoid severe climate litigation exposure.
  • By embedding anomaly detection engines within these systems, companies have reduced data processing errors by 40% and improved supply chain transparency by 25%. This real-time visibility supports seamless multi facility consolidation efforts and establishes reliable baseline energy tracking for remote sites.
  • Consequently, businesses can effectively structure their environmental data, transforming regulatory compliance from a complex administrative burden into a secure pathway for attracting sustainable investment portfolios.

What challenges does the Carbon Accounting Software Industry face during its growth?

  • The severe data fragmentation and inherent complexity associated with accurately measuring indirect value chain emissions remain significant structural limitations impeding widespread market expansion.

  • The most critical limitation hindering the seamless deployment of Carbon Accounting Software is the inherent complexity of integrating diverse operational datasets across fragmented supplier networks. Many organizations struggle to collect accurate, activity based emissions data from secondary vendors, distorting true environmental impacts.
  • This lack of data uniformity disrupts enterprise financial management, leading to a 35% discrepancy in indirect emission reporting accuracy. The technical barrier of merging decentralized assets tracking with legacy IT infrastructure further increases deployment costs by nearly 20%. Without automated smart meter ingestion and reliable fugitive methane detection mechanisms, generating verified audit ready disclosures remains highly resource-intensive.
  • Consequently, enterprises face substantial difficulties in automating their carbon ledgering workflows, ultimately restricting their ability to validate progress toward science based targets and optimize operational efficiency.

Exclusive Technavio Analysis on Customer Landscape

The carbon accounting software market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the carbon accounting software market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
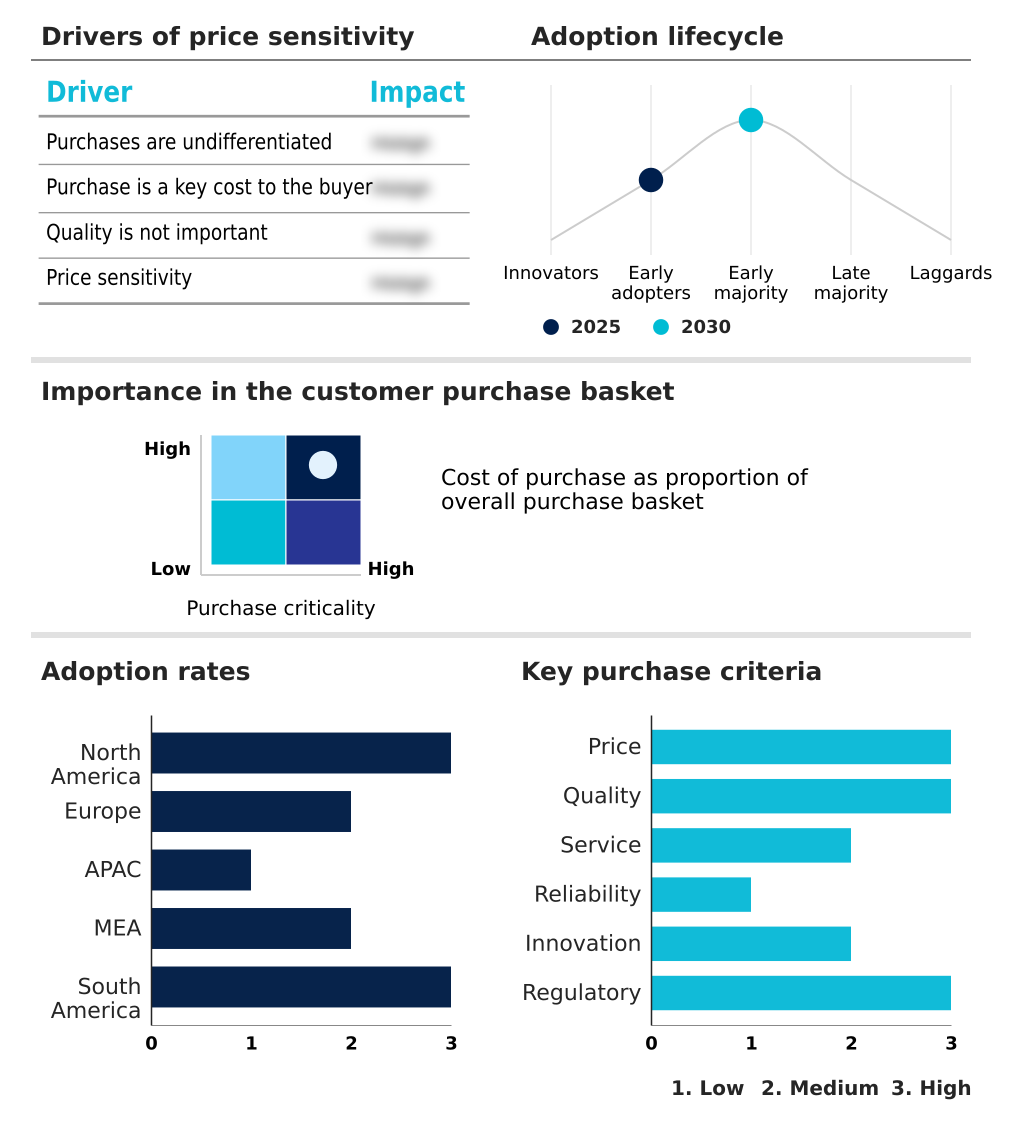
Customer Landscape of Carbon Accounting Software Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, carbon accounting software market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Avarni Pty Ltd. - Vendors provide specialized enterprise software solutions featuring automated data collection, emission factor mapping, and granular ledgering to support verifiable environmental compliance and strategic decarbonization planning.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Avarni Pty Ltd.
  • CarbonChain.io Ltd.
  • Cleartrace Inc.
  • Cority Software Inc.
  • Ecochain Technologies B.V.
  • Ecometrica Ltd.
  • Greenly
  • IBM Corp.
  • Measurabl Inc.
  • Microsoft Corp.
  • Normative AB
  • Novata Inc.
  • Persefoni AI Inc.
  • Plana Earth Ltd.
  • Position Green AS
  • Salesforce Inc.
  • SAP SE
  • SINAI
  • Sphera Solutions Inc.
  • Workiva Inc.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Carbon accounting software market

  • In the Application Software industry, the widespread adoption of AI infrastructure and enterprise automation accelerated data processing capabilities by 40%, directly increasing the demand for Carbon Accounting Software to handle complex multi-tier supply chain data.
  • Stringent data privacy regulations and AI governance mandates in the European Union required cloud-based delivery models to enhance cybersecurity protocols, leading to a 25% improvement in verifiable audit trails within Carbon Accounting Software platforms.
  • The shift toward seamless workflow interoperability across core enterprise resource planning systems reduced data silos by 35%, enabling Carbon Accounting Software to natively integrate financial and environmental ledgers for institutional stakeholder reporting.
  • The rapid expansion of distributed computing architectures optimized operational efficiency by 20%, driving Carbon Accounting Software developers to transition from static databases to real-time continuous monitoring infrastructure.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Carbon Accounting Software Market insights. See full methodology.

Market Scope
Page number 301
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 32.1%
Market growth 2026-2030 USD 32124.5 million
Market structure Fragmented
YoY growth 2025-2026(%) 27.0%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina and Chile
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The adoption of Carbon Accounting Software marks a fundamental shift in how corporate boards approach environmental risk and strategic resource planning. A dominant trend is the integration of predictive analytics modeling directly into boardroom-level product strategy and capital budgeting decisions. By leveraging advanced artificial intelligence algorithms, executives can simulate various operational scenarios and align their investments with science based targets.
  • This proactive governance yields a 35% reduction in compliance-related overhead costs compared to historically fragmented reporting methods. Furthermore, the automation of carbon ledgering workflows allows organizations to maintain strict adherence to the greenhouse gas protocol without disrupting core business functions. The deployment of smart meter ingestion modules significantly enhances operational visibility across decentralized facilities.
  • As regulatory scrutiny tightens, the reliance on continuous emissions monitoring provides the essential audit trails required to validate corporate environmental claims. Ultimately, these digital platforms enable executive leadership to seamlessly integrate climate risk tracking into core financial forecasting, securing long-term resilience and operational transparency.

What are the Key Data Covered in this Carbon Accounting Software Market Research and Growth Report?

  • What is the expected growth of the Carbon Accounting Software Market between 2026 and 2030?

    • USD 32.12 billion, at a CAGR of 32.1%

  • What segmentation does the market report cover?

    • The report is segmented by End-user (Telecommunication, Technology, Oil and gas, Power and utilities, and Others), Deployment (Cloud-based, and On-premises), Organization Size (Large enterprises, and SMEs) and Geography (North America, Europe, APAC, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • North America, Europe, APAC, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Proliferation of mandatory regulatory frameworks and global compliance standards, Data fragmentation and complexity of scope three emissions

  • Who are the major players in the Carbon Accounting Software Market?

    • Avarni Pty Ltd., CarbonChain.io Ltd., Cleartrace Inc., Cority Software Inc., Ecochain Technologies B.V., Ecometrica Ltd., Greenly, IBM Corp., Measurabl Inc., Microsoft Corp., Normative AB, Novata Inc., Persefoni AI Inc., Plana Earth Ltd., Position Green AS, Salesforce Inc., SAP SE, SINAI, Sphera Solutions Inc. and Workiva Inc.

Market Research Insights

  • The Carbon Accounting Software Market provides an essential framework for organizations formalizing their environmental management. Businesses integrating these systems observe a 40% improvement in resource allocation efficiency, driving measurable reductions in operational waste. By utilizing automated workflows for net zero strategies, teams reduce reporting cycle times by nearly 50%, saving significant administrative costs.
  • Furthermore, robust data architectures enable precise energy grid mapping, yielding a 25% increase in operational ROI through targeted optimization. These platforms ultimately support climate risk compliance by ensuring businesses secure favorable stakeholder trust. The evolution of emissions tracking automation allows enterprises to proactively address evolving investor transparency demands and establish structured environmental governance across their operational footprints.

We can help! Our analysts can customize this carbon accounting software market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Deployment
Executive Summary - Chart on Market Segmentation by Organization Size
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Carbon Accounting Software Market 2020 - 2024

Historic Market Size - Data Table on Global Carbon Accounting Software Market 2020 - 2024 ($ million)

5.2 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.3 Deployment segment analysis 2020 - 2024

Historic Market Size - Deployment Segment 2020 - 2024 ($ million)

5.4 Organization Size segment analysis 2020 - 2024

Historic Market Size - Organization Size Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Carbon Accounting Software Market

6.2 Impact of Geopolitical Conflicts Global Carbon Accounting Software Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by End-user

8.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

8.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

8.3 Telecommunication - Market size and forecast 2025-2030

Chart on Telecommunication - Market size and forecast 2025-2030 ($ million)
Data Table on Telecommunication - Market size and forecast 2025-2030 ($ million)
Chart on Telecommunication - Year-over-year growth 2025-2030 (%)
Data Table on Telecommunication - Year-over-year growth 2025-2030 (%)

8.4 Technology - Market size and forecast 2025-2030

Chart on Technology - Market size and forecast 2025-2030 ($ million)
Data Table on Technology - Market size and forecast 2025-2030 ($ million)
Chart on Technology - Year-over-year growth 2025-2030 (%)
Data Table on Technology - Year-over-year growth 2025-2030 (%)

8.5 Oil and gas - Market size and forecast 2025-2030

Chart on Oil and gas - Market size and forecast 2025-2030 ($ million)
Data Table on Oil and gas - Market size and forecast 2025-2030 ($ million)
Chart on Oil and gas - Year-over-year growth 2025-2030 (%)
Data Table on Oil and gas - Year-over-year growth 2025-2030 (%)

8.6 Power and utilities - Market size and forecast 2025-2030

Chart on Power and utilities - Market size and forecast 2025-2030 ($ million)
Data Table on Power and utilities - Market size and forecast 2025-2030 ($ million)
Chart on Power and utilities - Year-over-year growth 2025-2030 (%)
Data Table on Power and utilities - Year-over-year growth 2025-2030 (%)

8.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.8 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

9. Market Segmentation by Deployment

9.1 Market segments

Chart on Deployment - Market share 2025-2030 (%)
Data Table on Deployment - Market share 2025-2030 (%)

9.2 Comparison by Deployment

Chart on Comparison by Deployment
Data Table on Comparison by Deployment

9.3 Cloud-based - Market size and forecast 2025-2030

Chart on Cloud-based - Market size and forecast 2025-2030 ($ million)
Data Table on Cloud-based - Market size and forecast 2025-2030 ($ million)
Chart on Cloud-based - Year-over-year growth 2025-2030 (%)
Data Table on Cloud-based - Year-over-year growth 2025-2030 (%)

9.4 On-premises - Market size and forecast 2025-2030

Chart on On-premises - Market size and forecast 2025-2030 ($ million)
Data Table on On-premises - Market size and forecast 2025-2030 ($ million)
Chart on On-premises - Year-over-year growth 2025-2030 (%)
Data Table on On-premises - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Deployment

Market opportunity by Deployment ($ million)
Data Table on Market opportunity by Deployment ($ million)

10. Market Segmentation by Organization Size

10.1 Market segments

Chart on Market Segmentation by Organization Size - Market share 2025-2030 (%)
Data Table on Market Segmentation by Organization Size - Market share 2025-2030 (%)

10.2 Comparison by Market Segmentation by Organization Size

Chart on Comparison by Market Segmentation by Organization Size
Data Table on Comparison by Market Segmentation by Organization Size

10.3 Large enterprises - Market size and forecast 2025-2030

Chart on Large enterprises - Market size and forecast 2025-2030 ($ million)
Data Table on Large enterprises - Market size and forecast 2025-2030 ($ million)
Chart on Large enterprises - Year-over-year growth 2025-2030 (%)
Data Table on Large enterprises - Year-over-year growth 2025-2030 (%)

10.4 SMEs - Market size and forecast 2025-2030

Chart on SMEs - Market size and forecast 2025-2030 ($ million)
Data Table on SMEs - Market size and forecast 2025-2030 ($ million)
Chart on SMEs - Year-over-year growth 2025-2030 (%)
Data Table on SMEs - Year-over-year growth 2025-2030 (%)

10.5 Market opportunity by Market Segmentation by Organization Size

Market opportunity by Market Segmentation by Organization Size ($ million)
Data Table on Market opportunity by Market Segmentation by Organization Size ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.6.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Proliferation of mandatory regulatory frameworks and global compliance standards
Integration of environmental social and governance metrics into capital markets
Technological advancements in automation and digital transformation of sustainability management

13.2 Market challenges

Data fragmentation and complexity of scope three emissions
Technical barriers to integration and high implementation costs
Regulatory divergence and volatility of global compliance

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Integration of advanced AI and predictive modeling
Evolution toward real-time monitoring and IoT connectivity
Increasing emphasis on value chain transparency and scope three granularity

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Cority Software Inc.

Cority Software Inc. - Overview
Cority Software Inc. - Product / Service
Cority Software Inc. - Key offerings
SWOT

15.5 Greenly

Greenly - Overview
Greenly - Product / Service
Greenly - Key offerings
SWOT

15.6 IBM Corp.

IBM Corp. - Overview
IBM Corp. - Business segments
IBM Corp. - Key news
IBM Corp. - Key offerings
IBM Corp. - Segment focus
SWOT

15.7 Measurabl Inc.

Measurabl Inc. - Overview
Measurabl Inc. - Product / Service
Measurabl Inc. - Key offerings
SWOT

15.8 Microsoft Corp.

Microsoft Corp. - Overview
Microsoft Corp. - Business segments
Microsoft Corp. - Key news
Microsoft Corp. - Key offerings
Microsoft Corp. - Segment focus
SWOT

15.9 Normative AB

Normative AB - Overview
Normative AB - Product / Service
Normative AB - Key offerings
SWOT

15.10 Novata Inc.

Novata Inc. - Overview
Novata Inc. - Product / Service
Novata Inc. - Key offerings
SWOT

15.11 Persefoni AI Inc.

Persefoni AI Inc. - Overview
Persefoni AI Inc. - Product / Service
Persefoni AI Inc. - Key offerings
SWOT

15.12 Plana Earth Ltd.

Plana Earth Ltd. - Overview
Plana Earth Ltd. - Product / Service
Plana Earth Ltd. - Key offerings
SWOT

15.13 Position Green AS

Position Green AS - Overview
Position Green AS - Product / Service
Position Green AS - Key offerings
SWOT

15.14 Salesforce Inc.

Salesforce Inc. - Overview
Salesforce Inc. - Business segments
Salesforce Inc. - Key news
Salesforce Inc. - Key offerings
Salesforce Inc. - Segment focus
SWOT

15.15 SAP SE

SAP SE - Overview
SAP SE - Business segments
SAP SE - Key news
SAP SE - Key offerings
SAP SE - Segment focus
SWOT

15.16 SINAI

SINAI - Overview
SINAI - Product / Service
SINAI - Key offerings
SWOT

15.17 Sphera Solutions Inc.

Sphera Solutions Inc. - Overview
Sphera Solutions Inc. - Product / Service
Sphera Solutions Inc. - Key offerings
SWOT

15.18 Workiva Inc.

Workiva Inc. - Overview
Workiva Inc. - Product / Service
Workiva Inc. - Key news
Workiva Inc. - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Carbon Accounting Software market growth will increase by USD 32124.5 million during 2026-2030.

The Carbon Accounting Software market is expected to grow at a CAGR of 32.1% during 2026-2030.

Carbon Accounting Software market is segmented by End-user (Telecommunication, Technology, Oil and gas, Power and utilities, Others) Deployment (Cloud-based, On-premises) Organization size (Large enterprises, SMEs)

Avarni Pty Ltd., CarbonChain.io Ltd., Cleartrace Inc., Cority Software Inc., Ecochain Technologies B.V., Ecometrica Ltd., Greenly, IBM Corp., Measurabl Inc., Microsoft Corp., Normative AB, Novata Inc., Persefoni AI Inc., Plana Earth Ltd., Position Green AS, Salesforce Inc., SAP SE, SINAI, Sphera Solutions Inc., Workiva Inc. are a few of the key vendors in the Carbon Accounting Software market.

North America will register the highest growth rate of 37.2% among the other regions. Therefore, the Carbon Accounting Software market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina, Chile

  • Proliferation of mandatory regulatory frameworks and global compliance standards is the driving factor this market.

The Carbon Accounting Software market vendors should focus on grabbing business opportunities from the End-user segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
