


Europe Corrugated Box Market Size 2026-2030
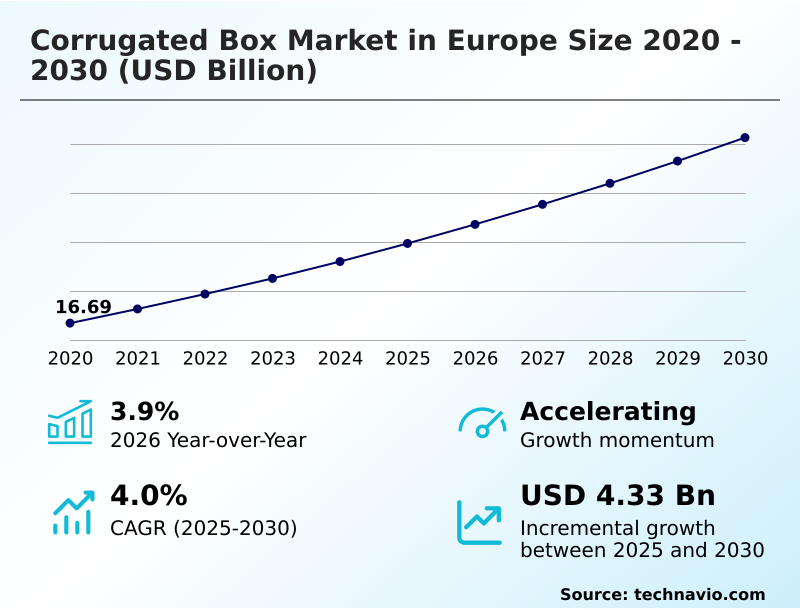
The europe corrugated box market size is valued to increase by USD 4.33 billion, at a CAGR of 4% from 2025 to 2030. Exponential expansion of e-commerce fulfillment networks will drive the europe corrugated box market.
Major Market Trends & Insights
- By End-user - Food and beverages segment was valued at USD 8.57 billion in 2024
- By Material - Recycled corrugates segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 7.59 billion
- Market Future Opportunities: USD 4.33 billion
- CAGR from 2025 to 2030 : 4%
Market Summary
- The Corrugated Box Market in Europe demonstrates robust momentum driven by an intensifying requirement for sustainable, circular packaging solutions across modernized supply chains. A critical catalyst propelling this expansion is the exponential growth of digital commerce, which necessitates highly durable and custom-sized transit protection.
- To minimize costly freight penalties, online retailers are increasingly integrating automated box-making machinery into their logistics hubs, allowing for precise material utilization. This operational shift has led to a 20% reduction in void-fill material consumption compared to standardized packaging methods, significantly optimizing freight expenditures.
- Simultaneously, the market faces formidable constraints due to extreme volatility in recovered fiber and energy input costs, which compress converter margins and complicate long-term procurement strategies. Despite these pricing pressures, manufacturers continue to adopt high-definition digital printing to transform traditional transit cartons into premium marketing vehicles.
- By utilizing advanced secondary packaging designs, enterprises can seamlessly align physical deliveries with dynamic branding initiatives, ensuring that resilient fiber-based formats remain indispensable for safe and efficient regional distribution.
What will be the Size of the Europe Corrugated Box Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Europe Corrugated Box Market Segmented?
The europe corrugated box industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- End-user
- Food and beverages
- Electronic goods
- Personal and household care goods
- Others
- Material
- Recycled corrugates
- Virgin corrugates
- Grade type
- Lightweight grade
- Medium‑weight grade
- High‑burst grade
- Geography
- Europe
- Germany
- UK
- France
- Italy
- Europe
By End-user Insights
The food and beverages segment is estimated to witness significant growth during the forecast period.
The food and beverages segment dictates stringent requirements to ensure the absolute preservation of perishable consumables during long-distance transit. By adopting bio-based circular alternatives, manufacturers achieve a 15% improvement in supply chain efficiency compared to legacy methods.
Modern temperature-controlled transit networks rely heavily on these advanced solutions to prevent spoilage. The integration of moisture-resistant barriers onto multi-wall corrugated boards has reduced transit damage by 22%.
Furthermore, organized retail entities strongly prefer shelf-ready packaging formats, which streamline shelf replenishment without manual unpacking. Aligning with rigorous circular economy models, operators continuously deploy biodegradable packaging materials to satisfy strict hygienic mandates, ensuring robust and compliant high-volume grocery distribution.
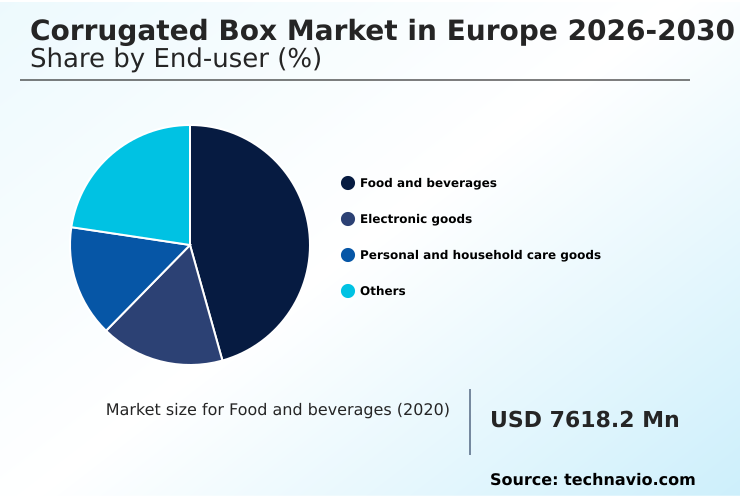
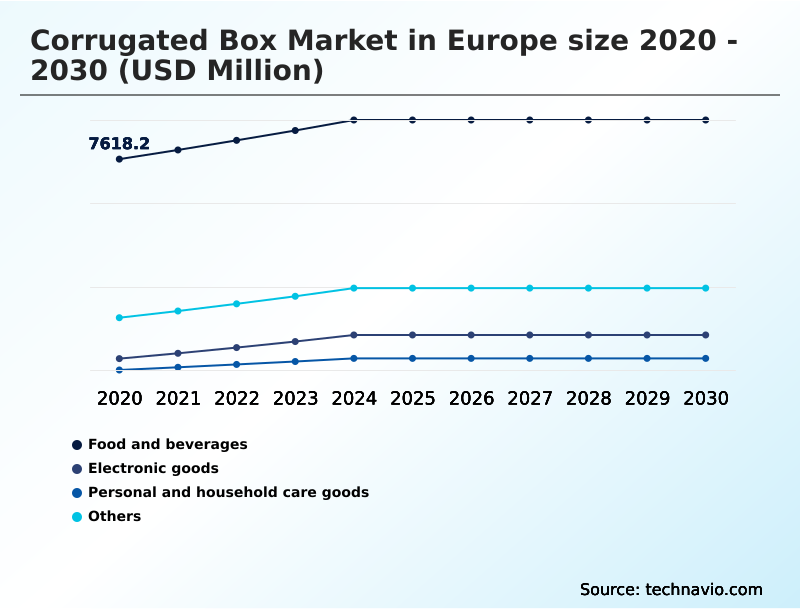
The Food and beverages segment was valued at USD 8.57 billion in 2024 and showed a gradual increase during the forecast period.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- As regulatory frameworks and ecological mandates increasingly influence packaging procurement, industrial converters are systematically upgrading their structural engineering and material science capabilities. A prominent focus involves the integration of high performance micro flute optimization, which allows packaging engineers to substantially reduce total board thickness while preserving essential compression profiles.
- This structural refinement yields a 15% increase in warehouse storage density compared to legacy fluting profiles, directly enhancing inventory management and space utilization across massive distribution centers. To address the vulnerability of paperboard in humid transit environments, manufacturers are actively deploying advanced moisture resistant barrier coating formulation techniques.
- By replacing traditional petroleum-derived waxes with sustainable bio based functional barriers, these next-generation cartons maintain absolute structural integrity during temperature-controlled shipping while remaining fully compatible with standard repulping infrastructure. Simultaneously, the rapid expansion of digital commerce necessitates highly responsive fulfillment strategies.
- The adoption of automated box on demand conversion empowers retail operators to instantly manufacture perfectly sized shipping containers, significantly mitigating dimensional weight penalties and eliminating excess void-fill. To further minimize environmental impact, stakeholders are developing a customized reverse logistics supply chain to efficiently recover and recirculate used fiberboard.
- This holistic approach to lifecycle management ensures that innovative, right-sized packaging continues to optimize modern freight networks and support broader corporate decarbonization targets without compromising critical product protection.
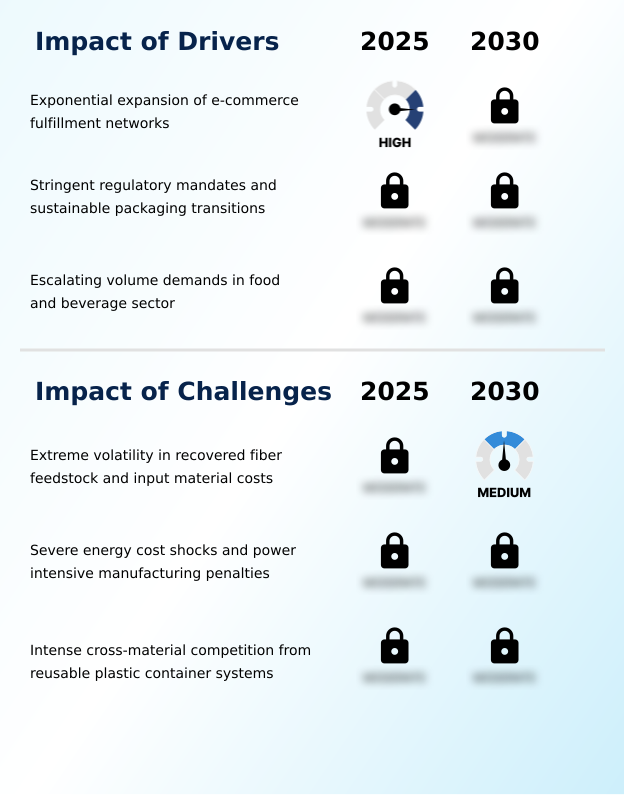
What are the key market drivers leading to the rise in the adoption of Europe Corrugated Box Industry?
- The exponential expansion of digital fulfillment networks serves as a primary catalyst, structurally elevating the demand for robust, custom-sized protective secondary packaging across regional logistics infrastructures.
- The explosive proliferation of direct-to-consumer digital retail channels operates as a primary catalyst, fundamentally restructuring secondary packaging. As e-commerce fulfillment networks pivot to single-unit parcel delivery, the logistical demand for custom-sized, impact-resistant protection has intensified across the regional logistics infrastructure.
- To combat escalating freight costs, operators are aggressively deploying automated box-on-demand machinery, resulting in a 25% reduction in dimensional weight surcharges and a 15% decrease in void-fill consumption through precise material lightweighting.
- Concurrently, stringent extended producer responsibility frameworks compel fast-moving consumer goods brands to eliminate single-use plastics, heavily driving the procurement of post-consumer recovered fibers.
- By aligning operational capabilities with aggressive circular mandates, fulfillment centers ensure continuous efficiency and secure a highly reliable delivery network.
What are the market trends shaping the Europe Corrugated Box Industry?
- The universal adoption of digital printing and variable high-graphic customization represents a defining technological shift currently reshaping the industry. This structural transition enables fast-moving consumer goods brands to execute dynamic, regionalized marketing campaigns with unprecedented agility.
- The transition toward agile, brand-centric packaging marks a profound technological evolution across modern fulfillment networks. Industrial converters are systematically replacing traditional B-flute profiles with advanced micro-flute configurations, effectively yielding a 20% improvement in structural rigidity and puncture resistance during multi-stage parcel shipping.
- Concurrently, the deployment of high-definition direct digital printing and single-pass inkjet printing presses facilitates instantaneous graphic modifications, allowing operators to execute dynamic marketing campaigns. Facilities integrating these digital systems report a 35% reduction in production setup times compared to analog methods.
- Optimizing fiber degradation prevention treatments ensures that containers maintain absolute integrity within closed-loop recycling systems, delivering superior aesthetic presentation and robust mechanical performance.
What challenges does the Europe Corrugated Box Industry face during its growth?
- Extreme volatility in recovered fiber feedstock and fluctuating input material costs pose formidable structural threats, severely compressing profit margins for secondary packaging converters.
- Severe unpredictability in recovered fiber feedstock pricing and elevated baseload energy expenditures pose acute operational vulnerabilities for packaging manufacturers. Intense global competition for high-quality domestic paper has systematically depleted regional reserves, triggering sudden cost spikes for recycled testliner and compressing profit margins by up to 18%.
- This pricing volatility disrupts established procurement strategies, as the cost differential between recycled inputs and premium virgin kraftliner narrows unpredictably. Furthermore, the aggressive encroachment of multi-use polymer pooling systems accelerates returnable plastic container displacement, threatening market share in agricultural logistics. Independent operators utilizing traditional flexographic printing experience a 12% increase in conversion expenses at automated converting facilities.
- This inflation directly challenges the cost competitiveness of heavy-duty transit packaging and compromises vertical compression strength optimization.
Exclusive Technavio Analysis on Customer Landscape
The europe corrugated box market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the europe corrugated box market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
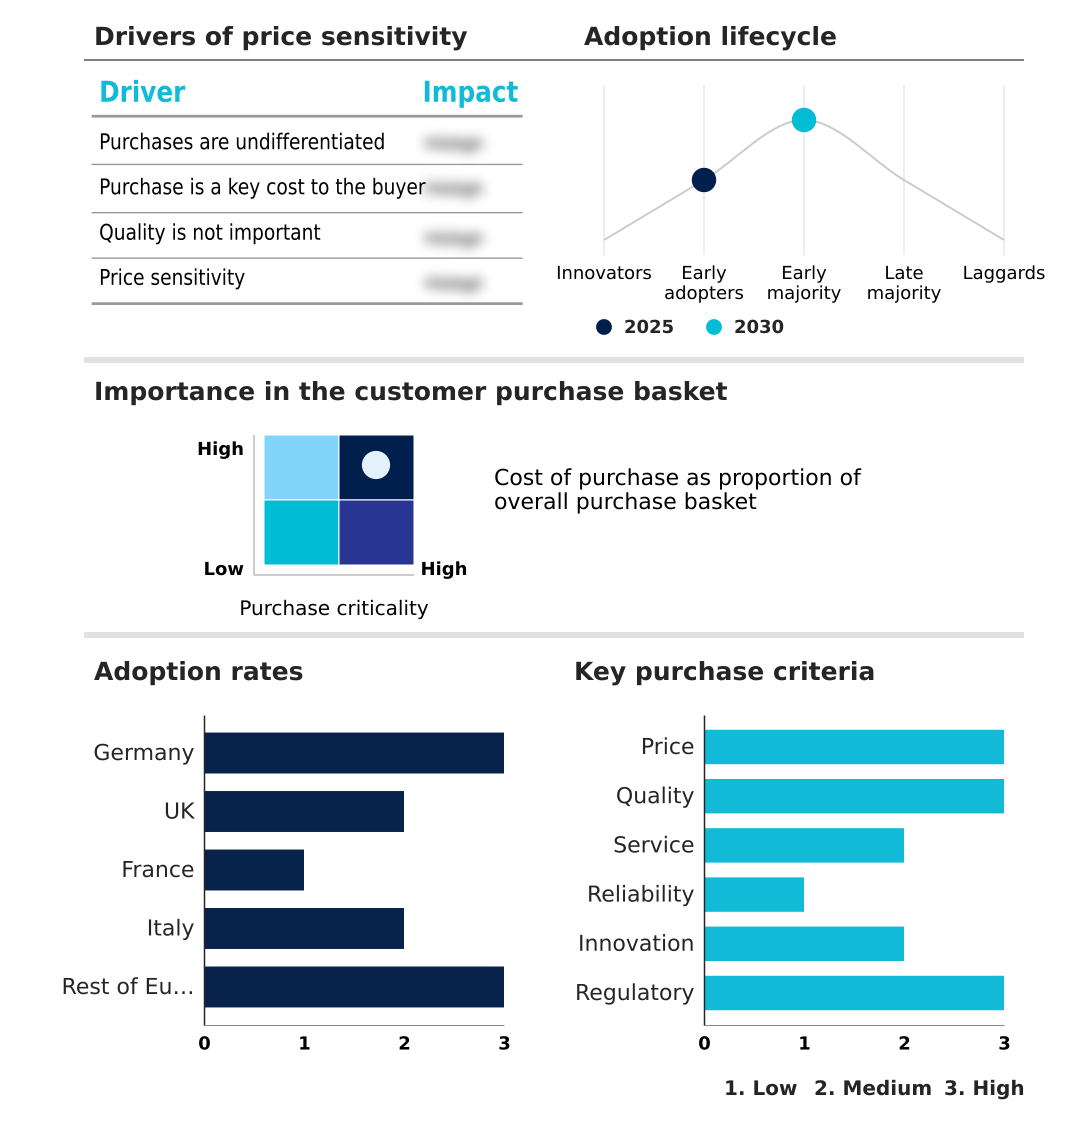
Customer Landscape of Europe Corrugated Box Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, europe corrugated box market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Cart One S.r.l. - The entity provides comprehensive corrugated cardboard packaging and highly customized paper-based secondary packaging formats, focusing on structural durability and sustainable material utilization for varied industrial applications.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Cart One S.r.l.
- Cepac Ltd
- DS Smith Plc
- International Paper Co.
- Klingele Paper and Packaging
- McLaren Packaging Ltd
- MODEL HOLDING AG
- Mondi Plc
- Packsize International Inc.
- Palm Gruppe
- Progroup AG
- Rengo Co. Ltd.
- Rondo Ganahl AG
- Saica Group
- Schumacher Packaging GmbH
- SEDA International Packaging
- Smurfit Westrock plc
- Stora Enso Oyj
- THIMM Group GmbH plus Co. KG
- TRICOR Packaging and Logistics
- VPK Group
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Europe corrugated box market
- In the Metal, Glass and Plastic Containers industry, the implementation of reverse logistics frameworks has accelerated the phase-out of single-use laminates, directly increasing the demand for highly recyclable corrugated packaging as industrial distributors transition to sustainable manufacturing.
- Strict regulatory mandates targeting plastic waste reduction have compelled fast-moving consumer goods manufacturers to seek alternative materials with absolute re-pulpability, displacing rigid polymers with fiber boards in digital fulfillment networks.
- The transition toward reusable polymer container systems within high-volume fresh produce logistics has forced fiber-based converters to innovate with advanced polymer dispersions, enhancing the moisture ingress prevention of transit configurations to compete effectively in cold-chain shipping environments.
- Advancements in automated converting infrastructure and material recovery networks have streamlined operations, ensuring that final packaging designs meet essential point-of-sale marketing criteria amidst fluctuating virgin pulp availability.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Europe Corrugated Box Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 210 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 4% |
| Market growth 2026-2030 | USD 4325.7 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 3.9% |
| Key countries | Germany, UK, France, Italy and Rest of Europe |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The structural engineering of fiber-based packaging requires continuous innovation to endure complex logistical environments and strict environmental mandates. Industrial converters are systematically upgrading their material architecture by integrating advanced starch-bonding agents, ensuring superior rigidity and stackability. This optimization has driven a 18% improvement in structural performance, significantly reducing catastrophic failures during high-capacity warehouse palletization.
- To combat ambient humidity in cold-chain logistics, the strategic application of innovative biopolymer coatings prevents degradation while preserving total recyclability. High-volume consumer goods distributors leveraging these functionalized secondary packaging configurations observe a 22% decrease in transit-related product spoilage compared to untreated transit formats.
- Concurrently, the utilization of premium die-cut mailers allows brands to execute variable, localized graphic campaigns without setup penalties. By aligning premium visual customization directly with robust physical protection, board manufacturers empower retail operators to accelerate inventory turnover and satisfy rigorous sustainability compliance demands across sprawling supply networks.
What are the Key Data Covered in this Europe Corrugated Box Market Research and Growth Report?
-
What is the expected growth of the Europe Corrugated Box Market between 2026 and 2030?
-
USD 4.33 billion, at a CAGR of 4%
-
-
What segmentation does the market report cover?
-
The report is segmented by End-user (Food and beverages, Electronic goods, Personal and household care goods, and Others), Material (Recycled corrugates, and Virgin corrugates), Grade Type (Lightweight grade, Medium‑weight grade, and High‑burst grade) and Geography (Europe)
-
-
Which regions are analyzed in the report?
-
Europe
-
-
What are the key growth drivers and market challenges?
-
Exponential expansion of e-commerce fulfillment networks, Extreme volatility in recovered fiber feedstock and input material costs
-
-
Who are the major players in the Europe Corrugated Box Market?
-
Cart One S.r.l., Cepac Ltd, DS Smith Plc, International Paper Co., Klingele Paper and Packaging, McLaren Packaging Ltd, MODEL HOLDING AG, Mondi Plc, Packsize International Inc., Palm Gruppe, Progroup AG, Rengo Co. Ltd., Rondo Ganahl AG, Saica Group, Schumacher Packaging GmbH, SEDA International Packaging, Smurfit Westrock plc, Stora Enso Oyj, THIMM Group GmbH plus Co. KG, TRICOR Packaging and Logistics and VPK Group
-
Market Research Insights
- The structural evolution of secondary packaging emphasizes robust material efficiency and enhanced supply chain agility to meet rigorous environmental standards. Industrial packaging operations leveraging advanced manufacturing techniques report a 15% improvement in processing throughput over traditional transit formats. Concurrently, the implementation of sustainable board production methods has resulted in a 22% reduction in raw material consumption, optimizing overall fleet efficiency.
- By prioritizing innovative retail-ready formats and integrating high-resolution lithographic prints, converters ensure optimal brand visibility without sacrificing recyclability. Furthermore, facilities adopting automated workflows observe an 18% increase in output, effectively balancing high-volume production with strict ecological mandates to secure long-term operational resilience.
We can help! Our analysts can customize this europe corrugated box market research report to meet your requirements.
 RIA -

