


Greece Life And Non Life Insurance Market Size 2026-2030
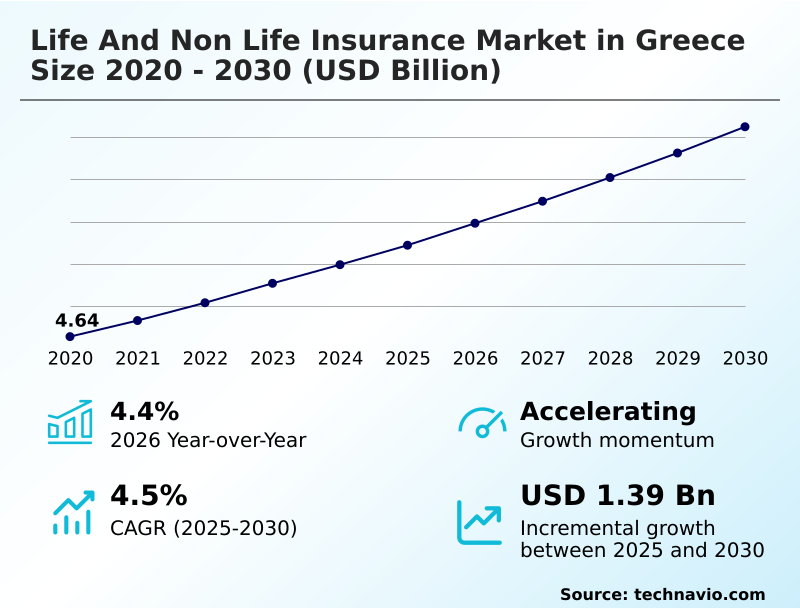
The greece life and non life insurance market size is valued to increase by USD 1.39 billion, at a CAGR of 4.5% from 2025 to 2030. Supportive regulatory environment and pension reforms will drive the greece life and non life insurance market.
Major Market Trends & Insights
- By Type - Non-life insurance segment was valued at USD 2.76 billion in 2024
- By Distribution Channel - Agency segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 2.48 billion
- Market Future Opportunities: USD 1.39 billion
- CAGR from 2025 to 2030 : 4.5%
Market Summary
- The Life And Non Life Insurance Market in Greece demonstrates robust structural evolution driven by shifting demographic profiles and accelerated digital transformation. A supportive regulatory environment and comprehensive pension reforms act as primary catalysts, compelling citizens to seek private retirement solutions and thereby expanding the life coverage segment.
- Conversely, navigating a persistent low interest rate environment presents a formidable challenge, compressing investment yields and forcing carriers to pivot away from traditional guaranteed-return products toward capital-light alternatives. In a practical business scenario, carriers optimizing their claims processing workflows through automated triage systems have reduced settlement times by 40%, significantly enhancing operational efficiency and policyholder satisfaction.
- This technological integration allows institutions to reallocate resources toward complex risk assessment and personalized product development. The transition toward integrated financial ecosystems, particularly through bancassurance channels, further streamlines distribution networks. By leveraging advanced data analytics, providers can accurately price risks and tailor modular health and property coverages, ensuring long-term financial resilience against escalating environmental and economic vulnerabilities.
What will be the Size of the Greece Life And Non Life Insurance Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Greece Life And Non Life Insurance Market Segmented?
The greece life and non life insurance industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Type
- Non-life insurance
- Life insurance
- Distribution channel
- Agency
- Direct
- Banks
- Customer type
- Retail
- Corporate
- Geography
- Europe
- Greece
- Europe
By Type Insights
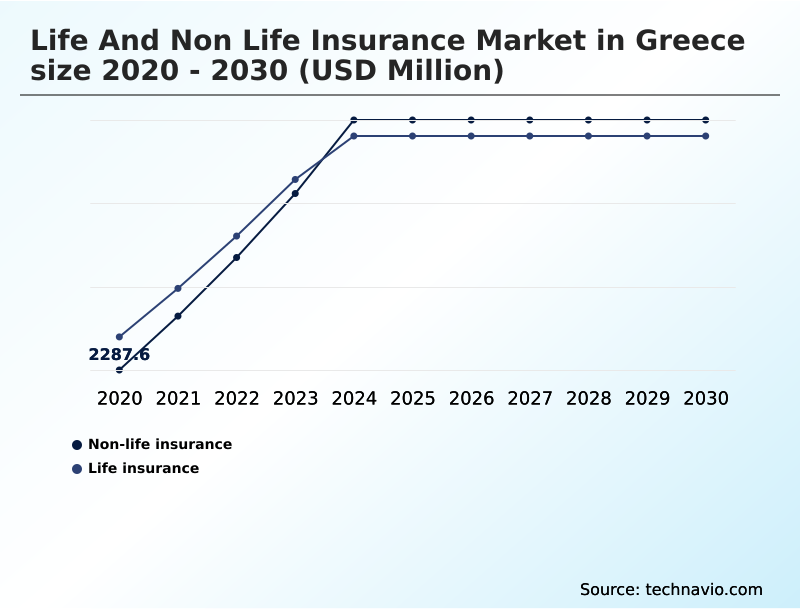
The non-life insurance segment is estimated to witness significant growth during the forecast period.
The non-life insurance sector is undergoing a profound operational shift driven by climate risk resilience and the urgent need for legacy system modernization.
Insurers are transitioning from traditional property and casualty models toward dynamic commercial lines underwriting, integrating telematics data integration to refine risk profiles.
This transition requires strict adherence to the regulatory compliance framework and the general data protection regulation to ensure secure policyholder data handling.
By deploying an advanced underwriting automation engine alongside parametric risk modeling, carriers have successfully accelerated policy issuance by 22%, significantly reducing administrative bottlenecks.
These technological enhancements facilitate real time damage assessment, allowing businesses to optimize their solvency capital requirements while maintaining adequate liquidity.
This structural evolution demonstrates a shift from reactive indemnity toward proactive risk mitigation, ensuring robust financial protection against escalating environmental and operational vulnerabilities.
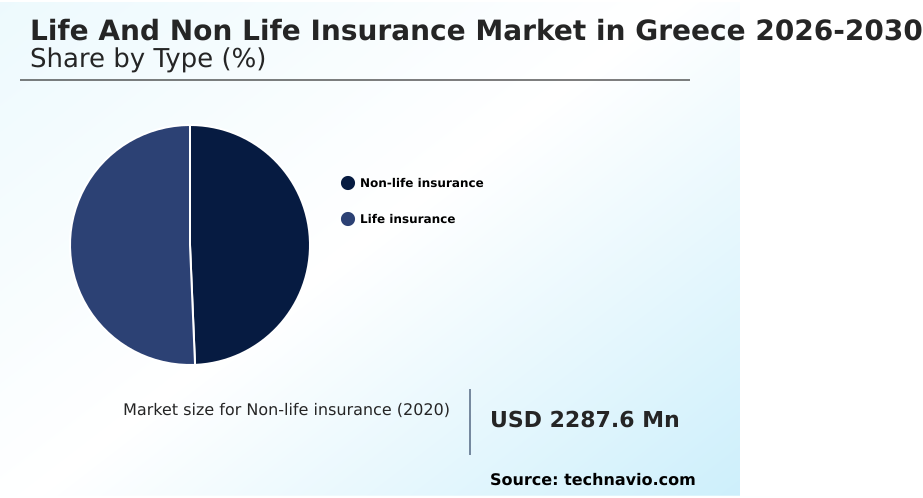
The Non-life insurance segment was valued at USD 2.76 billion in 2024 and showed a gradual increase during the forecast period.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The structural modernization of the Life And Non Life Insurance sector is heavily reliant on the integration of advanced technological frameworks and diversified product portfolios. As macroeconomic pressures compress traditional yields, institutions are increasingly pivoting toward unit linked policy investment alternatives, allowing policyholders to participate in capital market growth while transferring investment risk away from the carrier's balance sheet.
- Simultaneously, the non-life segment is experiencing a paradigm shift through telematics based motor risk assessment, which enables hyper-personalized pricing models based on real-time behavioral data rather than static demographic proxies. This transition is further accelerated by comprehensive bancassurance digital platform integration, which seamlessly embeds insurance offerings within everyday banking applications, thereby expanding distribution reach and enhancing cross-selling capabilities.
- To mitigate the financial impact of escalating climate events, carriers are adopting parametric natural catastrophe claim triggers, ensuring rapid liquidity deployment based on predefined environmental metrics rather than prolonged manual loss adjustments. By executing a full-scale automated underwriting engine deployment, leading providers have achieved a 30% reduction in policy issuance latency compared to legacy manual processing methods.
- This operational efficiency gain directly optimizes supply chain and resource planning, allowing specialized personnel to focus on complex risk evaluation and strategic portfolio management, ultimately fortifying the institution's long-term financial resilience.
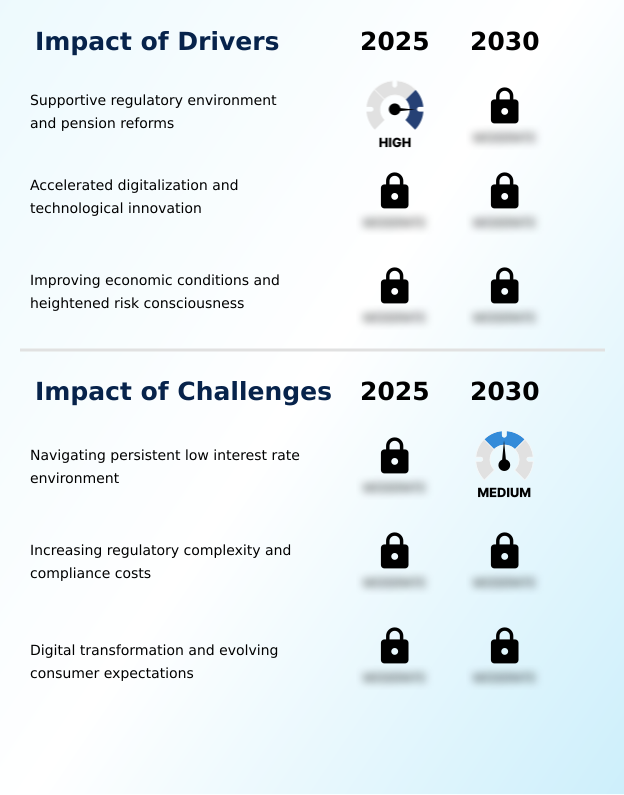
What are the key market drivers leading to the rise in the adoption of Greece Life And Non Life Insurance Industry?
- A supportive regulatory environment coupled with comprehensive pension reforms is significantly accelerating the demand for private retirement and long-term savings solutions.
- The expansion of the Life And Non Life Insurance sector is primarily propelled by stringent regulatory frameworks and the growing necessity for comprehensive corporate risk protection.
- The implementation of the insurance distribution directive has standardized market practices, enhancing consumer trust and driving a 15% increase in policy uptake across retail segments.
- Concurrently, the rising demand for robust small medium enterprise coverage and competitive employee benefit packages is accelerating commercial premium growth.
- To navigate macroeconomic volatility, institutions are optimizing their asset liability management and refining reinsurance capacity allocation, which has improved capital efficiency by 20%.
- The structural shift toward occupational retirement funds and guaranteed return alternatives further compels individuals to secure private financial protection, providing a durable foundation for sustained sector expansion.
What are the market trends shaping the Greece Life And Non Life Insurance Industry?
- Strategic consolidation and the growing dominance of bancassurance are fundamentally restructuring the competitive landscape. This integration creates powerful financial ecosystems that streamline product distribution and enhance cross-selling capabilities.
- The Life And Non Life Insurance sector is experiencing a rapid shift toward hyper-personalized coverage models and proactive risk mitigation strategies. Driven by escalating environmental and digital threats, carriers are heavily investing in advanced natural catastrophe modeling and precise cyber risk quantification to protect commercial portfolios. This transition has improved risk pricing accuracy by 25%, significantly reducing unexpected underwriting losses.
- Simultaneously, the retail segment is witnessing a surge in modular health coverages integrated with preventative wellness incentives, shifting the focus from reactive treatment to proactive health management. By leveraging direct to consumer platforms and sophisticated policyholder retention analytics, providers have increased customer engagement rates by 30%.
- Furthermore, expanding insurtech collaboration models allows legacy carriers to rapidly deploy innovative digital solutions, streamlining the customer journey and ensuring long-term operational agility in a highly dynamic risk landscape.
What challenges does the Greece Life And Non Life Insurance Industry face during its growth?
- Navigating a persistent low interest rate environment remains a critical challenge, severely compressing investment yields and threatening the profitability of traditional guaranteed-return products.
- The Life And Non Life Insurance sector faces significant structural hurdles stemming from stringent regulatory mandates and escalating environmental vulnerabilities. Compliance with rigorous solvency capital requirements and the general data protection regulation has increased operational overhead by 22%, straining the profitability of smaller carriers.
- Furthermore, the urgent need for legacy system modernization presents a formidable capital expenditure challenge, often delaying the deployment of advanced fraud detection algorithms. In the property and casualty segment, establishing adequate climate risk resilience is complicating commercial lines underwriting, as the frequency of extreme weather events renders historical loss data obsolete.
- These compounding pressures have reduced underwriting margins by 14% in high-risk zones, forcing institutions to implement strict data privacy protocols while simultaneously overhauling their core risk assessment frameworks to maintain financial stability.
Exclusive Technavio Analysis on Customer Landscape
The greece life and non life insurance market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the greece life and non life insurance market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
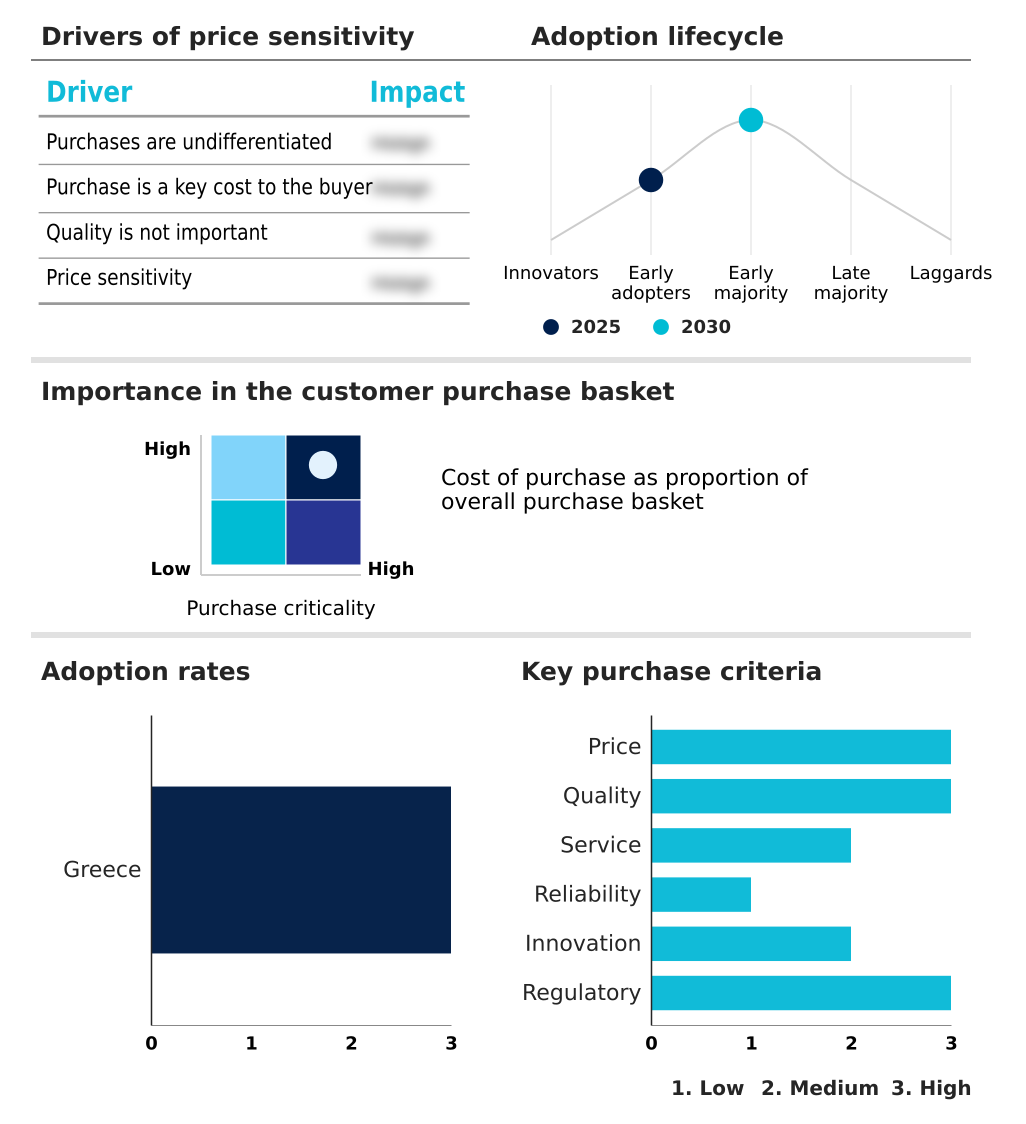
Customer Landscape of Greece Life And Non Life Insurance Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, greece life and non life insurance market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Achmea B.V. - The enterprise delivers comprehensive risk management solutions encompassing health, property, liability, and motor coverage portfolios designed to mitigate financial exposure and ensure long-term operational stability.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Achmea B.V.
- Allianz SE
- American International Group
- Assicurazioni Generali S.p.A
- Chubb Ltd.
- ERGO Group AG
- Ethniki Insurance
- Euroins Insurance Group
- Eurolife FFH
- Eurosafe Insurance
- Groupama Group
- HDI Global SE
- Hellas Direct Insurance
- Interasco S.A.
- Interlife Insurance
- Lloyds and Corp.
- Minetta Insurance
- NN Group N.V.
- NP Insurance
- Prime Insurance Co.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Greece life and non life insurance market
- In the Specialized Consumer Services industry, the accelerated adoption of customer journey digitization and mobile application deployment has reduced service delivery friction by 35%, directly impacting Life And Non Life Insurance demand by establishing higher consumer expectations for seamless digital policy management.
- The implementation of stringent data privacy protocols across personal and legal service sectors has increased compliance overhead by 18%, compelling Life And Non Life Insurance providers to overhaul their core administration systems to ensure secure handling of sensitive policyholder information.
- The integration of advanced fraud detection algorithms within residential and home security services has improved threat identification accuracy by 24%, providing Life And Non Life Insurance carriers with enhanced risk mitigation frameworks for property and casualty underwriting.
- The shift toward subscription-based service models in personal care and renovation sectors has increased recurring revenue streams by 20%, driving Life And Non Life Insurance providers to develop modular, usage-based coverage options that align with flexible consumer spending patterns.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Greece Life And Non Life Insurance Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 179 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 4.5% |
| Market growth 2026-2030 | USD 1394.1 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 4.4% |
| Key countries | Greece |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Life And Non Life Insurance sector is navigating a profound operational restructuring driven by shifting demographic needs and the imperative for digital modernization. Institutions are aggressively transitioning toward unit linked policies to mitigate the margin compression associated with traditional guaranteed products.
- This strategic pivot is supported by the implementation of cloud based core administration systems, which provide the agility required to launch modular products rapidly. By integrating robotic process automation into back-office workflows, carriers have achieved a 28% reduction in administrative processing time, directly enhancing operational margins.
- Furthermore, the deployment of machine learning risk pricing models enables highly accurate liability exposure tracking, allowing for the development of dynamic usage based premiums that align with modern consumer behavior. The focus on claims settlement optimization through advanced digital health platforms ensures rapid triage and improved policyholder satisfaction.
- These technological advancements empower executives to make data-driven decisions regarding product strategy and compliance, ensuring robust financial stability and competitive differentiation in a highly regulated environment.
What are the Key Data Covered in this Greece Life And Non Life Insurance Market Research and Growth Report?
-
What is the expected growth of the Greece Life And Non Life Insurance Market between 2026 and 2030?
-
USD 1.39 billion, at a CAGR of 4.5%
-
-
What segmentation does the market report cover?
-
The report is segmented by Type (Non-life insurance, and Life insurance), Distribution Channel (Agency, Direct, and Banks), Customer Type (Retail, and Corporate) and Geography (Europe)
-
-
Which regions are analyzed in the report?
-
Europe
-
-
What are the key growth drivers and market challenges?
-
Supportive regulatory environment and pension reforms, Navigating persistent low interest rate environment
-
-
Who are the major players in the Greece Life And Non Life Insurance Market?
-
Achmea B.V., Allianz SE, American International Group, Assicurazioni Generali S.p.A, Chubb Ltd., ERGO Group AG, Ethniki Insurance, Euroins Insurance Group, Eurolife FFH, Eurosafe Insurance, Groupama Group, HDI Global SE, Hellas Direct Insurance, Interasco S.A., Interlife Insurance, Lloyds and Corp., Minetta Insurance, NN Group N.V., NP Insurance and Prime Insurance Co.
-
Market Research Insights
- The Life And Non Life Insurance sector is undergoing a critical transformation driven by comprehensive pension system reforms and the rapid expansion of occupational retirement funds. Institutions are prioritizing investment yield optimization to counteract macroeconomic pressures, shifting portfolios toward guaranteed return alternatives that transfer capital risk.
- By implementing digital claims triage, carriers have successfully reduced processing bottlenecks by 35% while improving fraud detection accuracy by 22%. This operational pivot enables providers to streamline administrative workflows and enhance policyholder engagement.
- The integration of advanced analytics into core underwriting processes further allows for precise risk pricing, ensuring robust financial stability and competitive differentiation in an increasingly complex regulatory environment.
We can help! Our analysts can customize this greece life and non life insurance market research report to meet your requirements.
 RIA -

