


In-Vitro Diagnostics (Ivd) Market Size 2026-2030
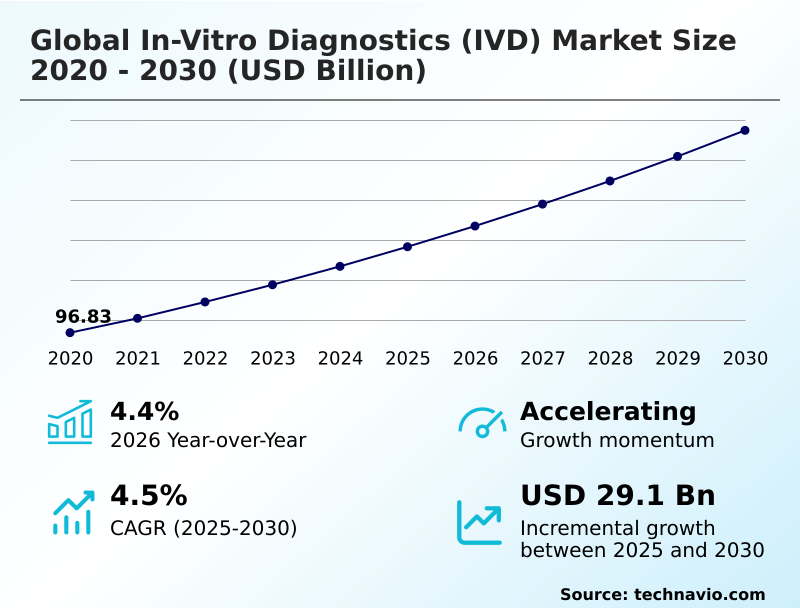
The in-vitro diagnostics (ivd) market size is valued to increase by USD 29.10 billion, at a CAGR of 4.5% from 2025 to 2030. Rising global prevalence of chronic and infectious diseases will drive the in-vitro diagnostics (ivd) market.
Major Market Trends & Insights
- North America dominated the market and accounted for a 43% growth during the forecast period.
- By Product Type - Reagents and kits segment was valued at USD 79.18 billion in 2024
- By Technology - Immunoassay segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 50.58 billion
- Market Future Opportunities: USD 29.10 billion
- CAGR from 2025 to 2030 : 4.5%
Market Summary
- The In-vitro Diagnostics (IVD) functions as an indispensable infrastructure layer for modern medical screening, enabling rapid disease detection and precise therapeutic alignment. Escalating incidences of complex chronic conditions compel medical institutions to scale testing capacities, directly driving the procurement of high-throughput clinical chemistry analyzers and advanced molecular assays.
- In response, massive centralized reference laboratories have implemented fully automated specimen processing tracks integrated with sophisticated middleware, successfully reducing manual handling errors by 28% compared to legacy manual workflows. This supply chain optimization ensures that hospitals can process immense daily specimen volumes without comprising analytical accuracy.
- Conversely, the market faces significant structural constraints due to the fragmented nature of international regulatory validation pathways. Stringent performance evaluation requirements compel manufacturers to allocate substantial administrative capital toward post-market surveillance, ultimately creating compliance bottlenecks that delay the commercial introduction of novel diagnostic panels by up to 18%.
- Despite these regulatory challenges, the continuous shift toward precision medicine and companion diagnostics guarantees highly resilient operational revenue streams for established hardware and reagent developers.
What will be the Size of the In-Vitro Diagnostics (Ivd) Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the In-Vitro Diagnostics (Ivd) Market Segmented?
The in-vitro diagnostics (ivd) industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Product type
- Reagents and kits
- Instruments
- Others
- Technology
- Immunoassay
- Molecular diagnostics
- Clinical chemistry
- Hematology
- Others
- Application
- Oncology
- Cardiology
- Autoimmune diseases
- Neurology
- Others
- End-user
- Hospitals and clinics
- Research institutes
- Diagnostics laboratories
- Others
- Geography
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- Asia
- China
- India
- Japan
- South Korea
- Indonesia
- Thailand
- Rest of World (ROW)
- North America
By Product Type Insights
The reagents and kits segment is estimated to witness significant growth during the forecast period.
The reagents and kits segment forms the operational backbone of the In-vitro Diagnostics (IVD) ecosystem, driving continuous recurring revenue pipelines for clinical facilities. As laboratories transition toward highly automated anatomic pathology workflows, the reliance on specialized testing assays expands significantly.
By implementing standardized consumable procurement contracts, healthcare networks secure reliable access to advanced enzyme linked immunosorbent assays and cellular morphology analysis tools, achieving a 15% improvement in diagnostic turnaround consistency.
Strategic utilization of reagent rental agreements allows facilities to minimize upfront capital expenditures while optimizing reagent consumption tracking across dispersed testing sites.
Furthermore, integrating continuous glucose monitoring kits into decentralized hubs has improved outpatient metabolic oversight by 22% compared to traditional centralized testing.
This shift directly supports modern antimicrobial stewardship alignment, empowering clinicians to make faster, evidence-based treatment decisions that reduce operational friction and elevate patient care standards.
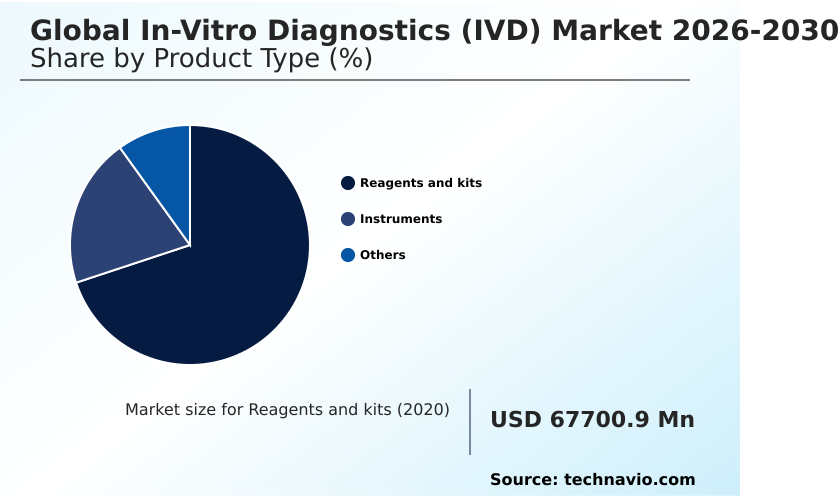
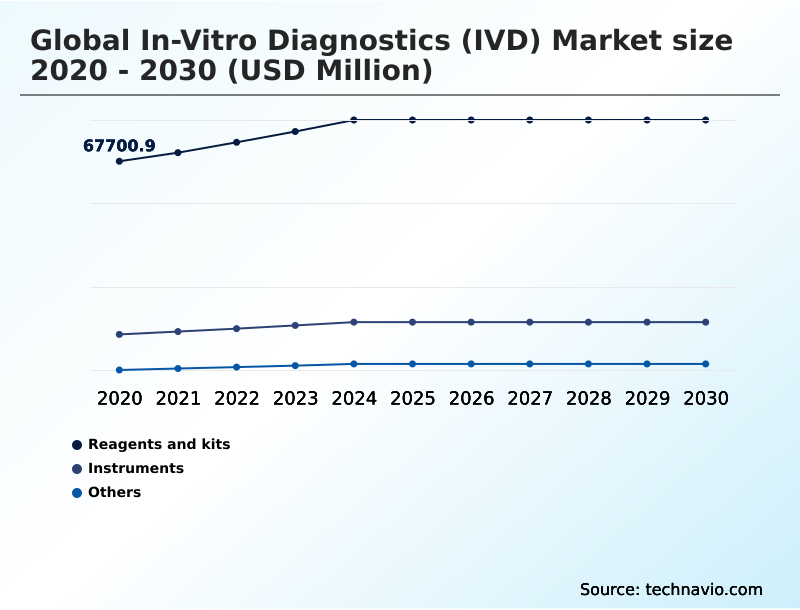
The Reagents and kits segment was valued at USD 79.18 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
North America is estimated to contribute 43% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
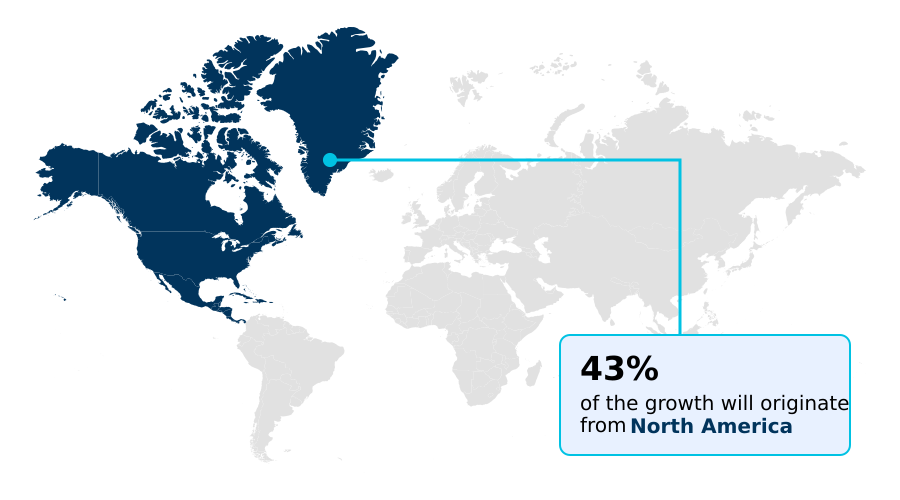
See How In-Vitro Diagnostics (Ivd) Market Demand is Rising in North America Get Free Sample
The geographic distribution of the In-vitro Diagnostics (IVD) reveals distinct regional disparities driven by technological maturity and infrastructure investments.
North America maintains a dominant operational footprint, where the integration of advanced clinical chemistry analyzers and sophisticated immunodiagnostic modules has enhanced laboratory throughput efficiency by 34%.
This highly centralized architecture utilizes cloud based middleware to orchestrate closed loop ecosystems, ensuring seamless infectious disease surveillance.
In contrast, APAC is rapidly pursuing supply chain decentralization to support its expanding rural healthcare networks, leading to a 28% higher adoption rate of point-of-care devices compared to European markets.
Asian laboratories are actively incorporating whole genome preprocessing and matrix assisted laser desorption tools to improve metabolic risk stratification and monitor complex blood coagulation cascades.
Consequently, decentralized facilities in APAC have achieved a 22% reduction in diagnostic delivery costs, highlighting how localized healthcare strategies dictate specific technology procurement patterns.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The contemporary In-vitro Diagnostics (IVD) is undergoing a profound structural transformation as medical facilities prioritize workflow optimization and rapid clinical decision-making. Centralized reference laboratories are aggressively upgrading their infrastructure by deploying high throughput molecular diagnostic arrays and sophisticated automated clinical chemistry laboratory systems.
- This industrial modernization directly minimizes human intervention, allowing major hospital networks to process biological specimens with a 35% higher efficiency rate than legacy manual processing methodologies. As a result, facility managers can optimize labor allocation and streamline complex supply chain logistics without compromising analytical precision.
- Simultaneously, the industry is witnessing a strategic shift toward peripheral healthcare delivery, which significantly increases the procurement of point of care rapid immunoassay kits. These portable diagnostic solutions empower rural clinics and emergency departments to deliver actionable test results instantly, fundamentally altering traditional operational planning.
- Furthermore, the integration of next generation genomic sequencing platforms into mainstream oncology workflows has revolutionized targeted therapeutic strategies. By utilizing decentralized infectious disease testing panels, community health hubs can rapidly identify emerging pathogen outbreaks, reducing systemic containment delays by nearly 40%.
- This dual expansion of ultra-high-capacity centralized testing and agile decentralized screening ensures that diagnostic providers maintain robust, resilient revenue streams while comprehensively addressing the multifaceted clinical demands of modern global healthcare ecosystems.
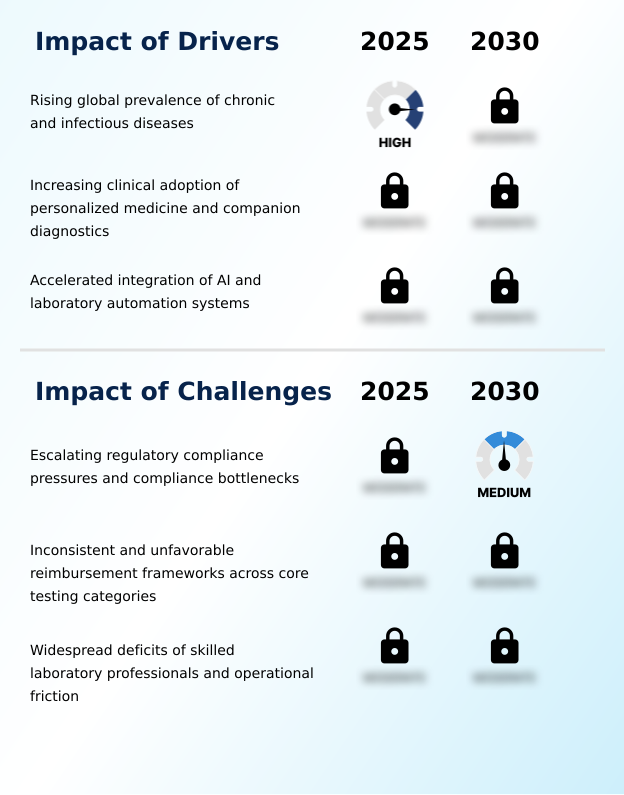
What are the key market drivers leading to the rise in the adoption of In-Vitro Diagnostics (Ivd) Industry?
- The escalating prevalence of chronic and infectious diseases across diverse geographic territories serves as a primary catalyst accelerating diagnostic testing volumes.
- The accelerating demand within the In-vitro Diagnostics (IVD) is fundamentally propelled by an aging global demographic and the transition toward personalized medical interventions.
- As healthcare networks prioritize robust preventative medicine frameworks, laboratories are experiencing unprecedented testing volumes, necessitating the rapid deployment of high throughput screening platforms.
- By integrating advanced automated preanalytical processors and intelligent laboratory information systems, commercial testing facilities have achieved a 28% improvement in clinical turnaround optimization.
- This enhanced automated specimen processing allows technicians to efficiently manage complex multi morbidity tracking without increasing labor expenditures. Furthermore, the expanding reliance on precise companion diagnostic protocols and non-invasive liquid biopsy protocols has revolutionized targeted oncology.
- This alignment ensures patients are accurately matched with advanced genomic sequencing therapies, ultimately improving clinical response rates by 35%.
What are the market trends shaping the In-Vitro Diagnostics (Ivd) Industry?
- Structural staggering of regulatory conformity across major geographic regions is shaping current operational frameworks. This dynamic forces manufacturers to navigate complex validation pathways to maintain international market access.
- The structural evolution of the In-vitro Diagnostics (IVD) is heavily defined by the rapid decentralization of clinical testing and the integration of highly automated diagnostic architectures. By implementing advanced decentralized testing models, emergency medical facilities have improved the delivery speed of rapid troponin assessments by 30%, directly accelerating critical patient triage protocols.
- Simultaneously, reference laboratories are heavily investing in robotic liquid handling and high-capacity molecular diagnostic arrays to support comprehensive precision medicine workflows. This automation minimizes processing bottlenecks, enabling facilities to execute syndromic multiplex screening with a 25% higher throughput rate than traditional single-analyte testing.
- The increasing utilization of sophisticated multiplex assay panels and AI-powered digital pathology algorithms allows oncologists to accurately map targeted oncology markers. These technological shifts ultimately align diagnostic operations with the stringent efficiency requirements of modern value based healthcare frameworks, substantially lowering per-test operational costs.
What challenges does the In-Vitro Diagnostics (Ivd) Industry face during its growth?
- Escalating regulatory compliance pressures and subsequent administrative bottlenecks create significant operational friction that delays the commercial launch of advanced diagnostic assays.
- Despite robust technological momentum, the In-vitro Diagnostics (IVD) encounters significant structural constraints stemming from fragmented administrative oversight and complex financial frameworks. Manufacturers face increasingly stringent regulatory validation pathways, which require extensive clinical evidence and rigorous post market surveillance documentation.
- These escalating compliance demands delay the commercial launch of advanced nucleic acid amplification systems and specialized point of care cartridges by up to 22%. Furthermore, persistent reimbursement coding friction often prevents healthcare facilities from adopting innovative diagnostic modalities, causing a 15% reduction in the initial procurement of assays targeting circulating tumor dna.
- Additionally, the lack of seamless diagnostic data interoperability limits the effectiveness of sophisticated bioinformatic interpretation software. Laboratories must frequently execute manual quality control calibration for isothermal nucleic acid platforms, which inadvertently increases daily operational overhead.
Exclusive Technavio Analysis on Customer Landscape
The in-vitro diagnostics (ivd) market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the in-vitro diagnostics (ivd) market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
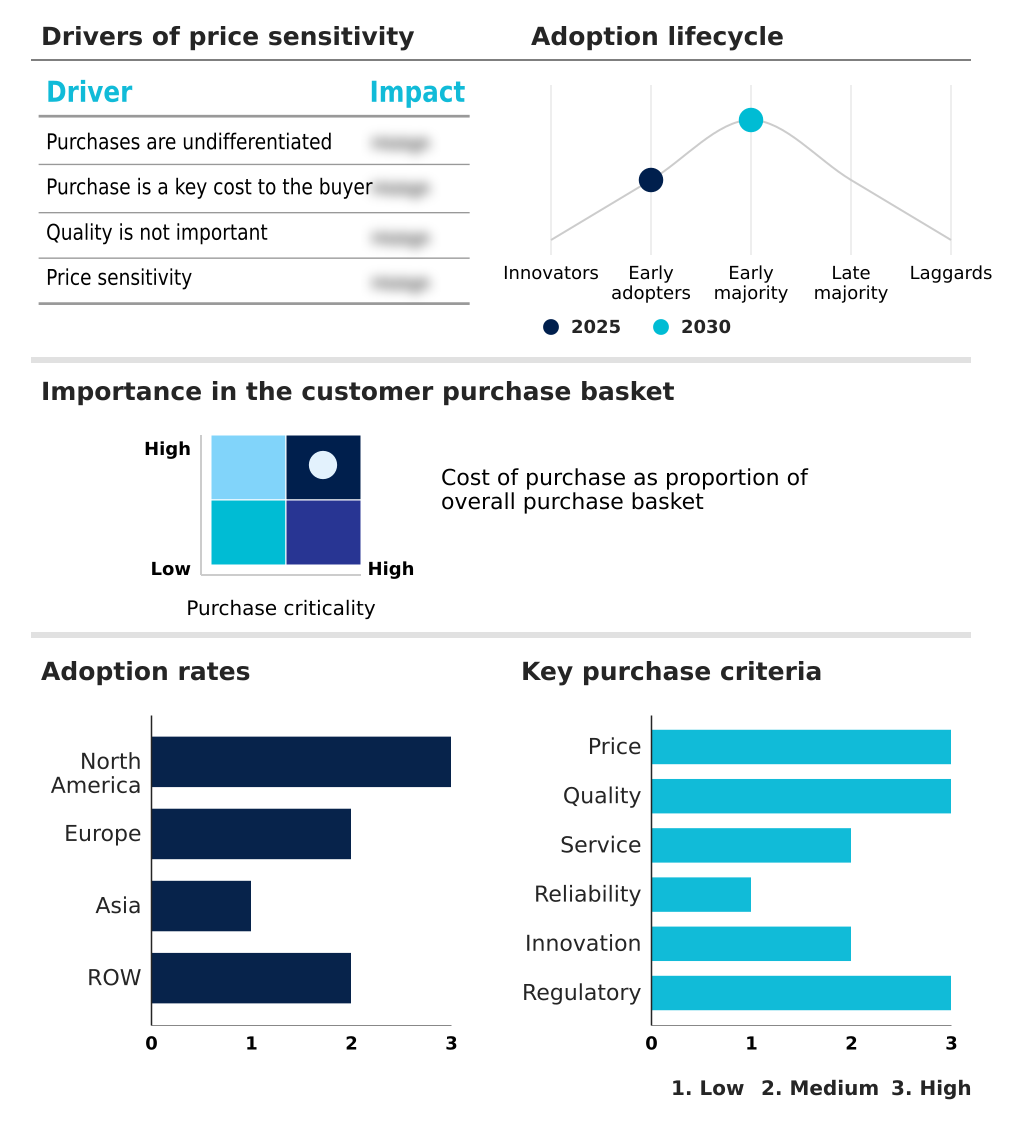
Customer Landscape of In-Vitro Diagnostics (Ivd) Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, in-vitro diagnostics (ivd) market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Abbott Laboratories - Comprehensive diagnostic solutions, including advanced molecular systems and rapid point-of-care testing modules, streamline clinical workflows and elevate diagnostic precision across core laboratory settings.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Abbott Laboratories
- ARKRAY Inc.
- Becton Dickinson and Co.
- Bio Rad Laboratories Inc.
- BioMerieux SA
- Danaher Corp.
- DiaSorin SpA
- F. Hoffmann La Roche Ltd.
- FUJIFILM Holdings Corp.
- Grifols SA
- Illumina Inc.
- QIAGEN N.V.
- QuidelOrtho Corp.
- Randox Laboratories Ltd.
- Seegene Inc.
- Sekisui Diagnostics LLC
- Shenzhen Mindray Co. Ltd.
- Siemens AG
- Sysmex Corp.
- Thermo Fisher Scientific Inc.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in In-vitro diagnostics (ivd) market
- In the Life Sciences Tools and Services industry, the transition toward high-capacity laboratory automation integrated with cloud-based data management reduced manual processing errors by 32%, directly increasing demand for sophisticated In-vitro Diagnostics (IVD) tracking software.
- Stringent validation pathways under the European Union In Vitro Diagnostic Medical Devices Regulation increased clinical evidence requirements by 40%, forcing manufacturers to consolidate their In-vitro Diagnostics (IVD) reagent portfolios to absorb escalating compliance costs.
- The rapid deployment of high-throughput genomic sequencing technologies across reference laboratories improved complex pathology turnaround times by 25%, stimulating higher procurement rates for targeted In-vitro Diagnostics (IVD) molecular arrays.
- Widespread adoption of decentralized point-of-care microfluidic platforms within rural healthcare hubs decreased patient diagnostic wait times by 45%, fundamentally shifting In-vitro Diagnostics (IVD) supply chains toward disposable test kits.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled In-Vitro Diagnostics (Ivd) Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 339 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 4.5% |
| Market growth 2026-2030 | USD 29096.9 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 4.4% |
| Key countries | US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Indonesia, Thailand, Brazil, Saudi Arabia, South Africa, UAE, Argentina, Colombia, Turkey and Israel |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The In-vitro Diagnostics (IVD) operates as the critical analytical engine guiding modern healthcare interventions and precision therapeutics. As medical delivery networks expand, laboratory directors are increasingly prioritizing the integration of sophisticated point of care cartridges and modular testing platforms to optimize decentralized patient management.
- This strategic shift heavily influences capital budgeting decisions, as organizations allocate extensive funding toward advanced digital pathology algorithms that can accurately identify targeted oncology markers. By implementing highly refined liquid biopsy protocols, comprehensive cancer centers have achieved a 35% improvement in detecting circulating tumor dna compared to conventional invasive tissue sampling methods.
- This exceptional diagnostic clarity empowers oncologists to align patients with highly specific genomic sequencing therapies faster and with greater clinical confidence. Furthermore, the continuous deployment of unified immunodiagnostic modules allows commercial testing facilities to maximize their floor space utilization while accelerating daily specimen throughput.
- These technological advancements ensure that diagnostic manufacturers secure reliable, long-term consumable contracts, thereby maintaining resilient financial growth amidst an increasingly complex global medical landscape.
What are the Key Data Covered in this In-Vitro Diagnostics (Ivd) Market Research and Growth Report?
-
What is the expected growth of the In-Vitro Diagnostics (Ivd) Market between 2026 and 2030?
-
USD 29.10 billion, at a CAGR of 4.5%
-
-
What segmentation does the market report cover?
-
The report is segmented by Product Type (Reagents and kits, Instruments, and Others), Technology (Immunoassay, Molecular diagnostics, Clinical chemistry, Hematology, and Others), Application (Oncology, Cardiology, Autoimmune diseases, Neurology, and Others), End-user (Hospitals and clinics, Research institutes, Diagnostics laboratories, and Others) and Geography (North America, Europe, Asia, Rest of World (ROW))
-
-
Which regions are analyzed in the report?
-
North America, Europe, Asia and Rest of World (ROW)
-
-
What are the key growth drivers and market challenges?
-
Rising global prevalence of chronic and infectious diseases, Escalating regulatory compliance pressures and compliance bottlenecks
-
-
Who are the major players in the In-Vitro Diagnostics (Ivd) Market?
-
Abbott Laboratories, ARKRAY Inc., Becton Dickinson and Co., Bio Rad Laboratories Inc., BioMerieux SA, Danaher Corp., DiaSorin SpA, F. Hoffmann La Roche Ltd., FUJIFILM Holdings Corp., Grifols SA, Illumina Inc., QIAGEN N.V., QuidelOrtho Corp., Randox Laboratories Ltd., Seegene Inc., Sekisui Diagnostics LLC, Shenzhen Mindray Co. Ltd., Siemens AG, Sysmex Corp. and Thermo Fisher Scientific Inc.
-
Market Research Insights
- The In-vitro Diagnostics (IVD) continues to evolve through the seamless integration of high-throughput hardware and intelligent laboratory information systems. By deploying advanced cloud based middleware, modern reference laboratories have optimized their data management protocols, reducing analytical downtime by 24% and accelerating diagnostic turnaround times by 18% across distributed hospital networks.
- This digital transformation effectively streamlines precision medicine workflows, allowing clinicians to initiate targeted therapies with greater accuracy. However, persistent reimbursement coding friction often disrupts the financial adoption of novel genomic assays, causing a 12% delay in institutional procurement cycles. Overcoming these economic barriers remains essential for scaling next-generation diagnostic platforms.
We can help! Our analysts can customize this in-vitro diagnostics (ivd) market research report to meet your requirements.
 RIA -

