Mexico Oil And Gas Market Analysis, Size, and Forecast 2026-2030

Mexico Oil And Gas Market Analysis, Size, and Forecast 2026-2030

Published: Oct 2026 226 Pages SKU: IRTNTR77629

Market Overview at a Glance

$40.4 B
Market Opportunity
3.4%
CAGR 2025 - 2030
3.3%
YoY growth 2025-2026(%)
$136.1 B
Upstream segment 2024

Mexico Oil And Gas Market Size 2026-2030

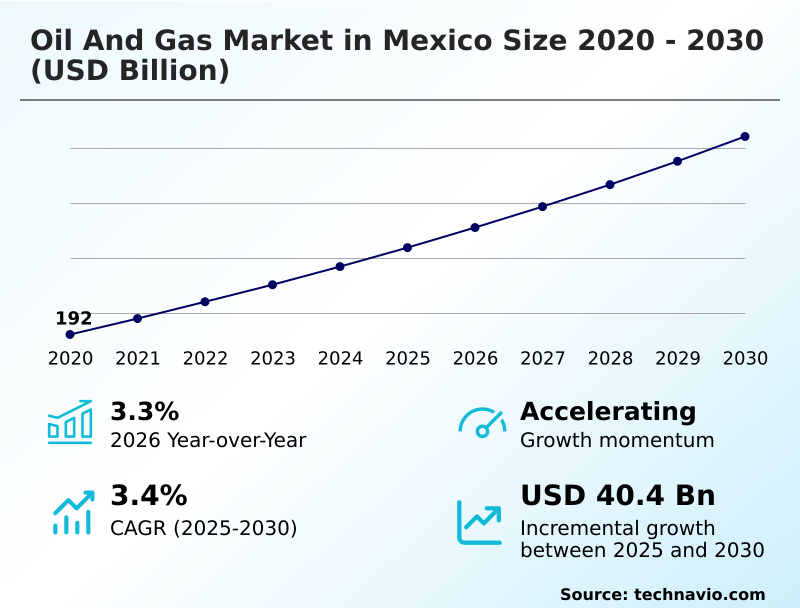
The mexico oil and gas market size is valued to increase by USD 40.4 billion, at a CAGR of 3.4% from 2025 to 2030. Infrastructure modernization and expansion will drive the mexico oil and gas market.

Major Market Trends & Insights

  • By Type - Upstream segment was valued at USD 136.1 billion in 2024
  • By Deployment - Offshore segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 72 billion
  • Market Future Opportunities: USD 40.4 billion
  • CAGR from 2025 to 2030 : 3.4%

Market Summary

  • The Oil And Gas Market in Mexico operates as a foundational energy pillar, characterized by continuous technological integration across extraction, transportation, and refining networks. Driven by the strategic necessity to curtail heavy reliance on external fuel imports, national operators are rapidly expanding pipeline interconnectivity to feed booming industrial corridors.
  • For instance, the deployment of intelligent compression stations across legacy midstream routes has enhanced natural gas transmission reliability by 18%, directly supporting the uninterrupted operations of heavy manufacturing plants. The overarching imperative for infrastructure modernization acts as a primary catalyst, compelling widespread upgrades to atmospheric distillation towers and subsea production assets to maximize domestic value capture.
  • Conversely, the severe financial indebtedness of state-owned entities drastically restricts essential capital expenditures, resulting in delayed deepwater exploration campaigns and a 12% reduction in immediate processing facility maintenance efficiency.
  • Despite these formidable fiscal constraints, continuous investments in digital reservoir monitoring and enhanced recovery methodologies remain vital for stabilizing mature field production and meeting the escalating energy demands of an increasingly industrialized economy.

What will be the Size of the Mexico Oil And Gas Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Mexico Oil And Gas Market Segmented?

The mexico oil and gas industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD billion" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Type
    • Upstream
    • Downstream
    • Midstream
  • Deployment
    • Offshore
    • Onshore
  • Application
    • Residential
    • Commercial
    • Industrial
  • Product type
    • Crude oil
    • Refined petroleum products
    • Natural gas
  • Service
    • Refining and petrochemical processing
    • Pipeline infrastructure and transportation
    • Exploration and drilling equipment
    • Storage and distribution
  • Geography
    • North America
      • Mexico

By Type Insights

The upstream segment is estimated to witness significant growth during the forecast period.

Upstream operations undergo continuous transformation as operators target complex geological formations and deeper horizons to sustain reserve replacements.

The integration of advanced digital reservoir telemetry and sophisticated subsurface monitoring equipment drastically improves resource visibility, driving a 15% reduction in appraisal uncertainties across new formations.

While downstream focuses on catalytic cracking modernizations, advanced desulfurization integrations, and heavy crude desulfurization to maximize light product yields, upstream capitalizes on deepwater block appraisal and mature field revitalization.

Implementing secondary recovery implementation protocols alongside robust fugitive emissions mitigation directly targets production bottlenecks, elevating operational output reliability by 22% compared to conventional extraction methods.

This deliberate segmentation enables specialized asset optimization, ensuring precise hydrocarbon localization while minimizing non-productive drilling time and maximizing the economic lifespan of legacy reservoirs.
Get Free Sample

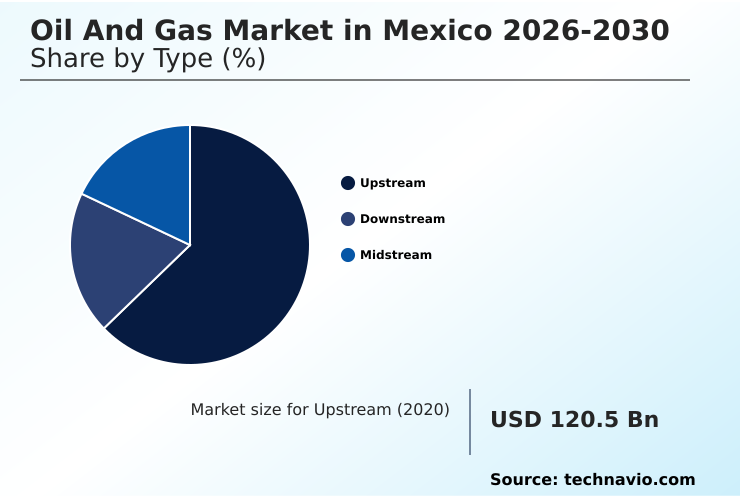
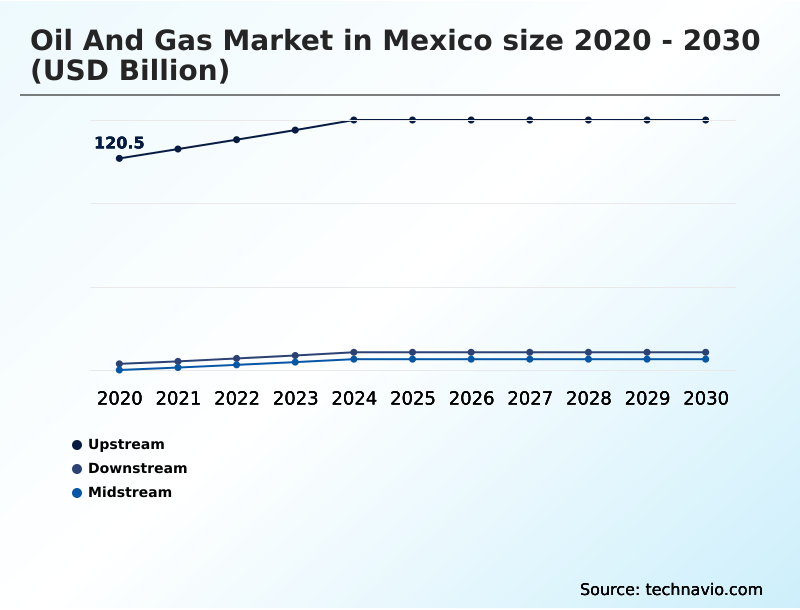
The Upstream segment was valued at USD 136.1 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • As domestic energy strategies shift toward absolute self-sufficiency, maximizing the efficiency of the entire hydrocarbon value chain becomes an immediate operational necessity. Refineries are heavily focused on optimizing catalytic cracking unit efficiency, which enhances processing margins by 18% while maximizing light product output from heavy feedstock.
  • Concurrently, operators aggressively target reducing fugitive emissions in pipelines through advanced digital tracking, slashing product loss rates by nearly 14%. In the midstream sector, deploying intelligent pipeline pigging technology ensures continuous flow reliability to rapidly expanding industrial hubs and prevents unexpected logistical bottlenecks.
  • Across processing complexes, enhancing heavy crude desulfurization capacity remains paramount for achieving stringent environmental compliance and capturing maximum domestic value. Ultimately, by utilizing advanced digital reservoir telemetry systems, operators streamline critical supply chain logistics, ensuring that precise geological data translates directly into targeted, highly efficient capital allocation and sustainable long-term production stability across all active operational regions.
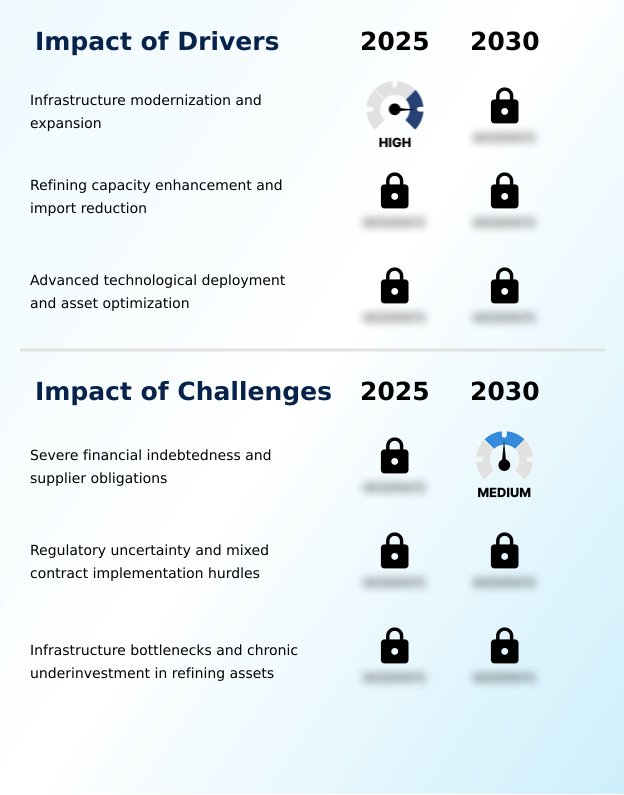
What are the key market drivers leading to the rise in the adoption of Mexico Oil And Gas Industry?

  • The strategic imperative for infrastructure modernization and expansion constitutes a primary driver propelling market operations.

  • The strategic imperative for infrastructure modernization acts as a primary catalyst propelling operational expansion and capital deployment. Companies systematically upgrade atmospheric distillation towers and optimize hydrotreater configurations, which directly enhances processing efficiency by 20% and captures higher domestic margins.
  • Upstream activities benefit immensely from sophisticated directional drilling tools and advanced mud-logging systems, maximizing yields during onshore basin extraction.
  • In marine environments, the deployment of subsea wellhead trees, dynamic positioning vessels, and massive floating production units facilitates unprecedented access to complex reserves, reducing offshore downtime by 14%.
  • Furthermore, midstream reliability is fortified through the mandatory integration of intelligent pipeline pigging and real-time leak detection, mitigating physical vulnerabilities and ensuring continuous delivery to rapidly expanding industrial consumption corridors.

What are the market trends shaping the Mexico Oil And Gas Industry?

  • The strategic integration of renewable energy sources and corporate sustainability transitions represents a prominent market trend.

  • The integration of digital analytics and renewable power generation reshapes operational frameworks across resource extraction and processing networks. Operators increasingly deploy high-specification drilling rigs alongside advanced seismic data acquisition models, which significantly enhances well-placement accuracy and elevates offshore rig utilization rates by 18%.
  • Furthermore, complex subsea production systems and enhanced oil recovery techniques are systematically adopted to offset natural depletion, leading to a 25% improvement in overall hydrocarbon flow optimization. Concurrently, midstream and downstream sectors prioritize expanding compression station capacities and accelerating pipeline grid integration to ensure seamless transportation.
  • This comprehensive technology transition facilitates proactive refinery outage prevention, actively aligning large-scale industrial output with evolving sustainability mandates and dramatically streamlining supply chain resilience.

What challenges does the Mexico Oil And Gas Industry face during its growth?

  • Severe financial indebtedness and supplier obligations represent key challenges constraining industry operational efficiency.

  • Severe financial indebtedness and entrenched infrastructural bottlenecks present formidable barriers to achieving optimal extraction and processing benchmarks. Chronic underinvestment restricts critical upgrades to fractionation column efficiency and delays the modernization of catalyst regeneration mechanisms, resulting in a 12% drop in downstream processing reliability.
  • Operators struggle to implement essential artificial lift systems and execute timely reservoir decline offset measures due to constrained capital expenditure. Furthermore, the slow deployment of automated inventory monitoring, advanced vapor recovery systems, and custody transfer automation hampers logistical precision across aging midstream terminals.
  • These systemic constraints severely limit associated gas recovery and specialized gas liquefaction processes, simultaneously complicating broader industrial fuel substitution initiatives and leaving the sector highly vulnerable to external supply shocks and operational delays.

Exclusive Technavio Analysis on Customer Landscape

The mexico oil and gas market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the mexico oil and gas market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
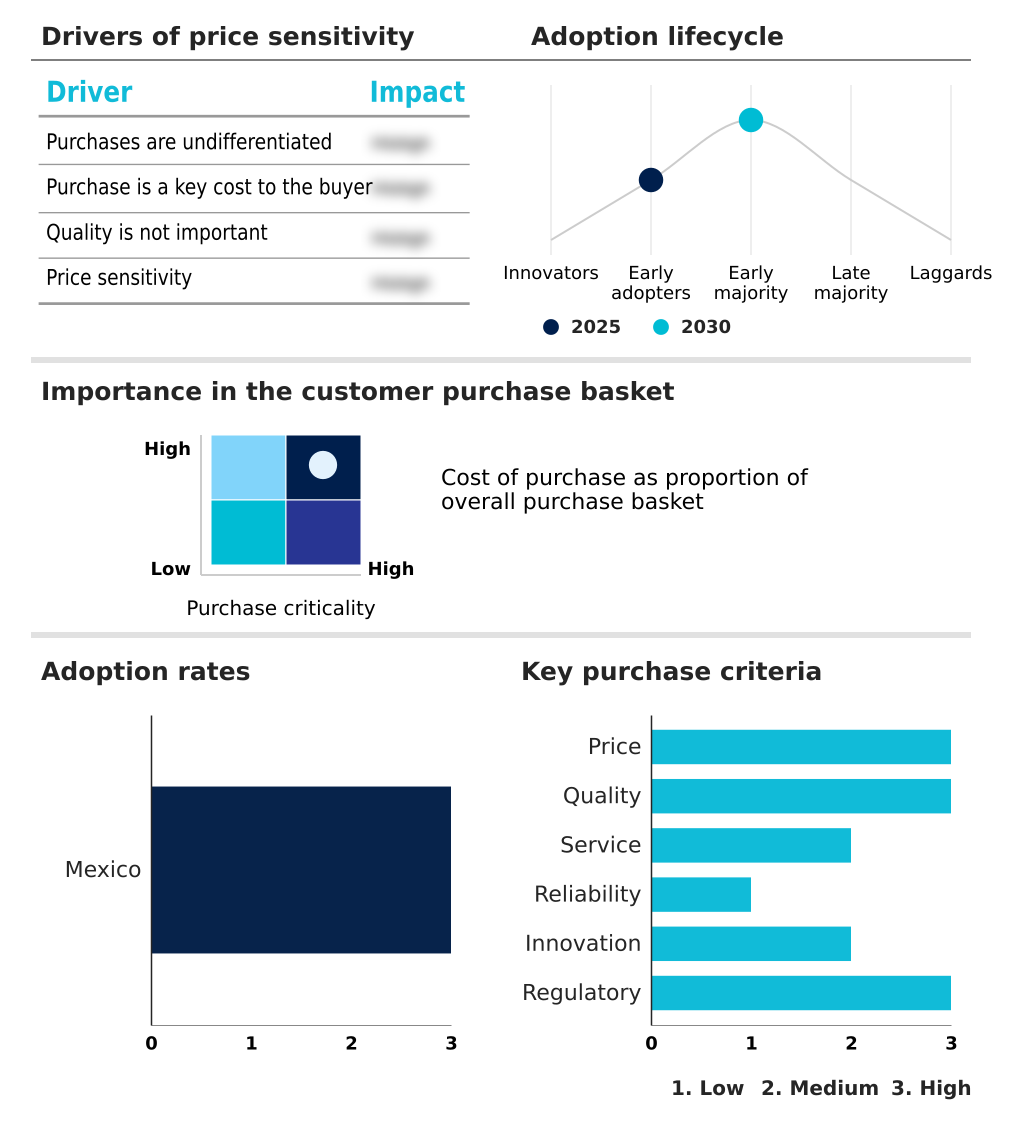
Customer Landscape of Mexico Oil And Gas Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, mexico oil and gas market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Baker Hughes Co. - The company offers advanced subsea production systems, critical drilling equipment, and integrated gas technology solutions to optimize extraction efficiency and support comprehensive industrial energy transitions.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Baker Hughes Co.
  • Corporativo Grupo R S.A. de C.V.
  • Cotemar S.A. de C.V.
  • Eni SpA
  • Grupo Diavaz
  • Grupo Mexicano de Infraestructura
  • Halliburton Co.
  • Harbour Energy plc
  • Helmerich and Payne Inc.
  • Hokchi Energy
  • Nabors Industries Ltd.
  • NOV Inc.
  • Oceaneering International Inc.
  • Perenco
  • Petroleos Mexicanos
  • Schlumberger Ltd.
  • TechnipFMC plc
  • Tenaris SA
  • Transocean Ltd.
  • Vallourec SA
  • Weatherford International Plc
  • Woodside Energy Group Ltd.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Mexico oil and gas market

  • In the Oil and Gas Refining and Marketing industry, the global shift toward stringent marine fuel desulfurization mandates under the MARPOL regulations has accelerated the deployment of advanced hydroprocessing units, directly impacting the Oil And Gas market by increasing demand for low-sulfur crude processing capabilities by 18%.
  • The widespread adoption of predictive maintenance algorithms in massive downstream complexes has reduced unexpected catalytic cracker outages, boosting the Oil And Gas market throughput efficiency and stabilizing regional fuel supply chains by over 12%.
  • Stringent environmental directives enforcing greenhouse gas emission reductions have prompted heavy investments in carbon capture technologies at primary processing facilities, forcing the Oil And Gas market to rapidly modernize legacy infrastructure to meet a 20% emissions reduction target.
  • The structural relocation of manufacturing hubs toward North America has driven a massive surge in regional natural gas consumption, compelling the Oil And Gas market to expand cross-border pipeline networks and increase midstream transmission capacity by nearly 25%.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Mexico Oil And Gas Market insights. See full methodology.

Market Scope
Page number 226
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 3.4%
Market growth 2026-2030 USD 40.4 billion
Market structure Fragmented
YoY growth 2025-2026(%) 3.3%
Key countries Mexico
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Oil And Gas Market in Mexico reflects a dynamic transition toward systemic infrastructural modernization and stringent operational optimization. Industry participants continuously navigate the complexities of mature field depletion by deploying high-specification equipment and sophisticated subsea frameworks, enabling unparalleled access to complex maritime reserves.
  • The integration of precision data acquisition systems has revolutionized geological analysis, directly improving well-placement accuracy and driving a 25% reduction in exploratory drilling downtime. Concurrently, processing facilities prioritize advanced distillation upgrades, allowing operators to maximize high-margin fuel outputs while strictly aligning with evolving environmental mandates.
  • This strategic shift fundamentally alters boardroom budgeting, as capital expenditure pivots toward sustainable secondary recovery methods and rigorous emissions tracking. Consequently, these targeted technological investments streamline the entire supply chain, fortifying asset resilience and enabling major operators to consistently meet the escalating energy demands of an aggressively expanding industrial manufacturing ecosystem.

What are the Key Data Covered in this Mexico Oil And Gas Market Research and Growth Report?

  • What is the expected growth of the Mexico Oil And Gas Market between 2026 and 2030?

    • USD 40.4 billion, at a CAGR of 3.4%

  • What segmentation does the market report cover?

    • The report is segmented by Type (Upstream, Downstream, and Midstream), Deployment (Offshore, and Onshore), Application (Residential, Commercial, and Industrial), Product Type (Crude oil, Refined petroleum products, and Natural gas), Service (Refining and petrochemical processing, Pipeline infrastructure and transportation, Exploration and drilling equipment, and Storage and distribution) and Geography (North America)

  • Which regions are analyzed in the report?

    • North America

  • What are the key growth drivers and market challenges?

    • Infrastructure modernization and expansion, Severe financial indebtedness and supplier obligations

  • Who are the major players in the Mexico Oil And Gas Market?

    • Baker Hughes Co., Corporativo Grupo R S.A. de C.V., Cotemar S.A. de C.V., Eni SpA, Grupo Diavaz, Grupo Mexicano de Infraestructura, Halliburton Co., Harbour Energy plc, Helmerich and Payne Inc., Hokchi Energy, Nabors Industries Ltd., NOV Inc., Oceaneering International Inc., Perenco, Petroleos Mexicanos, Schlumberger Ltd., TechnipFMC plc, Tenaris SA, Transocean Ltd., Vallourec SA, Weatherford International Plc and Woodside Energy Group Ltd.

Market Research Insights

  • The Oil And Gas Market in Mexico rapidly evolves as operators implement advanced digital frameworks to overcome structural production declines. Strategic emphasis on mature asset revitalization and precise marine block appraisal has improved reservoir extraction predictability by 22%, significantly mitigating operational downtime.
  • Concurrently, downstream facilities aggressively pursue processing facility upgrades, elevating high-margin light product yields by 18% to satisfy rising domestic transportation demands. By expanding vital midstream transportation capabilities, operators have reduced logistical bottlenecks by 15%, ensuring consistent raw material flow.
  • These targeted infrastructural and technological enhancements directly optimize supply chain resilience, enabling operators to strategically balance complex extraction costs with escalating regional industrial fuel requirements.

We can help! Our analysts can customize this mexico oil and gas market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Country Market Characteristics
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Deployment
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Market Segmentation by Product Type
Executive Summary - Chart on Market Segmentation by Service
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Overview on factors of disruption

2.4 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ billion)
Data Table on Mexico - Market size and forecast 2025-2030 ($ billion)
Chart on Mexico: Year-over-year growth 2025-2030 (%)
Data Table on Mexico: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Oil And Gas Market in Mexico 2020 - 2024

Historic Market Size - Data Table on Oil And Gas Market in Mexico 2020 - 2024 ($ billion)

5.2 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ billion)

5.3 Deployment segment analysis 2020 - 2024

Historic Market Size - Deployment Segment 2020 - 2024 ($ billion)

5.4 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ billion)

5.5 Product Type segment analysis 2020 - 2024

Historic Market Size - Product Type Segment 2020 - 2024 ($ billion)

5.6 Service segment analysis 2020 - 2024

Historic Market Size - Service Segment 2020 - 2024 ($ billion)

6. Qualitative Analysis

6.1 Impact of AI on oil and gas market in Mexico

6.2 Impact of geopolitical conflicts on oil and gas market in Mexico

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Type

8.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

8.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

8.3 Upstream - Market size and forecast 2025-2030

Chart on Upstream - Market size and forecast 2025-2030 ($ billion)
Data Table on Upstream - Market size and forecast 2025-2030 ($ billion)
Chart on Upstream - Year-over-year growth 2025-2030 (%)
Data Table on Upstream - Year-over-year growth 2025-2030 (%)

8.4 Downstream - Market size and forecast 2025-2030

Chart on Downstream - Market size and forecast 2025-2030 ($ billion)
Data Table on Downstream - Market size and forecast 2025-2030 ($ billion)
Chart on Downstream - Year-over-year growth 2025-2030 (%)
Data Table on Downstream - Year-over-year growth 2025-2030 (%)

8.5 Midstream - Market size and forecast 2025-2030

Chart on Midstream - Market size and forecast 2025-2030 ($ billion)
Data Table on Midstream - Market size and forecast 2025-2030 ($ billion)
Chart on Midstream - Year-over-year growth 2025-2030 (%)
Data Table on Midstream - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by Type

Market opportunity by Type ($ billion)
Data Table on Market opportunity by Type ($ billion)

9. Market Segmentation by Deployment

9.1 Market segments

Chart on Deployment - Market share 2025-2030 (%)
Data Table on Deployment - Market share 2025-2030 (%)

9.2 Comparison by Deployment

Chart on Comparison by Deployment
Data Table on Comparison by Deployment

9.3 Offshore - Market size and forecast 2025-2030

Chart on Offshore - Market size and forecast 2025-2030 ($ billion)
Data Table on Offshore - Market size and forecast 2025-2030 ($ billion)
Chart on Offshore - Year-over-year growth 2025-2030 (%)
Data Table on Offshore - Year-over-year growth 2025-2030 (%)

9.4 Onshore - Market size and forecast 2025-2030

Chart on Onshore - Market size and forecast 2025-2030 ($ billion)
Data Table on Onshore - Market size and forecast 2025-2030 ($ billion)
Chart on Onshore - Year-over-year growth 2025-2030 (%)
Data Table on Onshore - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Deployment

Market opportunity by Deployment ($ billion)
Data Table on Market opportunity by Deployment ($ billion)

10. Market Segmentation by Application

10.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

10.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

10.3 Residential - Market size and forecast 2025-2030

Chart on Residential - Market size and forecast 2025-2030 ($ billion)
Data Table on Residential - Market size and forecast 2025-2030 ($ billion)
Chart on Residential - Year-over-year growth 2025-2030 (%)
Data Table on Residential - Year-over-year growth 2025-2030 (%)

10.4 Commercial - Market size and forecast 2025-2030

Chart on Commercial - Market size and forecast 2025-2030 ($ billion)
Data Table on Commercial - Market size and forecast 2025-2030 ($ billion)
Chart on Commercial - Year-over-year growth 2025-2030 (%)
Data Table on Commercial - Year-over-year growth 2025-2030 (%)

10.5 Industrial - Market size and forecast 2025-2030

Chart on Industrial - Market size and forecast 2025-2030 ($ billion)
Data Table on Industrial - Market size and forecast 2025-2030 ($ billion)
Chart on Industrial - Year-over-year growth 2025-2030 (%)
Data Table on Industrial - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Application

Market opportunity by Application ($ billion)
Data Table on Market opportunity by Application ($ billion)

11. Market Segmentation by Product Type

11.1 Market segments

Chart on Product Type - Market share 2025-2030 (%)
Data Table on Product Type - Market share 2025-2030 (%)

11.2 Comparison by Product Type

Chart on Comparison by Product Type
Data Table on Comparison by Product Type

11.3 Crude oil - Market size and forecast 2025-2030

Chart on Crude oil - Market size and forecast 2025-2030 ($ billion)
Data Table on Crude oil - Market size and forecast 2025-2030 ($ billion)
Chart on Crude oil - Year-over-year growth 2025-2030 (%)
Data Table on Crude oil - Year-over-year growth 2025-2030 (%)

11.4 Refined petroleum products - Market size and forecast 2025-2030

Chart on Refined petroleum products - Market size and forecast 2025-2030 ($ billion)
Data Table on Refined petroleum products - Market size and forecast 2025-2030 ($ billion)
Chart on Refined petroleum products - Year-over-year growth 2025-2030 (%)
Data Table on Refined petroleum products - Year-over-year growth 2025-2030 (%)

11.5 Natural gas - Market size and forecast 2025-2030

Chart on Natural gas - Market size and forecast 2025-2030 ($ billion)
Data Table on Natural gas - Market size and forecast 2025-2030 ($ billion)
Chart on Natural gas - Year-over-year growth 2025-2030 (%)
Data Table on Natural gas - Year-over-year growth 2025-2030 (%)

11.6 Market opportunity by Product Type

Market opportunity by Product Type ($ billion)
Data Table on Market opportunity by Product Type ($ billion)

12. Market Segmentation by Service

12.1 Market segments

Chart on Service - Market share 2025-2030 (%)
Data Table on Service - Market share 2025-2030 (%)

12.2 Comparison by Service

Chart on Comparison by Service
Data Table on Comparison by Service

12.3 Refining and petrochemical processing - Market size and forecast 2025-2030

Chart on Refining and petrochemical processing - Market size and forecast 2025-2030 ($ billion)
Data Table on Refining and petrochemical processing - Market size and forecast 2025-2030 ($ billion)
Chart on Refining and petrochemical processing - Year-over-year growth 2025-2030 (%)
Data Table on Refining and petrochemical processing - Year-over-year growth 2025-2030 (%)

12.4 Pipeline infrastructure and transportation - Market size and forecast 2025-2030

Chart on Pipeline infrastructure and transportation - Market size and forecast 2025-2030 ($ billion)
Data Table on Pipeline infrastructure and transportation - Market size and forecast 2025-2030 ($ billion)
Chart on Pipeline infrastructure and transportation - Year-over-year growth 2025-2030 (%)
Data Table on Pipeline infrastructure and transportation - Year-over-year growth 2025-2030 (%)

12.5 Exploration and drilling equipment - Market size and forecast 2025-2030

Chart on Exploration and drilling equipment - Market size and forecast 2025-2030 ($ billion)
Data Table on Exploration and drilling equipment - Market size and forecast 2025-2030 ($ billion)
Chart on Exploration and drilling equipment - Year-over-year growth 2025-2030 (%)
Data Table on Exploration and drilling equipment - Year-over-year growth 2025-2030 (%)

12.6 Storage and distribution - Market size and forecast 2025-2030

Chart on Storage and distribution - Market size and forecast 2025-2030 ($ billion)
Data Table on Storage and distribution - Market size and forecast 2025-2030 ($ billion)
Chart on Storage and distribution - Year-over-year growth 2025-2030 (%)
Data Table on Storage and distribution - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by Service

Market opportunity by Service ($ billion)
Data Table on Market opportunity by Service ($ billion)

13. Customer Landscape

13.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

14. Drivers, Challenges, and Opportunity

14.1 Market drivers

Infrastructure modernization and expansion
Refining capacity enhancement and import reduction
Advanced technological deployment and asset optimization

14.2 Market challenges

Severe financial indebtedness and supplier obligations
Regulatory uncertainty and mixed contract implementation hurdles
Infrastructure bottlenecks and chronic underinvestment in refining assets

14.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

14.4 Market opportunities

Integration of renewable energy sources and corporate sustainability transitions
Digital transformation and AI integration
Nearshoring and regional supply chain relocation

15. Competitive Landscape

15.1 Overview

15.2

Overview on criticality of inputs and factors of differentiation

15.3 Landscape disruption

Overview on factors of disruption

15.4 Industry risks

Impact of key risks on business

16. Competitive Analysis

16.1 Companies profiled

Companies covered

16.2 Company ranking index

16.3 Market positioning of companies

Matrix on companies position and classification

16.4 Baker Hughes Co.

Baker Hughes Co. - Overview
Baker Hughes Co. - Business segments
Baker Hughes Co. - Key news
Baker Hughes Co. - Key offerings
Baker Hughes Co. - Segment focus
SWOT

16.5 Corporativo Grupo R S.A. de C.V.

Corporativo Grupo R S.A. de C.V. - Overview
Corporativo Grupo R S.A. de C.V. - Product / Service
Corporativo Grupo R S.A. de C.V. - Key offerings
SWOT

16.6 Cotemar S.A. de C.V.

Cotemar S.A. de C.V. - Overview
Cotemar S.A. de C.V. - Product / Service
Cotemar S.A. de C.V. - Key offerings
SWOT

16.7 Eni SpA

Eni SpA - Overview
Eni SpA - Business segments
Eni SpA - Key offerings
Eni SpA - Segment focus
SWOT

16.8 Grupo Diavaz

Grupo Diavaz - Overview
Grupo Diavaz - Product / Service
Grupo Diavaz - Key offerings
SWOT

16.9 Grupo Mexicano de Infraestructura

Grupo Mexicano de Infraestructura - Overview
Grupo Mexicano de Infraestructura - Product / Service
Grupo Mexicano de Infraestructura - Key offerings
SWOT

16.10 Halliburton Co.

Halliburton Co. - Overview
Halliburton Co. - Business segments
Halliburton Co. - Key news
Halliburton Co. - Key offerings
Halliburton Co. - Segment focus
SWOT

16.11 Harbour Energy plc

Harbour Energy plc - Overview
Harbour Energy plc - Product / Service
Harbour Energy plc - Key offerings
SWOT

16.12 Helmerich and Payne Inc.

Helmerich and Payne Inc. - Overview
Helmerich and Payne Inc. - Business segments
Helmerich and Payne Inc. - Key offerings
Helmerich and Payne Inc. - Segment focus
SWOT

16.13 Hokchi Energy

Hokchi Energy - Overview
Hokchi Energy - Product / Service
Hokchi Energy - Key offerings
SWOT

16.14 Nabors Industries Ltd.

Nabors Industries Ltd. - Overview
Nabors Industries Ltd. - Business segments
Nabors Industries Ltd. - Key offerings
Nabors Industries Ltd. - Segment focus
SWOT

16.15 NOV Inc.

NOV Inc. - Overview
NOV Inc. - Business segments
NOV Inc. - Key offerings
NOV Inc. - Segment focus
SWOT

16.16 Oceaneering International Inc.

Oceaneering International Inc. - Overview
Oceaneering International Inc. - Business segments
Oceaneering International Inc. - Key news
Oceaneering International Inc. - Key offerings
Oceaneering International Inc. - Segment focus
SWOT

16.17 Perenco

Perenco - Overview
Perenco - Product / Service
Perenco - Key offerings
SWOT

16.18 Petroleos Mexicanos

Petroleos Mexicanos - Overview
Petroleos Mexicanos - Product / Service
Petroleos Mexicanos - Key offerings
SWOT

17. Appendix

17.1 Scope of the report

Market definition
Objectives
Notes and caveats

17.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

17.3 Currency conversion rates for US$

17.4 Research methodology

17.5 Data procurement

Information sources

17.6 Data validation

17.7 Validation techniques employed for market sizing

17.8 Data synthesis

17.9 360 degree market analysis

17.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Mexico Oil And Gas market growth will increase by USD 40.4 billion during 2026-2030.

The Mexico Oil And Gas market is expected to grow at a CAGR of 3.4% during 2026-2030.

Mexico Oil And Gas market is segmented by Type (Upstream, Downstream, Midstream) Deployment (Offshore, Onshore) Application (Residential, Commercial, Industrial) Product type (Crude oil, Refined petroleum products, Natural gas) Service (Refining and petrochemical processing, Pipeline infrastructure and transportation, Exploration and drilling equipment, Storage and distribution)

Baker Hughes Co., Corporativo Grupo R S.A. de C.V., Cotemar S.A. de C.V., Eni SpA, Grupo Diavaz, Grupo Mexicano de Infraestructura, Halliburton Co., Harbour Energy plc, Helmerich and Payne Inc., Hokchi Energy, Nabors Industries Ltd., NOV Inc., Oceaneering International Inc., Perenco, Petroleos Mexicanos, Schlumberger Ltd., TechnipFMC plc, Tenaris SA, Transocean Ltd., Vallourec SA, Weatherford International Plc, Woodside Energy Group Ltd. are a few of the key vendors in the Mexico Oil And Gas market.

North America will register the highest growth rate of 100% among the other regions. Therefore, the Mexico Oil And Gas market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

Mexico

  • Infrastructure modernization and expansion is the driving factor this market.

The Mexico Oil And Gas market vendors should focus on grabbing business opportunities from the Type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
