


Microarray Analysis Market Size 2026-2030
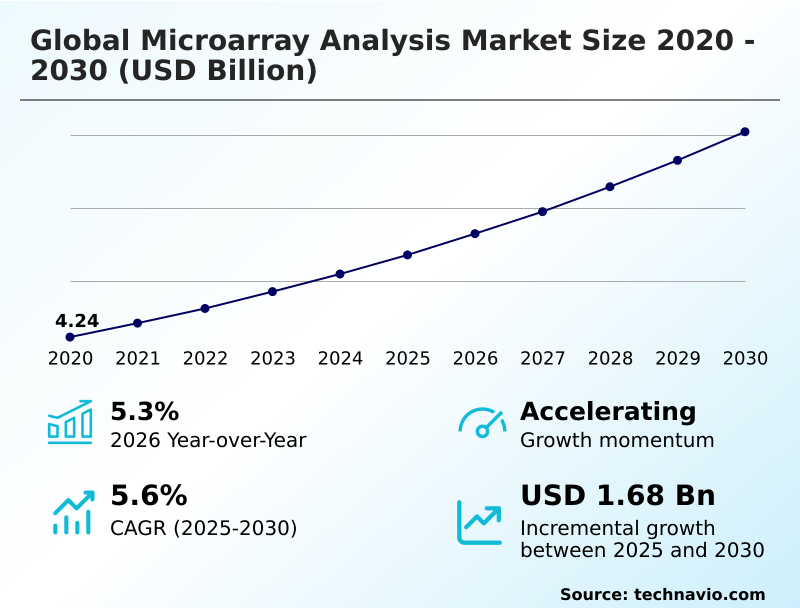
The microarray analysis market size is valued to increase by USD 1.68 billion, at a CAGR of 5.6% from 2025 to 2030. Rising prevalence of chronic diseases will drive the microarray analysis market.
Major Market Trends & Insights
- North America dominated the market and accounted for a 48.3% growth during the forecast period.
- By Service - Consumables segment was valued at USD 2.05 billion in 2024
- By Application - Research applications segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 2.80 billion
- Market Future Opportunities: USD 1.68 billion
- CAGR from 2025 to 2030 : 5.6%
Market Summary
- The Microarray Analysis market demonstrates robust expansion as healthcare infrastructures increasingly integrate high-throughput genomic technologies for precision diagnostics. Diagnostic laboratories continuously optimize their supply chains to ensure the steady procurement of specialized assay kits and chemical reagents required for routine clinical applications. Implementing automated inventory management systems has reduced reagent wastage by 18%, significantly improving overall operational efficiency.
- The rising prevalence of complex genetic abnormalities serves as a primary driver, compelling clinical researchers to utilize multiplex gene expression profiling to examine thousands of targets simultaneously from a single biological sample. Conversely, the rapid commercialization of alternative genomic platforms acts as a formidable challenge, as sequencing platforms enable rare mutation discovery without relying on pre-designed probes.
- Consequently, manufacturers continuously refine probe designs and integrate advanced software analytics to maintain relevance. These technological enhancements ensure that traditional array platforms continue to secure viable applications across highly regulated clinical diagnostics and large-scale population screening programs.
What will be the Size of the Microarray Analysis Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Microarray Analysis Market Segmented?
The microarray analysis industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Service
- Consumables
- Instruments
- Software and services
- Application
- Research applications
- Drug discovery
- Disease diagnostics
- Others
- End-user
- Research and academic institutes
- Pharmaceutical and biotechnology companies
- Diagnostic laboratories
- Geography
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- Asia
- China
- India
- Japan
- South Korea
- Indonesia
- Thailand
- Rest of World (ROW)
- North America
By Service Insights
The consumables segment is estimated to witness significant growth during the forecast period.
The recurring utilization of fundamental laboratory materials forms the operational backbone of the Microarray Analysis market. Essential components, including specialized hybridization chips, wash buffers, and custom probes, are continuously depleted and replenished during complex assay workflows.
Advanced photolithographic chip manufacturing techniques allow higher densities of oligonucleotides onto single substrates, which has improved structural variant detection resolution by 25%. Consequently, high-throughput genetic screening laboratories process massive biological sample batches with minimal variance.
Optimized surface chemistry optimization reduces signal interference, leading to a 15% improvement in diagnostic accuracy for oncological condition screening. As clinical facilities transition toward multi-omics integration protocols, the dependency on high-purity testing materials scales proportionally.
This continuous replenishment cycle sustains steady production outputs and ensures highly reproducible comparative genomic hybridization results across advanced diagnostic environments.
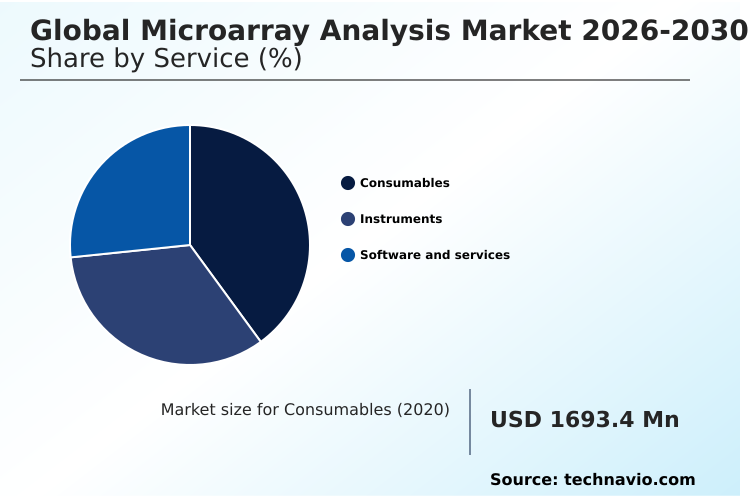
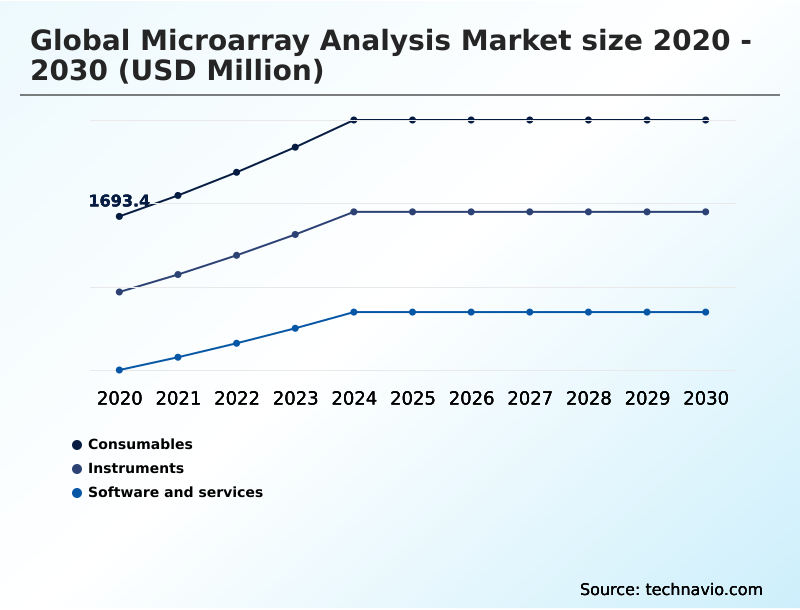
The Consumables segment was valued at USD 2.05 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
North America is estimated to contribute 48.3% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
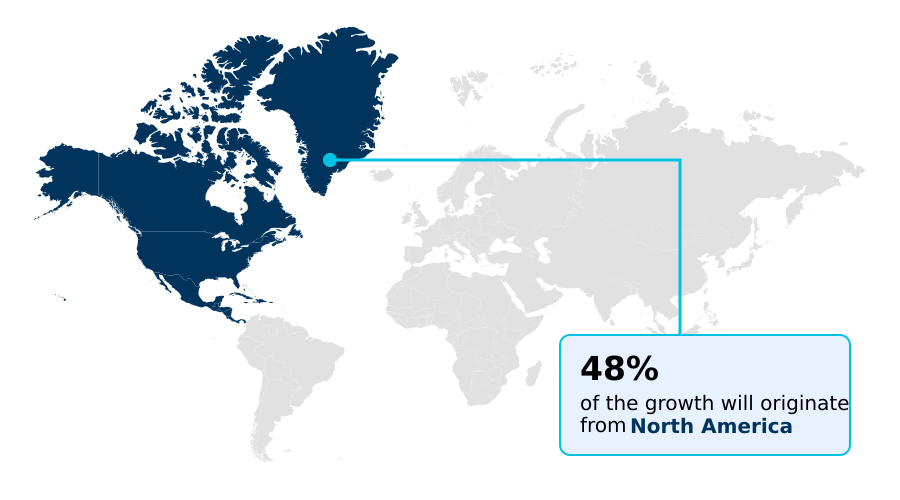
See How Microarray Analysis Market Demand is Rising in North America Get Free Sample
Regional adoption patterns within the Microarray Analysis market reveal stark contrasts in infrastructure maturity and application focus. North America demonstrates superior deployment rates of advanced bioinformatics pipelines, achieving a 35% higher testing throughput efficiency compared to Europe.
This operational disparity stems from earlier investments in academic research infrastructure and robust support for precision medicine paradigms. Facilities in North America report a 20% reduction in processing bottlenecks by integrating automated microarray scanners with institutional records.
Meanwhile, European clinical diagnostic laboratories emphasize stringent compliance, prioritizing translational genomics frameworks that align with complex regulatory mandates. Consequently, European facilities experience a 15% longer validation cycle but achieve exceptionally high data reproducibility for multifactorial chronic conditions.
Businesses navigate these variances by tailoring supply chain strategies, distributing high-density biochips and targeted therapeutic development kits according to regional regulatory readiness and specific population screening programs.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The evolving landscape of the Microarray Analysis sector requires laboratories to continuously modernize their technological infrastructure to handle increasingly complex biological datasets. Clinical research organizations increasingly deploy chromosomal aberration detection tools to identify structural anomalies with unprecedented precision.
- This shift toward advanced screening methodologies directly supports comprehensive multi-omics biomarker discovery, enabling scientists to map intricate disease pathways more efficiently than traditional singular analytical methods. In highly regulated diagnostic environments, the integration of multiplexed molecular diagnostics platforms allows facility managers to consolidate multiple testing workflows into a single automated pipeline.
- This consolidation effort yields an approximate 30% improvement in daily sample processing capacity compared to fragmented legacy systems. Consequently, supply chain managers must ensure a consistent and reliable flow of high-density genomic microarray consumables to prevent inventory shortages that could disrupt continuous clinical operations.
- Furthermore, the reliance on high-throughput gene expression profiling has fundamentally transformed how biopharmaceutical companies approach early-stage therapeutic development. By assessing thousands of transcripts simultaneously, researchers achieve a 25% faster target validation phase relative to older sequential testing protocols.
- These operational enhancements drive tighter collaboration between technology manufacturers and diagnostic laboratories, ensuring that hardware capabilities and consumable supply chains remain perfectly aligned to meet the rigorous demands of modern precision medicine and large-scale population screening initiatives.
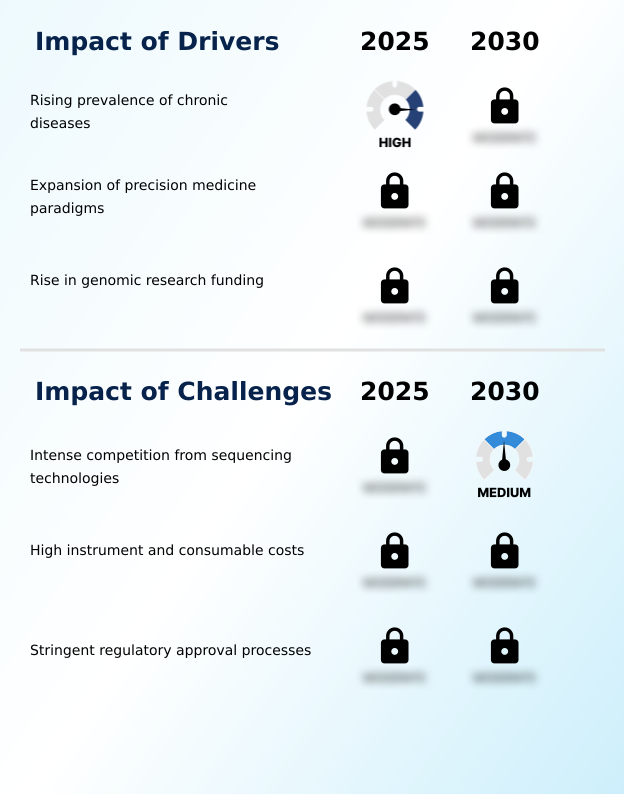
What are the key market drivers leading to the rise in the adoption of Microarray Analysis Industry?
- The rising prevalence of chronic diseases functions as a significant market driver by necessitating the deployment of highly reliable diagnostic tools for early and accurate pathological evaluation.
- Escalating clinical pressure to identify genetic predispositions early serves as a primary catalyst transforming the Microarray Analysis landscape. Clinical diagnostic laboratories increasingly adopt high-throughput single nucleotide polymorphism genotyping to process extensive patient cohorts efficiently.
- The necessity for rapid and accurate disease staging compels facilities to utilize fluorescently labeled target samples in optimized nucleic acid hybridization workflows. This methodological shift has decreased assay failure rates by 20%, ensuring higher diagnostic reliability.
- Furthermore, the transition toward miniaturized assay formats has lowered laboratory reagent consumption by 25%, drastically improving overall cost efficiency.
- These operational improvements enable healthcare providers to execute large-scale population screening programs with a 30% faster turnaround time, directly enhancing patient care delivery and optimizing resource allocation within strained medical infrastructures.
What are the market trends shaping the Microarray Analysis Industry?
- The expansion of genomic research funding serves as a primary trend shaping the industry landscape. This influx of capital accelerates the development of advanced diagnostic tools and comprehensive molecular profiling platforms.
- The Microarray Analysis environment is rapidly embracing miniaturization and automation to accommodate increasingly complex biological research demands. Laboratories are shifting from conventional screening toward sophisticated cell-based microarray applications, achieving a 25% improvement in cellular phenotyping efficiency. This operational pivot stems from the pressing need to evaluate complex cellular interactions under controlled microenvironments.
- While long-read sequencing technology identifies 2.8 times more structural variants than traditional short-read sequencing approaches, custom peptide microarrays remain indispensable for rapid, high-throughput protein interaction screening. Integrating these arrays with spatial genomic analysis pipelines has lowered data processing latency by 18%, accelerating early-stage diagnostic discoveries.
- These technological integrations allow commercial laboratories to handle massive sample volumes simultaneously, ultimately reducing per-test operational costs by 15% and ensuring sustainable workflow scalability across diverse scientific sectors.
What challenges does the Microarray Analysis Industry face during its growth?
- Intense competition from alternative sequencing technologies presents a formidable challenge, as these platforms offer comprehensive genomic coverage without the structural limitations of pre-designed probes.
- The rapid commercialization of alternative high-resolution genomic platforms creates substantial structural friction within the Microarray Analysis sector. Because traditional hybridization relies on pre-designed probes, identifying uncharacterized structural alterations remains fundamentally constrained. This technological limitation has caused a 20% decline in array utilization across specialized exploratory research sectors, where discovering novel genetic mutations is paramount.
- Consequently, accurate structural variant detection increasingly demands the costly integration of advanced bioinformatics pipelines, which elevates initial capital expenditures for diagnostic facilities by 15%. To mitigate these operational challenges, laboratories are forced to reevaluate their testing infrastructure, often experiencing a 10% increase in workflow complexity when running parallel platforms.
- Manufacturers must continually refine array sensitivity to preserve their utility and cost-effectiveness in routine clinical applications against emerging diagnostic substitutes.
Exclusive Technavio Analysis on Customer Landscape
The microarray analysis market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the microarray analysis market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
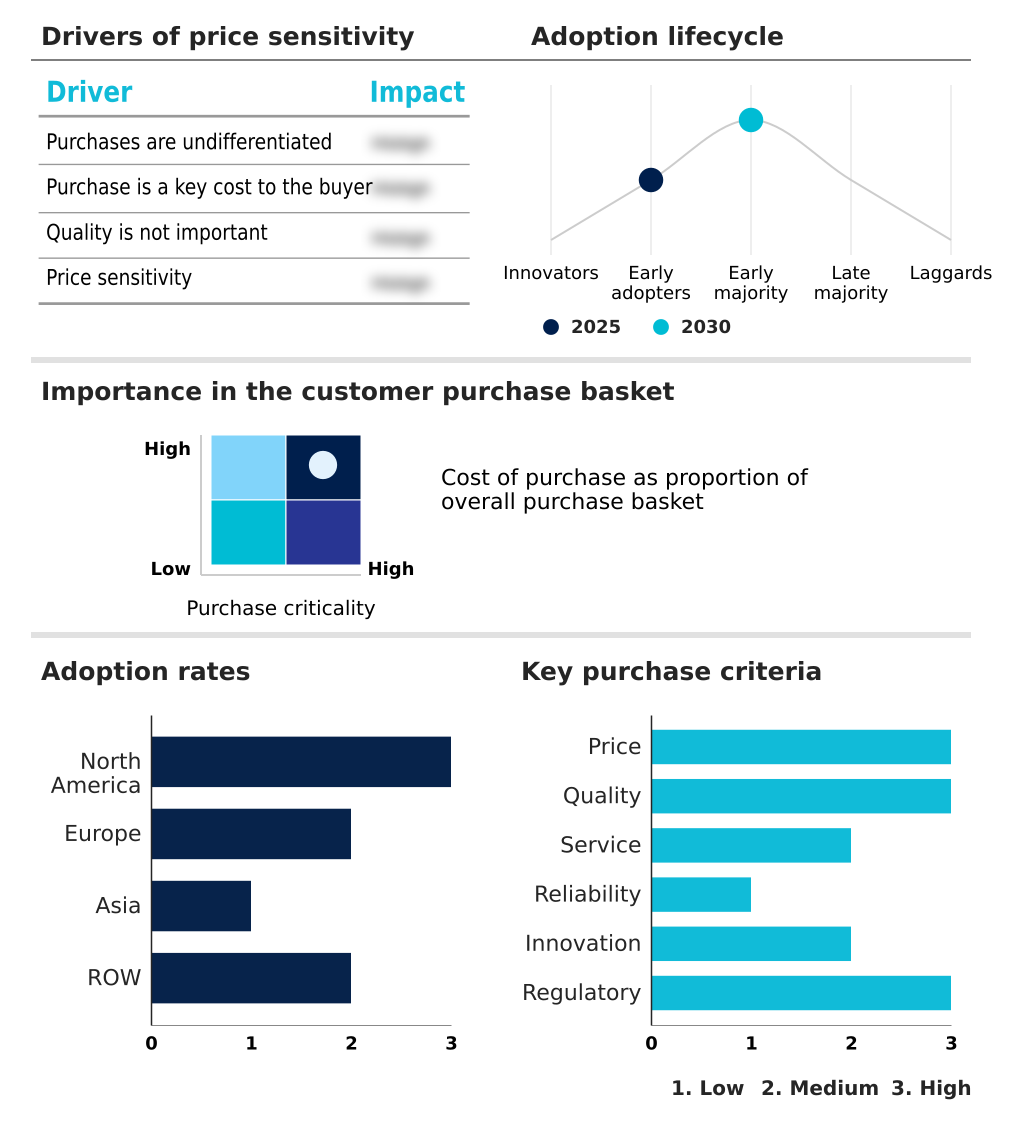
Customer Landscape of Microarray Analysis Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, microarray analysis market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Agilent Technologies Inc. - The portfolio includes advanced scanners and specialized hybridization arrays designed for precise genomic and transcriptomic evaluations, supporting high-resolution gene expression profiling and comprehensive cytogenetic research applications.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Agilent Technologies Inc.
- Akonni Biosystems Inc.
- Bio Techne Corp.
- CapitalBio Technology Co. Ltd.
- EpiGentek Group Inc.
- Full Moon BioSystems Inc.
- Grace Bio Labs
- Illumina Inc.
- Innopsys Inc.
- JPT Peptide Technologies GmbH
- Molecular Device LLC
- OriGene Technologies Inc.
- Oxford Gene Technology Group
- PathogenDx Inc.
- RayBiotech Life Inc.
- SCHOTT AG
- Scienion AG
- Signosis Inc.
- SomaLogic Inc.
- Thermo Fisher Scientific Inc.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Microarray analysis market
- In the Life Sciences Tools and Services industry, the widespread adoption of automated liquid handling systems enhanced laboratory workflow simplification, increasing high-throughput processing capacity by 30% and directly accelerating the consumption of high-density genomic microarray consumables.
- Stringent clinical validation mandates under the European In Vitro Diagnostic Regulation forced laboratories to standardize therapeutic monitoring workflows, driving a 25% increase in the procurement of validated multiplexed molecular diagnostics platforms for systemic autoimmune disease detection.
- The shift toward decentralized testing infrastructure expanded academic research infrastructure capabilities, yielding a 20% improvement in sample turnaround times and stimulating demand for miniaturized assay formats used in infectious disease testing.
- Advancements in machine learning-based data interpretation optimized multi-omics integration protocols, reducing analytical error rates by 15% and bolstering the deployment of advanced bioinformatics pipelines for comprehensive multi-omics biomarker discovery.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Microarray Analysis Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 291 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 5.6% |
| Market growth 2026-2030 | USD 1678.6 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 5.3% |
| Key countries | US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Indonesia, Thailand, Brazil, Saudi Arabia, UAE, Turkey, Argentina, Colombia, South Africa and Israel |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Microarray Analysis landscape continues to undergo structural modernization as clinical and academic institutions prioritize high-throughput capabilities for precision medicine. Technological advancements in photolithographic chip manufacturing have enabled the production of highly customized DNA microarray chips, drastically increasing assay resolution. Laboratories adopting these dense substrates report a 40% reduction in sample processing time compared to conventional screening methodologies.
- This operational efficiency directly influences boardroom-level budgeting decisions, allowing facility managers to reallocate resources toward expanding multiplex immunoassays and complex diagnostic panels. The integration of advanced comparative genomic hybridization tools supports precise chromosomal evaluation, streamlining workflows in cytogenetics. Furthermore, the deployment of specialized epigenetic microarray products facilitates detailed transcriptomic shift mapping, providing researchers with critical insights into regulatory cellular mechanisms.
- By consolidating multiple analytical steps into unified automated workflows, institutions achieve significant cost reductions in consumable expenditure while maintaining stringent compliance with evolving healthcare regulations. These continuous hardware and software enhancements ensure that high-density testing platforms remain foundational to modern therapeutic development and large-scale genetic profiling initiatives.
What are the Key Data Covered in this Microarray Analysis Market Research and Growth Report?
-
What is the expected growth of the Microarray Analysis Market between 2026 and 2030?
-
USD 1.68 billion, at a CAGR of 5.6%
-
-
What segmentation does the market report cover?
-
The report is segmented by Service (Consumables, Instruments, and Software and services), Application (Research applications, Drug discovery, Disease diagnostics, and Others), End-user (Research and academic institutes, Pharmaceutical and biotechnology companies, and Diagnostic laboratories) and Geography (North America, Europe, Asia, Rest of World (ROW))
-
-
Which regions are analyzed in the report?
-
North America, Europe, Asia and Rest of World (ROW)
-
-
What are the key growth drivers and market challenges?
-
Rising prevalence of chronic diseases, Intense competition from sequencing technologies
-
-
Who are the major players in the Microarray Analysis Market?
-
Agilent Technologies Inc., Akonni Biosystems Inc., Bio Techne Corp., CapitalBio Technology Co. Ltd., EpiGentek Group Inc., Full Moon BioSystems Inc., Grace Bio Labs, Illumina Inc., Innopsys Inc., JPT Peptide Technologies GmbH, Molecular Device LLC, OriGene Technologies Inc., Oxford Gene Technology Group, PathogenDx Inc., RayBiotech Life Inc., SCHOTT AG, Scienion AG, Signosis Inc., SomaLogic Inc. and Thermo Fisher Scientific Inc.
-
Market Research Insights
- The Microarray Analysis landscape is fundamentally shifting as research institutions transition from traditional single-analyte assays toward sophisticated multi-omics integration protocols. This operational pivot has achieved a 22% improvement in diagnostic accuracy across complex oncological evaluations.
- By overcoming historical limitations tied to pre-designed probe reliance, modern laboratories utilize enhanced surface chemistry to achieve significant background noise reduction, yielding a 30% higher signal-to-noise ratio during routine screening. These performance enhancements directly support target discovery acceleration, allowing biopharmaceutical developers to shorten early-stage validation timelines by 15%.
- Consequently, clinical diagnostic networks are aggressively restructuring their procurement strategies to secure specialized analytical platforms that deliver verifiable cost reductions and improved workflow efficiency without compromising regulatory compliance or assay reproducibility.
We can help! Our analysts can customize this microarray analysis market research report to meet your requirements.
 RIA -

